
 On-The-Go Pots Market | 2026-2036
On-The-Go Pots Market Size, Share, and Industry Trends Forecast 2026-2036
On-The-Go Pots Market Analytics
Buyer concentration among outdoor retailers and meal-kit platforms is expanding as e-commerce channels fragment traditional wholesale relationships. Scheurich Group leverages its European manufacturing footprint to serve garden-center chains transitioning into portable lifestyle categories. Keter Group anchors its position through durable polymer expertise originally developed for outdoor furniture. Elho competes in the premium segment with design-led formats targeting urban balcony gardeners seeking dual-use portability.
On-the-go pots are portable food containers engineered for thermal retention, leak resistance, and stackability, typically constructed with double-wall stainless steel or BPA-free polymer walls measuring 0.5 to 1.5 liters in functional capacity. Their primary commercial purpose centers on enabling prepared-meal consumption outside fixed kitchen infrastructure. Plastic variants sustain volume leadership in entry-level camping and student segments where cost sensitivity dominates purchase decisions. Stainless steel occupies the fastest-growing tier among professionals and outdoor enthusiasts prioritizing durability and temperature stability across multi-hour usage cycles. Ceramic and glass formats specialize in picnic and tailgating applications where aesthetic presentation commands premium positioning.
The US FDA regulates direct food-contact materials through 21 CFR standards, while the EPA oversees polymer production emissions affecting domestic manufacturing economics. REACH compliance in Europe constrains phthalate and heavy-metal content in colored polymer formulations, elevating testing costs for exporters. Stakeholders must monitor evolving extended producer responsibility frameworks in multiple jurisdictions to anticipate material passport requirements and recyclability mandates that will reshape supplier qualification criteria.
Market Dynamics
The European Union's Single-Use Plastics Directive is compressing polymer formulation choices while meal-kit platforms and outdoor retailers consolidate procurement volumes, forcing material suppliers to qualify reusable formats at accelerated timelines.
Growth Catalysts
- REACH compliance mandates:ECHA restrictions on phthalates and heavy metals in colored polymers are accelerating transitions toward stainless steel and certified BPA-free alternatives across German and French supply chains.
- Meal-kit platform expansion:Subscription services are standardizing thermal-retention specifications for multi-hour delivery windows, creating pull-through demand for double-wall insulated formats in urban commuter segments.
- Camping culture concentration:Germany's outdoor recreation participation rates and sustainability-conscious consumer base are converging to sustain premium pricing for durable, multi-use portable containers.
Market Restraints
- Polymer feedstock volatility:Propylene and PET resin price swings are compressing margins for entry-level plastic pot manufacturers serving cost-sensitive student and casual camping segments.
- Testing cost escalation:REACH migration testing and FDA 21 CFR compliance for direct food-contact materials are adding fixed qualification costs that disproportionately burden smaller format suppliers.
- Substitution pressure from rigid reusables:Glass meal-prep containers and silicone collapsible formats are capturing picnic and short-haul commuter occasions where thermal retention is secondary to microwave compatibility.
Strategic Opportunities
- Extended producer responsibility frameworks:France's AGEC law and impending EU-wide material passport requirements are creating first-mover advantages for suppliers with certified recyclability documentation and closed-loop take-back infrastructure.
- Smart packaging convergence:NFC-enabled temperature logging is converging with thermal-retention engineering to create premium traceability tiers for cold-chain meal delivery and pharmaceutical adjacent applications.
- Garden-center channel pivot:European horticultural retailers are expanding into portable lifestyle categories, creating shelf space for dual-use pots targeting urban balcony gardeners who alternate between plant cultivation and food transport.
Industry Challenges
- Multi-jurisdiction certification timelines:Simultaneous FDA, EFSA, and BIS clearance processes for new polymer formulations are extending product development cycles and freezing capital in pre-revenue inventory.
- Stacking and nesting geometry standardization:Absence of interoperable dimensional standards across meal-kit platforms is forcing redundant mold investments and fragmenting production runs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | On-The-Go Pots Market |
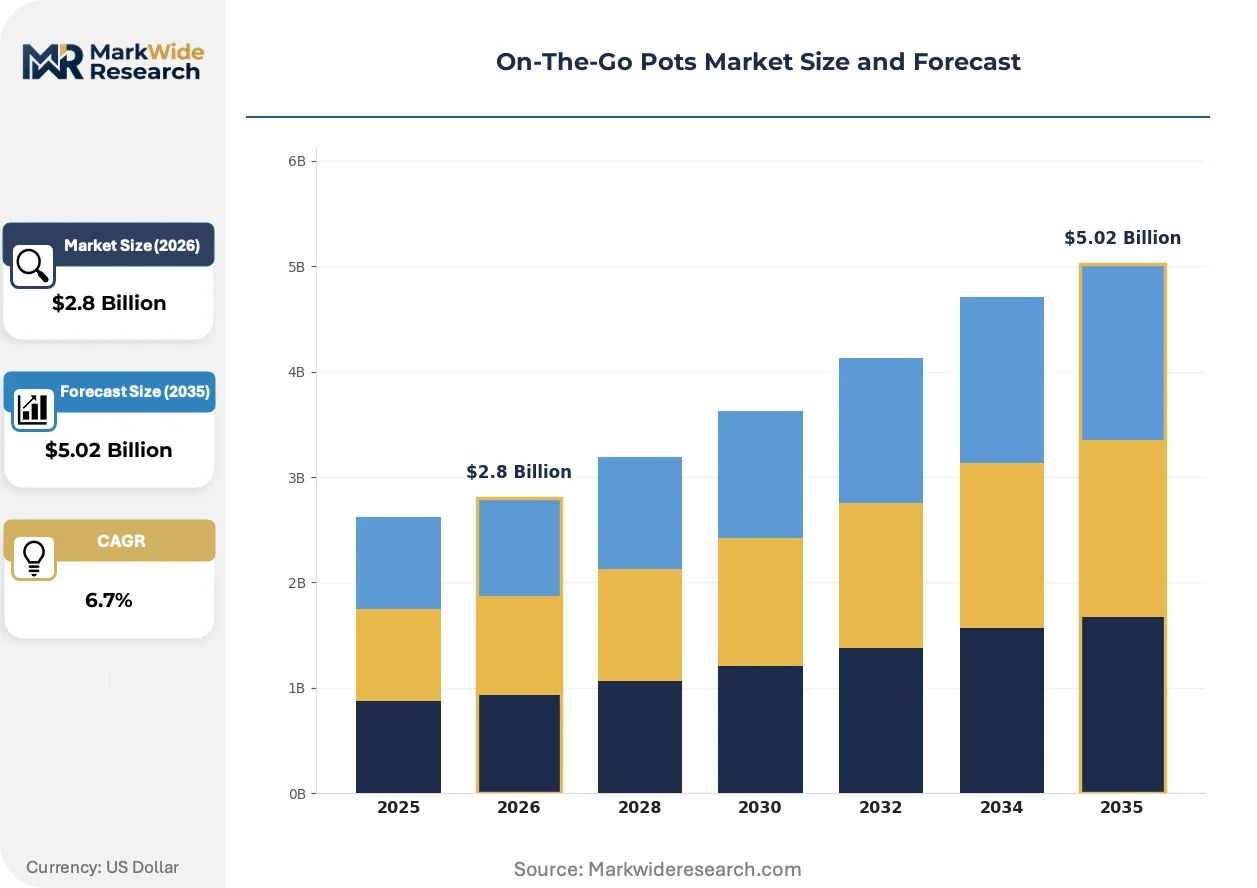
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stainless Steel, Plastic, Ceramic, Glass Size: Small, Medium, Large, Extra Large Application: Camping, Picnics, Tailgating, Travel Customer Type: Outdoor Enthusiasts, Families, Professionals, Students |
| Companies Covered | East Jordan Plastics, The Pot Company, Scheurich Group, Keter Group, Fiskars Group, Elho, HC Companies, Deroma Group, Bloem Living, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
On-The-Go Pots Market Evolving Landscape
Material science advances and regulatory stringency are compressing traditional product lifecycles while digital traceability requirements reshape supplier qualification protocols across European and North American value chains.
Double-wall vacuum insulation technology is converging with ceramic interior coatings to eliminate metallic taste transfer in stainless steel formats. Premium outdoor brands and professional meal-prep services are adopting these hybrid constructions for multi-hour temperature stability. This convergence is compressing the performance gap between entry-level polymer and mid-tier metal offerings, forcing repositioning across price tiers.
REACH Annex XVII restrictions on intentionally added microplastics are triggering reformulation investments in polymer colorants and slip agents. Manufacturers serving EU markets are accelerating transitions to mineral-based pigments and bio-derived plasticizers. Camping and student segments face the steepest cost pass-through challenges as reformulated compounds carry 15-25 percent raw material premiums.
Urban commuters are consolidating food-carry routines around single multi-function containers rather than accumulating occasion-specific formats. This behavioral compression is displacing specialized lunch-box and soup-thermos categories with convertible 0.8-1.2 liter pots featuring modular lid systems. German and Dutch metropolitan markets exhibit the most pronounced consolidation, with direct-to-consumer channels capturing share from traditional houseware retailers.
On-The-Go Pots Market Segmentation
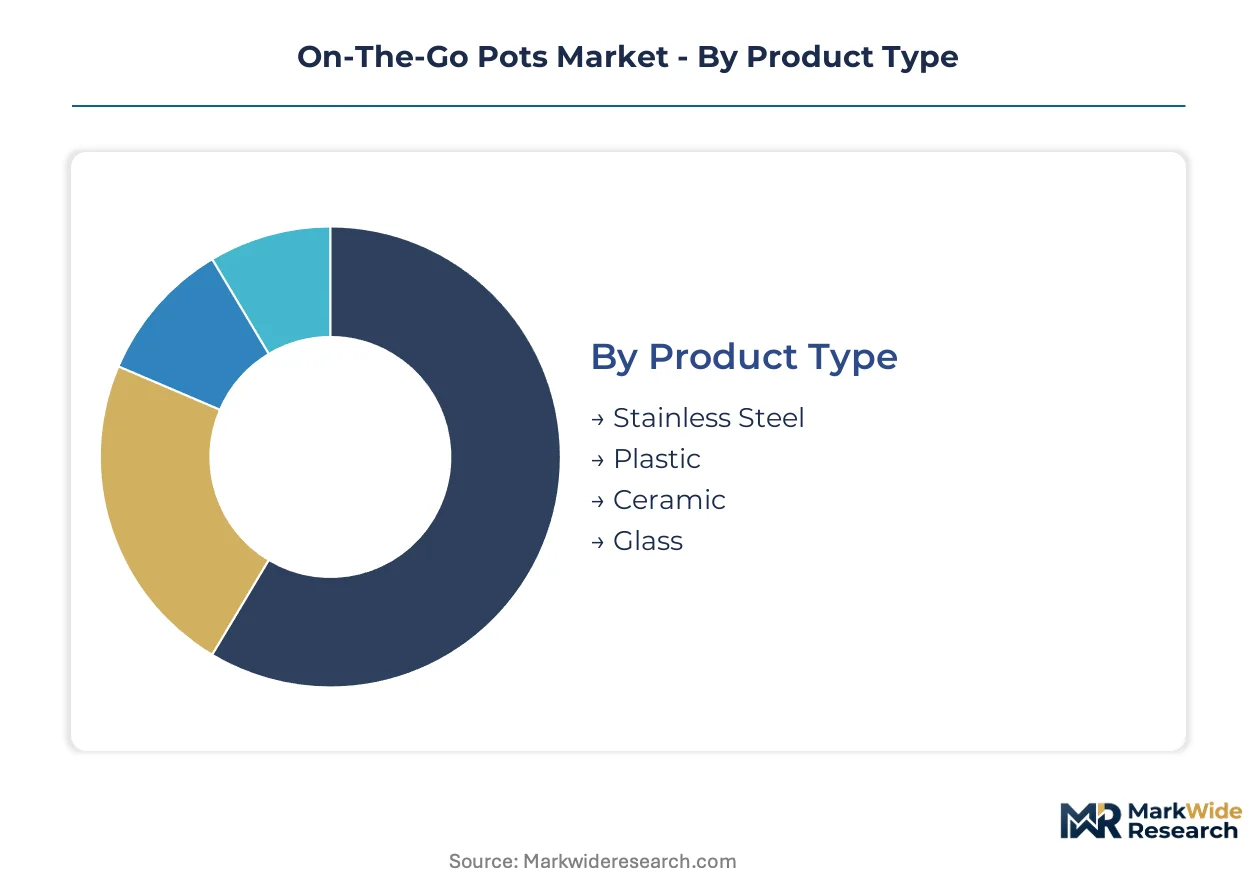
On-the-go pots fragment across four critical dimensions that determine material qualification burdens, thermal engineering specifications, and channel access requirements. Each segmentation axis carries distinct regulatory footprints and pricing architectures that shape supplier strategy.
Product Type:
FDA 21 CFR clearance dominates stainless steel and plastic variants, while ceramic and glass formats face additional CPSC breakage-testing protocols and state-level lead-content screening.
- Stainless Steel:Double-wall vacuum construction with 304 or 316 grade alloys delivers multi-hour thermal retention. Demand clusters among German outdoor enthusiasts and US meal-kit platforms specifying NSF-certified food-contact surfaces for professional segments.
- Plastic:Polypropylene and Tritan copolyester formulations dominate entry-level camping and student markets. REACH Annex XVII phthalate restrictions and FDA BPA-free mandates are forcing rapid reformulation toward bio-derived plasticizers with 15-25 percent raw material cost premiums.
- Ceramic:Glazed stoneware with silicone sleeve protection targets picnic aesthetics where microwave compatibility outweighs thermal performance. ANSM France and Health Canada maintain stricter lead-migration thresholds than US standards.
- Glass:Borosilicate construction with shock-resistant coatings serves short-haul commuter and pharmaceutical-adjacent cold-chain applications. EFSA migration testing for alkali and heavy-metal leaching adds fixed qualification costs.
Plastic sits at the top of the volume ranking, with stainless steel climbing the fastest.
Size:
Capacity tiers align with usage occasion duration and meal-complexity requirements, with certification burdens scaling nonlinearly above one-liter thresholds due to stacking-stability testing mandates.
- Small:0.3-0.5 liter single-serving formats for snack transport and pharmaceutical sample collection. Japanese METI compact-living standards and Korean MFDS portion-control labeling influence regional specifications.
- Medium:0.8-1.2 liter dual-use containers dominate urban commuter consolidation trends. German and Dutch direct-to-consumer channels capture disproportionate share as balcony gardeners alternate between plant cultivation and food transport.
- Large:1.5-2.0 liter family-format pots for tailgating and multi-person camping. Stackability geometry constraints force redundant mold investments across meal-kit platforms lacking interoperable dimensional standards.
- Extra Large:2.5+ liter catering and institutional formats with reinforced sealing mechanisms. BIS India and Saudi SFDA impose additional pressure-testing protocols for commercial food-service applications.
Medium formats command the steepest expansion trajectory as behavioral consolidation displaces specialized lunch-box categories.
Application:
End-use contexts determine thermal-retention specifications, leak-resistance engineering, and aesthetic positioning that together dictate margin structures and channel economics.
- Camping:Multi-day durability requirements favor stainless steel with carabiner-compatible lid attachments. Germany's outdoor recreation participation rates and sustainability mandates sustain premium pricing for repairable, modular constructions.
- Picnics:Presentation-driven demand elevates ceramic and glass formats with compartmentalized serving systems. French AGEC extended producer responsibility frameworks create first-mover advantages for suppliers with closed-loop take-back infrastructure.
- Tailgating:Large-capacity polymer formats with integrated utensil storage dominate US mass-market retail. NCAA and NFL licensing partnerships drive seasonal procurement cycles with concentrated Q3 order windows.
- Travel:Collapsible silicone hybrids and nesting sets address airline carry-on restrictions and hotel minibar compatibility. TSA liquid-container rules and EU cabin baggage dimension limits shape regional product development.
Camping anchors volume concentration, with travel applications gaining share fastest as business commuter patterns normalize.
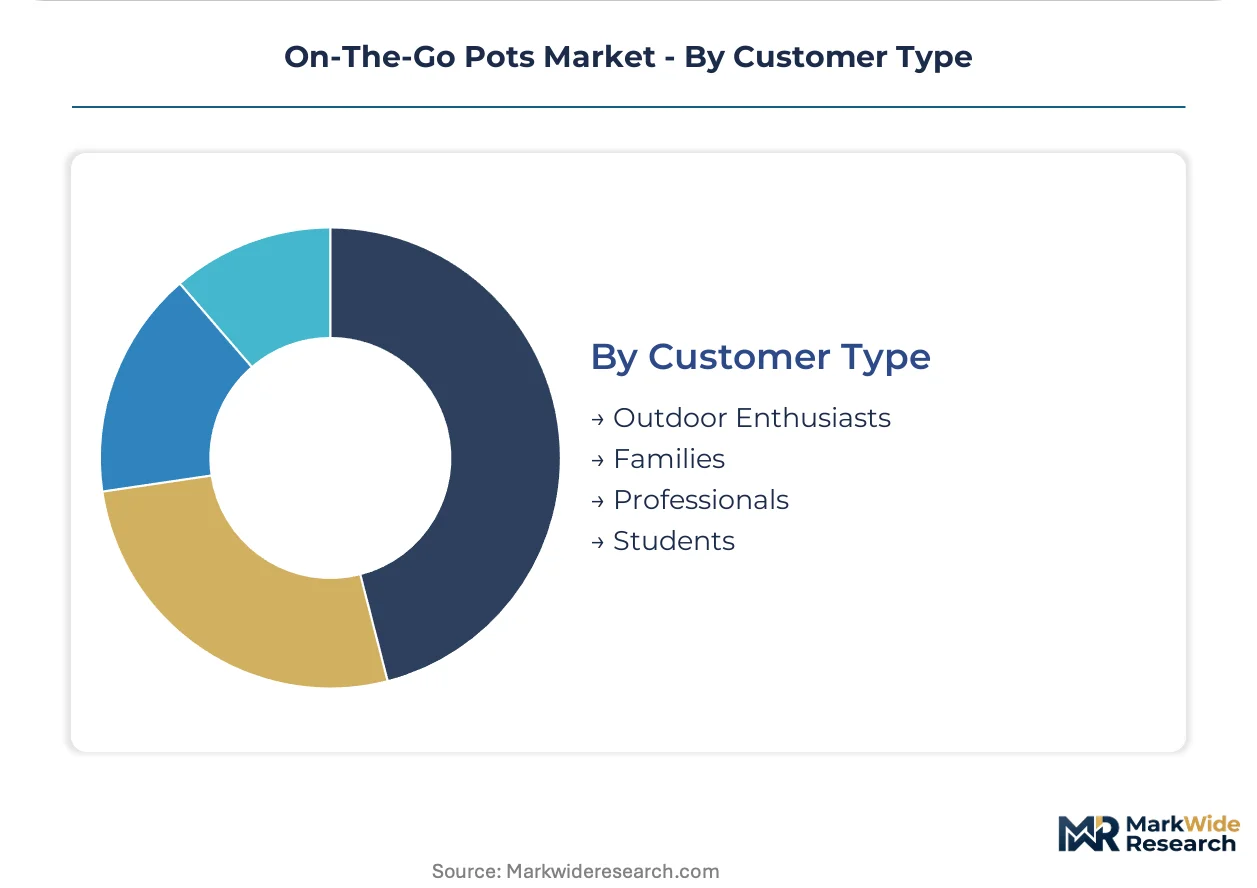
Customer Type:
Purchasing authority and price sensitivity diverge sharply across demographic segments, with institutional procurement emerging as a distinct channel requiring dedicated compliance documentation.
- Outdoor Enthusiasts:Durability prioritization drives stainless steel adoption with lifetime warranty expectations. REI and Decathlon private-label specifications are standardizing modular lid systems across European and North American supply chains.
- Families:Multi-person capacity requirements and dishwasher-safe mandates favor mid-tier polymer formats. Subscription meal-kit platforms are consolidating procurement volumes with standardized thermal-retention specifications for multi-hour delivery windows.
- Professionals:Aesthetic presentation and temperature stability across 8+ hour cycles command premium positioning. ESG procurement policies at financial and technology sector employers are mandating reusable format adoption with carbon-footprint documentation.
- Students:Extreme cost sensitivity sustains entry-level plastic dominance despite regulatory headwinds. Campus bookstore and quick-commerce channel fragmentation complicates brand-building economics.
Families represent the largest addressable base, with professionals showing the steepest willingness-to-pay expansion for certified sustainable formats.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands premium positioning through camping culture convergence with sustainability mandates, while the United States drives volume through meal-kit platform procurement standardization. Demand fragmentation across jurisdictions forces material suppliers to maintain parallel certification portfolios for FDA, EFSA, and REACH compliance.
United States
Meal-kit subscription services anchor procurement volumes with standardized thermal-retention specifications for multi-hour delivery windows. FDA 21 CFR direct food-contact material standards govern stainless steel and polymer qualification timelines. Pacific Northwest outdoor retailers concentrate demand for carabiner-compatible modular constructions among hiking enthusiasts.
Germany
Camping participation rates sustain premium pricing for durable, repairable portable containers across Bavarian and North Rhine-Westphalian markets. REACH Annex XVII phthalate restrictions accelerate transitions toward certified BPA-free polymer alternatives. Stuttgart industrial clusters specialize in double-wall vacuum insulation engineering for professional meal-prep segments.
France
Picnic-driven aesthetic demand elevates ceramic and glass formats with compartmentalized serving systems in Île-de-France and Provence-Alpes-Côte d'Azur. AGEC extended producer responsibility frameworks create first-mover advantages for suppliers with closed-loop take-back infrastructure. ANSM maintains stricter lead-migration thresholds than US standards for glazed stoneware.
Netherlands
Urban commuter consolidation around dual-use containers displaces specialized lunch-box categories in Randstad metropolitan corridors. ECHA mineral-based pigment mandates trigger reformulation investments in bio-derived plasticizers with raw material cost premiums. Amsterdam direct-to-consumer channels capture disproportionate share from traditional houseware retailers.
Japan
Compact-living standards under METI influence single-serving format specifications for snack transport and portion-controlled meal solutions. MFDS labeling requirements shape regional capacity tiering below one-liter thresholds. Nagoya industrial clusters specialize in shock-resistant borosilicate coatings for pharmaceutical-adjacent cold-chain applications.
On-The-Go Pots Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered pricing architectures. Market structure concentrates procurement authority among outdoor retailers and meal-kit platforms, compressing traditional wholesale relationships. Three archetypes dominate: European manufacturing-footprint generalists, durable-polymer expertise anchors, and design-led premium specialists. Competitive moves center on material qualification acceleration and garden-center channel pivots into portable lifestyle categories.
Among European-based fabricators, Scheurich Group and Keter Group exemplify distinct strategic positions. Scheurich leverages continental manufacturing infrastructure to serve retail chains transitioning into portable lifestyle categories. Keter anchors its market presence through polymer expertise originally developed for adjacent outdoor applications. Elho occupies the design-specialist tier, targeting urban consumers seeking dual-use portability across food transport and plant cultivation occasions.
| Leading Market Players |
|---|
| East Jordan Plastics |
| The Pot Company |
| Scheurich Group |
| Keter Group |
| Fiskars Group |
| Elho |
| HC Companies |
| Deroma Group |
| Bloem Living |
| Others |
Value Network & Pricing Analysis
Double-wall vacuum insulation engineering migrating from industrial thermos production into consumer-grade portable containers simultaneously compresses unit manufacturing costs and concentrates supply capability among German and Chinese industrial clusters with precision metalworking infrastructure. This technology diffusion tightens price competition in mid-tier stainless steel segments while elevating qualification barriers for polymer specialists lacking thermal engineering heritage.
Pricing Analysis
Capacity additions in Zhejiang Province are reshaping price floors for entry-level polymer pots as Chinese manufacturers achieve scale in BPA-free Tritan copolyester formulations. Three-tier pricing structure across premium, standard, and economy levels separates NSF-certified double-wall vacuum constructions from single-wall metal and basic polypropylene alternatives. Cost compression in student-targeted plastic tiers intensifies because propylene feedstock volatility passes through to contract manufacturers. Campus bookstore procurement exhibits extreme price sensitivity, while meal-kit platform buyers prioritize thermal-retention certification over unit cost.
Supply Chain Analysis
Closed-loop take-back programs emerging under France's AGEC law are creating reverse-logistics infrastructure that European suppliers leverage for customer lock-in. Manufacturing concentrates in China, Germany, and the Netherlands, with Stuttgart industrial clusters specializing in vacuum insulation engineering and Dongguan dominating polymer injection molding. Raw material procurement draws from 304/316 grade stainless steel mills, bio-derived plasticizer compounders, and borosilicate glass foundries. Single-source vulnerability in certified BPA-free polymer resin creates qualification bottlenecks. Distribution runs through outdoor retailer private-label specifications, meal-kit platform consolidated procurement, and direct-to-consumer channels capturing urban commuter demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The on-the-go pots market functions as a regulatory compounder where REACH Annex XVII phthalate restrictions and extended producer responsibility frameworks continuously elevate compliance investment requirements, compressing margin structures for undifferentiated suppliers while rewarding certified format specialists.
For Market Incumbents: Cement market position through accelerated FDA 21 CFR and EFSA dual-certification investments that freeze smaller competitors in pre-revenue inventory cycles. Deepen backward integration into bio-derived plasticizer supply to hedge REACH reformulation cost premiums. Defend against silicone collapsible format substitution by emphasizing multi-hour thermal retention performance in professional meal-prep segments. For New Entrants and Emerging Players: Launch via direct-to-consumer subscription models targeting Dutch and German urban balcony gardeners with dual-use pot formats that alternate between plant cultivation and food transport. Exploit white-space in pharmaceutical-adjacent cold-chain applications requiring borosilicate construction with shock-resistant coatings. Prioritize NFC-enabled temperature logging as a premium traceability tier for cold-chain meal delivery platforms. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier polymer specialists facing raw material cost premiums without brand equity to pass through pricing. Long-term viability hinges on certified recyclability documentation and closed-loop take-back infrastructure under impending EU material passport requirements. Monitor ECHA mineral-based pigment mandate implementation timelines as inflection indicators for reformulation investment intensity.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Material Reformulation | Accelerates transitions toward bio-derived plasticizers with 15-25 percent raw material premiums across German supply chains. |
| Garden-Center Channel Pivot | Captures dual-use demand from urban balcony gardeners alternating between plant cultivation and food transport occasions. |
| Smart Packaging Convergence | NFC-enabled temperature logging creates premium traceability tiers for cold-chain meal delivery platforms. |
| Extended Producer Responsibility Infrastructure | France's AGEC law creates first-mover advantages for suppliers with certified recyclability documentation. |
| Double-Wall Vacuum Insulation Scale-Up | Stuttgart industrial clusters specialize in thermal engineering that compresses performance gaps between metal and polymer tiers. |
Research Methodology
Bottom-up meal-kit platform and outdoor retailer procurement modeling reconciled against top-down polymer resin and stainless steel supply tracking forms the analytical core of this study. Primary interviews with category buyers at European garden-center chains, product development leads at meal-kit subscription services, procurement directors at outdoor retailers, and regulatory affairs specialists at polymer compounders were validated against secondary sources including FDA 21 CFR filings, ECHA REACH registration databases, EU Single-Use Plastics Directive implementation reports, and customs trade data for food-contact material imports.
Input-output matrices mapping raw material feedstock costs through manufacturing value-add stages to end-user price points structure the projection framework across the analysis window. Segmentation dimensions modeled include material type, capacity tier, application context, and customer archetype, with CAGRs derived from elasticity-adjusted demand curves and substitution scenario analysis. Forecast inputs incorporate REACH Annex XVII restriction timelines, meal-kit platform subscriber growth trajectories, and camping participation rate trends.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt polymer feedstock price spikes or accelerated EU material passport implementation. Practitioners should monitor ECHA mineral-based pigment mandate enforcement intensity and meal-kit platform thermal-retention specification standardization for early signals of competitive repositioning requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen Appliances
Digital BBQ Tongs and Thermometer Market
Kitchen Appliances
Malaysia Smart Kitchen Appliances Market
Kitchen Appliances
Italy Kitchen Appliances Market
Kitchen Appliances
Smart Induction Cooktop Market
Kitchen Appliances
Europe Electric Vegetable Chopper Market
Kitchen Appliances
Self-Heating Butter Knife Market
Kitchen Appliances
Residential Induction Cooktops Market
Kitchen Appliances
Global Portable Blenders Market
Kitchen Appliances
Household Kitchen Appliances Market
Kitchen Appliances
Induction Stove Market
Kitchen Appliances
Sandwich Maker Market
Kitchen Appliances
Sweden Kitchen Appliances Market
Kitchen Appliances
Europe Built-In Coffee Machine Market
Kitchen Appliances
Bakeware Market
Kitchen Appliances
Commercial Countertop Ranges Market
Kitchen Appliances
Toast Maker Market