
 Virtual Reality in Manufacturing Market | 2026-2036
Virtual Reality in Manufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
Virtual Reality in Manufacturing Market Analysis
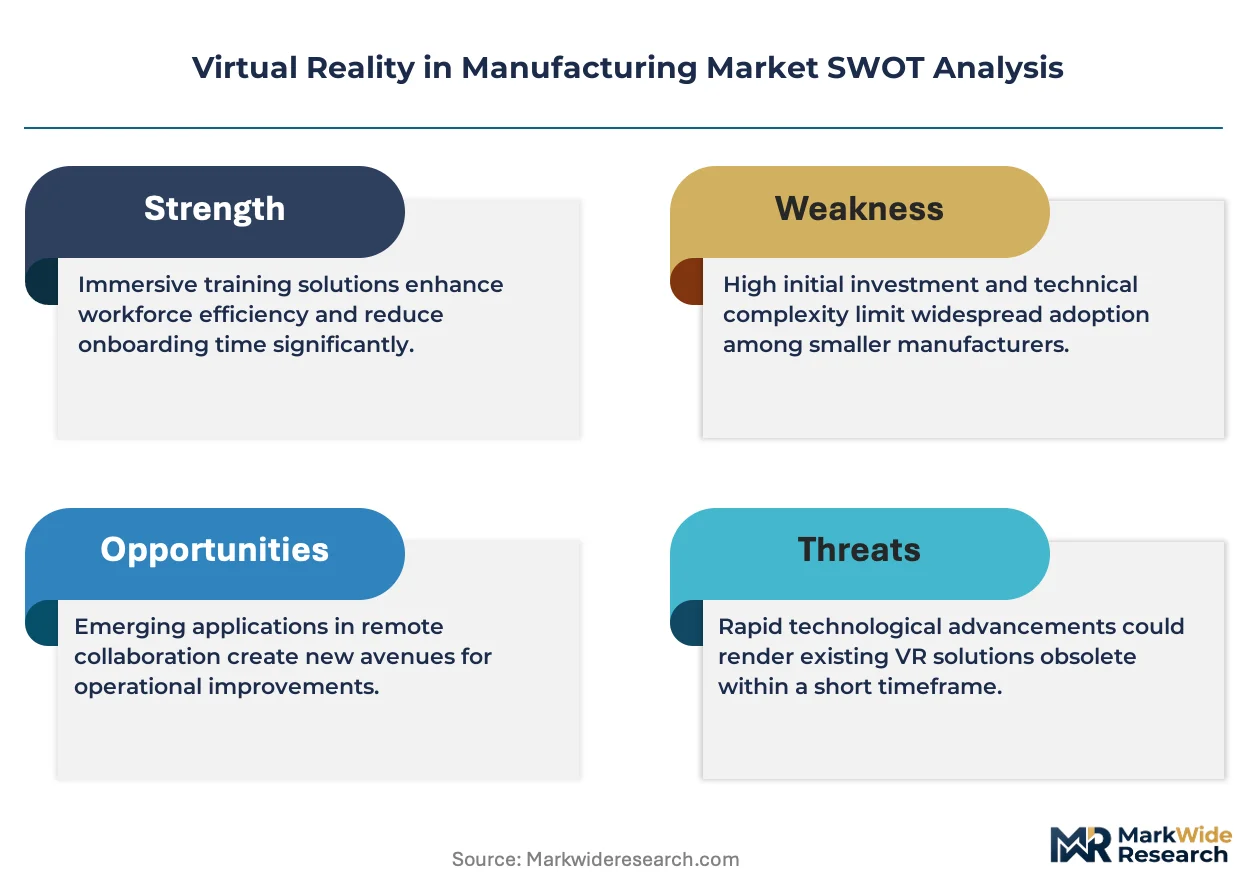
The EU Green Deal is rebalancing capital allocation across European manufacturing floors toward virtual prototyping and energy-efficient digital workflows. Microsoft leverages its mixed-reality industrial stack to anchor enterprise deployment in heavy-asset sectors. NVIDIA Corporation dominates GPU-accelerated simulation rendering for real-time factory digital twins. HTC Corporation specializes in precision tracking hardware for assembly-line training environments.
Virtual Reality in Manufacturing encompasses immersive hardware-software systems that generate computer-simulated three-dimensional environments with sub-20-millisecond motion-to-photon latency for industrial training, design validation, and remote maintenance operations. Hardware and VR Headsets lead current revenue as aerospace and automotive buyers refresh headset fleets for higher-resolution training modules. Enterprise Solutions capture expanding margin pools as pharmaceutical and electronics manufacturers adopt subscription-based immersive collaboration platforms for distributed engineering teams.
The EU AI Act and CE marking requirements for workplace equipment are tightening safety and interoperability standards for VR systems deployed on factory floors. OSHA in the United States enforces ergonomic and electrical safety protocols that shape headset design specifications for industrial settings. FDA guidance on VR-based medical device training creates adjacent compliance pathways that pharmaceutical end users must navigate. Stakeholders should monitor how evolving cybersecurity frameworks for operational technology networks redefine data governance requirements for cloud-connected immersive manufacturing platforms.
Market Dynamics
EU AI Act compliance deadlines and CE marking requirements for industrial workplace equipment are compressing vendor certification timelines while simultaneously accelerating replacement cycles for legacy headset fleets across automotive and aerospace assembly lines.
Growth Catalysts
- EU Green Deal digital-twin mandates:Brussels regulations now require virtual prototyping workflows for factories above certain emission thresholds, directly stimulating demand for immersive design-validation systems in German automotive supply chains.
- Aerospace pilot-training refresh cycles:Commercial aviation regulators in the United States and Europe are mandating higher-fidelity simulation environments, forcing carriers to upgrade VR-based cockpit training infrastructure on compressed schedules.
- GPU rendering acceleration:Real-time ray-tracing capabilities in next-generation graphics silicon are collapsing the latency gap between physical and virtual factory-floor visualization, enabling sub-20-millisecond motion-to-photon response for precision assembly tasks.
Market Restraints
- Display panel supply concentration:Micro-OLED and pancake-lens manufacturing capacity clusters in East Asian foundries, creating single-source vulnerability for high-resolution headset components destined for industrial training programs.
- OSHA ergonomic compliance costs:United States workplace safety protocols mandate extended comfort testing and electrical certification for headsets deployed in eight-hour manufacturing shifts, adding 14-18 months to product launch timelines.
- Flat-screen simulation persistence:Established CAVE systems and powerwall installations in automotive design studios resist full displacement, delaying pure-VR adoption where sunk capital in projection-based immersive rooms remains substantial.
Strategic Opportunities
- Pharmaceutical GMP training white space:FDA guidance on VR-based aseptic technique certification for sterile manufacturing operators remains underdeveloped, creating first-mover advantage for immersive platforms that document compliant training records.
- Electronics contract manufacturing penetration:Taiwanese and Vietnamese assembly houses serving Apple and Samsung supply chains currently underutilize immersive engineering collaboration, presenting expansion targets for remote-factory digital-twin platforms.
- 5G edge-compute convergence:Low-latency private cellular networks combined with localized GPU rendering pods are enabling untethered warehouse-scale VR for maintenance training without backpack computers or cable tethers.
Industry Challenges
- Industrial OT cybersecurity integration:Cloud-connected immersive platforms must navigate ISA/IEC 62443 segmentation requirements for operational technology networks, complicating real-time data synchronization between factory-floor sensors and remote VR visualization.
- Multidisciplinary talent scarcity:Deployment teams require simultaneous expertise in mechanical engineering workflows, real-time 3D engine optimization, and manufacturing safety protocols, a combination rarely found in single labor markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Virtual Reality in Manufacturing Market |
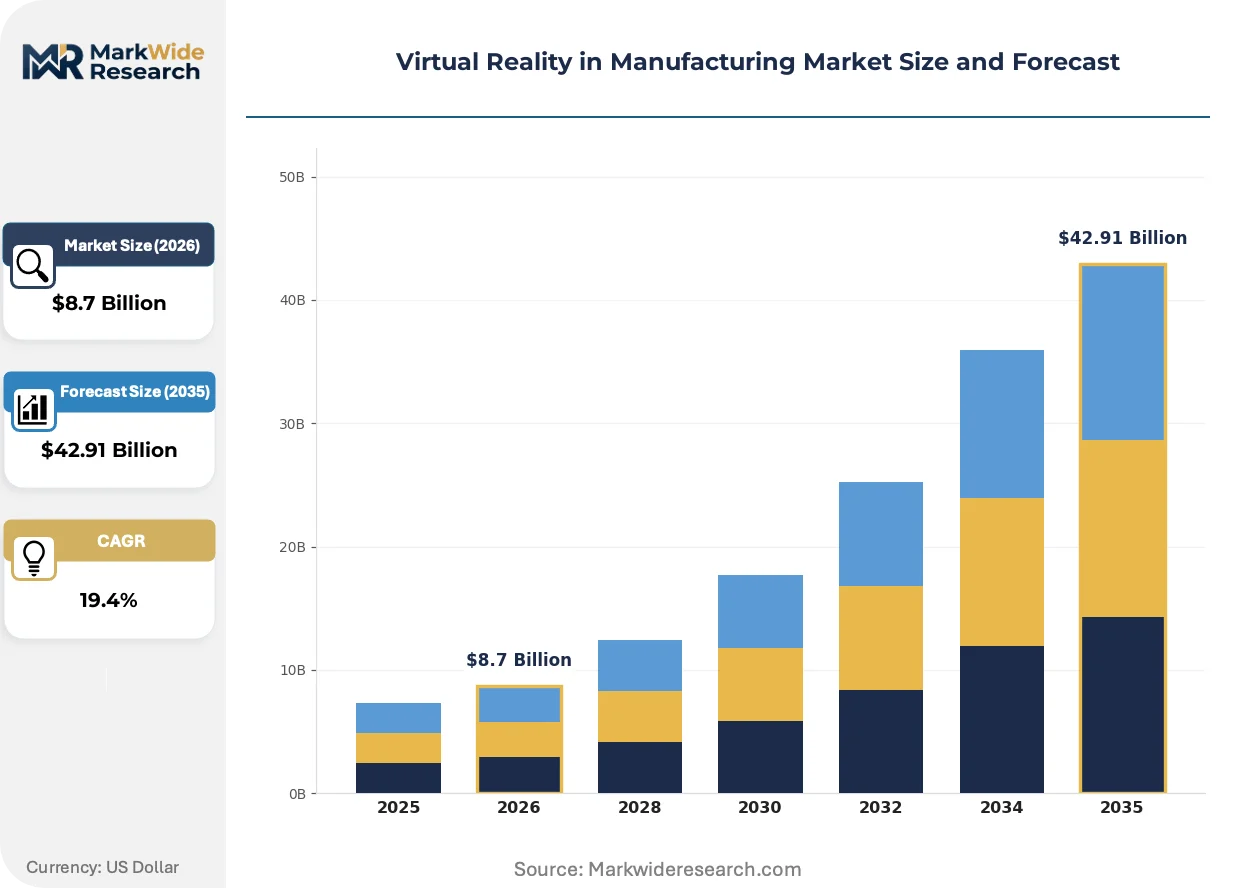
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $42.91 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Training, Simulation, Design Review, Maintenance Technology: Hardware, Software, VR Headsets, Motion Sensing End User: Aerospace, Automotive, Electronics, Pharmaceuticals Solution: Enterprise Solutions, Interactive Solutions, Visualization Tools, Prototyping Solutions |
| Companies Covered | Microsoft, Google, Sony, HTC Corporation, Meta, Unity Technologies, Samsung, NVIDIA Corporation, EON Reality, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Virtual Reality in Manufacturing Market Emerging Trajectories
Generative AI is collapsing content-creation bottlenecks for industrial digital twins while haptic feedback hardware advances toward force-feedback precision sufficient for assembly-line skill transfer.
Varjo's human-eye-resolution headsets are unifying optical see-through and full virtual-reality modes in single hardware platforms, allowing aerospace maintenance trainers to toggle between annotated physical equipment and completely simulated replacement scenarios without device swaps. German automotive OEMs now specify these mixed-reality systems for final assembly line-side training, compressing the traditional separation between classroom simulation and floor-based shadowing into contiguous immersive workflows.
REACH substance restrictions and impending RoHS amendments are forcing headset manufacturers to eliminate specific flame-retardant plastics and rare-earth magnet formulations from industrial-grade devices. The compliance burden falls heaviest on small-batch enterprise hardware specialists serving pharmaceutical cleanroom environments, where material purity documentation requirements intersect with electromagnetic compatibility testing for sensitive production equipment.
Buyer committees in heavy-asset sectors now require outcome-based validation metrics for immersive training investments, replacing traditional hardware procurement checklists with competency-assessment benchmarks tied to actual assembly error-rate reductions. This specification evolution disadvantages pure-hardware vendors while favoring integrated platform providers capable of delivering longitudinal skills-analytics dashboards, a pattern most visible in United States defense manufacturing where DFARS compliance documentation now extends to training-efficacy verification.
Virtual Reality in Manufacturing Market Segmentation
VR deployment in manufacturing splits across hardware intensity, software integration depth, and vertical-specific compliance requirements. Procurement committees evaluate segments through total-cost-of-ownership lenses rather than upfront capital expenditure alone.
Application:
Standardized training modules dominate procurement volumes, while bespoke design-review environments command premium engineering margins.
- Training:Structured competency programs for assembly-line operators and maintenance technicians leverage repeatable immersive scenarios. Aerospace OEMs in Germany and the United States refresh these systems on compressed regulatory cycles driven by FAA and EASA simulator mandates.
- Simulation:Physics-accurate digital twins replicate factory-floor dynamics for process optimization. Automotive manufacturers along Germany's industrial corridor deploy these for virtual commissioning of new production lines before physical build-out.
- Design Review:Collaborative spatial evaluation of CAD models enables distributed engineering teams to validate ergonomics and accessibility. Electronics manufacturers use these for early-stage enclosure and thermal design verification.
- Maintenance:Step-by-step guided repair procedures overlay animated instructions onto physical equipment. Pharmaceutical cleanroom operators access these for aseptic technique reinforcement without contamination risks.
Most installed capacity flows through Training. Expansion is steepest in Maintenance.
Technology:
Component sourcing strategies diverge between GPU-accelerated rendering stacks and precision tracking hardware.
- Hardware:Industrial-grade compute nodes, edge servers, and tethered backpack systems power warehouse-scale immersive environments. German automotive OEMs specify IP54-rated enclosures for assembly-line deployment.
- Software:Real-time 3D engines and factory-specific digital-twin platforms integrate with PLM and MES systems. Aerospace maintenance divisions demand these for airworthiness documentation traceability.
- VR Headsets:Sub-20-millisecond motion-to-photon latency devices with pancake optics and eye tracking dominate industrial procurement. Micro-OLED panel supply constraints from East Asian foundries limit fleet refresh velocity.
- Motion Sensing:Optical and inertial tracking systems capture operator limb position for assembly skill validation. Electronics contract manufacturers in Taiwan pilot these for precision hand-motion analysis.
Hardware captures the largest procurement budgets. Software is gaining share fastest.
End User:
Regulatory stringency and asset criticality shape adoption timelines across verticals.
- Aerospace:Pilot training and MRO simulation drive the highest-fidelity requirements. FAA and EASA mandates for recurrent training infrastructure compress replacement cycles for legacy simulator fleets.
- Automotive:Mixed-reality assembly training and virtual prototyping dominate capital allocation. German OEMs specify these systems for final line-side operator certification under EU Green Deal digital-twin requirements.
- Electronics:Cleanroom-compatible hardware and precision assembly guidance represent emerging demand pockets. Taiwanese and Vietnamese contract manufacturers remain underpenetrated relative to design-engineering intensity.
- Pharmaceuticals:Aseptic technique training and GMP compliance documentation create specialized procurement criteria. FDA guidance on VR-based sterile manufacturing certification remains underdeveloped.
Automotive deploys the most headset units. Pharmaceuticals shows the steepest expansion trajectory.
Solution:
Subscription-based platform economics are displacing perpetual-license procurement in enterprise accounts.
- Enterprise Solutions:Integrated hardware-software platforms with longitudinal analytics dashboards and skills-verification reporting. United States defense manufacturing mandates DFARS-compliant training-efficacy documentation.
- Interactive Solutions:Multi-user collaborative environments enabling real-time spatial annotation and remote expert guidance. Aerospace supply chains use these for distributed engineering review sessions.
- Visualization Tools:CAD-to-VR pipeline converters and factory-layout planners. Automotive studios employ these for ergonomic validation before physical mockup construction.
- Prototyping Solutions:Virtual-first design iteration platforms that reduce physical prototype counts. EU Green Deal emission thresholds directly stimulate demand in German supply chains.
Enterprise Solutions command the highest contract values. Prototyping Solutions are climbing fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial VR originated in United States aerospace and German automotive engineering halls during the 1990s simulation boom. Those two corridors remain the technology's commercial heartland. Expansion now radiates through East Asian electronics manufacturing and emerging South Asian contract assembly hubs.
United States
FAA mandates for recurrent pilot training and Pentagon DFARS compliance documentation drive defense and aviation procurement. OSHA ergonomic protocols extend product launch timelines but validate industrial-grade hardware for eight-hour manufacturing shifts. Boeing's Everett facility and Lockheed Martin's Fort Worth plant anchor immersive MRO simulation deployment.
Germany
EU Green Deal digital-twin requirements for emission-threshold factories force automotive supply chains into virtual prototyping workflows. CE marking and EU AI Act compliance compress vendor certification cycles for workplace VR equipment. Bavaria's Munich-Stuttgart industrial corridor concentrates Mittelstand supplier investment in mixed-reality assembly training.
China
MIIT smart-manufacturing initiatives and dual carbon goals accelerate digital-twin adoption in state-owned heavy industry. GB standards for workplace equipment safety create parallel certification tracks to Western regimes. Yangtze River Delta electronics contract manufacturers pilot precision hand-tracking for smartphone assembly guidance.
Japan
METI Society 5.0 automation roadmaps prioritize human-machine collaboration through immersive interfaces. JIS standards for industrial equipment interoperability shape procurement specifications for factory-floor VR systems. Toyota City and Nagoya's Chubu corridor lead automotive mixed-reality training integration with lean production workflows.
South Korea
MFDS guidance on medical device manufacturing training creates adjacent demand for pharmaceutical-grade immersive platforms. Government K-Semiconductor Belt investments subsidize smart-factory digital-twin infrastructure. Samsung's Suwon complex and Hyundai's Ulsan shipyards deploy warehouse-scale VR for maintenance technician certification.
Virtual Reality in Manufacturing Market Vendor Landscape
Capital-heavy GPU foundry operators compete with asset-light software platform designers for margin capture in industrial immersive systems. The vendor base stratifies across three tiers: cloud-scale platform integrators, specialized headset hardware fabricators, and vertical-specific simulation engine developers. Consolidation pressures concentrate in the middle tier as display panel supply constraints favor scaled procurement. Dominant competitive moves include strategic partnerships between semiconductor suppliers and industrial software vendors, plus geographic expansion into underpenetrated Asian electronics contract manufacturing.
Within the cloud-platform tier, Microsoft exemplifies enterprise integration depth through its mixed-reality industrial stack. NVIDIA Corporation anchors GPU-accelerated simulation rendering for real-time factory visualization. Among precision hardware specialists, HTC Corporation occupies a position representing industrial-grade tracking systems for assembly-line training environments.
| Leading Market Players |
|---|
| Microsoft |
| Sony |
| HTC Corporation |
| Meta |
| Unity Technologies |
| Samsung |
| NVIDIA Corporation |
| EON Reality |
| Others |
Supply Flow & Price Mechanics
EU Green Deal emission thresholds gate access to premium-tier immersive engineering contracts, restricting qualified supply to vendors with certified digital-twin platforms while compressing margins for uncertified hardware-only suppliers serving price-sensitive training-module buyers.
Pricing Analysis
Subscription-based platform licensing with outcome-based skills-verification reporting commands the dominant pricing architecture, separating integrated enterprise solutions from discrete hardware procurement. Price differentiation rests on CE marking tier and DFARS compliance documentation depth, with aerospace and defense manufacturing buyers absorbing premiums for longitudinal analytics dashboards. Cost compression in standard training-module hardware intensifies as East Asian electronics contract manufacturers enter with unbundled headset offerings. Pharmaceutical cleanroom operators exhibit the lowest price sensitivity due to GMP documentation requirements and FDA guidance uncertainty.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale automotive and aerospace buyer demand, while value-added resellers serve Mittelstand suppliers with bundled implementation services. Micro-OLED panel fabrication concentrates in South Korea and Taiwan, with pancake-lens assembly anchored in Chinese precision-optics clusters. Rare-earth magnet sourcing for precision tracking systems draws from Chinese separation facilities and Vietnamese downstream processing. Single-source vulnerability in high-resolution display substrates threatens fleet refresh schedules for German automotive OEMs. Distribution runs through certified industrial-technology distributors with CE marking and EU AI Act compliance verification capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Virtual Reality in Manufacturing Market functions as a stable compounder, with regulatory mandates for recurrent training infrastructure and virtual prototyping workflows generating predictable replacement-cycle revenue across aerospace and automotive end uses.
For Market Incumbents: Acquire specialized simulation engine developers with proven aerospace airworthiness documentation traceability. Consolidation of vertical-specific compliance expertise defends against cloud-platform entrants lacking FAA and EASA certification relationships. Backward integration into micro-OLED supply agreements mitigates East Asian foundry concentration risk. For New Entrants and Emerging Players: Taiwanese electronics contract manufacturers represent the most penetrable buyer archetype currently underserved by immersive engineering collaboration platforms. Precision hand-tracking for smartphone assembly guidance offers a narrow wedge with measurable ROI documentation. Partner with established industrial-technology distributors for CE marking compliance navigation rather than direct OEM sales cycles. For Investors and Strategic Acquirers: Roll-up economics work for vertical-specific training-content studios because pharmaceutical and electronics manufacturers demand bespoke GMP and cleanroom-compatible modules that resist pure-platform commoditization. Five-to-ten-year viability hinges on generative AI content-creation capabilities collapsing production costs. Monitor FDA guidance finalization on VR-based sterile manufacturing certification as the signal for pharmaceutical segment inflection.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Acceleration | EU AI Act deadlines compress vendor certification timelines for automotive supply chains. |
| GPU Rendering Partnership | NVIDIA silicon integration enables sub-20-millisecond latency for precision assembly tasks. |
| Pharmaceutical GMP Content Development | FDA guidance gaps create first-mover advantage for aseptic technique training platforms. |
| 5G Edge-Compute Deployment | Private cellular networks enable untethered warehouse-scale maintenance training without cable tethers. |
| East Asian Distribution Expansion | Taiwanese and Vietnamese contract manufacturers remain underpenetrated relative to design-engineering intensity. |
Methodological Framework
Bottom-up aerospace and automotive training-module modeling reconciled against top-down GPU-accelerated simulation rendering capacity tracking forms the analytical core. Primary interviews with immersive platform engineering directors, industrial safety compliance officers, and MRO training managers at German automotive OEMs and United States defense manufacturers combined with secondary validation from FAA simulator mandate documentation, EASA certification databases, EU Green Deal implementation guidelines, and SEC filings from semiconductor suppliers. Triangulation across supply-side component forecasts and demand-side procurement pipeline assessments ensures segment-level precision.
Historical trendline analysis of headset fleet replacement cycles and digital-twin adoption curves informed the projection framework across the analysis window. Segmentation dimensions modeled include application type, technology stack, end-user vertical, and solution architecture, with additional granularity on regulatory compliance tier. CAGRs derived from regression analysis of correlated industrial automation spending patterns and immersive technology penetration rates. Industry-specific forecast inputs encompass EU AI Act implementation phasing and FAA recurrent training mandate refresh schedules.
Underlying measurement precision varies by segment; aerospace pilot training and German automotive OEM procurement carry tighter precision than emerging pharmaceutical and electronics contract manufacturing adoption. Forecasts reflect assumptions regarding regulatory deadline adherence, display panel supply normalization, and generative AI content-creation velocity. Periodic stress-testing of base assumptions against CE marking enforcement intensity and OSHA ergonomic protocol updates is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Virtual Reality (VR) and Augmented Reality (AR)
Commercial Augmented Reality Glasses Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Augmented Reality Headsets Market
Virtual Reality (VR) and Augmented Reality (AR)
Europe Augmented Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
3D Telepresence Market
Virtual Reality (VR) and Augmented Reality (AR)
Automotive Augmented Reality (AR) HUD System Market
Virtual Reality (VR) and Augmented Reality (AR)
VR HMD Shipment Market
Virtual Reality (VR) and Augmented Reality (AR)
Mobile Virtualization Market
Virtual Reality (VR) and Augmented Reality (AR)
Asia-Pacific Augmented Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
US Augmented and Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Internet of Senses Market
Virtual Reality (VR) and Augmented Reality (AR)
Augmented Reality Book Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Location-Based Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
AR Glasses Market
Virtual Reality (VR) and Augmented Reality (AR)
Data Glove Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Visor Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Industrial AR Platforms Market