
 China Kitchen Appliances Market | 2026-2036
China Kitchen Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
China Kitchen Appliances Market Outlook
Urban residential households is bifurcating from price-sensitive rural buyers as the dominant growth archetype in China's kitchen appliance landscape. Haier Group leverages its smart-home ecosystem to anchor premium refrigerator sales in coastal megacities. Robam Appliances specializes in high-end range hood systems for luxury apartment developers. Midea Group competes across multiple price tiers while sustaining manufacturing scale advantages in Guangdong province.
China kitchen appliances comprise electrically powered domestic and semi-commercial equipment designed for food storage, preparation, cooking, and cleaning, typically operating at 220V/50Hz with energy efficiency grades certified under China's national standard GB 12021.2 for refrigeration products. Refrigerators occupy the largest revenue pool among product types due to mandatory replacement cycles and rising cold-chain expectations in residential kitchens. Smart appliances represent the fastest-expanding technology segment as MIIT IoT certification and voice-control integration reshape consumer expectations. Energy-efficient appliances command widening price premiums following NEEA label tightening and provincial subsidy programs.
China's national standard GB 12021.2 and MIIT IoT interoperability rules shape product design and market access for kitchen equipment sold domestically. SAMR enforces compulsory certification under CCC marks for electrical safety compliance across all appliance categories. GB standards on standby power and refrigerant phase-down under MEE directives force manufacturers toward inverter compressor and natural refrigerant transitions. Stakeholders must monitor provincial subsidy renewal schedules and NEEA efficiency tier migrations to time inventory and pricing decisions.
Market Dynamics
MIIT IoT certification mandates and NEEA efficiency tier migrations are compressing replacement cycles and forcing manufacturers toward inverter compressor architectures across China's coastal manufacturing belts.
Growth Catalysts
- Dual carbon policy framework:China's national carbon neutrality targets accelerate provincial subsidy programs for Grade 1 and Grade 2 efficiency appliances, pulling forward refrigerator and range hood replacements in tier-one cities.
- Smart-home ecosystem integration:Voice-control protocols and unified app platforms are standardizing across new residential developments, embedding kitchen appliances within whole-home automation architectures.
- Built-in appliance penetration:Luxury apartment developers in Shanghai and Shenzhen specify integrated refrigerator and cooking systems, creating specification-driven demand independent of retail replacement cycles.
Market Restraints
- Copper and rare-earth magnet volatility:Inverter compressor production depends on neodymium supply concentrated in Inner Mongolia processing facilities, exposing margins to raw material cost swings.
- GB 12021.2 compliance friction:NEEA label tightening forces simultaneous redesign of refrigerant chemistry and insulation foam formulations, extending product development timelines.
- Standalone small-format retail:Compact induction cookers and portable refrigeration units from cross-border e-commerce platforms substitute for built-in system upgrades among price-sensitive renters.
Strategic Opportunities
- Central and western provincial expansion:Chengdu and Xi'an residential markets show underpenetration of built-in range hood systems relative to coastal saturation levels.
- Natural refrigerant transition:R290 propane adoption aligns with MEE directives on HFC phase-down, creating first-mover positioning for manufacturers retooling compressor lines ahead of mandatory deadlines.
- Voice-AI convergence:Integration of Tmall Genie and Baidu DuerOS platforms enables predictive maintenance and consumables replenishment, shifting revenue toward recurring service attach rates.
Industry Challenges
- Embedded systems firmware talent:Appliance manufacturers compete with automotive and consumer electronics sectors for IoT security and edge-computing engineers in Guangdong and Jiangsu labor markets.
- CCC certification backlog:SAMR testing facility capacity constraints delay new product introductions, compressing selling seasons for seasonal appliance categories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Kitchen Appliances Market |
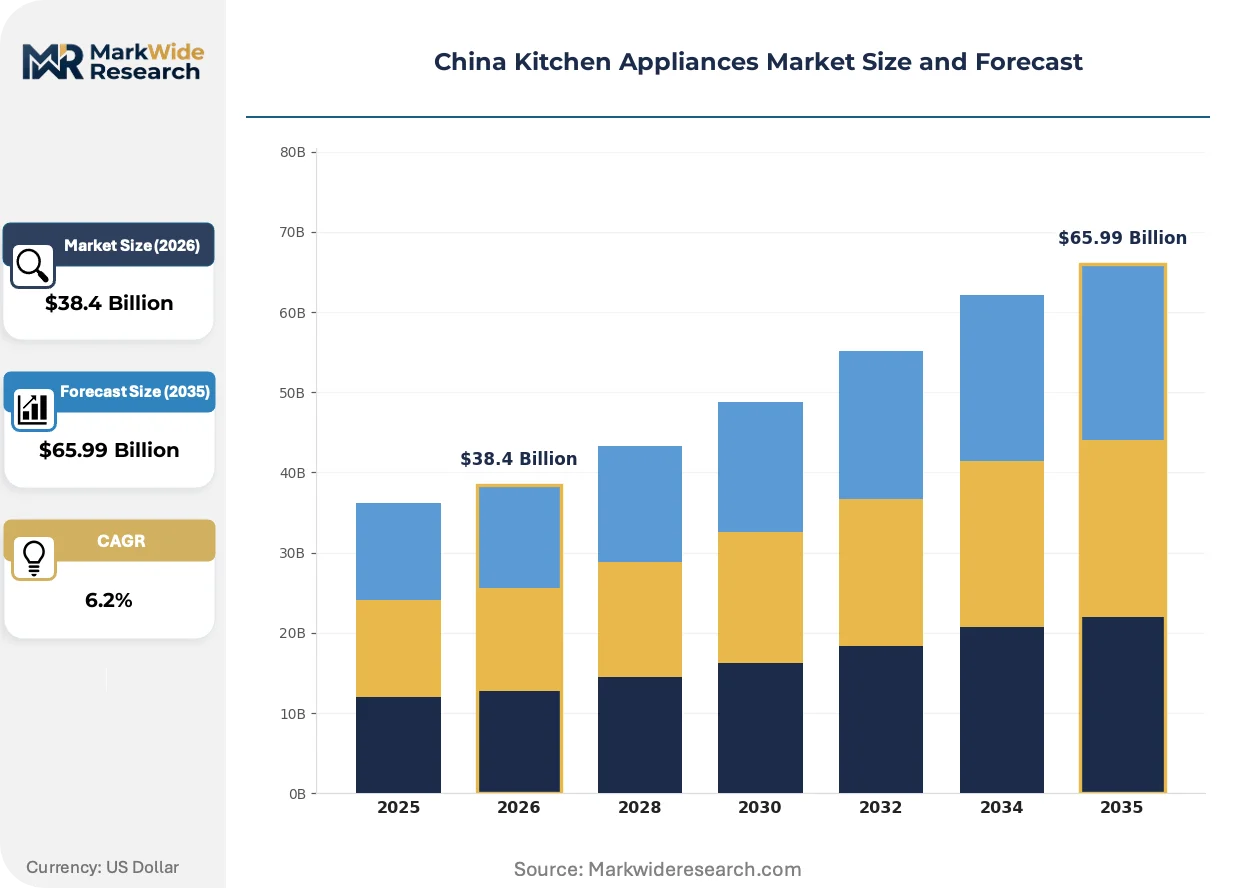
| Market Size in 2026 | $38.4 Billion |
| Market Size in 2035 | $65.99 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refrigerators, Ovens, Ranges, Dishwashers End User: Residential, Commercial, Catering Services, Hotels Technology: Smart Appliances, Conventional Appliances, Energy-Efficient Appliances, Built-in Appliances Distribution Channel: Online Retail, Specialty Stores, Department Stores, Wholesalers |
| Companies Covered | Hisense Group, Robam Appliances, Haier Group, Supor, Fotile Group, Midea Group, TCL Electronics Holdings Limited, Joyoung, Gree Electric Appliances, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Kitchen Appliances Market Strategic Shifts
Refrigeration architecture and control interfaces are fragmenting as manufacturers pursue divergent paths to efficiency compliance and smart-home integration, creating incompatible ecosystem lock-ins.
Inverter compressor technology is decomposing traditional fixed-speed refrigeration into variable-capacity systems that match cooling output to thermal load. Tier-one city households upgrading from mandatory-replacement programs specify inverter models at accelerating rates. This transition is decomposing the historical price-performance tradeoff between premium and standard tiers, collapsing margin structures for manufacturers dependent on volume-scale fixed-speed production.
MEE refrigerant phase-down directives under amended GB standards force R410A and R134a exit timelines, accelerating R290 and R600a adoption in domestic refrigeration. Compressor seal engineering and charge-size limitations dominate product redesign priorities. Guangdong-based manufacturers face the steepest retooling capex requirements given their concentration in legacy refrigerant platforms.
Appliance-as-service bundling is emerging among property management platforms in Shenzhen and Hangzhou, where developers lease rather than sell built-in kitchen systems to residential tenants. Subscription models displace upfront retail purchases in premium rental segments. This pattern concentrates most visibly in managed apartment complexes targeting mobile professional households.
China Kitchen Appliances Market Segmentation
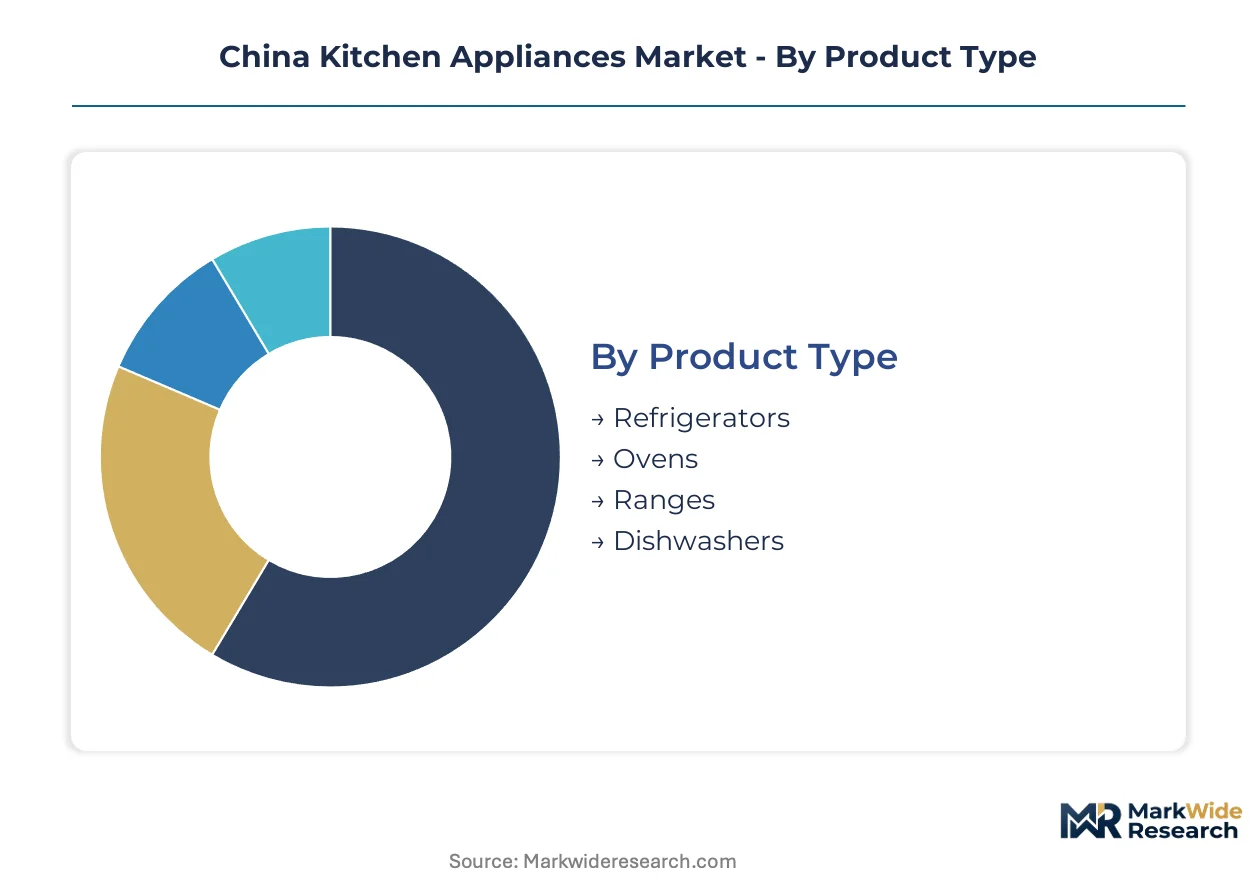
Segmentation in China's kitchen appliance market reflects divergent compliance burdens and channel economics. NEEA efficiency tiers and MIIT IoT certification reshape profitability differently across product categories and end-use applications.
Product Type:
GB 12021.2 efficiency mandates and refrigerant phase-down timelines create asymmetric compliance costs across product categories.
- Refrigerators:Mandatory replacement cycles and cold-chain expectations anchor the largest revenue pool. Shanghai and Beijing households upgrading under provincial subsidy programs specify inverter compressor models with Grade 1 efficiency labels, compressing margins for fixed-speed manufacturers concentrated in Guangdong.
- Ovens:Built-in electric and steam-combination units gain specification in luxury apartment developments. Shenzhen developers specify European-format compact ovens for premium rental inventory, creating demand independent of retail replacement cycles.
- Ranges:Gas and induction cooking systems face divergent installation requirements across municipal gas infrastructure availability. Chengdu residential markets show underpenetration of integrated range systems relative to coastal saturation.
- Dishwashers:Penetration remains concentrated in tier-one cities where water efficiency regulations and kitchen footprint constraints align. Compact countertop units from cross-border platforms substitute for built-in upgrades among price-sensitive renters.
Established volume favors refrigerators; emerging adoption favors ovens.
End User:
Customer type determines pricing power through specification authority and replacement cycle predictability.
- Residential:Urban households in tier-one cities drive premium built-in system demand. Dual carbon subsidies pull forward replacements among mortgage-backed buyers in Beijing and Shenzhen.
- Commercial:Restaurant chains and food service operators prioritize durability and service network density over efficiency premiums. Procurement concentrates through Guangdong-based wholesale channels with volume pricing structures.
- Catering Services:Central kitchen operations and institutional food preparation require semi-commercial equipment with 220V/50Hz compatibility and rapid service response. MEE refrigerant directives force simultaneous fleet-wide upgrades.
- Hotels:International brand standards and local procurement cost targets create tension in specification decisions. Managed apartment platforms in Hangzhou experiment with appliance-as-service leasing models.
Residential customers deliver margin stability; hotel procurement delivers volume concentration.
Technology:
Certification requirements fragment competitive positioning across efficiency and connectivity tiers.
- Smart Appliances:Voice-control integration via Tmall Genie and Baidu DuerOS platforms enables predictive maintenance revenue. MIIT IoT certification mandates create compliance bottlenecks for firmware development teams.
- Conventional Appliances:Fixed-speed refrigeration and basic cooking functions serve price-sensitive rural markets and rental property inventory. Manufacturers dependent on volume-scale production face margin compression from inverter transitions.
- Energy-Efficient Appliances:Grade 1 and Grade 2 NEEA labels command widening price premiums following provincial subsidy program expansions. Natural refrigerant transitions under MEE directives accelerate R290 adoption in compressor redesigns.
- Built-in Appliances:Integrated refrigerator and cooking systems specified by luxury developers in Shanghai and Shenzhen. Installation complexity and service network requirements create barriers for pure-play manufacturers.
Conventional technology retains rural volume; smart connectivity gains share fastest in coastal megacities.
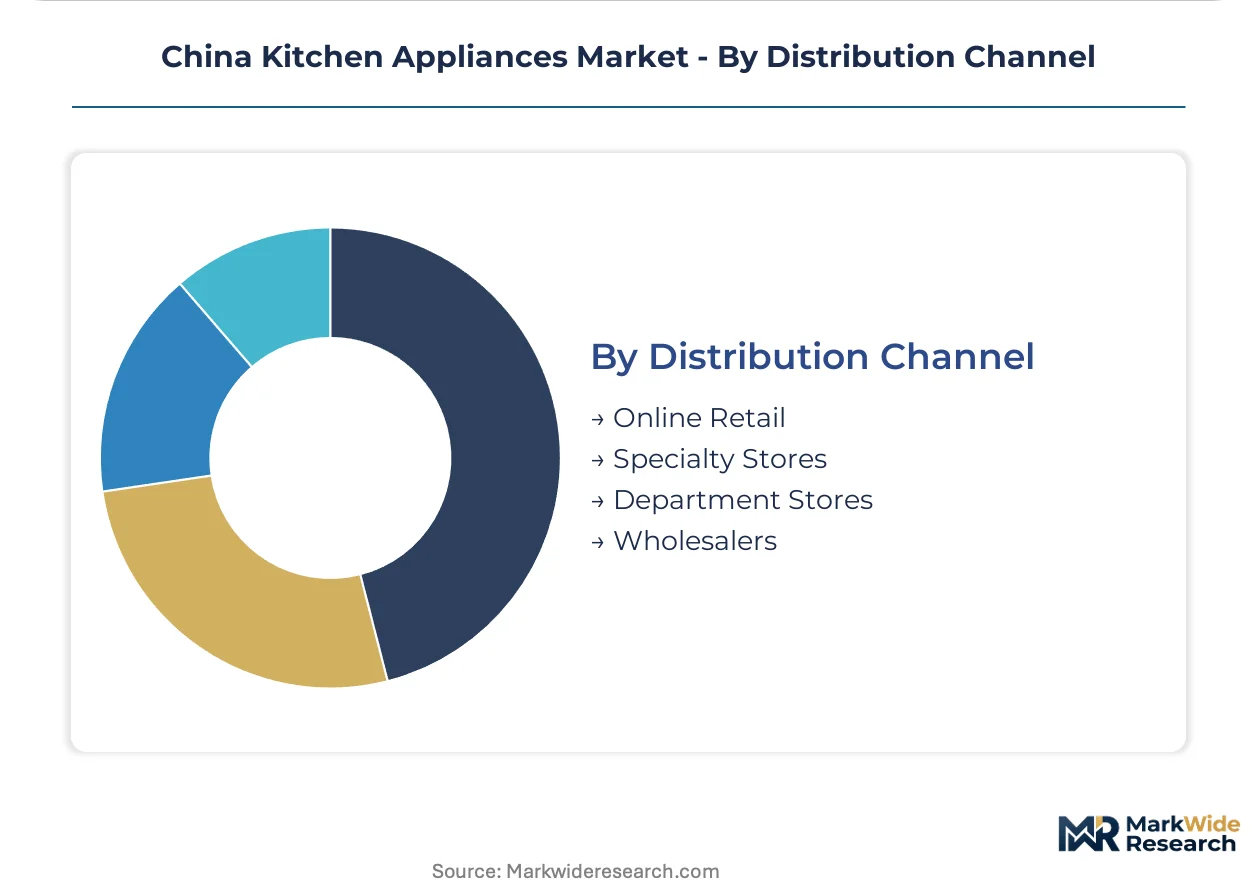
Distribution Channel:
Channel economics reflect divergent customer acquisition costs and installation service requirements.
- Online Retail:Tmall and JD.com platforms dominate standard appliance sales with logistics integration into tier-two and tier-three cities. Voice-AI convergence enables predictive consumables replenishment.
- Specialty Stores:Built-in system demonstrations and kitchen design consultation anchor premium transactions. Robam and Haier operate flagship locations in Shanghai and Beijing with specification authority for luxury developments.
- Department Stores:Mid-tier appliance sales face compression from online price transparency. Remaining relevance concentrates in gift-market seasonal purchasing and immediate delivery convenience.
- Wholesalers:Guangdong-based distributors serve commercial and catering procurement with volume pricing and service bundling. CCC certification documentation requirements create procurement friction for smaller operators.
Online channels capture geographic expansion; specialty stores capture specification-driven premium transactions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese manufacturers export kitchen appliances primarily to Southeast Asian markets, with Vietnam and Thailand absorbing significant volumes of refrigeration equipment and induction cooking systems.
Shanghai
Luxury residential developments specify built-in refrigerator and cooking systems at rates exceeding national averages. Municipal efficiency mandates under NEEA Grade 1 labeling accelerate replacement cycles among mortgage-backed households. Lujiazui and Pudong districts concentrate specification authority for premium appliance procurement.
Beijing
Dual carbon subsidy programs pull forward refrigerator replacements in established residential compounds. SAMR certification requirements create compliance friction for new product introductions. Chaoyang and Haidian districts anchor retail distribution networks for smart-connected kitchen systems.
Shenzhen
Property management platforms experiment with appliance-as-service leasing models in managed apartment complexes. MIIT IoT certification mandates standardize voice-control integration across new developments. Nanshan district hosts firmware development clusters for smart-home ecosystem integration.
Chengdu
Underpenetration of built-in range hood systems relative to coastal saturation creates expansion opportunities for specification-driven sales. Provincial subsidy programs extend NEEA efficiency incentives to western markets. High-tech Zone manufacturing parks attract component suppliers for regional distribution.
Guangdong Province
Manufacturing scale advantages concentrate compressor production and final assembly operations across the Pearl River Delta. MEE refrigerant phase-down directives force retooling investments in legacy production lines. Foshan and Zhongshan industrial clusters face steepest compliance costs from natural refrigerant transitions.
China Kitchen Appliances Market Competitive Environment
Player mix skews toward diversified home-appliance conglomerates with captive manufacturing infrastructure. Market structure exhibits tiered consolidation, with premium built-in segments commanding specification-driven pricing power while standard-tier categories face margin compression from scale competition. Three archetypes dominate: ecosystem-integrated smart-home platforms, specialized cooking-system fabricators, and volume-scale diversified manufacturers. Competitive dynamics center on backward integration into compressor production and strategic partnerships with property developers for pre-installation specification.
Among ecosystem-integrated platforms, Haier Group and Midea Group occupy positions that exemplify whole-home automation strategies. Robam Appliances represents the specialized fabricator archetype, anchoring premium range hood specification in luxury residential developments. These three companies illustrate divergent paths to market positioning—ecosystem breadth versus cooking-system depth versus manufacturing scale.
| Leading Market Players |
|---|
| Hisense Group |
| Robam Appliances |
| Haier Group |
| Supor |
| Fotile Group |
| Midea Group |
| TCL Electronics Holdings Limited |
| Joyoung |
| Gree Electric Appliances |
| Others |
Value Chain & Pricing Dynamics
Long-term capacity reservation contracts between Guangdong compressor manufacturers and Pearl River Delta assembly plants lock in neodymium magnet supply and insulate NEEA Grade 1 refrigerator pricing from rare-earth volatility. These arrangements tie inverter compressor availability to tier-one city subsidy program timing, embedding procurement flexibility into municipal efficiency mandates.
Pricing Analysis
Fixed-speed to inverter compressor pricing gaps are collapsing as NEEA label tightening accelerates technology transitions. Pricing stratifies across premium smart-connected, standard inverter, and economy fixed-speed tiers, with Grade 1 efficiency certification commanding widening premiums under provincial subsidy programs. Cost compression in economy tiers is intensifying because cross-border portable units substitute for built-in upgrades among price-sensitive renters. Commercial catering buyers show highest price sensitivity due to volume procurement and service network density requirements; luxury apartment developers exhibit lowest sensitivity through specification-driven pre-installation contracts.
Supply Chain Analysis
Inventory buffers for R290 refrigerant compressors stretch lead times as Guangdong manufacturers retool legacy R410A lines under MEE phase-down directives. Supply concentrates in China for compressor production, South Korea for inverter control modules, and Japan for precision sensors. Raw material dependencies center on Inner Mongolia neodymium processing, Jiangsu copper winding supply, and Zhejiang steel cabinet fabrication. Single-source vulnerability in rare-earth magnet supply exposes margins to processing facility disruptions. Distribution runs through Tmall and JD.com logistics networks for retail, with specialty store channels handling built-in system installation and after-sales service bundling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's kitchen appliance market demands substitution defense against cross-border portable refrigeration and cooking units that erode built-in system upgrades among urban renters. Incumbents must neutralize this threat while capturing efficiency-driven replacement cycles.
For Market Incumbents: Compound backward integration into inverter compressor production to secure neodymium supply and compress fixed-speed competitor margins. Lock in specification authority with Shanghai and Shenzhen luxury developers through appliance-as-service leasing pilots. Neutralize cross-border portable substitution by embedding voice-AI predictive maintenance into premium tiers, shifting revenue toward recurring service attach rates that portable units cannot replicate.
For New Entrants and Emerging Players: Anchor in Chengdu and Xi'an built-in range hood underpenetration, where coastal saturation levels have not yet reached specification-driven procurement. Target commercial catering services with semi-commercial equipment bundling rapid service response and 220V/50Hz compatibility. Enter through Guangdong wholesale channel partnerships with volume pricing structures and CCC certification documentation support.
For Investors and Strategic Acquirers: Capital is best deployed toward ecosystem-integrated smart-home platforms with captive compressor manufacturing and MIIT IoT certification completion. Long-term viability hinges on natural refrigerant transition readiness and firmware development talent retention in Nanshan and Hangzhou clusters. Monitor provincial subsidy renewal schedules as the inflection signal—expiration or expansion directly pulls forward or compresses replacement cycle revenue.
| Strategic Initiative | Industry Significance |
|---|---|
| Inverter Compressor Backward Integration | Captive neodymium supply from Inner Mongolia processors secures margin control against rare-earth volatility. |
| R290 Natural Refrigerant Retooling | MEE phase-down compliance ahead of mandatory deadlines creates first-mover positioning in Guangdong production clusters. |
| Voice-AI Platform Integration | Tmall Genie and Baidu DuerOS convergence enables predictive maintenance revenue shifting from transactional hardware sales. |
| Appliance-as-Service Leasing | Shenzhen property management platforms displace upfront retail purchases in premium rental segments through subscription bundling. |
| Central and Western Provincial Expansion | Chengdu and Xi'an underpenetration of built-in systems creates specification-driven sales growth outside coastal saturation. |
Study Parameters
Operator-level perspectives from appliance manufacturing executives, provincial subsidy program administrators, luxury apartment development procurement leads, and MIIT certification engineers anchored the qualitative base. Primary interview findings combined with secondary validation from SAMR CCC certification databases, NEEA efficiency tier migration schedules, MEE refrigerant directive filings, and Pearl River Delta customs export records. Bottom-up segment sizing triangulated against top-down macroeconomic consumption indicators across the analysis window.
Sensitivity analysis tested forecast robustness across refrigerant phase-down timeline scenarios and provincial subsidy renewal assumptions. The modeling framework disaggregated volume and value outputs by product type, technology tier, end-use application, and distribution channel across the projection horizon. CAGRs derived from replacement cycle elasticity estimates, efficiency mandate compliance cost curves, and smart-home penetration diffusion rates. Inverter compressor adoption curves and natural refrigerant transition capex schedules served as industry-specific forecast inputs.
Decision-makers should treat outputs as directional under assumptions of continued NEEA label tightening and MIIT IoT certification enforcement; material deviation in subsidy program continuity or rare-earth supply disruption would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen Appliances
Induction Stove Market
Kitchen Appliances
Electric Pressure Cooker Market
Kitchen Appliances
Smart Kitchen Appliances Market
Kitchen Appliances
Portable Sandwich Maker Market
Kitchen Appliances
Built-In Coffee Machine Market
Kitchen Appliances
North America Electric Vegetable Choppers Market
Kitchen Appliances
Electric Lunch Box Market
Kitchen Appliances
Household Cooking Appliance Market
Kitchen Appliances
Germany Kitchen Appliances Market
Kitchen Appliances
Built-In Kitchen Appliances Market
Kitchen Appliances
Household Bread Machine Market
Kitchen Appliances
Toaster Market
Kitchen Appliances
Residential Induction Cooktops Market
Kitchen Appliances
Portable Outdoor Pizza Oven Market
Kitchen Appliances
Global Single Serve Coffee Maker Market
Kitchen Appliances
Kitchen Knife Market