
 Brazil Data Center Power Market | 2026-2036
Brazil Data Center Power Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Data Center Power Market Insights
Software-defined power management is expanding how vendors monetize data center infrastructure, shifting contracts from hardware sales to subscription-based uptime guarantees. Schneider Electric leverages its integrated EcoStruxure platform to anchor large-scale deployments across Brazilian financial hubs. Vertiv competes through thermal-electrical co-design capabilities that sustain density thresholds in tropical climates. Siemens Energy specializes in gas-to-power integration for facilities seeking grid independence in constrained regions.
Data center power encompasses the generation, conditioning, distribution, and backup systems that maintain continuous electrical supply to server environments, typically operating at voltages from 480V downstream to 208V rack-level with redundancy architectures ranging from N+1 to 2N configurations. Its primary purpose is eliminating downtime in digital infrastructure where interruption costs exceed hardware replacement values by orders of magnitude. Colocation providers now drive the largest volume demand as enterprises outsource critical facility ownership. Edge deployments represent the fastest-expanding segment, though absolute capacity remains dwarfed by hyperscale commitments exceeding ten megawatts per site. Diesel backup retains dominant installed share despite regulatory pressure, while renewable power purchase agreements capture expanding margin pools from sustainability-linked financing.
ANEEL governs grid interconnection standards and renewable energy certification that determine which power sources qualify for corporate clean energy claims. INMETRO efficiency labeling and ABNT technical standards shape equipment procurement specifications for domestic installation. ANATEL's telecom infrastructure rules indirectly constrain data center siting decisions through fiber access requirements. Stakeholders must monitor how upcoming carbon disclosure mandates from Brazil's central bank reshape lender risk assessments for fossil-dependent facilities.
Market Dynamics
Hyperscale cloud operators are consolidating facility footprints across São Paulo and Rio de Janeiro, compressing procurement timelines and forcing power infrastructure vendors into long-term service contracts rather than equipment-only sales.
Growth Catalysts
- ANEEL renewable energy incentives:Feed-in tariffs and net metering rules redirect data center procurement toward hydroelectric and solar architectures, qualifying facilities for green financing.
- Hyperscale colocation demand:Financial services and e-commerce operators are outsourcing critical facility ownership to specialized providers operating ten-megawatt-plus sites.
- Lithium-ion battery chemistry:Declining cell costs and improved cycle life are displacing lead-acid systems in uninterruptible power supply installations.
Market Restraints
- Copper and rare earth price volatility:Transformer and switchgear manufacturing faces input cost pressure from commodity markets concentrated in Chilean and Chinese supply.
- Grid interconnection queues:ANEEL approval timelines for multi-megawatt connections extend eighteen to thirty-six months in southeastern load centers.
- Diesel generator regulatory friction:Municipal air quality ordinances in São Paulo and Rio de Janeiro restrict backup engine runtime and emissions.
Strategic Opportunities
- Northeast wind corridor:Ceará and Rio Grande do Norte offer untapped renewable capacity for latency-tolerant batch computing workloads.
- Edge micro-data center deployment:5G infrastructure rollout creates demand for sub-one-megawatt facilities in secondary cities.
- Gas-to-power integration:Pipeline access in constrained grid regions enables combined-cycle cogeneration for islanded operations.
Industry Challenges
- Medium-voltage electrical engineering talent:Shortage of certified technicians for 13.8kV switchgear maintenance limits expansion velocity.
- Legacy direct current plant integration:Telecommunications facilities upgrading to alternating current hyperscale standards face stranded asset complications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Data Center Power Market |
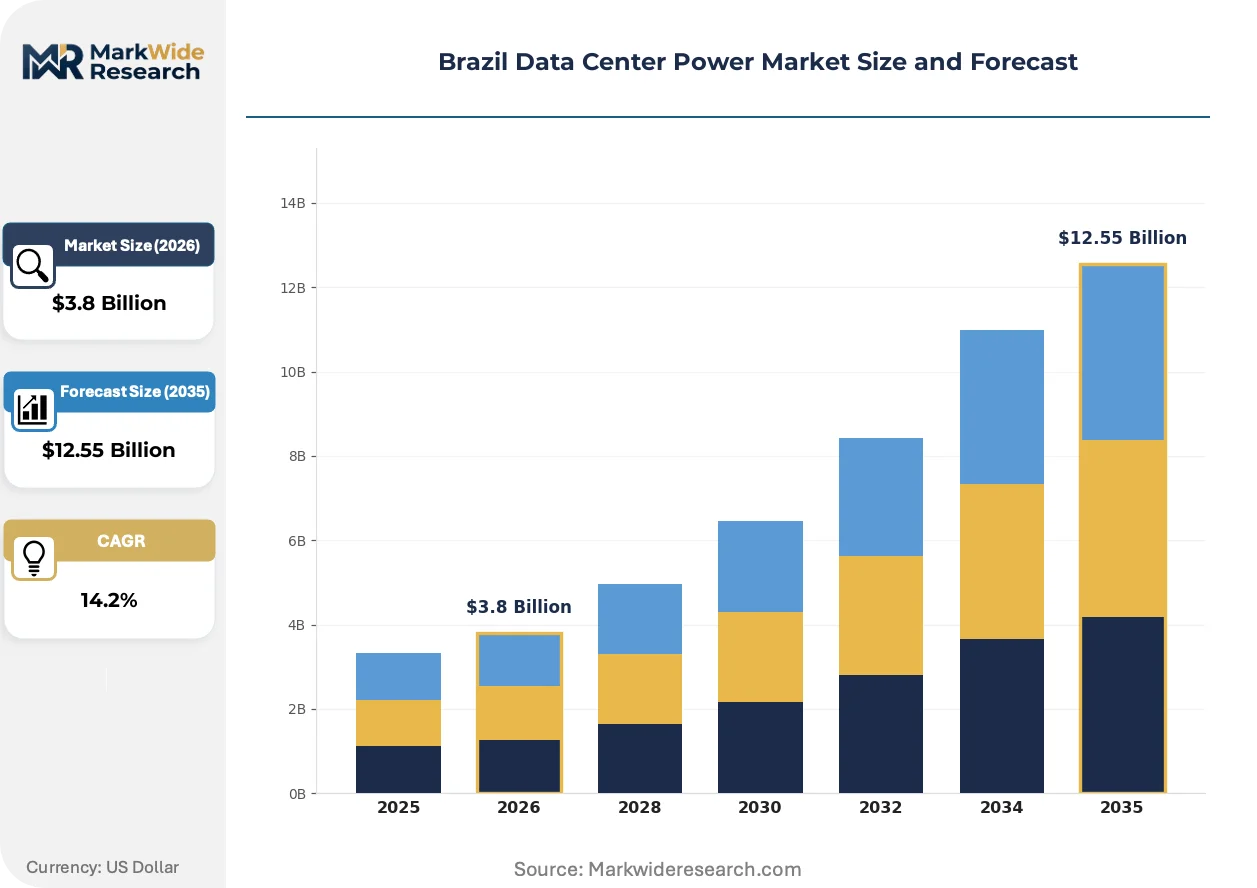
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Power Source: Renewable, Diesel, Natural Gas, Grid Power Data Center Type: Colocation, Enterprise, Edge, Hyperscale Power Capacity: Up to 1 MW, 1 to 5 MW, 5 to 10 MW, Above 10 MW Cooling Technology: Air Cooling, Liquid Cooling, Evaporative Cooling, Hybrid Cooling |
| Companies Covered | Schneider Electric, Vertiv, ABB Ltd, Eaton Corporation plc, Caterpillar Inc., Cummins Inc., Legrand Group, Huawei Technologies, Siemens Energy, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Data Center Power Market Trends and Innovations
Software-defined control architectures are redefining how power infrastructure is monetized, compressing the boundary between electrical hardware and digital operations platforms.
Modular uninterruptible power supply architectures are decentralizing capacity planning across Brazilian colocation facilities. Operators deploy containerized battery and power module units that scale in 250kW increments rather than traditional monolithic systems. This shift enables hyperscale tenants to match infrastructure commits to actual server deployment curves, reducing stranded power capacity.
ANEEL's carbon disclosure requirements for large energy consumers are tightening equipment procurement specifications. Data center operators must document lifecycle emissions for switchgear, transformers, and generation assets. Facilities seeking green bond certification now prioritize suppliers with verified environmental product declarations.
Financial services buyers are unbundling power infrastructure from real estate leases. Large banks and payment processors now contract directly with specialized power vendors for guaranteed uptime, bypassing traditional colocation providers. This pattern concentrates in São Paulo's financial district where interruption costs exceed infrastructure replacement values by orders of magnitude.
Brazil Data Center Power Market Segmentation
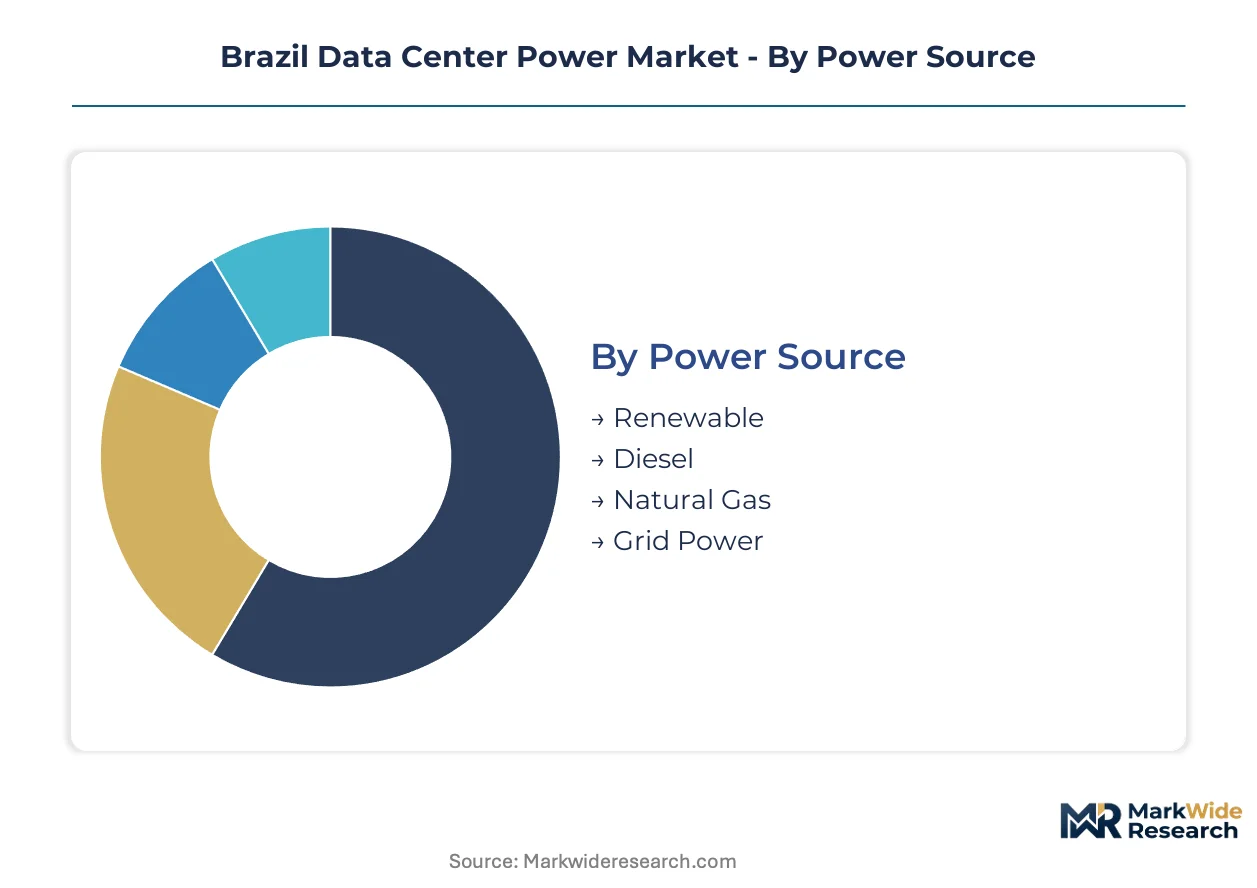
Power procurement patterns in Brazilian data centers diverge sharply across facility scale and energy sourcing strategies. Segmentation reveals how hyperscale operators, enterprise owners, and colocation providers each engineer distinct electrical architectures based on uptime requirements and sustainability commitments.
Power Source:
Buyer differentiation centers on carbon disclosure obligations and grid reliability risk tolerance rather than cost optimization alone.
- Renewable:Hydroelectric and solar procurement dominates southeastern facilities seeking ANEEL-certified clean energy claims. Large financial services operators in São Paulo now mandate renewable power purchase agreements to satisfy central bank climate disclosure rules.
- Grid Power:Utility-supplied electricity from the national interconnected system serves as primary feed for facilities with N+1 redundancy architectures. ANEEL interconnection queues extending eighteen to thirty-six months constrain expansion timelines in Rio de Janeiro load centers.
- Diesel:Backup generator sets retain dominant installed base despite municipal air quality restrictions in São Paulo and Rio de Janeiro limiting runtime hours.
- Natural Gas:Pipeline-fed cogeneration enables islanded operations in grid-constrained regions, particularly attracting facilities seeking independence from distribution network instability.
Grid Power leads volumes today; Renewable is gaining share fastest.
Data Center Type:
Facility ownership models determine procurement sophistication, with outsourced infrastructure demanding standardized power specifications.
- Hyperscale:Cloud operators deploy ten-megawatt-plus sites with dedicated substations and 2N electrical redundancy. São Paulo and Rio de Janeiro corridors concentrate these deployments where fiber density and tax incentives align.
- Colocation:Multi-tenant facilities modularize power delivery in 250kW increments to match tenant server deployment curves. Financial services and e-commerce operators drive demand through outsourcing of critical facility ownership.
- Enterprise:Single-organization facilities maintain customized power architectures reflecting internal IT governance requirements rather than standardized colocation specifications.
- Edge:Sub-one-megawatt deployments in secondary cities follow 5G infrastructure rollout, requiring simplified electrical designs for unmanned operation.
Hyperscale commands capital deployment; Edge is expanding most quickly.
Power Capacity:
Scale thresholds determine transformer specifications, switchgear complexity, and medium-voltage engineering requirements.
- Above 10 MW:Dedicated 13.8kV substations with custom switchgear configurations serve cloud campuses and financial district hubs. Certified technician scarcity for medium-voltage maintenance constrains expansion velocity in this tier.
- 5 to 10 MW:Large colocation halls in São Paulo's Berrini district standardize on this scale to capture enterprise outsourcing demand without hyperscale capital intensity.
- 1 to 5 MW:Mid-market colocation and enterprise facilities populate this segment, with lithium-ion UPS displacement of lead-acid systems accelerating.
- Up to 1 MW:Edge micro-data centers and legacy telecommunications upgrades cluster here, facing stranded asset complications during AC conversion from legacy DC plant.
Above 10 MW dominates absolute capacity; Up to 1 MW shows steepest expansion trajectory.
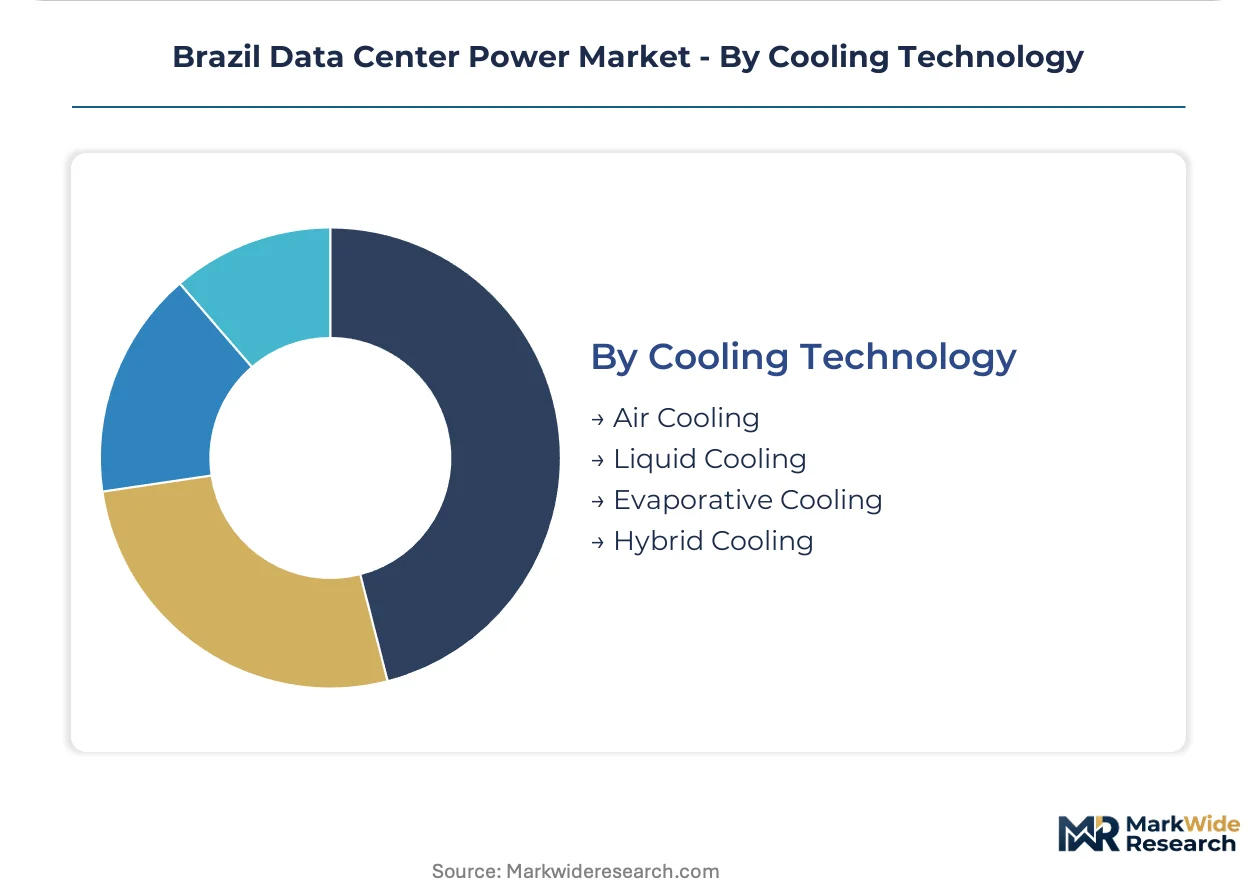
Cooling Technology:
Tropical climate conditions force thermal-electrical co-design decisions that directly impact power distribution architecture.
- Air Cooling:Conventional raised-floor designs with computer room air handlers remain prevalent in legacy facilities and lower-density enterprise deployments.
- Liquid Cooling:Direct-to-chip and immersion systems enable density thresholds exceeding 50kW per rack, attracting AI training clusters in São Paulo hyperscale campuses.
- Evaporative Cooling:Adiabatic designs exploit Brazil's water resources for efficiency gains in regions with lower wet-bulb temperatures.
- Hybrid Cooling:Combined air-liquid architectures optimize for mixed-density workloads, allowing colocation providers to serve diverse tenant requirements within shared electrical infrastructure.
Air Cooling retains installed base leadership; Liquid Cooling is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics favor southeastern states where ANEEL's renewable incentives and fiber density cluster, while northeastern wind corridors attract latency-tolerant workloads seeking cleaner power sourcing.
São Paulo
Hyperscale cloud operators anchor ten-megawatt-plus campuses in the Berrini financial district. ANEEL's net metering rules enable direct renewable procurement from hydroelectric generators. The metropolitan corridor concentrates Brazil's densest fiber interconnection and tax incentive zones.
Rio de Janeiro
Colocation providers modularize power delivery for financial services outsourcing demand. Municipal air quality ordinances restrict diesel generator runtime hours, accelerating lithium-ion UPS displacement. The Barra da Tijuca cluster hosts enterprise facilities seeking proximity to submarine cable landing stations.
Minas Gerais
Grid-constrained regions near Belo Horizonte drive gas-to-power cogeneration adoption for islanded operations. The state's industrial heritage supplies medium-voltage electrical engineering talent scarce elsewhere. Cemig's distribution network stability attracts batch computing workloads from latency-tolerant sectors.
Rio Grande do Norte
Northeastern wind corridors offer untapped renewable capacity at lower landed cost than southeastern hydroelectric. ANEEL's transmission expansion programs reduce interconnection queue timelines for coastal facilities. Natal's emerging data center cluster serves content delivery networks seeking geographic diversification.
Ceará
Fortaleza's submarine cable connectivity and wind resource density attract edge micro-data center deployment. ANATEL's 5G infrastructure rollout creates demand for sub-one-megawatt unmanned facilities. The Pecém port zone enables direct renewable energy import for coastal hyperscale development.
Brazil Data Center Power Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated platform vendors capturing hyperscale contracts while component fabricators serve modular retrofit demand. The vendor base concentrates around three strategic archetypes: full-stack infrastructure platforms, thermal-electrical co-design specialists, and backup power generation OEMs. Dominant competitive moves include long-term service contract anchoring and geographic partnership formation with local electrical contractors.
Within the integrated platform tier, Schneider Electric and Vertiv exemplify divergent positioning strategies. Schneider Electric anchors large-scale deployments through subscription-based uptime guarantees. Vertiv occupies a position emphasizing tropical climate thermal-electrical co-design capabilities. Siemens Energy represents the gas-to-power integration archetype for facilities seeking grid independence.
| Leading Market Players |
|---|
| Schneider Electric |
| Vertiv |
| ABB Ltd |
| Eaton Corporation plc |
| Caterpillar Inc. |
| Cummins Inc. |
| Legrand Group |
| Huawei Technologies |
| Siemens Energy |
| Others |
Pricing and Supply Chain Analysis
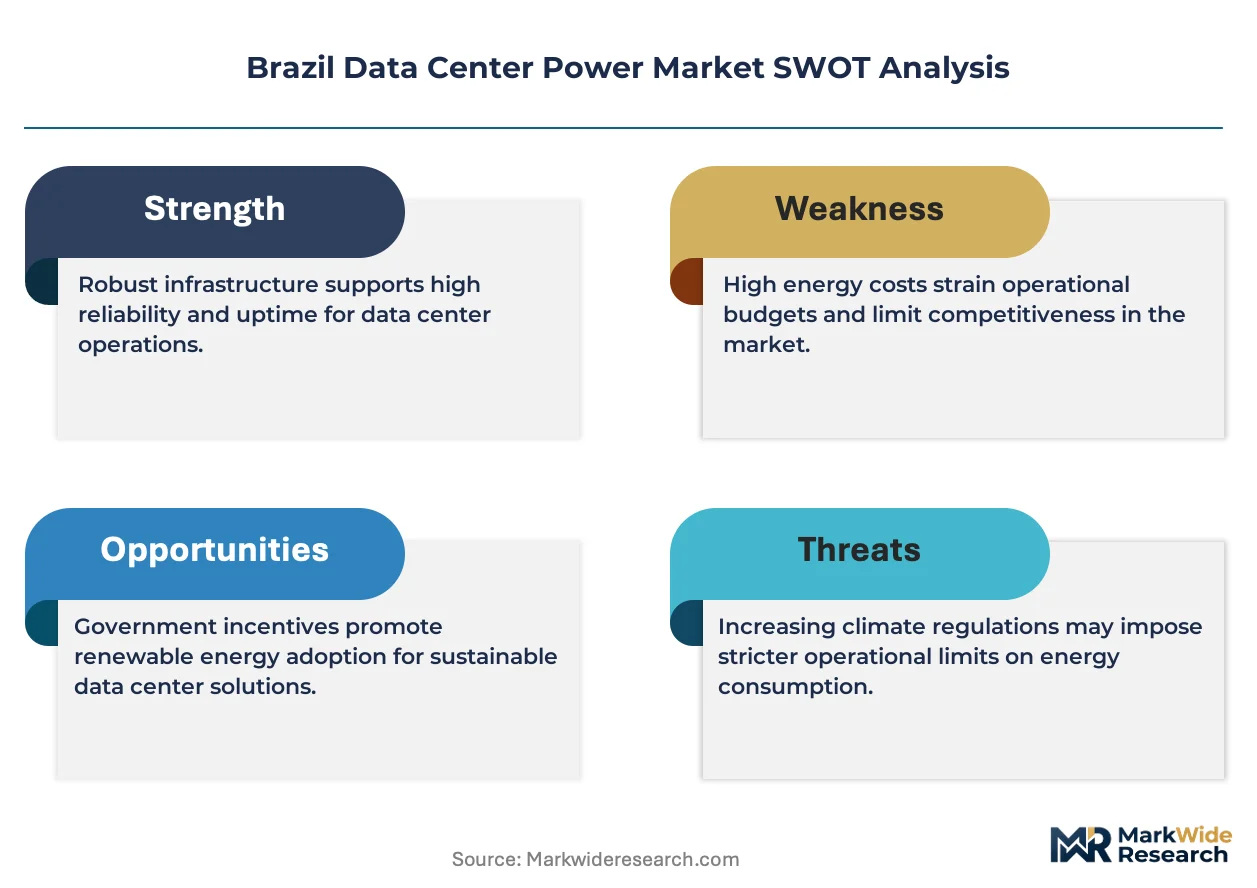
ANEEL's carbon disclosure requirements for large energy consumers gate both qualified supply and premium-tier pricing access, forcing vendors to document lifecycle emissions for switchgear and transformers while facilities seeking green bond certification prioritize suppliers with verified environmental product declarations.
Pricing Analysis
Capacity additions in São Paulo and Rio de Janeiro are reshaping price floors for medium-voltage electrical infrastructure. Three-tier pricing structure across premium, standard, and economy levels differentiates based on ANEEL certification tier and after-sales service bundling. Cost compression in standard-tier equipment is intensifying because lithium-ion battery chemistry advances displace legacy lead-acid systems. Colocation providers exhibit highest price sensitivity due to modular deployment curves, while financial services operators in São Paulo's Berrini district prioritize uptime guarantees over unit economics.
Supply Chain Analysis
Domestic-content mandates under Brazil's BNDES financing rules are reshaping sourcing patterns for transformer and switchgear assembly. Manufacturing draws from copper concentrate originating in Chile, rare earth processing centered in China, and electrical steel production anchored in South Korea. Single-source vulnerability concentrates in Chinese rare earth supply for high-efficiency transformer cores. Distribution runs through authorized electrical contractors certified for 13.8kV medium-voltage installation across southeastern load centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazil's data center power market functions as a regulatory compounder where ANEEL's renewable energy incentives and central bank climate disclosure mandates compound demand for certified clean power architectures.
For Market Incumbents: Anticipate lithium-ion chemistry advances eroding margins on legacy UPS maintenance contracts by accelerating backward integration into battery cell assembly partnerships. Lock in long-term service agreements with hyperscale cloud operators before modular containerized power units commoditize hardware margins. Certification investment in ANEEL environmental product declarations represents the critical defensive lever against specialized power vendors unbundling infrastructure from real estate leases.
For New Entrants and Emerging Players: Capture the Northeast wind corridor in Ceará and Rio Grande do Norte where latency-tolerant batch computing workloads seek lower-landed-cost renewable capacity than southeastern hydroelectric. Target edge micro-data center deployment in Fortaleza and Natal following ANATEL's 5G infrastructure rollout. Partner with local electrical contractors holding medium-voltage certification to bypass eighteen-to-thirty-six-month grid interconnection queue bottlenecks.
For Investors and Strategic Acquirers: Roll-up economics work for thermal-electrical co-design specialists because tropical climate density thresholds exceeding 50kW per rack demand integrated capabilities scarce in fragmented local vendor bases. Five-to-ten-year viability hinges on positioning for AI training cluster demand liquid-cooling integration. Monitor ANEEL transmission expansion program announcements as the inflection signal for Northeast corridor hyperscale development viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Service Contract Anchoring | Schneider Electric's subscription-based uptime guarantees lock hyperscale tenants into recurring revenue streams. |
| Thermal-Electrical Co-Design Investment | Vertiv's tropical climate capabilities sustain density thresholds that conventional vendors cannot match. |
| Gas-to-Power Integration | Siemens Energy's pipeline-fed cogeneration enables islanded operations in grid-constrained Minas Gerais regions. |
| Lithium-Ion Battery Chemistry Transition | Declining cell costs displace lead-acid systems in UPS installations across 1-5 MW colocation facilities. |
| Environmental Product Declaration Certification | ANEEL's lifecycle emissions documentation requirements qualify vendors for green bond-linked procurement. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with data center engineering directors, electrical contractor procurement leads, ANEEL regulatory affairs officers, and hyperscale cloud operator facility planners with secondary validation against ANEEL interconnection filings, ABNT technical standards databases, BNDES project finance disclosures, and central bank climate risk assessment circulars. Bottom-up capacity installation tracking and top-down power infrastructure spend estimates were triangulated for convergence.
Historical reference periods anchored the projection horizon across power source transitions, facility scale migrations, and cooling technology shifts. Segmentation dimensions modeled include power sourcing strategy, data center ownership archetype, capacity tier thresholds, and thermal management approach. CAGRs were derived from installed base displacement curves and capital commitment pipelines. Forecast inputs incorporated ANEEL renewable incentive phase-out schedules and lithium-ion cell cost decline trajectories.
ANEEL regulatory revision, copper and rare earth commodity volatility, and medium-voltage technician certification bottlenecks are the dominant revision risks to capacity expansion assumptions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Canada Data Center Market
Data Center Infrastructure
Europe Data Center Power Market
Data Center Infrastructure
Hong Kong Data Center Rack Market
Data Center Infrastructure
Vietnam Data Center Market
Data Center Infrastructure
Server Operating Environments Market
Data Center Infrastructure
Green Data Center Market
Data Center Infrastructure
Europe Data Center Rack Market
Data Center Infrastructure
LAMEA Virtual Desktop Infrastructure Market
Data Center Infrastructure
North America Data Center Power Market
Data Center Infrastructure
Data Center Construction Market
Data Center Infrastructure
Austria Data Center Power Market
Data Center Infrastructure
GCC Data Center Market
Data Center Infrastructure
Colocation Edge Data Center Market
Data Center Infrastructure
Data Processing and Hosting Services Market
Data Center Infrastructure
Data Center Renovation Market
Data Center Infrastructure
Brazil Data Center Rack Market