
 Chinese Gaming Industry Market | 2026-2036
Chinese Gaming Industry Market Size, Share, and Industry Trends Forecast 2026-2036
Chinese Gaming Industry Market Outlook
Subscription bundling is expanding across Chinese gaming platforms, combining cloud streaming access with premium mobile titles in unified monthly packages. Tencent Holdings Limited leverages its WeChat ecosystem to anchor distribution control across multiple game genres. miHoYo Co., Ltd. differentiates through proprietary engine development and cross-platform character IP continuity. NetEase Inc. sustains competitive positioning via self-operated publishing networks and in-house music integration.
The Chinese gaming industry encompasses interactive entertainment software developed for mobile, PC, and console platforms, requiring real-time network optimization and localized content compliance before commercial release. Its primary purpose centers on monetizing player engagement through free-to-play mechanics, season passes, and virtual goods economies. Mobile games capture the dominant revenue share as 5G infrastructure penetration enables richer multiplayer experiences on handheld devices. PC games retain structural importance in esports broadcasting and hardcore player monetization. Distribution through online stores now overshadows retail outlets as the primary commercial channel.
NMPA approval timelines directly determine product launch cadence and revenue recognition schedules for domestic publishers. MIIT network security assessments and SAMR anti-monopoly provisions shape platform interoperability requirements and in-game purchase transparency standards. Stakeholders must monitor regulatory interpretation shifts around youth playtime restrictions and their downstream effects on daily active user metrics and lifetime value calculations.
Market Dynamics
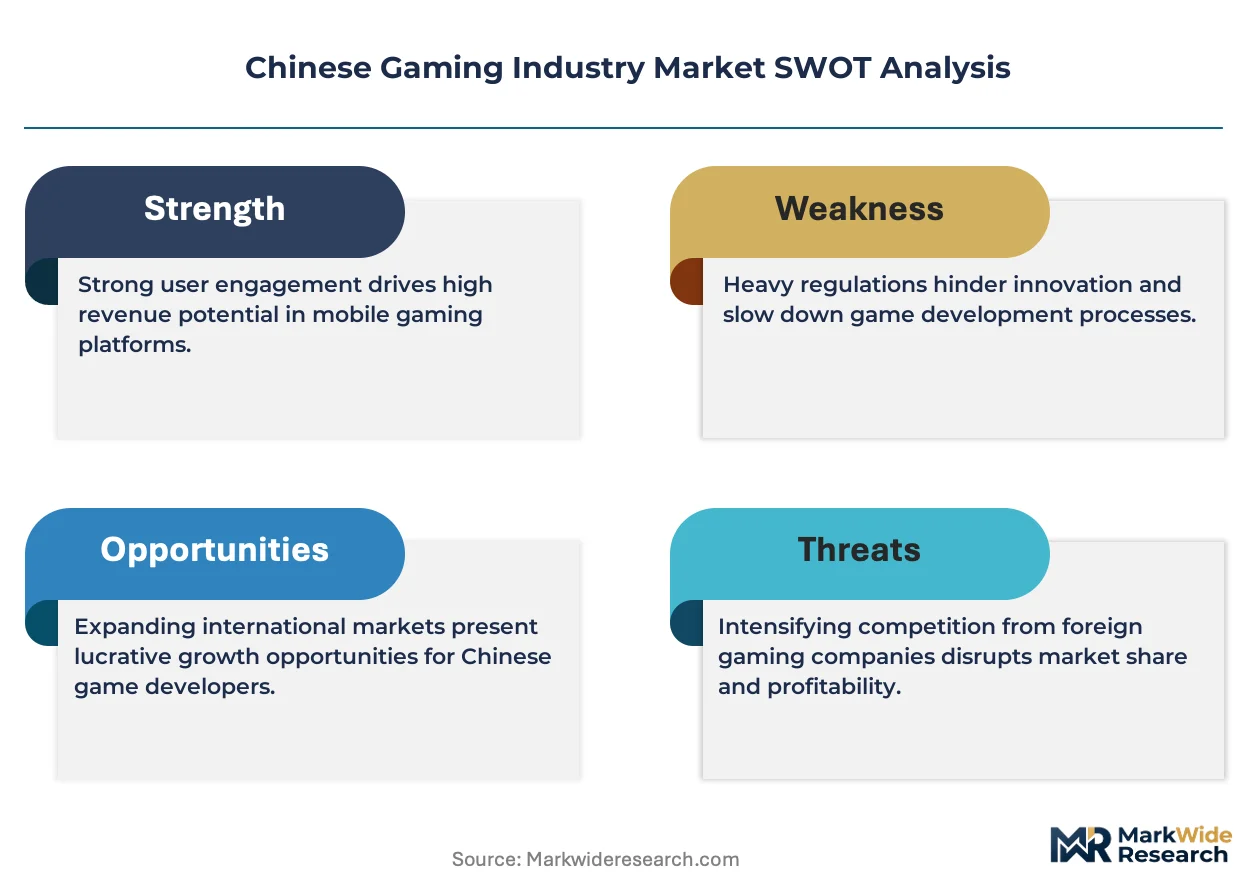
NMPA licensing bottlenecks and provincial esports investment programs now dominate strategic planning cycles for Chinese publishers, compressing release windows while expanding tournament infrastructure budgets.
Growth Catalysts
- Provincial esports subsidies:Guangdong and Jiangsu provincial governments now fund mobile tournament venues and training facilities, lowering publisher customer acquisition costs in tier-two cities.
- 5G network slicing:MIIT-mandated quality-of-service tiers enable sub-20ms latency guarantees for multiplayer cloud gaming sessions on handheld devices.
- Dual carbon goals:MEE energy efficiency standards for data centers accelerate publisher migration to renewable-powered server clusters, reducing long-term operational overhead.
Market Restraints
- Graphics processing unit supply concentration:Foundry capacity constraints in Taiwan and South Korea inflate cloud rendering infrastructure costs for domestic streaming platforms.
- NMPA approval backlog:SAMR content review queues now extend eighteen to twenty-four months for titles containing historical or fantasy martial arts themes.
- Cross-platform engine substitution:Unreal Engine licensing terms pressure mid-tier studios toward lower-fidelity proprietary tools with reduced multiplayer scalability.
Strategic Opportunities
- GB standards compliance exports:NMPA-certified titles gain accelerated regulatory pathways in Southeast Asian markets seeking pre-validated content frameworks.
- Rural township penetration:County-level 5G base station rollouts by China Tower Corporation unlock first-time smartphone gamer cohorts in Sichuan and Henan provinces.
- Cloud-native IP development:Real-time co-creation tools allow player communities to generate in-game assets, shifting production economics toward participatory design models.
Industry Challenges
- Real-time rendering engineer scarcity:Domestic universities produce insufficient talent in Vulkan API optimization and shader pipeline architecture for AAA mobile development.
- Anti-addiction system integration:SAMR-mandated facial recognition verification for youth accounts requires continuous algorithm retraining against evolving circumvention methods.
- Legacy console code base migration:Publishers with decade-old PC franchises face technical debt in porting to ARM-based mobile architectures without feature degradation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chinese Gaming Industry Market |
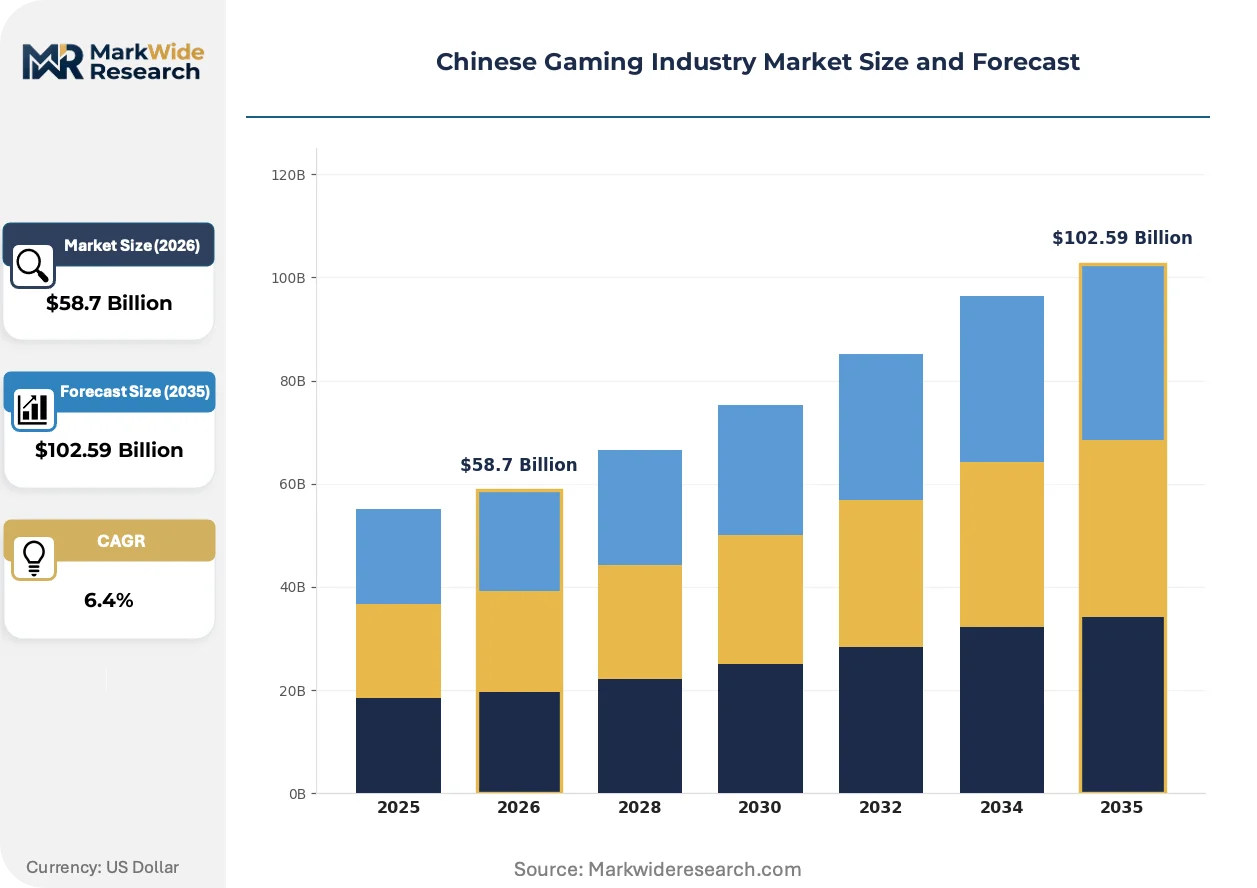
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $102.59 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Game Type: Mobile Games, Consoles, PC Games, Online Multiplayer Distribution Channel: Online Stores, Retail Outlets, Subscription Services, Independent Platforms Player Demographics: Casual Gamers, Hardcore Gamers, Esports Enthusiasts, Social Players Game Genre: Action, RPG, Strategy, Simulation |
| Companies Covered | Tencent Holdings Limited, NetEase Inc., miHoYo Co., Ltd., Perfect World Co., Ltd., 37 Interactive Entertainment Co., Ltd., Lilith Games, Bilibili Inc., IGG Inc., Game Science Interactive Technology Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chinese Gaming Industry Market Strategic Shifts
Cloud streaming architecture is compressing hardware barriers to entry while regulatory compliance automation and participatory content economies reshape how Chinese publishers build and monetize player relationships.
AI-generated asset pipelines are overtaking traditional manual art production workflows in Shenzhen and Chengdu studios. Mid-size publishers now deploy diffusion models for background environment generation and NPC dialogue variation, cutting pre-production cycles by half. This compression is overtaking the historical advantage of large in-house art teams, flattening competitive differentiation between tier-one and tier-two developers.
NMPA's 2023 content rating refinement guidelines now mandate explicit violence and spending probability disclosures on all storefront listings. Studios must re-engineer loot box interfaces to display real-money equivalent values and cooldown timers before purchase confirmation. Hardcore RPG and gacha titles face the heaviest redesign burdens, with several Guangzhou-based publishers delaying launches to rebuild monetization flows.
Community-driven IP extension now dominates franchise lifecycle management for established Chinese studios. Player councils vote on character skin designs and limited-time event narratives through integrated ballot systems, binding engagement metrics to perceived ownership stakes. miHoYo's Genshin Impact exemplifies this shift, with fan-submitted artwork regularly canonized into official merchandise and in-game cosmetics. This participatory model concentrates in Guangdong Province, where developer-community proximity enables rapid feedback loop iteration.
Chinese Gaming Industry Market Segmentation
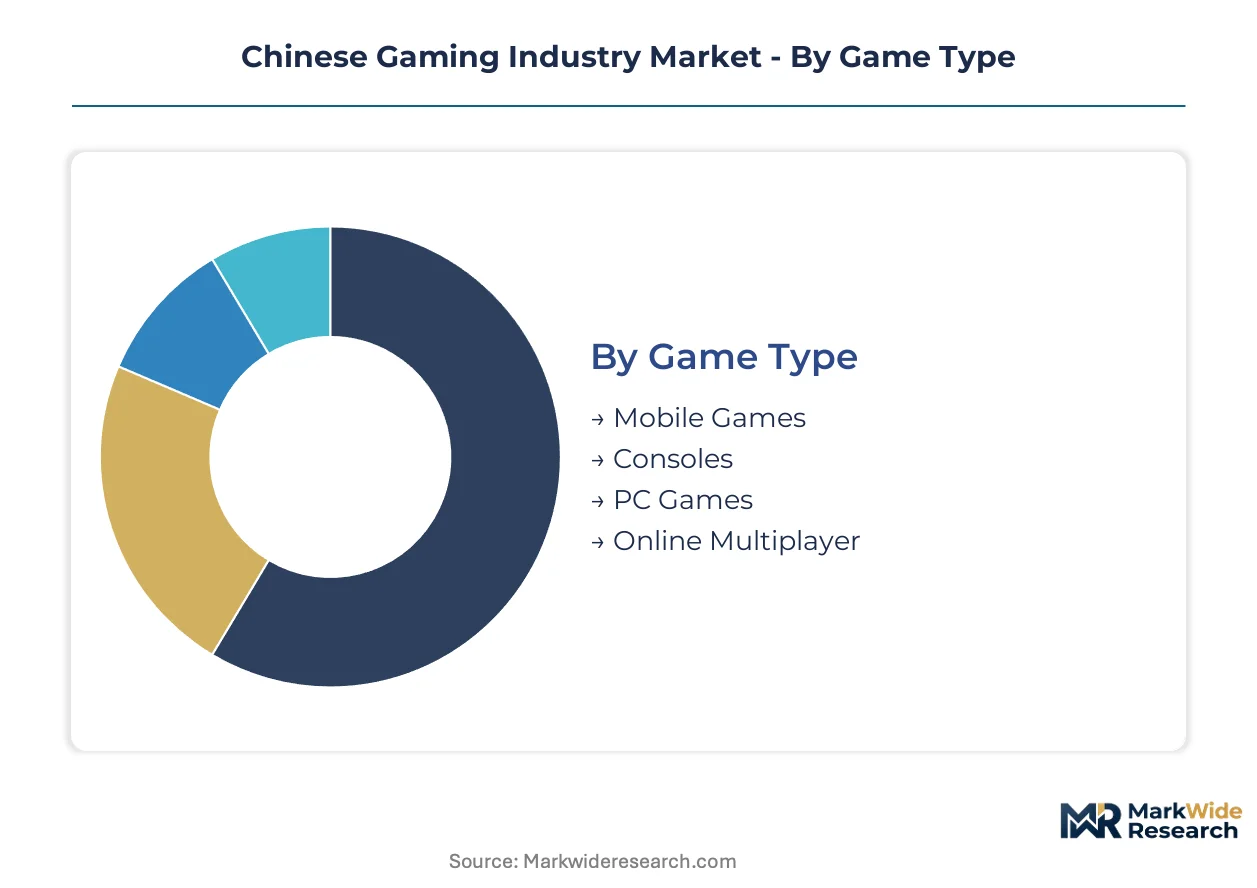
NMPA certification pathways diverge sharply across segment boundaries, with mobile titles facing streamlined approval queues while console imports endure extended content review cycles. Publishers calibrate portfolio mix against these regulatory velocity differentials to optimize revenue recognition timing.
Game Type:
Mobile Games and PC Games carry divergent NMPA documentation burdens, with handheld titles qualifying for accelerated review tracks under MIIT network security pre-certification protocols while desktop releases trigger deeper SAMR content audits for historical accuracy compliance.
- Mobile Games:Touch-optimized titles built on Unity or proprietary engines dominate Guangdong Province studio output. Shenzhen developers concentrate demand here, leveraging WeChat Mini Program distribution to bypass standalone app store friction and reduce NMPA filing overhead per title.
- Consoles:Hardware-tethered experiences require dual approval from NMPA for software and MIIT for networked peripherals. Import licensing bottlenecks constrain Sony and Nintendo platform growth, though domestic handheld manufacturers like AYANEO gain preferential regulatory treatment under Made in China 2025 industrial policy incentives.
- PC Games:Keyboard-mouse interfaces retain structural importance in esports broadcasting infrastructure. NetEase and Tencent self-operated client launchers circumvent third-party store revenue shares, though anti-addiction facial recognition integration adds per-user authentication costs.
- Online Multiplayer:Persistent server architectures trigger mandatory real-name registration systems under SAMR youth protection mandates. Cloud server placement in Beijing-Tianjin-Hebei clusters versus Greater Bay Area data centers affects latency performance for competitive ranked modes.
Mobile Games sits at the top of the volume ranking, with Online Multiplayer climbing the fastest.
Distribution Channel:
Channel selection determines margin retention and NMPA compliance automation feasibility, with first-party stores capturing authentication workflow integration advantages that third-party outlets cannot replicate.
- Online Stores:Tencent MyApp and Huawei AppGallery enforce pre-install content scanning that accelerates NMPA post-approval commercialization. These platforms extract 30-50% revenue shares but bundle anti-addiction system hosting that reduces publisher technical debt.
- Retail Outlets:Physical boxed copies persist for collectible console editions in tier-one city shopping malls. Logistics concentration in Jiangsu Province distribution centers creates working capital intensity that digital-native publishers avoid entirely.
- Subscription Services:Cloud streaming bundles from China Mobile and China Telecom reshape access economics for mid-core players. 5G network slicing guarantees enable sub-20ms latency commitments that justify recurring fee structures over perpetual license models.
- Independent Platforms:Developer-direct distribution via official websites and Bilibili gaming channels bypasses store gatekeepers. miHoYo pioneered this path with Genshin Impact, though customer acquisition costs run higher without pre-installed app store visibility.
Online Stores command the dominant revenue share, with Subscription Services expanding most quickly as 5G infrastructure penetration deepens.
Player Demographics:
Demographic targeting shapes monetization architecture and regulatory exposure, with youth-facing segments requiring heavier SAMR compliance investment than adult-oriented cohorts.
- Casual Gamers:Fragmented session patterns favor hyper-casual ad-supported titles and WeChat Mini Games. Shenzhen studios optimize for subway commute durations, with single-hand portrait orientation mandatory for this cohort's device grip preferences.
- Hardcore Gamers:Sustained engagement tolerates complex gacha economies and season pass structures. Guangzhou RPG specialists target this segment with character collection systems that monetize through pity mechanics and limited-time banner rotations.
- Esports Enthusiasts:Tournament viewership and ranked competitive play drive hardware upgrade cycles. Provincial government subsidies in Jiangsu and Guangdong lower venue construction costs for mobile esports arenas targeting this cohort.
- Social Players:Relationship-maintenance gaming through party games and cooperative modes dominates female player concentration. Honor of Kings and Peacekeeper Elite integrate voice chat and guild systems that bind retention to friend network density.
Social Players generate the highest daily active user counts, with Esports Enthusiasts delivering the steepest per-user revenue expansion trajectory.
Game Genre:
Genre classification determines content review risk profiles at NMPA, with historical martial arts themes facing extended scrutiny while contemporary settings qualify for expedited processing.
- Action:Real-time combat systems with combo mechanics dominate mobile control scheme innovation. miHoYo's Honkai Star Rail and Genshin Impact exemplify this genre's technical ambition, with proprietary engine development separating tier-one from tier-two studio output quality.
- RPG:Narrative-driven character progression with gacha monetization cores sustains the highest revenue per user metrics. NMPA approval delays for fantasy martial arts themes now extend eighteen to twenty-four months, compressing release window predictability for Guangzhou specialists.
- Strategy:Turn-based and real-time tactical systems attract older demographics with higher disposable income. Three Kingdoms historical settings face lighter regulatory scrutiny than contemporary military themes, creating content preference distortions among risk-averse publishers.
- Simulation:Life management and construction mechanics gain traction among female players and rural township first-time smartphone adopters. Lower development budgets and reduced art asset requirements attract Chengdu mid-tier studios seeking predictable returns.
RPG captures the premium revenue tier, with Simulation gaining share fastest among county-level 5G penetration markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's gaming industry traces its commercial roots to arcade halls and early PC cafés in Guangdong Province during the 1990s, where hardware manufacturing proximity seeded developer clusters that persist today.
Guangdong Province
Shenzhen and Guangzhou host the densest concentration of development studios in China, driven by smartphone manufacturing supply chains and WeChat ecosystem integration. Provincial esports subsidies from the Guangdong government fund mobile tournament venues in tier-two cities like Dongguan and Foshan. The Pearl River Delta corridor generates the majority of domestic mobile game exports through NMPA-certified titles.
Jiangsu Province
Nanjing and Suzhou attract publishers seeking lower operational costs than Guangdong while maintaining MIIT network security compliance capabilities. Jiangsu provincial authorities direct investment toward esports training facilities and cloud gaming data centers. The Yangtze River Delta integration policy accelerates talent exchange between Shanghai publishers and Suzhou rendering farms.
Beijing-Tianjin-Hebei
Regulatory headquarters concentration draws publishers requiring direct NMPA and SAMR relationship management. Beijing-based studios specialize in PC esports titles and anti-addiction system development to satisfy central government mandates. Tianjin data center clusters serve northern cloud gaming latency requirements under MEE dual carbon efficiency standards.
Sichuan-Chongqing
Chengdu's lower cost base attracts mid-tier studios developing simulation and casual titles for rural township markets. County-level 5G base station rollouts by China Tower Corporation unlock first-time smartphone gamer cohorts in Sichuan's interior counties. Chongqing's hardware manufacturing heritage supports peripheral development for mobile esports accessories.
Shandong Peninsula
Qingdao and Jinan host secondary publishing operations and customer service centers supporting Guangdong-headquartered publishers. Shandong's logistics infrastructure enables physical merchandise fulfillment for game IP extensions. The province's university system supplies backend engineering talent for server architecture roles.
Chinese Gaming Industry Market Competitive Environment
The competitive structure tilts toward platform-ecosystem dominance by conglomerates with distribution control. Three tiers define the landscape: mega-platforms with social media integration, premium IP developers with proprietary engine capabilities, and mid-tier specialists in genre niches. Competitive moves center on backward integration into cloud infrastructure and exclusive content licensing to secure player retention.
Within the mega-platform tier, Tencent Holdings Limited anchors distribution control through WeChat ecosystem integration. NetEase Inc. occupies a position defined by self-operated publishing networks and in-house music integration. miHoYo Co., Ltd. exemplifies the premium IP developer archetype through proprietary engine development and cross-platform character continuity. These three entities represent the structural poles around which mid-tier competitors position for NMPA approval queue priority and provincial subsidy access.
| Leading Market Players |
|---|
| Tencent Holdings Limited |
| NetEase Inc. |
| miHoYo Co., Ltd. |
| Perfect World Co., Ltd. |
| 37 Interactive Entertainment Co., Ltd. |
| Lilith Games |
| Bilibili Inc. |
| IGG Inc. |
| Game Science Interactive Technology Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
NMPA licensing backlogs and provincial esports subsidy competition are compressing publisher release windows and forcing infrastructure investment trade-offs that reshape cost structures across development tiers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates Chinese gaming monetization, with gacha probability transparency mandates and anti-addiction system hosting costs driving differentiation. Premium tiers absorb facial recognition integration and real-name verification expenses, while economy tiers rely on ad-supported WeChat Mini Program distribution. Price compression intensifies in mid-core RPG segments as miHoYo and NetEase escalate content production budgets. Hardcore gamers show lowest price sensitivity for character collection systems, whereas casual players in rural township markets demand sub-yuan per-session economics.
Supply Chain Analysis
Dual-sourcing requirements for GPU cloud rendering capacity mandate qualification of both Taiwan Semiconductor Manufacturing and Samsung Foundry capacity, though foundry concentration in Taiwan and South Korea inflates infrastructure costs for domestic streaming platforms. Unreal Engine licensing terms and proprietary engine development paths create divergent middleware dependencies. Single-source vulnerability concentrates in advanced node GPU supply for AAA mobile development. Distribution runs through Tencent MyApp and Huawei AppGallery first-party stores that bundle compliance hosting, though miHoYo-style independent platform development bypasses revenue share extraction entirely.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in Chinese gaming rests on cloud infrastructure cost-down trajectories and premium IP tier ascension as NMPA approval velocity differentiates revenue recognition timing.
For Market Incumbents: To counter Unreal Engine licensing pressure and mid-tier studio engine substitution, Tencent and NetEase should deepen proprietary tool development and secure exclusive cloud rendering capacity agreements with MIIT-certified data center operators in Beijing-Tianjin-Hebei clusters. Backward integration into anti-addiction algorithm hosting reduces per-user authentication costs.
For New Entrants and Emerging Players: Capture rural township first-time smartphone gamer cohorts in Sichuan and Henan provinces through simulation and casual titles optimized for China Tower Corporation 5G base station latency profiles. WeChat Mini Program distribution minimizes NMPA filing overhead and accelerates revenue recognition.
For Investors and Strategic Acquirers: Asymmetric upside sits with mid-tier studios possessing proprietary engine capabilities and NMPA-certified title pipelines for Southeast Asian export markets. Watch NMPA approval velocity for fantasy martial arts themes as inflection signal—eighteen-to-twenty-four month queues compressing would indicate regulatory interpretation shift.
| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Engine Development | miHoYo's cross-platform character IP continuity demonstrates engine control as competitive moat. |
| Cloud Gaming Infrastructure Partnership | China Mobile and China Telecom 5G network slicing guarantees enable sub-20ms latency subscription economics. |
| Provincial Esports Subsidy Capture | Guangdong and Jiangsu government tournament venue funding lowers customer acquisition costs in tier-two cities. |
| NMPA Certification Export Pathway | GB standards compliance unlocks accelerated regulatory pathways in Southeast Asian markets. |
| Community-Driven IP Extension | Player council ballot systems for character skins bind engagement metrics to perceived ownership stakes. |
Study Parameters
Multiple input streams — primary interviews with game development executives, publishing operations leads, and esports venue operators; NMPA filing database analysis; and MIIT network security compliance documentation — were reconciled against Tencent and NetEase SEC disclosures and provincial government subsidy program records. Bottom-up title-level revenue modeling and top-down provincial gaming output aggregation were cross-validated.
Historical publisher release cadences were cross-referenced against panel input from cloud infrastructure providers and anti-addiction system vendors across the analysis window. Segmentation dimensions modeled include game type, distribution channel, player demographics, and game genre. CAGRs were derived from trend extrapolation of 5G infrastructure penetration curves and NMPA approval queue dynamics.
NMPA interpretation shifts, GPU foundry capacity constraints, and SAMR youth protection mandate enforcement intensity are the dominant revision risks to the outlook. Deviation in NMPA approval velocity for historical martial arts content would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gaming
Russia in-Game Advertising Market
Gaming
AAA Games Market
Gaming
Gaming Software Market
Gaming
Game API Market
Gaming
Global Battle Royale Games Market
Gaming
Traditional Casual Games Market
Gaming
Online Strategy Games Market
Gaming
Global Game Testing Service Market
Gaming
Game Applications Market
Gaming
Slot Machine Market
Gaming
Germany Gaming Headset Market
Gaming
Gaming Hardware Market
Gaming
Europe Gaming Peripherals Market
Gaming
Global Trading Card Games Market
Gaming
Global Tarot Cards Market
Gaming
Australia Gaming Gadgets Market