
 Mobile Game Software Market | 2026-2036
Mobile Game Software Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile Game Software Market Insights
Capital-intensity divergence between cloud-native infrastructure and legacy server stacks is collapsing as mid-tier studios gain access to distributed computing. Tencent Holdings Ltd leverages its proprietary cloud architecture to sustain low-latency multiplayer experiences across emerging markets. Electronic Arts Inc anchors its mobile portfolio through licensed sports IP that differentiates against genre-saturated app stores.
Mobile game software encompasses executable applications designed for handheld wireless devices, typically distributed through platform-specific digital storefronts and optimized for touch-based input with screen resolutions ranging from 720p to 1440p. These programs generate revenue through real-time service models, in-game economies, and advertising mediation layers that monetize session length and player retention. The freemium monetization model dominates revenue generation while capturing the widest audience base, whereas subscription frameworks remain nascent but attract hardcore players seeking ad-free progression. Action and puzzle genres occupy divergent margin pools, with action titles demanding higher development budgets and puzzle games sustaining lower customer acquisition costs through viral mechanics.
China's SAMR enforces content approval and anti-addiction protocols that reshape product design cycles and limit release velocity for foreign publishers. The EU's GDPR and Digital Services Act impose data governance obligations on ad-supported titles targeting European players, compelling SDK audits and consent-layer redesigns. India's TRAI and Ministry of Electronics and Information Technology scrutinize in-app purchase transparency and gambling-adjacent mechanics in skill-based games. Stakeholders must monitor regulatory fragmentation across platform gatekeepers and national frameworks to calibrate compliance investment against market entry timing.
Market Dynamics
Real-name verification mandates and playtime restrictions for minors in China are forcing publishers to redesign monetization architectures and session mechanics across their entire development pipeline.
Growth Catalysts
- Cloud-Native Infrastructure:Mid-tier studios now access distributed computing resources that previously required proprietary data center investments, collapsing capital barriers for multiplayer title deployment.
- India's Young Adult Demographics:Concentrated demand among 18-34 year olds downloading free-to-play battle royale and puzzle titles on sub-$200 Android devices creates volume foundations for advertising-mediated revenue models.
- GDPR Consent-Layer Innovation:European data governance obligations compel SDK audits and privacy-first ad mediation redesigns that differentiate compliant publishers in regulated markets.
Market Restraints
- SAMR Content Approval Bottlenecks:China's State Administration for Market Regulation enforces anti-addiction protocols that limit release velocity and reshape product design cycles for foreign publishers seeking market entry.
- Customer Acquisition Cost Inflation:Genre saturation in app stores drives paid user acquisition spending upward while organic discovery algorithms favor incumbent titles with established retention metrics.
- Platform Gatekeeper Concentration:Apple App Store and Google Play Store extract 15-30% revenue shares while controlling distribution access, creating dependency risk for publishers without direct-to-consumer infrastructure.
Strategic Opportunities
- Southeast Asia First-Time Smartphone Adoption:Hyper-casual titles attract novice users across Indonesia, Vietnam, and Philippines where device penetration curves support low-friction onboarding mechanics.
- Subscription Framework Maturation:Hardcore player segments demonstrate willingness to pay for ad-free progression systems, creating alternative revenue streams beyond gacha and battle pass mechanics.
- Edge Computing Latency Reduction:5G network rollouts combined with distributed server nodes enable real-time multiplayer experiences previously constrained by infrastructure limitations in emerging markets.
Industry Challenges
- Live Operations Talent Scarcity:Persistent shortages in data science, economy design, and community management functions constrain studios' ability to sustain multi-year service models post-launch.
- Cross-Platform Certification Complexity:Fragmented technical requirements across iOS, Android, and emerging handheld devices extend quality assurance timelines and inflate testing budgets.
- Skill-Based Gaming Regulatory Ambiguity:India's TRAI and Ministry of Electronics scrutinize gambling-adjacent mechanics in real-money skill games, creating compliance uncertainty for publishers operating in gray-zone jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile Game Software Market |
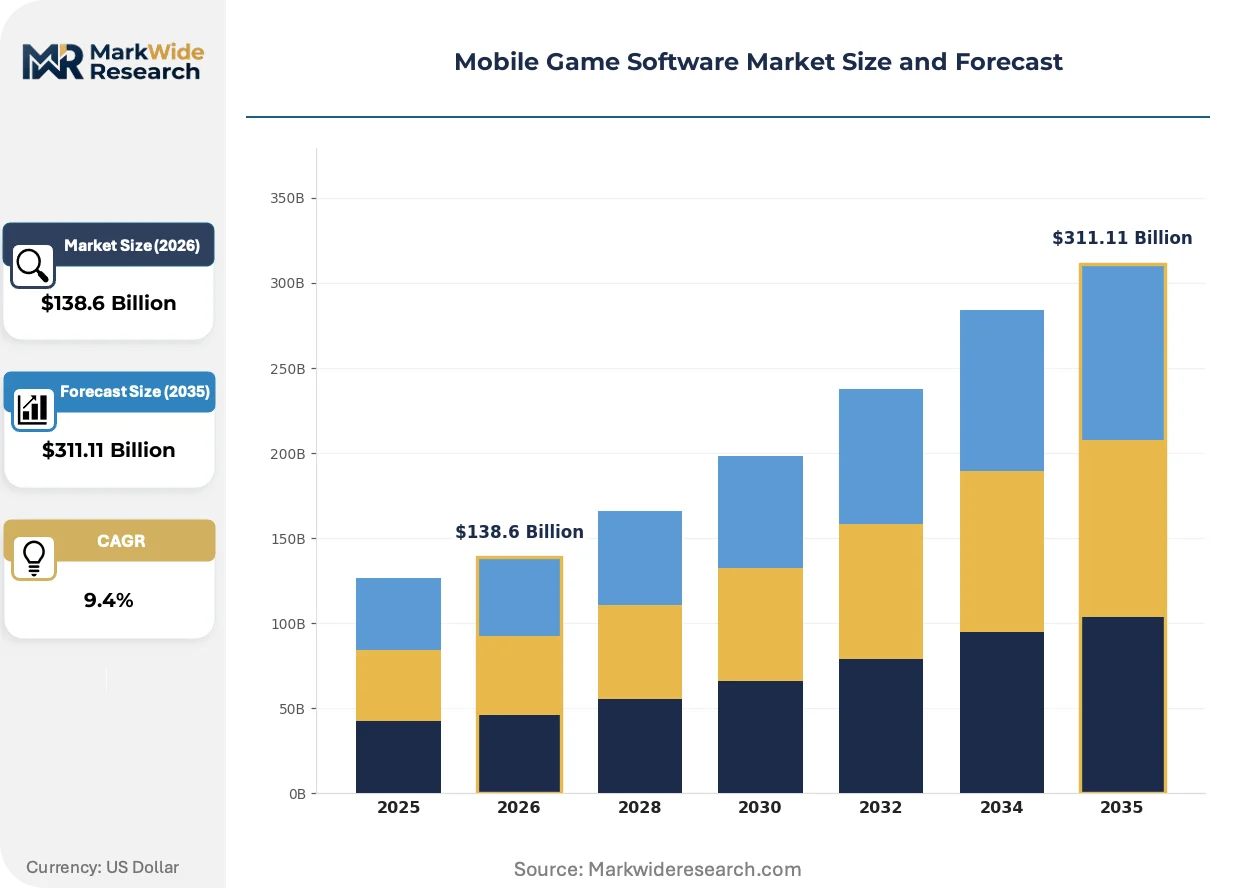
| Market Size in 2026 | $138.6 Billion |
| Market Size in 2035 | $311.11 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Platform: iOS, Android, Windows Phone, Others Monetization Model: Freemium, Subscription, In-App Purchases, Paid Game Genre: Action, Adventure, Puzzle, Simulation Target Audience: Casual Gamers, Hardcore Players, Children, Adults |
| Companies Covered | Tencent Holdings Ltd, NetEase Inc, Activision Blizzard Inc, Electronic Arts Inc, Take-Two Interactive Software Inc, Supercell Oy, Nintendo Co Ltd, Playrix Holding Ltd, Sea Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile Game Software Market Trends and Innovations
Generative AI tools are compressing asset production pipelines while regulatory fragmentation forces architectural divergence between privacy-first and surveillance-capable market architectures.
AI-assisted art and animation pipelines are displacing traditional outsourcing relationships with manual studios in Southeast Asia. Mid-tier developers in Poland and Brazil now generate character sprites, environment textures, and localization assets through proprietary fine-tuned models. This compression is displacing established art house vendors and collapsing production timelines from months to weeks for content updates.
China's MIIT enforcement of real-name verification and three-hour weekly playtime limits for minors is restructuring monetization design away from whale-dependent gacha systems. Publishers must now engineer progression curves that satisfy paying adults without exploiting compulsive behavior patterns in restricted demographics. Korean and Japanese studios targeting Chinese distribution are rebuilding their entire economy balancing frameworks to maintain SAMR compliance.
Hyper-casual player behavior is fragmenting across session length preferences that diverge sharply by device tier and connectivity quality. Publishers now segment their portfolio architectures between 30-second interstitial-ad titles for emerging market low-RAM devices and 15-minute session games for premium smartphone users in urban centers. This bifurcation is most visible in India, where Tier-1 cities sustain mid-core RPG retention while Tier-3 towns drive hyper-casual install velocity through offline-capable lightweight builds.
Mobile Game Software Market Segmentation
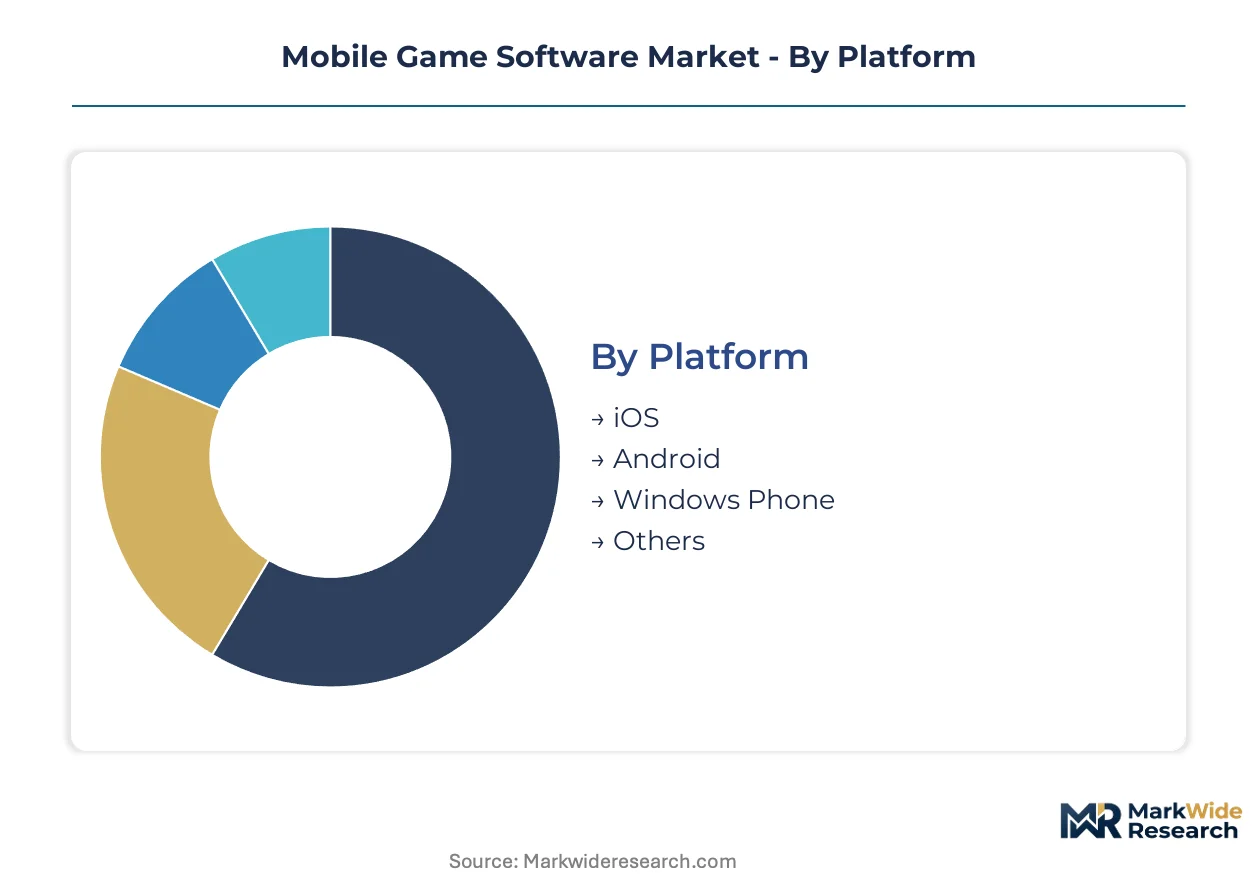
Platform gatekeepers and regulatory frameworks fragment the mobile game software landscape into distinct technical and commercial architectures. Publishers must calibrate development pipelines, monetization mechanics, and compliance investments against segment-specific requirements that vary sharply across operating systems and audience demographics.
Platform:
MIIT real-name verification mandates in China and GDPR consent-layer obligations in Europe create divergent certification pathways that reshape release velocity and technical architecture across mobile operating systems.
- iOS:Apple's closed ecosystem enforces strict App Store review protocols and 30% revenue share terms that favor established publishers with direct-to-consumer infrastructure. Premium device penetration in Tier-1 Chinese cities and Western European urban centers concentrates high-value player acquisition here, though SAMR content approval bottlenecks extend localization timelines for foreign titles.
- Android:Open-source architecture enables sideloading and alternative storefront distribution that reduces platform dependency risk for publishers. Sub-$200 device dominance across India, Indonesia, and Vietnam drives volume foundations for advertising-mediated revenue models, while fragmented OS versioning complicates quality assurance across manufacturer-customized skins.
- Windows Phone:Legacy platform with minimal active development support; residual enterprise and niche productivity-oriented gaming applications persist in limited educational and corporate training deployments.
- Others:Emerging handheld operating systems and proprietary smart TV gaming platforms capture experimental publisher investment, particularly in cloud-streaming service integrations targeting low-latency multiplayer experiences.
iOS handles the majority of throughput; Android is the fastest mover on share.
Monetization Model:
Cost tier differentiation separates mass-market acquisition strategies from premium retention architectures that command higher lifetime value per player.
- Freemium:Zero-entry-price mechanics with gated progression systems dominate install velocity across Southeast Asian first-time smartphone adopters. India's TRAI scrutiny of in-app purchase transparency and gambling-adjacent mechanics compels SDK audits that inflate compliance investment for skill-based titles.
- Subscription:Monthly recurring revenue frameworks attract hardcore player segments seeking ad-free progression systems. Korean and Japanese studios targeting Chinese distribution rebuild economy balancing frameworks to maintain SAMR compliance without whale-dependent exploitation patterns.
- In-App Purchases:Microtransaction layers monetize session length through cosmetic and functional virtual goods; three-hour weekly playtime limits for minors force architectural redesign away from compulsive spending triggers.
- Paid:Upfront purchase models retain niche positioning among premium puzzle and narrative-driven titles with complete content delivery at point of sale.
Freemium commands absolute volume leadership; Subscription is climbing the fastest as hardcore segments demonstrate willingness to pay for uninterrupted progression.
Game Genre:
Application-specific development budgets and player retention mechanics create divergent margin pools that reshape studio resource allocation and outsourcing relationships.
- Action:Real-time multiplayer infrastructure demands cloud-native server investments and low-latency edge computing deployment. Tencent leverages proprietary cloud architecture to sustain competitive experiences across emerging markets where 5G rollouts enable previously constrained gameplay.
- Adventure:Narrative-heavy content production benefits from generative AI compression of asset pipelines; Polish and Brazilian mid-tier developers displace traditional Southeast Asian art house vendors through proprietary fine-tuned models.
- Puzzle:Viral mechanics sustain lower customer acquisition costs through organic discovery algorithms that favor established retention metrics. Hyper-casual session length segmentation bifurcates between 30-second interstitial-ad titles for low-RAM devices and 15-minute builds for premium smartphones.
- Simulation:Economy design complexity requires persistent live operations talent in data science and community management functions that remain structurally scarce across the industry.
Action absorbs the largest development budgets; Puzzle is expanding most quickly through viral acquisition mechanics and AI-assisted production compression.
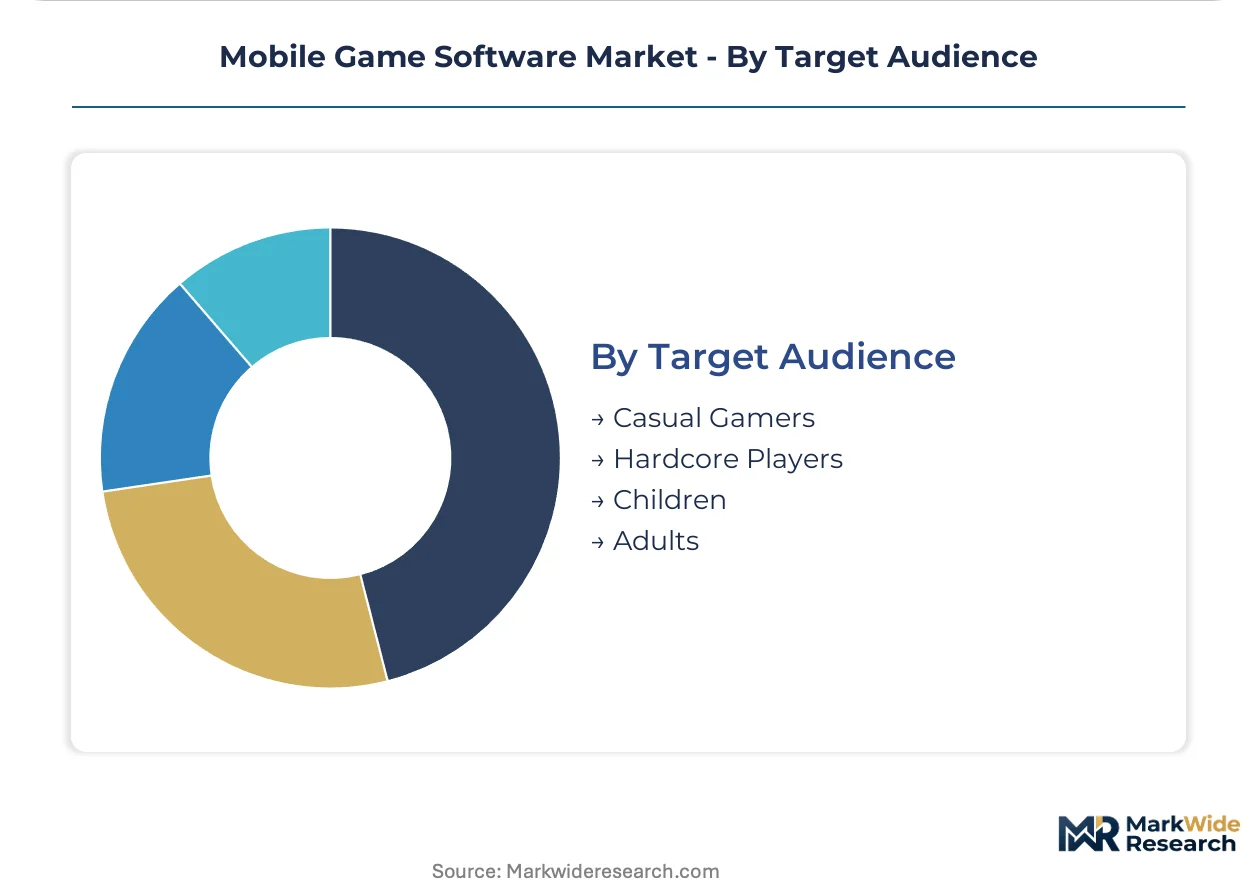
Target Audience:
Customer type concentration determines monetization depth, content rating requirements, and regulatory exposure across national frameworks.
- Casual Gamers:Fragmented session preferences by device tier and connectivity quality drive portfolio architecture segmentation; Tier-3 Indian towns generate hyper-casual install velocity through offline-capable lightweight builds.
- Hardcore Players:Willingness to pay for subscription frameworks and battle pass mechanics sustains higher lifetime value; economy design must satisfy paying adults without exploiting restricted demographics under Chinese anti-addiction protocols.
- Children:Real-name verification and playtime limits force fundamental restructuring of progression curves and gacha systems; foreign publishers face extended SAMR approval timelines for youth-targeted content.
- Adults:Concentrated demand among 18-34 year old demographics in India drives free-to-play battle royale and puzzle title adoption on budget Android devices.
Casual Gamers represent the broadest addressable base; Hardcore Players are gaining share fastest through subscription maturation and ad-free progression willingness.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across geographies, with Southeast Asian markets demanding sub-$200 device optimization while Western European and Chinese Tier-1 cities sustain premium monetization depths.
China
MIIT real-name verification and three-hour weekly playtime limits for minors force publishers to redesign gacha-dependent economies toward adult-paying segments. SAMR content approval bottlenecks extend localization timelines for foreign titles seeking distribution. Beijing and Shanghai host the dominant studio clusters where Tencent leverages proprietary cloud architecture for low-latency multiplayer deployment.
United States
High-value player concentration in coastal urban centers sustains subscription framework adoption and battle pass monetization. The FTC scrutinizes loot box mechanics and dark pattern design in youth-targeted titles. Los Angeles and San Francisco Bay Area clusters anchor Electronic Arts and Activision Blizzard's live operations talent pools for sports IP and shooter franchises.
India
18-34 year old demographics drive free-to-play battle royale and puzzle title adoption on sub-$200 Android devices across Tier-1 through Tier-3 towns. TRAI and the Ministry of Electronics scrutinize in-app purchase transparency and gambling-adjacent mechanics in skill-based games. Bangalore and Hyderabad studio ecosystems concentrate mid-tier developers optimizing lightweight offline-capable builds for low-RAM devices.
Indonesia
First-time smartphone penetration curves support hyper-casual install velocity through 30-second interstitial-ad session mechanics. The Ministry of Communication and Informatics enforces content rating and age verification frameworks for digital storefront distribution. Jakarta and Surabaya metropolitan areas concentrate publisher operations targeting novice users with low-friction onboarding architectures.
Germany
GDPR consent-layer obligations and the Digital Services Act compel SDK audits and privacy-first ad mediation redesigns for ad-supported titles. The Federal Network Authority monitors platform gatekeeper concentration under EU digital competition frameworks. Berlin and Hamburg clusters host mid-tier studios deploying generative AI pipelines for compressed asset production timelines.
Mobile Game Software Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with cloud-native infrastructure specialists and viral acquisition optimizers occupying distinct competitive positions. The market structures around three tiers: vertically integrated conglomerates with proprietary distribution, mid-tier studios leveraging distributed computing access, and hyper-casual specialists optimizing for low-friction onboarding. Dominant competitive moves include M&A for live operations talent and geographic expansion into regulatory-fragmented emerging markets.
Within the vertically integrated tier, Tencent Holdings Ltd and NetEase Inc represent archetypes of cloud-architecture control and regulatory compliance engineering. Electronic Arts Inc occupies a position exemplifying licensed sports IP differentiation against genre-saturated storefronts. These anchors demonstrate how geographic origin and corporate structure shape strategic positioning without requiring equivalent technical or cost capabilities.
| Leading Market Players |
|---|
| Tencent Holdings Ltd |
| NetEase Inc |
| Activision Blizzard Inc |
| Electronic Arts Inc |
| Take-Two Interactive Software Inc |
| Supercell Oy |
| Nintendo Co Ltd |
| Playrix Holding Ltd |
| Sea Ltd |
| Others |
Pricing and Supply Chain Analysis
Ninety-day localization timelines for SAMR content approval compress release windows and concentrate pricing power among publishers with pre-cleared asset pipelines and established Chinese distribution relationships. This lead-time band separates studios that can sustain live-service monetization from those forced into fire-sale revenue recognition cycles.
Pricing Analysis
In-app purchase tiers and battle pass renewals drive lifetime value across free-to-play architectures. Pricing stratifies across premium subscription, standard battle pass, and economy ad-supported tiers based on session depth and progression velocity. Cost compression in user acquisition is intensifying because genre saturation elevates paid install spending while organic discovery algorithms favor incumbents. Hyper-casual publishers in Southeast Asia exhibit highest price sensitivity; hardcore segments in Chinese Tier-1 cities demonstrate lowest sensitivity through subscription willingness.
Supply Chain Analysis
Inventory cycles for generative AI compute clusters and cloud rendering nodes stretch 60-90 days as demand outstrips GPU allocation from Taiwan, South Korea, and USA. Art production draws from proprietary fine-tuned models, outsourced Southeast Asian manual studios, and Polish-Brazilian mid-tier developer pipelines. Single-source vulnerability concentrates in NVIDIA hardware allocation for AI-assisted asset generation. Distribution runs through platform gatekeepers Apple App Store and Google Play Store, with sideloading alternatives reducing dependency for Android publishers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The mobile game software market functions as a defensive-moat story where live-service retention data and regulatory compliance engineering create switching costs that entrench established publishers against new entrants.
For Market Incumbents: Shield proprietary player data reservoirs and live operations talent pools through non-compete enforcement and equity retention structures. Acquire mid-tier studios in Poland and Brazil before generative AI compression fully displaces manual art house relationships. Threat substitution from AI-native entrants without legacy compliance burdens demands accelerated SAMR certification investment as defensive moat. For New Entrants and Emerging Players: Subscription framework gaps in ad-free progression systems for hardcore Indian and Southeast Asian players represent the most penetrable white-space target. Pursue direct-to-consumer infrastructure bypassing platform gatekeepers through progressive web app distribution. Go-to-market angle centers on privacy-first ad mediation redesigns for GDPR-compliant European entry. For Investors and Strategic Acquirers: Carve-out targets emerge from conglomerate entertainment divisions where mobile gaming assets sit under-optimized within broader IP portfolios. Long-term viability frames around studios with demonstrated live-service retention beyond 24 months and proprietary cloud architecture control. Signal to watch is MIIT enforcement expansion beyond minors into adult playtime guidance.| Strategic Initiative | Industry Significance |
|---|---|
| Live Operations Talent Acquisition | Addresses structural scarcity in economy design and community management functions constraining multi-year service models. |
| Generative AI Pipeline Integration | Compresses asset production timelines from months to weeks for content updates displacing Southeast Asian art vendors. |
| Direct-to-Consumer Infrastructure | Reduces platform gatekeeper dependency risk through sideloading and alternative storefront distribution on Android. |
| Regulatory Compliance Engineering | Builds SAMR and GDPR certification capabilities that extend release velocity advantages against foreign competitors. |
| Edge Computing Latency Investment | Enables real-time multiplayer experiences in emerging markets where 5G rollouts meet distributed server nodes. |
Research Methodology
A spread of perspectives from live operations directors, platform partnership leads, regulatory compliance officers, and user acquisition managers converged on the working assumptions underlying this analysis. Primary interview data combined with secondary validation from SEC filings, App Annie/Sensor Tower metrics, hyperscaler capex disclosures, and SAMR content approval databases. Bottom-up studio revenue modeling and top-down platform revenue share triangulation anchored value estimates.
Segmentation dimensions modeled include platform ecosystem, monetization architecture, game genre, and target audience demographic across the projection horizon. CAGRs derived from historical revenue trajectory analysis and forward-looking install velocity assumptions. Industry-specific forecast inputs encompass real-name verification enforcement intensity and 5G network rollout pace in emerging markets.
Material uncertainties — regulatory fragmentation acceleration, platform gatekeeper policy shifts, generative AI capability jumps — sit outside the modeled envelope. Forecasts reflect assumptions about compliance investment levels and player retention curve stability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gaming
Traditional Casual Games Market
Gaming
Australia Gaming Gadgets Market
Gaming
Playstation Network (PSN) Market
Gaming
North America Gaming Hardware and Accessories Market
Gaming
United Kingdom Online Gambling Market
Gaming
Gaming Chair Market
Gaming
South Asia Mobile Gaming Market
Gaming
Animation, VFX & Game Market
Gaming
Europe Video Game Software Market
Gaming
Japan Virtual Reality Gaming Market
Gaming
India Gaming Market
Gaming
VR Gaming Console Market
Gaming
H5 Games Market
Gaming
Connected Game Console Market
Gaming
Advanced Digital Gaming Market
Gaming
South Korea Subscription-Based Gaming Market