
 Gaming Simulation Market | 2026-2036
Gaming Simulation Market Size, Share, and Industry Trends Forecast 2026-2036
Gaming Simulation Market Analysis
Military and defense training is decoupling from legacy desktop simulators as institutional buyers demand cloud-streamed, multi-user environments. NVIDIA dominates GPU-accelerated physics rendering for these deployments. Microsoft anchors enterprise-grade cloud infrastructure through Azure-hosted simulation instances. Sony Interactive Entertainment leverages proprietary haptic feedback patents to differentiate its professional-grade hardware offerings.
Gaming simulation encompasses software and hardware systems that replicate real-world physics, environments, or competitive scenarios through computational models running at 60-120 frames per second with sub-20ms latency thresholds. These systems serve commercial entertainment, professional training, and broadcast production purposes. PC Games sustain the largest revenue pool among product types due to modding ecosystems and peripheral compatibility. VR Simulators represent the fastest-expanding category as enterprise buyers adopt head-mounted displays for pilot and surgical training. Racing titles within the genre classification command premium pricing through licensed vehicle partnerships and track scanning investments.
FCC equipment authorization rules shape wireless VR headset market access in the United States, while CE marking requirements under EU directives govern electromagnetic compatibility for European hardware distribution. GDPR compliance obligations constrain biometric data collection in player performance analytics across EU jurisdictions. Stakeholders must monitor evolving AI disclosure mandates from the EU AI Act as procedural content generation becomes standard in simulation engines.
Market Dynamics
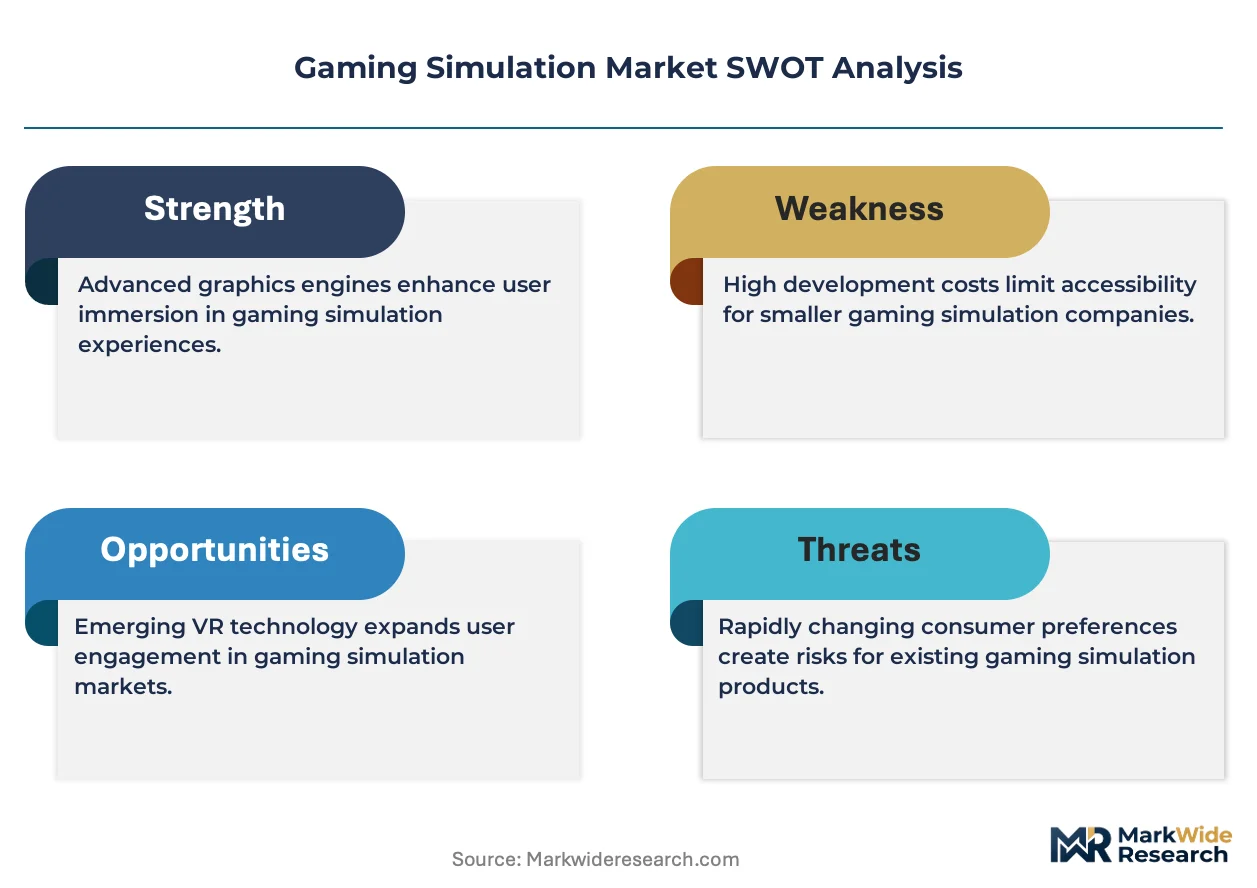
Cloud rendering infrastructure is displacing localized GPU clusters as the dominant processing architecture, forcing hardware vendors to pivot toward edge-streaming partnerships and subscription revenue models.
Growth Catalysts
- Military Training Modernization:Defense procurement offices in the United States, Germany, and Japan are mandating cloud-native simulation environments for joint-force exercises.
- GDPR-Compliant Biometric Analytics:EU-based esports leagues are investing in consent-managed player performance tracking to satisfy CNIL audit requirements.
- 5G mmWave Deployment:FCC equipment authorization for low-latency wireless VR headsets is enabling untethered enterprise training installations.
Market Restraints
- GPU Supply Concentration:Foundry capacity for advanced semiconductor lithography concentrates in Taiwan, creating single-point vulnerability for rendering hardware.
- CE Marking Complexity:Electromagnetic compatibility testing under EU directives adds months to European hardware launch timelines.
- Cloud Latency Floors:Sub-20ms response thresholds remain technically unachievable over standard residential broadband in rural service areas.
Strategic Opportunities
- Surgical Training VR:Teaching hospitals in Japan are piloting haptic-enabled procedure simulation for resident certification.
- EU AI Act Procedural Generation:Disclosure mandates for AI-generated content create first-mover advantage for transparent simulation engine architectures.
- Esports Certification Pathways:German technical institutes are formalizing professional gaming credentials through standardized simulation competency testing.
Industry Challenges
- Legacy Simulator Integration:Defense contractors face middleware compatibility gaps when connecting cloud-streamed environments to existing motion-platform hardware.
- Cross-Border Data Sovereignty:Biometric performance data storage requirements conflict between HIPAA, GDPR, and Japan's APPI frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gaming Simulation Market |
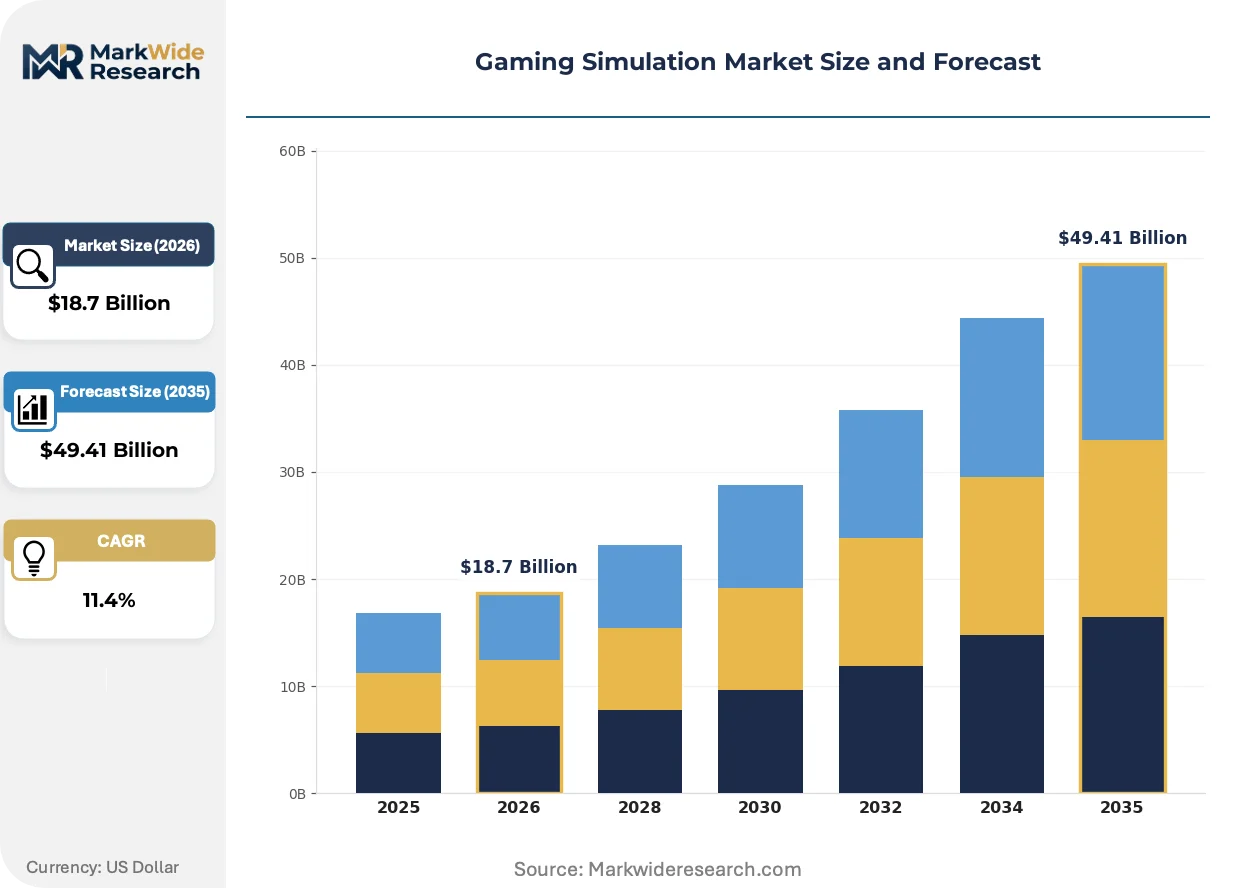
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PC Games, Console Games, VR Simulators, Mobile Games User Type: Casual Gamers, Professional Gamers, Esports Athletes, Streamers Platform: Windows, PlayStation, Xbox, Android Genre: First-Person Shooter, Racing, Role-Playing, Strategy |
| Companies Covered | Electronic Arts, Microsoft, Sony Interactive Entertainment, Activision Blizzard, Take-Two Interactive, Ubisoft, Epic Games, NVIDIA, Bandai Namco Entertainment, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gaming Simulation Market Emerging Trajectories
Physics engine unification and biometric feedback loops are compressing development cycles while regulatory disclosure requirements are reshaping content generation workflows.
Neural radiance fields (NeRF) are unifying photogrammetry and real-time rendering pipelines for environment digitization. Automotive manufacturers and motorsport leagues are adopting NeRF-based track scanning to reduce asset production timelines from months to days. This convergence is unifying previously separate modeling, texturing, and lighting disciplines into single-operator workflows.
The EU AI Act's transparency mandates for algorithmic content generation are forcing simulation studios to document procedural asset creation pipelines. Studios serving European broadcast and training markets must now maintain audit trails for AI-generated terrain, character behaviors, and physics parameters. Racing simulation developers with licensed vehicle partnerships face particular exposure given the volume of AI-assisted track surface generation in their products.
Subscription-based access models are displacing perpetual license sales across professional training segments. Corporate buyers in aviation and healthcare now prioritize operational expenditure structures over capital-intensive simulator installations. This preference shift is most pronounced in United States hospital networks and German automotive engineering departments, where finance teams favor predictable monthly costs tied to user seats rather than depreciating hardware assets.
Gaming Simulation Market Segmentation
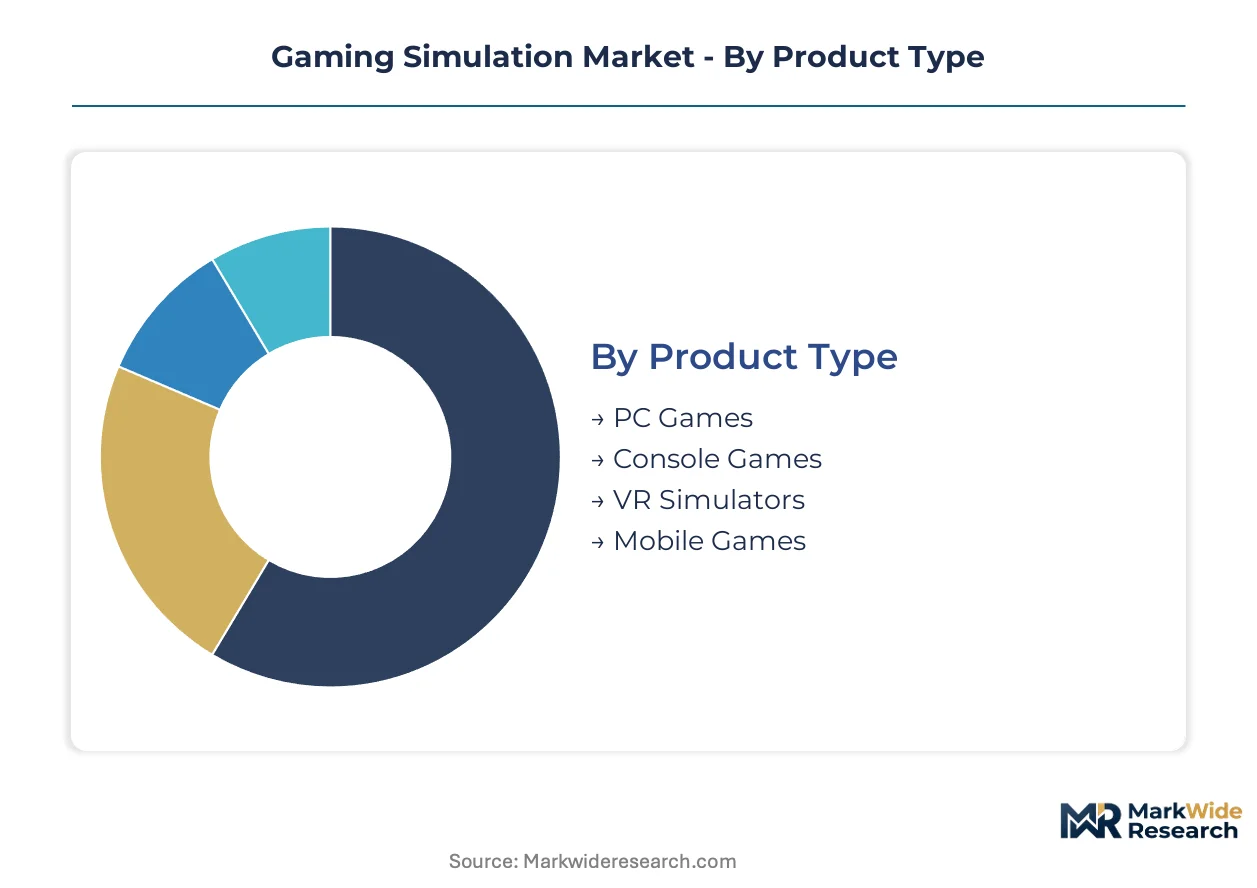
Segmentation in gaming simulation reveals divergent hardware requirements and latency tolerances across deployment contexts. Cloud-native training environments demand fundamentally different processing architectures than consumer entertainment systems.
Product Type:
Standalone installations dominate defense and medical certification use cases, while embedded streaming solutions serve consumer entertainment markets.
- PC Games:Open architecture supports modding ecosystems and peripheral interoperability across flight sticks, racing wheels, and haptic vests. United States hospital networks and German automotive engineering departments favor subscription-based PC simulation access over capital-intensive hardware procurement.
- VR Simulators:Head-mounted displays with sub-20ms motion-to-photon latency enable pilot and surgical training scenarios impossible on flat screens. Japanese teaching hospitals pilot haptic-enabled procedure simulation for resident certification pathways.
- Console Games:Closed ecosystems optimize for standardized controller inputs and living-room deployment.
- Mobile Games:Touch-based interaction models serve casual latency-tolerant use cases.
PC Games lead volumes today; VR Simulators are gaining share fastest.
User Type:
Professional certification requirements create tiered performance thresholds that consumer segments do not enforce.
- Professional Gamers:Standardized competency testing through German technical institutes validates simulation proficiency for employment credentialing. These users demand frame-time consistency below 8.3ms for competitive integrity.
- Esports Athletes:GDPR-compliant biometric analytics under CNIL audit requirements track reaction time and decision velocity for performance optimization. EU-based leagues invest heavily in consent-managed data infrastructure.
- Casual Gamers:Price-sensitive segment tolerates higher latency and variable frame rates.
- Streamers:Dual-system encoding requirements separate gameplay from broadcast processing.
Professional Gamers anchor revenue per user; Esports Athletes show steepest expansion trajectory.
Platform:
Enterprise procurement patterns favor operating systems with centralized device management and security audit capabilities.
- Windows:Dominates professional training installations through Azure-hosted cloud instances and Active Directory integration. Defense procurement offices in the United States mandate Windows-based environments for joint-force exercise compatibility.
- PlayStation:Proprietary haptic feedback patents differentiate hardware for licensed motorsport simulation partnerships.
- Xbox:Game Pass subscription infrastructure supports operational expenditure models preferred by corporate buyers.
- Android:Fragmented device ecosystem limits standardized performance guarantees for simulation workloads.
Windows leads enterprise deployment; PlayStation captures premium consumer hardware margins.
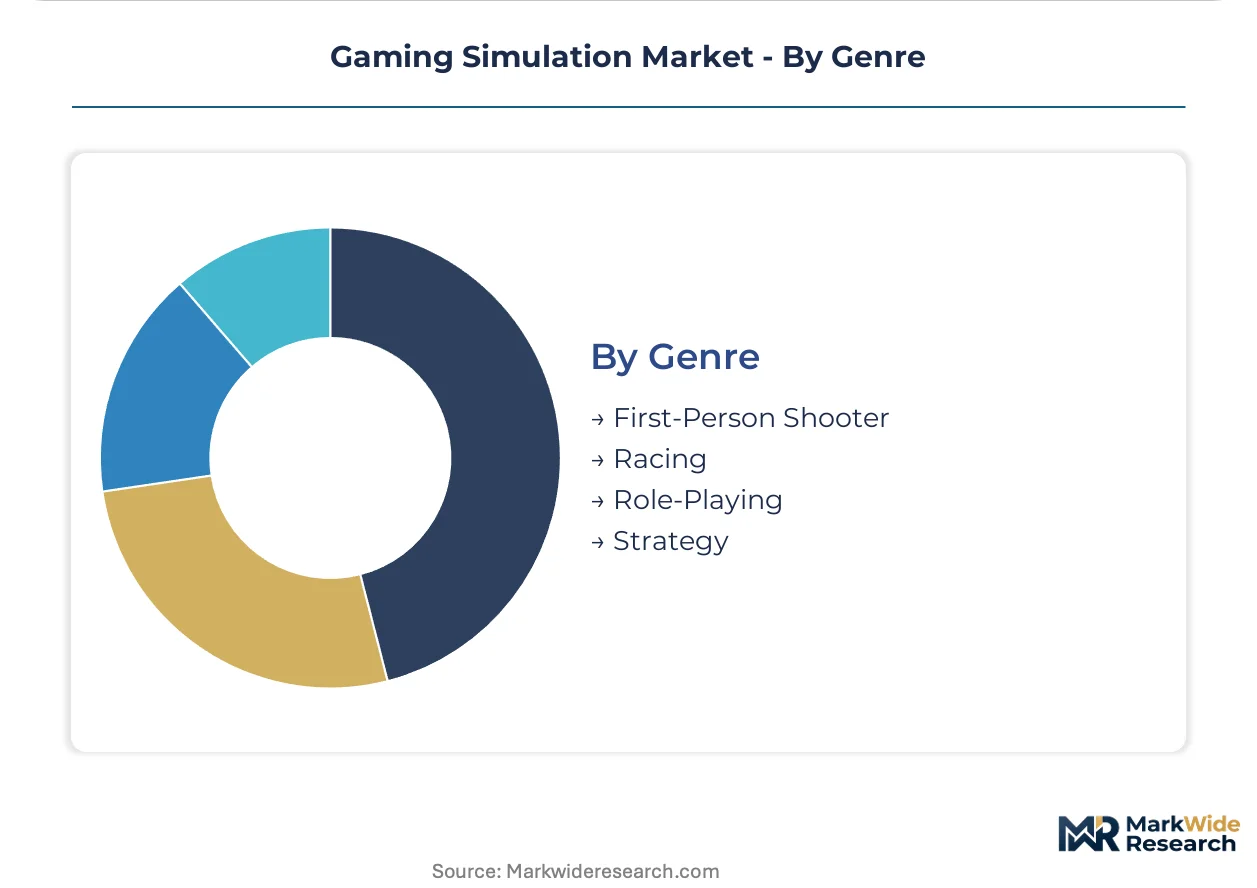
Genre:
Physics fidelity requirements and licensing complexity separate premium simulation from arcade approximations.
- Racing:Licensed vehicle partnerships and NeRF-based track scanning compress asset production timelines. Motorsport leagues adopt unified photogrammetry pipelines that merge modeling, texturing, and lighting into single-operator workflows.
- First-Person Shooter:Military training modernization drives cloud-native multi-user environment demand. United States, Germany, and Japan defense offices specify these platforms for force readiness validation.
- Role-Playing:Procedural content generation under EU AI Act disclosure mandates requires documented asset creation audit trails.
- Strategy:Lower frame-rate requirements accommodate broader hardware compatibility.
Racing commands highest per-title revenue; First-Person Shooter shows strongest defense procurement momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting simulation hardware production toward jurisdictions with streamlined electromagnetic compatibility certification. Taiwan's foundry concentration for advanced GPUs creates supply vulnerability, while Germany and Japan impose stringent data sovereignty requirements on cloud-streamed training platforms.
United States
Defense procurement offices mandate cloud-native simulation environments for joint-force exercises, with FCC equipment authorization enabling low-latency wireless VR headset deployment. HIPAA compliance obligations constrain biometric data collection in hospital-based surgical training installations. The Greater Boston cluster anchors medical simulation R&D, where teaching hospitals pilot haptic-enabled procedure certification.
Germany
Technical institutes formalize professional gaming credentials through standardized simulation competency testing, driving demand for frame-time-consistent hardware. CE marking requirements under EU directives extend electromagnetic compatibility testing timelines for hardware launches. The Bavaria region concentrates automotive engineering departments favoring subscription-based PC simulation access over capital-intensive procurement.
Japan
METI coordinates esports infrastructure expansion alongside defense modernization programs specifying multi-user simulation platforms. Japan's APPI framework governs biometric performance data storage, creating compliance complexity for cross-border training deployments. The Kanto/Tokyo metropolitan area hosts teaching hospitals piloting VR surgical certification and resident procedure simulation.
United Kingdom
GDPR-compliant biometric analytics investment from EU-based esports leagues spills into UK training technology procurement despite post-Brexit regulatory divergence. The country's national data protection authority enforces consent-managed player performance tracking standards. London/Southeast clusters concentrate broadcast production simulation studios adapting to EU AI Act procedural generation disclosure mandates.
South Korea
MFDS medical device classification rules shape VR surgical simulator market access, while 5G mmWave infrastructure investment supports untethered enterprise training installations. The Seoul Capital Area anchors esports athlete performance optimization facilities deploying sub-20ms latency motion-to-photon systems. Domestic semiconductor foundries are diversifying rendering hardware supply chains beyond Taiwan concentration.
Gaming Simulation Market Vendor Landscape
Strategic partnerships dominate the current landscape as hardware vendors pivot toward edge-streaming alliances and subscription revenue models. The vendor base concentrates around three tiers: cloud infrastructure providers, GPU-accelerated physics rendering specialists, and proprietary haptic feedback hardware developers. Technology licensing agreements and backward integration into semiconductor supply chains represent the two prevailing competitive moves.
Among North American technology conglomerates, Microsoft and NVIDIA exemplify divergent archetypes—Azure-hosted simulation instances versus GPU-accelerated rendering hardware. Sony Interactive Entertainment occupies a position within the premium hardware tier through proprietary haptic feedback patent portfolios. These three entities represent the dominant competitive anchors without implying specific strategic coordination.
| Leading Market Players |
|---|
| Electronic Arts |
| Microsoft |
| Sony Interactive Entertainment |
| Activision Blizzard |
| Take-Two Interactive |
| Ubisoft |
| Epic Games |
| NVIDIA |
| Bandai Namco Entertainment |
| Others |
Supply Flow & Price Mechanics
EU AI Act disclosure mandates for algorithmic content generation gate qualified supply access for simulation engines serving European broadcast and training markets, compressing margins for studios lacking documented procedural asset audit trails while enabling premium-tier pricing for transparent architectures. This regulatory filter simultaneously constrains vendor eligibility and stratifies pricing power across compliance-capable and non-compliant suppliers.
Pricing Analysis
Distributor margins in professional training segments compress as direct-to-OEM cloud subscription models displace perpetual license sales. Three-tier pricing structure across premium, standard, and economy levels separates military-grade multi-user environments with sub-20ms latency guarantees from single-seat consumer installations. Cost compression in mid-tier VR hardware intensifies because foundry capacity constraints limit GPU supply elasticity. Casual gamers exhibit highest price sensitivity; defense procurement offices show lowest sensitivity due to operational expenditure preference shifts.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan's foundry concentration for advanced semiconductor lithography feeding GPU-accelerated physics rendering. Hardware manufacturing draws from South Korean memory fabrication and Japanese precision component suppliers alongside Taiwanese wafer production. Tariff exposure runs through cross-border cloud infrastructure licensing between United States and European jurisdictions. Distribution runs through Azure-hosted enterprise instances for corporate buyers and direct-to-consumer retail channels for hardware peripherals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story. Defense procurement offices in the United States, Germany, and Japan are mandating cloud-native simulation environments with sub-20ms latency thresholds, filtering demand toward premium-tier vendors with proven enterprise deployment track records.
For Market Incumbents: Hedge against GPU supply concentration by securing alternative foundry relationships in South Korea while deepening backward integration into haptic feedback hardware design. Cloud rendering infrastructure is displacing localized processing, threatening perpetual license revenue streams; pivot toward subscription revenue models with Azure-hosted simulation instances to capture operational expenditure preference shifts among German automotive engineering departments and United States hospital networks. For New Entrants and Emerging Players: Begin with surgical training VR installations in Japanese teaching hospitals, where METI-coordinated infrastructure expansion creates first-mover windows before incumbent certification pathways solidify. White-space exists in GDPR-compliant biometric analytics platforms for EU-based esports leagues facing CNIL audit requirements. Target direct-to-institution sales bypassing distributor margin layers, leveraging 5G mmWave deployment for untethered enterprise training demonstrations. For Investors and Strategic Acquirers: Roll-up economics work for regional cloud-streaming specialists because defense procurement consolidation favors multi-territory compliance capabilities. Long-term viability centers on vendors with documented EU AI Act procedural generation audit trails and established HIPAA-compliant biometric data infrastructure. Watch for inflection when Japanese APPI framework amendments resolve cross-border data sovereignty conflicts with GDPR and HIPAA, unlocking unified training platform deployments.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud Infrastructure Partnership | Microsoft Azure anchors enterprise-grade simulation instances for defense procurement offices. |
| Proprietary Haptic Patent Acquisition | Sony Interactive Entertainment's feedback portfolios differentiate professional-grade hardware offerings. |
| NeRF-Based Asset Pipeline Integration | Neural radiance fields compress track scanning timelines from months to days for racing developers. |
| GDPR-Compliant Biometric Platform Launch | Consent-managed analytics satisfy CNIL audit requirements for EU esports league contracts. |
| 5G mmWave Hardware Certification | FCC equipment authorization enables untethered enterprise VR training installations. |
Methodological Framework
Multiple input streams — primary interviews with simulation engine developers, defense procurement officers, and hospital biomedical engineers; secondary validation through SEC filings of GPU manufacturers, hyperscaler capex disclosures, and EMA regulatory submission databases; plus customs records for VR headset trade flows — were reconciled through bottom-up and top-down triangulation. Stakeholder conversations spanned cloud infrastructure architects at Microsoft Azure, haptic hardware R&D leads at Sony Interactive Entertainment, and esports league operations directors in Germany and South Korea.
Data-stream reconciliation anchored volume and value outputs across product type, user category, platform ecosystem, and genre classification dimensions throughout the forecast period. CAGRs were derived from segment-level growth rate reconciliation against macro technology adoption curves. Industry-specific forecast inputs included 5G mmWave deployment timelines from FCC authorization records and METI-coordinated esports infrastructure investment schedules.
Several conditions sit outside the modeled scope, including potential Taiwan semiconductor foundry disruption, EU AI Act enforcement variance across member states, and unforeseen latency breakthroughs in residential broadband infrastructure. Forecasts reflect documented assumptions about cloud rendering adoption velocity and defense budget allocation stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gaming
Latin America Mobile Gaming Market
Gaming
Video Game Software Market
Gaming
Mobile Game Software Market
Gaming
Slot Machine Market
Gaming
Global Subscription-Based Gaming Market
Gaming
Asia-Pacific Casino Gambling Market
Gaming
China Subscription-Based Gaming Market
Gaming
Gaming As a Service Market
Gaming
3D Gaming Technology Market
Gaming
Gaming Accessories Market
Gaming
China Gaming Headsets Market
Gaming
South Korea Subscription-Based Gaming Market
Gaming
Cloud Gaming Market
Gaming
Console Games Market
Gaming
Game Engine Management Market
Gaming
Casino Gaming Equipment Market