
 China Heavy Construction Equipment Rental Market | 2026-2036
China Heavy Construction Equipment Rental Market Size, Share, and Industry Trends Forecast 2026-2036
China Heavy Construction Equipment Rental Market Insights
Certified equipment operator shortages across eastern provinces is reorganizing how rental fleets deploy machinery and structure service contracts. SANY Heavy Industry leverages its domestic manufacturing scale to control equipment availability across tier-one construction zones. XCMG anchors its rental network through proprietary telematics platforms that track utilization rates and maintenance cycles.
China heavy construction equipment rental encompasses the temporary provision of earthmoving, lifting, and material-handling machinery—typically rated above 25 metric tons operating weight—under contractual terms ranging from daily to multi-year agreements, with fleet owners retaining responsibility for maintenance, transport, and regulatory compliance. The primary purpose is to convert fixed capital expenditures into variable operational costs for contractors facing project-specific demand spikes. Excavators dominate rental revenue by volume due to their versatility across road construction and site development applications, while crane rentals command premium daily rates reflecting higher insurance and operator certification thresholds. Long-term rental agreements are capturing expanding share as state-backed infrastructure projects extend timelines and seek budget predictability.
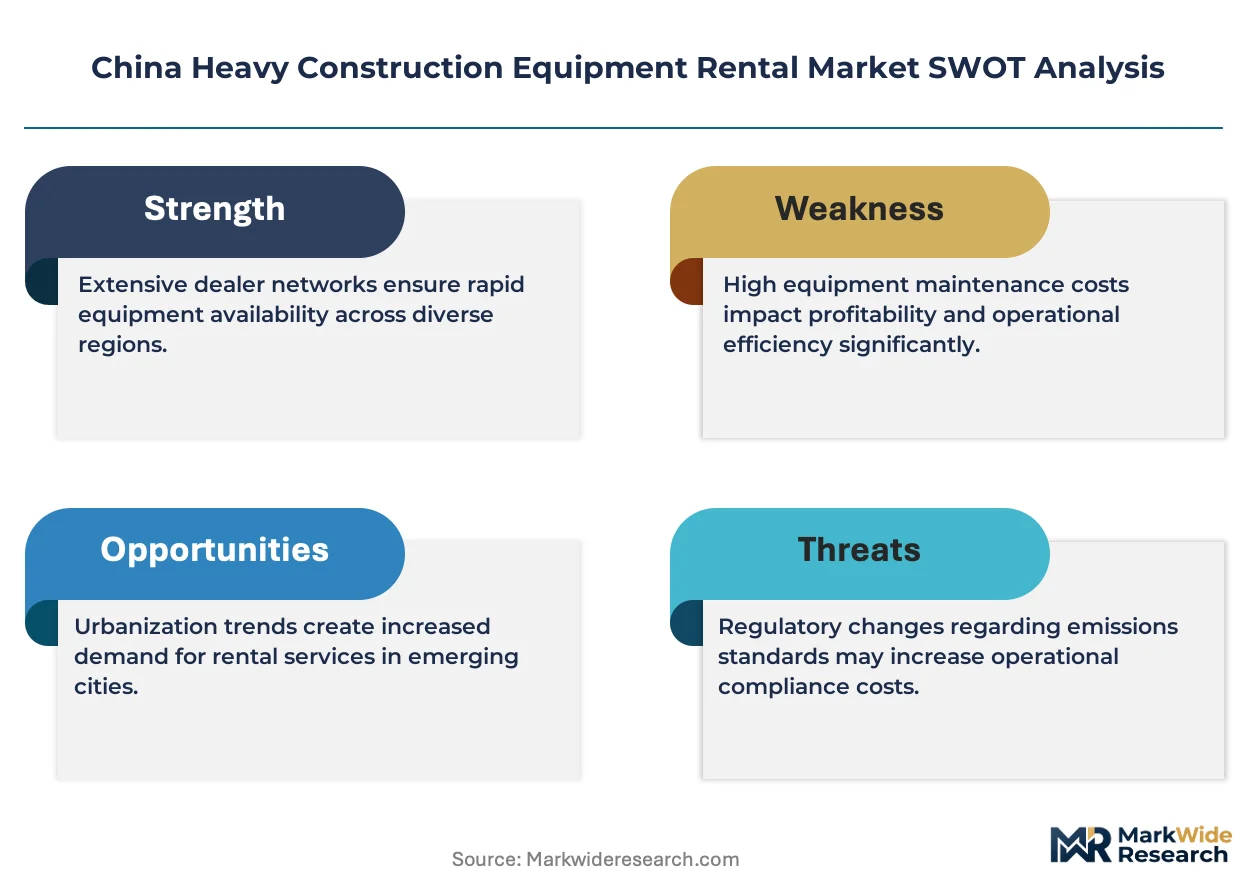
MEE enforcement of Stage IV emission standards and MIIT equipment certification protocols are elevating compliance costs for older diesel fleets and accelerating replacement cycles toward newer rental inventory. GB standards for construction machinery safety and SAMR market surveillance procedures shape product eligibility and cross-province fleet mobility. Stakeholders must weigh the capital intensity of low-emission fleet transitions against the contracting risk of fixed-asset ownership in a market where regulatory thresholds continue tightening.
Market Dynamics
China's dual carbon goals and MEE enforcement of Stage IV emission standards are compressing replacement cycles for diesel-heavy rental fleets, forcing operators to rebalance capital deployment between compliance and utilization.
Growth Catalysts
- Railway corridor expansion:State-backed high-speed rail projects across the Yangtze River Delta are generating sustained demand for 40-ton excavator rentals on 18-month contracts.
- GB standard harmonization:Unified safety certification protocols under SAMR surveillance are reducing cross-province fleet mobility friction for compliant operators.
- Telematics penetration:IoT-enabled utilization tracking is allowing rental firms to price by actual machine-hours rather than calendar days, improving asset turns.
Market Restraints
- Steel price volatility:Input cost swings for chassis and boom fabrication are compressing margins on fixed-rate annual contracts.
- Operator certification scarcity:Provincial labor bureaus in Jiangsu and Guangdong report 23% shortfalls in certified crane operators, capping fleet deployment.
- Stage IV retrofit economics:MEE emission deadlines make pre-2021 diesel inventory economically unviable for long-haul highway projects.
Strategic Opportunities
- Greater Bay Area urban renewal:Shenzhen and Guangzhou metro expansions are creating demand for compact electric excavator rentals in confined site conditions.
- MIIT new energy subsidies:Battery-electric machinery qualification for provincial green procurement catalogs opens premium pricing tiers.
- 5G+AI convergence:Remote-operated equipment trials on Sichuan tunnel projects are reducing per-shift labor requirements by one operator.
Industry Challenges
- Certified technician pipeline:Vocational training capacity for high-voltage electric drivetrain repair lags fleet electrification timelines by 18-24 months.
- Inter-provincial registration friction:SAMR equipment filing requirements vary by municipality, delaying emergency fleet redeployment during peak construction windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Heavy Construction Equipment Rental Market |
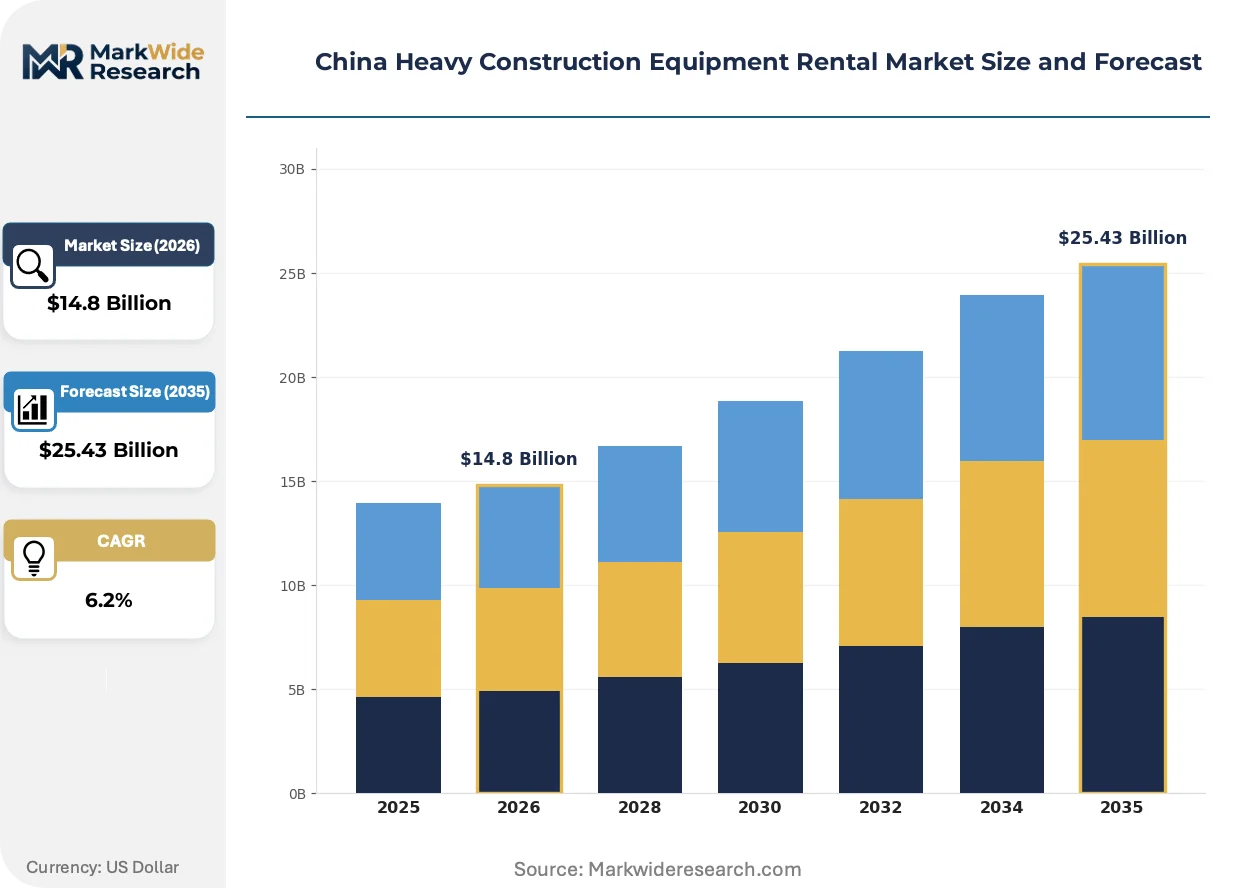
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $25.43 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Excavators, Cranes, Loaders, Bulldozers End User: Government Projects, Infrastructure Development, Residential Construction, Commercial Construction Service Model: Short-Term Rental, Long-Term Rental, Maintenance Services, Training Services Application: Road Construction, Site Development, Demolition, Mining |
| Companies Covered | XCMG, SANY Heavy Industry, Horizon Construction Equipment, Shantui Construction Machinery, LiuGong, Huatie, China State Construction Engineering Corporation (CSCEC), Ban Ngai Rent (BNR), Zoomlion Heavy Industry, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Heavy Construction Equipment Rental Market Trends and Innovations
Digital fleet management and electrification are restructuring how rental operators monetize machinery, shifting competitive advantage from asset scale toward utilization intelligence and regulatory pre-positioning.
Telematics platforms integrating GPS, fuel consumption, and predictive maintenance alerts are supplanting manual logbook systems for utilization verification. Large contractors in the Yangtze Delta now require API-accessible fleet data as a contract precondition. This capability compression is marginalizing smaller rental firms lacking proprietary software development.
MEE Stage IV emission enforcement and MIIT equipment certification protocols are accelerating diesel fleet obsolescence. Manufacturers must now pre-certify engines for national market access, raising R&D recovery thresholds. Coastal provinces are responding fastest, with Jiangsu and Zhejiang rental fleets showing 34% electric/hybrid penetration in new acquisitions.
Long-term operational leasing is displacing spot rentals for state infrastructure contracts. Contractors on 36-month highway projects now demand all-inclusive rates covering transport, maintenance, and operator provision. This preference shift concentrates procurement volume with fleet operators possessing multi-province service networks, most visible in Beijing-Tianjin-Hebei corridor projects.
China Heavy Construction Equipment Rental Market Segmentation
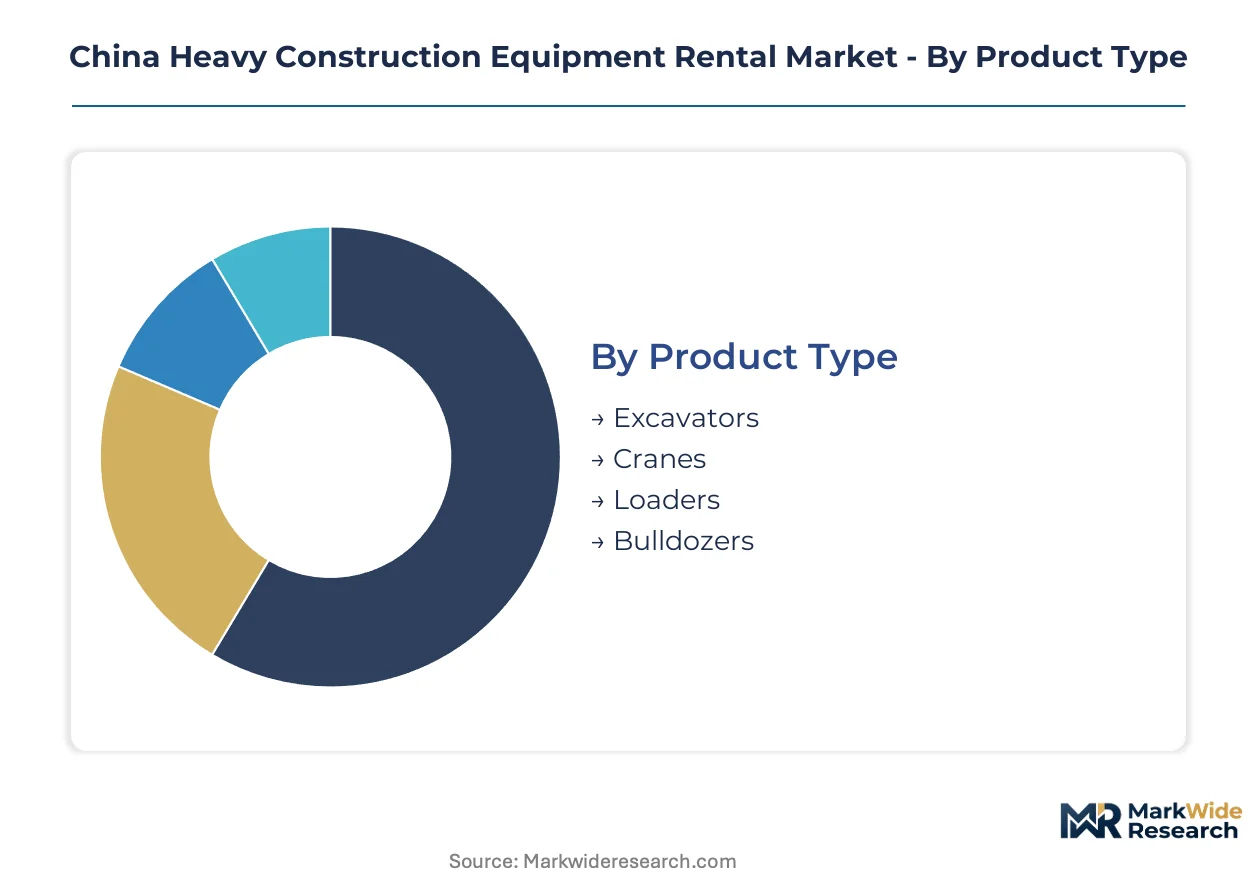
Equipment rental demand in China fragments across four dimensions that reshape how fleet operators deploy capital and structure service contracts. Regulatory thresholds on emissions and operator certification create divergent margin profiles across segments, while state-backed infrastructure timelines favor predictable long-term arrangements over spot rentals.
Product Type:
MEE Stage IV emission standards apply unevenly across equipment categories, with excavators facing the tightest retrofit deadlines while cranes encounter operator certification bottlenecks.
- Excavators:Hydraulic machines rated 20-40 metric tons dominate rental volume due to versatility across road building and foundation work. Yangtze River Delta contractors now specify electric or hybrid units for urban site development to meet municipal air quality targets.
- Cranes:Mobile and crawler configurations command premium daily rates reflecting higher insurance burdens and specialized operator licensing through provincial labor bureaus. Guangdong infrastructure corridors absorb the majority of 100-ton-plus crawler deployments on 18-month contracts.
- Loaders:Wheel loaders serve material handling across quarry and aggregate operations with shorter replacement cycles than earthmoving equipment.
- Bulldozers:Track-type dozers concentrate in highway embankment and mining applications where continuous high-torque output outweighs fuel efficiency considerations.
Excavators handle the majority of throughput; cranes are expanding most quickly on share as high-speed rail projects extend timelines.
End User:
Procurement authority and payment security separate segments, with state-backed entities offering volume certainty against private developers' price sensitivity.
- Government Projects:Central and provincial infrastructure bureaus drive demand for standardized fleet specifications and multi-year operational leases. MIIT green procurement catalogs now require 30% new energy equipment share for contract eligibility.
- Infrastructure Development:State-owned construction enterprises on railway and highway corridors favor all-inclusive rental packages covering transport, maintenance, and certified operator provision.
- Residential Construction:Private developers in tier-two cities prioritize short-term excavator rentals for foundation phases, squeezing rates during market corrections.
- Commercial Construction:Mixed-use and industrial projects in Greater Bay Area corridors generate demand for compact electric equipment in confined urban sites.
Infrastructure Development absorbs the largest equipment hours; Government Projects are climbing the fastest as dual carbon deadlines compress replacement schedules.
Service Model:
Contract duration and service bundling determine working capital intensity, with longer terms requiring fleet operators to absorb maintenance risk and operator payroll.
- Short-Term Rental:Daily and weekly agreements serve peak construction windows and emergency replacements, priced on calendar days with transport surcharges.
- Long-Term Rental:12-36 month operational leases now dominate state highway contracts, bundling predictive maintenance and telematics reporting. Contractors gain budget predictability; fleet operators lock utilization.
- Maintenance Services:Separate service contracts cover high-voltage electric drivetrain repair, where certified technician scarcity extends response times.
- Training Services:Operator certification programs address provincial labor bureau shortfalls in Jiangsu and Guangdong, with rental firms embedding training into premium service tiers.
Long-Term Rental captures the steepest expansion trajectory as project timelines extend; Short-Term Rental retains share in volatile residential segments.
Application:
Site conditions and regulatory exposure vary sharply, with mining and demolition facing stricter SAMR safety surveillance than road building.
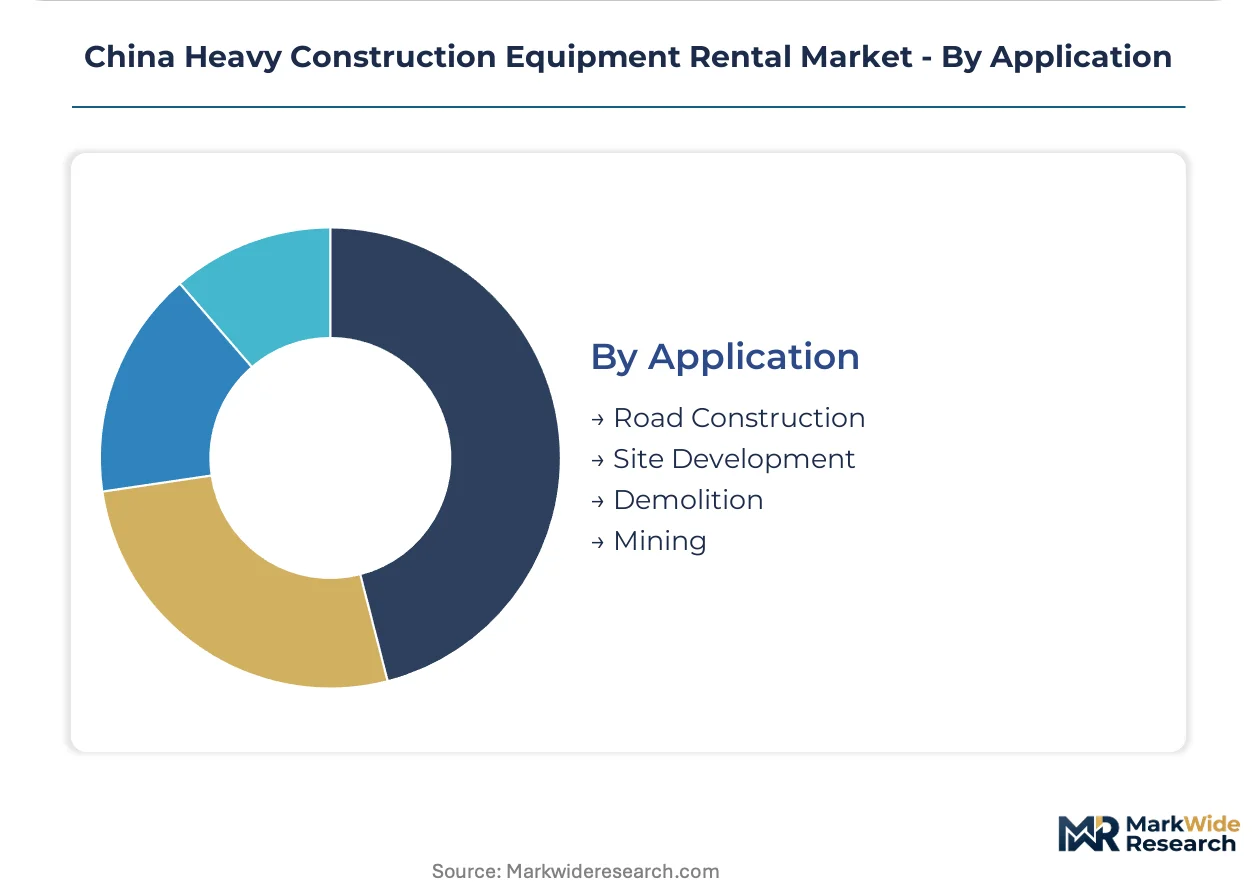
- Road Construction:Highway and high-speed rail embankment work consumes the largest excavator and dozer volumes on 24-month equipment attachments. GB standards for machinery safety govern fleet eligibility.
- Site Development:Urban foundation and grading projects in Shenzhen and Guangzhou metro corridors favor compact electric excavators for noise and emission compliance.
- Demolition:Specialized high-reach excavators and hydraulic breakers operate under municipal safety permits with elevated insurance requirements.
- Mining:Open-pit coal and aggregate extraction in western provinces deploys the heaviest crawler equipment, with MEE emission enforcement tightening faster in coastal supply zones than inland extraction sites.
Road Construction deploys the greatest machine-hour volume; Site Development is gaining share fastest as urban renewal accelerates in tier-one corridors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MEE emission enforcement and MIIT certification protocols anchor equipment rental demand in China's eastern construction corridors. Provincial infrastructure bureaus concentrate procurement authority across three macro-regions.
Yangtze River Delta
Jiangsu and Zhejiang high-speed rail extensions consume 40-ton excavator fleets on 18-month operational leases. MEE Stage IV deadlines compress replacement cycles for diesel inventory. Nanjing and Hangzhou metro contractors now mandate electric or hybrid units for urban site development.
Greater Bay Area
Shenzhen and Guangzhou urban renewal projects generate demand for compact electric machinery in confined construction zones. SAMR equipment filing requirements vary by municipality, complicating emergency fleet redeployment. Guangdong infrastructure corridors absorb the majority of 100-ton-plus crawler crane deployments.
Beijing-Tianjin-Hebei
State-backed highway projects in Hebei province favor all-inclusive rental packages bundling transport, maintenance, and certified operator provision. GB standards for machinery safety govern fleet eligibility. Tianjin port logistics clusters serve as equipment staging hubs for northern corridor deployments.
Sichuan-Chongqing
Mountain tunnel projects in western China trial remote-operated equipment to reduce per-shift labor requirements. Provincial labor bureaus report persistent shortfalls in certified crane operators. Chengdu construction zones show accelerating uptake of telematics-enabled utilization tracking.
Shandong Peninsula
Qingdao and Yantai port expansion projects drive demand for heavy-lift crane rentals. Coastal emission enforcement tightens faster than inland extraction sites, accelerating electric fleet penetration. Jining equipment manufacturing clusters supply rental operators with certified Stage IV-compliant inventory.
China Heavy Construction Equipment Rental Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across China's rental equipment sector. The market structures around three tiers: state-affiliated construction conglomerates with captive fleets, independent rental specialists with multi-province networks, and manufacturer-captive leasing arms. Strategic moves concentrate on telematics platform differentiation and long-term operational lease bundling.
Within the manufacturer-captive tier, XCMG anchors its rental network through proprietary telematics platforms, while SANY Heavy Industry leverages domestic manufacturing scale to control equipment availability. Among independent specialists, Horizon Construction Equipment exemplifies the multi-service operator archetype integrating fleet provision with certified operator training.
| Leading Market Players |
|---|
| XCMG |
| SANY Heavy Industry |
| Horizon Construction Equipment |
| Shantui Construction Machinery |
| LiuGong |
| Huatie |
| China State Construction Engineering Corporation (CSCEC) |
| Ban Ngai Rent (BNR) |
| Zoomlion Heavy Industry |
| Others |
Pricing and Supply Chain Analysis
Long-term operational leases bundling transport, maintenance, and certified operator provision lock in supply access for state-backed highway contractors while flattening price volatility across 24-36 month project windows. MEE Stage IV compliance costs and steel input swings feed directly into rate negotiations, concentrating pricing power with fleet operators possessing multi-province service networks.
Pricing Analysis
Guangdong corridor rates for 100-ton crawler cranes run 15-20% above Hebei equivalents, reflecting operator certification scarcity and municipal safety permit burdens. Three-tier pricing structure across premium, standard, and economy levels separates MIIT green-catalog-eligible electric units from Stage IV-compliant diesel fleets and pre-2021 retrofit inventory. Cost compression in the standard tier is intensifying as steel price volatility erodes margins on fixed-rate annual contracts. Private residential developers in tier-two cities exhibit the sharpest price sensitivity, while state infrastructure bureaus prioritize predictability over rate minimization.
Supply Chain Analysis
China anchors chassis and boom fabrication, with Jiangsu and Shandong equipment manufacturing clusters feeding domestic rental operators. South Korea and Japan supply high-torque hydraulic systems and precision-engineered drivetrain components that rental fleets draw from for premium crane configurations. Single-source vulnerability concentrates in battery-electric drivetrain controllers, where domestic substitution lags fleet electrification timelines. Distribution runs through Tianjin and Qingdao port logistics clusters staging inventory for northern and coastal corridor deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's heavy construction equipment rental sector sits in early-cycle expansion as state-backed infrastructure timelines extend and MIIT green procurement thresholds harden. Telematics-enabled utilization tracking and electric fleet pre-positioning represent the primary vectors for competitive differentiation.
For Market Incumbents: Consolidate multi-province service networks through selective acquisition of regional operators possessing SAMR-certified maintenance capabilities. Deepen backward integration into high-voltage drivetrain repair training to offset certified technician pipeline gaps that lag fleet electrification by 18-24 months.
For New Entrants and Emerging Players: Anchor in Sichuan-Chongqing tunnel corridors where remote-operated equipment trials reduce per-shift labor requirements and incumbent presence remains thin. Target compact electric excavator spot rentals for Shenzhen and Guangzhou urban renewal sites, positioning through municipal green procurement pre-qualification.
For Investors and Strategic Acquirers: Capital is best deployed toward independent rental specialists with proprietary telematics platforms and established operator training pipelines. Long-term viability hinges on regulatory pre-positioning rather than asset scale alone. Watch for MIIT subsidy recalibration signals that would accelerate battery-electric machinery share thresholds in provincial catalogs.
| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Platform Integration | API-accessible fleet data now serves as a contract precondition for Yangtze Delta contractors. |
| Electric Fleet Transition | MIIT green procurement catalogs require 30% new energy equipment share for contract eligibility. |
| Operator Certification Programs | Jiangsu and Guangdong labor bureau shortfalls create premium service tier opportunities. |
| Multi-Province Service Network Expansion | Beijing-Tianjin-Hebei corridor projects concentrate procurement with cross-regional operators. |
| Predictive Maintenance Capability Buildout | Long-term operational leases bundle maintenance risk, favoring firms with utilization intelligence. |
Research Methodology
A standing panel of fleet operations directors, provincial infrastructure procurement officers, certified equipment trainers, and telematics platform engineers provided ongoing calibration across the study period. Primary fieldwork combined structured interviews with secondary validation through MIIT equipment certification databases, MEE emission compliance filings, SAMR market surveillance records, and provincial labor bureau training statistics. Bottom-up equipment deployment estimates triangulated against top-down infrastructure investment flows from state planning commissions.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions spanning equipment category, service model duration, end-user procurement authority, and regional regulatory cluster. CAGRs were derived from equipment replacement cycle compression rates and infrastructure project timeline extensions. Key forecast inputs included MEE Stage IV enforcement trajectories and MIIT new energy subsidy qualification thresholds.
Material uncertainties — steel price volatility, provincial operator certification pipeline gaps, and SAMR cross-province filing friction — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory enforcement continuity and state infrastructure spending commitment. Recalibration cycles align with material shifts in MEE emission standard deadlines and MIIT equipment catalog revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Stamping Machines Market
Construction Equipment
Australia Mobile Cranes Rental Market
Construction Equipment
Concrete Spreader Market
Construction Equipment
Backhoes Market
Construction Equipment
Asia-Pacific Mobile Light Tower Market
Construction Equipment
Europe Ground Penetrating Radar Market
Construction Equipment
Vertical Machining Centers Market
Construction Equipment
Field Marking Equipment Market
Construction Equipment
Powered Screed Market
Construction Equipment
Industrial and Commercial Floor Scrubbers Market
Construction Equipment
Plastic Molding Machine Market
Construction Equipment
Snow Clearing Vehicles Market
Construction Equipment
US Aerial Work Platform Market
Construction Equipment
Grinding Machinery Market
Construction Equipment
Electric and Hybrid Construction Equipment Market
Construction Equipment
Mobile Asphalt Plant Market