
 Europe Hereditary Cancer Testing Market | 2026-2036
Europe Hereditary Cancer Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Hereditary Cancer Testing Market Foresight
Next-generation sequencing is rewriting the economics of hereditary cancer diagnostics across European clinical laboratories. Illumina Inc. leverages its installed base of sequencing platforms to sustain instrument recurring revenue in high-throughput oncology centers. QIAGEN NV anchors its position through sample-to-insight workflows that integrate DNA extraction with variant interpretation software. Thermo Fisher Scientific competes by extending its CE-IVD portfolio under the IVDR framework.
Hereditary cancer testing identifies germline mutations in genes such as BRCA1, BRCA2, and mismatch repair genes associated with Lynch Syndrome using blood or saliva specimens, with turnaround times typically ranging from ten to twenty-one days for comprehensive panel analysis. Its primary purpose is to stratify individual cancer risk and guide preventive surgery or intensified surveillance protocols. Next-generation sequencing panels dominate test type segmentation due to their multiplexing capacity and declining per-gene cost structure. Diagnostic laboratories capture the largest end-user share, though cancer centers are building in-house molecular pathology capabilities that shift volume away from centralized reference labs.
The European Medicines Agency (EMA) coordinates pharmacogenomic guidance that influences companion diagnostic development, while the EU In Vitro Diagnostic Regulation (IVDR) mandates notified body oversight for hereditary cancer assays previously self-certified under the IVDD. National health technology assessment bodies in France, Germany, and England determine reimbursement eligibility for predictive genetic testing, directly shaping manufacturer commercial strategy. Stakeholders must monitor how IVDR transition timelines and divergent national reimbursement decisions create fragmented market access conditions across the continent.
Market Dynamics
The IVDR transition is compressing market access timelines and forcing manufacturers to rebuild certification portfolios under notified body oversight, fundamentally restructuring competitive positioning across European hereditary cancer diagnostics.
Growth Catalysts
- Germany's statutory health insurance expansion:Broadened reimbursement for predictive genetic testing has unlocked patient access in university hospital oncology departments. Diagnostic laboratories in Berlin and Munich are scaling BRCA panel throughput.
- CE-IVD pathway maturation:Manufacturers achieving IVDR certification gain preferential procurement status in France's hospital purchasing consortia. The notified body stamp accelerates tender participation.
- Next-generation sequencing cost compression:Multiplexed germline panels now deliver BRCA1/2 plus Lynch Syndrome analysis at per-gene economics that enable population-scale screening programs in England's NHS trusts.
Market Restraints
- Notified body capacity bottleneck:IVDR technical documentation review queues now extend eighteen to twenty-four months, freezing product launch calendars for mid-tier assay developers.
- Reimbursement fragmentation:France's HAS maintains restrictive criteria for predictive testing outside confirmed familial mutations, limiting addressable volume versus Germany's statutory coverage.
- Variant interpretation labor intensity:VUS (variants of uncertain significance) rates in moderate-penetrance genes require genetic counselor review, capping laboratory scalability.
Strategic Opportunities
- Spain and Italy reimbursement gap closure:Regional health services in Catalonia and Lombardy are piloting predictive testing pilots that could expand to national coverage frameworks.
- Liquid biopsy germline confirmation:Cell-free DNA platforms are converging with tissue-based hereditary panels to enable cascade screening without venipuncture, opening pediatric and needle-phobic segments.
- Pharmacogenomic companion diagnostic bundling:EMA guidance on PARP inhibitor labeling creates regulatory tailwind for BRCA testing integration into oncology prescribing workflows.
Industry Challenges
- Bioinformatics pipeline validation:Each laboratory must independently verify variant calling algorithms against reference materials, duplicating effort across European sites without harmonized standards.
- Genetic counselor workforce density:Pre-test consent and post-test disclosure requirements strain specialized staffing in England's regional genetics services, extending turnaround times.
- Legacy LIMS integration:Hospital laboratories running decades-old laboratory information management systems face middleware complexity when connecting to cloud-based variant interpretation platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Hereditary Cancer Testing Market |
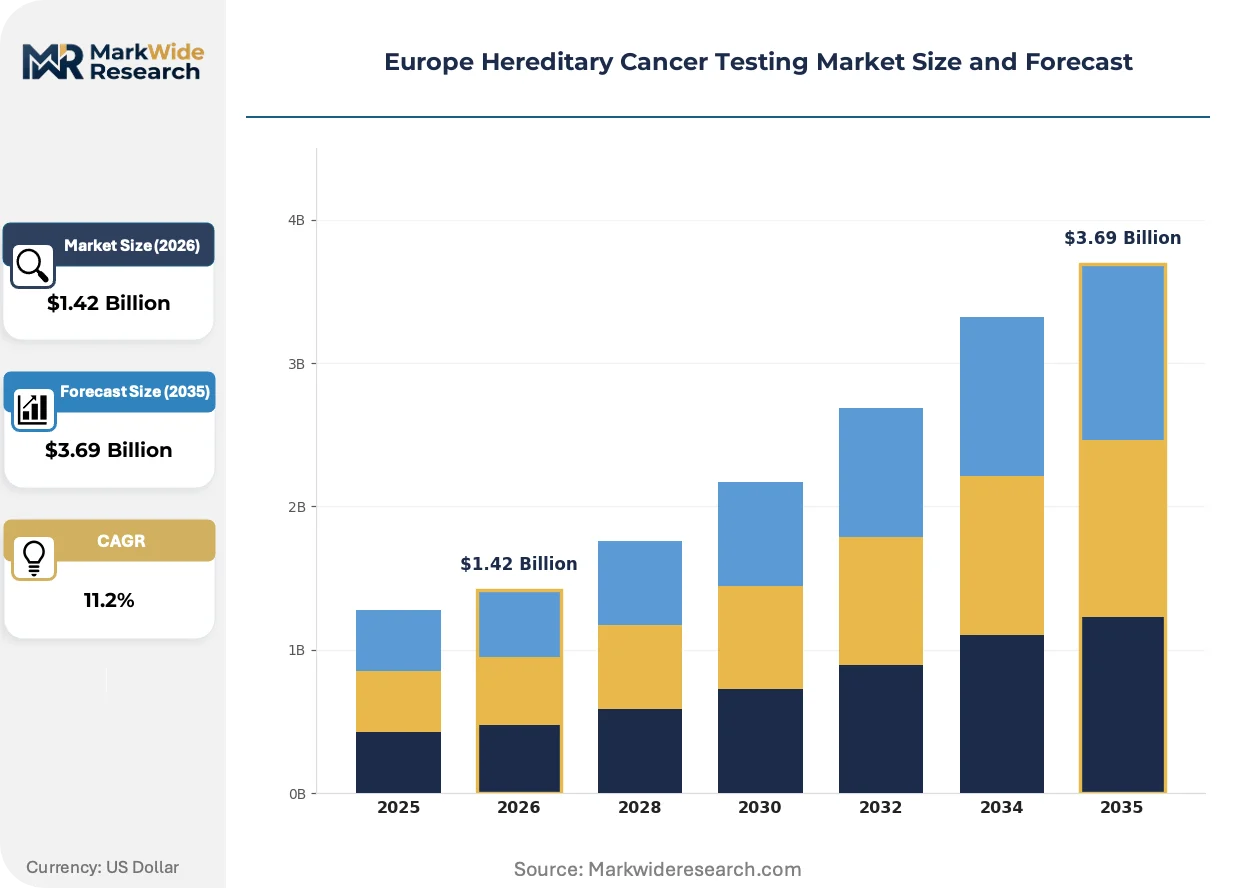
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $3.69 Billion |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Test Type: BRCA1, BRCA2, Lynch Syndrome, Familial Adenomatous Polyposis End User: Hospitals, Diagnostic Laboratories, Research Institutions, Cancer Centers Technology: Sanger Sequencing, Next-Generation Sequencing, Microarray Analysis, PCR Service Type: Genetic Counseling, Testing, Interpretation, Data Management |
| Companies Covered | F. Hoffmann-La Roche AG, Invitae Corporation, Myriad Genetics, Quest Diagnostics, Eurofins Scientific, Illumina Inc., QIAGEN NV, Centogene AG, Thermo Fisher Scientific, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Hereditary Cancer Testing Market Shifts & Advancements
Hereditary cancer diagnostics is virtualizing laboratory infrastructure and compressing the distance between sample acquisition and clinical decision, with three forces actively restructuring value capture.
Cloud-based variant interpretation is virtualizing the bioinformatics layer that previously anchored competitive advantage to on-premise server farms. Mid-sized diagnostic laboratories in the Netherlands and Belgium are adopting SaaS platforms for automated ACMG classification, eliminating capital expenditure on local compute clusters. This virtualization is compressing the economic moat between high-throughput reference laboratories and hospital-based molecular pathology units.
The EU In Vitro Diagnostic Regulation is mandating clinical evidence requirements that exceed IVDD self-certification thresholds. Manufacturers must now submit performance evaluation reports with patient cohort data to notified bodies, extending development timelines. Cancer centers in France and Germany are responding by consolidating procurement around IVDR-certified suppliers with established quality management systems.
Direct-to-consumer genetic testing fallout has sensitized European regulators to consent documentation standards. Hospital laboratories are now requiring pre-test genetic counseling as a condition of BRCA panel ordering, with England's NHS embedding counselor video consultation into electronic referral pathways. This behavioral shift is most visible in Nordic countries, where national biobank infrastructure enables population-wide cascade screening with centralized consent tracking.
Europe Hereditary Cancer Testing Market Segmentation
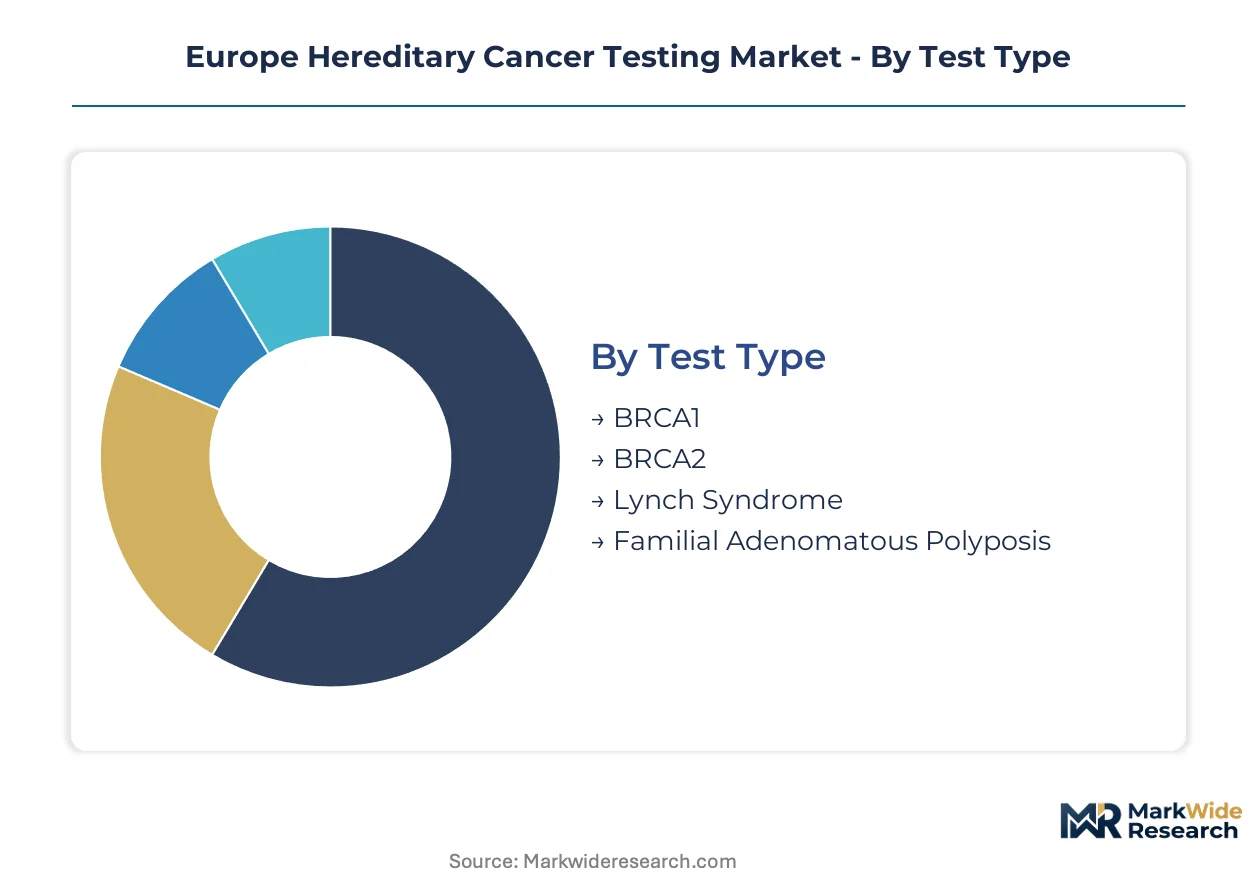
Hereditary cancer testing segments reflect divergent technology maturities and reimbursement pathways across European healthcare systems. Test type and technology choices determine laboratory capital requirements, while end-user concentration shapes regional competitive intensity.
Test Type:
Mature screening panels dominate hospital procurement budgets, while emerging gene combinations capture pilot program funding in precision oncology networks.
- BRCA1:Germline mutation screening for breast and ovarian cancer susceptibility using blood or saliva specimens. Demand concentrates in Germany's university hospital oncology departments, where statutory health insurance reimbursement has broadened access beyond familial risk criteria.
- BRCA2:Complementary high-penetrance gene analysis often multiplexed with BRCA1 in single-panel workflows. France's HAS maintains restrictive prescription criteria, limiting volume versus Germany's statutory coverage expansion.
- Lynch Syndrome:Mismatch repair gene panel for colorectal and endometrial cancer risk stratification. England's NHS trusts are piloting population-scale screening programs.
- Familial Adenomatous Polyposis:APC gene testing for inherited colorectal polyposis syndromes. Regional genetics services in the Netherlands handle most referrals.
BRCA1 retains volume leadership; Familial Adenomatous Polyposis holds the steepest expansion curve in specialized hereditary gastroenterology clinics.
End User:
Customer type determines service intensity and pricing power, with in-house molecular pathology capabilities shifting volume away from centralized reference models.
- Hospitals:University medical centers in Berlin, Paris, and London anchor BRCA panel throughput with embedded genetic counseling services.
- Diagnostic Laboratories:High-throughput reference labs in Munich and Rotterdam process cascade screening for regional health networks.
- Research Institutions:National biobank infrastructure in Nordic countries enables population-wide germline studies with centralized consent tracking.
- Cancer Centers:Comprehensive oncology units in France and Germany are building in-house NGS capabilities to reduce turnaround times.
Diagnostic Laboratories retain volume leadership; Cancer Centers are gaining share fastest through vertical integration of molecular pathology.
Technology:
Cost tier stratification separates capital-intensive platforms from accessible entry-level methods, with cloud-based bioinformatics compressing the economic gap between deployment scales.
- Next-Generation Sequencing:Multiplexed germline panels deliver BRCA1/2 plus Lynch Syndrome analysis with declining per-gene economics. Mid-sized labs in Belgium and the Netherlands are adopting SaaS variant interpretation to eliminate local compute clusters.
- Sanger Sequencing:Gold-standard confirmation method for variant validation in moderate-penetrance genes. Regional genetics services in England maintain capacity for targeted familial mutation tracking.
- PCR:Rapid targeted amplification for known founder mutations in Ashkenazi Jewish populations. Community laboratories in London and Paris deploy for pre-test screening.
- Microarray Analysis:Copy number variant detection for large genomic rearrangements missed by short-read sequencing. Reference laboratories in Germany offer as reflex testing.
Next-Generation Sequencing retains volume leadership; PCR holds the steepest expansion curve in point-of-care screening pilots.
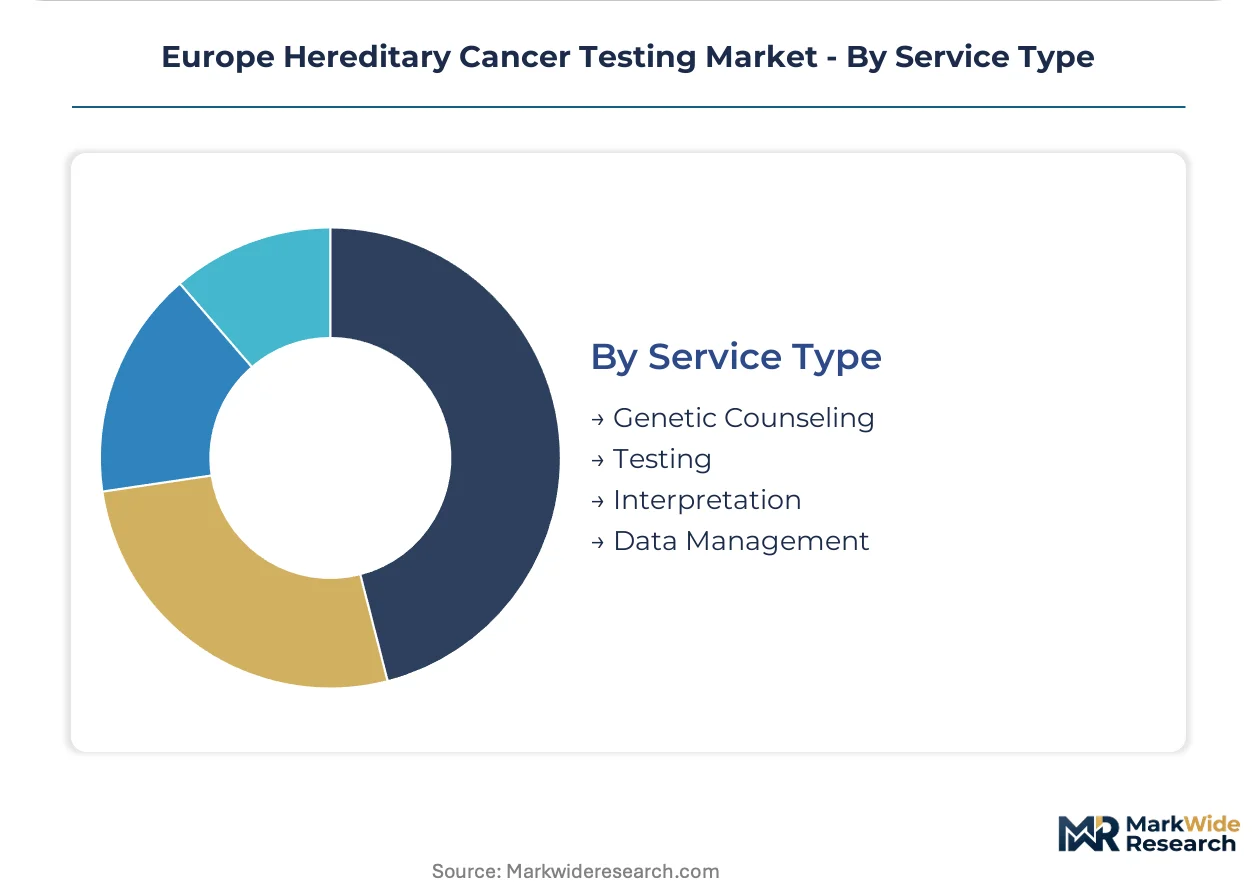
Service Type:
Margin structure varies by labor intensity, with interpretation and counseling services commanding premium pricing over commoditized wet-lab processing.
- Testing:Wet-lab processing of blood or saliva specimens with ten-to-twenty-one-day turnaround for comprehensive panels. Automation is compressing unit costs in high-throughput facilities.
- Genetic Counseling:Pre-test consent and post-test disclosure requirements strain specialized staffing in England's regional genetics services, extending turnaround times.
- Interpretation:ACMG classification of variants of uncertain significance requires board-certified molecular pathologist review. Cloud platforms are virtualizing this layer.
- Data Management:Longitudinal risk tracking and family cascade screening coordination. Nordic national biobank infrastructure enables centralized consent documentation.
Testing retains volume leadership; Genetic Counseling holds the steepest expansion curve as mandatory pre-test requirements spread across EU jurisdictions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
University hospital oncology departments concentrate procurement authority across Europe, with statutory reimbursement frameworks determining patient access velocity in each national market. Germany's statutory health insurance system and England's NHS commissioning structures represent divergent buyer archetypes shaping regional demand patterns.
Germany
Statutory health insurance reimbursement for predictive genetic testing has broadened beyond familial risk criteria, unlocking BRCA panel volume in Berlin and Munich university hospitals. The G-BA (Federal Joint Committee) determines inclusion of genetic tests in the uniform benefit catalogue. Munich's diagnostic laboratories are scaling high-throughput NGS workflows to serve cascade screening for regional health networks.
United Kingdom
NHS England's Genomic Medicine Service consolidates hereditary cancer testing through designated genomic laboratory hubs with standardized panel menus. NICE technology appraisals influence PARP inhibitor companion diagnostic requirements. The Cambridge-Oxford-London corridor anchors molecular pathology capacity with embedded genetic counseling services in regional genetics services.
France
HAS (Haute Autorité de Santé) maintains restrictive criteria for predictive testing outside confirmed familial mutations, limiting addressable volume versus German statutory coverage. ANSM oversees IVD market access under IVDR transition timelines. Paris university hospital purchasing consortia prioritize IVDR-certified suppliers with established quality management systems in tender participation.
Netherlands
Regional genetics services in Rotterdam and Leiden handle mismatch repair gene referrals with centralized consent tracking enabled by national biobank infrastructure. The Dutch Healthcare Authority (NZa) regulates genetic testing tariff structures. Mid-sized laboratories in Belgium and the Netherlands are adopting SaaS variant interpretation platforms to eliminate local compute cluster capital expenditure.
Spain
Catalonia's regional health service pilots predictive testing programs that could expand to national coverage frameworks pending health technology assessment outcomes. The Spanish Agency for Medicines and Health Products (AEMPS) coordinates IVDR implementation timelines. Barcelona's hospital laboratories are building in-house NGS capabilities to reduce turnaround times for hereditary gastroenterology referrals.
Europe Hereditary Cancer Testing Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented procurement environments where IVDR certification status determines tender eligibility. The vendor base stratifies between sequencing platform incumbents with installed instrument bases and assay developers seeking notified body approval. Two strategic archetypes dominate: integrated sample-to-insight workflow providers and modular test kit specialists. Competitive moves center on IVDR certification portfolio expansion and strategic partnerships with university hospital oncology departments.
Among North American-listed diagnostics corporations, Invitae Corporation and Myriad Genetics exemplify the direct-to-patient and hereditary cancer specialist archetypes respectively. European-headquartered players include QIAGEN NV, representing integrated workflow positioning, and Centogene AG, occupying a rare disease and hereditary testing focus. Thermo Fisher Scientific and Illumina Inc. anchor the instrumentation and consumables tier with platform-centric recurring revenue models. F. Hoffmann-La Roche AG sits within the pharmaceutical-diagnostic convergence archetype, while Eurofins Scientific represents the laboratory services network expansion model.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche AG |
| Invitae Corporation |
| Myriad Genetics |
| Quest Diagnostics |
| Eurofins Scientific |
| Illumina Inc. |
| QIAGEN NV |
| Centogene AG |
| Thermo Fisher Scientific |
| Others |
Supply & Pricing Matrix
Notified body certification bottlenecks under the EU IVDR regime compress both pricing tier spreads and supply chain configuration, forcing mid-tier assay developers into extended queue positions while IVDR-certified incumbents capture preferential procurement status in German and French hospital purchasing consortia.
Pricing Analysis
Cost-plus contracts with reagent indexation dominate German statutory health insurance reimbursement frameworks, anchoring per-test pricing to consumable input costs rather than clinical value. Price differentiation stems from IVDR certification tier and volume scale, with high-throughput reference laboratories in Munich and Rotterdam commanding standard-tier economics while hospital-based molecular pathology units absorb premium pricing for rapid-turnaround services. Pricing pressure intensifies in England's NHS genomic laboratory hubs as standardized panel menus compress margins across centralized procurement. Cancer centers building in-house NGS capabilities exhibit the highest price sensitivity, while university hospital oncology departments in Berlin and Paris demonstrate lower sensitivity due to embedded genetic counseling service bundling.
Supply Chain Analysis
Contract manufacturing for sequencing consumables concentrates in the United States, Singapore, and Germany, with Thermo Fisher Scientific and Illumina Inc. operating captive production facilities that anchor reagent supply security. The supply chain draws from specialized biochemical inputs including fluorophore-labeled nucleotides, polymerase enzymes, and synthetic oligonucleotide libraries sourced from Swiss and Japanese specialty chemical suppliers. Single-source vulnerability in flow-cell manufacturing for next-generation sequencing platforms creates chokepoint exposure for European laboratories dependent on Illumina's proprietary consumables ecosystem. Distribution runs through authorized distributor networks in France and direct-hospital contracts in Germany, with regional reference laboratories in the Netherlands and Belgium consolidating procurement through group purchasing organizations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat environment where IVDR certification entrenchment creates switching costs that lock hospital laboratories into validated workflow ecosystems and freeze out unnotified competitors.
For Market Incumbents: Entrench certification portfolio breadth by accelerating IVDR technical documentation submission for Lynch Syndrome and moderate-penetrance gene panels before notified body queues extend further. Deepen backward integration into variant interpretation software development to capture recurring SaaS revenue from mid-sized laboratories adopting cloud-based ACMG classification platforms. The primary threat stems from emerging liquid biopsy germline confirmation technologies that could displace tissue-based cascade screening workflows in pediatric and needle-phobic patient segments. For New Entrants and Emerging Players: Build out specialized service capabilities in Spain and Italy's reimbursement gap markets, where regional health services in Catalonia and Lombardy are piloting predictive testing programs without established incumbent relationships. The most penetrable segment lies in genetic counseling virtualization, where England's NHS electronic referral pathways and Nordic centralized consent tracking infrastructure create demand for scalable pre-test consultation platforms. A direct-to-hospital SaaS go-to-market angle bypasses the IVDR certification barrier by positioning as workflow enhancement rather than diagnostic device. For Investors and Strategic Acquirers: The market sits at a regulatory consolidation phase that favors IVDR-certified workflow providers with established quality management systems and notified body relationships. Long-term viability across the projection horizon hinges on pharmacogenomic companion diagnostic bundling as EMA guidance on PARP inhibitor labeling tightens BRCA testing integration into oncology prescribing workflows. Acquisition targets should display rare disease testing diversification to offset hereditary cancer panel commoditization. The critical signal to watch is G-BA reimbursement expansion into moderate-penetrance genes beyond BRCA1/2 and Lynch Syndrome, which would inflect addressable market size in Germany's statutory health insurance system.| Strategic Initiative | Industry Significance |
|---|---|
| IVDR Certification Acceleration | Notified body approval unlocks tender participation in France's hospital purchasing consortia and Germany's G-BA reimbursement pathways. |
| Cloud-Based Variant Interpretation Platform | SaaS delivery of ACMG classification eliminates capital expenditure barriers for mid-sized Belgian and Dutch diagnostic laboratories. |
| Genetic Counselor Workforce Expansion | Pre-test consent mandates across EU jurisdictions create scalable service revenue attached to mandatory testing workflows. |
| Liquid Biopsy Germline Integration | Cell-free DNA convergence with tissue-based panels opens pediatric and needle-phobic patient segments previously excluded from cascade screening. |
| Pharmacogenomic Companion Diagnostic Bundling | EMA guidance on PARP inhibitor labeling creates regulatory tailwind for BRCA testing integration into oncology prescribing workflows. |
Research Methodology
Cross-validation between primary interviews with molecular pathologists, genetic counselors, hospital procurement managers, and regulatory affairs specialists and secondary analysis of EMA pharmacogenomic guidance documents, IVDR technical documentation requirements, and national health technology assessment outcomes anchors the qualitative findings. Bottom-up triangulation across test volume data from German statutory health insurance claims, English NHS genomic laboratory hub throughput reports, and French HAS reimbursement eligibility criteria converges with top-down market sizing derived from sequencing platform installed base estimates and reagent consumables pricing indices.
Calibration against historical IVDD-to-IVDR transition timelines in comparable diagnostic categories informs the projection framework across the analysis window. Segmentation dimensions modeled include test type (BRCA1, BRCA2, Lynch Syndrome, Familial Adenomatous Polyposis), end user (hospitals, diagnostic laboratories, cancer centers, research institutions), technology (next-generation sequencing, Sanger sequencing, PCR, microarray analysis), and service type (testing, genetic counseling, interpretation, data management). CAGRs were derived from weighted average growth assumptions applied to each segment with cross-reference to statutory reimbursement expansion trajectories in Germany and pilot program scaling patterns in England's NHS trusts.
Practitioners should monitor IVDR notified body capacity expansion and G-BA reimbursement criteria broadening for early signals of competitive access relaxation or demand acceleration. Forecasts reflect assumptions regarding regulatory transition timelines, national reimbursement harmonization, and sequencing cost compression curves that could shift materially based on EMA guidance updates or health technology assessment reversals. Quarterly review of German statutory insurance claims data, English NHS genomic medicine service commissioning decisions, and French HAS predictive testing eligibility criteria is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Genomics
Dna Polymerase Market
Genomics
Reproductive Genetics Market
Genomics
SNP Genotyping Market
Genomics
North America Whole Exome Sequencing Market
Genomics
Alagille Syndrome Market
Genomics
UAE Genetic Testing Market
Genomics
Human Genetics Market
Genomics
Global Artificial Intelligence in Genomics Market
Genomics
Global Single Nucleotide Polymorphism (SNP) Genotyping Market
Genomics
AI in Genomics Market
Genomics
DNA Sequencing Market
Genomics
Agrigenomics Market
Genomics
Transcriptomics Technologies Market
Genomics
Next Generation Molecular Assay Market
Genomics
DNA Microarray Market
Genomics
Predisposition Biomarkers Market