
 China Emulsifiers Market | 2026-2036
China Emulsifiers Market Size, Share, and Industry Trends Forecast 2026-2036
China Emulsifiers Market Insights
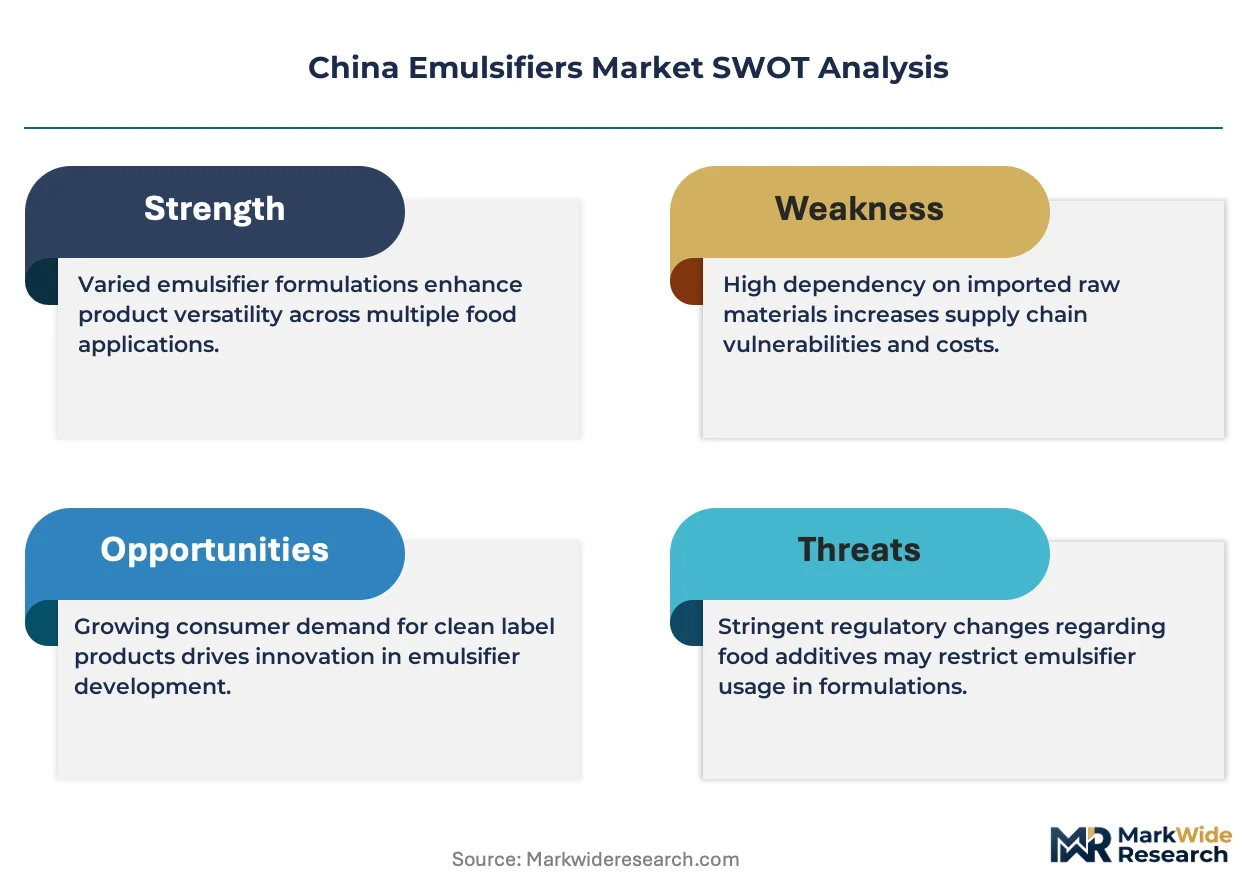
Direct supply contracts between emulsifier producers and large food manufacturers is narrowing the role of traditional chemical distributors in coastal provinces. BASF SE leverages its integrated Ludwigshafen-Shanghai technical network to sustain premium positioning in specialty emulsifier grades. Cargill Incorporated anchors its China footprint through backward integration into vegetable oil feedstocks, while Henan Eastar Chem. & Tech. Co., Ltd. competes on cost-optimized powder emulsifier output for mid-tier bakery clients.
Emulsifiers are surface-active agents with hydrophilic-lipophilic balance values typically between 3 and 16, functioning to stabilize immiscible phases in multicomponent systems. Industrial production proceeds through esterification of fatty acids with polyols or ethoxylation of natural lipids, yielding compounds that reduce interfacial tension in food matrices, cosmetic creams, and coating dispersions. Non-ionic emulsifiers dominate volume flows due to their pH stability and broad compatibility, while acrylic emulsifiers command margin premiums in high-performance paints and coatings applications. The food and beverages application segment absorbs the largest share of domestic output, though pharmaceutical-grade emulsifiers carry the highest purity-adjusted returns.
SAMR administers the national food additive positive list under GB 2760, restricting which emulsifier chemistries may enter food-contact applications, while MEE enforces wastewater and VOC discharge limits on emulsifier synthesis facilities under evolving environmental compliance schedules. NMPA oversight of pharmaceutical excipient registration creates a dual-track regulatory burden for suppliers serving both food and drug end users. Stakeholders must monitor the pace of GB standard revisions and MEE enforcement intensity to calibrate capital allocation between commodity and specialty emulsifier capacity.
Market Dynamics
MEE environmental enforcement is compressing smaller emulsifier synthesis facilities while concentrating production among integrated chemical parks in Jiangsu and Zhejiang provinces.
Growth Catalysts
- Clean-label bakery demand:Food processors in Shanghai are reformulating bread and pastry lines to eliminate synthetic additives, pulling through lecithin and mono-diglyceride emulsifiers that meet GB 2760 positive-list requirements.
- GB 2760 standard expansion:SAMR's periodic revision of permitted food additive categories creates new formulation latitude for domestic emulsifier suppliers serving dairy and beverage clients.
- Yangtze River Delta clustering:Proximity between Jiangsu chemical parks and Shanghai food manufacturing hubs shortens logistics cycles and enables just-in-time emulsifier delivery for perishable ingredient schedules.
Market Restraints
- Palm oil feedstock volatility:Vegetable oil price swings directly compress margins for domestic emulsifier producers lacking backward integration into oilseed crushing.
- Shandong supply concentration:A disproportionate share of non-ionic surfactant intermediates originates from this province, creating geographic single-point vulnerability.
- Pharmaceutical-grade purity thresholds:NMPA excipient registration demands impurity profiles below 10 ppm for injectable applications, excluding most commodity producers from high-margin drug channels.
Strategic Opportunities
- Guangdong-Hong Kong-Macao Greater Bay Area:Underdeveloped local emulsifier production relative to food processing density creates import substitution potential for Guangdong-based chemical investors.
- Acrylic emulsifier coatings demand:Waterborne architectural paint specifications in Tier-1 cities are displacing solvent systems, opening formulation partnerships with local coatings manufacturers.
- Dual carbon policy alignment:MEE carbon intensity benchmarks favor producers with biomass-derived fatty acid feedstocks and membrane filtration wastewater recovery.
Industry Challenges
- Process analytical chemistry talent:Shortage of specialists capable of validating HPLC and GC-MS methods for emulsifier purity testing extends NMPA registration timelines.
- Legacy esterification reactor retrofit:Continuous flow chemistry upgrades require eight-figure RMB capital commitments that mid-tier producers struggle to finance.
- Cross-border IP licensing:Foreign specialty emulsifier patents covering ethoxylated sorbitan esters create formulation barriers for domestic exporters targeting ASEAN markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Emulsifiers Market |
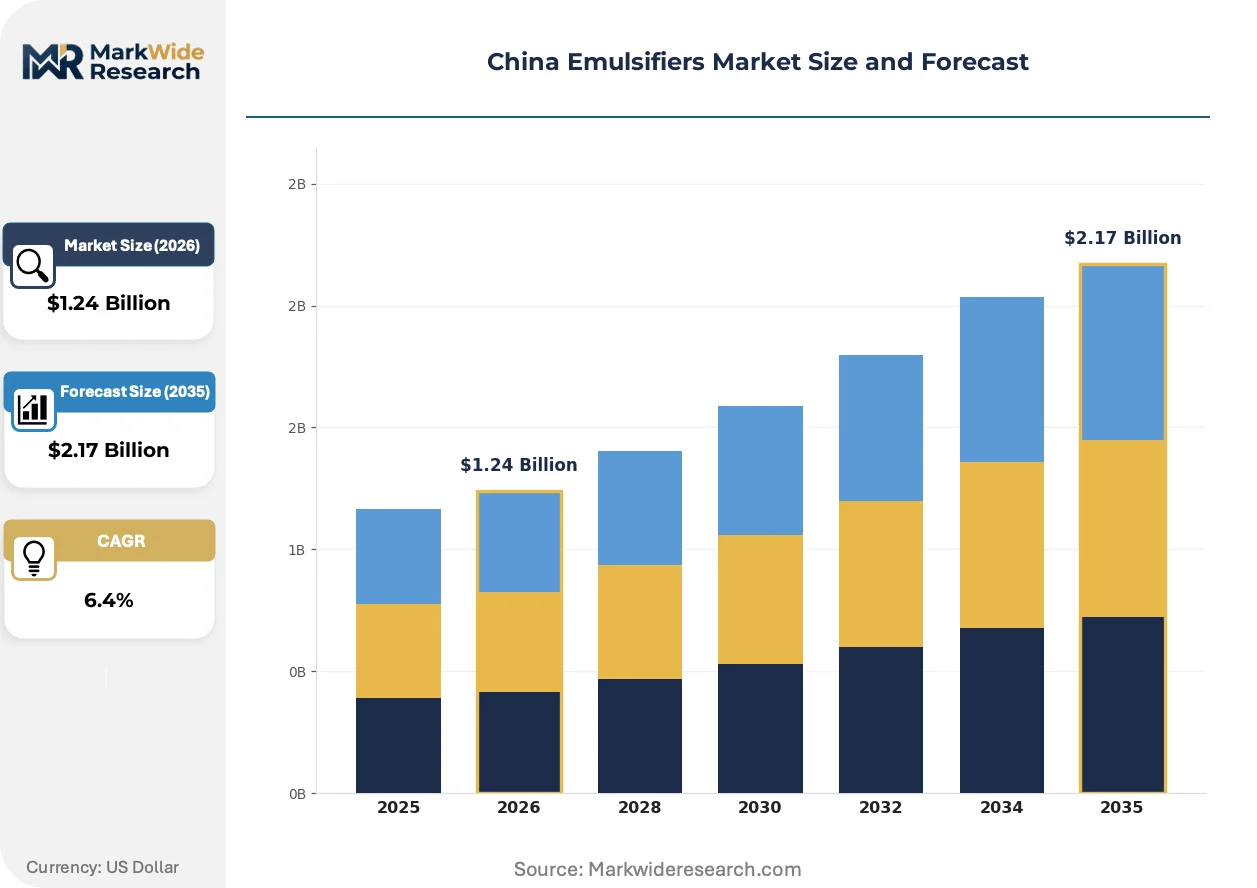
| Market Size in 2026 | $1.24 Billion |
| Market Size in 2035 | $2.17 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
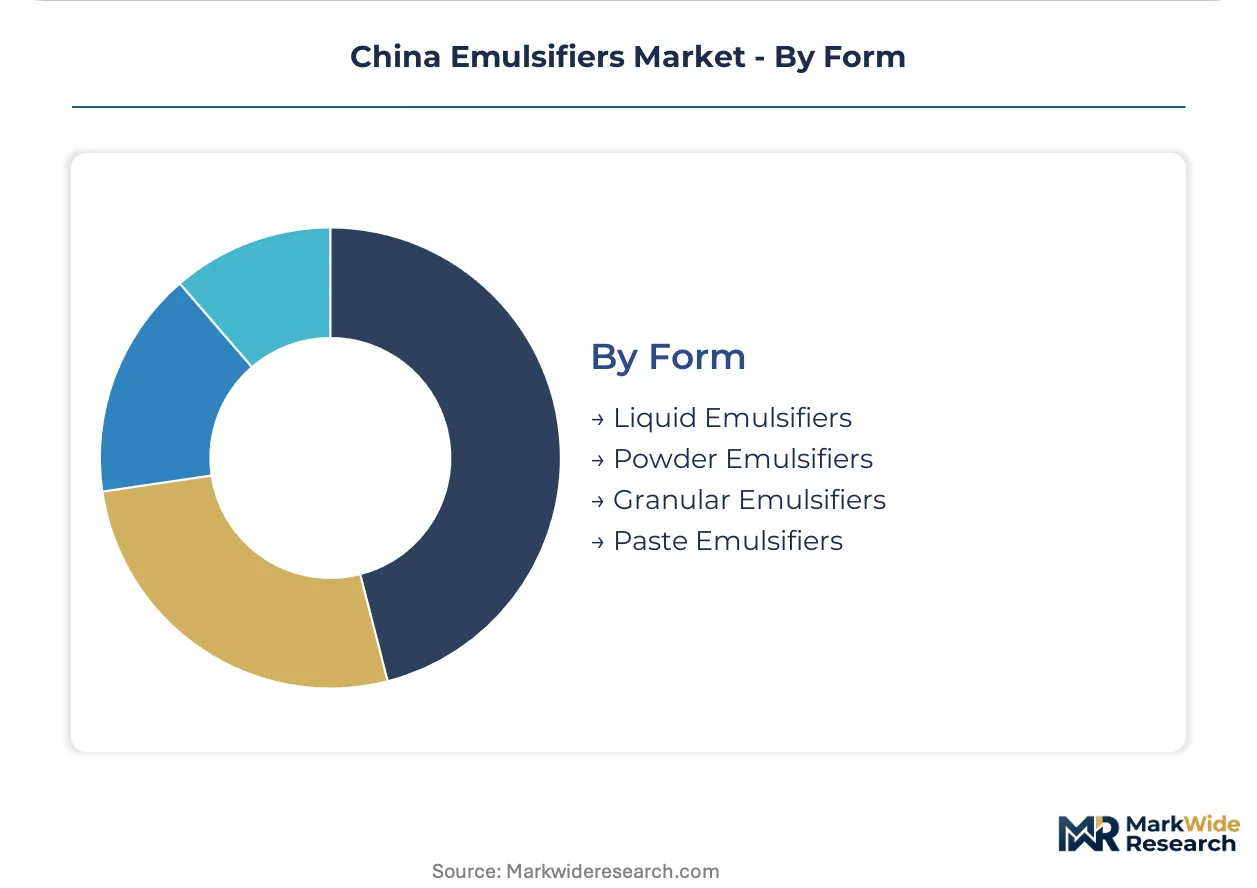
| Segmentation | Product Type: Acrylic Emulsifiers, Non-ionic Emulsifiers, Anionic Emulsifiers, Cationic Emulsifiers Application: Food & Beverages, Personal Care, Pharmaceuticals, Paints & Coatings End User: Food Manufacturers, Cosmetic Companies, Pharmaceutical Firms, Paint Producers Form: Liquid Emulsifiers, Powder Emulsifiers, Granular Emulsifiers, Paste Emulsifiers |
| Companies Covered | Cargill Incorporated, Ingredion Incorporated, DuPont de Nemours, Inc, Archer Daniels Midland Company, BASF SE, Henan Eastar Chem. & Tech. Co., Ltd., Palsgaard A/S, Kerry Group plc, Hugestone Enterprise Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Emulsifiers Market Trends and Innovations
Digital process control and biosynthetic feedstock engineering are reconfiguring how emulsifier manufacturers balance cost, compliance, and clean-label positioning in China.
Automated distributed control systems are digitizing batch consistency across Jiangsu chemical parks. BASF SE and Cargill Incorporated have deployed real-time viscosity and HLB monitoring in their Shanghai technical centers, compressing formulation development cycles from months to weeks for bakery and dairy clients. This digitization is narrowing the performance gap between commodity and specialty emulsifier grades.
MEE's 2024 wastewater discharge amendments have tightened COD and VOC limits on esterification facilities. Chemical parks in Ningbo and Taizhou are mandating closed-loop solvent recovery systems, raising compliance capital requirements. Pharmaceutical-grade producers with existing membrane bioreactor infrastructure are absorbing the burden more readily than commodity powder emulsifier plants.
Direct technical service contracts between emulsifier producers and food manufacturers are displacing traditional distributor networks in coastal provinces. Large bakery chains in Shanghai and Suzhou now source through annual formulation partnership agreements rather than spot chemical trading. This channel compression is most visible in the Yangtze River Delta, where distributor margins have compressed by half over three years.
China Emulsifiers Market Segmentation
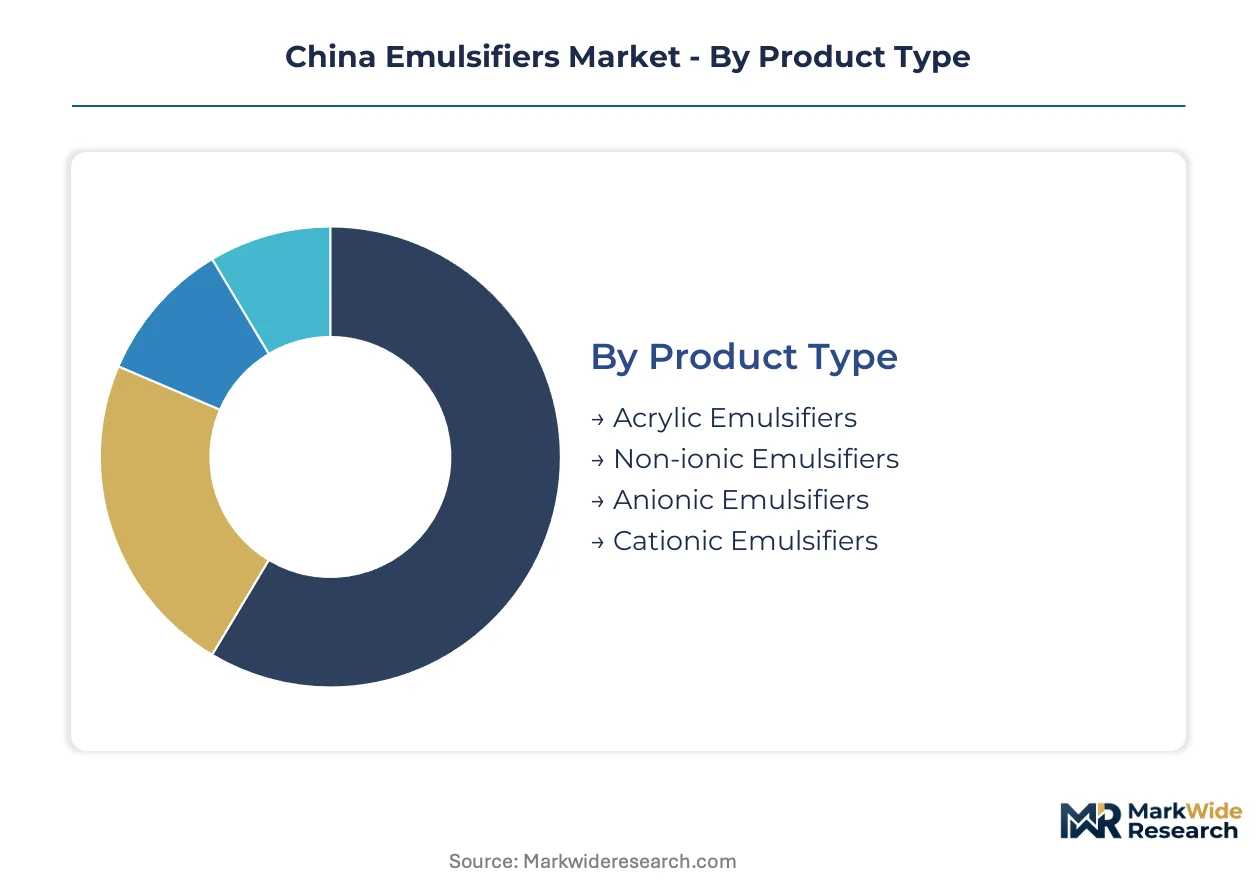
Emulsifier procurement in China fractures across product chemistry, application purity requirements, and physical handling constraints. SAMR's GB 2760 positive list and MEE discharge standards force suppliers to align segment portfolios with divergent compliance burdens and margin structures.
Product Type:
Cost tier differentiation separates commodity volume plays from specialty margin capture in China's emulsifier synthesis base.
- Non-ionic Emulsifiers:Polyoxyethylene sorbitan esters and fatty acid ethoxylates dominate tonnage flows through pH stability and broad formulation compatibility. Jiangsu chemical parks ship bulk volumes to Shanghai dairy processors seeking clean-label stability in UHT milk and whipped toppings.
- Acrylic Emulsifiers:Styrene-acrylic and pure acrylic copolymers command premium positioning in waterborne architectural coatings for Tier-1 city green building codes. Ningbo production clusters supply local paint manufacturers displacing solvent-based systems under MEE VOC restrictions.
- Anionic Emulsifiers:Alkyl sulfates and sulfonates anchor detergent and industrial cleaning applications.
- Cationic Emulsifiers:Quaternary ammonium compounds serve conditioning and antimicrobial formulations in personal care.
Non-ionic emulsifiers hold installed capacity. Acrylic emulsifiers are rotating up the share rankings.
Application:
Volume concentration in food processing contrasts with purity-adjusted returns in regulated pharmaceutical channels.
- Food & Beverages:Mono- and diglycerides plus lecithin variants stabilize bakery creams, chocolate, and margarine matrices. Yangtze River Delta food manufacturers drive procurement through reformulation campaigns eliminating synthetic additives under clean-label positioning.
- Pharmaceuticals:Injectable-grade polysorbates and sorbitan esters demand impurity profiles below 10 ppm per NMPA excipient registration. Zhejiang specialty producers with membrane bioreactor infrastructure capture margin premiums unavailable to commodity suppliers.
- Personal Care:Cosmetic emulsifiers balance skin feel and stability in creams and lotions.
- Paints & Coatings:Waterborne system migration under MEE enforcement expands acrylic emulsifier formulation partnerships.
Food & Beverages holds installed capacity. Pharmaceuticals is rotating up the share rankings.
End User:
Customer type determines procurement modality, with direct technical contracts displacing distributor channels among large-scale buyers.
- Food Manufacturers:Shanghai and Suzhou bakery chains source through annual formulation partnerships specifying HLB values and clean-label certification. BASF SE and Cargill Incorporated anchor supply through integrated technical service networks.
- Paint Producers:Local coatings manufacturers in Ningbo and Taizhou specify acrylic emulsifiers for architectural waterborne systems. MEE carbon intensity benchmarks favor suppliers with biomass-derived feedstocks and closed-loop solvent recovery.
- Cosmetic Companies:Personal care formulators demand sensory-optimized emulsifier grades.
- Pharmaceutical Firms:Drug manufacturers impose NMPA-validated purity testing extending supplier qualification timelines.
Food Manufacturers holds installed capacity. Paint Producers is rotating up the share rankings.
Form:
Physical state selection hinges on handling infrastructure, dissolution kinetics, and perishable ingredient scheduling in downstream processing.
- Liquid Emulsifiers:Pumpable concentrates enable automated dosing in continuous bakery and dairy processing lines. Taizhou chemical parks supply bulk tanker deliveries to Shanghai manufacturing hubs under just-in-time logistics contracts.
- Powder Emulsifiers:Spray-dried mono-diglycerides store stably and disperse rapidly in dry mix applications. Henan Eastar Chem. & Tech. Co., Ltd. competes on cost-optimized output for mid-tier bakery clients lacking liquid handling systems.
- Granular Emulsifiers:Free-flowing particles reduce dusting in bulk handling operations.
- Paste Emulsifiers:Semi-solid consistency suits small-batch cosmetic compounding.
Liquid emulsifiers hold installed capacity. Powder emulsifiers are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MEE carbon intensity benchmarks and dual carbon policy implementation are redistributing emulsifier production capacity toward provinces with integrated chemical park infrastructure and biomass feedstock access.
Jiangsu Province
Taizhou and Ningbo chemical parks host the densest concentration of non-ionic emulsifier synthesis facilities serving Shanghai food manufacturers. MEE wastewater discharge amendments mandate closed-loop solvent recovery systems, raising compliance capital requirements for esterification plants. Yangtze River Delta logistics networks enable just-in-time liquid emulsifier delivery to perishable ingredient schedules.
Shanghai
Bakery chains and dairy processors in Pudong and Songjiang districts drive clean-label reformulation demand for lecithin and mono-diglyceride emulsifiers. SAMR's GB 2760 positive-list enforcement restricts synthetic additive categories, pulling through permitted natural-origin stabilizers. BASF SE and Cargill Incorporated anchor supply through technical service centers in the Waigaoqiao free trade zone.
Zhejiang Province
Pharmaceutical-grade polysorbate producers in Hangzhou and Shaoxing capture margin premiums through NMPA excipient registration. Membrane bioreactor infrastructure investments position specialty manufacturers for injectable-grade purity thresholds below 10 ppm impurity profiles. Ningbo coatings manufacturers source acrylic emulsifiers for waterborne architectural paint systems displacing solvent-based alternatives.
Henan Province
Henan Eastar Chem. & Tech. Co., Ltd. anchors cost-optimized powder emulsifier output for mid-tier bakery clients lacking liquid handling infrastructure. Central China location offers freight cost advantages to inland food processing clusters. Provincial industrial policy supports chemical sector capacity expansion under national food security objectives.
Guangdong Province
Pearl River Delta food processing density exceeds local emulsifier production capacity, creating import substitution opportunities for Guangdong-based chemical investors. Shenzhen and Guangzhou beverage manufacturers source emulsifiers through distributor networks rather than direct technical contracts. Greater Bay Area integration initiatives accelerate cross-border formulation partnerships with Hong Kong cosmetic laboratories.
China Emulsifiers Market Competitive Landscape
On the supply side, the industry is consolidating around integrated chemical parks with MEE-compliant wastewater infrastructure while fragmenting among specialty-grade producers serving pharmaceutical and clean-label food channels. Three strategic archetypes dominate: multinational technical service networks with backward vegetable oil integration, domestic cost-optimized powder specialists, and regional acrylic emulsifier suppliers for coatings applications. Competitive moves center on direct formulation partnerships with large food manufacturers and membrane bioreactor investments for pharmaceutical-grade purity compliance.
Within the multinational technical service tier, BASF SE and Cargill Incorporated exemplify integrated supply architectures spanning Ludwigshafen-Shanghai technical coordination and captive oilseed crushing respectively. Henan Eastar Chem. & Tech. Co., Ltd. occupies a position among domestic cost-optimized producers serving mid-tier bakery segments through powder emulsifier formats. These three anchors illustrate the market's tripartite structure: premium specialty grades with formulation partnership depth, commodity volumes with geographic cost positioning, and regional acrylic specialists for industrial coatings migration.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Ingredion Incorporated |
| DuPont de Nemours, Inc |
| Archer Daniels Midland Company |
| BASF SE |
| Henan Eastar Chem. & Tech. Co., Ltd. |
| Palsgaard A/S |
| Kerry Group plc |
| Hugestone Enterprise Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Jiangsu chemical park capacity expansions in Taizhou and Ningbo are compressing spot-market premiums for commodity non-ionic emulsifiers while pharmaceutical-grade producers in Zhejiang defend margin structures through NMPA-certified purity premiums. This geographic supply asymmetry concentrates pricing power among membrane bioreactor-equipped facilities serving injectable-grade channels.
Pricing Analysis
Certification level creates the primary spread between commodity and specialty tiers, with NMPA excipient registration separating pharmaceutical-grade premiums from powder emulsifier spot pricing. Three-tier pricing structure across pharmaceutical, food-grade, and industrial tiers reflects purity-adjusted returns, with injectable-grade polysorbates commanding substantial premiums over bakery mono-diglycerides. Cost compression in commodity powder segments is intensifying because palm oil feedstock volatility transmits directly to non-integrated producers. Mid-tier bakery clients exhibit highest price sensitivity, while pharmaceutical firms prioritize supply security over unit economics.
Supply Chain Analysis
Export-control scrutiny on advanced process analytical equipment limits domestic pharmaceutical-grade producers' access to validated HPLC and GC-MS systems, constraining NMPA registration velocity. Supply concentrates in China, Malaysia, and Indonesia for palm oil-derived fatty acid feedstocks, with Jiangsu and Zhejiang chemical parks hosting downstream esterification capacity. Raw material flows draw from vegetable oil crushing, ethylene oxide supply, and polyol intermediates. Single-source vulnerability concentrates in Shandong province for non-ionic surfactant precursors. Distribution runs through direct technical service contracts with large food manufacturers, displacing traditional chemical distributors in coastal provinces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical service contracts and formulation partnership agreements are expanding faster than commodity spot sales, creating recurring-revenue streams that outpace hardware-like product transactions. This service-attach dynamic rewards suppliers investing in application laboratories and just-in-time logistics infrastructure.
For Market Incumbents: Build regulatory compliance moats through NMPA excipient registration and MEE-certified wastewater infrastructure. BASF SE and Cargill Incorporated anchor positioning through Ludwighafen-Shanghai technical coordination and captive oilseed crushing respectively. Defend against commodity powder specialists by deepening formulation partnership density with Yangtze River Delta bakery chains. Prioritize membrane bioreactor investments to absorb tightening COD discharge limits. For New Entrants and Emerging Players: Pursue import substitution in Guangdong Province, where Pearl River Delta food processing density exceeds local emulsifier production capacity. Acrylic emulsifier supply for waterborne architectural coatings in Ningbo and Taizhou presents the most penetrable segment under MEE VOC restrictions. Establish direct technical service capabilities rather than distributor-dependent channel strategies to capture formulation partnership economics. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among pharmaceutical-grade producers with NMPA-validated purity testing and annual supply agreements with injectable drug manufacturers. Long-term viability across the analysis window favors specialty-grade assets with membrane bioreactor infrastructure over commodity powder plants exposed to palm oil margin compression. Target acquisition archetypes include Zhejiang-based polysorbate specialists and acrylic emulsifier suppliers serving Tier-1 city coatings migration. Watch MEE enforcement intensity on Jiangsu chemical parks as the inflection signal for capacity consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Vegetable Oil Feedstocks | Cargill Incorporated anchors margin stability through captive oilseed crushing operations. |
| Membrane Bioreactor Infrastructure Investment | Zhejiang specialty producers absorb MEE wastewater amendments more readily than commodity plants. |
| Direct Technical Service Contract Expansion | BASF SE compresses distributor margins through annual formulation partnerships with Shanghai bakery chains. |
| Guangdong Production Capacity Buildout | Pearl River Delta import substitution opportunity exceeds local emulsifier supply availability. |
| Acrylic Emulsifier Formulation Partnership | Ningbo coatings manufacturers displace solvent systems under MEE VOC restrictions. |
Research Methodology
Desk research of customs trade databases, MEE discharge compliance filings, and SAMR GB standard amendments preceded structured interviews with Jiangsu chemical park plant managers, Shanghai bakery chain procurement directors, Zhejiang pharmaceutical excipient quality leads, and Ningbo coatings manufacturer technical directors. Bottom-up emulsifier volume estimates triangulated against top-down food processing capacity data across the Yangtze River Delta and Pearl River Delta clusters.
Assumptions held fixed include MEE carbon intensity benchmark trajectories and SAMR GB 2760 positive-list composition, while palm oil price volatility and NMPA registration timelines were modeled as stochastic variables. Segmentation dimensions spanned product chemistry tier, application purity requirement, physical handling format, and regional production hub concentration. CAGRs derived from elasticity-adjusted demand projections across food, pharmaceutical, and coatings end-use channels, with feedstock cost pass-through coefficients calibrated to vegetable oil futures correlation patterns.
Sensitivities concentrate around MEE enforcement intensity on Jiangsu esterification facilities and NMPA excipient registration timeline acceleration. Forecasts reflect documented assumptions on clean-label reformulation velocity and waterborne coatings migration in Tier-1 cities. Material shifts in palm oil supply chain configuration or GB standard revision scope would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Alcohol Additives Market
Food Additives and Ingredients
Beta Agonist Feed Additive Market
Food Additives and Ingredients
Microencapsulated Phytosterols Market
Food Additives and Ingredients
Fat Replacers Salt Reducers and Replacers Market
Food Additives and Ingredients
Lactoperoxidase Market
Food Additives and Ingredients
Chocolate Wax Market
Food Additives and Ingredients
France Anti Caking Market
Food Additives and Ingredients
Australia Food Emulsifiers Market
Food Additives and Ingredients
Acetylated Distarch Phosphate Market
Food Additives and Ingredients
Japan Anti-Caking Market
Food Additives and Ingredients
Food Grade Glue Market
Food Additives and Ingredients
Locust Bean Gum Market
Food Additives and Ingredients
Food Stabilizer Systems Market
Food Additives and Ingredients
Granulated Tapioca Market
Food Additives and Ingredients
Russia Food Emulsifiers Market
Food Additives and Ingredients
India Food Color Industry Market