
 China Gaming Headsets Market | 2026-2036
China Gaming Headsets Market Size, Share, and Industry Trends Forecast 2026-2036
China Gaming Headsets Market Insights
Aftermarket service revenue from driver replacement and firmware upgrades is reconfiguring margin capture away from pure hardware sales. Razer Inc leverages its Shenzhen R&D center to sustain rapid prototyping cycles for wireless latency optimization. Edifier Technology Co., Ltd. anchors domestic supply chain relationships that control component costs across the Pearl River Delta. Logitech International SA competes through global quality certifications that position its products in premium retail channels.
China gaming headsets integrate electret condenser or MEMS microphones with 20 Hz–20 kHz frequency response drivers, active noise cancellation DSPs, and low-latency 2.4 GHz or Bluetooth 5.3 wireless modules to deliver positional audio for competitive multiplayer environments. Wireless technology leads volume growth as latency thresholds drop below 20 milliseconds, while RGB lighting technology differentiates at retail but carries thinner margins due to commoditized LED controller supply. Professional gamers and eSports teams concentrate demand in the premium and luxury price tiers, where surround sound implementations command sustained pricing power.
MIIT radio type approval and GB standard electromagnetic compatibility testing govern wireless headset market access, while SAMR consumer protection enforcement shapes warranty and return policy structures. NMPA does not directly regulate gaming peripherals, but its medical device acoustic standards indirectly influence maximum decibel limits. Stakeholders must monitor MIIT's evolving spectrum allocation for unlicensed wireless devices, as channel congestion in the 2.4 GHz band could force hardware redesigns toward 5 GHz or proprietary protocols.
Market Dynamics
MIIT spectrum allocation for unlicensed 2.4 GHz devices is forcing hardware redesign cycles as channel congestion intensifies, compressing product lifecycles and redistributing R&D budgets toward proprietary wireless protocols.
Growth Catalysts
- Professional eSports Standards:Competitive leagues in China mandate sub-20 millisecond latency thresholds, compelling hardware refresh cycles among semi-professional players seeking tournament eligibility.
- GB Standard Electromagnetic Compatibility:Mandatory certification streamlines domestic distribution by eliminating regional testing duplication, accelerating time-to-market for Shenzhen-Dongguan OEM clusters.
- MEMS Microphone Adoption:Solid-state acoustic components replace electret condensers, enabling thinner driver housings and expanding industrial design freedom for wearable comfort optimization.
Market Restraints
- 2.4 GHz Spectrum Saturation:Unlicensed band congestion in dense urban corridors degrades connection stability, forcing costly dual-radio implementations or proprietary protocol development.
- Pearl River Delta Concentration:Component sourcing and final assembly cluster within 150 kilometers of Shenzhen, creating geographic vulnerability to logistics disruptions or labor mobility constraints.
- RGB LED Controller Commoditization:Standardized lighting ICs eliminate differentiation margins, compressing retail pricing power despite continued consumer preference for visual customization.
Strategic Opportunities
- Central China Urbanization:Tier-2 cities Chengdu and Wuhan exhibit underpenetrated gaming peripheral retail density relative to per-capita disposable income growth rates.
- Dual Carbon Policy Alignment:MIIT energy-efficiency mandates for wireless devices create first-mover advantage for manufacturers optimizing active noise cancellation DSP power consumption.
- Cloud Gaming Audio Pipelines:Latency-tolerant streaming architectures reduce hardware decoding requirements, opening peripheral compatibility with lower-specification client devices.
Industry Challenges
- RF Engineering Talent Scarcity:Shenzhen R&D centers compete intensely for antenna design specialists capable of optimizing 2.4 GHz/5 GHz coexistence in compact form factors.
- SAMR Warranty Enforcement:Expanded consumer protection mandates extend replacement obligation periods, straining after-sales service infrastructure and reverse logistics capabilities.
- Firmware Signing Complexity:MIIT radio type approval requires locked bootloader architectures, complicating over-the-air update deployment and security patch velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Gaming Headsets Market |
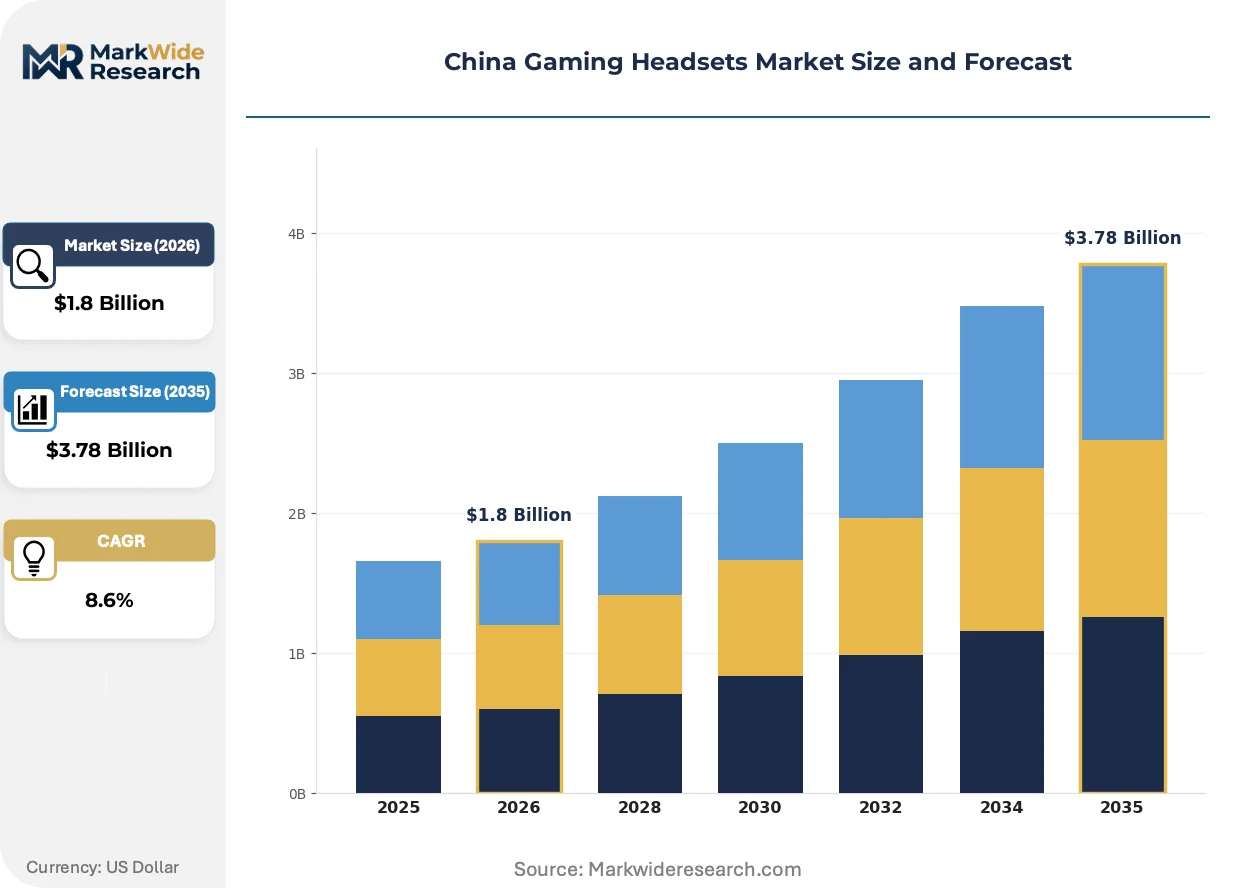
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.78 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wired, Wireless, Over-ear, On-ear Technology: Noise Cancelling, Surround Sound, Bluetooth, RGB Lighting End User: Casual Gamers, Professional Gamers, Streamers, eSports Teams Price Tier: Low-end, Mid-range, Premium, Luxury |
| Companies Covered | Logitech International SA, Razer Inc, HyperX (Kingston), Corsair Gaming, SteelSeries, Audio-Technica Ltd, Sony Interactive Entertainment, Creative Technology, Edifier Technology Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Gaming Headsets Market Trends and Innovations
Spatial audio rendering is compressing the boundary between hardware and software-defined acoustic experiences, redistributing value capture toward algorithmic licensing and away from driver component differentiation.
Beamforming microphone arrays is virtualizing directional voice capture through DSP-driven phase manipulation, eliminating mechanical boom arm requirements. Professional streamers in Guangdong province adopt these configurations fastest, prioritizing visual unobtrusiveness during camera-facing broadcasts. This virtualization is collapsing the premium tier's historical reliance on physical microphone positioning hardware.
MIIT's evolving unlicensed spectrum management guidelines are tightening electromagnetic emission ceilings for 2.4 GHz consumer devices. Manufacturers now pre-certify prototypes through Shenzhen-based testing laboratories to avoid redesign cycles. Gaming peripheral divisions absorb compliance costs that consumer audio divisions previously externalized.
Subscription-based firmware feature unlocking is displacing perpetual-license software bundles in premium channel distribution. Specialty retailers in Shanghai and Beijing pilot hardware-plus-service contracts where spatial audio algorithms update quarterly. This model concentrates recurring revenue with direct-to-consumer brands possessing captive app ecosystems.
China Gaming Headsets Market Segmentation
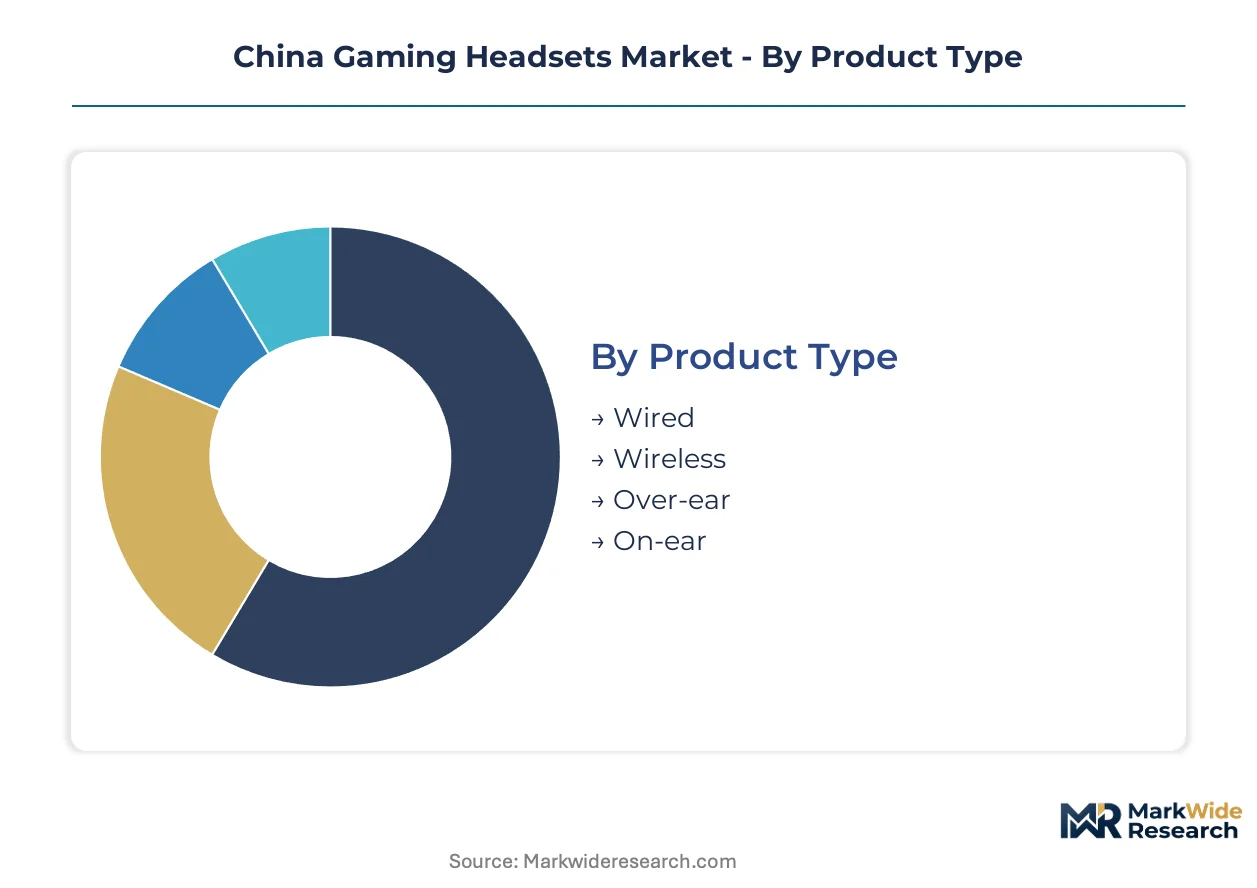
Segmentation in the China gaming headsets market reveals how technical specifications, user sophistication, and price sensitivity fragment demand across distinct purchasing logics. Manufacturers configure product portfolios around these divides to capture margin pools that vary dramatically by use case intensity and channel access.
Product Type:
Form factor and connectivity architecture shape the core hardware trade-offs between latency performance, mobility freedom, and acoustic isolation depth.
- Wireless:2.4 GHz and Bluetooth 5.3 modules deliver sub-20 millisecond latency thresholds demanded by MIIT-certified tournament equipment standards. Demand concentrates among semi-professional players in Guangdong province seeking competitive eligibility without cable constraints.
- Wired:USB-C and 3.5mm analog connections eliminate battery dependency and RF interference risks in dense urban signal environments. Shenzhen-Dongguan OEM clusters prioritize these configurations for cost-sensitive institutional procurement in internet café chains.
- Over-ear:Closed-back circumaural designs with 50mm+ drivers provide acoustic isolation for extended session comfort. These dominate premium channel distribution in Shanghai and Beijing specialty retailers.
- On-ear:Supra-aural compact housings reduce weight for portable use cases. Demand clusters among mobile-first casual gamers in Tier-2 cities with lower per-capita peripheral spending.
Wired configurations command the established base. The steepest expansion runs through wireless implementations as latency optimization closes the performance gap.
Technology:
Feature integration depth determines pricing power and differentiation sustainability against rapid component commoditization.
- Noise Cancelling:Active noise cancellation DSPs with feed-forward microphone arrays suppress environmental interference in shared living spaces. These configurations concentrate demand among streamers in Guangdong province requiring broadcast-quality isolation without dedicated studio infrastructure.
- Surround Sound:Virtual 7.1 channel rendering through proprietary DSP algorithms creates positional audio cues for competitive multiplayer environments. Professional eSports teams in Chengdu and Wuhan mandate these implementations for tournament training regimens.
- Bluetooth:Standardized wireless connectivity enables cross-device pairing with mobile and console ecosystems. MIIT radio type approval requirements extend certification timelines for these implementations relative to proprietary 2.4 GHz protocols.
- RGB Lighting:Addressable LED controller arrays provide visual customization through software-defined effects. Controller IC commoditization has compressed hardware margins despite persistent consumer preference for aesthetic differentiation.
Surround sound implementations anchor premium tier pricing. Active noise cancellation is climbing the fastest as apartment-dwelling gamers prioritize acoustic privacy.
End User:
User sophistication and income elasticity create distinct hardware refresh cadences and feature prioritization hierarchies.
- Professional Gamers:Tournament-eligible players require MIIT-certified sub-20 millisecond latency, replaceable microphone modules, and durability ratings for daily 8+ hour use. This segment concentrates in Guangdong province's organized competitive leagues.
- eSports Teams:Organized squads procure standardized equipment lots through sponsorship arrangements with peripheral manufacturers. Bulk purchasing agreements prioritize firmware uniformity and centralized IT manageability over individual customization.
- Streamers:Broadcast-facing content creators prioritize visual unobtrusiveness through beamforming microphone arrays that eliminate boom arms. Guangdong province hosts the densest concentration of these users.
- Casual Gamers:Price-sensitive intermittent users prioritize basic stereo output and plug-and-play compatibility. This segment dominates volume in Tier-2 and Tier-3 city retail channels.
Casual gamers represent the volume foundation. The professional tier is expanding most quickly as competitive league structures formalize hardware standardization requirements.
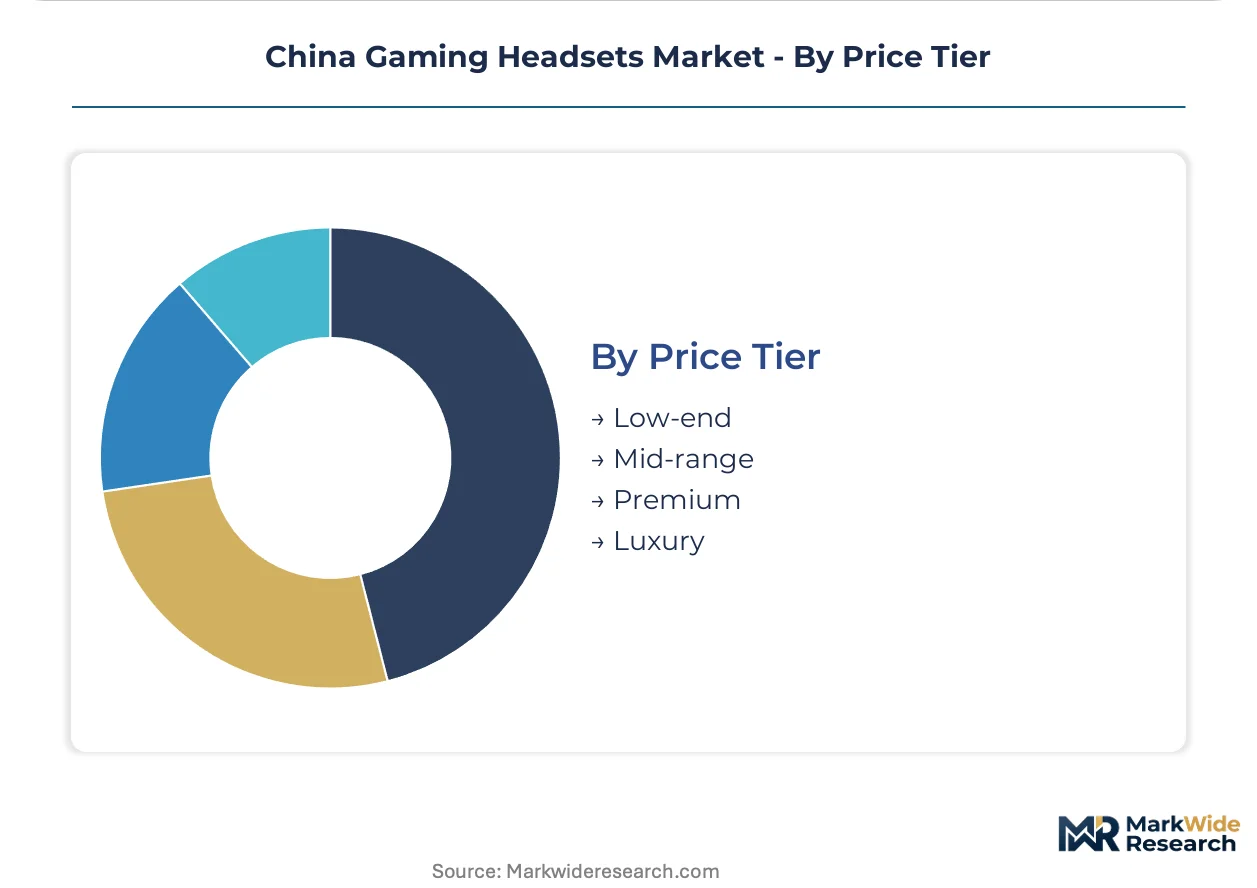
Price Tier:
Cost positioning aligns with certification depth, component grade, and channel margin structures across retail and direct-to-consumer distribution.
- Premium:Products in this tier incorporate MEMS microphones, multi-driver acoustic arrays, and extended warranty terms. These configurations dominate specialty retail in Shanghai and Beijing where informed purchasers prioritize specification transparency.
- Luxury:Ultra-premium implementations feature machined aluminum housings, replaceable ear pads, and exclusive algorithm licensing for spatial audio. Limited production runs target collector-oriented professional gamers with sponsorship income.
- Mid-range:Balanced specifications with selective premium feature inclusion capture upgrade-oriented casual gamers. Shenzhen-Dongguan OEM ecosystems optimize these SKUs for e-commerce volume efficiency.
- Low-end:Basic electret condenser implementations with plastic construction serve price-elastic first-time purchasers. Internet café bulk procurement and rural market penetration drive this tier.
Mid-range SKUs command the established base. The steepest expansion trajectory runs through premium configurations as disposable income growth in Tier-2 cities enables quality upgrades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across Chinese sub-regions. Tier-1 coastal cities absorb premium pricing with minimal volume sacrifice, while inland markets remain highly sensitive to cost positioning despite rapid income growth.
Pearl River Delta
Professional eSports leagues in Guangdong province drive hardware refresh cycles with sub-20 millisecond latency mandates. MIIT radio frequency certification requirements filter product roadmaps before national rollout. Shenzhen-Dongguan OEM-ODM ecosystems concentrate final assembly and component sourcing within 150 kilometers.
Yangtze River Delta
Shanghai specialty retailers command premium channel margins through specification-transparent purchasing behavior. SAMR consumer protection enforcement shapes extended warranty obligations across distribution networks. Hangzhou-Ningbo electronics corridors host firmware development centers for spatial audio algorithm licensing.
Beijing-Tianjin-Hebei
Central government procurement policies influence institutional buying patterns for internet café chains. GB standard electromagnetic compatibility testing accelerates domestic market access for certified products. Zhongguancun technology districts anchor wholesale distribution to northern provincial markets.
Sichuan-Chongqing
Tier-2 city disposable income growth outpaces gaming peripheral retail density in Chengdu and Wuhan. Dual carbon policy alignment creates procurement preference for energy-efficient active noise cancellation implementations. Chongqing manufacturing zones absorb labor-intensive assembly migration from coastal cost pressures.
Western China
Underpenetrated rural markets sustain low-end volume through price-elastic first-time purchasers. Logistics infrastructure gaps extend delivery timelines and elevate working capital requirements for distributors. Xi'an hub cities mediate cross-border e-commerce flows into Central Asian neighboring markets.
China Gaming Headsets Market Competitive Landscape
Global peripheral specialists and domestic supply chain anchors split the market into contrasting strategic postures. The vendor base concentrates around three archetypes: multinational certification-leveraged brands, Pearl River Delta integrated manufacturers, and audio heritage specialists diversifying into gaming applications. Competitive moves cluster on firmware subscription monetization and proprietary wireless protocol development to escape 2.4 GHz commoditization.
Within the multinational tier, Logitech International SA and Razer Inc occupy positions shaped by global quality certification portfolios and Shenzhen-based R&D proximity respectively. Edifier Technology Co., Ltd. anchors domestic supply chain control across the Pearl River Delta, exemplifying the integrated manufacturer archetype that compresses component costs through captive supplier relationships. These three representations illustrate how competitive positioning diverges between certification-mediated premium access and ecosystem-integrated cost leadership.
| Leading Market Players |
|---|
| Logitech International SA |
| Razer Inc |
| HyperX (Kingston) |
| Corsair Gaming |
| SteelSeries |
| Audio-Technica Ltd |
| Sony Interactive Entertainment |
| Creative Technology |
| Edifier Technology Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Shenzhen-Dongguan electronics corridor capacity dynamics compress component costs for domestic OEMs while amplifying pricing power for brands with captive firmware ecosystems. Aftermarket service revenue from driver replacement and firmware upgrades now captures margin pools that pure hardware sales cannot sustain.
Pricing Analysis
Aftermarket service tiers including extended warranty contracts and algorithm subscription unlocks now drive lifetime value capture beyond initial hardware transactions. Pricing stratifies across premium MIIT-certified tournament equipment, standard wireless implementations, and economy wired configurations for internet café bulk procurement. Cost compression in the RGB lighting tier intensifies because LED controller ICs have commoditized, while active noise cancellation DSP implementations retain pricing power through power-efficiency optimization. Casual gamers in Tier-3 cities exhibit highest price sensitivity, whereas professional eSports teams in Guangdong province absorb premium positioning with minimal volume elasticity.
Supply Chain Analysis
Foxconn and BYD Electronics hold dominant contract manufacturing capacity for wireless audio module assembly across the Pearl River Delta. Component sourcing draws from Taiwan for Bluetooth 5.3 SoCs, South Korea for MEMS microphone dies, and domestic China for driver magnet assemblies and injection-molded housings. Single-source vulnerability concentrates in 2.4 GHz RF front-end chips where Qualcomm and MediaTek dominate licensed protocol stacks. Distribution runs through Shenzhen Huaqiangbei wholesale markets for low-end volume, Shanghai specialty retail for premium tier validation, and direct-to-consumer brand storefronts for subscription-attach revenue.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now govern this market as firmware-defined audio experiences displace hardware-only differentiation. Interoperability between gaming peripherals and cloud gaming pipelines is collapsing traditional device-bound value capture.
For Market Incumbents: Build proprietary wireless protocol moats that escape 2.4 GHz spectrum congestion through Shenzhen R&D center investment in 5 GHz or ultra-wideband implementations. Defensive consolidation should prioritize backward integration into MEMS microphone die sourcing to neutralize Taiwan foundry pricing volatility. Channel control through direct-to-consumer app ecosystems locks in recurring algorithm revenue against emerging audio-heritage competitors. For New Entrants and Emerging Players: Establish a beachhead in Tier-2 city specialty retail where Chengdu and Wuhan disposable income growth outpaces gaming peripheral penetration. White-space targets include energy-efficient active noise cancellation implementations aligned with dual carbon procurement mandates, and beamforming microphone arrays for Guangdong streamers seeking visual unobtrusiveness. Go-to-market should leverage e-commerce livestreaming channels that bypass incumbent retail margin structures. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors firmware-subscription platforms with captive user bases over pure hardware OEMs. Long-term viability across the projection horizon hinges on algorithm licensing recurring revenue rather than transactional device sales. Acquisition target archetype: domestic brands with MIIT certification pipelines and Pearl River Delta supplier relationships. The signal to watch is MIIT spectrum reallocation announcements that would force hardware redesign cycles and consolidate R&D scale advantages.| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Wireless Protocol Development | Escapes 2.4 GHz congestion through Shenzhen R&D investment in alternative spectrum implementations. |
| Firmware Subscription Platform Launch | Captures recurring revenue from spatial audio algorithm updates via direct-to-consumer app ecosystems. |
| MEMS Microphone Supply Integration | Secures acoustic component cost control through upstream relationships with Taiwan foundry partners. |
| Tier-2 City Retail Expansion | Penetrates underexploited Chengdu and Wuhan markets where income growth exceeds peripheral density. |
| Dual Carbon Certification Alignment | Positions energy-efficient ANC implementations for preferred procurement under MIIT efficiency mandates. |
Research Methodology
Demand-side practitioners including professional eSports team equipment managers and streamer content creators were both consulted alongside supply-side operators at Shenzhen OEM facilities and Dongguan component suppliers. Primary interviews with MIIT certification consultants, specialty retail buyers in Shanghai and Beijing, and firmware engineering leads at wireless audio R&D centers combined with secondary validation from MIIT radio type approval filings, SAMR consumer protection enforcement records, and SEC 10-K disclosures from listed peripheral manufacturers. Bottom-up shipment estimates from Pearl River Delta assembly facilities triangulated against top-down disposable income elasticity models across Chinese city tiers.
Calibration anchored volume and value outputs to historical MIIT certification issuance patterns and eSports league hardware standardization timelines across the analysis window. Segmentation dimensions modeled include connectivity architecture, acoustic technology integration depth, end-user sophistication tier, price positioning, and regional retail channel structure. CAGRs derived from regression against per-capita gaming expenditure growth and tournament participation rates, with sensitivity testing for spectrum congestion scenarios and cloud gaming adoption curves.
Stress conditions across 2.4 GHz channel saturation, MEMS microphone foundry pricing, and SAMR warranty mandate expansion were modeled; outcomes outside those bands fall beyond the analytical envelope. Quarterly review of MIIT spectrum allocation bulletins and professional league equipment standardization updates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gaming
FPS Game Market
Gaming
Gaming Chair Market
Gaming
Japan Virtual Reality Gaming Market
Gaming
Global Gaming Market
Gaming
Global Online Board Games Market
Gaming
North America in-Game Advertising Market
Gaming
Australia Casino Tourism Market
Gaming
Traditional Casual Games Market
Gaming
Europe Serious Gaming Market
Gaming
Latin America Mobile Gaming Market
Gaming
Board Games Market
Gaming
Gaming Controller Market
Gaming
Galgames Market
Gaming
MMORPG Gaming Market
Gaming
Videogames Market
Gaming
Gaming Software Market