
 China Camping Equipment Market | 2026-2036
China Camping Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
China Camping Equipment Market Insights
Buyer concentration in China's camping equipment sector is recalibrating as outdoor enthusiasts fragment across specialized sub-communities while family segment buyers consolidate through organized camping clubs and social group purchasing. TANXIANZHE leverages its brand strength in the adventure tourist segment to sustain premium positioning across tier-one cities. Everich Outdoor anchors its competitive presence through manufacturing scale in Zhejiang Province, where it controls significant nylon and polyester supply channels.
Camping equipment encompasses portable shelters, sleep systems, cooking apparatus, and load-bearing gear engineered from technical fabrics such as ripstop nylon with silicone waterproof coatings and 7000-series aluminum alloy poles, designed to protect users from environmental exposure during temporary outdoor habitation. Tents and backpacks dominate volume due to their essential functional role across all end-user tiers, while camping stoves capture expanding margin pools as consumers prioritize multi-fuel compatibility and ultralight designs. Online retailers represent the fastest-growing distribution channel, displacing specialty stores among younger casual campers who research gear through short-video platforms before purchasing.
China's MIIT oversees manufacturing standards for aluminum and fiberglass structural components, while SAMR enforces product safety labeling under GB standards that govern flame resistance and weatherproofing claims for tent fabrics. The national dual carbon goals are forcing material suppliers to reformulate polyester production processes, creating compliance costs that smaller Zhejiang-based factories struggle to absorb. Stakeholders must monitor how evolving GB standard revisions for biodegradable fabric treatments will reshape sourcing requirements and supplier qualification timelines.
Market Dynamics
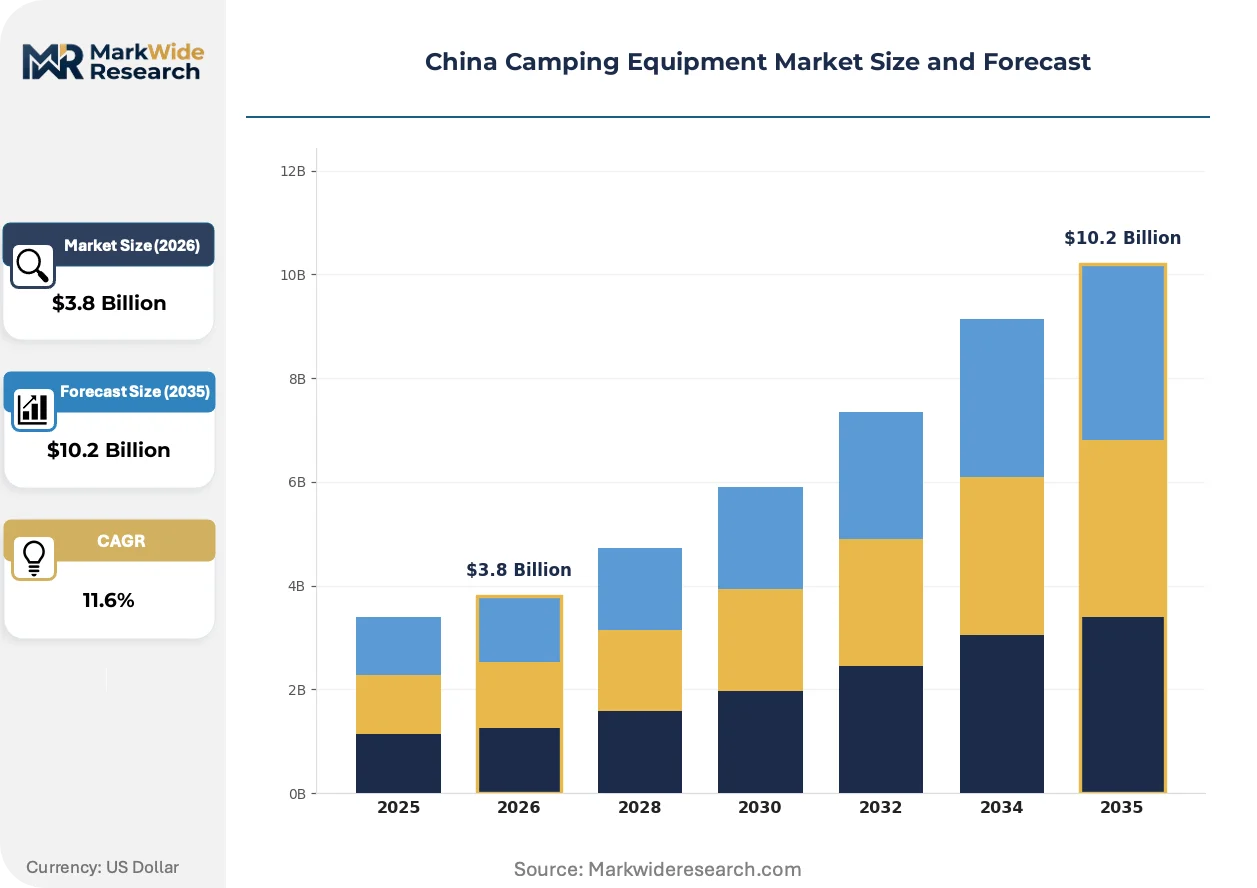
China's camping equipment sector is experiencing structural compression as MIIT-mandated aluminum and fiberglass standards force Zhejiang-based manufacturers to retool production lines, while young urban professionals in Shanghai and Hangzhou accelerate demand for sub-kilogram shelter systems.
Growth Catalysts
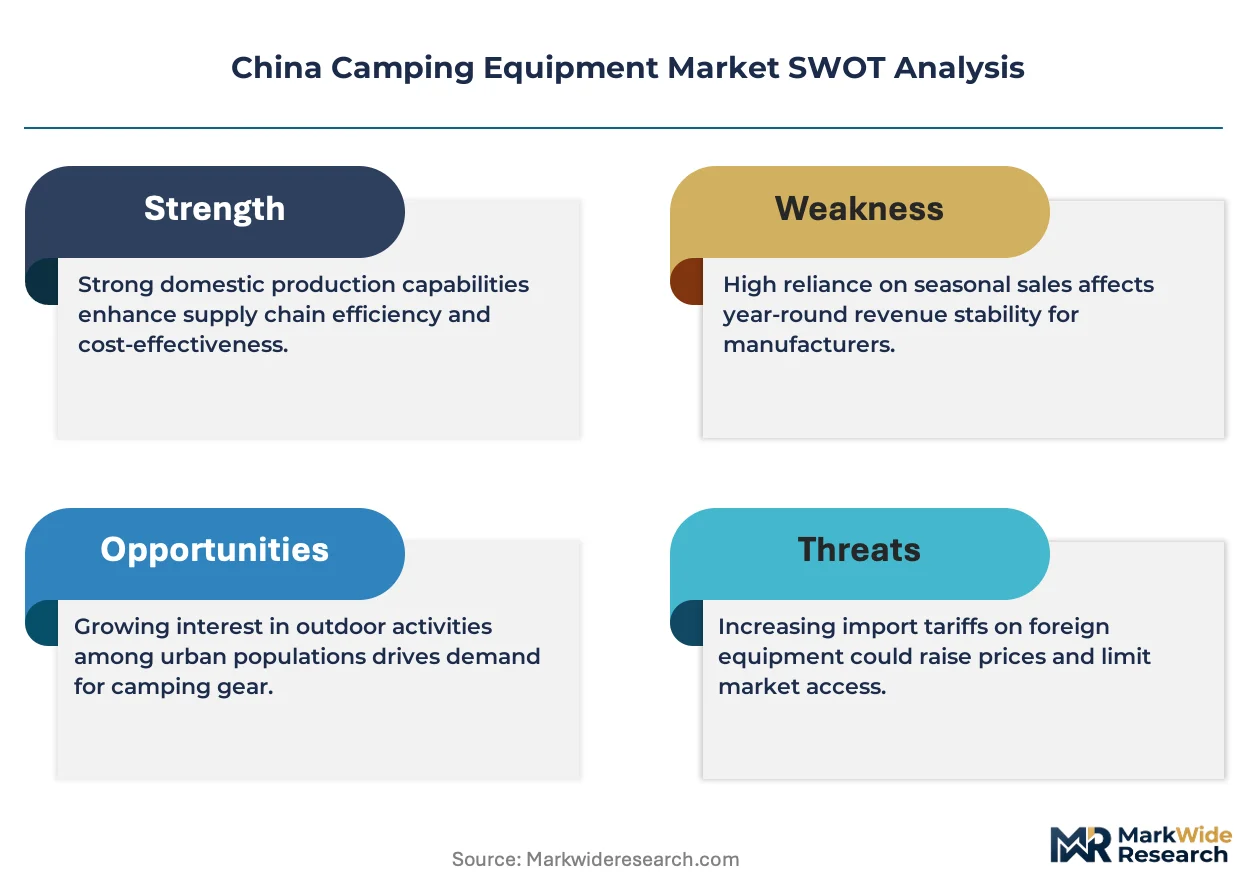
- GB Standard Harmonization:SAMR-enforced flame resistance and weatherproofing certifications for tent fabrics are consolidating supplier bases and elevating quality baselines across domestic production.
- Yangtze River Delta Cluster Effects:Concentrated nylon and polyester supply channels around Shanghai and Zhejiang Province are reducing procurement lead times for technical fabric components.
- Dual Carbon Policy Alignment:Beijing's national emissions targets are incentivizing reformulated polyester production processes that favor larger manufacturers with capital for green chemistry investments.
Market Restraints
- Petrochemical Input Volatility:Ripstop nylon and silicone coating prices fluctuate with crude oil derivatives, squeezing margin pools for mid-tier tent producers.
- Zhejiang Supplier Concentration:Dependence on a single province for 7000-series aluminum pole fabrication creates geographic vulnerability to regional power rationing or logistics disruptions.
- Biodegradable Treatment Uncertainty:Pending GB standard revisions for fabric biodegradability are freezing long-term sourcing contracts as suppliers await compliance specifications.
Strategic Opportunities
- Short-Video Platform Commerce:Douyin and Xiaohongshu are displacing specialty retail as primary research-to-purchase channels for first-time campers in tier-one cities.
- Multi-Fuel Stove Innovation:Ultralight cooking apparatus compatible with butane, white gas, and alcohol is capturing premium positioning among adventure tourists.
- Guangdong and Sichuan Penetration:Underdeveloped outdoor recreation infrastructure in southern and western provinces offers whitespace for organized camping club expansion.
Industry Challenges
- Technical Textile Engineering Talent:Shortage of specialists in silicone waterproof coating application and ripstop weaving is extending product development cycles.
- GB Certification Timeline Compression:Accelerated standard revision schedules are forcing simultaneous compliance re-engineering across multiple product lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Camping Equipment Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.2 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tents, Sleeping Bags, Camping Stoves, Backpacks End User: Outdoor Enthusiasts, Families, Adventure Tourists, Casual Campers Distribution Channel: Specialty Stores, Online Retailers, Department Stores, Rental Services Material: Nylon, Polyester, Aluminum, Fiberglass |
| Companies Covered | Yiwu City Yuelang Outdoor Co., Ltd., Xingyi Travel Products Factory, TANXIANZHE, Abris Outdoor Ltd., Xiamen Camping Co., Ltd., Yiwu Youngman Outdoor Product Factory, SUSUN OUTDOORS CO., LTD., Everich Outdoor, Ningbo Xinqiu Traveling Products Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Camping Equipment Market Trends and Innovations
Material science advances and regulatory tightening are converging to reshape competitive positioning in China's camping equipment sector, with particular intensity around structural component safety and digital-native distribution models.
Silicone-coated ripstop nylon is absorbing the functional requirements previously met by heavier polyurethane-laminated fabrics, reducing packed tent weights by thirty to forty percent for three-season shelters. Young professionals in Shanghai and Hangzhou are adopting these ultralight systems at pace, compressing demand for traditional double-wall designs and forcing Zhejiang manufacturers to reallocate loom capacity toward thinner denier weaves.
MIIT's updated structural standards for aluminum and fiberglass poles are mandating burst-strength testing protocols that exceed previous self-regulated industry benchmarks. The industrial consequence is a supplier qualification bottleneck as smaller Zhejiang fabricators lack capital for upgraded testing equipment. Backpack and tent categories face the steepest compliance ramps, with larger manufacturers absorbing certification costs to secure SAMR labeling priority.
Short-video platforms have become the dominant research and purchase channel for casual campers under thirty-five, displacing specialty outdoor retailers in tier-one cities. Douyin's integrated commerce tools enable direct manufacturer-to-consumer transactions that bypass traditional distributor margins. This behavioral shift concentrates most visibly in Shanghai and Beijing, where urban density supports same-day fulfillment of compact gear categories like camping stoves and sleep pads.
China Camping Equipment Market Segmentation
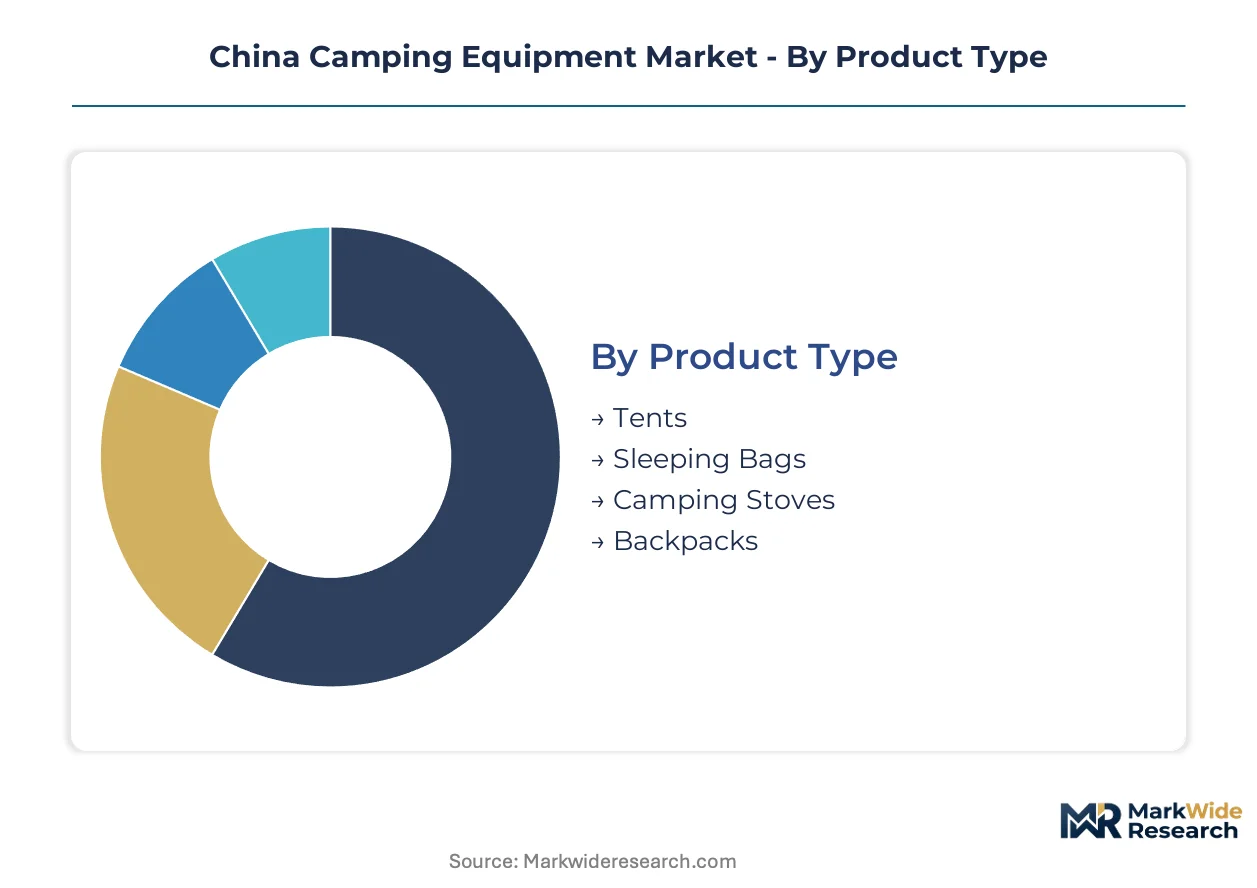
China's camping equipment manufacturers configure production lines around divergent capital requirements across product categories. Segment-specific tooling investments in Zhejiang Province are reshaping competitive entry barriers.
Product Type:
Capital intensity varies sharply across fabrication processes, with structural components demanding the heaviest upfront equipment outlays.
- Tents:Silicone-coated ripstop nylon shelters with 7000-series aluminum poles require precision cutting and seam-sealing machinery. Shanghai-based outdoor enthusiasts drive demand for sub-kilogram three-season designs that compress packed volume.
- Backpacks:Load-bearing systems engineered from technical fabrics with internal frame suspensions demand specialized sewing automation and ergonomic testing rigs. Adventure tourists in Hangzhou prioritize ultralight models with reinforced hip belts.
- Sleeping Bags:Down and synthetic insulation baffles sewn into nylon shells.
- Camping Stoves:Multi-fuel burner heads with pressure-regulated valves.
Tents absorb the bulk of installed capacity; camping stoves are expanding most quickly.
End User:
Volume concentration tilts toward recreational participants rather than technical specialists, though margin profiles invert this pattern.
- Casual Campers:First-time buyers purchasing entry-level gear through short-video platforms. Douyin commerce in Beijing and Guangzhou funnels these users toward bundled starter kits with minimal technical specifications.
- Adventure Tourists:Experienced users requiring expedition-grade equipment for multi-day treks. This segment commands premium pricing for SAMR-certified flame-resistant fabrics and MIIT-tested structural poles sourced through Zhejiang manufacturers.
- Outdoor Enthusiasts:Dedicated hobbyists with high equipment turnover rates.
- Families:Group purchasers consolidating through organized camping clubs.
Casual campers dominate transaction volume; adventure tourists capture the steepest expansion trajectory in value terms.
Distribution Channel:
Channel economics favor direct-to-consumer models that eliminate distributor markups in dense urban markets.
- Online Retailers:Integrated commerce platforms enabling manufacturer-direct fulfillment. Xiaohongshu content-to-purchase funnels in tier-one cities are displacing specialty retail for sleeping bags and compact stoves.
- Specialty Stores:Staffed showrooms with fitting services and technical consultation. These outlets retain importance for backpack suspension fitting among serious users in Chengdu and Xi'an.
- Department Stores:Seasonal retail partnerships with limited technical staffing.
- Rental Services:Equipment libraries serving trial users before purchase commitment.
Online retailers command the largest revenue share; rental services are climbing the fastest as trial-before-buy behavior spreads.
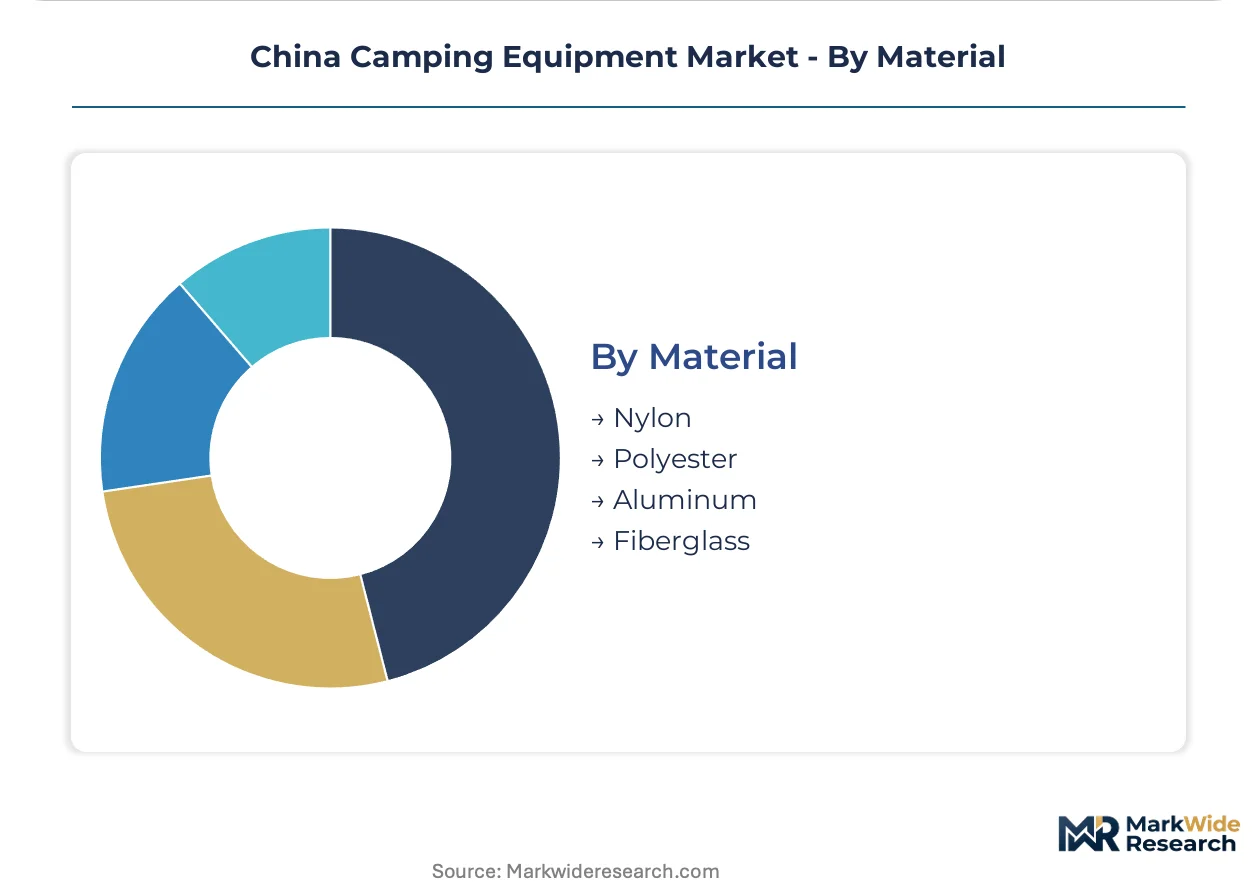
Material:
Dual carbon policy compliance costs are concentrating supply among capitalized producers capable of green chemistry investments.
- Nylon:Ripstop weaves with silicone waterproof coatings. Yangtze River Delta suppliers around Shanghai are reformulating production to meet pending GB biodegradability standards.
- Aluminum:7000-series alloys for tent poles and backpack frames. MIIT burst-strength testing mandates have consolidated fabrication among Zhejiang factories with upgraded metallurgical equipment.
- Polyester:Lower-cost alternative to nylon with heavier packed weights.
- Fiberglass:Budget structural poles for entry-level tent lines.
Nylon retains the dominant share of technical fabric consumption; aluminum is gaining share fastest as ultralight designs proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Young urban professionals in Shanghai and Hangzhou concentrate demand for ultralight camping systems. Provincial manufacturing clusters in Zhejiang and Jiangsu anchor supply-side capacity. MIIT structural standards and dual carbon targets are reshaping regional production economics.
Yangtze River Delta
Shanghai-based outdoor enthusiasts drive adoption of sub-kilogram tent designs. SAMR enforces GB flame-resistance certifications for technical fabrics sold through this corridor. Zhejiang Province manufacturers around Ningbo and Hangzhou control nylon supply channels and aluminum pole fabrication.
Pearl River Delta
Guangzhou and Shenzhen consumers purchase entry-level gear through Douyin commerce platforms. The region lacks established outdoor recreation infrastructure compared to eastern China. Dongguan-based polyester suppliers face reformulation costs under pending biodegradable treatment standards.
Beijing-Tianjin-Hebei
Adventure tourists in Beijing command premium pricing for SAMR-certified expedition equipment. MIIT burst-strength testing mandates have consolidated supplier relationships toward Zhejiang-certified fabricators. Tianjin port logistics handle imported aluminum alloy raw materials for regional distribution.
Sichuan-Chongqing
Underdeveloped camping infrastructure in western China offers whitespace for organized club expansion. Chongqing consumers show rising interest through Xiaohongshu content engagement. Local manufacturers remain absent; equipment flows eastward from Yangtze River Delta clusters.
Shandong Peninsula
Qingdao and Yantai consumers participate in coastal recreational camping with lower equipment turnover rates. The province hosts limited technical fabric production. Regional demand depends on e-commerce fulfillment from Zhejiang-based inventory positions.
China Camping Equipment Market Competitive Landscape
Zhejiang-based producers anchor one tier; specialized outdoor brands from manufacturing hubs hold differentiated positions. The vendor base separates into scale-driven fabricators with captive nylon supply, brand-positioned specialists serving tier-one cities, and commodity assemblers competing on short-video platform visibility. Three archetypes dominate: integrated manufacturers controlling upstream material channels, marketing-heavy brands leveraging social commerce, and export-oriented OEMs pivoting toward domestic channels. Capacity consolidation and certification pre-emption represent the dominant competitive moves as smaller fabricators exit under compliance cost pressure.
Within the brand-positioned tier, TANXIANZHE and Everich Outdoor exemplify divergent strategic anchors. TANXIANZHE occupies a premium positioning archetype targeting adventure tourists in Shanghai and Hangzhou with SAMR-certified product lines. Everich Outdoor represents the integrated manufacturing archetype, leveraging Zhejiang Province production scale and nylon supply channel control. Yiwu City Yuelang Outdoor Co., Ltd. sits within the export-to-domestic pivot archetype, reflecting Yiwu's broader small-commodity manufacturing ecosystem.
| Leading Market Players |
|---|
| Yiwu City Yuelang Outdoor Co., Ltd. |
| Xingyi Travel Products Factory |
| TANXIANZHE |
| Abris Outdoor Ltd. |
| Xiamen Camping Co., Ltd. |
| Yiwu Youngman Outdoor Product Factory |
| SUSUN OUTDOORS CO., LTD. |
| Everich Outdoor |
| Ningbo Xinqiu Traveling Products Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between SAMR-certified expedition equipment and unlabeled commodity gear manifests in pricing spreads exceeding threefold for comparable tent specifications, while simultaneously concentrating supply relationships among Zhejiang fabricators with upgraded metallurgical testing capacity. This bifurcation rewards manufacturers who absorbed MIIT burst-strength compliance costs early, locking in procurement priority from adventure tourists in Shanghai and Hangzhou.
Pricing Analysis
Volume concentrates in entry-level polyester shelters sold through Douyin commerce, while margin pools accrue to ultralight nylon systems with silicone waterproof coatings. Price differentiation rests on GB flame-resistance certification status and 7000-series aluminum pole sourcing from MIIT-qualified Zhejiang suppliers. Cost compression in the casual camper tier intensifies because Dongguan polyester suppliers face reformulation expenses under pending biodegradable standards. Family segment buyers through organized camping clubs show lowest price sensitivity; first-time short-video purchasers exhibit highest.
Supply Chain Analysis
Returns and refurbishment flows remain minimal in technical outdoor equipment, though rental service growth in Beijing and Guangzhou is creating secondary circulation channels for sleeping bags and compact stoves. Raw material dependencies draw from Zhejiang Province for ripstop nylon and 7000-series aluminum, with silicone coating chemicals sourced through Yangtze River Delta petrochemical corridors. Single-source vulnerability concentrates in aluminum pole fabrication, where regional power rationing would freeze tent production nationwide. Distribution runs through Xiaohongshu and Douyin integrated commerce platforms for casual campers, while specialty retail retains backpack fitting services for adventure tourists in Chengdu and Xi'an.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
MIIT structural standards and pending GB biodegradability revisions are erecting capital barriers that favor incumbents with pre-positioned compliance infrastructure, transforming manufacturing certification into a durable competitive moat.
For Market Incumbents: Extend SAMR certification coverage across sleeping bag and stove categories before standard revisions accelerate, preempting smaller Zhejiang competitors who lack testing equipment capital. Deepen backward integration into silicone coating application to capture margin pools currently flowing to Yangtze River Delta chemical suppliers. Channel control through Douyin flagship stores defends against emerging direct-to-consumer brands. For New Entrants and Emerging Players: Short-video platform content creators represent the most penetrable channel partner type for bypassing established distributor networks. Target Sichuan-Chongqing whitespace through organized camping club partnerships, where underdeveloped outdoor infrastructure creates first-mover advantages. Position around multi-fuel stove innovation as the go-to-market angle, exploiting technical textile engineering talent scarcity that slows incumbent product development cycles. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated manufacturing groups seeking Zhejiang production scale and nylon supply channel control. Long-term viability favors capitalized producers with green chemistry investments aligned to dual carbon compliance timelines. Monitor GB standard revision publication schedules as the critical inflection signal for supplier qualification bottlenecks and consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| GB Certification Pre-emption | Early compliance with SAMR flame-resistance mandates locks in supplier relationships before smaller fabricators exit. |
| Short-Video Platform Flagship Launch | Douyin and Xiaohongshu direct commerce displaces distributor margins in tier-one city casual camper segments. |
| Multi-Fuel Stove R&D Investment | Ultralight burner compatibility with butane, white gas, and alcohol captures premium positioning among adventure tourists. |
| Zhejiang Aluminum Pole Capacity Expansion | MIIT burst-strength testing mandates consolidate fabrication among upgraded metallurgical equipment holders. |
| Organized Camping Club Partnership | Social group purchasing in Guangdong and Sichuan penetrates underdeveloped western China outdoor recreation markets. |
Research Methodology
Industry association filings, SAMR certification databases, and Yangtze River Delta customs records formed the secondary backbone, cross-referenced against primary interviews with Zhejiang manufacturing plant managers, outdoor brand procurement directors, Douyin commerce platform category leads, and organized camping club organizers. Bottom-up demand modeling from end-user segment sizing triangulated against top-down production capacity estimates across nylon weaving and aluminum pole fabrication clusters.
Historical trendline analysis of technical fabric consumption and structural component shipments established baseline growth patterns across the projection horizon. Segmentation dimensions modeled include product category, end-user archetype, distribution channel, and material composition, with CAGRs derived from elasticity-adjusted demand curves. Forecast inputs incorporated MIIT standard implementation timelines and dual carbon policy compliance cost trajectories specific to polyester reformulation chemistry.
Caveats apply where GB biodegradability standard revisions or regional power rationing in Zhejiang could materially shift the outlook for supplier qualification and production continuity. Practitioners should monitor SAMR labeling priority announcements and short-video platform commerce policy changes for early signals of channel structure evolution.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor Gear
US Backpacks Market
Outdoor Gear
Spain Camping Equipment Market
Outdoor Gear
Inflatable Tents Market
Outdoor Gear
Cordless Garden Equipment Market
Outdoor Gear
Australia Camping Equipment Market
Outdoor Gear
Diving Regulator Market
Outdoor Gear
Outdoor Hot Tub Market
Outdoor Gear
Global Automatic Mower Market
Outdoor Gear
Wheeled Insulated Cooler Market
Outdoor Gear
Japan Camping Tent Market
Outdoor Gear
Rechargeable Camping Gear Market
Outdoor Gear
Camping Equipment and Furniture Market
Outdoor Gear
Singapore Camping Equipment Market
Outdoor Gear
Deer Hunting Blinds Market
Outdoor Gear
Camping Gas Canister Market
Outdoor Gear
Hiking Backpack Water Filters Market