
 Australia Camping Equipment Market | 2026-2036
Australia Camping Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Camping Equipment Market Insights
AS/NZS 5263 certification for portable gas appliances is reorganizing competitive access, forcing smaller brands to invest in third-party testing or exit the category. Sea to Summit leverages its Perth-based design hub to sustain technical leadership in ultralight sleeping systems. OZtrail anchors mass-market volume through exclusive retail partnerships with Big W and Bunnings Warehouse. Macpac differentiates via its lifetime warranty program and New Zealand-Australia dual-market manufacturing footprint.
Camping equipment encompasses portable shelters, sleep systems, cooking apparatus, and load-bearing gear engineered from ripstop nylon, DAC aluminum, and hydrophobic down to withstand ultraviolet exposure, moisture, and terrain stress across remote Australian environments. Tents and sleeping bags command the largest revenue pools, though glamping application demand is expanding fastest as operators invest in permanent canvas structures and elevated furnishings. Specialty stores and online retail together dominate distribution, with direct-to-consumer channels capturing margin from repeat purchasers seeking technical upgrades.
TGA guidelines for therapeutic goods intersect with camping equipment where first-aid and water purification kits carry medical claims, while ACCC mandatory standards govern product safety labeling and recall protocols. Biosecurity Queensland regulations on imported timber and bamboo products affect trekking pole and utensil sourcing, adding documentation burdens for Asian suppliers. Stakeholders must monitor evolving state-level fire restrictions on portable gas appliances, as Victoria and New South Wales tighten seasonal bans that directly impact cookware sales cycles and inventory planning.
Market Dynamics
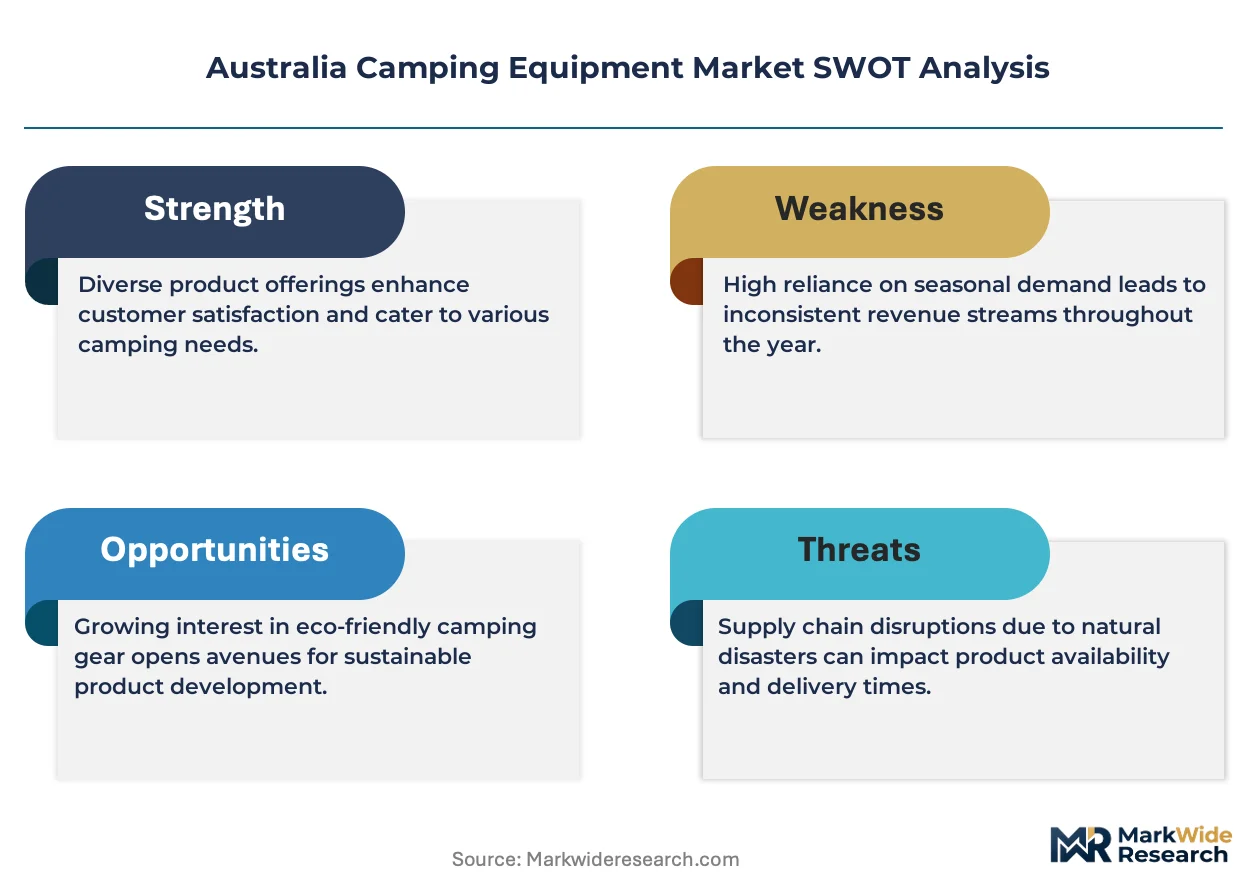
AS/NZS 5263 certification mandates for portable gas appliances are restructuring competitive access across Australia's camping equipment sector, forcing capital reallocations toward testing infrastructure and compliance documentation.
Growth Catalysts
- Domestic Tourism Pivot:Rising international airfares redirect Australian holiday spending toward intrastate camping corridors, particularly Queensland's coastal routes and Tasmania's wilderness zones.
- Glamping Infrastructure Investment:Permanent canvas structures and elevated furnishings attract hospitality operators seeking yield from experiential accommodation models.
- Biosecurity Queensland Timber Protocols:Documentation requirements for imported bamboo and hardwood trekking components create compliance moats for established suppliers with dedicated import teams.
Market Restraints
- Ripstop Nylon and DAC Aluminum Input Volatility:Petrochemical feedstock fluctuations and aluminum smelter energy costs compress margin predictability for tent and pole manufacturers.
- Single-Source Hydrophobic Down Concentration:Premium insulation supply chains cluster with limited European processors, exposing Australian brands to quota and shipping disruptions.
- ACCC Mandatory Recall Protocols:Product safety labeling requirements extend liability exposure and insurance costs across the portable appliance category.
Strategic Opportunities
- Therapeutic Goods Administration Intersection:First-aid and water purification kits carrying medical claims access differentiated retail placement through pharmacy and outdoor store dual-channel distribution.
- Victoria and New South Wales Seasonal Fire Restrictions:Electric and induction cookware lines capture displaced gas appliance demand during summer prohibition windows.
- Direct-to-Consumer Technical Upgrades:Repeat purchaser segments seeking performance improvements bypass traditional retail markups through brand-owned digital channels.
Industry Challenges
- AS/NZS 5263 Certification Timeline Compression:Third-party testing queue backlogs delay product launches and seasonal inventory positioning for emerging brands.
- Ultraviolet Degradation Engineering Talent Scarcity:Polymer scientists with remote-environment durability expertise command premium compensation in a thin Australian labor pool.
- State-Level Fire Ban Coordination Fragmentation:Inconsistent seasonal restriction calendars across jurisdictions complicate national inventory planning and marketing calendar synchronization.
Report Scope
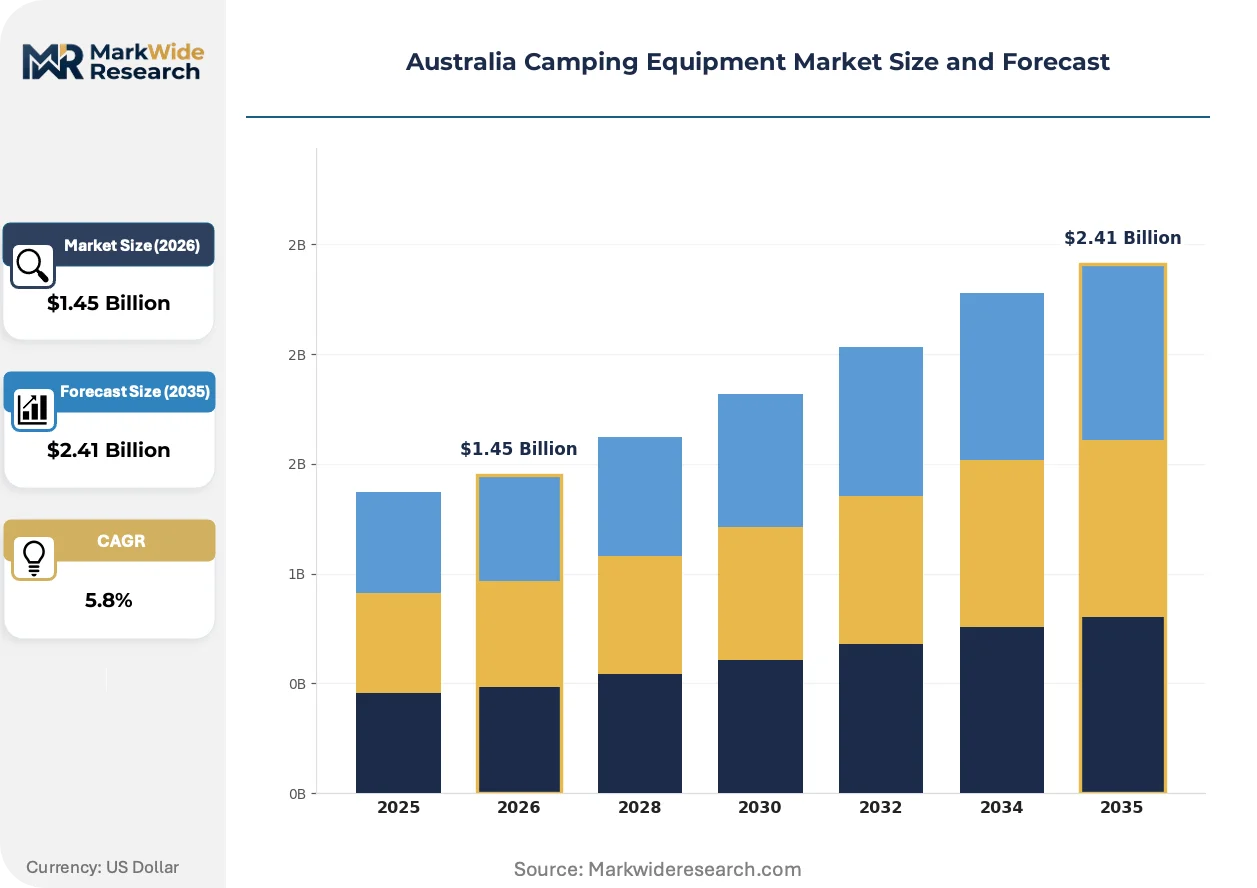
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Camping Equipment Market |
| Market Size in 2026 | $1.45 Billion |
| Market Size in 2035 | $2.41 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tents, Sleeping Bags, Cookware, Backpacks Application: Hiking, Backpacking, Glamping, Family Camping End User: Outdoor Enthusiasts, Families, Casual Campers, Professionals Distribution Channel: Online Retail, Specialty Stores, Department Stores, Direct Sales |
| Companies Covered | Sea to Summit, OZtrail, Anaconda, Wild Earth, One Planet, Macpac, Paddy Pallin, Caribee, Snowys Outdoors, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Camping Equipment Market Trends and Innovations
Technical material evolution and regulatory compliance automation are actively redrawing competitive boundaries across Australia's camping equipment landscape, with specialization premiums widening between certified and non-certified product tiers.
Ultralight composite pole systems utilizing carbon fiber hybrid constructions are fragmenting traditional aluminum dominance in technical tent architectures. Specialist backcountry retailers and expedition-grade consumers adopt these structures despite price premiums. The technology is fragmenting volume concentration among legacy aluminum suppliers and compressing their margin structures in premium segments.
ACCC mandatory standards for portable gas appliance labeling and recall traceability impose documentation automation requirements across manufacturing operations. Industrial consequence includes ERP system upgrades and batch-level serialization investments. Queensland and Western Australia distribution centers bear the heaviest adaptation burden as they process the highest import volumes from Asian assembly points.
Buyer concentration among repeat technical upgraders is unbundling traditional retail service packages and compressing switching cycles. Specialty stores lose attachment revenue as direct channels capture calibration and repair instruction through video content and chat support. Tasmania's wilderness tourism operators and Victorian alpine clubs exhibit the most pronounced migration toward manufacturer-direct procurement models.
Australia Camping Equipment Market Segmentation
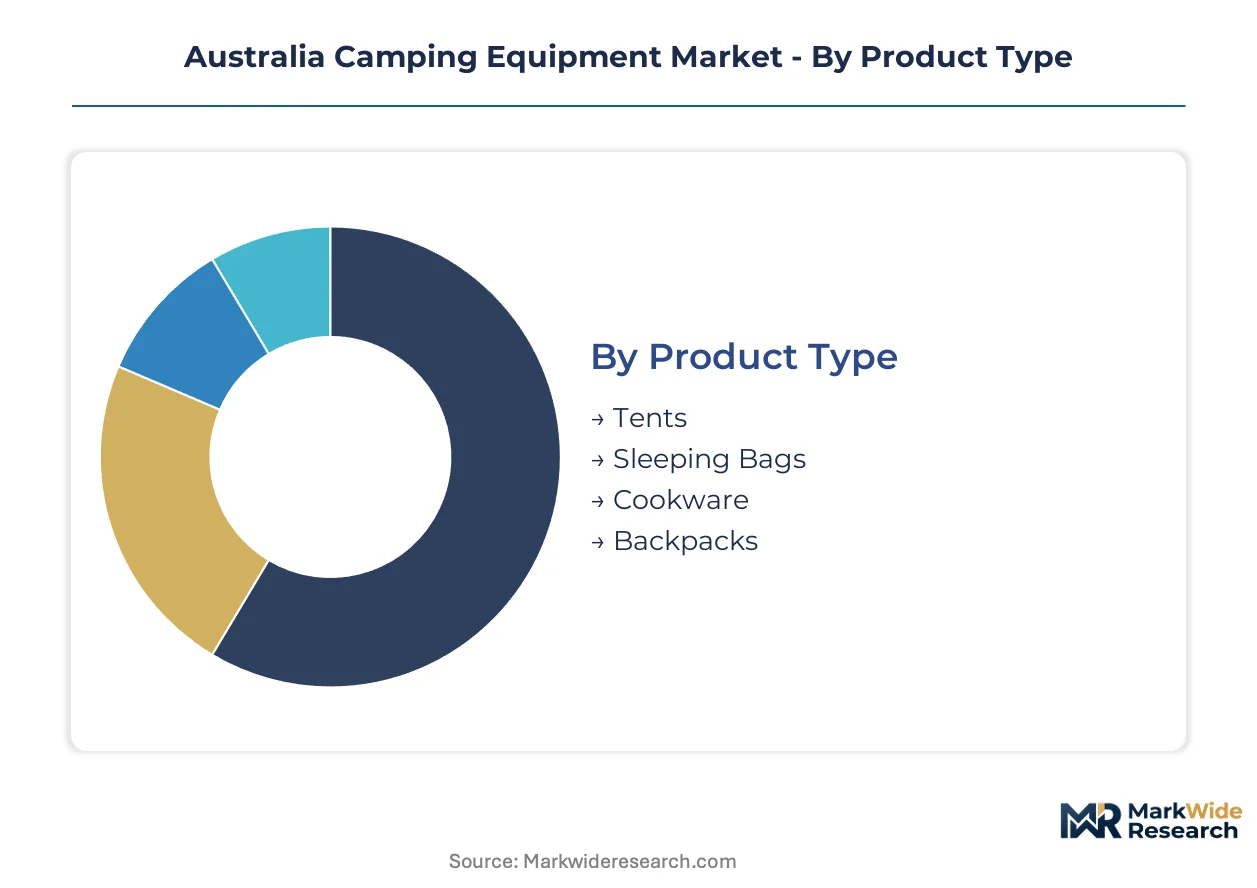
Segmentation in Australia's camping equipment market reveals distinct margin architectures across product categories and channel configurations. Procurement patterns diverge sharply between technical backcountry users and mass-market recreational segments, with regulatory compliance costs unevenly distributed across these divides.
Product Type:
Margin pools concentrate in sleep systems and technical shelters where material innovation commands pricing power.
- Tents:Engineered from ripstop nylon with DAC aluminum or carbon fiber hybrid pole systems, these structures face acute cost pressure from petrochemical feedstock volatility. Queensland's coastal campground corridors and Tasmania's wilderness tourism zones drive replacement cycles for UV-degraded fabrics.
- Sleeping Bags:Insulation grades span synthetic fills to hydrophobic down clustered with limited European processors, exposing Australian brands to quota disruptions. Demand concentrates among repeat technical upgraders seeking weight-to-warmth optimization for alpine conditions.
- Cookware:AS/NZS 5263 certification mandates force capital reallocations toward testing infrastructure for portable gas appliances, compressing margin predictability for smaller brands.
- Backpacks:Load-bearing systems utilizing reinforced nylon and aluminum frame stays serve multi-day trekkers with durability requirements that extend replacement cycles versus recreational segments.
The dominant share belongs to Tents, while Sleeping Bags is closing the gap fastest.
Application:
Volume distribution tracks the domestic tourism pivot away from international travel toward intrastate experience investment.
- Hiking:Technical day-trip and multi-day foot travel demands ultralight equipment with gram-counting precision. Western Australia's Bibbulmun Track and Victorian alpine routes concentrate specialist retailer foot traffic.
- Backpacking:Self-supported wilderness travel requires integrated sleep-cook-carry systems with redundancy engineering for remote-area failure scenarios. Tasmania's Overland Track operators bulk-procure expedition-grade kits.
- Glamping:Permanent canvas structures and elevated furnishings attract hospitality operators seeking yield from experiential accommodation models, expanding fastest as infrastructure investment redirects from traditional hotel development.
- Family Camping:Vehicle-accessible basecamp configurations prioritize durability over weight, with Big W and Bunnings Warehouse capturing volume through seasonal promotional cycles.
Family Camping retains volume leadership, though Glamping exhibits the steepest expansion trajectory.
End User:
Customer lifetime value spreads widest across technical users with repeat upgrade patterns versus single-purchase casual entrants.
- Outdoor Enthusiasts:Dedicated backcountry practitioners with equipment knowledge sufficient to bypass retail service packages, migrating toward manufacturer-direct channels for calibration and repair instruction.
- Families:Multi-person shelter and sleep system procurement concentrates in pre-summer retail windows, with durability preferences extending replacement cycles versus individual users.
- Casual Campers:Infrequent users with low brand loyalty and high price sensitivity, susceptible to private-label capture through department store seasonal promotions.
- Professionals:Guides, outdoor educators, and emergency services requiring commercial-grade durability with accelerated depreciation schedules and bulk replacement protocols.
Outdoor Enthusiasts generate the highest per-customer margin contribution, while Professionals is gaining share fastest.
Distribution Channel:
Channel economics fragment as direct-to-consumer capture erodes traditional retail attachment revenue.
- Online Retail:Digital marketplaces aggregate comparison shopping with fulfillment infrastructure concentrating in Queensland and Western Australia distribution centers processing Asian import volumes.
- Specialty Stores:Technical consultation and fitting services retain relevance for complex sleep system matching, though losing calibration and repair revenue to manufacturer video content.
- Department Stores:Mass-market volume through exclusive retail partnerships anchors seasonal procurement for price-sensitive segments with lower service expectations.
- Direct Sales:Brand-owned digital channels capture margin from repeat purchasers seeking technical upgrades, with Tasmania's wilderness tourism operators and Victorian alpine clubs exhibiting pronounced migration toward this model.
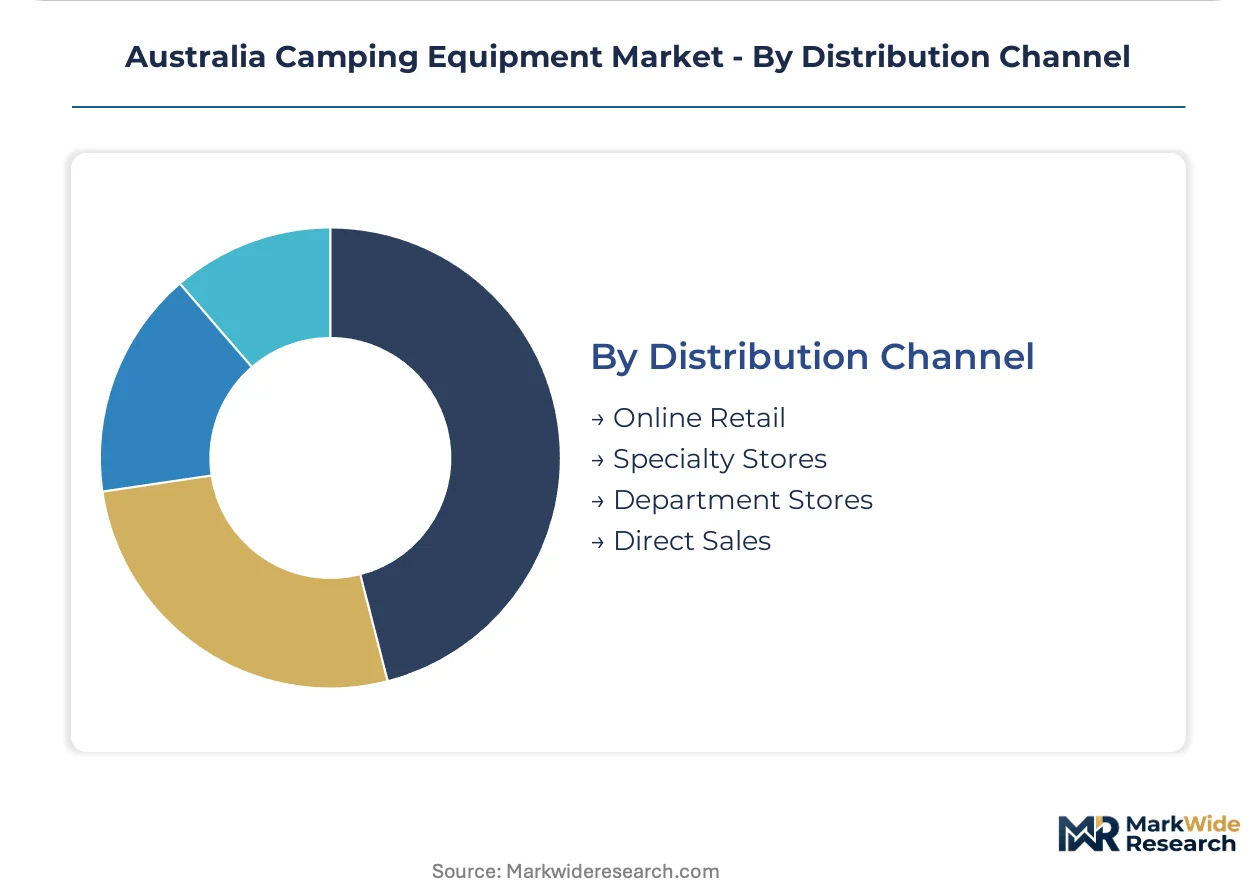
Specialty Stores hold the dominant position, yet Direct Sales is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Australian Competition and Consumer Commission's tightening product safety standards and Queensland's biosecurity timber protocols are redistributing manufacturing and distribution investments across state-level camping corridors.
New South Wales
Victorian alpine clubs and Sydney's outdoor retail clusters drive technical equipment procurement for multi-day trekking. State-level fire restrictions on portable gas appliances tighten seasonal sales windows, compressing inventory cycles for cookware distributors. The Blue Mountains and Kosciuszko National Park corridors concentrate specialist retailer foot traffic and manufacturer-direct procurement migration.
Victoria
Seasonal fire ban calendars disrupt national inventory planning for gas appliance vendors, with summer prohibition windows redirecting demand toward electric alternatives. The state's therapeutic goods guidelines intersect with camping equipment where first-aid kits carry medical claims, enabling pharmacy channel placement. Melbourne's design and polymer science talent pool supports UV-degradation engineering for tent fabric suppliers.
Queensland
Coastal campground corridors anchor the highest volume of family camping equipment turnover through Big W and Bunnings Warehouse seasonal promotions. Biosecurity Queensland regulations on imported timber and bamboo products add documentation burdens for trekking pole and utensil sourcing. Distribution centers in Brisbane and the Gold Coast process the heaviest import volumes from Asian assembly points for national fulfillment.
Western Australia
The Bibbulmun Track and remote-area tourism operators bulk-procure expedition-grade sleep and shelter systems with redundancy engineering requirements. Perth-based design hubs sustain technical leadership in ultralight sleeping systems through polymer science specialization. ACCC mandatory recall protocols extend liability exposure for portable appliances distributed through this import gateway.
Tasmania
Wilderness tourism zones and Overland Track operators drive demand for integrated sleep-cook-carry systems with commercial-grade durability. The state's concentration of glamping infrastructure investment redirects hospitality procurement toward permanent canvas structures and elevated furnishings. Tasmanian operators exhibit pronounced migration toward manufacturer-direct channels for technical calibration and repair support.
Australia Camping Equipment Market Competitive Landscape
Player mix skews toward domestic heritage brands with dual-channel retail partnerships and direct-to-consumer technical specialists. Market structure concentrates around three tiers: mass-market volume anchors through exclusive retail partnerships, premium technical specialists with design hub proximity, and emerging direct-to-consumer challengers capturing repeat upgrade segments. Two strategic archetypes dominate competitive positioning: compliance-forward incumbents with dedicated import teams navigating biosecurity documentation, and ultralight innovation specialists leveraging polymer science talent scarcity. Dominant competitive moves include exclusive retail partnership renewals and direct channel infrastructure expansion.
Among Australia-based heritage operators, Sea to Summit and OZtrail occupy distinct tier positions. Sea to Summit exemplifies the technical specialist archetype with design hub proximity to polymer science talent pools. OZtrail anchors mass-market volume through exclusive retail partnerships with national warehouse chains. Macpac represents the trans-Tasman dual-market fabricator with warranty program differentiation. These three operators illustrate the competitive spectrum from technical innovation to scale-driven distribution capture.
| Leading Market Players |
|---|
| Sea to Summit |
| OZtrail |
| Anaconda |
| Wild Earth |
| One Planet |
| Macpac |
| Paddy Pallin |
| Caribee |
| Snowys Outdoors |
| Others |
Pricing and Supply Chain Analysis
Big W and Bunnings Warehouse procurement volumes compress unit economics for mass-market tent and cookware suppliers, creating scale thresholds that price out smaller competitors while reinforcing concentration among AS/NZS 5263-certified incumbents. This dynamic tightens margin floors for uncertified entrants and elevates pricing power for established brands with dedicated compliance infrastructure.
Pricing Analysis
Certification level creates the primary spread across Australia's camping equipment landscape, with AS/NZS 5263-compliant portable gas appliances commanding substantial premiums over uncertified alternatives. Three-tier pricing structure separates expedition-grade technical gear with lifetime warranties from standard recreational equipment and economy private-label offerings at Big W. Pricing pressure stems from ripstop nylon feedstock volatility and DAC aluminum smelter energy costs, compressing predictability for tent manufacturers. Casual campers through department store channels exhibit highest price sensitivity, while Outdoor Enthusiasts accept premiums for gram-counting precision.
Supply Chain Analysis
Strategic stockpile preferences dominate camping equipment procurement, with Queensland and Western Australia distribution centers maintaining elevated inventory buffers against seasonal fire ban disruptions and biosecurity documentation delays. Manufacturing concentrates in China, Vietnam, and Taiwan for ripstop nylon weaving, DAC aluminum extrusion, and carbon fiber pole fabrication. Raw material dependencies tether Australian brands to European hydrophobic down processors, petrochemical feedstocks, and aluminum smelter output. Single-source vulnerability clusters around premium insulation supply chains. Distribution runs through Brisbane and Perth import gateways feeding national specialty retail and direct-to-consumer channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hardware attachment rates for calibration services, repair support, and seasonal equipment refresh programs expand faster than tent and sleeping bag unit sales, repositioning margin capture toward recurring-revenue layers.
For Market Incumbents: Secure exclusive renewal terms with Big W and Bunnings Warehouse before emerging direct-to-consumer challengers erode mass-market channel control. Invest in backward integration into DAC aluminum pole sourcing to offset smelter energy cost volatility. Defend against Sea to Summit's technical leadership by acquiring Perth-based polymer science talent for UV-degradation engineering. For New Entrants and Emerging Players: AS/NZS 5263 certification fast-track through third-party testing partnerships opens competitive access for electric and induction cookware lines capturing displaced gas appliance demand during Victoria and New South Wales summer prohibition windows. Target Tasmania's wilderness tourism operators with manufacturer-direct technical support models. Penetrate via subscription-based equipment refresh programs for repeat technical upgraders. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among direct-to-consumer technical specialists with repair and calibration service attach. Long-term viability favors dual-channel operators with compliance infrastructure and design hub proximity to polymer science talent pools. Acquisition targets should display AS/NZS 5263 certification completion and established import documentation teams. Watch for fire ban calendar harmonization across jurisdictions as inflection indicator for gas appliance demand recovery.| Strategic Initiative | Industry Significance |
|---|---|
| AS/NZS 5263 Certification Completion | Unlocks retail placement with Big W and Bunnings Warehouse seasonal procurement cycles. |
| Direct-to-Consumer Channel Launch | Captures margin from Tasmania's wilderness tourism operators seeking technical calibration support. |
| Perth Design Hub Establishment | Accesses scarce polymer science talent for UV-degradation engineering in tent fabrics. |
| Electric Cookware Line Introduction | Captures displaced demand during Victoria and New South Wales seasonal fire restrictions. |
| Lifetime Warranty Program Implementation | Differentiates against OZtrail mass-market positioning and Macpac trans-Tasman offerings. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of ACCC product safety filings, Biosecurity Queensland import documentation, and retail audit data from specialty camping chains. The analysis combined interviews with procurement managers at Big W and Bunnings Warehouse, technical directors at Perth-based design hubs, compliance officers navigating AS/NZS 5263 certification, and wilderness tourism operators in Tasmania and Queensland. Secondary sources included TGA therapeutic goods guidelines, state-level fire restriction calendars, and customs records for ripstop nylon and DAC aluminum imports. Bottom-up demand modeling from campground corridor equipment replacement cycles triangulated against top-down market sizing from retail channel revenue aggregation.
Segmentation dimensions modeled span product type, application, end user, and distribution channel across the projection horizon. The analytical framework incorporated hiking, backpacking, glamping, and family camping applications with distinct procurement patterns and margin architectures. CAGRs derived from equipment replacement cycle analysis, domestic tourism spending redirection, and glamping infrastructure investment trajectories. Industry-specific inputs included UV-degradation rates for Queensland coastal fabrics, alpine condition performance requirements, and seasonal fire ban impact coefficients for cookware demand.
Decision-makers should treat outputs as directional under assumptions of continued international airfare elevation and stable biosecurity documentation requirements; material deviation would warrant model refresh. Forecasts reflect base-case assumptions regarding AS/NZS 5263 certification timeline compression and petrochemical feedstock volatility. Revision becomes warranted when state-level fire ban harmonization crosses coordination thresholds or when European hydrophobic down processor quotas disrupt supply.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor Gear
Spain Camping Equipment Market
Outdoor Gear
Rain Boots Market
Outdoor Gear
Japan Camping Equipment Market
Outdoor Gear
Camping Equipment Market
Outdoor Gear
Wheeled Insulated Cooler Market
Outdoor Gear
Rechargeable Camping Gear Market
Outdoor Gear
Camp Fire Tripod Market
Outdoor Gear
Outdoor Hot Tub Market
Outdoor Gear
Inflatable Tents Market
Outdoor Gear
US Backpacks Market
Outdoor Gear
Snow Chain Market
Outdoor Gear
Mexico Camping Equipment Market
Outdoor Gear
Rooftop Tent Market
Outdoor Gear
North America Pocket Knives Market
Outdoor Gear
Hunting Boots Market
Outdoor Gear
New Zealand Camping Equipment Market