
 Camping Equipment and Furniture Market | 2026-2036
Camping Equipment and Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
Camping Equipment and Furniture Market Insights
Modular tent systems with detachable vestibules and interchangeable poles is hardening as the default configuration for serious backpackers. The Coleman Company, Inc. leverages its mass-production infrastructure to dominate the family camping segment through big-box retail partnerships. Johnson Outdoor Inc. anchors its position in specialty channels with premium backpacking shelters engineered for alpine conditions. Helinox differentiates through ultralight furniture using DAC aluminum pole technology originally developed for trekking equipment.
Camping equipment and furniture encompasses portable shelters, sleep systems, seating, and cooking apparatus designed for temporary outdoor habitation, typically constructed from ripstop polyester or silicone-coated nylon with hydrostatic head ratings exceeding 1200mm for waterproof performance. The primary commercial purpose is enabling safe, comfortable overnight stays in non-permanent locations ranging from designated campgrounds to remote backcountry zones. Tents command the largest revenue pool as families prioritize weatherproof living space with quick-pitch architecture, while portable stoves represent the fastest-growing category as backcountry cooking and boil-in-bag meal formats gain traction among time-constrained outdoor enthusiasts. Aluminum-framed camping chairs sustain margin concentration in the specialty retail channel where weight-to-durability ratios justify premium positioning above steel or wood alternatives.
REACH in Europe and EPA regulations in the United States restrict perfluorinated compounds in durable water repellent treatments, forcing manufacturers to reformulate tent fabrics with silicone or polyurethane-based alternatives. The EU Green Deal's extended producer responsibility frameworks are pressuring brands to design for disassembly and establish take-back programs for end-of-life synthetic gear. China's GB standards and NMPA oversight on imported outdoor products create additional compliance layers for brands sourcing manufacturing through East Asian supply chains. Stakeholders must monitor how pending state-level fire-retardant bans in California and New York reshape sleeping bag insulation specifications and factory certification requirements.
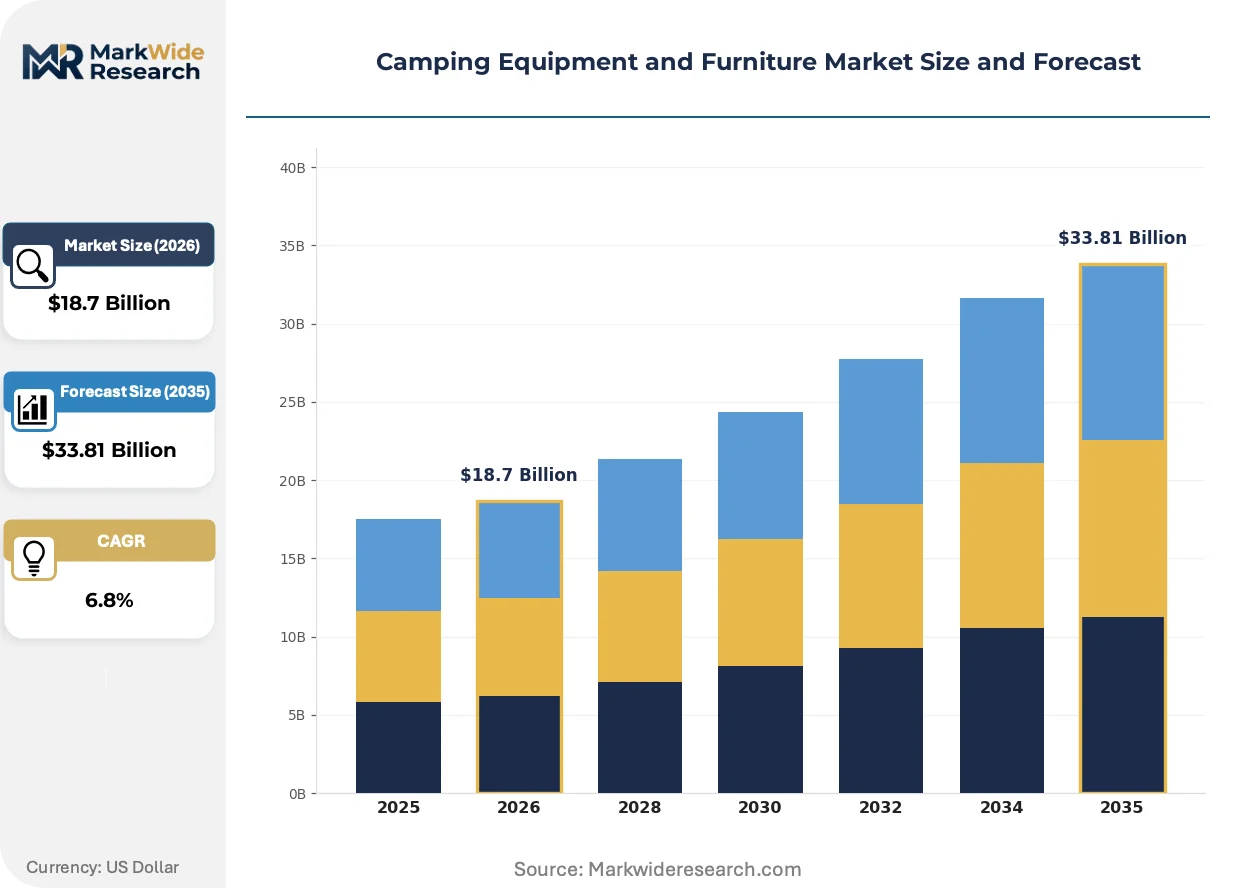
Market Dynamics
REACH chemical compliance in Europe is forcing wholesale reformulation of tent fabrics and coatings, compressing supplier margins while creating first-mover advantages for brands with silicone-based alternatives already in production.
Growth Catalysts
- Backpacker segment expansion:Lightweight gear preferences among alpine and thru-hiking communities are pulling demand toward sub-kilogram shelter systems and collapsible furniture.
- Dispersed camping permits:United States national forest and BLM permit volume is climbing, extending addressable demand beyond designated campground infrastructure.
- Silicone-coated nylon migration:Fabric mills are retooling production lines to eliminate perfluorinated compounds ahead of regulatory deadlines.
Market Restraints
- Raw material concentration:DAC aluminum pole supply concentrates among Japanese and Korean specialty extruders, creating single-source vulnerability for ultralight furniture brands.
- REACH compliance costs:European small-batch manufacturers face disproportionate testing and certification burdens relative to mass-market competitors with in-house labs.
- Insulation substitution pressure:Down-alternative synthetic fills from recycled polyester are displacing traditional goose down in sleeping bags, compressing margin pools for premium suppliers.
Strategic Opportunities
- EU Green Deal take-back programs:Extended producer responsibility frameworks reward brands designing tents for field-repairability and component disassembly.
- Boil-in-bag meal integration:Portable stove manufacturers can capture incremental attach rates by optimizing burner geometry for dehydrated food pouch dimensions.
- Modular architecture licensing:Pole-connector and vestibule-attachment IP represents licensable value for brands without internal R&D capacity.
Industry Challenges
- Pattern-making talent scarcity:Technical designers capable of optimizing seam taping and guy-out geometry for sub-two-pound shelters command premium compensation in a shallow labor pool.
- Multi-standard certification overlap:Brands selling into both California and New York must navigate divergent state-level fire-retardant specifications for synthetic insulation.
- Supply chain reconfiguration friction:Shifting tent production from coastal China to Vietnam or India requires rebuilding dye-house and coating-facility relationships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Camping Equipment and Furniture Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tents, Sleeping Bags, Camping Chairs, Portable Stoves End User: Outdoor Enthusiasts, Families, Backpackers, Campgrounds Material: Polyester, Nylon, Aluminum, Wood Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Wholesale |
| Companies Covered | The Coleman Company, Inc., Johnson Outdoor Inc., Newell Brands, Oase Outdoors ApS, Nemo Equipment, Inc., ALPS Mountaineering, Helinox, Thule Group, Big Agnes Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Camping Equipment and Furniture Market Trends and Innovations
Automation in fabric manufacturing and regulatory pressure on chemical treatments are converging to reshape how camping equipment is engineered, sourced, and certified across price tiers.
Robotic cutting and seam-taping systems are automating the production of complex tent geometries that previously required skilled manual assembly. Specialty backpacking brands with limited production runs are adopting these systems fastest, compressing lead times from prototype to market-ready shelter from months to weeks. This automation is automating the traditional trade-off between customization scale and unit economics.
REACH restrictions on perfluorinated durable water repellents are eliminating long-dominant C8 and C6 chemistry from tent and rainfly production. Manufacturers are responding with hybrid silicone-polyurethane coatings that sacrifice some oil resistance for regulatory compliance. European-sourced fabrics are experiencing the most acute reformulation pressure, with certification timelines extending six to eighteen months for new chemistry validation.
Direct-to-consumer pre-order campaigns are displacing traditional seasonal wholesale commitments for emerging ultralight brands. Crowdfunding platforms enable inventory-free production planning, with backers accepting delivery windows stretching six to twelve months. This model concentrates in the United States and Germany, where digitally native outdoor enthusiasts tolerate extended fulfillment in exchange for specification input and early-access pricing.
Camping Equipment and Furniture Market Segmentation
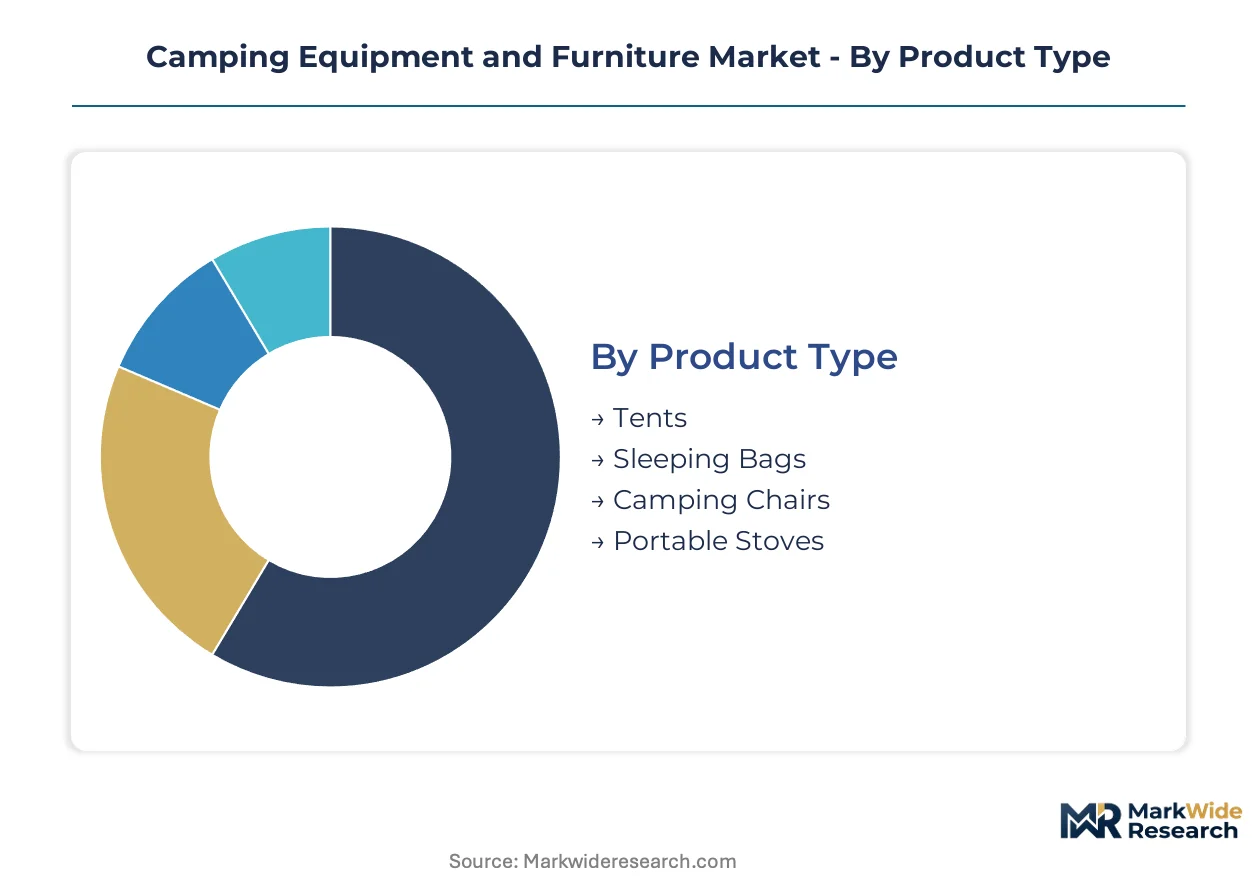
Segmentation in camping equipment reveals how divergent use cases—family car camping versus alpine thru-hiking—demand incompatible engineering priorities. Manufacturers must choose which technical trade-offs to optimize, as no single configuration serves all buyer types profitably.
Product Type:
Buyers differentiate primarily by portability requirements and weather exposure duration, not price alone.
- Tents:Ripstop polyester or silicone-coated nylon shelters with hydrostatic head ratings exceeding 1200mm command the largest revenue pool. Families in the United States prioritize quick-pitch architecture for weekend campground stays, while dispersed camping permit expansion extends demand beyond designated infrastructure.
- Portable Stoves:Compact burners optimized for dehydrated meal pouch dimensions represent the category expanding most quickly. Backcountry cooking adoption among time-constrained outdoor enthusiasts drives attach-rate growth with shelter purchases.
- Sleeping Bags:Insulation systems using down-alternative synthetic fills from recycled polyester are displacing traditional goose down, compressing margin pools for premium suppliers.
- Camping Chairs:Aluminum-framed seating sustains margin concentration in specialty retail where weight-to-durability ratios justify premium positioning above steel or wood alternatives.
Tents lead volumes today; portable stoves are gaining share fastest.
End User:
Volume concentration varies sharply by trip duration and gear mobility requirements.
- Families:Car-camping households purchasing weatherproof living space through big-box retail partnerships. Weekend trip frequency and national park visitation growth in the United States anchor this segment's scale.
- Backpackers:Alpine and thru-hiking communities pulling demand toward sub-kilogram shelter systems and collapsible furniture. REACH chemical compliance in Europe is tightening material specifications for this technical buyer group.
- Outdoor Enthusiasts:Broad-day-use campers prioritizing versatility across casual overnight scenarios.
- Campgrounds:Commercial operators sourcing durable inventory for rental programs and guest amenities.
Families dominate current revenue; backpackers show the steepest expansion trajectory.
Material:
Regulatory pressure on chemical treatments is reshaping sourcing decisions across price tiers.
- Polyester:Dominant tent body fabric for family camping applications. REACH restrictions on perfluorinated durable water repellents are forcing wholesale reformulation of coatings, compressing supplier margins.
- Nylon:Premium silicone-coated variants preferred by ultralight specialists. Fabric mills are retooling production lines to eliminate perfluorinated compounds ahead of regulatory deadlines.
- Aluminum:DAC pole technology anchors ultralight furniture differentiation, though supply concentrates among Japanese and Korean specialty extruders creating single-source vulnerability.
- Wood:Limited to glamping and base-camp aesthetics where weight constraints are absent.
Polyester leads installed base; nylon is climbing the fastest among technical buyers.
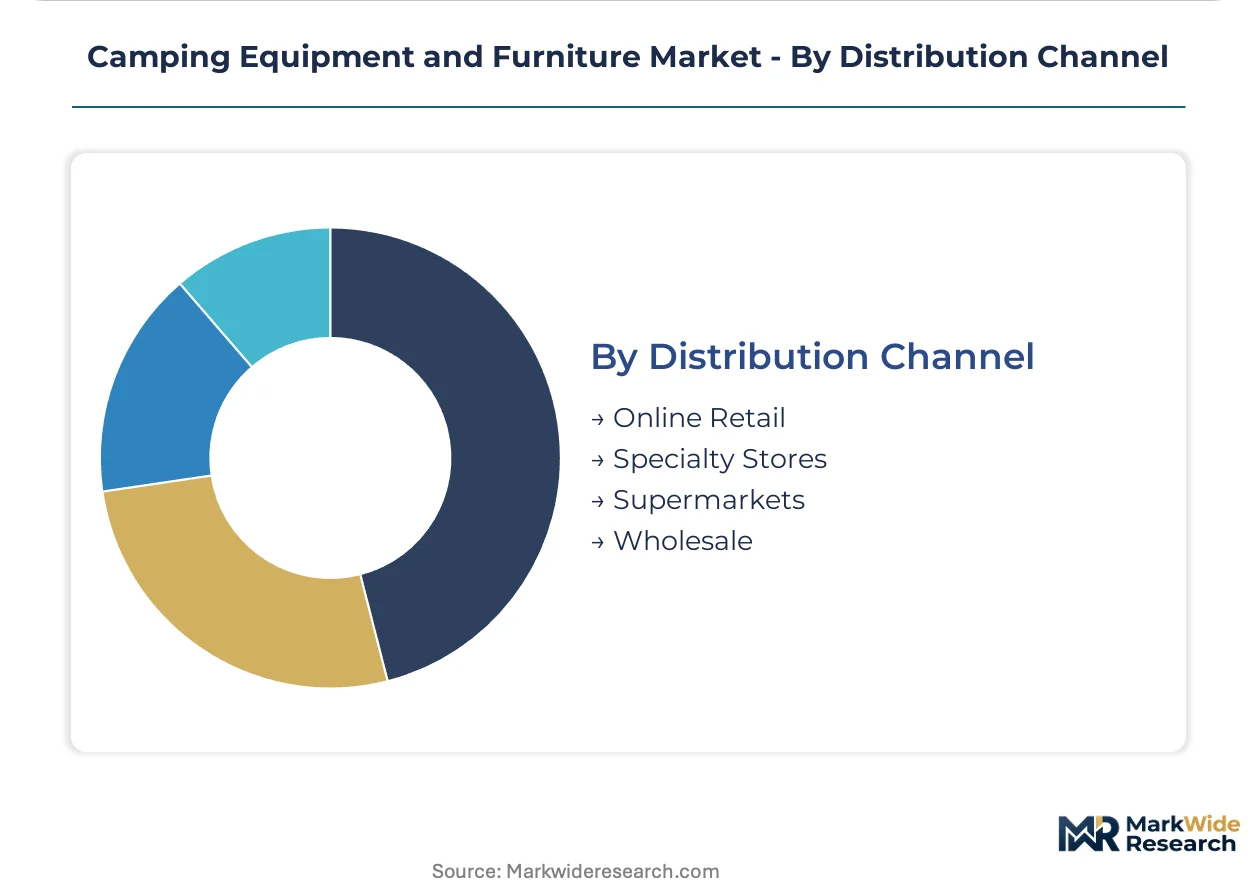
Distribution Channel:
Channel selection determines margin structure and inventory risk allocation.
- Specialty Stores:Premium backpacking shelters engineered for alpine conditions anchor Johnson Outdoor Inc.'s positioning. Technical staff expertise justifies higher price points through specification guidance.
- Online Retail:Direct-to-consumer pre-order campaigns displace traditional seasonal wholesale commitments. Crowdfunding platforms enable inventory-free production planning with six-to-twelve month fulfillment windows.
- Supermarkets:Mass-market family camping volume dominated by Coleman Company, Inc. through big-box retail partnerships.
- Wholesale:Bulk procurement by campground operators and rental programs seeking durable commercial-grade specifications.
Specialty stores capture the highest margins; online retail is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mass-market camping equipment manufacturing scaled in the United States during the post-war recreational boom, then fragmented across Asian production bases as lightweight technical gear gained priority.
United States
Dispersed camping permit issuance across national forests and BLM lands is climbing steadily. EPA restrictions on perfluorinated compounds in durable water repellents are forcing fabric reformulation timelines. Seattle and Boulder anchor technical design clusters where pattern-makers optimize sub-two-pound shelter geometries.
Germany
Alpine hiking participation rates sustain demand for collapsible furniture and modular tent systems. REACH enforcement through ECHA is eliminating C8 and C6 chemistry from rainfly production. Munich hosts specialist retailers that anchor Johnson Outdoor Inc.'s premium positioning in the European specialty channel.
China
Domestic outdoor recreation participation is expanding beyond tier-one cities into provincial markets. GB standards and NMPA oversight on imported products create compliance layers for brands sourcing through East Asian supply chains. Yangtze River Delta fabric mills are retooling silicone-coating lines ahead of regulatory deadlines.
Japan
Thru-hiking culture on the Kumano Kodo and Nakasendo trails pulls demand toward sub-kilogram shelter systems. METI guidance on chemical safety aligns with broader Asian regulatory convergence. Osaka and Nagoya concentrate DAC aluminum pole extrusion capacity for ultralight furniture brands.
Vietnam
Factory relocation from coastal China is accelerating as brands seek tariff-advantaged production bases. The country's national standards body is developing alignment with EU chemical safety frameworks. Ho Chi Minh City industrial zones are attracting dye-house and coating-facility investment from relocated supply chains.
Camping Equipment and Furniture Market Competitive Landscape
The competitive structure tilts toward heritage mass-market manufacturers with big-box retail scale. Three tiers have hardened: volume-driven family camping suppliers, technical alpine specialists, and direct-to-consumer ultralight insurgents. Capacity expansion and strategic partnerships dominate competitive moves, with brands seeking dye-house relationships in Vietnam and India to replace Chinese coastal dependency.
Within the heritage tier, The Coleman Company, Inc. and Johnson Outdoor Inc. exemplify divergent scale strategies—one leveraging mass-production infrastructure through supermarket channels, the other anchoring specialty retail with premium positioning. Helinox occupies a distinct position as an ultralight specialist. Newell Brands and Thule Group represent diversified conglomerate approaches, while Oase Outdoors ApS, Nemo Equipment, Inc., ALPS Mountaineering, and Big Agnes Inc. sit within the technical specialist archetype.
| Leading Market Players |
|---|
| The Coleman Company, Inc. |
| Johnson Outdoor Inc. |
| Newell Brands |
| Oase Outdoors ApS |
| Nemo Equipment, Inc. |
| ALPS Mountaineering |
| Helinox |
| Thule Group |
| Big Agnes Inc. |
| Others |
Pricing and Supply Chain Analysis
REACH-mandated silicone-coating migration in Europe is forcing fabric mills to absorb reformulation costs and extend certification timelines, which compresses supplier margins while creating first-mover premiums for brands with compliant alternatives already scaled.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates ultralight backpacking specialists from family camping mass-market suppliers and entry-level private-label importers. Price differentiation hinges on hydrostatic head certification tiers and DAC aluminum pole sourcing for weight-to-durability ratios. Cost compression in the standard tier is intensifying because polyester fabric mills face overlapping REACH compliance and dye-house relocation expenses. Family car-camping buyers through supermarket channels exhibit highest price sensitivity, while alpine thru-hikers purchasing through specialty retail tolerate premium positioning for sub-kilogram specifications.
Supply Chain Analysis
Technical pattern-making talent scarcity in Vietnam and Ho Chi Minh City industrial zones is constraining how quickly relocated dye-house operations can rebuild coating-facility relationships previously concentrated in coastal China. Manufacturing draws from Yangtze River Delta fabric mills, Osaka and Nagoya DAC aluminum extrusion capacity, and emerging Vietnamese coating facilities. Single-source vulnerability concentrates in Japanese and Korean specialty pole extruders. Distribution runs through big-box retail partnerships for family volume, specialty channels for technical gear, and direct-to-consumer pre-order platforms for ultralight insurgents.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on silicone-coating chemistry transitions that eliminate perfluorinated compound testing burdens while commanding sustainability premiums from regulatory-sensitive European buyers.
For Market Incumbents: Anchor market position through backward integration into Vietnamese dye-house partnerships and captive DAC aluminum pole supply negotiations with Osaka extruders. Defend against direct-to-consumer ultralight insurgents by accelerating field-repairability certification under EU Green Deal extended producer responsibility frameworks. Prioritize in-house silicone-coating R&D to compress eighteen-month chemistry validation timelines. For New Entrants and Emerging Players: REACH in Europe opens a window for silicone-polyurethane hybrid coating specialists to capture premium positioning ahead of mass-market reformulation completion. White-space concentration sits with dispersed camping permit growth in United States national forests, where sub-kilogram shelter demand outpaces established brand capacity. Launch through crowdfunding platforms with six-to-twelve month fulfillment windows to validate specification input from digitally native outdoor enthusiasts before scaling production. For Investors and Strategic Acquirers: Asymmetric upside sits with technical pattern-making studios capable of optimizing seam taping and guy-out geometry for sub-two-pound shelters, as this labor pool remains shallow relative to expanding ultralight demand. Long-term viability favors acquisition targets with established Vietnamese manufacturing relationships and EU take-back program infrastructure already operational. Watch for inflection when California and New York fire-retardant specification divergence forces dual-sku inventory strategies that favor agile mid-cap specialists over mass-market incumbents.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Vietnamese Coating Facilities | Cuts REACH compliance lag by rebuilding dye-house relationships outside tariff-exposed coastal China. |
| Silicone-Polyurethane Hybrid R&D Investment | Accelerates eighteen-month chemistry validation timelines ahead of perfluorinated compound bans. |
| EU Green Deal Take-Back Program Launch | Captures extended producer responsibility premiums through field-repairable modular architecture. |
| Direct-to-Consumer Pre-Order Platform Buildout | Eliminates inventory risk via crowdfunding with specification input from alpine thru-hiking communities. |
| Pattern-Making Talent Acquisition in Seattle and Boulder | Secures scarce technical designers optimizing sub-two-pound shelter geometries for premium positioning. |
Research Methodology
Multiple input streams — primary interviews with brand product directors and fabric mill procurement leads, secondary validation through customs records and outdoor industry association filings, and technical specification database analysis — were reconciled through bottom-up and top-down triangulation. Stakeholder consultations included category buyers at specialty retail chains, pattern-making studio operators, and regulatory affairs specialists navigating REACH and EPA perfluorinated compound restrictions. Secondary sources encompassed ECHA substance registration data, United States Forest Service dispersed camping permit issuance records, and SEC 10-K disclosures from publicly traded outdoor equipment conglomerates.
Historical shipment volumes from fabric mills and aluminum extruders were cross-referenced against panel input from brand supply chain executives to construct analytical framework projections. Segmentation dimensions modeled include product type, end-user mobility requirements, material chemistry tiers, and distribution channel margin structures. CAGRs were derived from trend extrapolation of national park visitation patterns and regulatory deadline phasing across the projection horizon. Forecast inputs incorporated silicone-coating adoption curves and DAC aluminum pole supply constraints specific to ultralight furniture manufacturing.
Revisions become necessary when REACH enforcement timelines accelerate, California fire-retardant specifications diverge from New York frameworks, or Vietnamese dye-house capacity expansion stalls. Forecasts reflect assumptions about regulatory stability and supply chain relocation momentum. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor Gear
Mexico Camping Equipment Market
Outdoor Gear
Hiking Backpack Water Filters Market
Outdoor Gear
New Zealand Camping Equipment Market
Outdoor Gear
Germany Camping Equipment Market
Outdoor Gear
Campsite Cooking Gears Market
Outdoor Gear
Camping Cooler Market
Outdoor Gear
Rechargeable Camping Gear Market
Outdoor Gear
China Camping Equipment Market
Outdoor Gear
Japan Camping Tent Market
Outdoor Gear
Diving Regulator Market
Outdoor Gear
Fairway Mowers Market
Outdoor Gear
Camp Fire Tripod Market
Outdoor Gear
Trail Running Bags Market
Outdoor Gear
UK Camping Equipment Market
Outdoor Gear
Europe Camping Equipment Market
Outdoor Gear
Bicycle Bags and Bag Packs Market