
 Deer Hunting Blinds Market | 2026-2036
Deer Hunting Blinds Market Size, Share, and Industry Trends Forecast 2026-2036
Deer Hunting Blinds Market Outlook
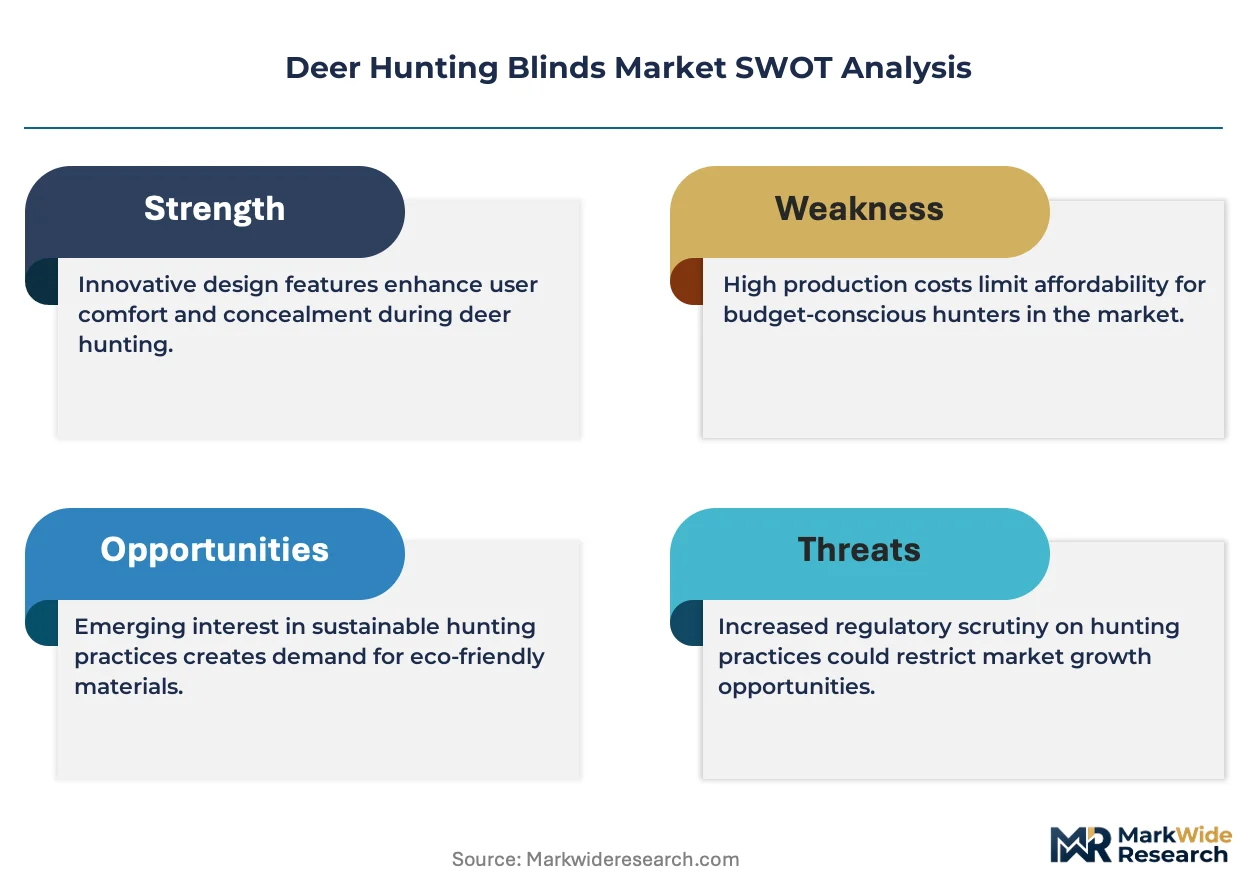
Lease-to-own and asset-light distribution models is tilting competitive dynamics toward operators with flexible capital structures. Shadow Hunter Blinds by Summit Outdoors leverages captive retail networks to control shelf placement. Hughes Products anchors its position through specialized fabrication capacity in the Midwest. Redneck Blinds differentiates via premium fixed-blind engineering for lease-managed hunting properties.
Deer hunting blinds are enclosed or semi-enclosed structures engineered to conceal hunters from wildlife, typically fabricated from weather-treated wood, extruded aluminum, or synthetic fabrics with scent-containment liners and ballistic-rated viewing windows. Box blinds dominate commercial volume due to year-round durability on leased land, while portable blinds capture fastest growth among transient hunters prioritizing packability. Fabric-based ground blinds concentrate margin pools in the camouflage-design segment where pattern licensing creates pricing power.
The US Fish and Wildlife Service coordinates with state departments of natural resources to enforce season dates and blind-placement setbacks near waterways. OSHA guidelines for elevated platforms influence ladder-blind engineering standards, while EPA treatment regulations govern preservative chemicals in wooden structures. Stakeholders must track evolving state-level lease regulations and platform-safety mandates that will determine which material and design configurations retain market access.
Market Dynamics
Lease-to-own distribution models are compressing working-capital cycles across the deer hunting blinds supply base, forcing fabricators to restructure balance sheets around recurring revenue streams rather than one-time equipment sales.
Growth Catalysts
- Wildlife Management Agency Procurement:State departments of natural resources in Texas, Michigan, and Wisconsin are expanding blind placement programs on public hunting lands, creating institutional demand for weather-treated box structures.
- OSHA Platform Safety Standards:Elevated blind engineering now incorporates ladder-guard railings and load-rated platforms, opening compliance-driven replacement cycles for aging wooden installations.
- Polymer Composite Maturation:Rotomolded polyethylene shells are displacing traditional wood framing in commercial lease operations, extending service intervals and reducing seasonal maintenance labor.
Market Restraints
- Aluminum Extrusion Cost Volatility:Frame fabricators face margin compression from Midwest smelter capacity constraints and energy-price pass-throughs in primary metal supply.
- EPA Preservative Chemical Restrictions:Chromated copper arsenate treatment bans have forced wooden blind manufacturers toward alternative rot inhibitors with shorter proven-field lifespans.
- Ground Blind Substitution:Lightweight fabric shelters with carbon-fiber hubs are capturing transient hunter preference, eroding entry-level rigid-structure demand.
Strategic Opportunities
- Lease-Managed Property Premiumization:High-fence hunting operations in Texas and Oklahoma are specifying climate-controlled blinds with HVAC integration, expanding addressable spend per unit.
- Camouflage Pattern Licensing:Exclusive Realtree and Mossy Oak sub-licenses are creating pricing power in fabric ground blind segments where visual differentiation drives purchase decisions.
- USDA Rural Development Financing:Farm Bill conservation program eligibility is expanding hunter-access infrastructure grants, subsidizing landowner blind purchases on agricultural acreage.
Industry Challenges
- Welding Certification Bottlenecks:Aluminum tower blind fabricators face six-month lead times for AWS D1.2-certified structural welders, constraining production scaling.
- Scent-Containment Liner Integration:Bonding activated-carbon fabrics to polymer shells without delamination requires process engineering expertise that remains concentrated among a handful of Midwest converters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Deer Hunting Blinds Market |
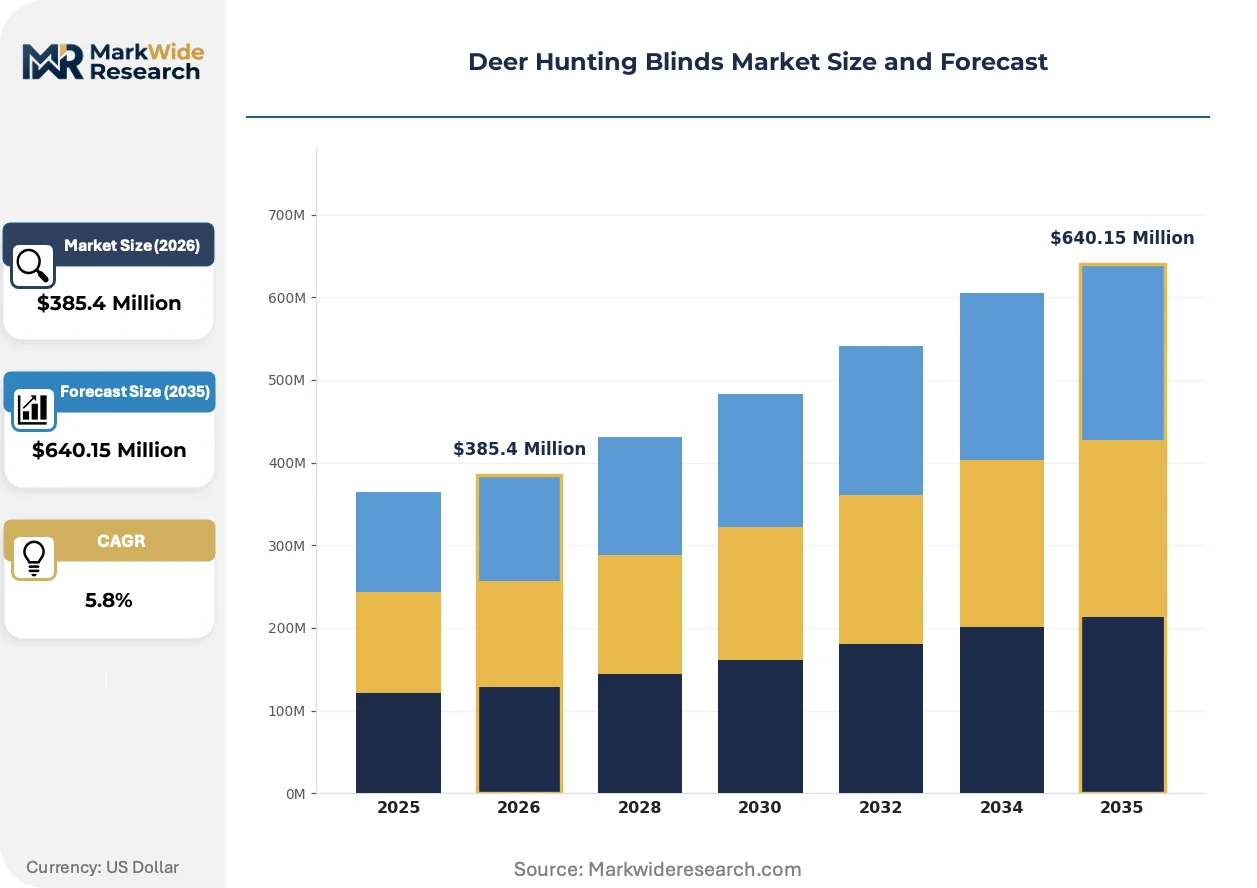
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $640.15 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Box Blinds, Ladder Blinds, Portable Blinds, Ground Blinds Material: Wood, Aluminum, Fabric, Plastic Design: Pop-Up, Fixed, Camouflage, Transparent Size: Single Person, Two-Person, Family Size, Large Group |
| Companies Covered | Shadow Hunter Blinds by Summit Outdoors, Hughes Products, Redneck Blinds, Muddy Outdoors, Barronett Blinds, Primos Hunting, FBi Buildings, Monarch Hunting Products, Game Winner, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Deer Hunting Blinds Market Strategic Shifts
Material science advances and regulatory safety mandates are converging to redefine durability expectations and distribution economics across the deer hunting blinds category.
Rotomolded polymer construction is hybridizing with integrated insulation cores to create thermally stable hunting environments that extend effective season length. Commercial lease operators in northern tier states are adopting these hybrid structures at twice the rate of traditional wood-framed alternatives. The technology is hybridizing product categories by collapsing the distinction between permanent box blinds and seasonal shelters.
OSHA elevated-platform guidelines are mandating load-rated ladder systems and fall-arrest anchor points on all commercial installations above six feet. Fabricators are redesigning tower geometries to accommodate integrated safety rails without compromising sight-line angles. Elevated blind segments in Wisconsin and Michigan are responding fastest, with state natural resource departments incorporating OSHA language into public-land lease specifications.
Recreational hunters are consolidating purchases through cooperative buying groups that aggregate demand across multiple lease members. These collectives are displacing traditional retail channel relationships by negotiating direct mill pricing on volume orders. The pattern concentrates in Texas Hill Country and Michigan Lower Peninsula counties where lease density supports group formation.
Deer Hunting Blinds Market Segmentation
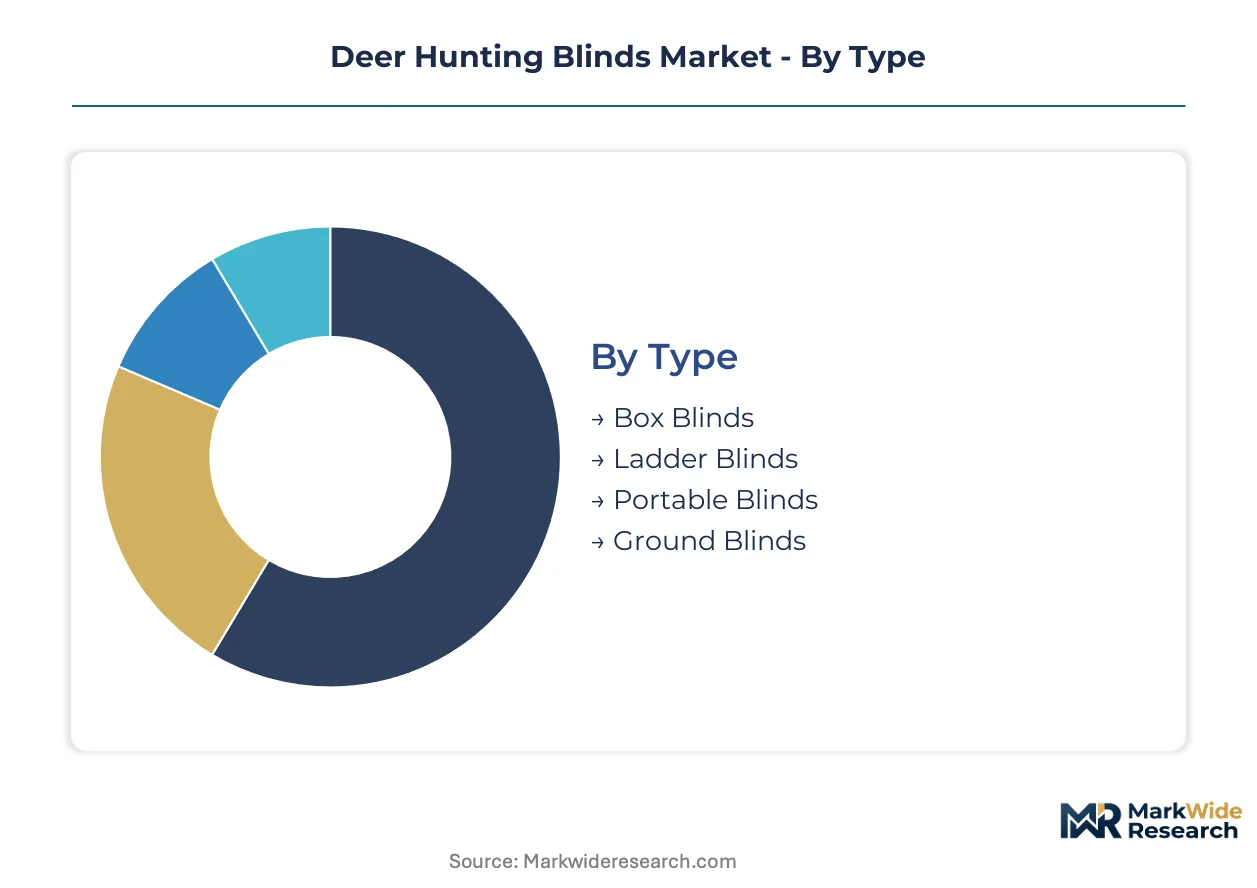
Deer hunting blinds fragment across four distinct classification axes that govern procurement patterns and margin structures. Type and material configurations dominate commercial lease economics, while design and size specifications track hunter demographics and property management models.
Type:
Application context—permanent lease installations versus transient mobility—determines structural choice and capital deployment intensity.
- Box Blinds:Enclosed weather-treated structures with ballistic-rated windows and scent-containment liners anchor commercial lease operations. Texas and Wisconsin wildlife management agencies specify these for public land programs where durability reduces seasonal maintenance labor.
- Ladder Blinds:Elevated platforms with integrated ladder systems incorporate OSHA-mandated guard railings and load-rated anchor points. Michigan state natural resource departments now require these safety features in public-land lease specifications, driving compliance replacement cycles.
- Portable Blinds:Collapsible aluminum or polymer structures prioritize packability for transient hunters.
- Ground Blinds:Low-profile fabric shelters dominate entry-level recreational segments.
Box blinds command the established base. The steepest expansion runs through portable configurations.
Material:
Cost tier and service interval expectations reshape material selection across lease-managed versus owner-operated properties.
- Wood:Traditional pressure-treated framing faces EPA preservative restrictions that shorten proven-field lifespans. Alternative rot inhibitors now dominate wooden blind fabrication, though performance uncertainty constrains commercial lease adoption.
- Aluminum:Extruded frame construction delivers structural longevity but faces margin compression from Midwest smelter capacity constraints and energy-price volatility in primary metal supply.
- Fabric:Synthetic camouflage patterns with carbon-fiber hubs capture transient hunter preference.
- Plastic:Rotomolded polyethylene shells displace wood framing in northern tier commercial operations.
Wood retains legacy installed base. Plastic configurations gain share fastest in lease-managed properties.
Design:
Visual concealment technology and deployment speed differentiate product tiers across recreational and institutional buyer segments.
- Pop-Up:Spring-tensioned hub systems enable sub-minute deployment for mobile hunters. Carbon-fiber frame variants concentrate in Texas Hill Country cooperative buying groups where lease members prioritize rapid repositioning.
- Fixed:Permanent anchored structures with integrated platforms dominate high-fence hunting operations in Oklahoma and Texas.
- Camouflage:Exclusive Realtree and Mossy Oak pattern licensing creates pricing power.
- Transparent:Ballistic-rated polycarbonate viewing panels with one-way visibility properties.
Fixed designs anchor commercial revenue. Pop-up configurations climb the fastest among transient recreational hunters.
Size:
Hunter party composition and property lease economics drive capacity specification across single-occupancy through group configurations.
- Single Person:Compact footprints minimize disturbance zones on limited-acreage leases. Wisconsin and Michigan private landowners favor these for solo bow hunting where scent control and thermal management take priority over capacity.
- Two-Person:Paired seating with independent shooting lanes supports mentor-youth hunting programs. USDA Rural Development financing eligibility is expanding infrastructure grants that subsidize these configurations on agricultural acreage.
- Family Size:Extended capacity with climate stabilization for multi-generational hunting parties.
- Large Group:Commercial lodge specifications with HVAC integration for premium lease operations.
Two-person units anchor volume demand. Large group configurations expand most quickly in premium Texas and Oklahoma lease properties.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States runs a substantial trade surplus in deer hunting blinds, exporting rotomolded polymer structures to Canada and Australia while importing minimal volumes of fabric ground blinds from Asian contract manufacturers. Export flows concentrate through Gulf Coast ports serving Australian recreational hunting cooperatives.
United States
Texas, Michigan, and Wisconsin hunting corridors generate concentrated demand for box blinds and elevated ladder structures. USDA Rural Development financing under the Farm Bill conservation program subsidizes landowner blind purchases on agricultural acreage. Fabrication clusters in the Midwest supply rotomolded polyethylene shells to commercial lease operators extending service intervals.
Canada
Provincial wildlife agencies in Ontario and Alberta procure weather-treated box blinds for public land hunting programs. Health Canada/PMRA regulates preservative chemicals in wooden structures entering the Canadian market. Quebec-based distributors import US-manufactured polymer blinds for lease-managed properties in the Eastern Townships.
Australia
Recreational hunting cooperatives in New South Wales and Victoria aggregate demand for portable ground blinds suited to transient sambar deer hunters. The Therapeutic Goods Administration does not regulate hunting equipment, leaving state environmental agencies to manage blind placement near waterways. Import volumes from US manufacturers climb through Melbourne and Sydney distribution hubs.
Germany
Forest management cooperatives in Bavaria and Baden-Württemberg specify elevated hunting stands with OSHA-equivalent platform safety standards. REACH regulations govern chemical treatments in wooden blind imports from Eastern European suppliers. Stuttgart-area fabricators produce aluminum frame components for domestic high-seat installations.
United Kingdom
Deer management trusts in Scotland and England deploy box blinds for cull operations on estate lands. The Health and Safety Executive mandates load-rated platforms on commercial elevated structures. Midlands-based metalworkers supply aluminum tower components to Irish and Nordic export markets.
Deer Hunting Blinds Market Competitive Environment
On the supply side, the industry is moderately consolidated around regional fabricators with captive fabrication capacity and specialized distribution relationships. Tier-one operators control polymer rotomolding and aluminum extrusion capabilities, while tier-two players concentrate in fabric ground blind assembly and pattern licensing. Three archetypes dominate: vertically integrated manufacturers with in-house polymer molding, regional metal fabricators with AWS-certified welding capacity, and brand licensors outsourcing production to Asian contract manufacturers. Competitive moves center on lease-to-own distribution restructuring and exclusive camouflage pattern sub-licensing to capture pricing power in fabric segments.
Among US-based operators, Shadow Hunter Blinds by Summit Outdoors exemplifies the captive retail network archetype, Hughes Products occupies a position anchored in Midwest fabrication capacity, and Redneck Blinds represents premium fixed-blind engineering for lease-managed properties. These three fabricators illustrate how control over distribution channels, regional production infrastructure, and specialized product configurations shapes competitive positioning without requiring uniform scale or vertical scope.
| Leading Market Players |
|---|
| Shadow Hunter Blinds by Summit Outdoors |
| Hughes Products |
| Redneck Blinds |
| Muddy Outdoors |
| Barronett Blinds |
| Primos Hunting |
| FBi Buildings |
| Monarch Hunting Products |
| Game Winner |
| Others |
Value Chain & Pricing Dynamics
Midwest fabrication clusters around Ohio and Indiana polymer rotomolding capacity dictate pricing power for commercial lease operators seeking extended-service-interval box blinds. The concentration of AWS-certified aluminum welding expertise in Michigan and Wisconsin creates regional cost premiums for elevated ladder structures, while Asian contract manufacturers of fabric ground blinds compress entry-level pricing through scale economies.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on certification grade—OSHA-compliant elevated platforms command substantial premiums over residential-grade alternatives—and volume scale through cooperative buying groups in Texas Hill Country. Pricing pressure stems from aluminum extrusion cost volatility as Midwest smelter capacity constraints pass through energy-price surcharges. Transient recreational hunters exhibit highest price sensitivity, while high-fence lease operators in Oklahoma demonstrate lowest sensitivity due to HVAC-integrated climate control specifications.
Supply Chain Analysis
Asian contract manufacturers in Vietnam and Bangladesh concentrate fabric ground blind assembly capacity for North American brand licensors. Raw material dependencies include rotomolded polyethylene resin from Gulf Coast petrochemical complexes, carbon-fiber hub components from Chinese suppliers, and ballistic-rated polycarbonate from German optical-grade manufacturers. Supply chain risk centers on single-source vulnerability for AWS D1.2-certified structural welders constraining aluminum tower blind scaling. Distribution runs through captive retail networks, direct mill relationships with cooperative buying groups, and USDA Rural Development financing channels subsidizing agricultural landowner purchases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a service-attach opportunity where seasonal maintenance contracts and scent-containment liner replacement programs expand faster than hardware unit sales. Lease-to-own distribution restructuring creates recurring revenue streams that outperform transactional equipment margins.
For Market Incumbents: Pre-empt ground blind substitution threats by integrating rotomolded polymer shells with modular scent-containment systems that shorten replacement cycles. Capture AWS-certified welding capacity in Michigan through apprenticeship pipeline investments before competitors lock in labor. Deepen backward integration into polymer resin sourcing to insulate margins from Gulf Coast petrochemical volatility. For New Entrants and Emerging Players: Build out portable blind configurations for Australian recreational hunting cooperatives importing through Melbourne distribution hubs, where US trade surplus positioning creates favorable landed cost structures. Target USDA Rural Development financing eligibility as the most penetrable procurement channel, embedding Farm Bill conservation program compliance into product specifications from design phase. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because regional fabrication capacity scarcity—particularly AWS D1.2-certified welding and activated-carbon bonding expertise—will drive roll-up economics for Midwest metalworkers and polymer converters. Monitor state natural resource department procurement specifications as the critical inflection signal; OSHA platform safety language adoption into public-land lease requirements accelerates compliance-driven replacement demand.| Strategic Initiative | Industry Significance |
|---|---|
| Lease-to-Own Distribution Restructuring | Converts one-time equipment sales into recurring revenue streams with superior working-capital efficiency. |
| AWS D1.2 Welding Certification Investment | Resolves six-month lead times constraining aluminum tower blind production scaling in Michigan. |
| Realtree/Mossy Oak Exclusive Sub-Licensing | Captures pricing power in fabric ground blind segments where visual differentiation drives purchase decisions. |
| Rotomolded Polymer Shell Integration | Displaces wood framing in northern tier commercial operations, extending service intervals and reducing maintenance labor. |
| USDA Rural Development Financing Alignment | Unlocks Farm Bill conservation program subsidies for landowner blind purchases on agricultural acreage. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with wildlife management agency procurement officers, commercial lease property managers, AWS-certified welding supervisors, polymer rotomolding plant engineers, and cooperative buying group organizers. Secondary validation drew from US Fish and Wildlife Service season regulation filings, OSHA elevated platform safety guidelines, EPA preservative chemical restriction notices, USDA Rural Development program eligibility databases, and state natural resource department lease specifications. Bottom-up demand aggregation across hunter demographics and property management models was triangulated against top-down supply capacity assessments for Midwest fabrication clusters.
Calibration against historical seasonality patterns and regulatory implementation timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include blind type, material composition, design configuration, size capacity, and regional hunting corridor density. CAGRs were derived through regression analysis of procurement volume trends correlated with wildlife agency budget appropriations and lease property expansion rates. Industry-specific forecast inputs incorporated aluminum extrusion cost indices from Midwest smelter capacity utilization and polymer resin pricing from Gulf Coast petrochemical production data.
Practitioners should monitor state-level OSHA platform safety mandate adoption and EPA alternative rot inhibitor performance field data for early signals of material substitution acceleration. Forecasts reflect assumptions regarding sustained recreational hunter participation rates and continued Farm Bill conservation program funding authorization. Quarterly review of wildlife management agency procurement specifications and aluminum welding certification pipeline outputs is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor Gear
Wheeled Insulated Cooler Market
Outdoor Gear
Germany Camping Equipment Market
Outdoor Gear
Canoe Paddles Market
Outdoor Gear
Mexico Camping Equipment Market
Outdoor Gear
Diving Equipment Market
Outdoor Gear
Spain Camping Equipment Market
Outdoor Gear
Global Automatic Mower Market
Outdoor Gear
North America Robotic Lawn Mower Market
Outdoor Gear
Picnic Coolers Market
Outdoor Gear
Artificial Grass Turf Market
Outdoor Gear
Camp Fire Tripod Market
Outdoor Gear
Trail Running Bags Market
Outdoor Gear
Rechargeable Camping Gear Market
Outdoor Gear
North America and Europe Leaf Blower Market
Outdoor Gear
Hiking Backpack Water Filters Market
Outdoor Gear
UK Camping Equipment Market