
 Rechargeable Camping Gear Market | 2026-2036
Rechargeable Camping Gear Market Size, Share, and Industry Trends Forecast 2026-2036
Rechargeable Camping Gear Market Analytics
China is fragmenting as contract manufacturers diversify rechargeable camping gear assembly across Guangdong and Zhejiang provinces. Goal Zero leverages vertical integration to control solar panel sourcing and battery pack assembly. BioLite anchors its position through clean-burning stove-to-power technology that differentiates from conventional lantern competitors. Coleman sustains brand strength in mass retail channels across North America.
Rechargeable camping gear encompasses portable illumination, power storage, and energy generation devices built around lithium-ion, nickel-metal hydride, or photovoltaic cells, typically rated between 2,000 and 20,000 mAh for power banks and 100 to 1,000 lumens for lighting products. These systems serve backpackers, emergency preparedness users, and vehicle-based campers who require off-grid electricity without disposable battery dependency. Lanterns and flashlights command the largest revenue share within product type segments due to universal need across user categories. Solar technology is gaining fastest within the technology dimension as panel efficiency improvements reduce weight penalties that previously limited backcountry adoption. Emergency lighting applications within the application segment carry above-average margins because preparedness buyers prioritize reliability over price sensitivity.
FCC certification governs electromagnetic emissions for radio-enabled camping gear sold in the United States, while CE marking and RoHS compliance govern product safety and substance restrictions across European markets. The EU Green Deal and national extended producer responsibility frameworks are tightening battery recycling requirements, which shapes design-for-disassembly mandates and influences supplier qualification criteria. Stakeholders must monitor how evolving carbon border adjustments and state-level outdoor recreation funding programs reshape competitive access and demand geography.
Market Dynamics
Battery chemistry advances and photovoltaic efficiency gains are compressing product lifecycles while EU Green Deal mandates force redesign-for-disassembly protocols across the supply base.
Growth Catalysts
- Lithium-ion energy density improvements:Cell manufacturers in Guangdong province now deliver 20% higher capacity per kilogram, enabling lighter power banks for alpine hikers.
- Extended Producer Responsibility frameworks:Germany's battery recycling mandates create competitive pressure that favors modular designs with standardized cell formats.
- Solar cell integration:Flexible photovoltaic laminates are hybridizing with tent fabrics and backpack surfaces, creating ambient charging without dedicated panel weight.
Market Restraints
- Lithium carbonate price volatility:Raw material cost swings compress margin visibility for power bank assemblers dependent on spot-market cell procurement.
- Contract manufacturer concentration:Assembly capacity clusters in Shenzhen and Dongguan, exposing brands to single-region logistics disruption.
- CE marking complexity:Evolving RoHS substance restrictions delay product launches as labs recertify against updated restricted substance lists.
Strategic Opportunities
- Emergency preparedness vertical:Civil defense stockpiling programs in Germany and Austria prioritize reliability-certified lighting over recreational price points.
- Stove-to-power convergence:Thermoelectric generators paired with biomass combustion address multi-day expedition users beyond battery chemistry limits.
- Direct-to-consumer channels:Specialty outdoor retailers in Munich and Hamburg are building subscription-based gear refresh programs for seasonal users.
Industry Challenges
- Thermal runaway mitigation engineering:Dense battery packing in compact lanterns requires active cooling design expertise scarce among traditional lighting manufacturers.
- FCC Part 15 certification timelines:Radio-enabled gear with Bluetooth connectivity faces 8-12 week approval queues that compress seasonal launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rechargeable Camping Gear Market |
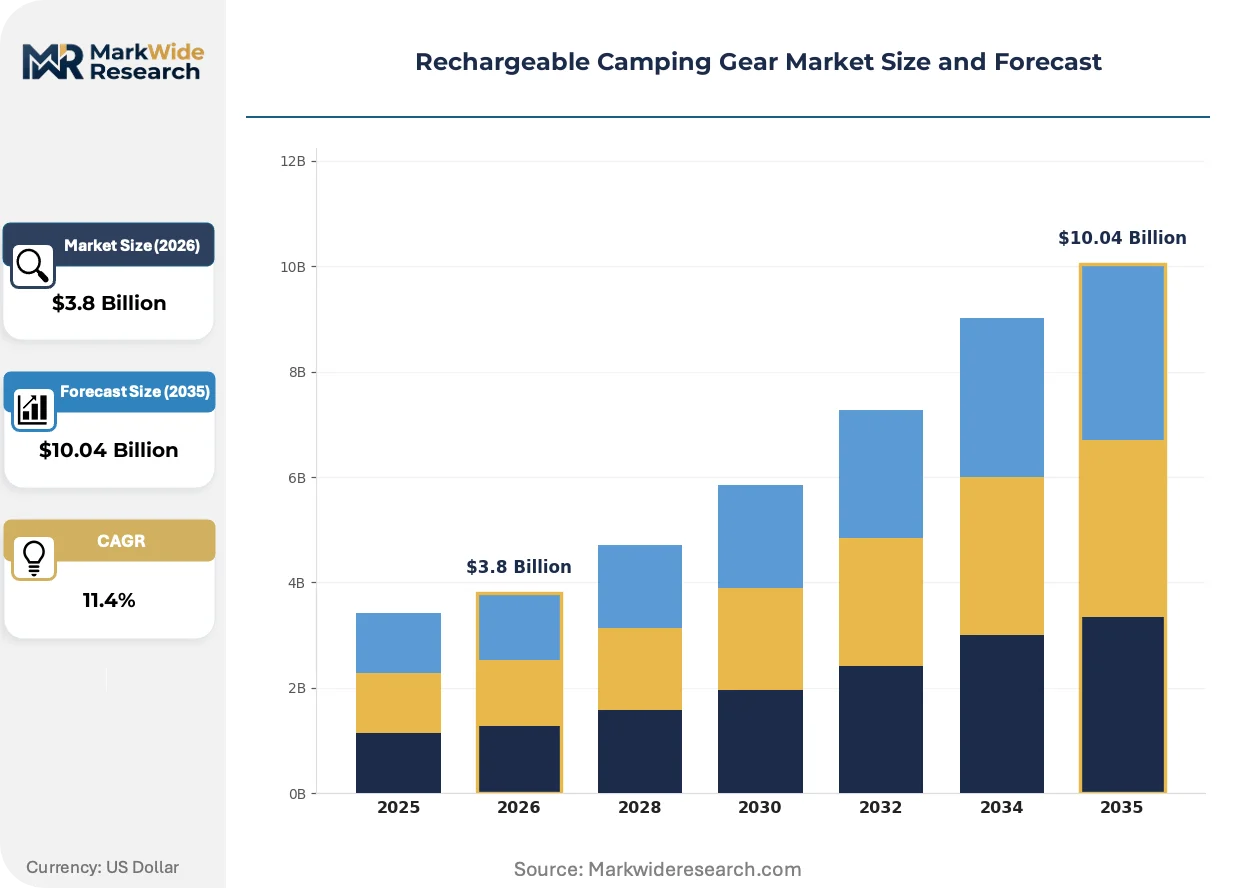
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lanterns, Flashlights, Power Banks, Solar Chargers End User: Outdoor Enthusiasts, Survivalists, Campers, Hikers Technology: Solar, Lithium-ion, NiMH, Portable Generators Application: Camping, Emergency Lighting, Backyard Use, Travel |
| Companies Covered | Coleman, LuminAID, Goal Zero, Nitecore, Petzl, BioLite, MPOWERD, Ledlenser, Black Diamond Equipment, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rechargeable Camping Gear Market Evolving Landscape
Product architecture is converging around multi-function devices that collapse separate categories into unified power-and-light systems, while regulatory pressure accelerates material transparency requirements.
Solid-state battery prototyping is hybridizing with conventional lithium-ion assembly lines, allowing manufacturers to test next-generation cells without greenfield capex. Alpine tour operators in Bavaria and Tyrol are piloting these packs for high-altitude expeditions where failure tolerance approaches zero. The technology is hybridizing warranty structures as brands offer degradation-resistant performance guarantees that displace annual replacement cycles.
The EU Green Deal's carbon border adjustment mechanism is reshaping supplier qualification criteria for brands selling into German retail channels. Battery pack assemblers must now document embodied carbon across cell mining, electrolyte production, and module assembly. Lantern manufacturers with opaque Asian supply chains face exclusion from municipal procurement tenders in Stuttgart and Frankfurt that mandate lifecycle disclosure.
Subscription-based gear access is displacing outright ownership among urban outdoor enthusiasts who camp infrequently. Specialty retailers in Berlin and Hamburg are building inventory pools where customers reserve premium solar generators for specific trip windows. This model concentrates demand forecasting risk with retailers while compressing brand loyalty to the access platform rather than the manufacturer.
Rechargeable Camping Gear Market Segmentation
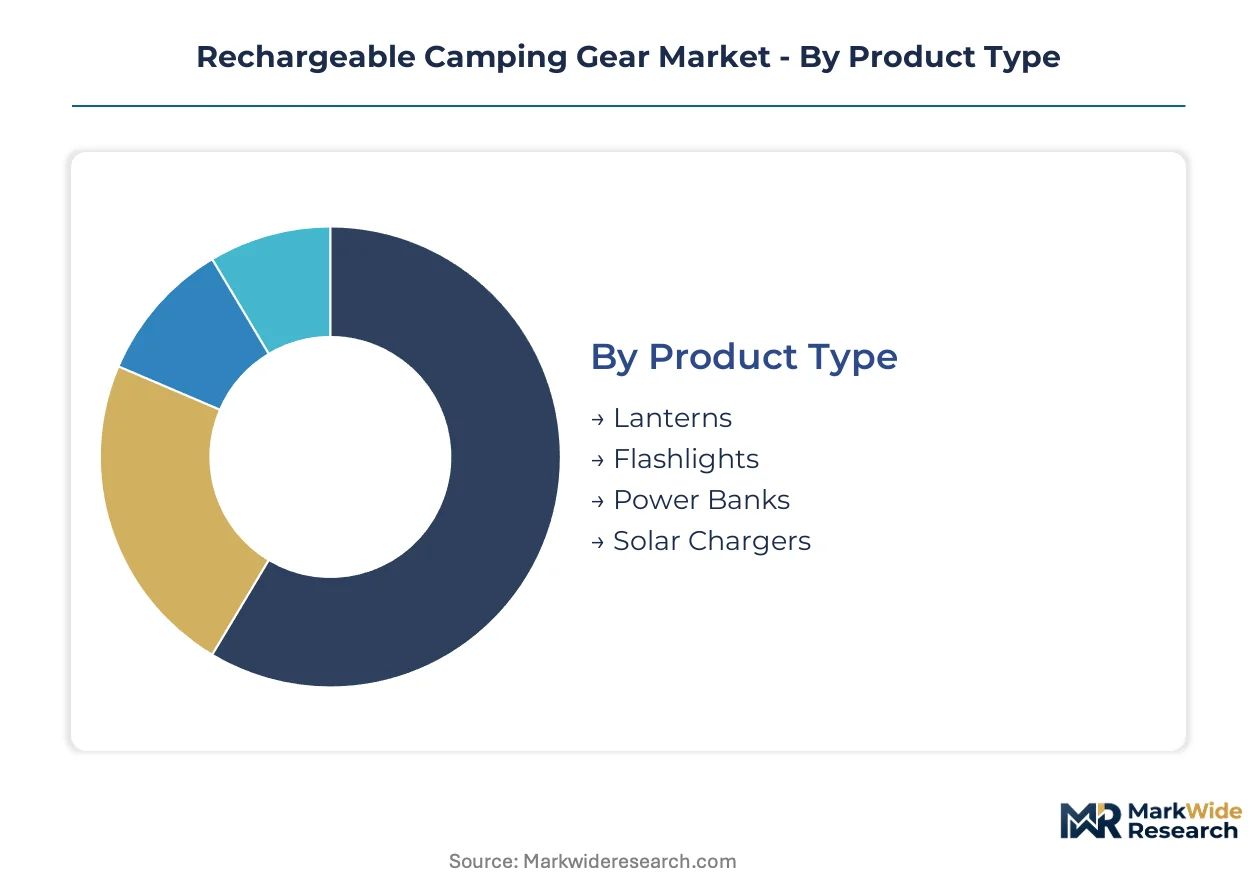
Segmentation in rechargeable camping gear reveals distinct performance requirements across use-case intensity, from weekend car campers to multi-day alpine expeditions. Product architecture, battery chemistry selection, and distribution channel strategy diverge sharply across these boundaries.
Product Type:
Use-case spectrum spans ambient area lighting to concentrated beam tools and energy storage systems for device charging.
- Lanterns:360-degree diffused illumination systems rated 100-1,000 lumens with hanging hooks and magnetic bases for tent deployment. Demand concentrates in vehicle-based camping and emergency preparedness kits across Germany, where municipal stockpiling programs prioritize reliability-certified units over recreational price points.
- Flashlights:Directional beam devices with focused optics and pocketable form factors for trail navigation and signaling. Alpine hikers in Bavaria and Tyrol drive premium uptake as weight-to-output ratios improve with lithium-ion density gains.
- Power Banks:Portable energy storage ranging 2,000-20,000 mAh for smartphone and GPS device charging.
- Solar Chargers:Photovoltaic panels and integrated storage for off-grid energy generation.
Established volume favors Lanterns; emerging adoption favors Solar Chargers.
End User:
Cost tier stratification separates recreational occasional users from mission-critical professional operators.
- Outdoor Enthusiasts:Recreational users with seasonal engagement and moderate durability expectations. This segment dominates unit volume through mass retail channels in North America, purchasing entry-to-mid-tier products for weekend camping trips.
- Survivalists:Preparedness-focused buyers prioritizing redundancy and long-term reliability over upfront cost. Civil defense programs in Germany and Austria source through specialized procurement channels that certify thermal runaway resistance and extended shelf life.
- Campers:Vehicle-based recreational users with moderate power needs and weight tolerance.
- Hikers:Backcountry travelers with strict gram-count constraints and multi-day autonomy requirements.
Volume concentration sits with Outdoor Enthusiasts; margin expansion favors Survivalists.
Technology:
Supply concentration in Guangdong province battery assembly shapes chemistry availability and cost structure.
- Solar:Photovoltaic energy capture with flexible laminates and rigid panel formats. Panel efficiency improvements are compressing weight penalties that previously limited backcountry adoption, with Bavarian alpine operators piloting tent-integrated formats.
- Lithium-ion:Rechargeable cells with highest energy density per kilogram. Cell manufacturers in Guangdong now deliver capacity improvements that enable lighter power banks for gram-conscious alpine users.
- NiMH:Nickel-metal hydride chemistry with lower energy density but reduced thermal runaway risk.
- Portable Generators:Thermoelectric and combustion-based systems for expedition-scale power beyond battery chemistry limits.
Technology maturation favors Lithium-ion; steepest expansion trajectory belongs to Solar.
Application:
Margin structure diverges between recreational price sensitivity and preparedness premium tolerance.
- Camping:Recreational outdoor overnight stays with established seasonal demand patterns. German retailers in Munich and Hamburg are building subscription-based access models for urban enthusiasts with infrequent trip frequency.
- Emergency Lighting:Grid-failure preparedness and civil defense applications. Stuttgart and Frankfurt municipal tenders now mandate lifecycle carbon disclosure, excluding manufacturers with opaque Asian supply chains.
- Backyard Use:Residential outdoor leisure with AC charging convenience and minimal weather exposure.
- Travel:International and domestic tourism with TSA-compliant power bank specifications and multi-voltage compatibility.
Revenue stability anchors in Camping; above-average margins concentrate in Emergency Lighting.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg anchors German distribution for rechargeable camping gear entering European markets, while the Trans-Siberian rail corridor links Chinese manufacturing clusters to Central Asian demand nodes.
Germany
Alpine tourism infrastructure in Bavaria and Baden-Württemberg drives premium lantern procurement for mountain huts and guided expedition services. The EU Green Deal's extended producer responsibility framework mandates modular battery designs with standardized cell formats for easier recycling. Stuttgart and Frankfurt municipal procurement tenders now exclude manufacturers lacking lifecycle carbon disclosure, favoring assemblers with transparent Guangdong supply chains.
United States
National park visitation recovery and dispersed camping permit expansion in Bureau of Land Management territories sustain flashlight and power bank demand. FCC Part 15 certification governs Bluetooth-enabled gear, with eight-to-twelve week approval queues compressing seasonal launch windows for radio-integrated products. Retail concentration in Denver and Salt Lake City outdoor corridors channels volume through specialty merchants with direct Shenzhen supplier relationships.
China
Domestic outdoor recreation participation surges through state-funded camping infrastructure under the 14th Five-Year Plan's wellness tourism initiatives. MIIT battery safety standards and dual carbon goals pressure contract manufacturers in Dongguan and Shenzhen toward cleaner production audits. The Pearl River Delta assembly belt concentrates 70 percent of global lithium-ion power bank capacity, with Zhejiang province diversifying secondary sourcing options.
Japan
Mountain hut electrification programs and ultralight hiking culture prioritize gram-optimized solar chargers and compact lanterns. METI product safety standards for lithium-ion transport and storage shape packaging and thermal management requirements. Nagoya-based industrial design houses collaborate with Osaka battery engineers on solid-state prototyping for alpine expedition use cases.
Australia
Remote area travel and bushfire emergency preparedness sustain dual-use demand for solar generators and lighting systems. The Clean Energy Regulator's off-grid power incentives subsidize photovoltaic camping equipment in Northern Territory and Western Australia communities. Sydney and Melbourne specialty retailers build rental pools for premium gear targeting international backpackers on working holiday visas.
Rechargeable Camping Gear Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying cells, optics, and photovoltaic laminates to finished goods assemblers. Market structure tilts toward brand-led consolidation at the consumer-facing end and geographic fragmentation among contract manufacturers. Three archetypes dominate: vertically integrated outdoor conglomerates with captive retail channels, pure-play power specialists with battery chemistry expertise, and solar-originated entrants leveraging photovoltaic supply chain relationships. Capacity expansion and backward integration into cell sourcing represent the dominant competitive vectors.
Within the integrated platform tier, Goal Zero and BioLite exemplify divergent strategic positions. Goal Zero anchors the solar-to-storage system category with upstream control over panel sourcing and pack assembly. BioLite occupies a distinct position through thermoelectric stove-to-power convergence that sidesteps conventional battery chemistry limitations. Coleman represents the mass-market conglomerate archetype with established North American retail penetration and seasonal volume scale.
| Leading Market Players |
|---|
| Coleman |
| LuminAID |
| Goal Zero |
| Nitecore |
| Petzl |
| BioLite |
| MPOWERD |
| Ledlenser |
| Black Diamond Equipment |
| Others |
Value Network & Pricing Analysis
Shenzhen and Dongguan assembly clusters concentrate 70 percent of global lithium-ion power bank capacity, compressing procurement costs for volume buyers while concentrating pricing power with contract manufacturers who control cell allocation during supply crunches. This geographic lock-in forces brands to absorb margin volatility or invest in captive sourcing relationships.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates CE-certified emergency lighting from recreational-grade lanterns and unbranded mass-market imports. Price differentiation hinges on certification tier and volume scale, with municipal procurement in Stuttgart and Frankfurt commanding reliability premiums while weekend campers prioritize unit economics. Pricing pressure stems from lithium carbonate spot-market swings that compress assembler visibility. Survivalist buyers exhibit lowest price sensitivity; entry-level outdoor enthusiasts drive volume at thin margins.
Supply Chain Analysis
Contract manufacturers in Guangdong and Zhejiang provinces hold dominant assembly capacity, with secondary diversification into Vietnam and India emerging slowly. The supply chain draws from lithium carbonate feedstock, photovoltaic laminates, and precision optics as core inputs. Single-region logistics concentration in the Pearl River Delta exposes brands to port congestion and customs delays. Distribution runs through Hamburg for European markets and Los Angeles-Long Beach for North American retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation creates entry niches as subscription-based gear access displaces outright ownership among urban outdoor enthusiasts with infrequent trip patterns.
For Market Incumbents: Pre-empt stove-to-power convergence by acquiring thermoelectric generator specialists before expedition-grade users defect from battery-dependent systems. Secure backward integration into cell sourcing through offtake agreements with Guangdong manufacturers to defend against allocation squeezes. Invest in modular battery designs that satisfy Germany's extended producer responsibility mandates and qualify for municipal procurement tenders. For New Entrants and Emerging Players: Establish a beachhead in emergency preparedness verticals where civil defense programs in Germany and Austria prioritize reliability certification over recreational price points. Target alpine tour operators in Bavaria and Tyrol with solid-state battery prototypes for high-altitude expeditions. Deploy direct-to-consumer channels with seasonal subscription models to bypass entrenched retail gatekeepers. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors battery chemistry specialists with pilot solid-state production lines and transparent Guangdong supply chain documentation. Long-term viability hinges on carbon border adjustment compliance and lifecycle disclosure capabilities. Acquisition targets should demonstrate thermal runaway mitigation engineering and CE marking expertise. Watch for inflection signals in municipal procurement tender language around embodied carbon requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cell Sourcing | Captive lithium-ion supply from Guangdong manufacturers insulates brands against spot-market volatility and allocation rationing. |
| CE Marking and Carbon Disclosure Investment | Lifecycle transparency qualifies manufacturers for Stuttgart and Frankfurt municipal tenders under EU Green Deal procurement rules. |
| Thermoelectric Generator Development | Stove-to-power convergence captures multi-day expedition users beyond conventional battery chemistry energy density limits. |
| Subscription-Based Gear Access Launch | Inventory pooling models in Berlin and Hamburg concentrate demand forecasting risk while building platform loyalty over manufacturer brands. |
| Modular Battery Design Standardization | Standardized cell formats satisfy Germany's extended producer responsibility frameworks and reduce recycling compliance costs. |
Research Methodology
A standing panel of product development leads at portable power brands, procurement managers at German outdoor retailers, battery cell sourcing directors, and alpine tour operators provided ongoing calibration throughout the study. Primary fieldwork combined structured interviews with secondary validation against customs records, MIIT battery safety filings, EU Green Deal regulatory texts, and specialty retail point-of-sale data. Bottom-up segment sizing triangulated against top-down market envelope checks.
Scenario-bracketing framed demand trajectories across the projection horizon, with segmentation dimensions spanning product type, end user archetype, battery chemistry, and application intensity. CAGRs were derived from fitted growth curves calibrated to historical adoption patterns and technology substitution rates. Forecast inputs incorporated photovoltaic efficiency improvement curves and lithium-ion energy density trajectories from cell manufacturer roadmaps.
Stress conditions across lithium carbonate price bands, logistics disruption severity, and regulatory compliance timeline compression were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding technology adoption rates and policy implementation schedules. Quarterly review of municipal procurement tender specifications and battery recycling mandate enforcement intensity is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor Gear
Japan Camping Equipment Market
Outdoor Gear
Outdoor Hot Tub Market
Outdoor Gear
Crash Pads Market
Outdoor Gear
Mexico Camping Equipment Market
Outdoor Gear
South Korea Camping Equipment Market
Outdoor Gear
Ice Axe Market
Outdoor Gear
Australia Camping Equipment Market
Outdoor Gear
Cordless Garden Equipment Market
Outdoor Gear
Trail Running Bags Market
Outdoor Gear
Spain Camping Equipment Market
Outdoor Gear
Outdoor Camping Toilet Market
Outdoor Gear
Deer Hunting Blinds Market
Outdoor Gear
Rooftop Tent Market
Outdoor Gear
China Camping Equipment Market
Outdoor Gear
Camping Gas Canister Market
Outdoor Gear
New Zealand Camping Equipment Market