
 Diving Regulator Market | 2026-2036
Diving Regulator Market Size, Share, and Industry Trends Forecast 2026-2036
Diving Regulator Market Outlook
Buyer concentration among commercial dive operators is repositioning procurement toward fleet-level contracts rather than individual diver purchases. Aqua Lung International leverages its integrated manufacturing footprint to serve this shift. Scubapro anchors its position through specialized first-stage designs for cold-water commercial applications. Mares competes aggressively in the recreational channel through controlled distribution networks across Mediterranean dive centers.
A diving regulator is a demand-controlled pressure-reduction device that transforms high-pressure breathing gas from a cylinder into ambient-pressure gas suitable for human respiration at depth, typically incorporating a first stage, second stage, and alternate air source with working pressures rated to 300 bar. Its primary purpose is to deliver breathable gas reliably across varying depths, temperatures, and exertion levels while preventing free-flow or icing failures. Balanced regulators command the strongest margin pools due to their performance consistency at extreme depths and cold temperatures, while unbalanced designs retain volume in entry-level recreational segments where cost sensitivity dominates. Electronic technology represents the fastest-growing category as integrated dive computers and automatic buoyancy systems converge on regulator platforms, though pneumatic mechanisms still occupy the bulk of military and scientific deployments where mechanical simplicity ensures field repairability.
The US Coast Guard and OSHA enforce commercial diving equipment standards that mandate redundant alternate air sources and specified burst-disk ratings for occupational underwater operations. ISO 25078 and EN 250 certification requirements from European notified bodies shape product development cycles and market access conditions for manufacturers seeking CE-marked distribution. Stakeholders must monitor evolving military procurement specifications and the divergence between recreational and commercial certification pathways as regulatory fragmentation intensifies.
Market Dynamics
Fleet-level procurement contracts among Southeast Asian liveaboard operators are compressing traditional retail channels and forcing manufacturers to restructure distribution economics around volume-based servicing agreements rather than individual unit sales.
Growth Catalysts
- ISO 25078 Certification Mandates:European notified bodies are accelerating CE-marking requirements for first-stage assemblies, compelling upgrade cycles across Mediterranean dive centers and creating replacement demand for non-compliant inventory.
- Thailand's Liveaboard Fleet Expansion:Coastal provinces from Phuket to Similan Islands are witnessing concentrated equipment procurement as tourism operators rebuild post-pandemic capacity with standardized regulator configurations.
- Cold-Water Performance Engineering:Balanced diaphragm technologies are penetrating commercial diving segments where thermal reliability at depth determines operational safety margins and insurance underwriting terms.
Market Restraints
- Titanium Alloy Input Volatility:Aerospace-grade titanium sourcing concentrates among Japanese and Russian smelters, exposing manufacturers to price swings that compress margin pools on premium regulator lines.
- EN 250 Testing Bottlenecks:European certification backlogs at notified body laboratories extend product launch timelines by 8-14 months, freezing working capital in pre-approved inventory.
- Rebreather Substitution Threat:Closed-circuit rebreather systems are capturing technical diving segments where extended bottom times outweigh the simplicity advantages of open-circuit regulators.
Strategic Opportunities
- Indonesia's Archipelago Underpenetration:Raja Ampat and Komodo National Park operators remain fragmented in equipment sourcing, presenting first-mover advantages for manufacturers establishing direct fleet servicing infrastructure.
- Integrated Dive Computer Convergence:Bluetooth-enabled regulators transmitting real-time breathing-gas data to wrist-mounted displays are opening premium pricing tiers among affluent recreational divers.
- USCG Commercial Mandates:Occupational diving regulations requiring redundant alternate air sources are institutionalizing multi-regulator configurations that double unit sales per diver in offshore inspection and construction segments.
Industry Challenges
- Hyperbaric Welding Technician Scarcity:Qualified technicians capable of servicing first-stage valve seats under pressure-rated conditions command wage premiums that inflate after-sales service costs and constrain manufacturer expansion.
- Legacy Pneumatic Integration Complexity:Electronic regulator platforms must maintain backward compatibility with existing cylinder valve threading standards and hose configurations, delaying full-system redesigns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Diving Regulator Market |
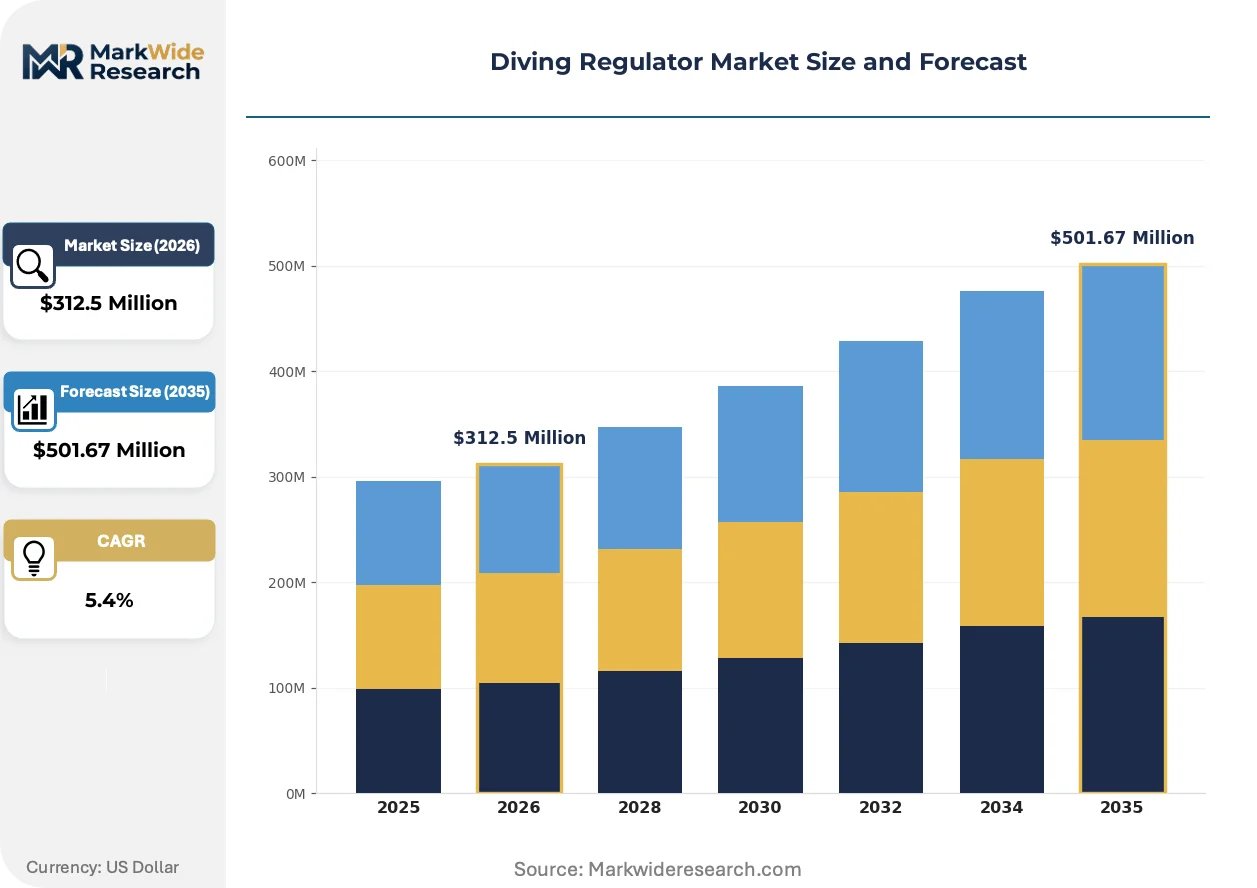
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $501.67 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Hose, Double Hose, Balanced, Unbalanced End User: Recreational Divers, Commercial Divers, Military Divers, Scientific Divers Technology: Pneumatic, Electronic, Automatic, Manual Distribution Channel: Online Retail, Diving Shops, Wholesale, Direct Sales |
| Companies Covered | Aqua Lung International, Scubapro, Mares, Cressi Sub, Huish Outdoors, Apeks, Atomic Aquatics, Halcyon, Dive Rite, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Diving Regulator Market Strategic Shifts
Electronic sensing and pneumatic reliability are fusing into hybrid architectures that redefine performance benchmarks, while regulatory divergence between recreational and occupational certification pathways fragments product development roadmaps.
Wireless tank-pressure transmitters embedded in first-stage yoke assemblies are converging with dive computer ecosystems to deliver real-time gas-availability calculations directly to diver displays. Technical training agencies are mandating these configurations for advanced certification tracks, compressing demand for analog submersible pressure gauges in recreational channels. The structural consequence is a bifurcation between integrated-system manufacturers and standalone pneumatic specialists.
REACH substance restrictions on chromium plating processes are forcing European manufacturers to migrate toward physical vapor deposition coatings for corrosion resistance in saltwater environments. Industrial consequence includes retooling costs that disadvantage smaller fabricators lacking capital for vacuum-chamber infrastructure. Mediterranean commercial operators sourcing EN 250-certified equipment are absorbing price premiums as compliant inventory filters through restricted supply channels.
Buyer concentration among Thai liveaboard fleet operators is consolidating procurement decisions under marine operations managers rather than individual divemasters or retail customers. Direct manufacturer-to-fleet service contracts are displacing traditional dive-center intermediaries in Phuket and Krabi provinces. This channel compression is most visible where aging regulator inventories require synchronized replacement across vessel manifests to standardize maintenance protocols and spare-part inventories.
Diving Regulator Market Segmentation
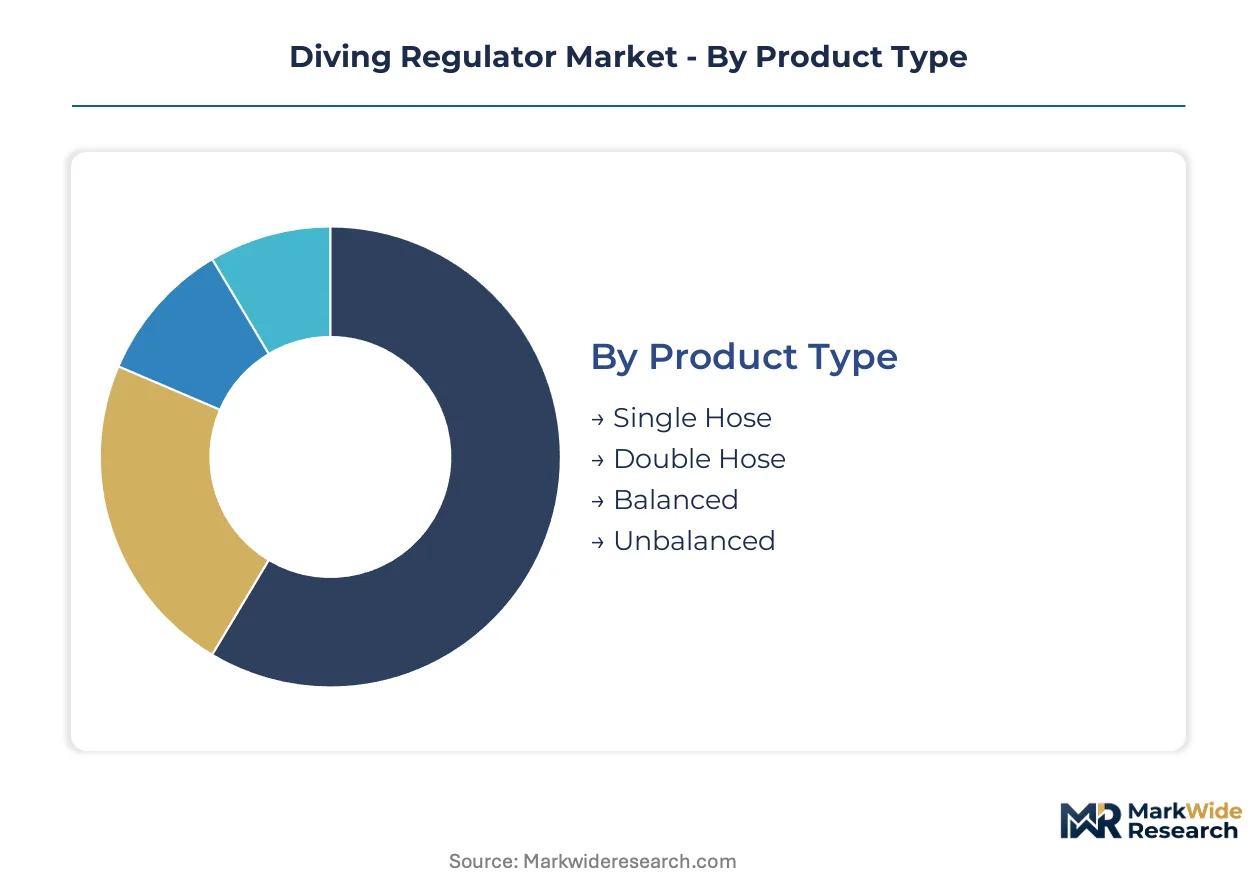
Diving regulator segmentation reflects divergent performance requirements across depth ratings, thermal environments, and operational duty cycles. Procurement patterns fragment between standardized fleet configurations and individually customized technical setups.
Product Type:
Customization intensity varies from mass-produced recreational units to precision-balanced assemblies engineered for extreme depth and temperature stability.
- Balanced:Diaphragm or piston designs maintain consistent breathing effort regardless of cylinder pressure or depth, using intermediate pressure chambers to isolate downstream mechanics. Demand concentrates among North Sea commercial operators where thermal reliability at depth determines insurance underwriting terms and operational safety margins.
- Unbalanced:Simpler mechanical architecture links second-stage valve directly to first-stage output, creating progressive breathing resistance as cylinder pressure drops. Recreational dive centers in Thailand's Phuket province favor these configurations for rental fleets where acquisition cost outweighs performance optimization.
- Single Hose:Standard configuration routing intermediate pressure through one hose to the second stage, with alternate air source on separate hose. Mares and Scubapro dominate this architecture across Mediterranean recreational channels.
- Double Hose:Vintage design with both inhalation and exhalation routed through a single hose loop, now restricted to historical equipment collectors and film production rental houses seeking period-accurate appearances.
Leading the category by volume: Unbalanced designs. Growing fastest: Balanced configurations.
End User:
Operational risk profiles and regulatory oversight intensity create tiered procurement specifications across diver categories.
- Commercial Divers:Occupational underwater operations mandate redundant alternate air sources and specified burst-disk ratings under USCG and OSHA frameworks. Offshore inspection contractors in the Gulf of Mexico institutionalize multi-regulator configurations that double unit sales per technician.
- Recreational Divers:Leisure diving generates volume through standardized rental inventories and personal equipment upgrades. Liveaboard fleet operators from Thailand's Similan Islands to Indonesia's Raja Ampat are consolidating procurement under marine operations managers rather than individual divemasters.
- Military Divers:Combat swimmer operations prioritize mechanical simplicity and field repairability over electronic integration, sustaining pneumatic mechanism demand despite civilian market digitization.
- Scientific Divers:Research institutions require extended bottom times and precise gas mixture control, creating hybrid demand between open-circuit reliability and rebreather substitution threats.
Dominant procurement volume flows to recreational channels. Steepest expansion trajectory: Commercial segments under tightening occupational safety mandates.
Technology:
Mechanical heritage confronts sensor integration as dive computer ecosystems converge on regulator platforms.
- Pneumatic:Purely mechanical pressure reduction using springs, diaphragms, and levers without electrical components. Military and scientific deployments sustain this category where battery failure risks outweigh convenience benefits.
- Electronic:Sensor-activated solenoids and microprocessor-controlled valve timing enable real-time breathing gas data transmission to wrist-mounted displays. Bluetooth-enabled first stages are opening premium pricing tiers among affluent recreational divers in Japanese and Australian markets.
- Automatic:Pre-set inhalation resistance and flow rates optimized for standard recreational depths and exertion levels, minimizing diver adjustment requirements.
- Manual:Diver-adjustable venturi switches and cracking pressure knobs for technical diving scenarios requiring precise gas conservation at depth.
Pneumatic mechanisms retain plurality share. Electronic platforms are climbing the fastest as training agencies mandate integrated-system configurations.
Distribution Channel:
Channel economics restructure around fleet-scale servicing agreements versus individual unit retail.
- Direct Sales:Manufacturer-to-fleet contracts bypass traditional intermediaries, concentrating procurement decisions among Thai and Indonesian liveaboard marine operations managers. Aqua Lung International leverages integrated manufacturing footprints to serve this shift.
- Diving Shops:Local retail and service infrastructure remains critical for recreational diver education, equipment fitting, and annual maintenance. Mediterranean centers in Greece and Spain maintain this channel's relevance.
- Online Retail:E-commerce penetration accelerates for standardized replacement parts and known-configuration purchases, though regulators requiring custom fitting resist full digital migration.
- Wholesale:Volume aggregation for dive center chains and resort operators, increasingly displaced by direct manufacturer relationships as buyer concentration intensifies.
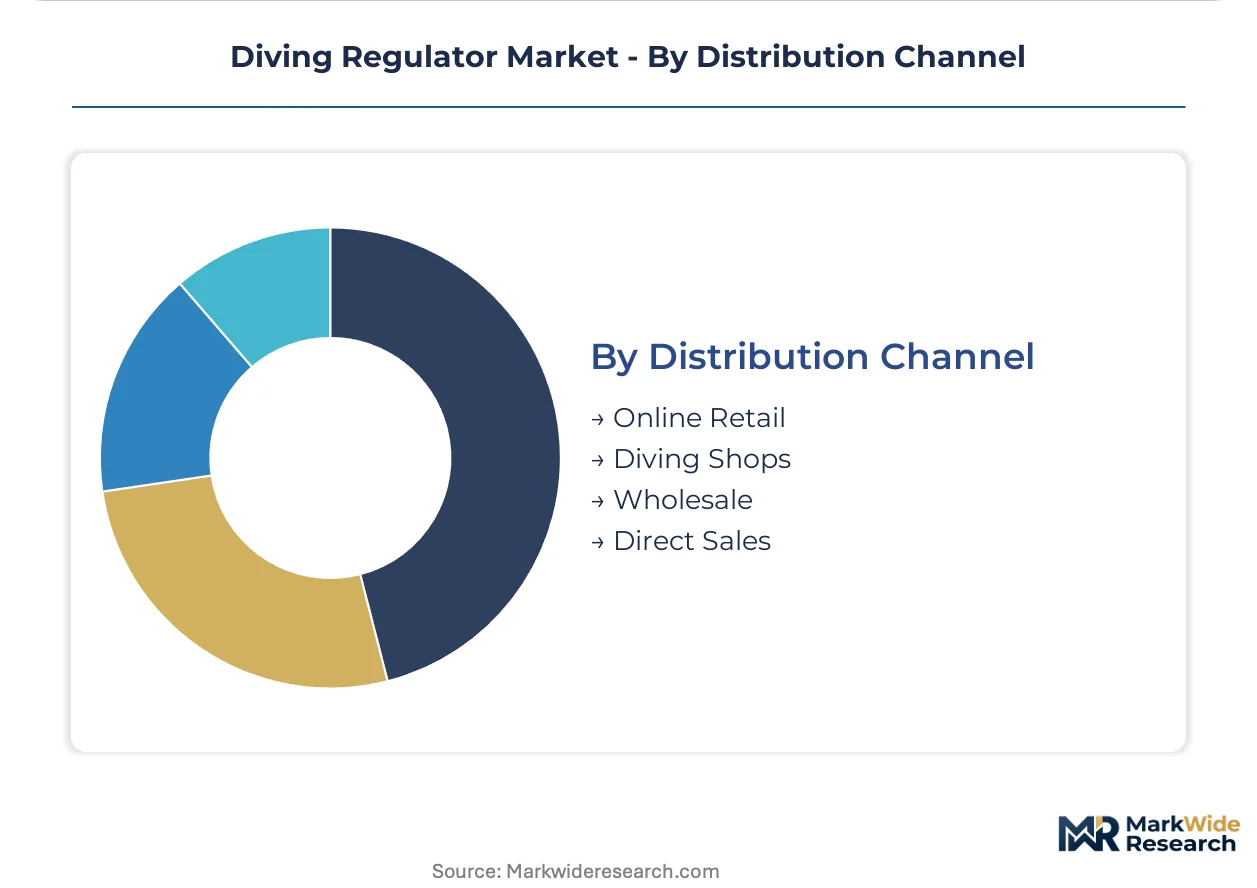
Diving shops retain plurality position. Direct sales channels are gaining share fastest as fleet procurement consolidates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thailand's liveaboard fleet operators concentrate procurement decisions under marine operations managers, compressing traditional retail channels and forcing manufacturers to restructure distribution economics around volume-based servicing agreements.
United States
Gulf of Mexico offshore inspection contractors institutionalize multi-regulator configurations that double unit sales per technician under USCG commercial diving mandates. OSHA enforces redundant alternate air source requirements for occupational underwater operations. Houston-based diving service companies synchronize equipment replacement cycles to comply with updated burst-disk rating specifications.
Germany
North Sea commercial operators demand balanced diaphragm technologies where thermal reliability at depth determines insurance underwriting terms. ECHA REACH substance restrictions on chromium plating processes force migration toward physical vapor deposition coatings. Industrial fabricators in the Ruhr region absorb retooling costs for vacuum-chamber infrastructure to maintain EN 250 certification compliance.
Thailand
Coastal provinces from Phuket to Similan Islands witness concentrated equipment procurement as tourism operators rebuild post-pandemic capacity. The country's national tourism authority coordinates fleet standardization initiatives. Marine operations managers in Krabi province displace traditional dive-center intermediaries through direct manufacturer service contracts.
Japan
Bluetooth-enabled regulators transmitting real-time breathing-gas data to wrist-mounted displays open premium pricing tiers among affluent recreational divers. METI oversees industrial standards coordination for integrated dive computer convergence. Osaka-based training agencies mandate sensor-activated configurations for advanced certification tracks.
Australia
Technical diving segments show hybrid demand between open-circuit reliability and rebreather substitution threats for extended bottom times. The country's national standards body aligns with ISO 25078 certification frameworks. Queensland dive operators along the Great Barrier Reef upgrade aging regulator inventories to meet tightened material certification requirements.
Diving Regulator Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue electronic integration and fleet-direct servicing models. The vendor base concentrates among integrated manufacturing specialists and precision-engineering boutiques rather than diversified conglomerates. Three archetypes dominate: full-system manufacturers controlling casting-to-assembly workflows, component specialists supplying first-stage valve trains, and regional assemblers serving price-sensitive rental channels. Competitive moves center on backward integration into titanium alloy sourcing and exclusive fleet-servicing contracts that lock out distributor intermediaries.
Among heritage diving equipment fabricators, Aqua Lung International and Scubapro exemplify full-system manufacturers with integrated production footprints, while Mares occupies a position within the Mediterranean-focused recreational channel. These three entities represent contrasting strategic postures: one anchored in commercial cold-water applications, another in fleet-direct volume contracts, and the third in controlled distribution networks across dive-center retail.
| Leading Market Players |
|---|
| Aqua Lung International |
| Scubapro |
| Mares |
| Cressi Sub |
| Huish Outdoors |
| Apeks |
| Atomic Aquatics |
| Halcyon |
| Dive Rite |
| Others |
Value Chain & Pricing Dynamics
Aerospace-grade titanium alloy sourcing from Japanese and Russian smelters flows through three distinct pricing tiers, with raw material volatility compressing margin pools on premium balanced regulator lines while unbalanced recreational units absorb cost pass-through more readily.
Pricing Analysis
Volume concentrates in unbalanced recreational configurations where acquisition cost outweighs performance optimization, while margin pools accrue to balanced diaphragm assemblies engineered for North Sea thermal reliability. Price differentiation separates EN 250-certified commercial units from rental-grade inventory through certification grade and after-sales service bundling. Cost compression in the premium tier intensifies because titanium alloy input volatility exposes manufacturers to price swings. Recreational dive centers in Thailand's Phuket province exhibit the highest price sensitivity, whereas Gulf of Mexico offshore contractors demonstrate the lowest due to insurance-mandated safety specifications.
Supply Chain Analysis
EN 250 certification bottlenecks at European notified body laboratories gate market access, freezing working capital in pre-approved inventory and extending product launch timelines. Manufacturing concentrates in Italy, Germany, and the United States, with first-stage valve seat machining and diaphragm assembly anchoring production clusters. Raw material dependencies draw from aerospace-grade titanium alloys, chromium plating substrates, and precision spring steel. Single-source vulnerability runs through Japanese and Russian titanium smelters exposed to geopolitical disruption. Distribution runs through direct manufacturer-to-fleet contracts that displace wholesale intermediaries in Southeast Asian liveaboard markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The diving regulator market sits in a technology-transition phase where electronic sensing platforms displace purely pneumatic mechanisms, with Bluetooth-enabled first stages transmitting real-time breathing-gas data to wrist-mounted displays now mandated by advanced certification tracks.
For Market Incumbents: Hedge against rebreather substitution threats in technical diving segments by deepening backward integration into titanium alloy sourcing and locking exclusive fleet-servicing contracts with Thai and Indonesian liveaboard operators. Secure EN 250 certification pipeline capacity at notified body laboratories to prevent competitor product launch acceleration.
For New Entrants and Emerging Players: Enter via Indonesia's Raja Ampat and Komodo National Park operator fragmentation, where direct servicing infrastructure remains underdeveloped and procurement decisions lack standardization. Target commercial cold-water applications in the North Sea where balanced diaphragm demand outstrips qualified supplier capacity, deploying precision-engineering boutiques with vacuum-chamber physical vapor deposition coating capabilities.
For Investors and Strategic Acquirers: Bluetooth transmitter integration into first-stage yoke assemblies is the leading indicator that electronic-pneumatic hybrid architectures will capture premium pricing tiers. Long-term viability favors manufacturers controlling casting-to-assembly workflows with captive titanium sourcing and established fleet-direct relationships. Monitor EN 250 testing backlog resolution at European notified bodies as the signal for working capital release and inventory velocity recovery.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Titanium Sourcing | Captive supply of aerospace-grade alloys insulates margin pools from Japanese and Russian smelter price volatility. |
| Fleet-Direct Servicing Infrastructure | Exclusive contracts with Thai liveaboard operators displace dive-center intermediaries and standardize maintenance protocols. |
| EN 250 Certification Pipeline Investment | Secured laboratory capacity at European notified bodies accelerates product launch timelines ahead of competitors. |
| Electronic-Pneumatic Hybrid Development | Bluetooth-enabled first stages meet Japanese and Australian training agency mandates for advanced certification tracks. |
| Physical Vapor Deposition Coating Transition | REACH-compliant corrosion resistance maintains European market access as chromium plating faces substance restrictions. |
Study Parameters
Multi-period observation of fleet procurement volumes, certification backlog durations, and titanium alloy price movements anchored the trend analysis, supplemented by interviews with marine operations managers at Southeast Asian liveaboard operators, precision-engineering directors at first-stage valve manufacturers, and regulatory affairs leads at European notified bodies. Secondary validation drew from ISO 25078 and EN 250 certification databases, USCG commercial diving equipment filings, and Thailand national tourism authority fleet standardization records. Bottom-up demand aggregation across recreational, commercial, and military end-use segments was triangulated against top-down manufacturer shipment estimates.
Segment-weighting approaches distributed value and volume across balanced versus unbalanced product architectures, pneumatic versus electronic technology platforms, and direct sales versus dive shop distribution channels over the projection horizon. CAGRs were derived from regression analysis of historical procurement patterns and forward-looking fleet expansion announcements. Industry-specific forecast inputs included liveaboard vessel manifest replacement cycles and rebreather penetration rates in technical diving segments.
Revisions become necessary when EN 250 certification timelines extend beyond current notified body capacity, when titanium alloy supply disruptions alter input cost structures, or when rebreather substitution accelerates in scientific diving applications. Forecasts reflect assumptions about post-pandemic tourism normalization in Southeast Asia and occupational safety mandate enforcement continuity in Gulf of Mexico offshore operations. A model refresh is warranted upon material change in military procurement specifications for field-repairable pneumatic mechanisms.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor Gear
Germany Camping Equipment Market
Outdoor Gear
North America and Europe Leaf Blower Market
Outdoor Gear
Outdoor Hot Tub Market
Outdoor Gear
Outdoor Camping Toilet Market
Outdoor Gear
China Camping Tent Market
Outdoor Gear
North America Pocket Knives Market
Outdoor Gear
China Camping Equipment Market
Outdoor Gear
Japan Camping Equipment Market
Outdoor Gear
Crash Pads Market
Outdoor Gear
Campsite Cooking Gears Market
Outdoor Gear
Inflatable Tents Market
Outdoor Gear
Mexico Camping Equipment Market
Outdoor Gear
Singapore Camping Equipment Market
Outdoor Gear
Diving Equipment Market
Outdoor Gear
Fairway Mowers Market
Outdoor Gear
Camping Cooler Market