
 US Backpacks Market | 2026-2036
US Backpacks Market Size, Share, and Industry Trends Forecast 2026-2036
US Backpacks Market Analytics
Aftermarket repair and warranty service revenue is rewriting how US backpack brands capture lifetime customer value. Osprey leverages its All Mighty Guarantee to sustain repeat purchases across multiple product cycles. Patagonia anchors its market position through the Worn Wear program, which competes with new-unit sales while building brand loyalty. GORUCK differentiates via SCARS lifetime warranty coverage that occupies a premium position in tactical-adjacent segments.
A backpack is a load-bearing container constructed from woven textiles—typically denier-rated nylon or polyester—with padded suspension systems, internal frames or frame sheets, and compartmentalized storage architecture designed for portable cargo management. The primary commercial purpose spans daily commuting, educational use, outdoor recreation, and specialized professional transport. Hiking backpacks command the highest average unit margins due to technical suspension engineering and weatherproofing requirements. Travel segments are expanding fastest as hybrid remote-work patterns normalize multi-day mobile office setups. Casual and student-oriented nylon constructions remain the volume base but face margin compression from private-label competition.
The Federal Trade Commission's Green Guides and California's SB 657 supply chain transparency requirements shape how brands source and label recycled polyester and fair-trade components. The Consumer Product Safety Commission monitors lead content and flammability standards for youth-oriented designs. ASTM International maintains voluntary durability testing protocols that influence retailer procurement criteria. Stakeholders must monitor how state-level extended producer responsibility legislation evolves and whether repair-service infrastructure becomes a regulatory compliance pathway rather than purely a brand differentiation tool.
Market Dynamics
The FTC's Green Guides enforcement is compressing how brands communicate recycled-content claims, forcing material sourcing transparency that restructures procurement relationships between manufacturers and textile suppliers.
Growth Catalysts
- Ergonomic design mandates:School districts in California and Washington are updating equipment guidelines that require padded suspension systems and lumbar support in student backpacks, expanding the addressable market for technically designed daily-carry products.
- SB 657 supply chain transparency:California's disclosure requirements for fair-trade components are creating competitive differentiation for brands that document ethical polyester sourcing, pulling procurement decisions toward verified supply chains.
- Remote-work normalization:Hybrid employment patterns are expanding demand for multi-day mobile office configurations, with travel-oriented backpacks incorporating laptop compartments and TSA-compliant access points.
Market Restraints
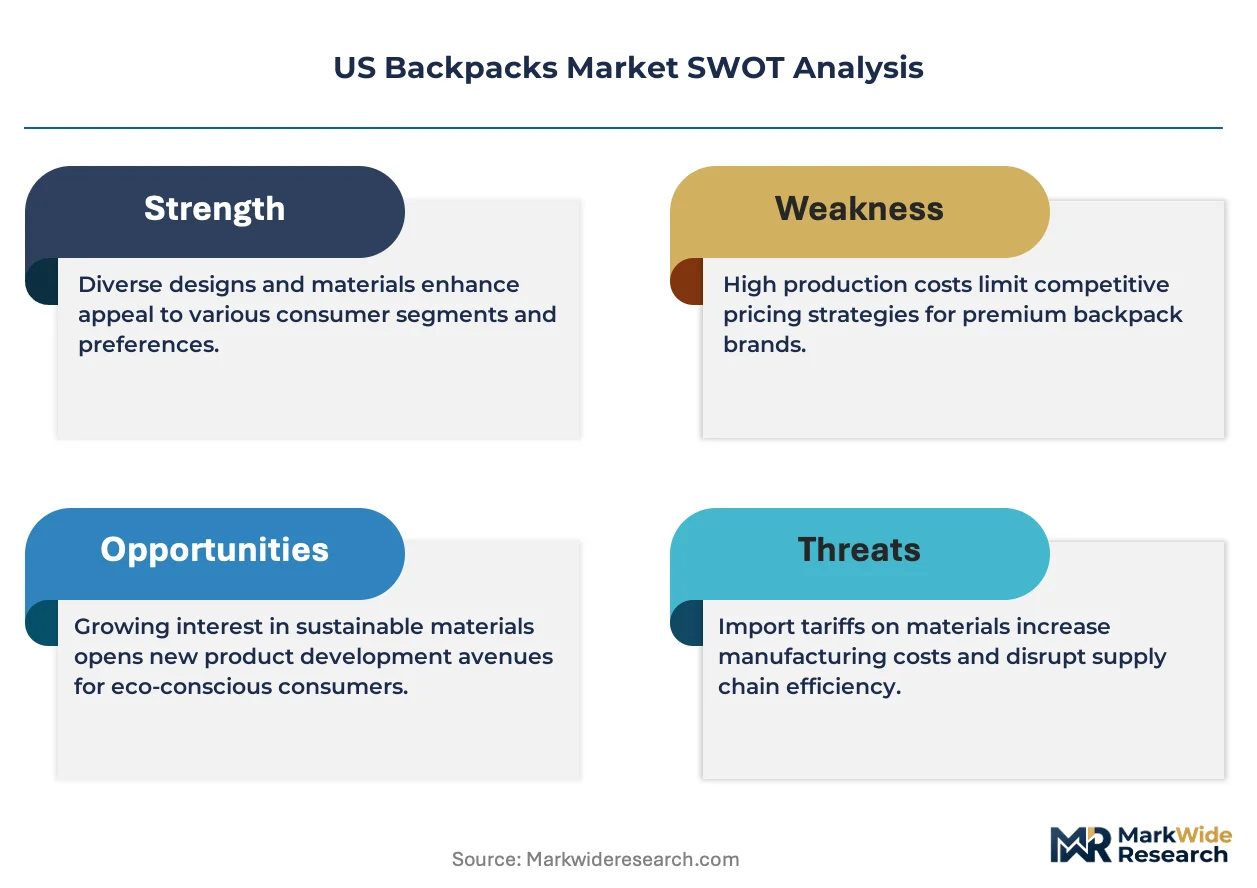
- Denier-rated nylon price volatility:Petroleum-derived synthetic textiles face input cost pressure from energy market fluctuations, compressing margins on volume-oriented casual and student segments.
- Private-label concentration:Mass retailers' captive brands are capturing shelf space in big-box channels, constraining branded manufacturers' distribution access in price-sensitive consumer tiers.
- Lead content testing requirements:CPSC flammability and chemical standards for youth-oriented designs impose compliance costs that disproportionately burden smaller manufacturers lacking in-house testing infrastructure.
Strategic Opportunities
- Extended producer responsibility legislation:State-level repair-service mandates in Oregon and Colorado are creating regulatory pathways where warranty infrastructure becomes a compliance asset rather than purely a cost center.
- Frame sheet technology convergence:Integration of lightweight aluminum stays with thermoformed back panels is enabling crossover products that serve both urban commuting and light hiking applications.
- Pacific Northwest outdoor recreation density:Washington and Oregon's overlapping urban commuting and trail-use cultures support premium positioning for technical suspension systems that transition between environments.
Industry Challenges
- ASTM durability certification timelines:Voluntary testing protocols for zipper cycle counts and seam strength are extending product development schedules, delaying seasonal launches.
- Recycled-content verification complexity:Mechanical recycling of post-consumer polyester requires chain-of-custody documentation that strains supplier relationship management capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Backpacks Market |
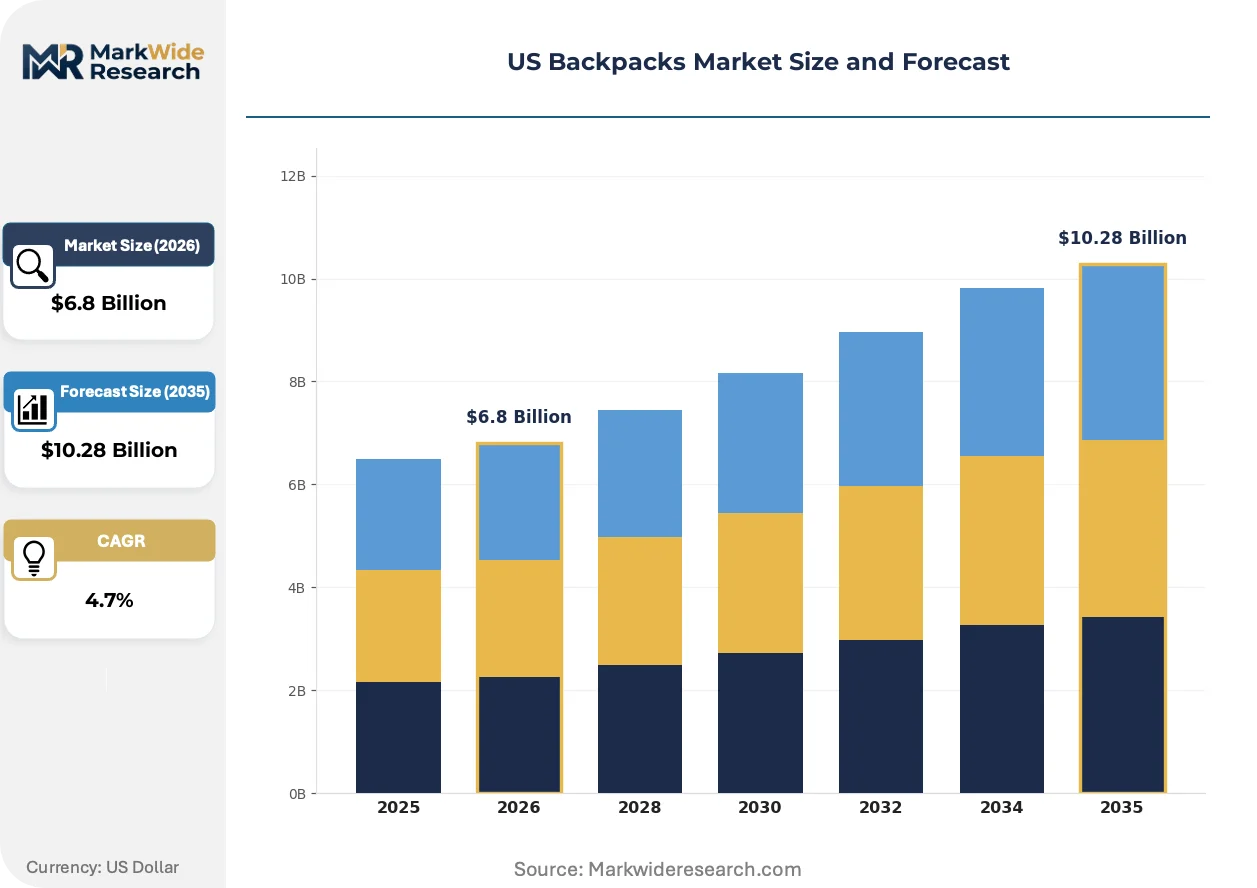
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.28 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Casual, Hiking, Sports, Travel End User: Students, Professionals, Travelers, Athletes Material: Nylon, Polyester, Canvas, Leather Size: Small, Medium, Large, Extra Large |
| Companies Covered | JanSport, Mystery Ranch, Osprey, Timbuk2, GORUCK, Kelty, Patagonia, Tom Bihn, Gregory, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Backpacks Market Evolving Landscape
Material science advances and regulatory disclosure requirements are converging to transform how backpacks are specified, manufactured, and marketed across price tiers and use cases.
Recycled ocean-bound polyester is collapsing the cost premium between virgin and sustainable textiles. Outdoor recreation brands are adopting Repreve and similar certified fibers at scale, with hiking and travel segments leading integration. The technology is collapsing the historical 15-20% price gap that constrained sustainable positioning to premium tiers.
FTC Green Guides enforcement is tightening substantiation standards for environmental marketing claims. Brands must now document recycled-content percentages through third-party certification, reshaping how suppliers are qualified and contracts are structured. Student and casual segments face the steepest compliance adjustment as they retrofit labeling and sourcing documentation.
After-sales service unbundling is restructuring buyer relationships in technical segments. Consumers are evaluating lifetime repair accessibility alongside initial purchase price, with warranty infrastructure influencing brand selection in hiking and tactical-adjacent categories. This pattern concentrates most visibly in California and Pacific Northwest markets where outdoor participation rates support premium positioning for durability guarantees.
US Backpacks Market Segmentation
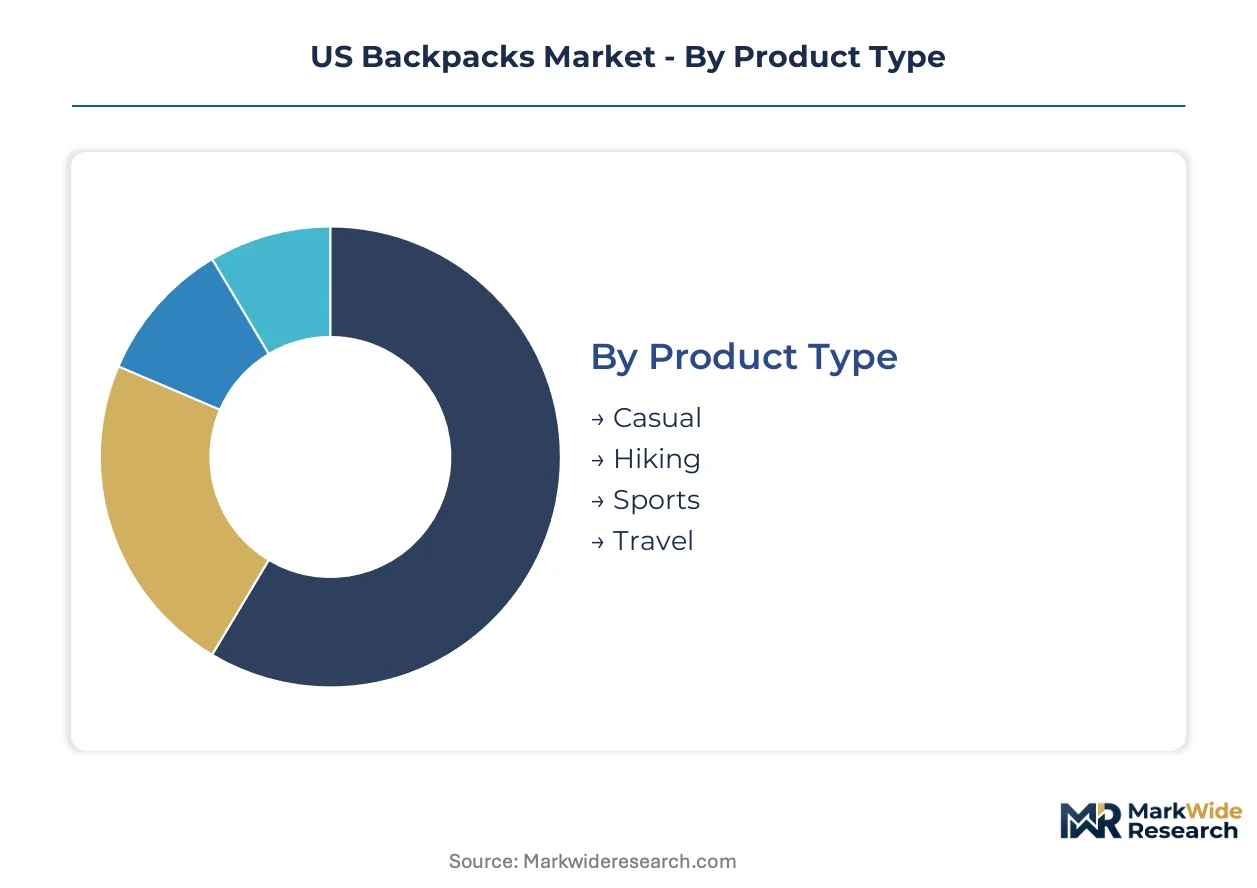
Backpack purchasing cycles vary dramatically across use cases, from annual student replacements to decade-long hiking investments. Understanding these turnover patterns reveals where brands must prioritize inventory velocity versus durability engineering.
Product Type:
Replacement frequency spans eighteen months for casual daily carriers to seven-plus years for technical hiking designs, reshaping how manufacturers allocate R&D and warranty resources.
- Hiking:Technical suspension systems with aluminum stays and weatherproof laminates command extended development timelines. Demand clusters in Washington and Oregon where urban commuting and trail access overlap, with Pacific Northwest retailers prioritizing ASTM-certified durability ratings.
- Travel:Hybrid remote-work configurations incorporating TSA-compliant laptop compartments and clamshell opening architectures. California's tech corridor drives adoption as multi-day mobile office setups normalize among hybrid employees.
- Casual:Volume-oriented nylon constructions facing margin pressure from private-label competition in big-box channels.
- Sports:Activity-specific compartmentalization for equipment transport with moisture-wicking liner integration.
Casual designs anchor the volume base while Travel configurations gain share at the steepest rate.
End User:
Procurement authority and replacement triggers differ fundamentally between institutional buyers and individual consumers.
- Students:California and Washington school districts are mandating ergonomic padded suspension and lumbar support, converting equipment guidelines into technical specifications. District-level purchasing concentrates volume in late summer cycles with three-to-four year replacement horizons.
- Professionals:Hybrid employment patterns in Seattle and San Francisco are normalizing premium daily-carry investments with integrated tech organization and weatherproofing.
- Travelers:Leisure and business trip frequency directly correlates with multi-day capacity requirements and checkpoint-friendly access points.
- Athletes:Gear-intensive sports participation drives demand for ventilated back panels and external attachment systems.
Students generate the highest unit volumes while Professionals deliver the strongest margin contribution per transaction.
Material:
Input cost exposure and sustainability certification complexity separate commodity textiles from premium positioned alternatives.
- Nylon:Denier-rated petroleum-derived fabrics dominate casual and student segments. Price volatility from energy market fluctuations compresses margins on volume-oriented production runs.
- Polyester:Recycled ocean-bound variants from Repreve and similar certified fiber suppliers are collapsing the historical price gap with virgin material. FTC Green Guides enforcement requires third-party chain-of-custody documentation, favoring manufacturers with established supplier verification infrastructure.
- Canvas:Natural fiber heritage positioning with waxed weatherproofing treatments for style-conscious urban markets.
- Leather:Premium artisan positioning with extended patina-based aging narratives and repair-service integration.
Polyester is climbing the fastest as recycled-content verification becomes a procurement differentiator under California's SB 657 disclosure requirements.
Size:
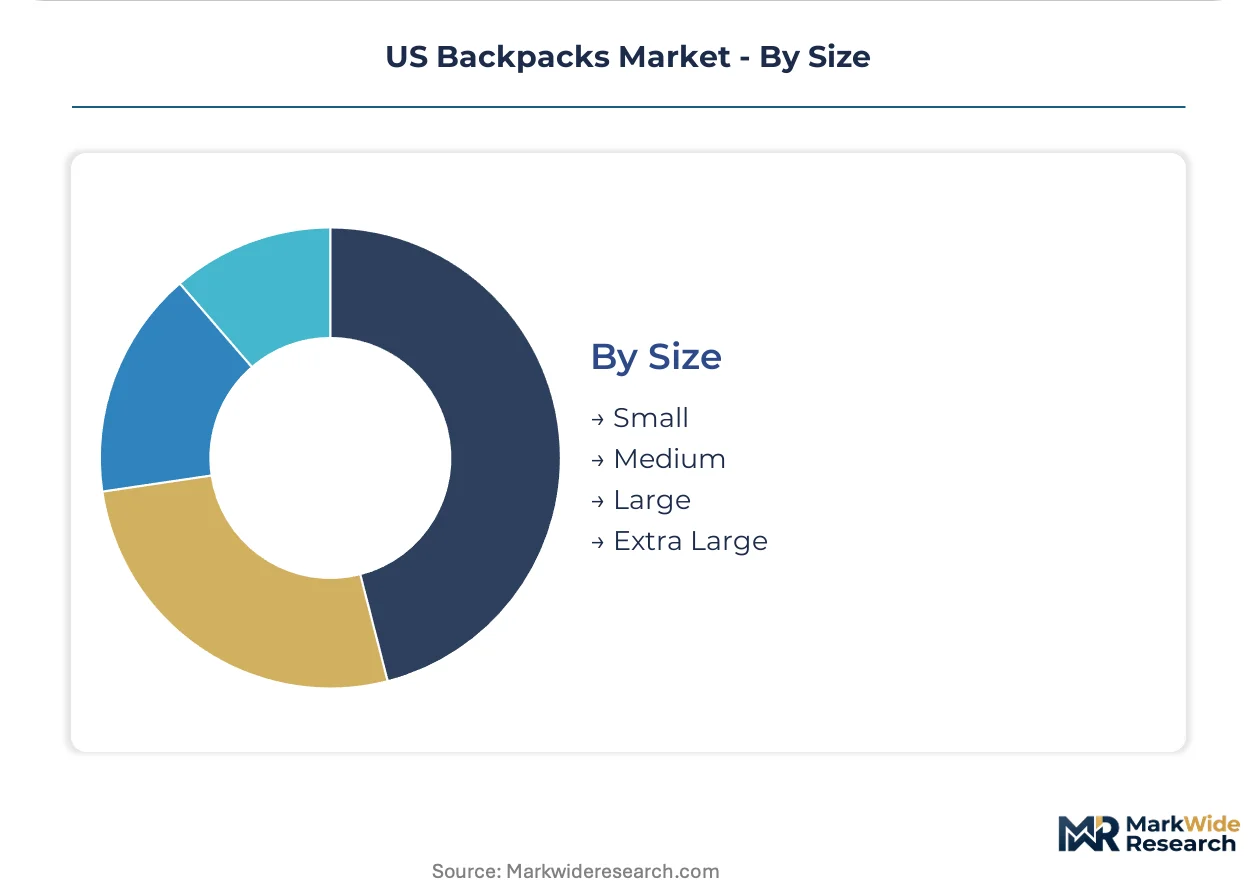
Capacity requirements map directly to trip duration and load-bearing expectations, with suspension engineering investments scaling non-linearly above medium thresholds.
- Large:Multi-day trekking and extended travel applications requiring internal frame sheets and load-lifter strap integration. Oregon and Colorado outdoor recreation density supports premium positioning for technical suspension systems.
- Medium:Daily commuting and single-day hiking crossover products with thermoformed back panel convergence. Frame sheet technology advances are enabling urban-to-trail transition designs.
- Small:Minimalist everyday carry and hydration-focused trail running configurations.
- Extra Large:Expedition-grade applications with expedition-specific portage and gear attachment architectures.
Medium capacity anchors the volume base while Large formats expand most quickly as hybrid remote-work patterns extend trip durations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
US backpack consumption patterns diverge sharply between coastal urban corridors and interior markets, with technical suspension systems dominating Pacific Northwest purchasing while value-oriented nylon constructions anchor Midwest and Southern volume.
California
Ergonomic design mandates from Los Angeles and San Francisco school districts are converting equipment guidelines into technical specifications for padded suspension systems. The state's SB 657 supply chain transparency requirements pull procurement toward verified recycled-polyester supply chains. San Diego and Sacramento retail corridors concentrate premium daily-carry demand from hybrid tech workers.
Pacific Northwest
Washington and Oregon's overlapping urban commuting and trail-use cultures support premium positioning for crossover frame-sheet technology. Oregon's extended producer responsibility legislation creates regulatory pathways where warranty infrastructure becomes compliance infrastructure. Seattle and Portland anchor the densest concentration of outdoor recreation retailers prioritizing ASTM-certified durability ratings.
Texas
Energy sector employment patterns drive demand for tactical-adjacent configurations with modular attachment systems. The Texas Education Agency's district-level purchasing concentrates student backpack volume in late summer cycles. Dallas-Fort Worth and Houston retail channels emphasize value-oriented nylon constructions facing private-label competition.
Northeast Corridor
Finance and professional services employment in New York and Boston normalizes premium daily-carry investments with integrated tech organization. Massachusetts and New York state procurement guidelines influence institutional purchasing for student and professional segments. Boston's outdoor retailer density supports technical hiking demand alongside urban commuting applications.
Mountain West
Colorado's outdoor recreation economy and remote-work normalization extend trip durations for multi-day travel configurations. State-level repair-service mandates in Colorado create compliance assets for brands with established warranty infrastructure. Denver and Boulder retail clusters concentrate demand for technical suspension systems serving both urban and trail environments.
US Backpacks Market Competitive Landscape
Capability concentration sits with technical suspension specialists; scale advantage sits with heritage daily-carry manufacturers. The market structures around three tiers: premium outdoor brands with warranty differentiation, mid-market heritage labels with institutional channel access, and private-label suppliers capturing big-box volume. Strategic moves center on repair-service infrastructure investment and recycled-content supply chain verification.
Within the technical warranty tier, Osprey, Patagonia, and GORUCK exemplify competitive positioning through durability guarantees and repair-service integration. These companies occupy positions where lifetime value capture depends on aftermarket infrastructure rather than unit velocity alone. Heritage daily-carry specialists including JanSport and Timbuk2 anchor institutional and urban commuting segments through established retail channel relationships.
| Leading Market Players |
|---|
| JanSport |
| Mystery Ranch |
| Osprey |
| Timbuk2 |
| GORUCK |
| Kelty |
| Patagonia |
| Tom Bihn |
| Gregory |
| Others |
Value Network & Pricing Analysis
Guangdong and Fujian province textile clusters anchor global woven nylon and polyester capacity, with their synthetic fiber output volumes directly determining margin compression or expansion for US-bound backpack tiers. Contract structures linking these hubs to American brands transmit energy-market volatility into landed cost fluctuations that reshape domestic pricing power across student, casual, and technical segments.
Pricing Analysis
Long-term offtake agreements with certified recycled-polyester suppliers dominate procurement for premium hiking and travel tiers, insulating Osprey and Patagonia from spot-market petroleum volatility that erodes casual-segment margins. Price differentiation separates ASTM-certified durability tiers from uncertified private-label alternatives, with brand premium and after-sales warranty bundling commanding 40-60 point spreads. Cost compression in student-oriented nylon constructions intensifies because mass retailers' captive brands force branded manufacturers toward promotional pricing cycles. District-level institutional buyers exhibit highest price sensitivity, while Pacific Northwest outdoor enthusiasts demonstrate lowest sensitivity when warranty infrastructure accompanies technical suspension systems.
Supply Chain Analysis
Contract manufacturing concentration sits with Vietnam and Bangladesh apparel complexes for cut-and-sew assembly, while Chinese Zhejiang and Jiangsu provinces control woven textile upstream. Raw material dependencies encompass petroleum-derived denier-rated nylon, mechanically recycled ocean-bound polyester from Repreve-certified facilities, and aluminum stay extrusions for frame sheet integration. Single-source vulnerability concentrates in Taiwanese zipper and fastener component suppliers, where geopolitical friction threatens seasonal production timelines. Distribution runs through three-channel architecture: outdoor specialty retailers prioritizing ASTM certification, big-box mass merchants emphasizing private-label penetration, and direct-to-consumer warranty-integrated platforms capturing lifetime value.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Private-label nylon backpacks from mass retail captive brands pose immediate substitution pressure on branded student and casual tiers, forcing incumbents to justify premium positioning through durability verification and repair-service integration rather than styling alone.
For Market Incumbents: Harden warranty infrastructure into regulatory compliance assets as Oregon and Colorado extended producer responsibility legislation matures, converting repair-service costs into defensible market access. Deepen backward integration into verified recycled-polyester supply chains under FTC Green Guides enforcement, using third-party chain-of-custody documentation to distance from private-label competitors facing substantiation failures. Prioritize ASTM durability certification investment for zipper cycle counts and seam strength to maintain outdoor specialty retail shelf access against uncertified alternatives. For New Entrants and Emerging Players: Build out repair-service platforms targeting the Pacific Northwest's dense outdoor recreation economy, where Washington and Oregon consumers evaluate lifetime repair accessibility alongside initial purchase price. White-space penetration concentrates in hybrid remote-work travel configurations serving California's tech corridor, where TSA-compliant clamshell architectures with integrated laptop organization remain underdeveloped relative to demand velocity. Go-to-market positioning should anchor on frame-sheet technology convergence enabling urban-to-trail crossover utility, bypassing established players' segment-specific silos. For Investors and Strategic Acquirers: Long-term, this sits as a circular-economy infrastructure play because warranty and repair-service networks transform from cost centers into regulatory compliance assets and customer lifetime value capture mechanisms. Acquisition target archetype: mid-market technical brands with established ASTM certification and underutilized repair infrastructure capable of scaling under state-level extended producer responsibility mandates. Monitor Oregon and Colorado legislative rulemaking timelines as the critical inflection signal—accelerated repair-service mandate implementation would revalue warranty-capable assets upward while stranding pure unit-velocity competitors.| Strategic Initiative | Industry Significance |
|---|---|
| Warranty Infrastructure Investment | Oregon's extended producer responsibility legislation converts repair networks into compliance assets for market access. |
| Recycled-Polyester Supply Chain Verification | FTC Green Guides enforcement requires third-party chain-of-custody documentation that strains smaller competitors. |
| Frame-Sheet Technology Convergence | Thermoformed back panel integration enables crossover products serving both Seattle commuting and Cascade trail use. |
| Direct-to-Consumer Platform Launch | Patagonia's Worn Wear program demonstrates lifetime value capture that competes with new-unit sales. |
| ASTM Durability Certification | Pacific Northwest outdoor retailers prioritize certified zipper cycle counts and seam strength in procurement criteria. |
Research Methodology
A spread of perspectives from brand product development directors, outdoor specialty retail buyers, textile procurement managers, and warranty service operations heads converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews across these stakeholder categories with secondary validation from CPSC flammability standard filings, FTC Green Guides enforcement actions, California SB 657 disclosure databases, and ASTM International protocol documentation. Bottom-up segment sizing triangulated against top-down macroeconomic indicators to constrain projection variance.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with capacity utilization at Vietnamese and Bangladeshi contract manufacturers cross-referenced against US import volume trends. Segmentation dimensions modeled encompass product type, end-user procurement authority, material certification tier, and capacity size class. CAGRs derived from historical trajectory analysis adjusted for regulatory inflection points including extended producer responsibility legislation timelines. Industry-specific forecast inputs incorporated school district equipment guideline adoption rates and hybrid employment pattern normalization indices.
Practitioners should monitor state-level extended producer responsibility rulemaking progress, FTC Green Guides enforcement intensity, and petroleum-derived textile input cost volatility for early signals requiring forecast revision. Quarterly review of Oregon and Colorado regulatory dockets, ASTM protocol update schedules, and mass retailer private-label expansion announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor Gear
Rechargeable Camping Gear Market
Outdoor Gear
Picnic Coolers Market
Outdoor Gear
Campsite Cooking Gears Market
Outdoor Gear
Shoulder Strap Insulated Cooler Market
Outdoor Gear
Hunting Boots Market
Outdoor Gear
Crash Pads Market
Outdoor Gear
Rain Boots Market
Outdoor Gear
Global Automatic Mower Market
Outdoor Gear
Bicycle Bags and Bag Packs Market
Outdoor Gear
Camping Equipment and Furniture Market
Outdoor Gear
UK Camping Equipment Market
Outdoor Gear
South Korea Camping Equipment Market
Outdoor Gear
Outdoor Hot Tub Market
Outdoor Gear
Camp Fire Tripod Market
Outdoor Gear
Professional Gear Bags Market
Outdoor Gear
Diving Regulator Market