
 North America Agricultural Biologicals Market | 2026-2036
North America Agricultural Biologicals Market Size, Share, and Industry Trends Forecast 2026-2036
North America Agricultural Biologicals Market Insights
The EPA's streamlined biopesticide registration framework is consolidating the cost-of-entry calculus for new biological active ingredients. Syngenta Group leverages its integrated seed-and-biological pipeline to anchor shelf space across major agricultural retailers. Corteva Agriscience competes through proprietary microbe discovery platforms that sustain year-over-year R&D yields. Novozymes A/S dominates enzyme-based biostimulant formulations, extending its technical leadership into North American corn and soybean programs.
Agricultural biologicals comprise living organisms, derived metabolites, and natural substances applied to crops for pest management, fertility enhancement, or abiotic stress mitigation, typically formulated with colony-forming units exceeding 10^8 per milliliter for microbial products. Biopesticides command the largest revenue share among product types due to grower familiarity and established residue exemption protocols, while biostimulants represent the fastest-expanding category as foliar spray applications gain traction in drought-prone growing regions. Seed treatment applications concentrate margin pools through premium pricing tied to proprietary microbe-strain coatings, whereas soil treatment volumes anchor the tonnage base across broadacre operations.
The EPA regulates biopesticide efficacy and toxicity thresholds under FIFRA, while USDA organic certification standards shape permissible input lists for certified operations, and Health Canada's PMRA maintains parallel review timelines that influence cross-border product development priorities. The FDA's residue monitoring protocols for food commodities indirectly steer biological adoption rates among export-oriented growers. Stakeholders must monitor pending revisions to EPA data requirements for microbial products, as these determinations will reshape registration economics and competitive moats.
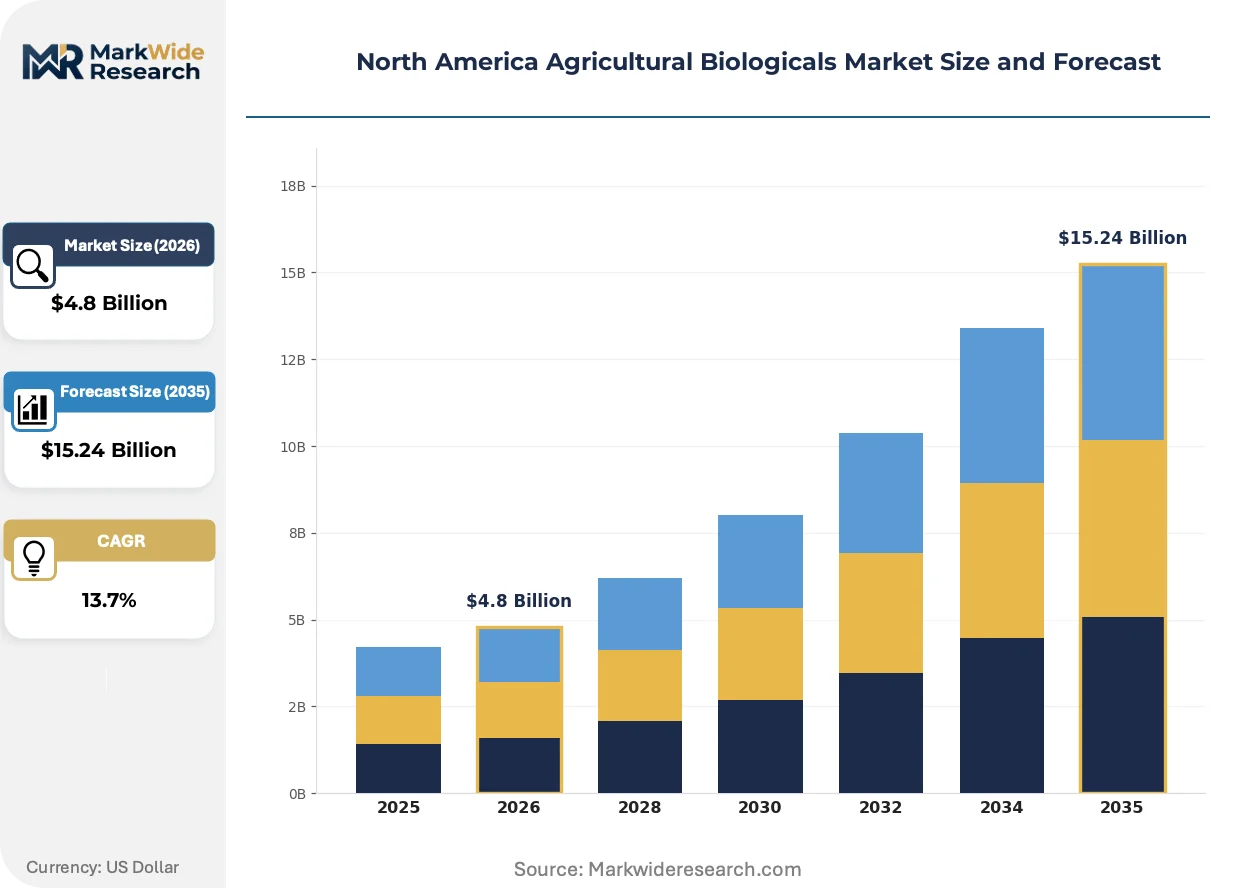
Market Dynamics
The EPA's compressed biopesticide registration timelines are restructuring competitive entry economics, enabling smaller microbial discovery firms to challenge incumbent shelf-space dominance in North American agricultural retail channels.
Growth Catalysts
- Streamlined EPA Pathways:The agency's reduced data requirements for microbial active ingredients are collapsing registration costs for novel biological pesticides.
- Specialty Crop Expansion:California and Florida growers are scaling foliar biostimulant programs across high-value permanent crops.
- Residue Exemption Protocols:USDA organic certification standards are expanding permissible biological input lists for export-oriented operations.
Market Restraints
- Live Culture Supply Concentration:North American fermentation capacity for colony-forming unit production concentrates in Great Lakes contract manufacturers.
- Formulation Stability Limits:Microbial shelf-life constraints above 10^8 CFU per milliliter restrict distribution radius and inventory cycles.
- Synthetic Fertilizer Substitution:Ammonia price volatility creates intermittent cost advantages that stall biological fertility adoption in corn-soy rotations.
Strategic Opportunities
- Midwest Row-Crop Penetration:Illinois and Iowa soybean acres remain underpenetrated for seed-treatment biological coatings relative to specialty crop benchmarks.
- Enzyme-Synthetic Convergence:Novozymes-style enzyme platforms paired with precision application hardware enable variable-rate biostimulant deployment.
- Retailer Private Label:Agricultural cooperatives are developing captive biological brands to capture margin pools from proprietary microbe-strain formulations.
Industry Challenges
- Microbiologist Talent Scarcity:Strain characterization and fermentation optimization expertise concentrates in limited academic and corporate research centers.
- Cross-Border Registration Divergence:Health Canada's PMRA maintains parallel but non-identical review timelines that fragment product launch sequencing.
- Legacy Equipment Compatibility:Existing spray tank cleanout protocols designed for synthetic chemistries degrade live microbial inoculum viability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Agricultural Biologicals Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.24 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biofertilizers, Biopesticides, Biostimulants, Microbial Products End Use Industry: Crops, Horticulture, Turf & Ornamentals, Specialty Plants Application: Soil Treatment, Seed Treatment, Foliar Spray, Post-Harvest Treatment Distribution Channel: Direct Sales, Retail, Wholesale, E-commerce |
| Companies Covered | Syngenta Group, Valent BioSciences, Corteva Agriscience, Novozymes A/S, Marrone Bio Innovations, Bayer AG, FMC Corporation, Lallemand Inc., BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Agricultural Biologicals Market Trends and Innovations
Biological formulation science is converging with digital agriculture infrastructure, compressing the gap between microbial discovery and field-scale deployment across North American production agriculture.
RNA interference biopesticides are electrifying pest management protocols by enabling species-specific suppression without non-target organism impact. Specialty vegetable growers in California's Central Valley are piloting these platforms at commercial scale this growing season. The technology is electrifying R&D yield expectations by collapsing the timeline between target identification and field efficacy demonstration.
The EPA's evolving data requirements for microbial products are reshaping registration dossier preparation costs. Reduced mammalian toxicity study mandates are redirecting development budgets toward field efficacy trials. Corn and soybean seed treatment segments are responding fastest, with several pipeline candidates advancing under the streamlined framework.
Buyer consolidation among agricultural retailers is compressing supplier negotiation leverage. Independent biological manufacturers now face centralized procurement committees at major cooperatives. This concentration is most visible across the U.S. Midwest, where three buying groups control access to the majority of row-crop acreage.
North America Agricultural Biologicals Market Segmentation
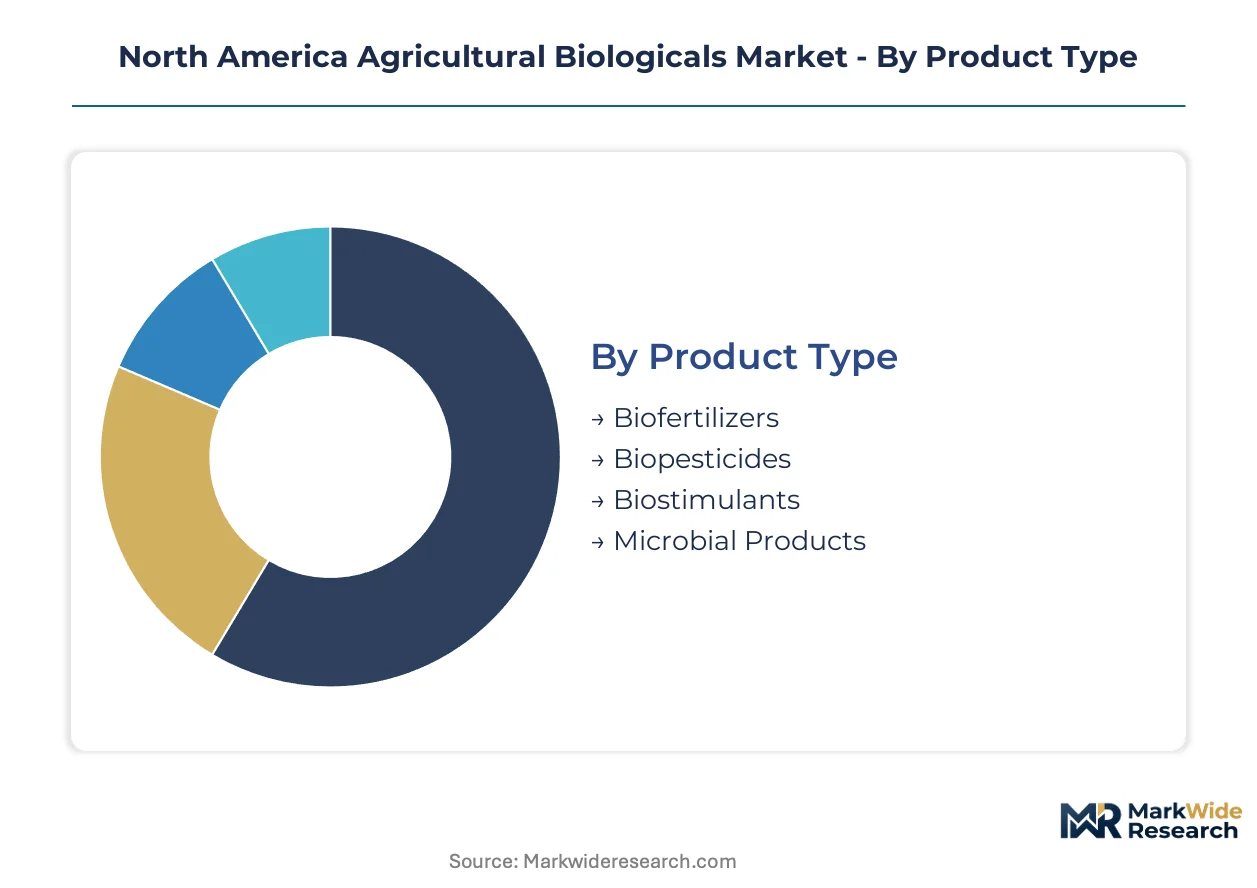
Segmentation in agricultural biologicals reveals how growers prioritize efficacy assurance, residue compliance, and application compatibility when selecting inputs. Purchase decisions diverge sharply between broadacre commodity producers and high-value specialty crop operators across the U.S. and Canada.
Product Type:
Cost tier structures the procurement calculus, with premium microbial formulations commanding shelf space against commodity-priced alternatives.
- Biopesticides:These living organism-based pest control agents, typically formulated at colony-forming units exceeding 10^8 per milliliter, dominate revenue pools due to established EPA residue exemption protocols and grower familiarity. Demand concentrates in California specialty vegetable operations and Florida citrus groves where export certification requirements drive biological preference over synthetic chemistries.
- Biostimulants:Enzyme and metabolite formulations that enhance nutrient uptake efficiency and abiotic stress tolerance represent the category climbing fastest, with foliar spray applications gaining particular traction across drought-prone Texas High Plains and Nebraska dryland corn acres where irrigation constraints amplify plant stress.
- Biofertilizers:Nitrogen-fixing and phosphate-solubilizing microbial inoculants anchor volume in Midwest soybean rotations where Bradyrhizobium seed treatments have achieved near-ubiquitous adoption.
- Microbial Products:Multi-strain consortia targeting soil health restoration concentrate in degraded acreage reclamation projects across the U.S. Southern Plains.
Volume sits with Biopesticides; growth tilts toward Biostimulants.
End Use Industry:
Application complexity and price sensitivity separate customer archetypes, with permanent crop operators accepting premium biological pricing against annual crop commodity economics.
- Crops:Row-crop corn, soybean, and wheat operations across Illinois, Iowa, and Indiana represent the tonnage foundation, with seed treatment biologicals achieving systematic penetration through bundled pricing with proprietary genetics.
- Horticulture:High-value fruit and vegetable production in California's Central Valley, Florida's Everglades Agricultural Area, and British Columbia's Fraser Valley drives premium biological adoption where labor-intensive scouting justifies input investment.
- Specialty Plants:Nursery stock and propagation operations in Oregon's Willamette Valley and Ontario's Niagara Peninsula concentrate demand for disease-suppressive microbial inoculants.
- Turf & Ornamentals:Golf course superintendents and landscape contractors across Arizona, Texas, and Southern California sustain niche volumes for aesthetic-quality biological maintenance programs.
Revenue concentrates in Crops; margin expansion tilts toward Horticulture.
Application:
Equipment compatibility and labor timing determine adoption sequencing, with existing farm infrastructure either accelerating or blocking biological deployment.
- Seed Treatment:Proprietary microbe-strain coatings applied at commercial conditioning facilities or on-farm capture margin pools through premium pricing tied to performance guarantees, with Illinois and Iowa soybean acres remaining underpenetrated relative to specialty crop benchmarks.
- Foliar Spray:Aerial and ground rig applications of biostimulants during critical growth stages concentrate in drought-prone regions where abiotic stress mitigation delivers visible yield protection.
- Soil Treatment:Pre-plant inoculum applications anchor volume across broadacre operations where equipment pass efficiency favors bulk delivery over precision placement.
- Post-Harvest Treatment:Biological coatings for storage disease suppression sustain limited adoption in potato and apple storage facilities across Washington State and New York's Hudson Valley.
Volume sits with Soil Treatment; value capture tilts toward Seed Treatment.
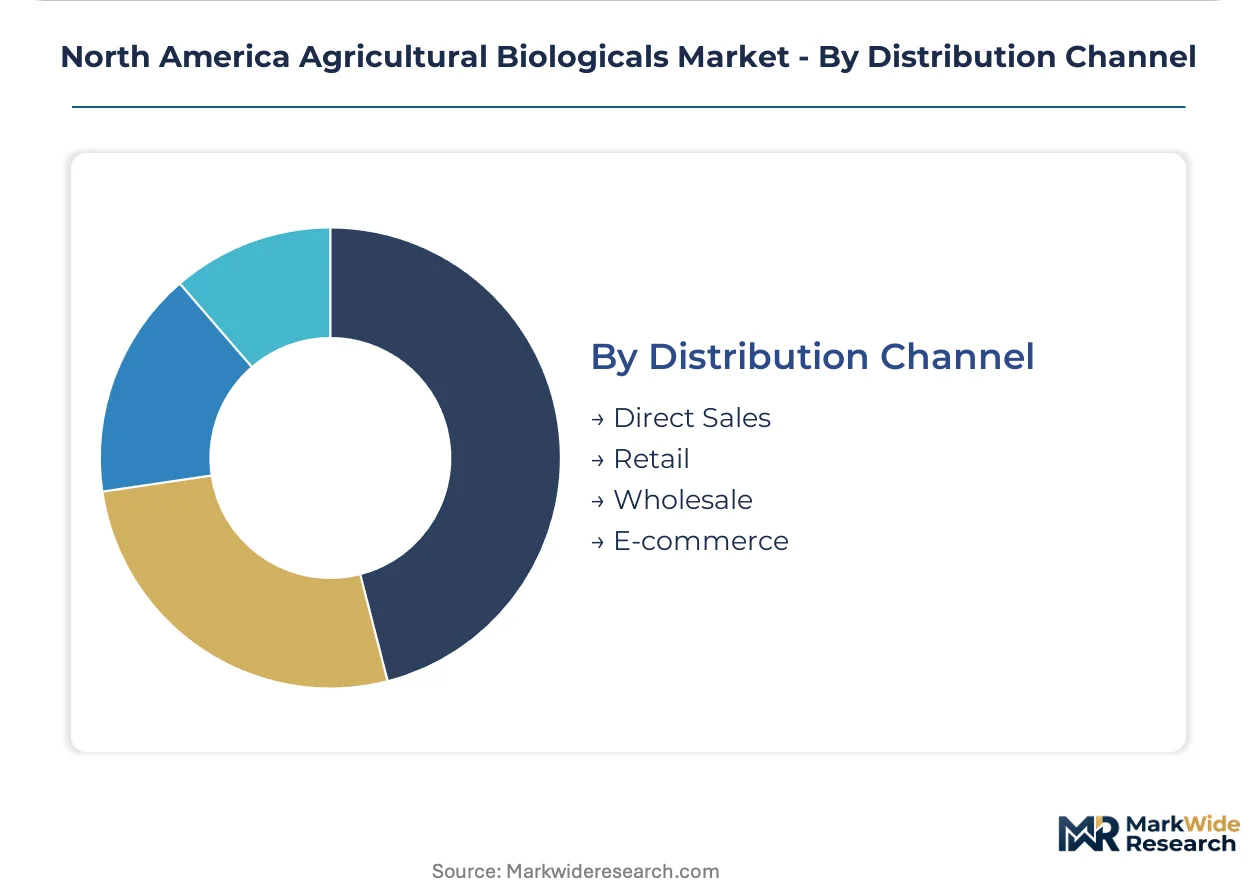
Distribution Channel:
Customer scale and technical service requirements fragment procurement pathways, with consolidation among agricultural retailers restructuring supplier access.
- Retail:Agricultural cooperatives and independent dealers across the U.S. Midwest control the majority of row-crop acreage access, with three buying groups centralizing procurement committee leverage over biological suppliers.
- Direct Sales:Large-scale specialty crop operations in California and Florida negotiate direct manufacturer relationships for volume pricing and technical support.
- Wholesale:Regional distributors serving smaller independent retailers concentrate inventory risk in Great Lakes fermentation capacity corridors.
- E-commerce:Direct-to-grower platforms gain traction among hobbyist and small-acreage producers in Texas and Florida seeking bypass pricing.
Volume sits with Retail; margin pressure concentrates in Wholesale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Research Triangle Park and the Great Lakes fermentation corridor concentrate North American biological manufacturing capacity. USDA conservation incentive programs and EPA biopesticide registration pathways drive regional investment patterns. State-level organic agriculture expansion targets shape demand concentration.
United States
Midwest corn-soybean rotations anchor volume demand for seed-treatment biologicals across Illinois, Iowa, and Indiana. EPA streamlined biopesticide registration under FIFRA reduces data requirements for microbial active ingredients. California's Central Valley specialty vegetable growers pilot RNA interference biopesticides at commercial scale this season.
Canada
Prairie province canola and pulse growers expand rhizobial inoculant adoption for nitrogen fixation. Health Canada's PMRA maintains parallel review timelines with EPA that influence cross-border product launch sequencing. Ontario's Guelph-Waterloo corridor concentrates microbial strain characterization and fermentation optimization expertise.
Mexico
Export-oriented fruit and vegetable operations in Sinaloa and Baja California drive biological pesticide demand for residue compliance. SADER's alignment with USDA organic certification standards expands permissible input lists for certified operations. Jalisco's agro-industrial cluster around Guadalajara hosts formulation tolling capacity for North American distribution.
North America Agricultural Biologicals Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across shelf-space and R&D yield dimensions. The vendor base structures around three tiers: integrated agrochemical majors with seed-and-biological pipelines, dedicated microbial discovery platforms, and contract fermentation manufacturers supplying active ingredients. Consolidation among agricultural retailers compresses supplier negotiation leverage. Strategic moves concentrate on proprietary microbe-strain acquisitions and precision application technology partnerships.
Within the integrated-major tier, Syngenta Group and Corteva Agriscience anchor competitive positioning through captive seed distribution channels. Novozymes A/S exemplifies the enzyme-platform specialist archetype, extending technical leadership into North American row-crop programs. These three entities represent divergent pathways to biological market participation: bundled genetics, microbe discovery, and enzymatic formulation science.
| Leading Market Players |
|---|
| Syngenta Group |
| Valent BioSciences |
| Corteva Agriscience |
| Novozymes A/S |
| Marrone Bio Innovations |
| Bayer AG |
| FMC Corporation |
| Lallemand Inc. |
| BASF SE |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up contract fermentation specialists have consolidated Great Lakes manufacturing capacity, tightening input pricing discipline while compressing margin pools for independent biological formulators competing against captive supply chains.
Pricing Analysis
Short lead-time premiums dominate microbial procurement, with California specialty crop growers paying substantial markups for expedited CFU production against standard-cycle Illinois row-crop contracts. Three-tier pricing structure across premium, standard, and economy levels separates guaranteed-performance seed treatments from commodity bulk inoculants. Pricing pressure stems from retailer buying group consolidation, which is forcing volume discounts. Commodity corn-soybean operators exhibit highest price sensitivity; organic-certified specialty growers show lowest.
Supply Chain Analysis
EPA biopesticide registration and USDA organic certification gating requirements concentrate qualified supply in United States, Canada, and Mexico manufacturing corridors. Active ingredient production draws from Great Lakes fermentation capacity, California formulation tolling, and Jalisco agro-industrial clustering. Single-source vulnerability runs through concentrated CFU fermentation infrastructure. Distribution runs through agricultural cooperative retail networks controlling Midwest acreage access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biological input markets are consolidating as retailer procurement centralization eliminates sub-scale formulators lacking captive fermentation or seed-channel integration.
For Market Incumbents: Deploy proprietary microbe-strain patent walls to lock in seed-treatment premium positioning against generic inoculant commoditization. Acquire distressed fermentation capacity in the Great Lakes corridor to secure CFU supply independence from tolling relationships. Channel control through exclusive retailer shelf-space agreements represents the critical defensive lever against emerging microbial discovery platforms. For New Entrants and Emerging Players: EPA streamlined biopesticide registration in the United States opens a window for novel RNA interference platforms to bypass incumbent microbe-strain patent thickets. Target Illinois and Iowa soybean seed-treatment white space where biological penetration lags specialty crop benchmarks. Pursue direct-to-grower technical service models that bypass consolidated cooperative procurement committees. For Investors and Strategic Acquirers: Distressed-cycle entries focus on enzyme-platform specialists with Novozymes-style precision application partnerships in drought-prone Texas and Nebraska territories. Long-term viability hinges on convergence with digital agriculture infrastructure rather than standalone biological efficacy. Watch EPA microbial data requirement revisions as the inflection signal for registration cost restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Microbe-Strain Acquisition | Captures patent-protected seed-treatment premium pools across Illinois and Iowa soybean rotations. |
| Precision Application Technology Partnership | Enables variable-rate biostimulant deployment through Novozymes-style enzyme platform integration. |
| Retailer Private Label Development | Agricultural cooperatives capture margin pools from proprietary formulations via captive branding. |
| Fermentation Capacity Expansion | Reduces single-source vulnerability in Great Lakes CFU production corridors for microbial inputs. |
| RNA Interference Pipeline Advancement | California Central Valley specialty vegetable pilots validate species-specific pest suppression protocols. |
Research Methodology
EPA registration filings, USDA organic certification databases, and Health Canada PMRA submissions formed the secondary backbone, cross-referenced with primary interviews of microbial discovery scientists, agricultural cooperative procurement directors, and seed-treatment facility managers. Bottom-up triangulation against top-down acreage penetration estimates validated volume assumptions.
Bottom-up modeling segmented the market by product type, end-use crop category, application method, and distribution channel across the projection horizon. CAGRs derived from historical EPA approval velocity and organic acreage expansion trajectories. Forecast inputs incorporated drought-frequency indices for biostimulant demand elasticity and retailer consolidation pace for pricing power shifts.
The model assumes a particular technology adoption path; alternative pathways for RNA interference biopesticides would alter the outlook. Forecasts reflect assumptions regarding EPA data requirement stability and fermentation capacity expansion timing. A model refresh is warranted upon material change in retailer buying group consolidation velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bio-Agriculture
Biocontrol Agents Market
Bio-Agriculture
Europe Biostimulants Market
Bio-Agriculture
German Biopesticides Market
Bio-Agriculture
Biochar Market
Bio-Agriculture
China Biopesticides Market
Bio-Agriculture
Bio-Seeds Market
Bio-Agriculture
Africa Biofertilizer Market
Bio-Agriculture
Global Feed Phytogenics Market
Bio-Agriculture
United States Bio-Fungicide Market
Bio-Agriculture
India Biopesticides Market
Bio-Agriculture
South America Biological Organic Fertilizers Market
Bio-Agriculture
Japan Biofertilizer Market
Bio-Agriculture
Asia-Pacific Biofertilizers Market
Bio-Agriculture
Asia-Pacific Bio-Ethanol Market
Bio-Agriculture
United States Biopesticides Market
Bio-Agriculture
United States Agricultural Biologicals Market