
 Global Biofungicides Market | 2026-2036
Global Biofungicides Market Size, Share, and Industry Trends Forecast 2026-2036
Global Biofungicides Market Analysis
North American microbial fermentation capacity is consolidating as contract manufacturers scale up submerged culture facilities for agricultural biocontrol agents. Bayer AG leverages its strain development platform to sustain leadership in Trichoderma-based formulations. BASF SE anchors its position through dedicated fermentation assets in Germany and the United States. Koppert Biological Systems specializes in live organism delivery systems for greenhouse applications.
Biofungicides comprise living microorganisms or their metabolites formulated to suppress plant pathogenic fungi through antibiosis, parasitism, or induced systemic resistance, typically requiring colony-forming unit counts exceeding 10^8 per milliliter for field efficacy. The agricultural application segment dominates volume as row-crop growers integrate Bacillus subtilis seed treatments into commodity production protocols. Bacteria-based products represent the fastest-expanding product type category, driven by shorter development cycles and broader spectrum activity against soilborne pathogens. Plant extracts occupy a premium niche where organic certification requirements command formulation prices above microbial alternatives.
The EPA regulates biofungicides under FIFRA with reduced data requirements compared to synthetic chemistry, while the EU's 1107/2009 regulation governs microorganism-based plant protection products through mutual recognition procedures. India's Central Insecticides Board mandates registration under the Insecticides Act for all biocontrol agents entering commercial distribution. Stakeholders must monitor evolving residue tolerance policies in import-dependent markets where maximum residue limits for biological inputs remain unsettled.
Market Dynamics
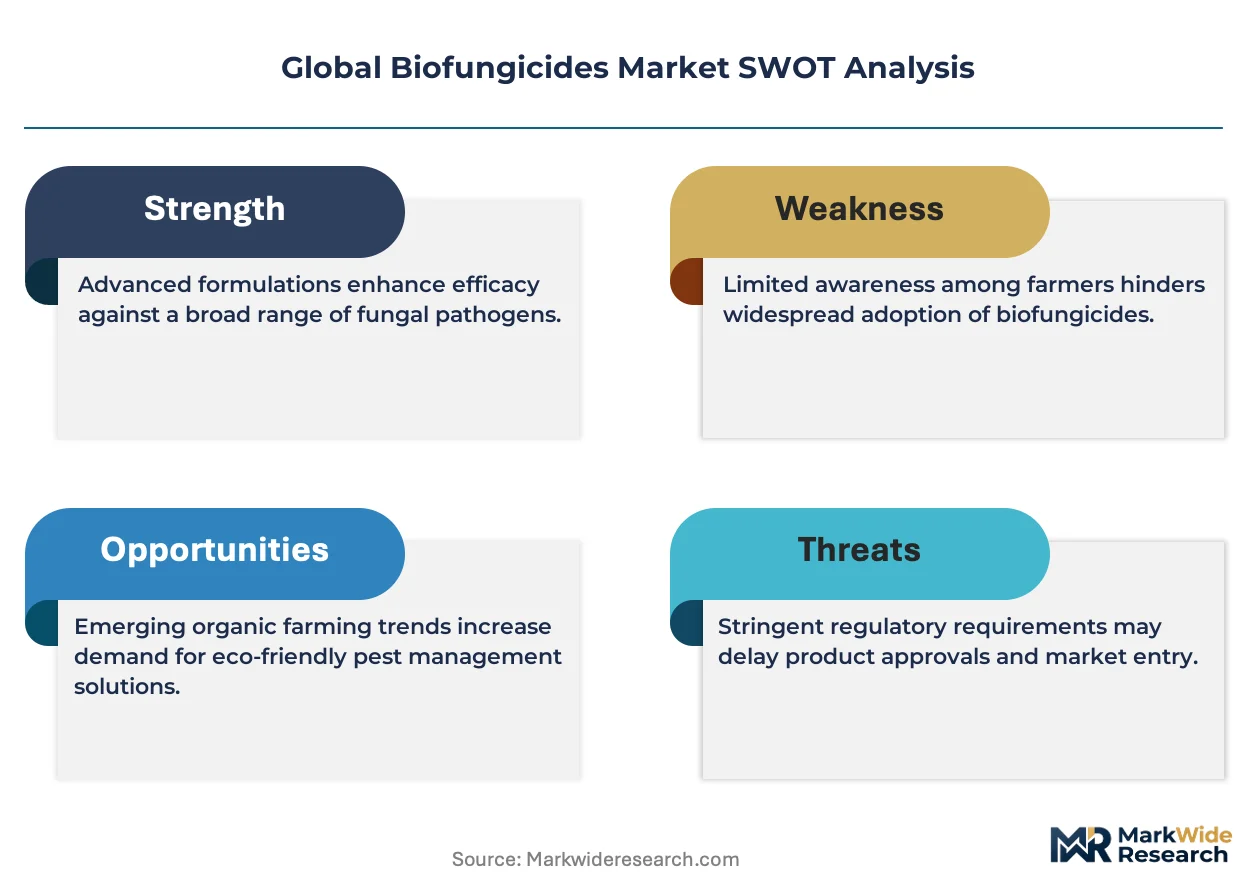
EU Green Deal's Farm to Fork strategy is forcing synthetic fungicide displacement across European specialty crop production, redirecting R&D investment toward microbial fermentation platforms and live organism delivery systems.
Growth Catalysts
- EU 1107/2009 Regulation:Accelerated approval pathways for microorganism-based plant protection products reduce time-to-market for biocontrol developers, stimulating pipeline investment.
- Brazil Soybean Belt:Expanding resistance to synthetic strobilurins in Asian soybean rust management is concentrating grower demand for Trichoderma harzianum seed treatments.
- Submerged Culture Fermentation:Advances in industrial-scale aerobic fermentation enable cost-competitive production of Bacillus subtilis formulations with colony-forming unit counts exceeding 10^9 per milliliter.
Market Restraints
- Cold Chain Dependency:Live microbial formulations require uninterrupted temperature-controlled distribution, limiting penetration in infrastructure-deficient regions of Sub-Saharan Africa and Central Asia.
- Input Cost Volatility:Fermentation-grade molasses and soy peptone prices fluctuate with commodity crop cycles, compressing margins for contract manufacturers in India and Brazil.
- Residue Uncertainty:Import-dependent markets including Japan and South Korea maintain unsettled maximum residue limits for biological inputs, creating regulatory friction for exporters.
Strategic Opportunities
- India Cotton Districts:Maharashtra and Gujarat growers face escalating Fusarium wilt pressure, creating white space for Pseudomonas fluorescens soil drench applications.
- Greenhouse Delivery Systems:Precision irrigation integration enables direct-to-root microbial inoculation in controlled-environment agriculture, bypassing foliar spray limitations.
- USDA Organic Certification:Premium pricing for certified organic produce sustains formulation price premiums 15-40% above conventional microbial alternatives.
Industry Challenges
- Strain Characterization Expertise:Shortage of taxonomists and molecular biologists delays species identification for novel biocontrol candidates, extending development timelines.
- Legacy Synthetic Integration:Row-crop agronomists lack training in biological product stewardship, creating adoption friction in commodity corn and wheat systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Biofungicides Market |
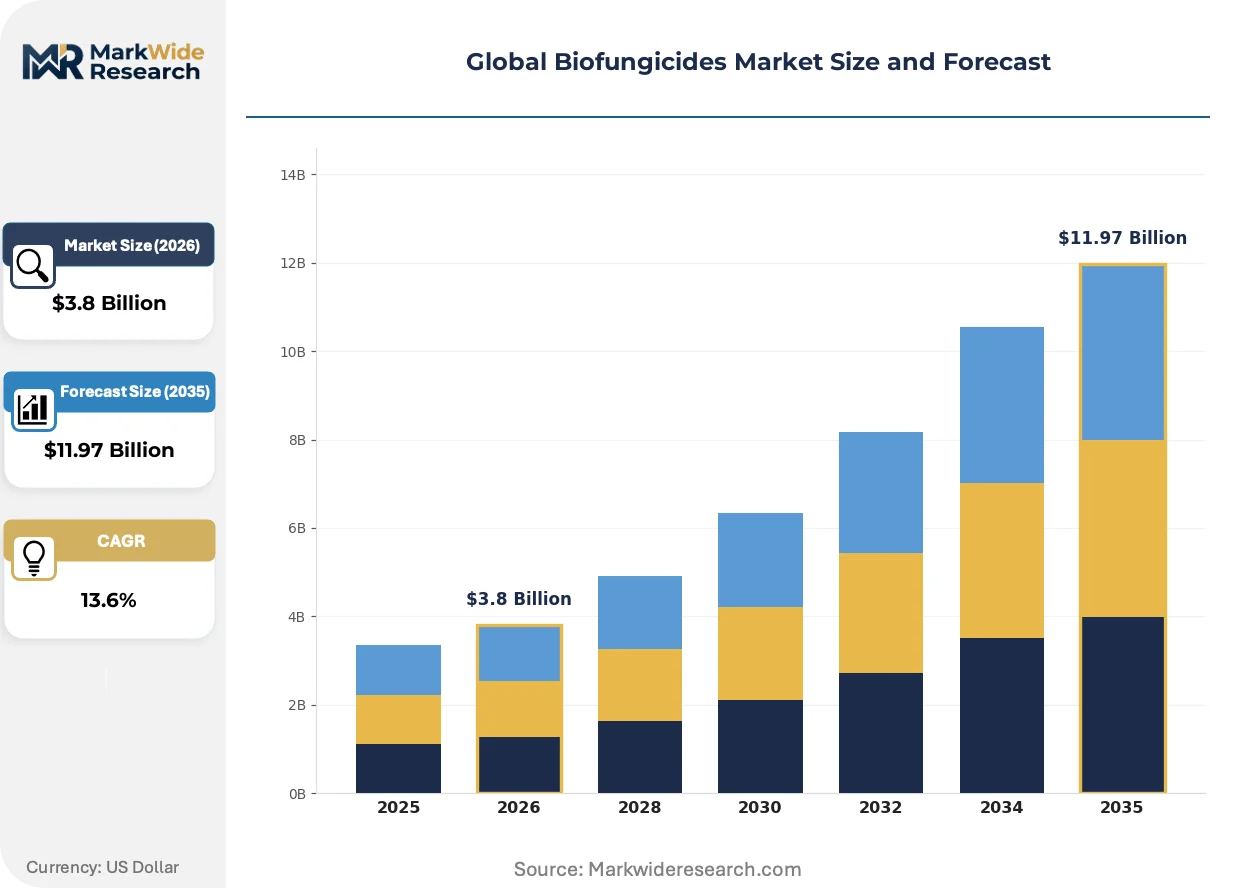
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $11.97 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fungi, Bacteria, Plant Extracts, Others Application: Agricultural, Horticultural, Turf and Ornamentals, Others End User: Farmers, Agricultural Cooperatives, Distributors, Agrochemical Companies Distribution Channel: Online, Offline, Retail, Wholesale |
| Companies Covered | Bayer AG, BASF SE, Syngenta AG, Corteva Agriscience, FMC Corporation, Marrone Bio Innovations, Koppert Biological Systems, UPL Limited, Bioceres Crop Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Biofungicides Market Emerging Trajectories
Formulation science is unifying previously incompatible microbial consortia with chemical stabilizers, enabling shelf-stable multi-strain products that expand addressable disease spectra beyond single-organism limitations.
Consortia engineering is unifying Bacillus and Trichoderma strains in single-tank fermentation processes, reducing production costs 20-30% versus sequential cultivation. Greenhouse operators in the Netherlands and Spain are adopting these formulations for soilless substrate applications. The technology is unifying disease suppression modes—combining antibiosis with induced systemic resistance—reducing grower need for tank-mix complexity.
REACH registration requirements for microbial metabolites are tightening analytical standards for secondary metabolite characterization across EU member states. German and French regulators now mandate complete genomic sequencing for strain-level identification in regulatory dossiers. Biocontrol developers are responding by establishing captive sequencing capabilities or partnering with academic microbiome laboratories.
Direct procurement from fermentation facilities is displacing traditional distributor networks among large-scale specialty crop cooperatives in California's Central Valley. These buyers now negotiate volume contracts specifying minimum viable cell counts at delivery, transferring quality risk upstream. The shift is most visible in strawberry and lettuce production systems where application timing windows compress to 48-72 hours post-harvest.
Global Biofungicides Market Segmentation
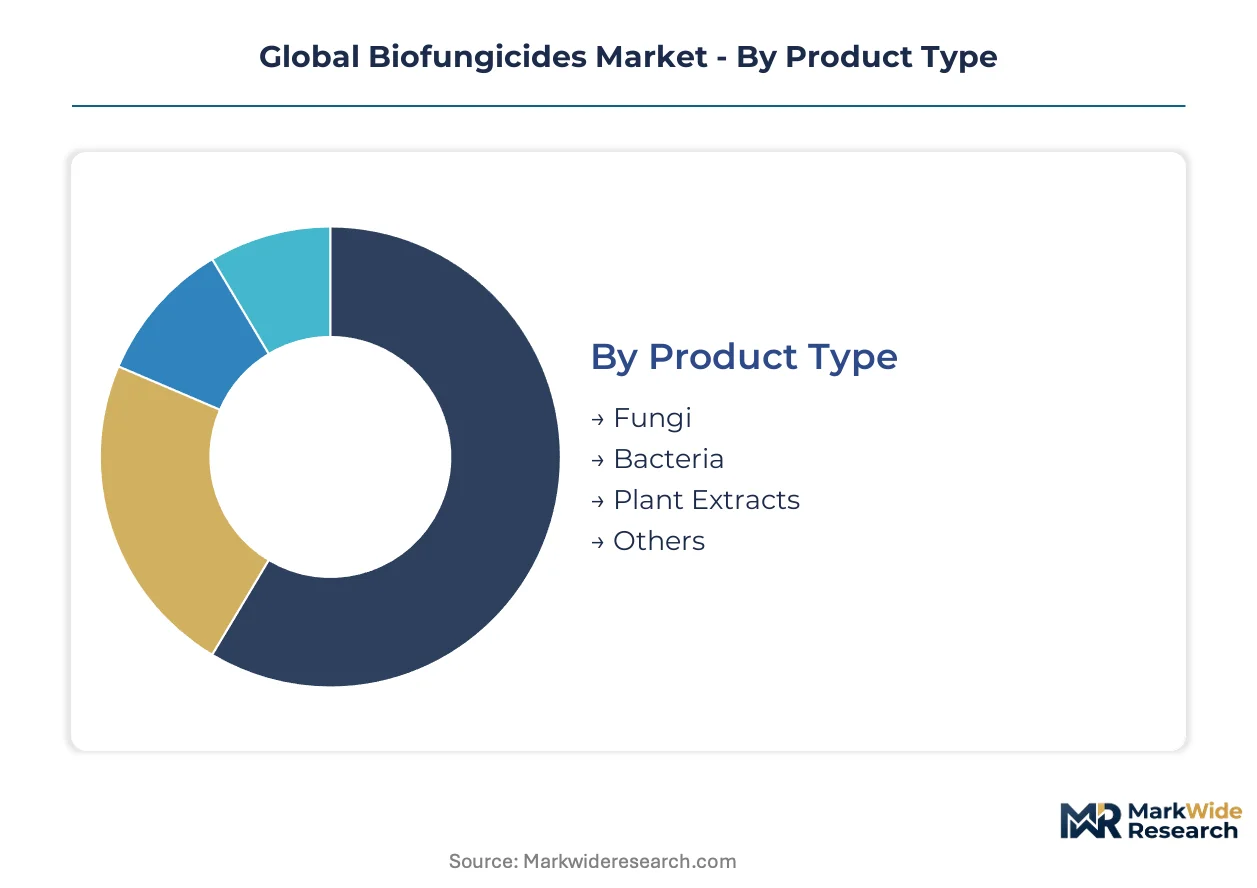
Segmentation in biofungicides reveals how formulation chemistry, application setting, and procurement channel each impose distinct technical and commercial requirements on suppliers. Buyers prioritize shelf stability, spectrum breadth, and integration complexity differently across these dimensions, fragmenting vendor strategies.
Product Type:
Bacteria-based formulations command the steepest R&D investment trajectories due to shorter strain development cycles and broader pathogen suppression spectra.
- Bacteria:Bacillus subtilis and Pseudomonas fluorescens dominate submerged fermentation output, with colony-forming unit specifications exceeding 10^9 per milliliter for field efficacy. Demand concentrates in Brazil's soybean belt where seed treatment protocols now integrate these organisms against Asian soybean rust resistance breakdown.
- Fungi:Trichoderma harzianum and Trichoderma asperellum formulations require dedicated solid-state fermentation infrastructure and longer production cycles. California strawberry growers in Monterey and Ventura counties anchor volume through soil drench applications against Fusarium and Verticillium complexes.
- Plant Extracts:Essential oil and alkaloid-based products from neem, thyme, and cinnamon sources occupy organic certification premiums in EU specialty crop markets.
- Others:Algal metabolites and viral biocontrol agents remain developmental, with limited commercial scale outside experimental greenhouse networks.
Volume sits with Bacteria; growth tilts toward Fungi as consortia engineering unifies both organism classes in single-tank processes.
Application:
Application setting determines formulation stability requirements, with controlled-environment agriculture permitting live organism delivery that open-field deployment cannot sustain.
- Agricultural:Row-crop seed treatment and soil inoculation protocols in commodity soybean, corn, and cotton systems. Maharashtra cotton districts in India drive expansion against escalating Fusarium wilt pressure.
- Horticultural:Greenhouse tomato, pepper, and cucumber production in the Netherlands and Spain integrates precision irrigation inoculation, bypassing foliar spray timing constraints.
- Turf and Ornamentals:Golf course and landscape maintenance in Florida and California requires fast-acting metabolite formulations with immediate knockdown rather than colonization-dependent suppression.
- Others:Forestry and post-harvest disease management occupy niche volumes with specialized registration pathways.
Agricultural applications anchor current revenue; horticultural deployment climbs fastest as controlled-environment agriculture expands substrate-based production.
End User:
Procurement scale and technical sophistication fragment buyer requirements, with large cooperatives demanding direct fermentation contracts that smaller operators cannot negotiate.
- Farmers:Individual growers in India's Gujarat and Maharashtra states purchase through distributor networks, prioritizing price accessibility over strain documentation.
- Agricultural Cooperatives:California Central Valley strawberry and lettuce cooperatives negotiate volume contracts specifying minimum viable cell counts at delivery, transferring quality risk upstream to fermentation facilities.
- Distributors:Inventory holding requirements and cold chain investment limit participation to regionally concentrated players with refrigerated logistics infrastructure.
- Agrochemical Companies:Multinational firms integrate biofungicide formulations into bundled crop protection portfolios, requiring regulatory dossier compatibility across multiple national jurisdictions.
Cooperative procurement concentrates volume; distributor channels face margin compression as direct sourcing accelerates.
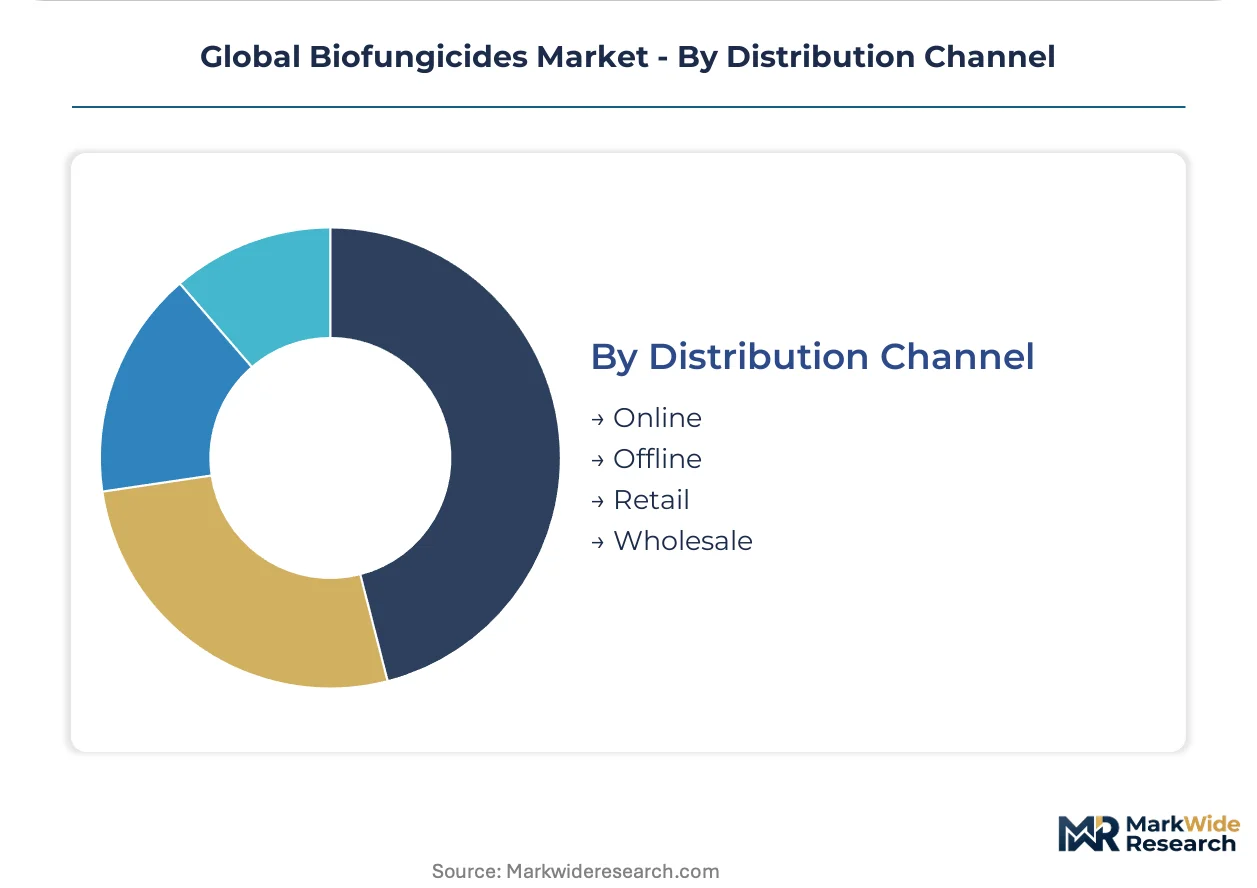
Distribution Channel:
Channel selection reflects cold chain capability and buyer technical confidence, with live organism formulations penalizing infrastructure-deficient routes.
- Offline:Agronomic service relationships dominate in Brazil's Mato Grosso and Goias soybean regions, where field advisors specify tank-mix protocols.
- Wholesale:Bulk fermentation output moves through dedicated biocontrol distributors with temperature-controlled warehousing in Germany and the United States.
- Retail:Garden center and farm supply outlets carry shelf-stable metabolite products with longer viability windows than live microbial alternatives.
- Online:Direct-to-grower platforms gain traction in data-rich specialty crop segments where application timing precision reduces agronomic support dependency.
Offline relationships retain volume leadership; online channels expand fastest where digital agronomy tools reduce in-person advisory requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fermentation-grade molasses from Brazil's sugarcane belt anchors regional supply economics, while India's soy peptone processors feed submerged culture facilities across Asia-Pacific and Europe.
United States
California's Central Valley strawberry cooperatives negotiate direct fermentation contracts specifying minimum viable cell counts. EPA regulates biofungicides under FIFRA with reduced data requirements versus synthetic chemistry. Monterey and Ventura counties anchor volume through soil drench applications against Fusarium and Verticillium complexes.
Brazil
Soybean belt growers face expanding resistance to synthetic strobilurins in Asian soybean rust management. ANVISA oversees registration of microorganism-based plant protection products through accelerated pathways. Mato Grosso and Goias field advisors specify tank-mix protocols integrating Trichoderma harzianum seed treatments.
Germany
EU Green Deal's Farm to Fork strategy forces synthetic fungicide displacement across specialty crop production. ECHA mandates complete genomic sequencing for strain-level identification in regulatory dossiers. BASF SE anchors position through dedicated fermentation assets serving European demand.
India
Maharashtra and Gujarat cotton growers face escalating Fusarium wilt pressure creating demand for Pseudomonas fluorescens soil drench applications. Central Insecticides Board mandates registration under the Insecticides Act for all biocontrol agents. Gujarat individual growers purchase through distributor networks prioritizing price accessibility.
Netherlands
Greenhouse tomato, pepper, and cucumber producers integrate precision irrigation inoculation bypassing foliar spray timing constraints. EU 1107/2009 regulation governs microorganism-based products through mutual recognition procedures. Koppert Biological Systems specializes in live organism delivery systems for controlled-environment agriculture.
Global Biofungicides Market Vendor Landscape
Global majors compete with regional champions across fermentation capacity and strain development capabilities. The vendor base splits between multinational agrochemical conglomerates with captive biological platforms and dedicated biocontrol specialists with live organism delivery expertise. Three archetypes dominate: integrated agrochemical giants, pure-play microbial fermentation specialists, and greenhouse-focused live organism suppliers. Competitive moves concentrate on consortia engineering partnerships and direct procurement contract capture with large-scale cooperatives.
Among integrated agrochemical conglomerates, Bayer AG and BASF SE exemplify the fermentation-asset-heavy archetype, while Koppert Biological Systems occupies a position within the live organism delivery specialist tier. These three entities represent contrasting strategic postures: strain development platform leverage, dedicated fermentation infrastructure control, and precision application system integration respectively.
| Leading Market Players |
|---|
| Bayer AG |
| BASF SE |
| Syngenta AG |
| Corteva Agriscience |
| FMC Corporation |
| Marrone Bio Innovations |
| Koppert Biological Systems |
| UPL Limited |
| Bioceres Crop Solutions |
| Others |
Supply Flow & Price Mechanics
Molecular taxonomists and fermentation specialists in Germany's Rhineland region command wage premiums that widen pricing spreads between premium consortia formulations and economy-grade single-strain alternatives. Labor-cost differentials between European strain-characterization hubs and Indian contract manufacturing centers translate into tiered procurement options for buyers with varying technical documentation requirements.
Pricing Analysis
Warranty-backed viability guarantees separate premium formulations from unbundled commodity alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and genomic documentation depth. Price differentiation hinges on strain-level sequencing completeness versus genus-level identification. Cost compression in economy tiers is intensifying because Brazilian and Indian contract manufacturers compete on fermentation-scale efficiency. Agricultural cooperatives in California's Central Valley exhibit lowest price sensitivity due to direct-contract quality specifications, while individual cotton growers in Gujarat prioritize accessible distributor pricing over documentation rigor.
Supply Chain Analysis
Reverse-logistics networks for expired live microbial formulations remain underdeveloped, creating disposal cost externalities that manufacturers increasingly internalize. Supply concentrates in Brazil's sugarcane belt for fermentation-grade molasses, Germany for precision strain-engineering infrastructure, and India for soy peptone processing. Raw material flows draw from agricultural commodity cycles, with inputs tethered to sugar and soybean market volatility. Single-source vulnerability runs through cold-chain distribution partners in infrastructure-deficient regions. Distribution runs through dedicated biocontrol wholesalers with temperature-controlled warehousing in Germany and the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The biofungicides sector is consolidating around captive fermentation capacity and direct-to-grower procurement relationships. Players are racing to secure submerged-culture infrastructure and genomic sequencing capabilities as vertical-integration levers.
For Market Incumbents: Lock in strain-banking advantages by acquiring regional fermentation facilities in Brazil and India before contract manufacturers consolidate. Prioritize consortia-engineering R&D to extend patent-protected formulation moats against generic single-strain competitors. Bayer AG and BASF SE already anchor positions through dedicated assets; laggards risk exclusion from direct-procurement negotiations with California strawberry cooperatives. For New Entrants and Emerging Players: CRISPR-guided strain optimization offers a technology-first wedge against legacy fermentation specialists with longer development cycles. Target India's Maharashtra cotton districts where escalating Fusarium wilt pressure outpaces established supplier capacity. Pursue greenhouse delivery system partnerships with Dutch and Spanish precision-irrigation providers to bypass foliar-spray timing limitations that constrain open-field competitors. For Investors and Strategic Acquirers: Re-rating potential sits with pure-play microbial fermentation specialists given EU regulatory tightening on genomic documentation requirements. Long-term viability favors operators with captive sequencing capabilities or exclusive academic microbiome laboratory partnerships. Monitor ANVISA registration acceleration in Brazil and ECHA metabolite-characterization mandates as inflection indicators for acquisition timing.| Strategic Initiative | Industry Significance |
|---|---|
| Consortia Engineering Partnership | Unifying Bacillus and Trichoderma strains reduces production costs 20-30% versus sequential cultivation. |
| Direct Fermentation Contracting | California Central Valley cooperatives now specify minimum viable cell counts at delivery, transferring quality risk upstream. |
| Genomic Sequencing Captivity | German and French regulators mandate complete strain-level identification, favoring operators with in-house capabilities. |
| Greenhouse Delivery System Integration | Precision irrigation inoculation in Dutch and Spanish controlled-environment agriculture bypasses foliar spray limitations. |
| Cold Chain Infrastructure Expansion | Temperature-controlled distribution networks unlock penetration in Sub-Saharan Africa and Central Asia markets. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this biofungicides market analysis. Primary interviews with fermentation facility managers, strain development scientists, agricultural cooperative procurement officers, and greenhouse operations directors complemented documentary sources. EPA FIFRA registration databases, EU 1107/2009 mutual recognition records, and Indian Central Insecticides Board filings provided regulatory trajectory inputs. Bottom-up strain-level production estimates and top-down agricultural input expenditure patterns were triangulated to validate volume assumptions.
Granularity-level modeling distinguished bacteria-based, fungi-based, plant extract, and algal metabolite product categories at the formulation chemistry dimension. Agricultural, horticultural, turf and ornamentals, and forestry applications were modeled separately with distinct shelf-stability and delivery-system requirements. End-user segmentation captured farmer, cooperative, distributor, and agrochemical company procurement behaviors. CAGRs were derived from segment-level growth rate synthesis across the projection horizon. Fermentation-grade molasses and soy peptone price indices, alongside cold-chain logistics cost structures, informed input-cost sensitivity analysis.
Several conditions sit outside the modeled scope, including unforeseen regulatory reversals on biological input residue tolerances in Japan and South Korea, and breakthrough synthetic fungicide resistance-management protocols that could slow grower transition. Forecasts reflect assumptions about continued EU Green Deal implementation pace and Brazilian soybean rust resistance trajectories. Practitioners should monitor ANVISA registration processing times and ECHA metabolite-characterization enforcement intensity for early signals of competitive repositioning requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bio-Agriculture
United Kingdom Biopesticides Market
Bio-Agriculture
Bioherbicides Market
Bio-Agriculture
Biopesticides Market
Bio-Agriculture
India Biostimulants Market
Bio-Agriculture
Microphytes Market
Bio-Agriculture
Hydroponics Market
Bio-Agriculture
Canada Biofertilizers Market
Bio-Agriculture
Germany Biostimulants and Biopesticides Market
Bio-Agriculture
China Biocontrol Agents Market
Bio-Agriculture
China Biofertilizer Market
Bio-Agriculture
Australia Biopesticides Market
Bio-Agriculture
Asia-Pacific Bio-Ethanol Market
Bio-Agriculture
Global Bio-Organic Acid Market
Bio-Agriculture
Italy Biopesticides Market
Bio-Agriculture
North America Agricultural Biologicals Market
Bio-Agriculture
Japan Biofertilizer Market