
 Inulin Market | 2026-2036
Inulin Market Size, Share, and Industry Trends Forecast 2026-2036
Inulin Market Analysis
Precision fermentation and enzymatic refinement is rewriting how inulin extracts achieve targeted degree of polymerization for specific functional roles. BENEO GmbH leverages its Belgian chicory root supply chain to sustain long-chain inulin output for bakery applications. Suedzucker AG anchors European volume through integrated agricultural processing across multiple crop sources. Cosucra Groupe Warcoing SA specializes in organic-certified grades that command premium positioning in French and German retail channels.
Inulin is a soluble dietary fiber composed primarily of fructose units linked by beta-(2,1) glycosidic bonds, typically extracted from chicory root through hot water diffusion followed by spray drying or chromatographic purification to achieve specific chain lengths. Its primary commercial purpose centers on replacing fat and sugar in processed foods while delivering prebiotic fermentation substrate for gut microbiota modulation. Powdered inulin dominates current formulation volumes due to its shelf stability and ease of dispersion in dry blends, though high-performance inulin with enhanced solubility profiles captures expanding share in beverage applications where clarity and mouthfeel standards are stringent. Chicory root remains the dominant agricultural source, with Jerusalem artichoke gaining traction among organic supply chains seeking rotation-crop diversification.
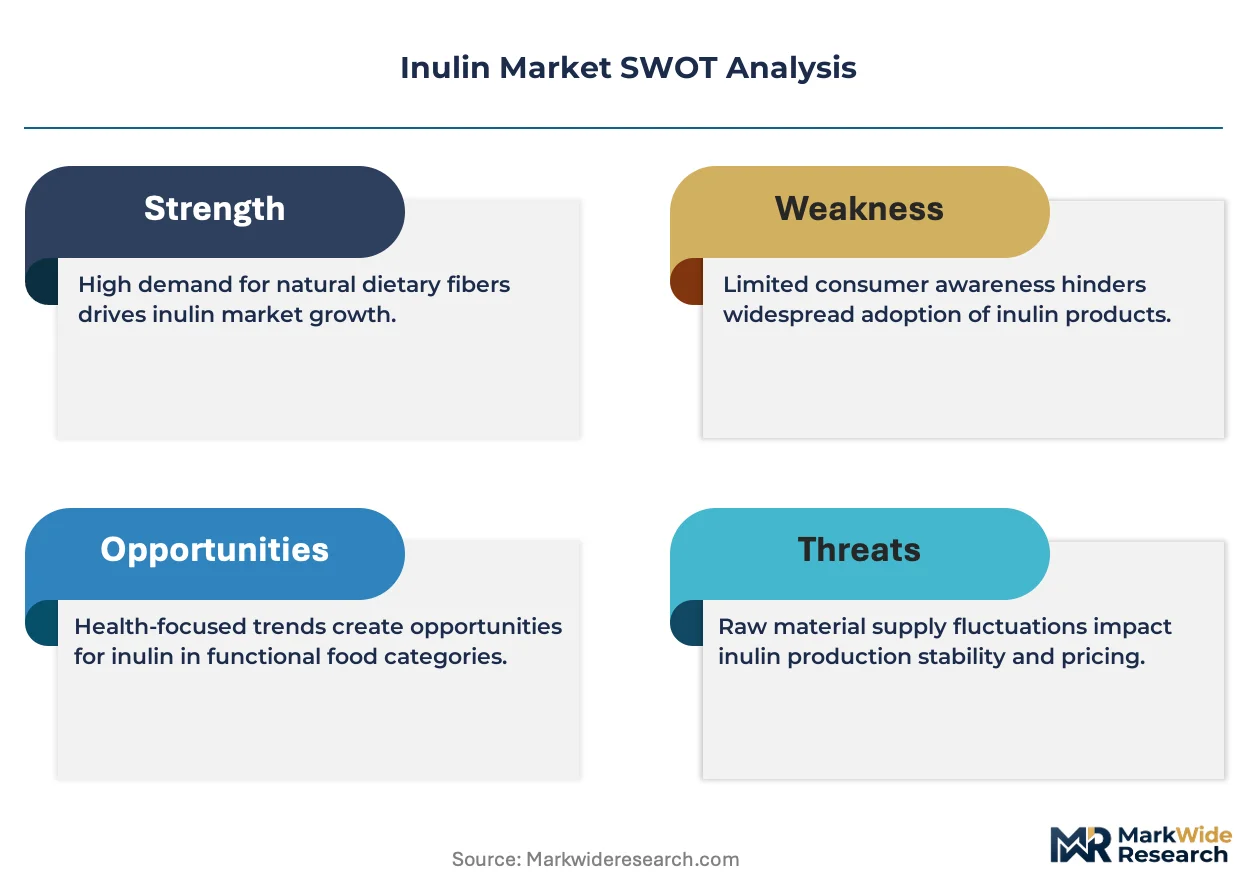
The European Food Safety Authority evaluates health claim substantiation under EU Regulation 1924/2006, directly determining which prebiotic and digestive health statements manufacturers may deploy on packaging. The U.S. Food and Drug Administration governs inulin's classification as dietary fiber in Nutrition Facts labeling, influencing formulation decisions for products targeting the American retail market. Stakeholders must monitor evolving fiber definition rulings and emerging microbiome clinical data to determine which polymer lengths and purity grades warrant capacity investment.
Market Dynamics
Chicory root supply concentration in Belgium and northern France creates structural dependency for long-chain inulin grades, forcing formulators to secure multi-year agricultural contracts or pivot to Jerusalem artichoke alternatives.
Growth Catalysts
- EU Nutrition and Health Claims Regulation:EFSA-approved prebiotic claims for chicory-derived inulin create label differentiation that commands retail shelf placement in German and French supermarkets.
- Precision fermentation:Enzymatic tailoring of degree of polymerization enables beverage-grade inulin with enhanced cold-water solubility, opening formulation access to ready-to-drink applications.
- Clean-label dairy alternatives:Oat and almond milk processors in the Netherlands and Denmark integrate inulin as fat-mimetic texture modulators to replace modified starches.
Market Restraints
- Chicory root monoculture risk:Belgian and French agricultural belts face climate volatility that threatens root yield consistency for long-chain extraction.
- Fructan purification cost structure:Chromatographic separation to achieve high-performance grades requires energy-intensive processing that compresses margin at mid-tier producers.
- Polydextrose substitution:Synthetic soluble fibers from corn-derived dextrose compete on price in cost-sensitive bakery applications where prebiotic claims carry less weight.
Strategic Opportunities
- Japanese functional foods channel:FOSHU (Foods for Specified Health Uses) approval pathway for prebiotic ingredients remains underexploited by European suppliers relative to domestic isomaltooligosaccharide producers.
- Regenerative agriculture certification:EU Green Deal soil health incentives reward chicory cultivation as deep-rooted rotation crop, creating premium positioning for carbon-negative supply chains.
- Pediatric nutrition fortification:Infant formula manufacturers seek clinically substantiated prebiotic fibers with established safety dossiers for gut microbiome establishment claims.
Industry Challenges
- Clinical substantiation capacity:EFSA health claim requirements demand human intervention studies that strain R&D budgets at specialized extractors without pharmaceutical pipelines.
- Organic certification lag:Three-year conversion timelines for chicory root prevent rapid scaling of organic-grade output to match retail channel commitments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Inulin Market |
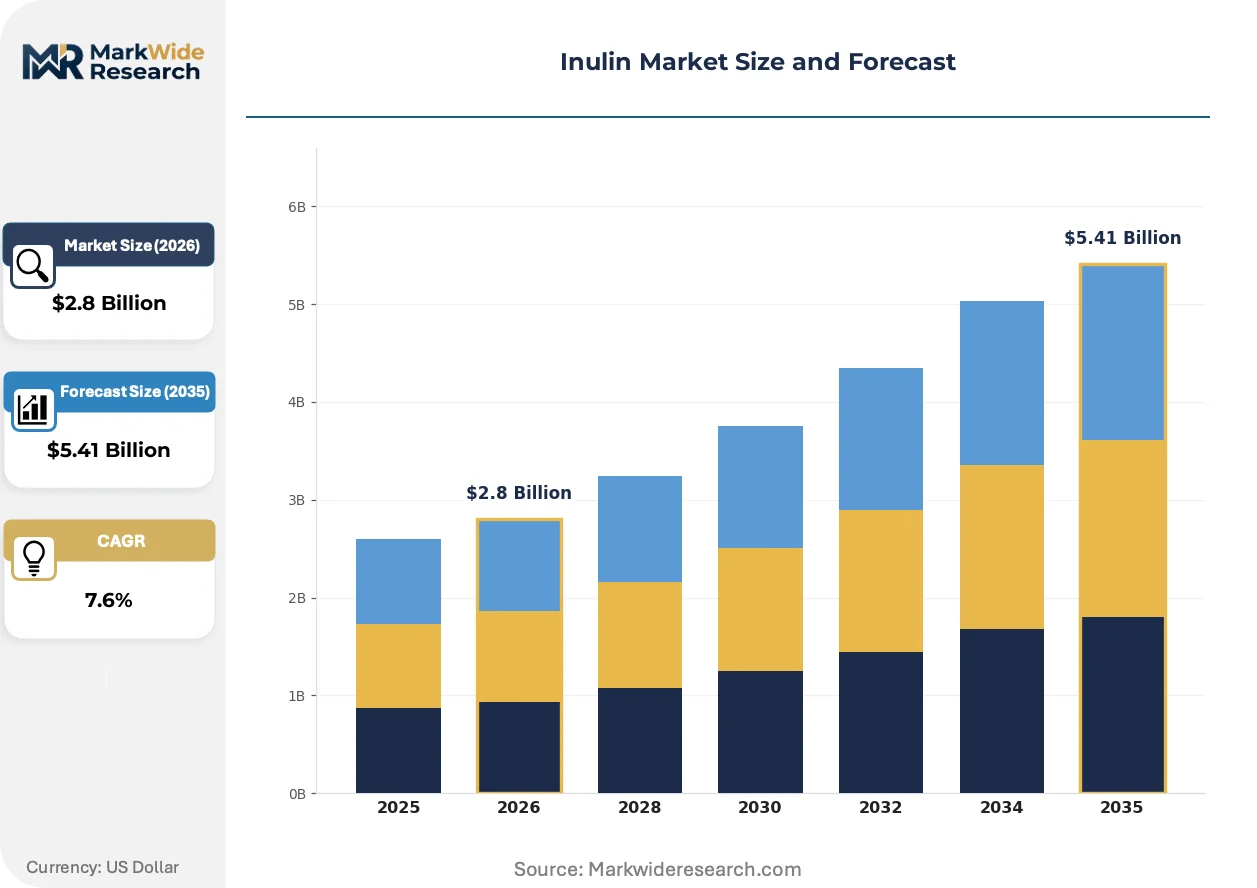
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.41 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Inulin, Powdered Inulin, Granulated Inulin, High-Performance Inulin End User: Food Industry, Pharmaceutical Sector, Nutraceuticals, Dietary Supplements Application: Baking Products, Dairy Alternatives, Nutritional Bars, Beverages Source: Chicory Root, Jerusalem Artichoke, Agave, Others |
| Companies Covered | Cosucra Groupe Warcoing SA, Suedzucker AG, BENEO GmbH, Kerry Group plc, Cooperative Royal Cosun U.A., Sensus Food Ingredients B.V., Ingredion Incorporated, Tereos Syral S.A.S., Cargill, Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Inulin Market Emerging Trajectories
Enzymatic refinement and bioprocessing advances are compressing the traditional extraction-to-formulation timeline, while regulatory clarity on fiber definitions forces ingredient suppliers to validate specific polymer lengths.
Membrane filtration technology paired with controlled enzymatic hydrolysis is rendering obsolete conventional spray-dried inulin for beverage applications. Ready-to-drink smoothie brands in California and São Paulo now specify sub-10 DP (degree of polymerization) grades that dissolve at refrigeration temperatures without turbidity. This specification shift compresses demand for standard powdered grades in premium liquid formulations.
EFSA's evolving interpretation of Article 13.5 health claims creates compliance complexity for prebiotic substantiation dossiers. Manufacturers must now demonstrate selective fermentation by beneficial gut microbiota rather than general fiber effects. Chicory-derived inulin with documented bifidogenic activity commands preferential placement in German pharmacy-channel digestive health products.
Direct procurement relationships between ingredient suppliers and clean-label CPG brands are displacing traditional distributor intermediaries. BENEO and Cosucra now operate technical service laboratories in Chicago and Singapore where formulation scientists co-develop reduced-sugar prototypes with brand R&D teams. This channel compression accelerates specification lock-in but requires regional technical staffing investments that smaller extractors struggle to match.
Inulin Market Segmentation
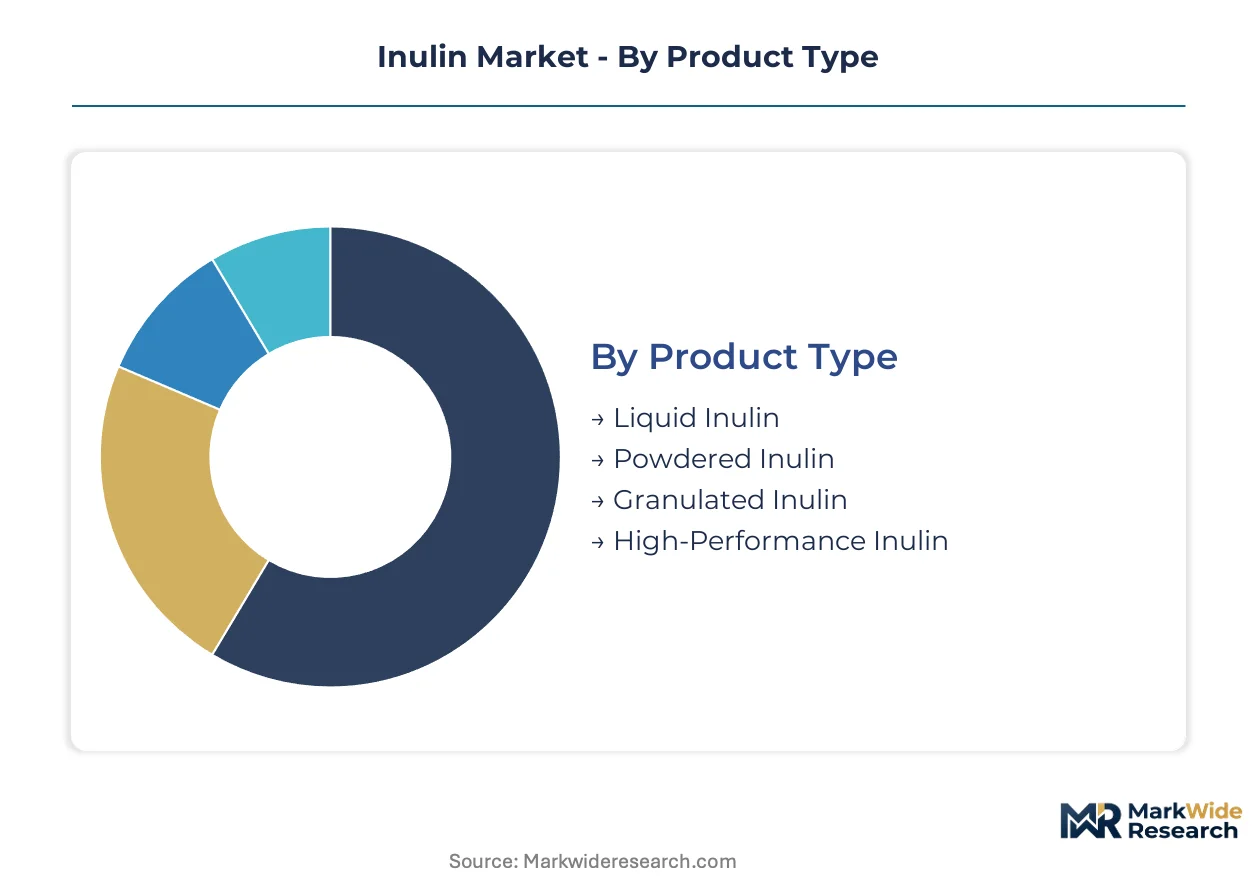
Inulin's functional versatility across fat replacement, fiber fortification, and prebiotic delivery creates distinct specification requirements by product format and end-use. Segmentation reveals where formulation technology and agricultural sourcing decisions concentrate value capture.
Product Type:
Powdered formats dominate mature applications while liquid and high-performance grades emerge in beverage and clean-label sectors.
- Powdered Inulin:Spray-dried chicory root extract with standard degree of polymerization (DP 2-60) serves bakery and dry-mix applications. German and French dairy alternative processors specify this grade for cost-effective texture modification in oat milk powder formulations.
- High-Performance Inulin:Chromatographically purified sub-10 DP fractions achieve cold-water solubility without turbidity. California ready-to-drink smoothie brands now mandate this specification for refrigerated beverage clarity standards.
- Liquid Inulin:Concentrated aqueous solutions reduce dust exposure in high-volume manufacturing environments. Nutritional bar producers in the Netherlands favor liquid delivery for continuous processing lines.
- Granulated Inulin:Agglomerated particles improve flowability in tablet compression and instant beverage applications. Dietary supplement manufacturers specify this grade for direct-compression prebiotic capsules.
Powdered inulin handles the majority of throughput; high-performance inulin is climbing the fastest on share.
End User:
Food industry procurement concentrates volume while pharmaceutical and nutraceutical channels command specification rigor and margin premiums.
- Food Industry:Clean-label bakery and dairy alternative formulators drive bulk demand for fat-mimetic and fiber fortification functions. Belgian chicory supply chains anchor this segment through BENEO and Suedzucker production clusters.
- Pharmaceutical Sector:Excipient-grade inulin with documented safety dossiers serves tablet binders and controlled-release matrices. EMA guidelines on pharmaceutical excipients determine permissible purity thresholds for EU market access.
- Nutraceuticals:Prebiotic positioning requires EFSA-approved health claim substantiation for chicory-derived grades. German pharmacy-channel digestive health products specify bifidogenic-documented inulin at premium pricing.
- Dietary Supplements:Capsule and powder formats target gut microbiome modulation claims. US FDA dietary fiber classification rulings directly influence formulation decisions for American retail positioning.
Food industry procurement anchors volume scale; nutraceuticals deliver the steepest expansion trajectory.
Application:
Texture modification needs in plant-based dairy accelerate fastest while baking maintains foundational demand.
- Dairy Alternatives:Oat and almond milk processors integrate inulin as fat-mimetic texture modulators replacing modified starches. Danish and Dutch clean-label brands specify long-chain grades for creamy mouthfeel without emulsifier additives.
- Baking Products:Reduced-fat cookies and cakes utilize inulin's water-binding capacity to maintain crumb structure. French industrial bakeries represent mature demand with established supply contracts.
- Beverages:Ready-to-drink applications require high-solubility grades that dissolve at refrigeration temperatures. São Paulo functional beverage startups specify sub-10 DP fractions for tropical climate stability.
- Nutritional Bars:Binding and fiber fortification functions support meal replacement and sports nutrition positioning. Protein bar manufacturers balance inulin inclusion against digestive tolerance thresholds.
Baking products retain the largest installed formulation base; dairy alternatives are expanding most quickly.
Source:
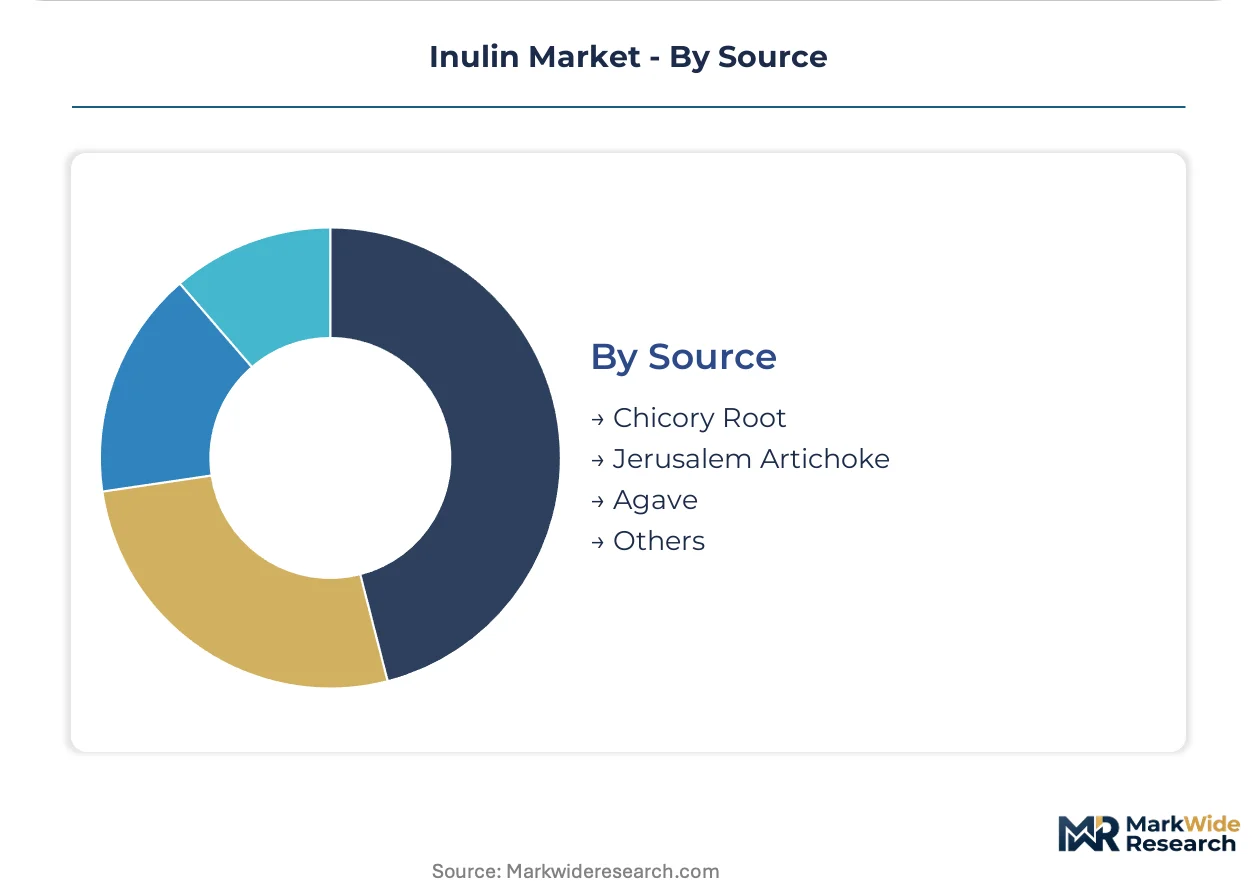
Agricultural concentration in Belgian chicory creates supply vulnerability that Jerusalem artichoke and agave alternatives address.
- Chicory Root:Cichorium intybus cultivation in Belgium and northern France supplies long-chain inulin (DP >23) for bakery and texture-heavy applications. EU Green Deal soil health incentives reinforce chicory's positioning as deep-rooted rotation crop.
- Jerusalem Artichoke:Helianthus tuberosus offers rotation-crop diversification for organic supply chains seeking reduced monoculture risk. Three-year organic certification timelines constrain rapid scaling despite retail channel interest.
- Agave:Mexican desert agriculture provides fructan extracts with distinct fermentation profiles for tequila co-product utilization. Premium positioning targets functional beverage channels seeking geographic differentiation.
- Others:Dandelion root and yacon supply niche organic grades for specialty supplement positioning. Limited commercial volumes restrict penetration beyond artisanal and direct-to-consumer channels.
Chicory root commands the dominant agricultural base; Jerusalem artichoke is gaining share fastest among organic-certified supply chains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Belgian chicory root exports supply formulation labs in Chicago and Singapore, anchoring transatlantic and Asia-Pacific trade corridors for long-chain inulin grades. European processing clusters in northern France and the Netherlands feed clean-label dairy alternative brands across northern Europe. Supply chain managers negotiate multi-year agricultural contracts to secure yield consistency against climate volatility.
Germany
Clean-label oat milk processors in Hamburg and Berlin integrate inulin as fat-mimetic texture modulators. EFSA-approved prebiotic claims under EU Regulation 1924/2006 command pharmacy-channel shelf placement. BENEO GmbH anchors production in Offstein, supplying long-chain grades to domestic dairy alternative brands.
United States
Ready-to-drink smoothie startups in California specify sub-10 DP high-performance grades for refrigerated beverage clarity. FDA dietary fiber classification rulings directly influence Nutrition Facts labeling decisions. Chicago technical service laboratories co-develop reduced-sugar prototypes with CPG brand R&D teams.
France
Industrial bakeries in Paris and Lyon maintain mature demand for powdered inulin in reduced-fat cookie formulations. EU Green Deal soil health incentives reinforce chicory cultivation as deep-rooted rotation crop. Cosucra Groupe Warcoing SA specializes in organic-certified grades from northern French agricultural belts.
Netherlands
Nutritional bar producers in Utrecht favor liquid inulin delivery for continuous processing lines. REACH compliance requirements shape excipient-grade purity thresholds for EU market access. Cooperative Royal Cosun U.A. operates extraction facilities serving Dutch and German clean-label manufacturers.
Japan
Functional beverage formulators in Tokyo and Osaka seek FOSHU approval pathways for prebiotic positioning. METI standards govern ingredient safety dossiers for gut health claims. Domestic isomaltooligosaccharide producers currently outpace European suppliers in regulatory familiarity.
Inulin Market Vendor Landscape
On the supply side, the industry is consolidating around integrated agricultural processors with captive chicory root supply chains. Three to five specialized extractors control premium-grade output, while diversified ingredient conglomerates compete on volume in standard powdered segments. Strategic archetypes include chicory-root-integrated specialists, diversified carbohydrate processors, and organic-certified niche operators. Dominant competitive moves encompass backward integration into agricultural sourcing and enzymatic refinement capacity expansion for beverage-grade specifications.
Among Belgian and German integrated processors, BENEO GmbH and Suedzucker AG exemplify the agricultural-anchored archetype with northern European supply chain control. Cosucra Groupe Warcoing SA occupies a position within the organic-certified specialist tier, commanding premium positioning in French and German retail channels. Kerry Group plc represents the diversified ingredient conglomerate model, leveraging broad formulation expertise across multiple prebiotic and fiber categories.
| Leading Market Players |
|---|
| Cosucra Groupe Warcoing SA |
| Suedzucker AG |
| BENEO GmbH |
| Kerry Group plc |
| Cooperative Royal Cosun U.A. |
| Sensus Food Ingredients B.V. |
| Ingredion Incorporated |
| Tereos Syral S.A.S. |
| Cargill, Incorporated |
| Others |
Supply Flow & Price Mechanics
Belgian chicory root processing clusters around Offstein and Tienen concentrate long-chain inulin extraction capacity, granting integrated processors pricing leverage over formulators seeking EFSA-substantiated prebiotic grades. This geographic concentration forces dairy alternative brands into multi-year agricultural contracts or acceptance of volatile spot-market exposure for Jerusalem artichoke alternatives.
Pricing Analysis
Chromatographic purification technology commands substantial premiums over conventional spray-dried grades, while enzymatic refinement for sub-10 DP beverage specifications opens a third pricing tier. Three-tier pricing structure across premium, standard, and economy levels separates EFSA-approved health claim grades from industrial bakery inputs and commodity fiber fortifiers. Cost compression in standard powdered segments is intensifying because polydextrose substitutes compete aggressively in price-sensitive bakery applications. Mid-tier producers face the steepest price sensitivity, while pharmaceutical excipient buyers accept premiums for documented safety dossiers.
Supply Chain Analysis
Extended payment terms from Belgian and Dutch processors to French chicory growers strain working capital for smaller extractors competing against Suedzucker's integrated financing capacity. Supply concentrates in Belgium, France, and the Netherlands for long-chain extraction, with Mexican agave and Chinese Jerusalem artichoke operations serving geographic diversification strategies. Raw material dependencies center on chicory root monoculture, chromatographic resin supplies, and enzymatic processing catalysts. Single-source vulnerability in Belgian agricultural belts threatens yield consistency under climate volatility. Distribution runs through direct technical service relationships with CPG brand R&D teams, displacing traditional ingredient distributor intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment around EFSA health claim substantiation creates substantial switching costs for formulators who have invested in clinical dossier validation.
For Market Incumbents: Build regulatory data moats by expanding human intervention study portfolios beyond current bifidogenic documentation to capture evolving EFSA Article 13.5 interpretations. Backward integration into regenerative agriculture certification programs secures premium positioning as EU Green Deal soil health incentives mature. Threats from precision fermentation startups and synthetic prebiotic alternatives demand accelerated enzymatic refinement capacity expansion in Chicago and Singapore technical centers. For New Entrants and Emerging Players: Pursue organic-certified Jerusalem artichoke supply chains where three-year conversion timelines have constrained incumbent scaling responses to retail channel commitments. Japanese FOSHU approval pathways remain underexploited by European suppliers relative to domestic isomaltooligosaccharide producers, creating a penetrable geography. Pediatric nutrition fortification offers a white-space application where established safety dossiers command formulation lock-in. Go-to-market positioning should emphasize carbon-negative supply chain credentials aligned with EU Green Deal procurement preferences. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-entrenchment play because EFSA health claim requirements and FDA fiber classification rulings create durable barriers to commodity substitution. Acquisition targets should display integrated agricultural processing with captive chicory root supply and existing clinical substantiation capacity. The signal to watch is FDA evolution on dietary fiber definitions, which would reshape formulation economics for American retail positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Regenerative Agriculture | Captures EU Green Deal soil health incentives for carbon-negative chicory positioning. |
| Enzymatic Refinement Capacity Expansion | Enables sub-10 DP beverage-grade specifications demanded by California smoothie brands. |
| Clinical Substantiation Investment | Builds EFSA Article 13.5 dossiers that command pharmacy-channel premium placement. |
| Direct Technical Service Laboratory Deployment | Accelerates specification lock-in through Chicago and Singapore formulation partnerships. |
| Japanese FOSHU Regulatory Pathway Pursuit | Opens functional foods channel where European suppliers lag domestic isomaltooligosaccharide producers. |
Methodological Framework
A standing panel of chicory root procurement managers, dairy alternative formulators, pharmaceutical excipient buyers, and EFSA regulatory consultants provided ongoing calibration across primary interview programs. Secondary validation drew from EU customs trade data, EFSA health claim register entries, FDA fiber classification rulings, and SEC filings from diversified ingredient conglomerates. Bottom-up volume triangulation against top-down value estimates anchored segmentation-level precision.
Scenario-bracketing framed demand trajectories across the projection horizon, modeling sensitivity to regulatory interpretation shifts and agricultural yield volatility. Segmentation dimensions included product type tier, end-use industry, application format, and geographic regulatory cluster. CAGRs derived from polynomial trend fitting against historical volume trajectories, with input from chicory root acreage expansion plans and enzymatic processing capacity announcements.
The forecast holds incumbent behavior within observed patterns; aggressive moves by precision fermentation startups or synthetic prebiotic developers would shift outcomes beyond modeled ranges. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Canada Compound Feed Market
Agriculture and Agri Products
United Kingdom Compound Feed Market
Agriculture and Agri Products
Specialty Egg Market
Agriculture and Agri Products
South America Poultry Feed Market
Agriculture and Agri Products
Sweet Potato Flour Market
Agriculture and Agri Products
Africa Animal Protein Market
Agriculture and Agri Products
India Palm Oil Market
Agriculture and Agri Products
LAMEA Rapeseed Oil Market
Agriculture and Agri Products
Tunisia Agriculture Market
Agriculture and Agri Products
Marine Algae Market
Agriculture and Agri Products
Cassava Starch Market
Agriculture and Agri Products
Africa Orange Market
Agriculture and Agri Products
Alfalfa Protein Concentrate Market
Agriculture and Agri Products
Marine Seaweed Market
Agriculture and Agri Products
Kenya Floriculture Market
Agriculture and Agri Products
American Ginseng Market