
 Australia Floriculture Market | 2026-2036
Australia Floriculture Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Floriculture Market Outlook
Queensland's protected flower farms is expanding glasshouse acreage for year-round rose and gerbera production. Lynch Group anchors East Coast supply chains through its vertically integrated cool-chain logistics network. Paradise Plants differentiates via heritage rose cultivars bred for subtropical climates. Tesselaar Flowers competes on direct-to-florist distribution, bypassing traditional wholesale tiers in Victoria and New South Wales.
Australia floriculture encompasses the commercial cultivation, post-harvest handling, and distribution of ornamental plants including cut flowers, potted specimens, and bedding stock, typically grown under controlled-environment agriculture with specified vase-life benchmarks of seven to fourteen days for cut products. The sector serves retail consumers, event coordinators, and wholesale florists seeking perishable decorative botanicals for ceremonial, commercial, and residential applications. Cut flowers command the largest revenue pool due to recurring demand from wedding and corporate event segments, while potted plants capture margin premiums through longer shelf life and reduced perishability risk. E-commerce channels represent the fastest-growing distribution vector, though retail supermarkets still dominate volume throughput for everyday consumer purchases.
TGA biosecurity protocols govern importation of propagation material, restricting pest pathways while creating compliance costs for breeders seeking exotic germplasm. The Australian Pesticides and Veterinary Medicines Authority regulates agrochemical residues on export-bound blooms, directly shaping spray programs for growers targeting Asian premium markets. State-level water licensing under the Murray-Darling Basin Plan constrains expansion in southern growing districts, pushing new investment toward coastal Queensland and northern New South Wales with more reliable rainfall profiles. Stakeholders must weigh capital allocation between protected-environment intensification and regional diversification as climate variability and biosecurity barriers tighten operational constraints.
Market Dynamics
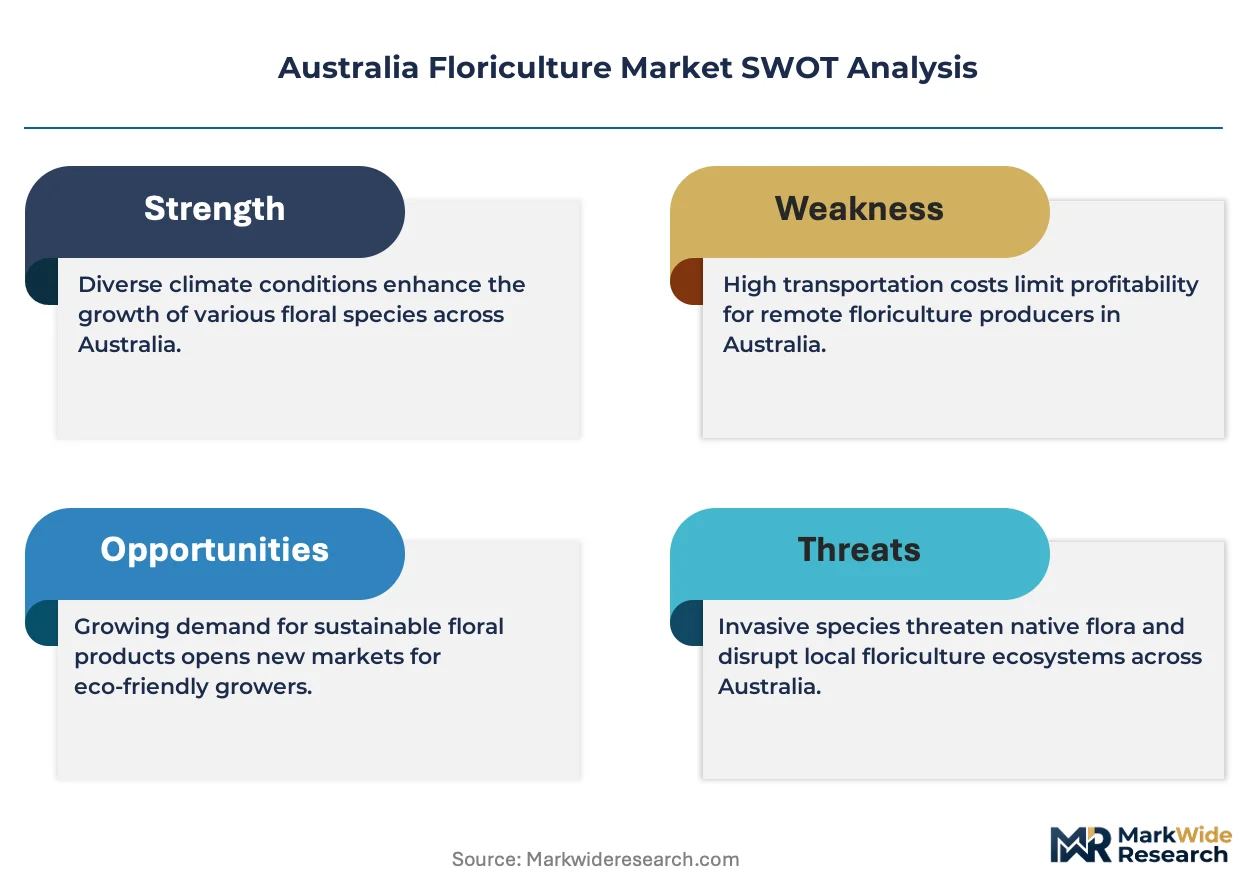
Water licensing under Australia's Murray-Darling Basin Plan is redistributing production capacity toward coastal Queensland and northern New South Wales, forcing growers to choose between protected-environment intensification and regional relocation.
Growth Catalysts
- E-commerce channels:Direct-to-consumer platforms bypass traditional wholesale tiers, capturing margin premiums from time-poor urban buyers seeking subscription-based flower delivery.
- Protected cultivation clusters:Glasshouse acreage expansion on Queensland's Sunshine Coast enables year-round rose and gerbera output with predictable quality benchmarks.
- Biosecurity protocols:TGA import restrictions on propagation material create captive demand for domestic breeding programs and heritage cultivar development.
Market Restraints
- Input cost volatility:Natural gas and electricity price swings disproportionately impact heated glasshouse operations during winter production cycles.
- Supply concentration risk:Cool-chain logistics networks cluster around Lynch Group's vertically integrated infrastructure, creating single-point vulnerability for East Coast distribution.
- Substitution pressure:Dried and preserved floral alternatives capture ceremonial segment share from perishable cut flowers through extended shelf life.
Strategic Opportunities
- Underpenetrated segments:Corporate wellness programs in Melbourne and Sydney offer recurring contract potential for indoor plant leasing and maintenance services.
- Regulatory tailwind:Australian Pesticides and Veterinary Medicines Authority residue standards, when met, unlock premium Asian export channels with price multiples above domestic wholesale.
- Channel innovation:Supermarket floral kiosks with in-store bouquet assembly stations merge impulse purchasing with customization previously exclusive to florists.
Industry Challenges
- Specialized labor scarcity:Protected environment agronomy and post-harvest physiology expertise concentrates among aging grower cohorts with limited vocational pipeline replacement.
- Compliance timeline compression:Dual accreditation requirements for both domestic supermarket specifications and export residue protocols strain quality assurance staffing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Floriculture Market |
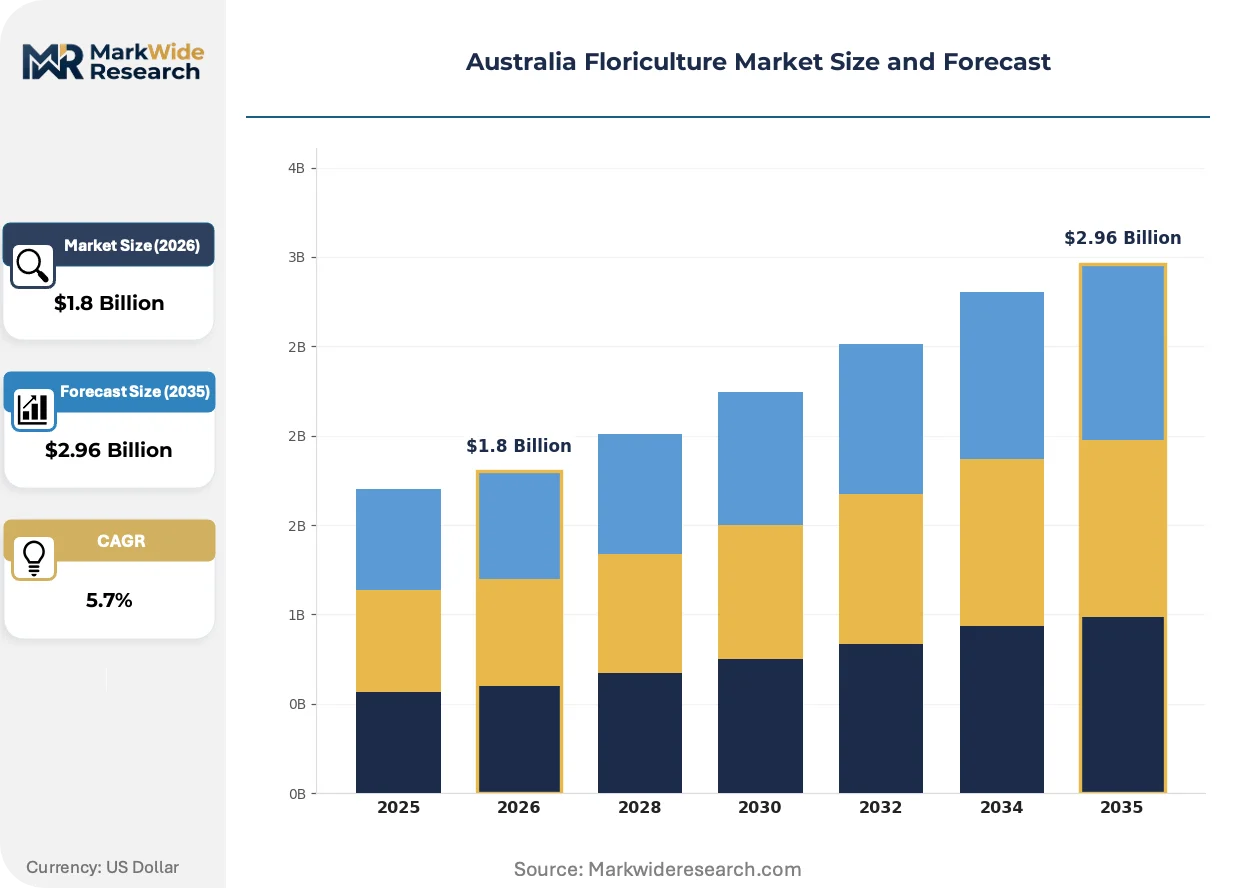
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cut Flowers, Potted Plants, Bedding Plants, Foliage Plants Distribution Channel: Retail, Wholesale, E-commerce, Direct Sales End User: Retail Consumers, Event Planners, Florists, Businesses Packaging Type: Plastic Wrap, Cardboard Boxes, Bouquet Bags, Gift Packs |
| Companies Covered | Helix Australia, Everbloom, Lynch Group, Paradise Plants, Treloar Roses, Grandiflora, Tesselaar Flowers, Interflora Australia, WAFex, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Floriculture Market Strategic Shifts
Climate adaptation and digital distribution are converging to reshape how Australian growers cultivate, certify, and deliver ornamental products to fragmented buyer bases.
LED supplemental lighting is consolidating controlled-environment production economics across Queensland glasshouses. Large-scale rose and gerbera operations deploy spectrum-tunable arrays to compress flowering cycles and standardize stem length for supermarket grading. Energy management software integrating solar generation with grid draw is consolidating operational cost structures that previously favored open-field seasonal production.
Murray-Darling Basin Plan water licensing is reallocating production geography toward coastal rainfall zones. Southern Victorian and South Australian districts face extraction cap reductions that render expansion uneconomical. Growers respond by relocating propagation facilities to northern New South Wales irrigation districts with more secure entitlement profiles.
Subscription-based floral procurement is displacing event-driven bulk purchasing among Sydney and Melbourne corporate accounts. Facilities managers now contract weekly rotation services rather than ad-hoc ceremonial orders. This shift is most visible in financial services and professional services verticals where workplace experience budgets compete for employee retention impact.
Australia Floriculture Market Segmentation
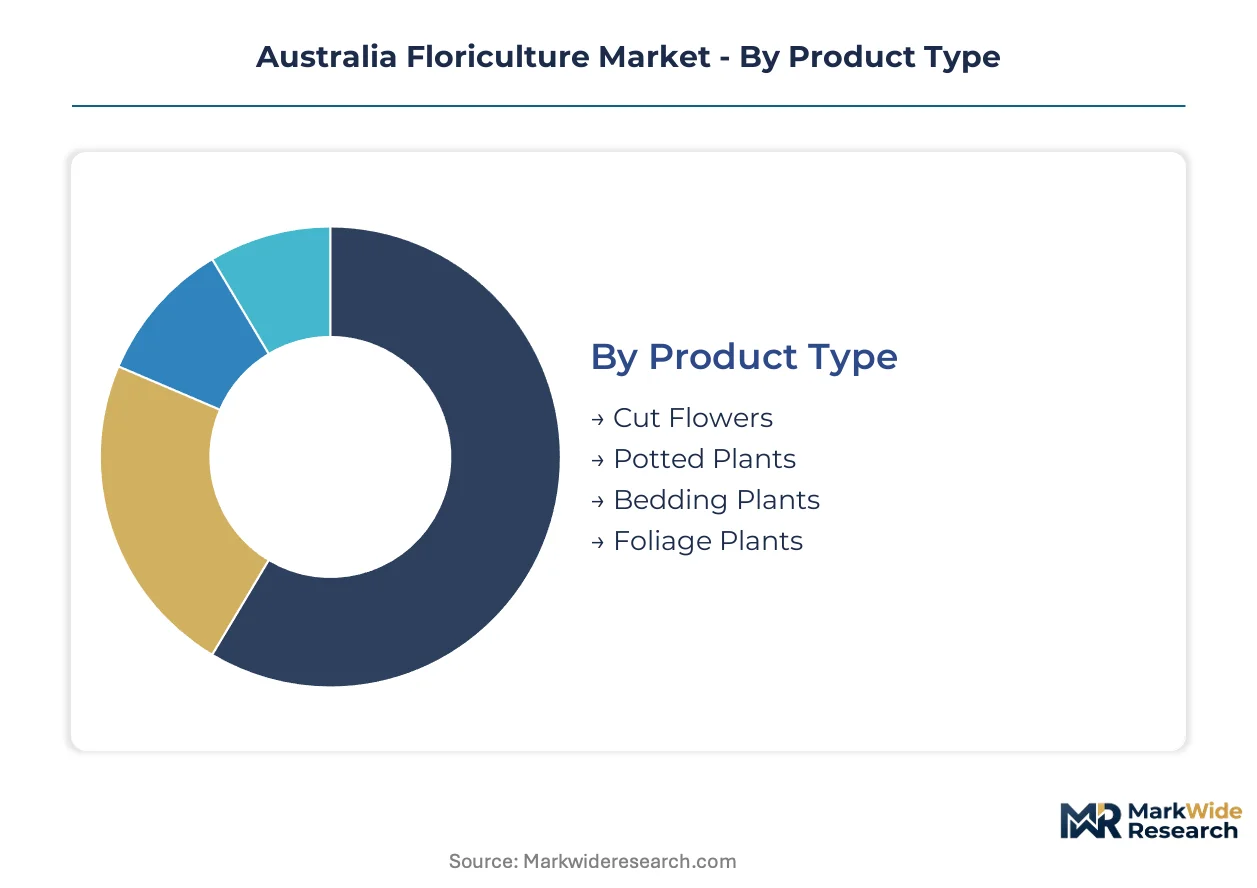
Australian floriculture segments reveal divergent margin structures and supply chain requirements. Cut flowers demand rapid cool-chain throughput while potted plants reward inventory holding capacity. Distribution channel selection directly determines customer acquisition economics and perishability risk exposure.
Product Type:
Volume throughput concentrates in mass-market cut stems, while premium margin capture favors longer-cycle potted specimens.
- Cut Flowers:Perishable blooms harvested at specified maturity stages with vase-life benchmarks of seven to fourteen days. Sydney and Melbourne event planners drive demand for premium rose, gerbera, and native wildflower varieties used in corporate functions and weddings. TGA biosecurity protocols on imported propagation material restrict exotic cultivar access, strengthening domestic breeding programs.
- Potted Plants:Container-grown ornamental specimens with shelf life extending weeks to months, reducing perishability risk for retailers. Queensland's Sunshine Coast protected cultivation clusters supply national supermarket chains with year-round flowering and foliage varieties. Indoor plant leasing services to Melbourne and Sydney corporate wellness programs represent an emerging recurring revenue vector.
- Bedding Plants:Seasonal ornamental seedlings for residential garden planting, concentrated in spring and autumn sales windows.
- Foliage Plants:Non-flowering decorative specimens valued for architectural form and low-maintenance characteristics in commercial interiors.
Mature deployment sits with Cut Flowers. Newer deployment is concentrated in Potted Plants.
Distribution Channel:
Customer touchpoint selection governs margin retention, with direct channels capturing value previously absorbed by wholesale intermediaries.
- Retail:Supermarket floral kiosks and garden center outlets dominate everyday consumer volume, with in-store bouquet assembly stations merging impulse purchasing with customization. Coles and Woolworths floral procurement specifications shape grower grading standards nationwide.
- E-commerce:Direct-to-consumer platforms bypass traditional wholesale tiers, capturing margin premiums from time-poor urban buyers seeking subscription-based flower delivery. This channel is expanding most quickly among Sydney and Melbourne metropolitan accounts.
- Wholesale:Traditional tier serving independent florists and event coordinators, concentrated around Lynch Group's vertically integrated cool-chain infrastructure on the East Coast.
- Direct Sales:Grower-to-florist relationships eliminating intermediary handling, practiced by Tesselaar Flowers in Victoria and New South Wales.
Established volume flows through Retail. Channel innovation is concentrated in E-commerce.
End User:
Procurement patterns split between ceremonial occasion purchasing and recurring facility services.
- Retail Consumers:Individual purchasers seeking decorative botanicals for residential applications, concentrated in supermarket and online channels.
- Event Planners:Professional coordinators sourcing premium cut flowers for weddings, corporate functions, and ceremonial occasions across Sydney and Melbourne. This segment commands highest per-stem pricing for specified varieties and colors.
- Florists:Independent retail operators assembling custom arrangements, dependent on wholesale supply tiers for variety access and daily freshness.
- Businesses:Corporate accounts contracting weekly rotation services for workplace experience programs, displacing ad-hoc ceremonial orders in financial and professional services verticals.
Traditional revenue concentration sits with Retail Consumers. Contractual recurring models are expanding fastest among Businesses.
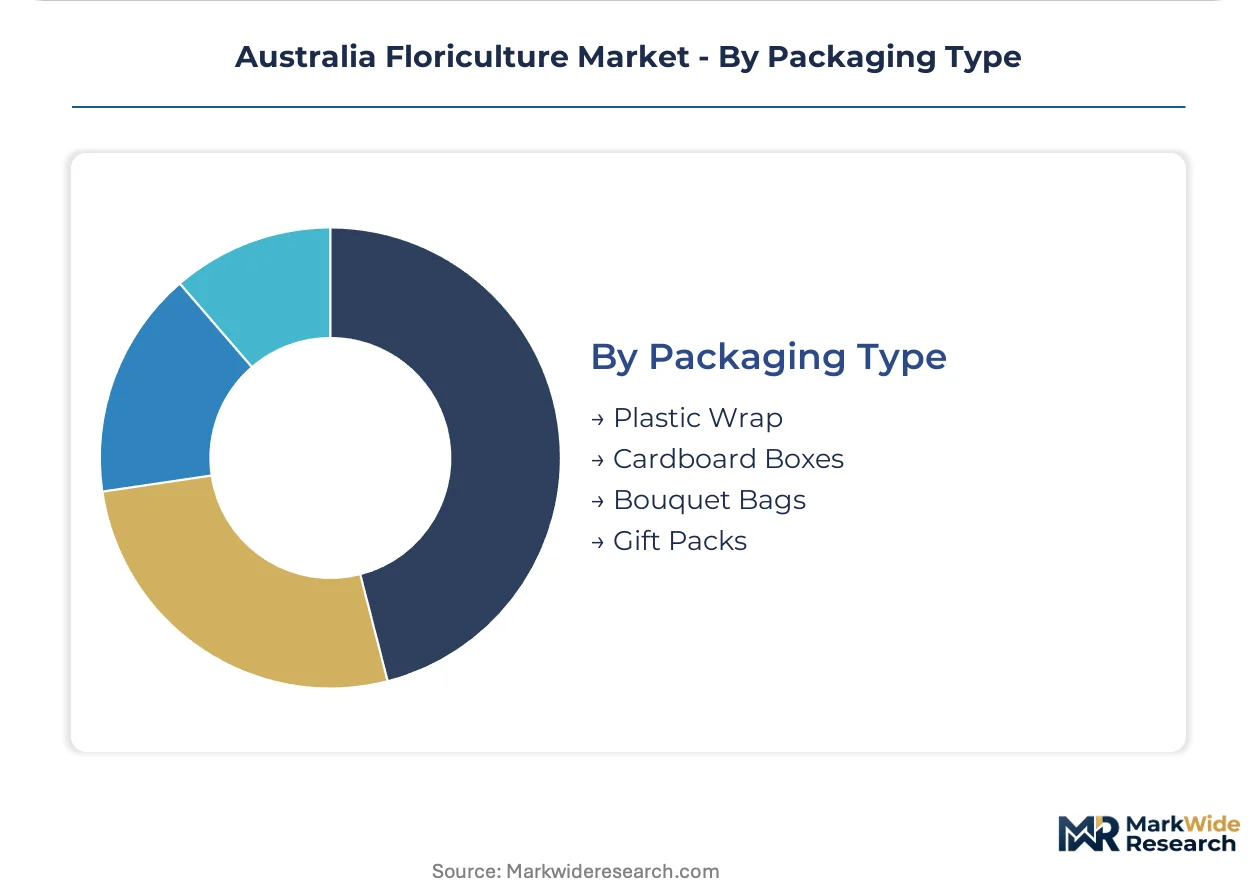
Packaging Type:
Material selection balances protection, presentation, and emerging sustainability specifications from major retail buyers.
- Plastic Wrap:Standard protection for cut stem hydration and mechanical damage prevention during transport.
- Cardboard Boxes:Structural containment for potted plant distribution, with recycled content specifications tightening under supermarket sustainability procurement standards.
- Bouquet Bags:Presentation packaging for impulse retail purchases, enabling grab-and-go floral acquisition.
- Gift Packs:Premium presentation formats combining botanical products with ancillary items for ceremonial gifting occasions.
Functional protection relies on Plastic Wrap. Sustainability-driven substitution is concentrated in Cardboard Boxes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Queensland's Sunshine Coast hinterland anchors Australian floriculture production through protected glasshouse clusters. Water entitlement scarcity under the Murray-Darling Basin Plan is reallocating investment toward coastal rainfall zones with more secure supply profiles.
New South Wales
Sydney event planners and corporate wellness programs drive premium cut flower procurement. The state's water licensing under the Murray-Darling Basin Plan constrains expansion in traditional southern growing districts. Northern New South Wales irrigation districts near the Queensland border attract relocated propagation facilities seeking more secure entitlement profiles.
Victoria
Melbourne's financial and professional services verticals contract weekly rotation services for workplace experience programs. TGA biosecurity protocols on imported propagation material restrict exotic cultivar access, strengthening domestic breeding concentration in this state. Tesselaar Flowers operates direct-to-florist distribution networks across metropolitan and regional Victorian markets.
Queensland
Protected cultivation clusters on the Sunshine Coast supply national supermarket chains with year-round rose and gerbera output. The state's reliable rainfall profile attracts capital fleeing water-constrained southern jurisdictions. Paradise Plants develops heritage rose cultivars specifically bred for subtropical climatic conditions.
South Australia
Murray-Darling Basin Plan extraction cap reductions render expansion uneconomical in traditional southern districts. The state's national pharmaceutical regulator, TGA, shapes import compliance costs for breeders seeking exotic germplasm. Adelaide-based operations face pressure to relocate propagation activities to northern jurisdictions with more favorable water security.
Western Australia
Perth's isolated metropolitan market supports localized production for regional consumption. WAFex anchors west coast distribution infrastructure connecting domestic growers to export channels. The state's distance from eastern population centers limits participation in national supermarket supply contracts dominated by Queensland and New South Wales producers.
Australia Floriculture Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue direct-to-consumer subscription models and corporate wellness services. The vendor base distributes across vertically integrated logistics networks, heritage breeding specialists, and digital-native floral platforms. Three archetypes dominate: cool-chain infrastructure operators, cultivar development houses, and direct-distribution challengers. Competitive moves concentrate on protected-environment capacity expansion and backward integration into breeding programs.
Among infrastructure-anchored operators, Lynch Group exemplifies the vertically integrated archetype through East Coast cool-chain dominance. Heritage breeding specialists include Paradise Plants and Treloar Roses, occupying positions centered on climate-adapted cultivar development. Direct-distribution challengers such as Tesselaar Flowers represent the bypass model, eliminating wholesale intermediaries to capture margin premiums from metropolitan florist accounts.
| Leading Market Players |
|---|
| Helix Australia |
| Everbloom |
| Lynch Group |
| Paradise Plants |
| Treloar Roses |
| Grandiflora |
| Tesselaar Flowers |
| Interflora Australia |
| WAFex |
| Others |
Value Chain & Pricing Dynamics
Certification-grade divergence between export-bound blooms and domestic supermarket tiers shapes both margin capture and procurement geography across Australian floriculture. TGA biosecurity protocols and APVMA residue standards bifurcate the market into premium export-qualified supply chains and volume-focused domestic retail channels, with compliance investment determining which growers access Asian price multiples versus commodity wholesale rates.
Pricing Analysis
Warranty-backed vase-life guarantees differentiate subscription-tier offerings from transactional bulk procurement in Sydney and Melbourne corporate accounts. Three-tier pricing structure across premium, standard, and economy levels reflects APVMA certification status, with export-qualified growers capturing multiples above domestic wholesale through residue-compliant spray programs. Pricing pressure stems from natural gas and electricity volatility disproportionately impacting heated glasshouse operations during winter cycles. Event planners demonstrate lowest price sensitivity for specified varieties and colors, while supermarket procurement teams drive hardest volume negotiations.
Supply Chain Analysis
Dual-sourcing mandates from Coles and Woolworths procurement specifications require qualified backup suppliers for national account continuity, fragmenting volume across multiple Queensland glasshouse clusters. Production concentrates in Queensland's Sunshine Coast hinterland, northern New South Wales irrigation districts, and select Victorian propagation facilities. Cool-chain logistics draws from Lynch Group's vertically integrated infrastructure, natural gas for climate control, and imported propagation material restricted under TGA protocols. Single-point vulnerability concentrates in East Coast distribution networks anchored to one operator's cool-chain footprint. Distribution runs through vertically integrated wholesale tiers, direct-to-florist bypass models, and emerging e-commerce subscription platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cost-of-compliance dynamics under TGA biosecurity protocols and APVMA residue standards erect formidable barrier-to-entry moats, rewarding early certification investment with captive access to premium export channels and supermarket supply contracts.
For Market Incumbents: Extend protected-environment capacity on Queensland's Sunshine Coast ahead of water licensing constraints tightening across southern jurisdictions. Secure backward integration into heritage breeding programs to reduce germplasm import dependency under TGA restrictions. Dried and preserved floral alternatives threaten ceremonial segment share, demanding counter-positioning through vase-life extension R&D and subscription-based recurring revenue models.
For New Entrants and Emerging Players: Capture underpenetrated corporate wellness programs in Melbourne and Sydney financial services verticals through indoor plant leasing and maintenance contracts displacing ad-hoc ceremonial orders. Bypass wholesale intermediaries via direct-to-florist digital platforms, replicating Tesselaar Flowers' distribution model across untapped regional Victorian and New South Wales markets.
For Investors and Strategic Acquirers: Re-rating potential sits with heritage breeding specialists given biosecurity tailwinds restricting exotic cultivar importation and strengthening domestic germplasm value. Long-term viability favors operations with secured water entitlements in coastal rainfall zones over Murray-Darling Basin-exposed southern districts. Watch LED supplemental lighting adoption rates as inflection indicator for operational cost compression and year-round production economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Protected Cultivation Expansion | Glasshouse acreage additions on Queensland's Sunshine Coast secure year-round rose and gerbera output for supermarket contracts. |
| Heritage Breeding Program Investment | Climate-adapted cultivar development at Paradise Plants and Treloar Roses reduces TGA import dependency for subtropical rose varieties. |
| Direct-to-Florist Distribution Launch | Tesselaar Flowers' bypass model eliminates wholesale margin absorption in Victoria and New South Wales metropolitan markets. |
| Corporate Wellness Service Expansion | Weekly rotation contracts with Melbourne financial services firms displace event-driven bulk purchasing through recurring revenue. |
| Cool-Chain Infrastructure Consolidation | Lynch Group's vertically integrated logistics network anchors East Coast perishable distribution against single-point vulnerability risks. |
Study Parameters
Multi-period observation of water licensing allocations, glasshouse acreage expansion, and e-commerce penetration rates anchored the trend analysis, supplemented by interviews with protected environment agronomists, supermarket category buyers, event planning coordinators, and cool-chain logistics operators. Primary fieldwork combined with secondary validation from APVMA residue monitoring reports, Murray-Darling Basin Plan entitlement registers, Queensland agricultural statistics, and supermarket procurement specifications. Bottom-up grower capacity modeling and top-down demand segmentation triangulation ensured cross-verification of volume and value estimates.
Input-output matrices mapped propagation material flows, energy consumption per stem, and cool-chain throughput against end-user procurement patterns across the projection horizon. Segmentation dimensions modeled included product type, distribution channel, end-user archetype, and state-level production geography. CAGRs derived from trend-line extrapolation of historical acreage expansion, subscription service adoption curves, and export qualification growth. Industry-specific forecast inputs incorporated LED lighting adoption rates and Murray-Darling Basin Plan water entitlement reallocation timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to biosecurity protocol amendments, natural gas price volatility, and substitution acceleration from preserved floral alternatives. Deviation in TGA import restriction severity or APVMA residue threshold tightening would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Mushroom Substrate Market
Agriculture and Agri Products
North America Alfalfa Hay Market
Agriculture and Agri Products
Animal Feed Market
Agriculture and Agri Products
Australia Lime Market
Agriculture and Agri Products
Saudi Arabia Alfalfa Market
Agriculture and Agri Products
Live Goods Market
Agriculture and Agri Products
Africa Rice Market
Agriculture and Agri Products
Agrimony Market
Agriculture and Agri Products
Black Sapote Market
Agriculture and Agri Products
Agriculture in Egypt Market
Agriculture and Agri Products
Colombia Hemp Market
Agriculture and Agri Products
Sorghum by-Products Market
Agriculture and Agri Products
Animal Feed and Pet Food Market
Agriculture and Agri Products
China Compound Feed Market
Agriculture and Agri Products
Colombia Floriculture Market
Agriculture and Agri Products
Corn Gluten Feed Concentrates Market