
 Apple Juice Market | 2026-2036
Apple Juice Market Size, Share, and Industry Trends Forecast 2026-2036
Apple Juice Market Analysis
Subscription-based replenishment services for household beverage delivery is repositioning how apple juice brands secure recurring revenue and consumer loyalty. Tree Top Inc. leverages its Pacific Northwest orchard network to control raw material quality from cultivation through processing. Martinelli & Company sustains premium positioning through heritage branding and glass-bottle packaging that commands shelf-space differentiation. The Coca-Cola Company extends its Minute Maid portfolio into functional juice blends that compete on vitamin fortification and convenience formats.
Apple juice is the aqueous extract of pressed apples, typically containing 10-12% natural sugars and standardized to a specific gravity of 1.040-1.050, serving primarily as a ready-to-drink beverage and food manufacturing ingredient. Clear juice dominates volume production due to enzymatic clarification efficiency and extended shelf stability, while cloudy juice commands margin premiums from consumers seeking minimally processed alternatives with retained polyphenol content. Carton packaging leads ambient distribution channels for household consumption, though pouches are gaining traction in food service and on-the-go segments where portion control and reduced shipping weight matter.
The FDA governs juice safety through Hazard Analysis Critical Control Point mandates and pasteurization standards, while the USDA administers organic certification requirements that gate premium pricing for certified apple juice producers. The EPA regulates agricultural chemical residues on orchard inputs, directly influencing sourcing compliance costs for concentrate and single-strength products alike. Stakeholders must monitor evolving clean-label enforcement thresholds and sugar-reduction guidance across multiple jurisdictions to anticipate reformulation investments and label-claim risks.
Market Dynamics
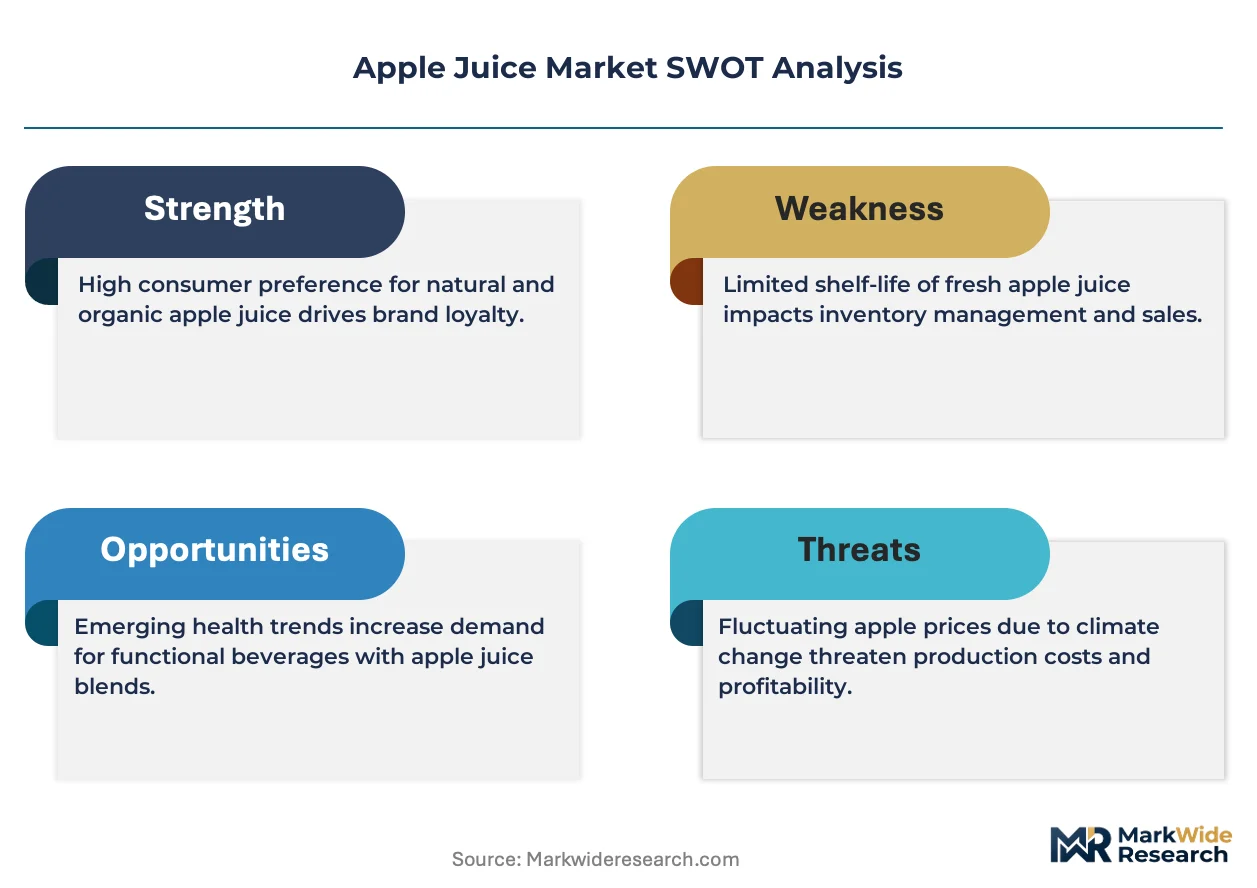
The FDA's updated nutrition labeling mandates for added sugars are forcing wholesale reformulation across North American apple juice portfolios, compressing margins for manufacturers dependent on conventional sweetened concentrates while creating first-mover advantages for clean-label specialists.
Growth Catalysts
- USDA Organic Certification:Premium pricing gates in the United States reward orchard operators who achieve certified organic status, pulling acreage conversion in Washington and New York states.
- Enzymatic Clarification Advances:Pectinase and amylase efficiency gains are reducing processing energy inputs by enabling faster filtration cycles at ambient temperatures.
- China:Urban middle-class consumers in Shanghai and Beijing are displacing traditional soft drinks with 100% juice consumption in household replenishment channels.
Market Restraints
- Apple Concentrate Input Volatility:Weather-driven crop yields in Poland and China create price swings that concentrate producers cannot fully hedge.
- Single-Origin Dependency:Pacific Northwest orchard networks control disproportionate volumes of high-acid dessert varieties suitable for juice processing.
- EPA Agricultural Chemical Residue Limits:Tightening tolerances for organophosphate insecticides force sourcing switches that elevate compliance audit costs.
Strategic Opportunities
- Germany:Discounter channel expansion creates private-label entry points for mid-tier concentrate suppliers seeking scale over margin.
- Functional Fortification:Vitamin D and probiotic integration is converging with ambient-stable aseptic packaging to capture pharmacy-channel distribution.
- Subscription Replenishment Platforms:Direct-to-household delivery services bypass traditional grocery slotting fees and build proprietary consumer data assets.
Industry Challenges
- Clean-Label Reformulation Timelines:Removing added sugars while maintaining 1.040-1.050 specific gravity standards demands extended R&D cycles that compress product launch windows.
- Aseptic Packaging Equipment Capex:Tetra Pak and SIG Combibloc line installations require capital commitments that strain regional processor balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Apple Juice Market |
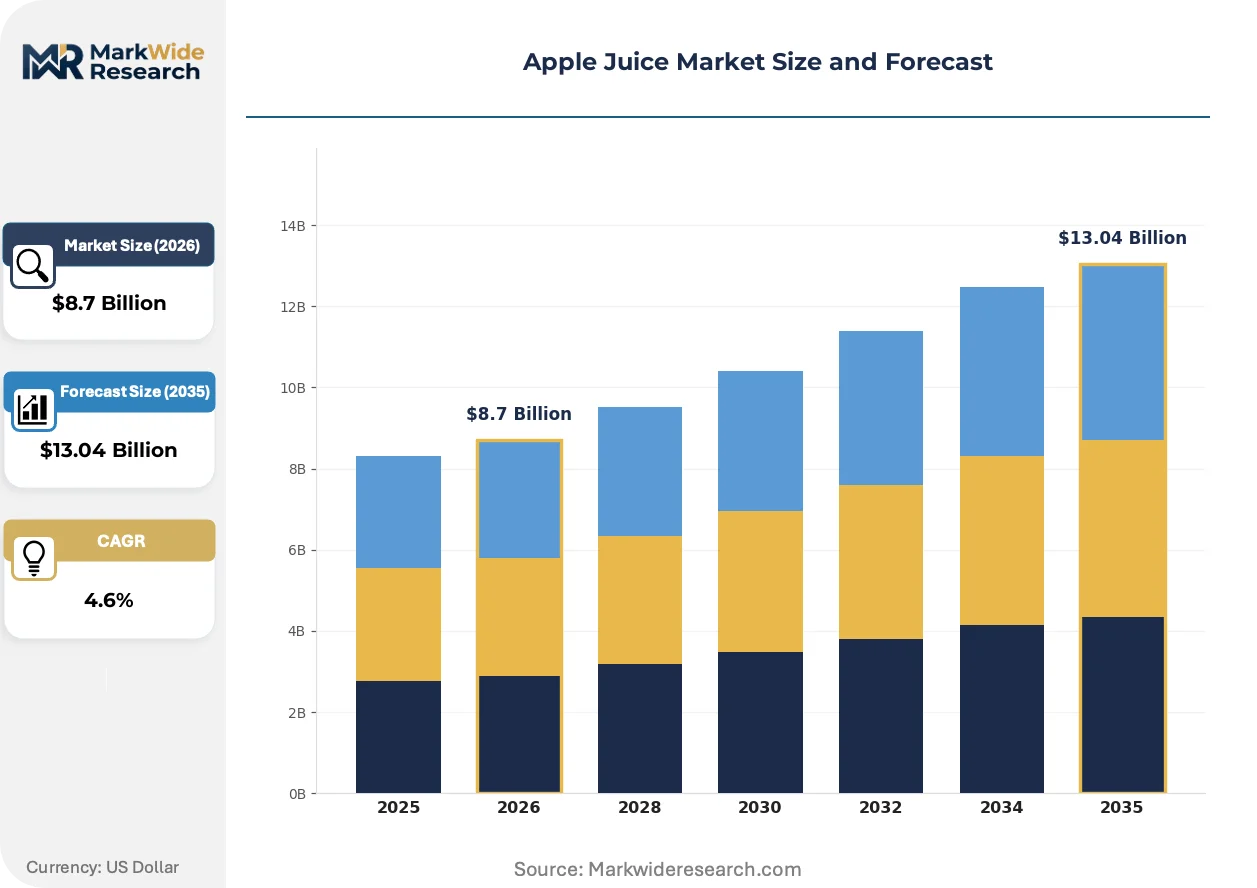
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Clear Juice, Cloudy Juice, Concentrated Juice, Sparkling Juice Packaging Type: Bottles, Cartons, Pouches, Cans Sales Channel: Supermarkets, Online Retailers, Convenience Stores, Wholesale Distributors Customer Type: Households, Food Service, Beverage Manufacturers, Health Conscious Consumers |
| Companies Covered | Martinelli & Company, Apple & Eve LLC, Tree Top Inc., PepsiCo Inc., Manzana Products Co. Ltd., Mott's, Musselman Premium, The Coca-Cola Company, Minute Maid, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Apple Juice Market Emerging Trajectories
Processing technology, regulatory disclosure requirements, and household purchasing channels are simultaneously reshaping how apple juice is formulated, labeled, and delivered to end consumers across concentrated demand zones.
High-pressure processing is converging with cloudy juice production to extend refrigerated shelf life without thermal degradation of polyphenol content. Premium beverage buyers in California and New York metropolitan areas are adopting HPP-treated SKUs at rates exceeding conventional pasteurized alternatives. This convergence is compressing the price gap between ambient-stable concentrates and chilled single-strength products.
REACH chemical registration requirements in the European Union are mandating full supply chain disclosure for processing aids and packaging migrants. Industrial consequence includes reformulated enzyme cocktails and liner material switches that add 8-12% to packaging input costs. German and Dutch private-label retailers are responding by consolidating supplier audits to reduce duplicative compliance documentation.
Direct-to-consumer subscription models are displacing conventional retail replenishment for household juice consumption. Food service distributors and institutional buyers are consolidating purchasing through platforms like Amazon Fresh and specialized beverage subscription services. This channel rotation is most visible in United States coastal metropolitan markets where delivery density supports economically viable last-mile logistics.
Apple Juice Market Segmentation
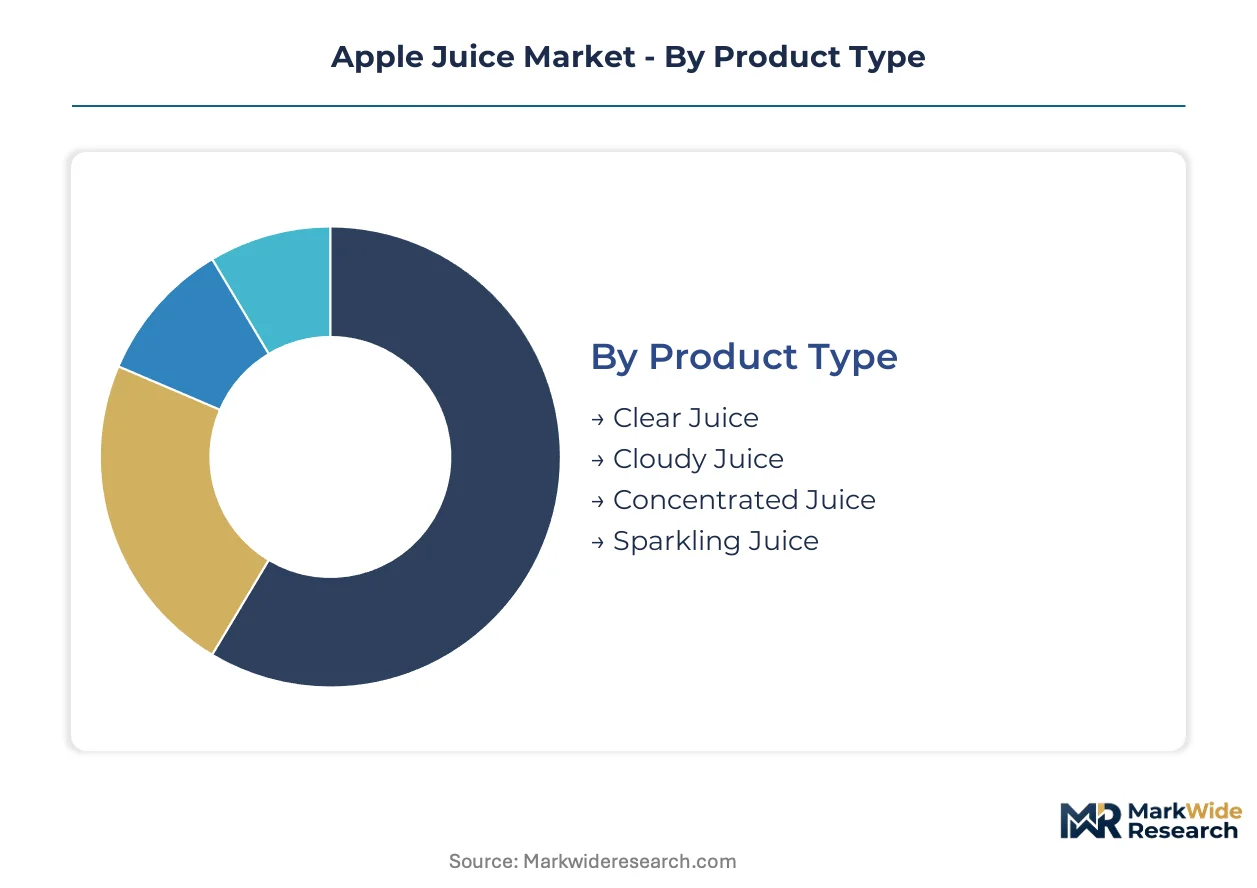
Apple juice segmentation reveals how processing methods, packaging economics, and channel access create distinct profit pools. Manufacturers configure supply chains differently for ambient-stable concentrates versus chilled single-strength products, while packaging choices determine distribution reach and shelf-life performance.
Product Type:
Volume production concentrates in clarified formats, while premium positioning clusters around minimally processed alternatives with retained nutritional content.
- Clear Juice:Enzymatic clarification removes pectin and starch to achieve optical clarity and 12-18 month ambient stability. Demand concentrates in German discounter channels and United States school nutrition programs where cost efficiency and extended shelf life dominate procurement criteria.
- Cloudy Juice:Minimal filtration preserves polyphenol content and authentic orchard flavor profiles, commanding margin premiums from California and New York metropolitan consumers seeking clean-label alternatives. HPP treatment is expanding refrigerated distribution reach without thermal degradation.
- Concentrated Juice:Water removal to 70-72 Brix enables efficient intercontinental shipping and year-round blending flexibility for beverage manufacturers.
- Sparkling Juice:Carbonation and secondary fermentation create occasion-based positioning in European on-premise channels and celebratory retail segments.
Mature deployment sits with Clear Juice. Newer deployment is concentrated in Cloudy Juice.
Packaging Type:
Cost tier determines material selection, with aseptic cartons dominating household replenishment and alternative formats capturing food service and convenience occasions.
- Cartons:Aseptic brick packs from Tetra Pak and SIG Combibloc enable 12-month ambient shelf life without refrigeration, capturing United States and German household volume through supermarket channels. Laminated paperboard construction reduces shipping weight versus glass alternatives.
- Bottles:PET and glass formats support premium positioning and resealability for multi-serve consumption, with glass commanding shelf differentiation in heritage-branded portfolios. Higher unit economics limit distribution to specialty retailers and direct-to-consumer channels.
- Pouches:Flexible film construction reduces material costs and shipping cube, gaining traction in food service portion control and children's lunchbox segments.
- Cans:Aluminum single-serve formats align with on-the-go consumption and recycling infrastructure in Japanese and South Korean convenience channels.
Cartons capture the steepest expansion trajectory in household replenishment channels. Cans represent the fastest-growing format in Asian convenience retail.
Sales Channel:
Customer access patterns split between consolidated grocery procurement and fragmented food service distribution, with digital platforms restructuring replenishment economics.
- Supermarkets:Slotting fees and promotional calendars govern brand visibility in United States and German mass retail, where private-label concentration pressures manufacturer margins. Category management practices favor multi-SKU suppliers with year-round promotional budgets.
- Online Retailers:Amazon Fresh and specialized beverage platforms bypass traditional distribution markups while building proprietary consumer data assets, expanding fastest in coastal United States metropolitan markets with delivery density economics.
- Convenience Stores:Impulse-driven single-serve purchases concentrate in urban Japan and South Korea, where refrigerated grab-and-go sets command premium pricing.
- Wholesale Distributors:Food service and institutional volume moves through Sysco and US Foods networks, with concentrate formats dominating bulk procurement for schools, hospitals, and airline catering.
Supermarkets anchor current volume concentration. Online Retailers are gaining share fastest in direct-to-household replenishment.
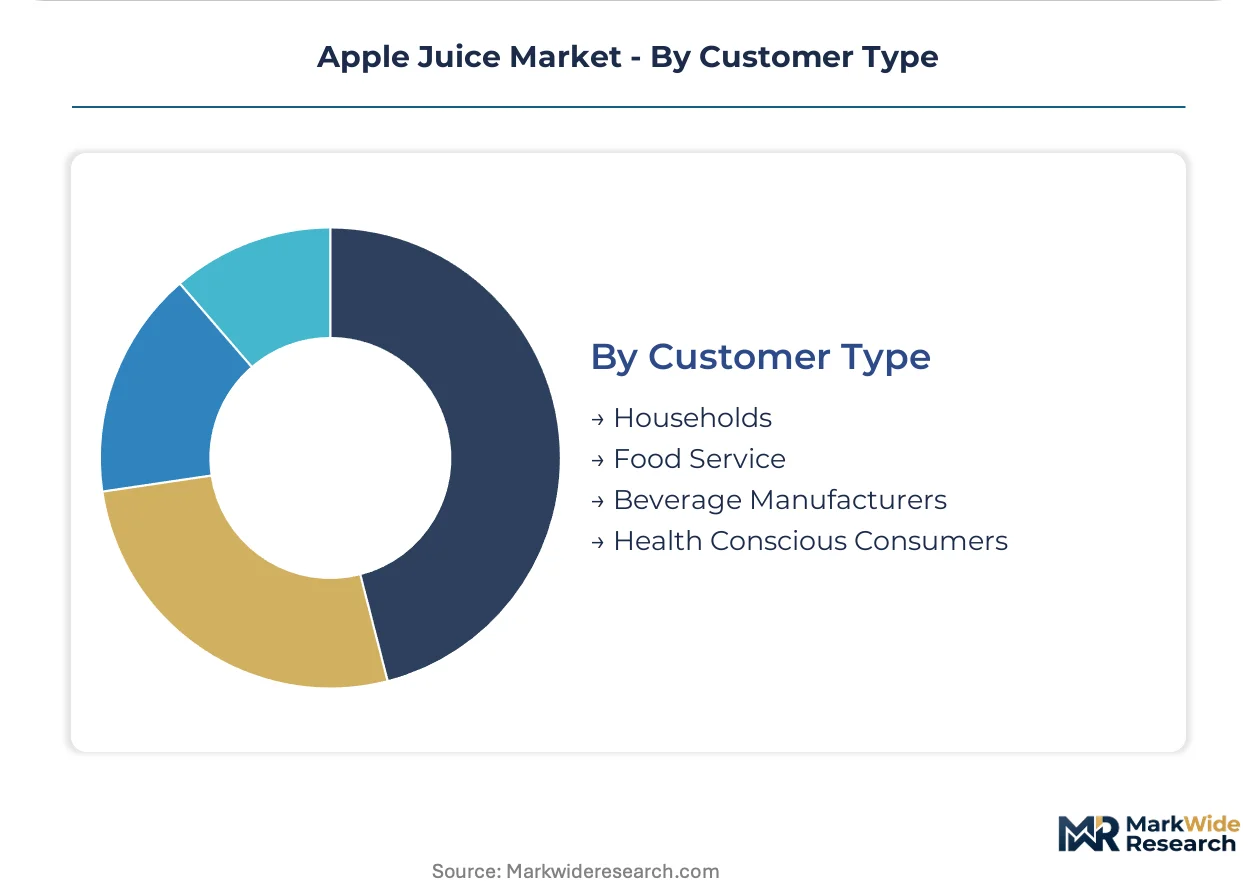
Customer Type:
Application requirements diverge between beverage-grade ingredient specifications and finished-product consumption occasions, with health positioning creating distinct formulation standards.
- Households:Multi-serve cartons and bottles dominate pantry replenishment in China, the United States, and Germany, with organic certification and reduced-sugar formulations commanding price premiums in affluent postal codes.
- Food Service:Fountain dispensers and portion-controlled pouches serve restaurants, hotels, and institutional cafeterias, where concentrate economics and minimal storage requirements drive procurement decisions.
- Beverage Manufacturers:Concentrate and clarified single-strength inputs supply juice blenders, cider producers, and functional beverage formulators requiring consistent Brix and acid profiles for recipe standardization.
- Health Conscious Consumers:Subscription platforms and specialty retailers target buyers prioritizing organic certification, HPP processing, and polyphenol retention, with willingness-to-pay premiums supporting smaller-batch production economics.
Beverage Manufacturers represent mature demand concentration. Health Conscious Consumers are expanding most quickly in subscription-based replenishment channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Poland and China dominate raw apple concentrate output, while the United States and Germany absorb the highest per-capita volumes of finished juice products. This production-consumption divide shapes trade flows and regional investment priorities across the value chain.
United States
Household replenishment through subscription platforms and organic certification premiums drive demand concentration in coastal metropolitan markets. The FDA enforces Hazard Analysis Critical Control Point mandates and updated added-sugar labeling requirements that force reformulation across conventional portfolios. Washington State orchard networks supply high-acid dessert varieties to Pacific Northwest processing facilities.
China
Urban middle-class consumers in Shanghai and Beijing displace carbonated soft drinks with 100% juice consumption in household channels. The Ministry of Ecology and Environment regulates agricultural chemical residues through tightening GB standards on orchard inputs. Shandong Province concentrate processors face volatile weather-driven crop yields that create price swings in international markets.
Germany
Discounter channel expansion creates private-label entry points for mid-tier concentrate suppliers prioritizing scale over margin capture. REACH chemical registration requirements mandate full supply chain disclosure for processing aids and packaging migrants, adding compliance costs. North Rhine-Westphalia packaging clusters host Tetra Pak and SIG Combibloc line installations serving Central European distribution networks.
Poland
Weather-driven crop volatility in European orchard belts concentrates price risk for concentrate producers dependent on regional raw material sourcing. The European Food Safety Authority governs maximum residue limits for agricultural chemicals that influence sourcing audit protocols. Mazovia Province processing facilities export bulk concentrate to German and Dutch beverage manufacturers.
India
Health-conscious urban consumers in Maharashtra and Karnataka adopt packaged juice alternatives to traditional beverages in modern retail channels. The Food Safety and Standards Authority of India enforces labeling and fortification standards that gate market access for imported concentrate products. Nashik orchard clusters in Maharashtra supply domestic processors with Sharabati and Kinnaur varieties.
Apple Juice Market Vendor Landscape
Top-tier vendors anchor premium positioning through heritage branding and controlled orchard networks, while mid-tier players compete on private-label scale and discounter channel access. The vendor base splits between vertically integrated orchard-to-bottle operators and concentrate-dependent blenders serving institutional buyers. Three archetypes dominate: heritage brand custodians, private-label scale suppliers, and functional beverage diversifiers. Competitive moves concentrate on backward integration into orchard assets and portfolio expansion into vitamin-fortified functional blends.
Within the heritage-brand tier, Martinelli & Company and Tree Top Inc. exemplify orchard-controlled supply chain strategies that command shelf-space differentiation. The Coca-Cola Company occupies a position spanning mass-market convenience formats through its Minute Maid portfolio. PepsiCo Inc. represents diversified beverage conglomerate exposure to juice category dynamics. These three anchors illustrate how scale, origin control, and distribution reach define competitive positioning across price tiers.
| Leading Market Players |
|---|
| Martinelli & Company |
| Apple & Eve LLC |
| Tree Top Inc. |
| PepsiCo Inc. |
| Manzana Products Co. Ltd. |
| Mott's |
| Musselman Premium |
| The Coca-Cola Company |
| Minute Maid |
| Others |
Supply Flow & Price Mechanics
Apple concentrate futures volatility cascades through three distinct pricing tiers, with Polish and Chinese crop yields compressing margins for economy-grade processors while organic-certified Pacific Northwest supply commands premium-mid-economy pricing differentiation for heritage brands.
Pricing Analysis
Cost-down pressure on economy-grade concentrate accelerates because weather-driven Polish crop shortfalls tighten raw material availability, forcing discounter private-label suppliers to absorb margin erosion. Three-tier pricing structure across premium, standard, and economy levels separates HPP-treated cloudy juice from enzymatically clarified cartons and bulk concentrate. Brand heritage and orchard-controlled provenance anchor premium tier pricing power. Food service buyers exhibit highest price sensitivity due to concentrate-dependent procurement economics.
Supply Chain Analysis
Direct-to-household subscription channels handle replenishment demand from health-conscious coastal consumers, while wholesale distributors move institutional volume through Sysco and US Foods networks. Raw apple concentrate supply draws from Poland, China, and the Pacific Northwest, with beverage manufacturers dependent on consistent Brix and acid profiles for recipe standardization. Single-origin dependency on Washington State high-acid dessert varieties creates structural vulnerability. Distribution runs through aseptic carton networks for ambient stability and refrigerated cold chains for HPP-treated SKUs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Competitive advantage in apple juice is consolidating around upstream orchard control and downstream subscription platform ownership, with first-movers capturing captive supply of organic-certified raw material.
For Market Incumbents: Hedge against concentrate price volatility through long-term offtake agreements with Polish and Chinese processors, while accelerating backward integration into Washington and New York organic orchard assets. Defensive patenting of HPP processing protocols protects polyphenol-retention claims from emerging clean-label competitors.
For New Entrants and Emerging Players: Begin with white-space targeting of India's Maharashtra and Karnataka modern retail channels, where packaged juice penetration remains nascent against traditional beverages. Direct-to-consumer subscription platforms offer lowest customer acquisition cost in United States coastal metropolitan markets with established delivery density.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier concentrate suppliers with discounter channel scale in Germany, where REACH compliance costs strain regional processor balance sheets. Orchard-controlled heritage brands with Pacific Northwest supply bases offer longest-dated optionality. Watch FDA enforcement thresholds on clean-label claims as inflection signal for reformulation investment cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Orchard Network Acquisition | Captive supply of organic-certified raw material locks in premium tier pricing power. |
| HPP Processing Scale-Up | Refrigerated shelf-life extension enables polyphenol-positioned SKUs in California metro markets. |
| Subscription Platform Launch | Direct-to-household channels bypass grocery slotting fees and build proprietary consumer data. |
| Discounter Private-Label Entry | German Aldi and Lidl expansion creates volume anchor for mid-tier concentrate suppliers. |
| Clean-Label Reformulation | FDA added-sugar disclosure compliance defends shelf position in school nutrition programs. |
Methodological Framework
USDA crop production reports, FDA enforcement actions, and customs trade data formed the secondary backbone, cross-referenced with primary interviews of orchard operations managers, beverage manufacturer procurement leads, Tetra Pak line engineers, and retail category buyers. Bottom-up volume modeling triangulated against top-down macroeconomic demand indicators to establish segment-level sizing.
Bottom-up modeling anchored the analytical lens, with top-down GDP-elasticity checks validating consumption projections across the analysis window. Segmentation dimensions included product type clarity, packaging material, sales channel, and customer application. CAGRs derived from historical volume trajectories and elasticity-adjusted per-capita consumption trends, with orchard yield volatility and regulatory reformulation timelines as key forecast inputs.
Underlying measurement precision varies by segment; subscription channel data carries tighter precision than fragmented food service estimates. Forecasts reflect assumptions on organic certification conversion rates and HPP equipment deployment timelines. Periodic stress-testing of base assumptions is recommended given EPA agricultural chemical tolerance revisions and weather-driven crop volatility.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
North America Juices Market
Beverages
India Bottled Water Market
Beverages
Hot Cocoa Mix Market
Beverages
Premium Bottled Water Market
Beverages
Global Soft Drinks Concentrate Market
Beverages
Whole Grain Drinks Market
Beverages
Bottled Beverages Market
Beverages
North America Ready-To-Drink (RTD) Beverages Market
Beverages
Italy Probiotic Drinks Market
Beverages
Saudi Arabia Drinking Water Market
Beverages
Hydration Infusers Market
Beverages
United Kingdom Energy Drink Market
Beverages
Saudi Arabia Food & Beverage Market
Beverages
Chocolate Malt Drink Market
Beverages
Aloe Vera-Based Drink Market
Beverages
Coconut Water Market