
 United States Rice Protein Market | 2026-2036
United States Rice Protein Market Size, Share, and Industry Trends Forecast 2026-2036
United States Rice Protein Market Analytics
Asset-light toll manufacturing is narrowing the capital barrier for mid-tier entrants in rice protein production. Axiom Foods Inc. leverages its proprietary extraction infrastructure to supply isolate-grade material to co-packers nationwide. RiceBran Technologies anchors its position through backward integration into rice bran sourcing across Gulf Coast milling networks. Kerry Group plc competes by extending its flavor masking technology to offset rice protein's sensory limitations.
Rice protein denotes the globulin and albumin fraction extracted from brown or white rice, typically yielding protein concentrations between 50% and 90% depending on processing intensity, with alkaline extraction and enzymatic hydrolysis constituting the dominant commercial methods. Its primary commercial purpose centers on delivering hypoallergenic, vegan protein fortification in applications where soy and dairy allergens exclude conventional alternatives. Isolate commands the dominant value share within product type segmentation due to its superior amino acid completeness and solubility profile. Nutritional supplements represent the fastest-expanding application channel, though food and beverage integration sustains larger absolute volume as mainstream CPG brands reformulate legacy lines. Online retail channels capture disproportionate growth velocity among market channels, reflecting direct-to-consumer protein brand proliferation.
The FDA exercises jurisdiction over rice protein safety and labeling under the Federal Food, Drug, and Cosmetic Act, while USDA Organic certification governs premium positioning for certified organic rice protein variants. California's Proposition 65 enforcement creates additional compliance burdens for heavy metal disclosure, directly influencing supplier qualification protocols for brands distributing in that state. Stakeholders must monitor evolving FDA positions on protein quality scoring methodologies, as PDCAAS and DIAAS adoption decisions will reshape competitive rankings among plant protein sources.
Market Dynamics
California's Proposition 65 enforcement is compressing supplier qualification timelines, forcing rice protein brands to pre-certify heavy metal compliance before entering the state's functional food manufacturing corridor. This regulatory pressure is reshaping procurement protocols nationwide as distributors demand batch-level documentation to avoid liability exposure.
Growth Catalysts
- FDA Plant-Based Protein Guidance:The agency's updated labeling framework clarifies protein quality claims, reducing formulation uncertainty for sports nutrition brands developing clean-label rice protein isolates.
- Enzymatic Hydrolysis Advancement:Improved extraction efficiency is lowering isolate production costs, enabling mid-tier co-packers to enter hypoallergenic protein fortification.
- Gulf Coast Rice Bran Concentration:Backward integration into regional milling networks secures captive supply for isolate-grade material, insulating processors from commodity volatility.
Market Restraints
- Input Cost Volatility:Organic brown rice premiums fluctuate with drought cycles in Arkansas and Louisiana, compressing margins for certified organic isolate variants.
- Sensory Limitation Barrier:Rice protein's inherent chalky mouthfeel requires expensive flavor masking technology, raising finished product costs versus pea or soy alternatives.
- Substitution Pressure:Pea protein isolate offers comparable amino acid profiles at lower price points, diverting R&D budgets from rice-based formulations in mainstream CPG.
Strategic Opportunities
- Pediatric Nutrition Expansion:Hypoallergenic positioning opens formulation opportunities in infant formula and toddler snack segments where soy and dairy exclusions dominate.
- Direct-to-Consumer Channel:Online retail velocity outpaces traditional distribution, allowing emerging brands to bypass broker networks and capture margin.
- USDA Organic Premium Tier:Certified organic rice protein commands price multiples in California's natural products retail cluster, rewarding early certification investment.
Industry Challenges
- PDCAAS Implementation Timeline:FDA adoption of updated protein quality scoring methodologies threatens competitive positioning versus animal proteins, requiring reformulation investment.
- Heavy Metal Testing Burden:California's Proposition 65 disclosure mandates necessitate third-party arsenic and cadmium screening for every production lot, extending quality control cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Rice Protein Market |
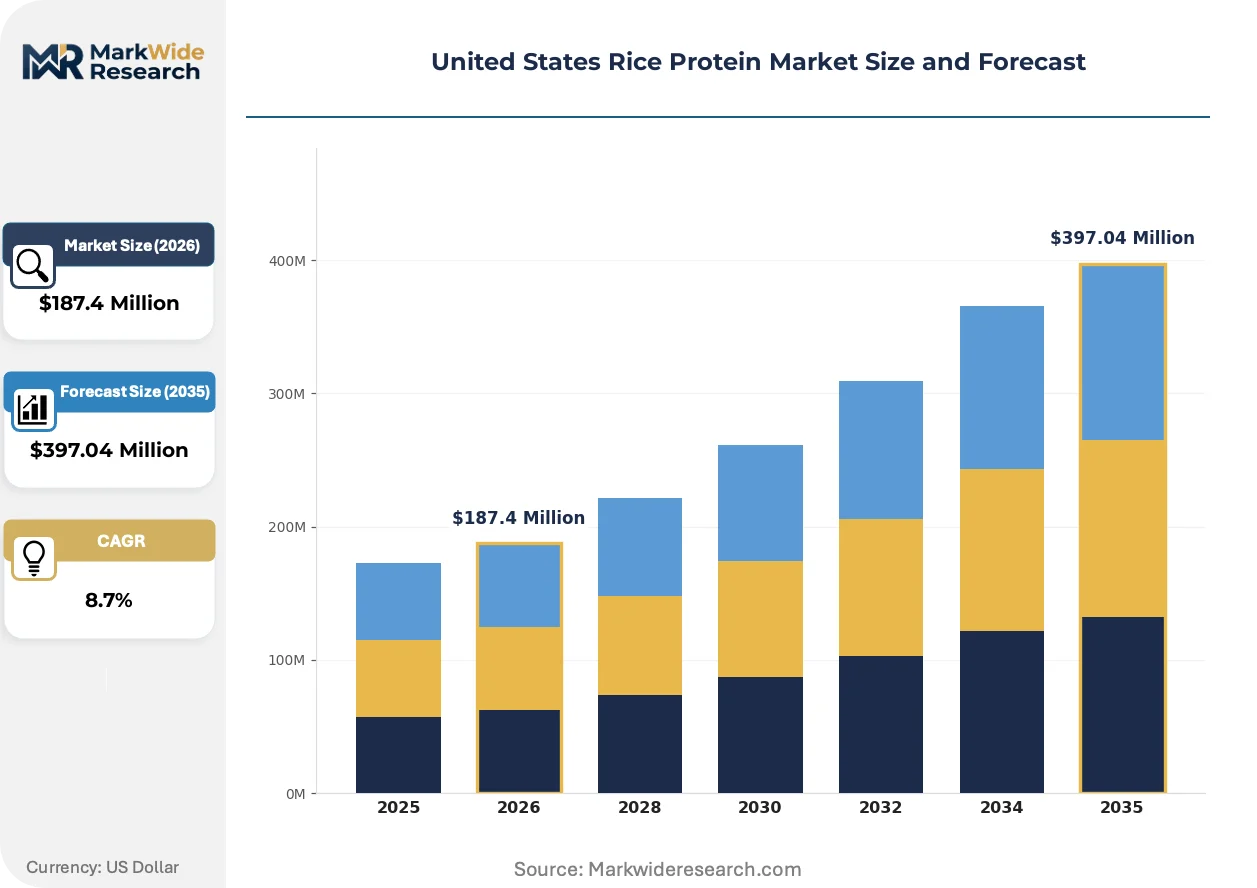
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Isolate, Concentrate, Hydrolysate, Native Application: Food & Beverage, Nutritional Supplements, Animal Feed, Bakery Products Market Channel: Online Retail, Supermarkets, Health Food Stores, Specialty Shops End User: Retail Consumers, Fitness Enthusiasts, Food Manufacturers, Healthcare Facilities |
| Companies Covered | Axiom Foods Inc., RiceBran Technologies, Kerry Group plc, Archer Daniels Midland Co., BENEO GmbH, AIDP Inc., Growing Naturals LLC, The Green Labs LLC, Shafi Gluco Chem Pvt. Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Rice Protein Market Evolving Landscape
Digital traceability infrastructure is penetrating rice protein supply chains, replacing paper-based batch records with blockchain-verified provenance systems. This shift is compressing audit timelines while elevating transparency expectations among California-based functional food manufacturers.
Inline spectroscopy is digitizing real-time protein concentration monitoring during enzymatic hydrolysis. Toll manufacturers in Arkansas and Louisiana are deploying these systems to reduce off-spec batches and accelerate isolate-grade output. The technology is compressing quality control labor costs while enabling continuous rather than batch processing.
FDA's evolving stance on plant-based protein quality scoring is forcing formulation teams to reconsider amino acid fortification strategies. The agency's DIAAS methodology exploration threatens rice protein's competitive standing versus dairy and egg alternatives. Sports nutrition brands in California are preemptively adding lysine to isolate formulations to protect label claims.
Buyer concentration among direct-to-consumer protein startups is fragmenting procurement patterns. These brands reject traditional distributor markups, sourcing isolate directly from Gulf Coast processors and co-packing in regional facilities. Texas and Florida have emerged as secondary co-manufacturing hubs serving this channel shift.
United States Rice Protein Market Segmentation
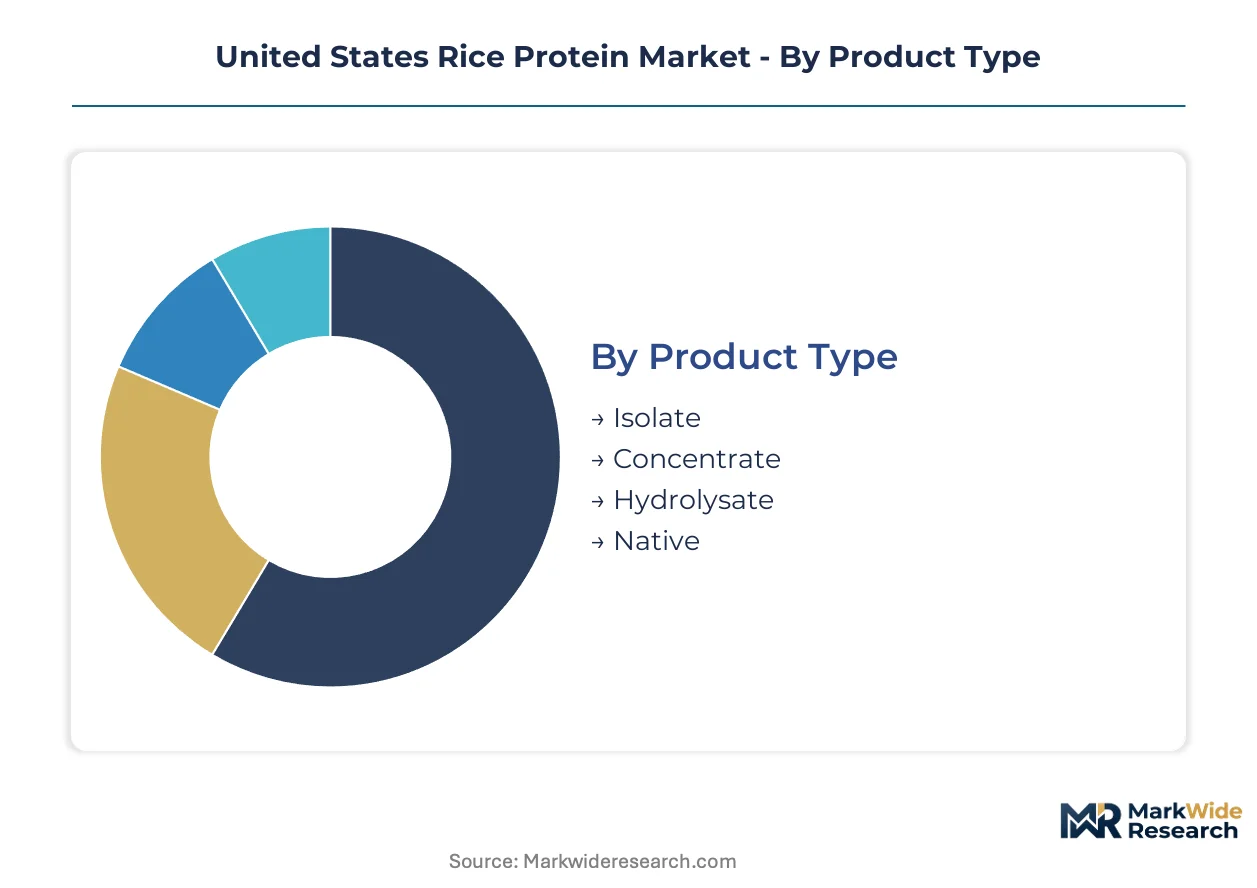
Rice protein segmentation reflects divergent technical specifications and procurement behaviors across the value chain. Manufacturers select grades based on solubility requirements, while channel choice determines margin capture and brand control.
Product Type:
The use-case spectrum spans clinical-grade isolates for infant nutrition to cost-optimized concentrates for mass-market fortification.
- Isolate:Protein concentrations reach 80-90% through intensive enzymatic hydrolysis and membrane filtration. California's functional food manufacturers specify isolate for pediatric and hypoallergenic applications where amino acid completeness determines regulatory approval.
- Concentrate:Processing yields 50-80% protein with retained fiber and starch fractions. Arkansas toll manufacturers supply concentrate to mainstream CPG brands reformulating legacy snack lines for clean-label positioning.
- Hydrolysate:Pre-digested peptide chains accelerate absorption kinetics. Sports nutrition formulators in Texas specify hydrolysate for post-workout recovery products targeting rapid amino acid availability.
- Native:Minimally processed rice protein retains natural protein structures. Louisiana processors market native grades to organic-certified pet food manufacturers seeking unmodified ingredient declarations.
Established volume favors concentrate; emerging adoption favors isolate.
Application:
Cost tier differentiation separates premium clinical applications from commodity feed inputs.
- Food & Beverage:Dairy alternatives, meat analogs, and functional beverages integrate rice protein for vegan positioning. National CPG brands in Illinois and Ohio specify isolate for plant-based milk fortification.
- Nutritional Supplements:Powder and ready-to-drink formats target fitness and senior nutrition segments. Direct-to-consumer brands bypass traditional distribution, sourcing directly from Gulf Coast processors.
- Animal Feed:Rice protein concentrate replaces soy in premium pet food formulations. Missouri pet food manufacturers specify non-GMO concentrate for grain-free product lines.
- Bakery Products:Gluten-free bread and pastry applications leverage rice protein for structure and protein fortification. Artisan bakeries in Oregon and Washington state specify organic concentrate.
Food & Beverage commands absolute volume; Nutritional Supplements climbs the fastest.
Market Channel:
Customer type determines margin structure and brand proximity.
- Online Retail:Direct-to-consumer protein brands capture 40-60 point margin premiums through subscription models. Amazon and brand-owned storefronts dominate isolate sales to fitness enthusiasts.
- Supermarkets:Mass-market distribution requires slotting fee investments and broker networks. National chains in Texas and Florida drive concentrate volume through private label placement.
- Health Food Stores:Regional cooperatives and natural products retailers prioritize USDA Organic certification. California's independent stores command premium pricing for traceable supply chains.
- Specialty Shops:CrossFit boxes, yoga studios, and nutrition clinics sell curated protein portfolios. These outlets favor hydrolysate for personalized coaching relationships.
Supermarkets retain volume leadership; Online Retail gains share fastest.
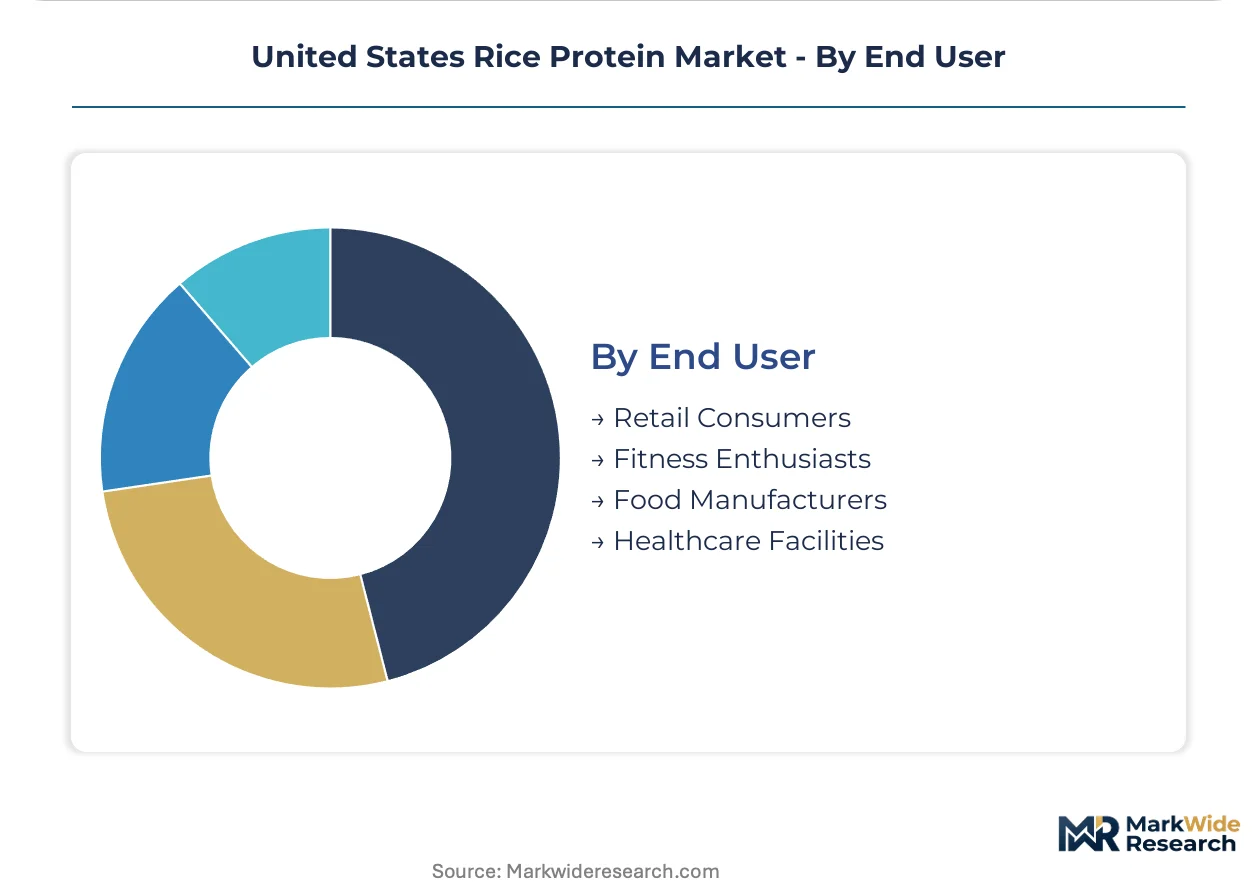
End User:
Maturity gradients separate established food manufacturing demand from emerging clinical applications.
- Retail Consumers:Home cooking and smoothie preparation drive concentrate purchases through grocery and online channels. Clean-label awareness elevates organic specification rates.
- Fitness Enthusiasts:Strength athletes and endurance competitors prioritize leucine content and digestibility scores. This segment over-indexes on hydrolysate and isolate grades.
- Food Manufacturers:Ingredient procurement teams negotiate long-term contracts with Arkansas and Louisiana processors. Reformulation timelines extend 18-24 months for legacy brand renovations.
- Healthcare Facilities:Hospital systems and long-term care facilities specify hypoallergenic protein for enteral nutrition. Clinical dietitians in Massachusetts and Minnesota drive institutional adoption.
Food Manufacturers anchor procurement volume; Healthcare Facilities represent the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Functional food manufacturers cluster in specific states where rice bran supply chains intersect with clean-label demand centers. Procurement teams prioritize proximity to Gulf Coast milling networks and California's regulatory corridor.
California
Clean-label sports nutrition brands drive isolate demand in Los Angeles and San Francisco functional food corridors. Proposition 65 enforcement mandates third-party heavy metal screening for every production lot entering distribution. Sacramento's regulatory proximity shapes nationwide compliance protocols as brands pre-certify arsenic thresholds before multi-state expansion.
Arkansas
Toll manufacturers leverage enzymatic hydrolysis infrastructure to supply concentrate grades for mainstream CPG reformulation. USDA Organic certification rates fluctuate with drought cycles affecting brown rice premiums. Little Rock processors anchor backward integration into regional milling networks, securing captive bran supply for isolate production.
Louisiana
Gulf Coast rice bran concentration supports both food-grade and pet food applications. Native protein grades dominate organic-certified pet food manufacturing in Baton Rouge industrial zones. New Orleans port access enables bulk export positioning for isolate-grade material serving Texas co-manufacturing hubs.
Texas
Secondary co-manufacturing clusters emerged in Dallas-Fort Worth and Houston serving direct-to-consumer protein startups. These brands bypass traditional broker networks, sourcing isolate directly from Gulf Coast processors. FDA labeling guidance compliance costs compress margins for emerging entrants without established quality systems.
Illinois and Ohio
National CPG headquarters in Chicago and Cincinnati drive long-term concentrate contracts for plant-based milk fortification. Reformulation timelines extend eighteen to twenty-four months for legacy brand renovations. Midwest procurement teams negotiate volume commitments with Arkansas processors to secure price stability.
United States Rice Protein Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented procurement patterns. The vendor base separates into three tiers: integrated bran processors with captive supply, toll manufacturers with extraction infrastructure, and flavor technology providers masking sensory limitations. Consolidation pressure concentrates among mid-tier entrants facing California compliance costs. Dominant competitive moves include backward integration into Gulf Coast milling networks and enzymatic hydrolysis licensing to co-packers.
Among integrated processors, Axiom Foods Inc. and RiceBran Technologies occupy positions spanning extraction infrastructure and regional bran sourcing. Kerry Group plc exemplifies the technology-provider archetype, extending flavor masking capabilities to offset rice protein's chalky mouthfeel. These three entities represent distinct competitive vectors: captive supply security, toll manufacturing scale, and sensory modification expertise.
| Leading Market Players |
|---|
| Axiom Foods Inc. |
| RiceBran Technologies |
| Kerry Group plc |
| Archer Daniels Midland Co. |
| BENEO GmbH |
| AIDP Inc. |
| Growing Naturals LLC |
| The Green Labs LLC |
| Shafi Gluco Chem Pvt. Ltd. |
| Others |
Value Network & Pricing Analysis
Gulf Coast milling networks in Arkansas and Louisiana concentrate isolate-grade rice protein capacity, granting processors downstream pricing leverage over California functional food manufacturers facing Proposition 65 compliance premiums. This geographic asymmetry between raw material supply and regulatory demand centers compresses margin capture for mid-tier brands while rewarding backward-integrated players.
Pricing Analysis
Cost-plus contracts indexed to organic brown rice futures dominate procurement between Arkansas toll manufacturers and national CPG buyers. Price differentiation separates USDA Organic-certified isolate from conventional concentrate grades, with California's natural products retail cluster absorbing the widest premium spreads. Pricing pressure intensifies in the concentrate tier as pea protein substitution erodes volume commitments from mainstream snack reformulators. Food manufacturers exhibit highest price sensitivity due to eighteen-to-twenty-four-month reformulation timelines, while direct-to-consumer brands prioritize amino acid completeness over unit economics.
Supply Chain Analysis
Tariff exposure between the United States and Asian rice bran feedstock markets elevates input cost volatility for non-integrated processors. Geographic supply concentrates in Arkansas, Louisiana, and California, with Gulf Coast networks anchoring food-grade extraction and Sacramento corridor facilities handling final isolate refinement. Raw material dependencies rest on organic brown rice premiums, enzymatic hydrolysis reagents, and membrane filtration equipment. Single-source vulnerability characterizes the toll manufacturing tier where Axiom Foods and RiceBran Technologies control captive bran supply. Distribution runs through direct processor-to-brand contracts for isolate, while concentrate moves via regional distributors serving Midwest CPG headquarters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a certification-attach opportunity. Third-party heavy metal screening and USDA Organic validation generate recurring revenue layers expanding faster than base isolate production as California's Proposition 65 enforcement propagates nationwide.
For Market Incumbents: Build regulatory compliance moats by pre-certifying arsenic thresholds for every production lot before multi-state expansion. Deepen backward integration into Gulf Coast milling networks to insulate margin from organic brown rice premium volatility. Pea protein substitution in mainstream CPG represents the primary threat vector; counter by extending enzymatic hydrolysis licensing to co-packers seeking hypoallergenic differentiation. For New Entrants and Emerging Players: Establish a beachhead in pediatric nutrition formulations where hypoallergenic positioning commands regulatory-driven premiums. The healthcare facilities segment offers lowest competitive density as clinical dietitians in Massachusetts and Minnesota drive institutional adoption. Bypass traditional broker networks by sourcing isolate directly from Louisiana processors and co-packing in Texas facilities serving direct-to-consumer subscription brands. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because FDA's evolving DIAAS methodology exploration threatens rice protein's competitive standing versus animal proteins, rewarding early movers in amino acid fortification infrastructure. Target toll manufacturers with proprietary extraction infrastructure and established California compliance protocols. The signal to watch is batch-level heavy metal disclosure mandates spreading beyond California to other state jurisdictions.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Gulf Coast Milling | Captive bran supply from Arkansas and Louisiana networks insulates processors from commodity volatility. |
| Enzymatic Hydrolysis Licensing | Technology transfer to co-packers expands isolate-grade output without capital-intensive capacity expansion. |
| USDA Organic Certification Investment | Premium positioning in California's natural products retail cluster rewards early certification with price multiples. |
| Direct-to-Consumer Channel Bypass | Processor-to-brand contracts eliminate distributor markups and capture forty-to-sixty-point margin premiums. |
| Flavor Masking Technology Partnership | Sensory modification expertise from Kerry Group plc offsets rice protein's inherent chalky mouthfeel barrier. |
Research Methodology
Operator-level perspectives from rice protein extraction engineers, California functional food formulators, Gulf Coast milling procurement leads, and FDA regulatory affairs specialists anchored the qualitative base. Primary interview data combined with secondary validation from USDA organic certification databases, FDA guidance documents, California OEHHA Proposition 65 enforcement records, and Arkansas agricultural extension reports. Bottom-up capacity modeling and top-down demand segmentation triangulated volume estimates.
Scenario-bracketing framed the analytical approach across the projection horizon, with CAGRs derived from segmented growth rate blending. Modeling dimensions spanned product type tier, application channel, certification status, and regional production cluster. Forecast inputs incorporated enzymatic hydrolysis yield improvements and direct-to-consumer channel velocity shifts.
Sensitivities concentrate around FDA DIAAS adoption timelines, California heavy metal disclosure mandate propagation, and organic brown rice drought-cycle premiums. Forecasts reflect documented assumptions on protein quality scoring methodology evolution and channel migration patterns. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
India Plant Based Meat Alternatives Market
Plant Based Food
Low Fat Plant-Based Diet Market
Plant Based Food
Fermented Plant-Based Food Market
Plant Based Food
Plant-Based Fish Market
Plant Based Food
Plant Based Cheese Market
Plant Based Food
India Plant Based Milk Market
Plant Based Food
France Plant Protein Market
Plant Based Food
Fermented Plant Protein Market
Plant Based Food
US Plant-Based Meat Market
Plant Based Food
United Kingdom Soy Protein Market
Plant Based Food
Plant Based Eggs Market
Plant Based Food
Insoluble Pea Protein Market
Plant Based Food
Plant-Based Chicken Market
Plant Based Food
Oat Protein Market
Plant Based Food
Vegan Protein Foods Market
Plant Based Food
Faba Bean Protein Market