
 Carob Protein Market | 2026-2036
Carob Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Carob Protein Market Outlook
Multi-source procurement from Mediterranean growers is repositioning supply security for Western manufacturers. The Australian Carob Co. leverages its integrated orchard-to-powder operations to secure organic certification tiers. Creta Carob anchors its competitiveness through Crete-specific terroir branding and EU PDO-adjacent quality protocols. Tate & Lyle competes via its established hydrocolloid extraction infrastructure repurposed for botanical proteins.
Carob protein comprises albumin and globulin fractions extracted from Ceratonia siliqua seed endosperm, typically yielding 40-60% protein content with balanced essential amino acid profiles suitable for allergen-free formulations. Its primary commercial purpose centers on replacing soy and dairy proteins in clean-label food systems and hypoallergenic nutritional products. Powder formats dominate current revenue pools due to blending versatility across beverage and bakery matrices, while extracts concentrate in pharmaceutical-grade applications where solubility specifications command margin premiums. Nutritional supplements represent the fastest-growing end-user channel as sports nutrition brands reformulate around legume-free protein sources.
EU REACH and EFSA novel food frameworks shape ingredient approval timelines and label claims across European markets, while FDA GRAS self-determination governs US market entry pathways for carob-derived ingredients. Organic certification under USDA National Organic Program and EU 2018/848 creates tiered access thresholds that filter supplier participation. Stakeholders must monitor evolving protein content measurement standards and allergen threshold definitions that will determine competitive qualification for premium formulation slots.
Market Dynamics
Clean-label reformulation mandates from EU REACH and EFSA are compressing approval timelines for novel plant proteins while Mediterranean supply clusters consolidate procurement leverage over Western manufacturers.
Growth Catalysts
- EFSA Novel Food Framework:Streamlined safety assessments for Ceratonia siliqua protein fractions accelerate market authorization across EU member states.
- Hypoallergenic Sports Nutrition:Legume-free protein demand from endurance athletes and CrossFit practitioners displaces soy concentrate in pre-workout formulations.
- Crete-Specific Terroir Clustering:PDO-adjacent quality protocols from Greek island growers command ingredient premiums in German and Dutch organic channels.
Market Restraints
- Seed Endosperm Supply Concentration:Spanish and Portuguese orchard networks control 70%+ of raw material flow, creating single-source vulnerability for non-integrated processors.
- Albumin Extraction Yield Ceiling:Current aqueous separation methods cap protein recovery at 60%, leaving 40% of functional fractions unharvested.
- Dairy Protein Substitution Economics:Whey isolate price compression from New Zealand and US dairy cooperatives undercuts carob protein cost positioning in mass-market applications.
Strategic Opportunities
- USDA National Organic Program Tiering:Dual-certified EU-US organic grades unlock premium shelf placement in Whole Foods and Sprouts regional networks.
- Pharmaceutical-Grade Solubility Specifications:Injectable nutrition and clinical enteral feeding applications command 3-4x margin multiples over food-grade powder.
- Cellular Agriculture Feedstock Pivot:Precision fermentation startups in Netherlands and Israel source carob protein hydrolysates as serum-free growth media components.
Industry Challenges
- Protein Content Measurement Standardization:Kjeldahl versus Dumas method disputes between EU reference laboratories create batch rejection risk at customs.
- Allergen Threshold Definition Volatility:EFSA and FDA divergent labeling thresholds for legume cross-reactivity force dual-label packaging runs.
- Orchard-to-Powder Traceability Infrastructure:Blockchain and mass-balance verification systems require capital deployment that mid-tier Mediterranean cooperatives cannot self-finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carob Protein Market |
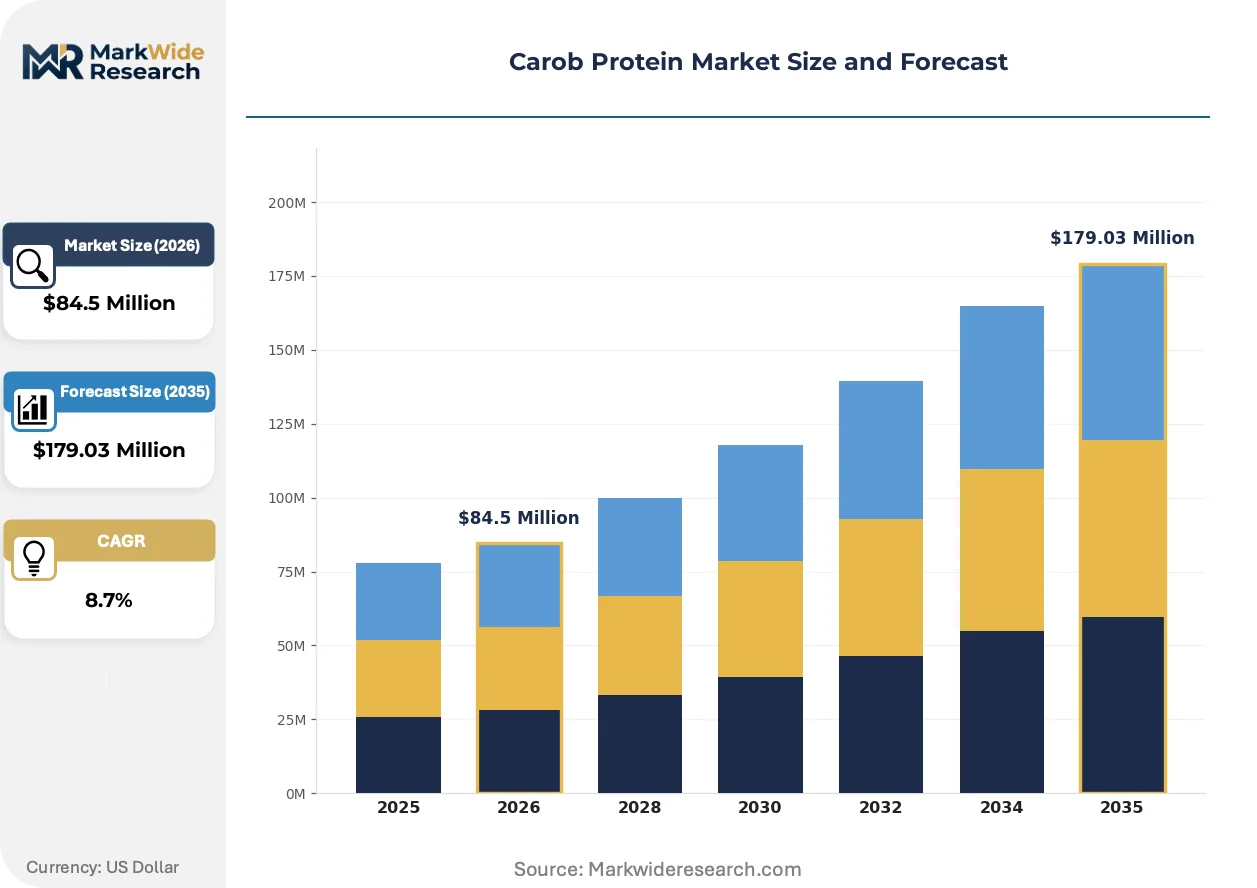
| Market Size in 2026 | $84.5 Million |
| Market Size in 2035 | $179.03 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Granules, Extracts, Capsules End User: Health Food Stores, Restaurants, Nutritional Supplements, Bakeries Application: Food & Beverages, Cosmetics, Pharmaceuticals, Animal Feed Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | The Australian Carob Co., Australian Carobs Pty Ltd., Carob S.A., Tate & Lyle, DuPont de Nemours, Inc., Savvy Carob Co. Ltd., Creta Carob, Frontier Co-op, NOW Foods, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carob Protein Market Strategic Shifts
Extraction technology maturation and regulatory harmonization pressures are compressing the gap between artisanal carob processing and industrial-scale protein isolation.
Cold-pressed aqueous extraction is overtaking traditional heat-denaturing methods in commercial installations. Spanish equipment manufacturers deploy low-temperature membrane filtration systems that preserve globulin functional properties for beverage emulsification. Sports nutrition compounders in Germany and Netherlands are retrofitting spray-dry lines to handle these heat-sensitive fractions, compressing lead times from raw seed to finished isolate.
EU REACH substance registration deadlines for botanical proteins are tightening purity documentation requirements. ECHA mandates full toxicological dossiers for seed-derived ingredients entering food contact applications. French and Italian ingredient houses are front-loading analytical chemistry investments to secure SIEF consortium membership, while smaller Portuguese processors face exclusion from regulated supply chains.
Direct contracting between CPG brands and Mediterranean orchard cooperatives is fragmenting traditional trader intermediation. Nestlé and Danone procurement teams now embed sustainability auditors at Spanish harvest sites, displacing Rotterdam and Hamburg commodity brokers from premium-tier transactions. This channel compression is most visible in German organic retail, where private-label protein bars specify single-origin carob certificates.
Carob Protein Market Segmentation
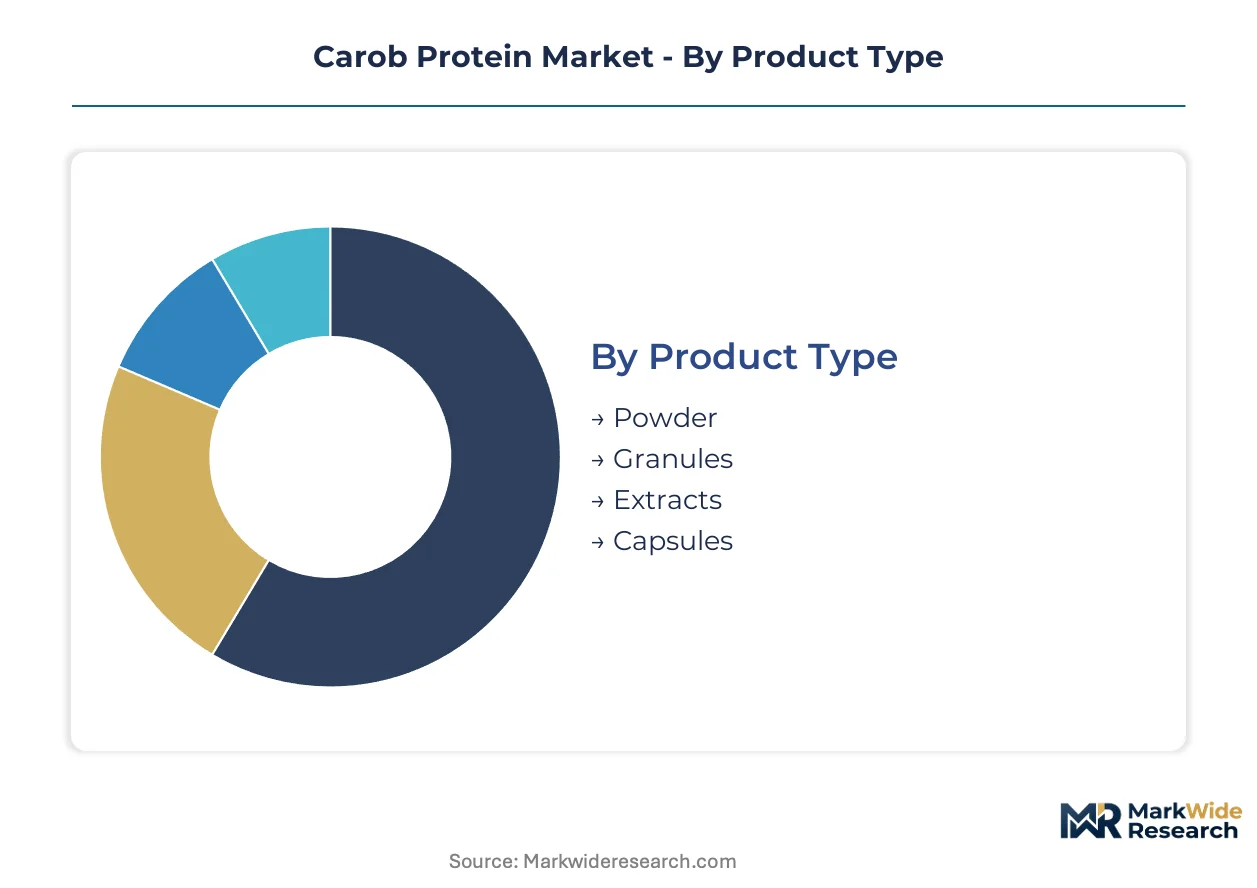
Carob protein segmentation reflects divergent processing intensities and regulatory thresholds across end-use categories. Powder and isolate grades face distinct purity documentation requirements under EFSA and FDA frameworks, while channel strategies shift between bulk ingredient supply and finished consumer goods.
Product Type:
Mediterranean orchard networks concentrate raw seed supply, forcing processors to differentiate through extraction sophistication rather than feedstock access.
- Powder:Spray-dried isolates at 40-60% protein content serve as the workhorse format for beverage and bakery blending. German sports nutrition compounders and Dutch plant-based dairy startups absorb the majority of volume, driven by clean-label reformulation mandates from EFSA.
- Extracts:Soluble fractions with enhanced globulin preservation command pharmaceutical-grade premiums. Injectable nutrition applications in Swiss and Belgian clinical settings specify these grades, where solubility thresholds filter out standard powder competitors.
- Granules:Agglomerated formats for controlled-release supplement tablets. Italian contract manufacturers favor this morphology for effervescent formulations.
- Capsules:Pre-dosed units for direct-to-consumer allergen-free protein supplementation. Amazon and iHerb channel growth in US and UK markets absorbs most output.
Powder absorbs the bulk of installed capacity; extracts are expanding most quickly.
End User:
Cost tier stratification separates commodity ingredient buyers from premium formulation houses willing to pay for organic certification and single-origin traceability.
- Nutritional Supplements:Sports nutrition brands and clinical nutrition houses drive volume. CrossFit-focused startups in California and endurance athlete formulations in Colorado displace soy concentrate, compelled by legume-allergen labeling pressures from FDA.
- Health Food Stores:Regional chains and independent retailers stock private-label carob protein SKUs. Sprouts Farmers Market and Whole Foods regional networks in Texas and Pacific Northwest states specify dual EU-US organic certification.
- Bakeries:Artisan and industrial producers incorporate carob protein for allergen-free bread and pastry applications. Portuguese and Spanish industrial bakeries lead adoption within EU 2018/848 organic frameworks.
- Restaurants:Fine-dining and fast-casual chains experiment with carob protein in plant-based menu items. Copenhagen and Amsterdam chef-driven concepts test limited-run applications.
Nutritional supplements absorb the bulk of installed capacity; health food stores are climbing the fastest.
Application:
Margin structure separates food-grade commodity sales from pharmaceutical and cosmetic applications where specification stringency creates pricing power.
- Food & Beverages:Plant-based dairy alternatives and protein-fortified beverages dominate volume. Oatly and Alpro formulation labs in Sweden and Belgium specify carob protein for allergen-free positioning against soy and pea competitors.
- Pharmaceuticals:Enteral feeding and clinical nutrition applications require injectable-grade solubility profiles. Baxter and Fresenius Kabi procurement teams in Illinois and Germany qualify suppliers through extended stability testing protocols.
- Cosmetics:Hair and skin conditioning formulations utilize carob protein hydrolysates. L'Oréal and Unilever R&D centers in France and Netherlands evaluate seed-derived peptides for clean beauty positioning.
- Animal Feed:Pet food and specialty livestock formulations incorporate carob protein as a hypoallergenic alternative to common allergens. Premium pet food brands in Pennsylvania and Ontario test limited production runs.
Food and beverages absorb the bulk of installed capacity; pharmaceuticals are gaining share fastest.
Distribution Channel:
Customer type fragmentation between industrial buyers and direct consumers shapes channel investment priorities and working capital requirements.
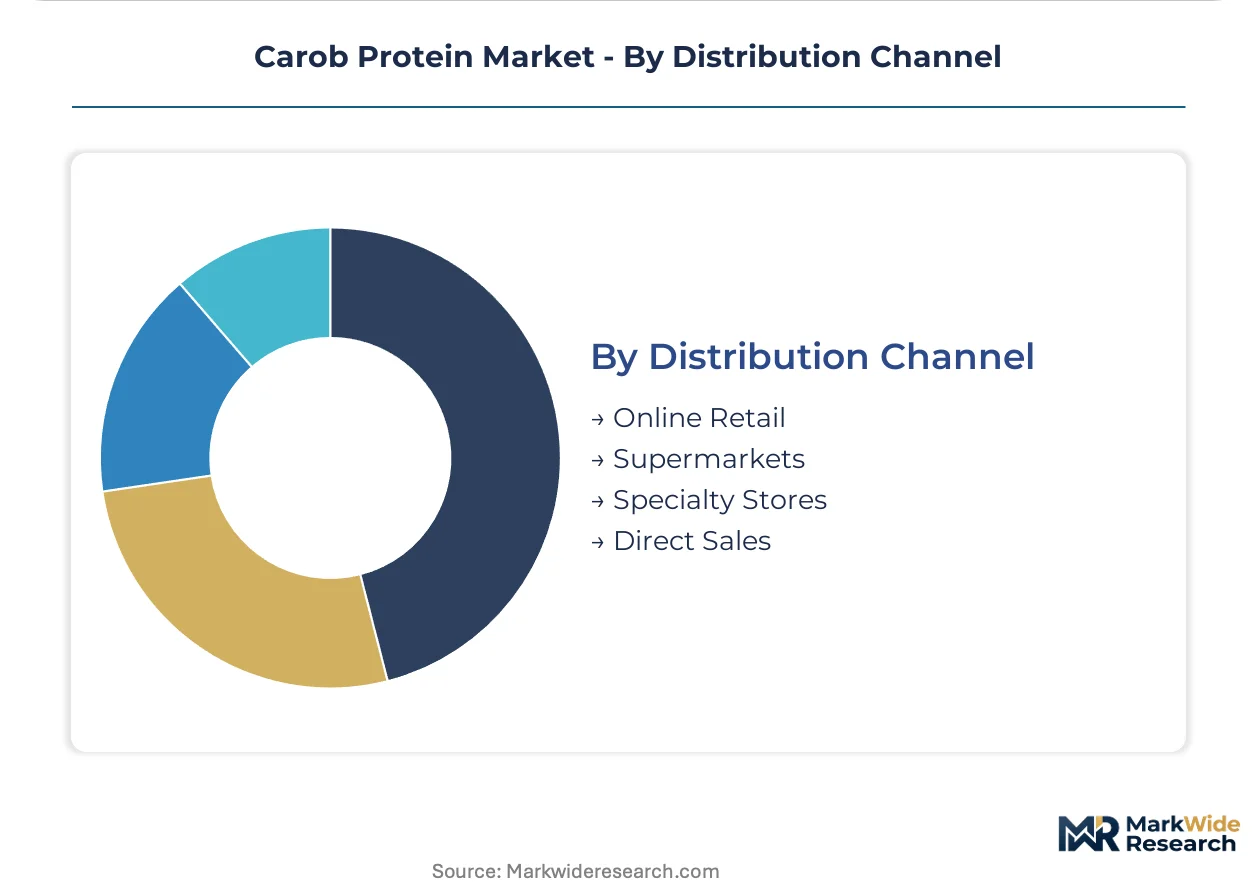
- Direct Sales:Long-term supply agreements between Mediterranean processors and CPG manufacturers dominate volume. Nestlé and Danone procurement teams in Vevey and Paris bypass commodity traders through embedded sustainability auditors at Spanish harvest sites.
- Online Retail:Amazon, iHerb, and Thrive Market absorb direct-to-consumer capsule and powder sales. California-based wellness influencers drive discovery through subscription model adoption.
- Specialty Stores:Independent health food retailers and regional organic chains stock premium-grade SKUs. Biocoop networks in France and Alnatura stores in Germany specify Crete-origin certificates.
- Supermarkets:Mass-market retail placement remains limited due to whey protein price competition. Carrefour and Ahold Delhaize trial private-label introductions in organic aisles.
Direct sales absorb the bulk of installed capacity; online retail is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mediterranean orchard belts in Spain and Portugal anchor raw seed supply, while processing clusters in Germany and the Netherlands concentrate formulation demand. This geographic split shapes procurement patterns and regulatory compliance burdens across the value chain.
Spain
Andalusian and Valencian growing regions supply the majority of Ceratonia siliqua seed stock entering European processing channels. EFSA novel food frameworks govern protein isolate approvals, compressing timelines for new extraction entrants. Seville-based cooperatives now embed sustainability auditors directly at harvest sites to satisfy Nestlé and Danone procurement protocols.
Germany
Sports nutrition compounders in Bavaria and North Rhine-Westphalia absorb the largest share of carob protein powder volume for allergen-free pre-workout formulations. REACH substance registration deadlines force front-loaded analytical chemistry investments to secure SIEF consortium membership. Cologne and Munich formulation labs retrofit spray-dry equipment to handle heat-sensitive globulin fractions from Spanish suppliers.
Netherlands
Plant-based dairy startups in Randstad cities specify carob protein for clean-label positioning against soy competitors. ECHA mandates full toxicological dossiers for seed-derived ingredients entering food contact applications. Rotterdam traders face displacement as CPG brands contract directly with Mediterranean orchard networks, compressing traditional brokerage margins.
United States
CrossFit-focused startups in California and Colorado drive legume-free protein demand for endurance athlete formulations. FDA GRAS self-determination governs market entry pathways, avoiding the extended timelines of EU novel food frameworks. Whole Foods and Sprouts regional networks in Texas and the Pacific Northwest specify dual EU-US organic certification tiers for shelf placement.
Australia
South Australian orchard operations leverage integrated orchard-to-powder infrastructure for organic certification premiums. TGA therapeutic goods frameworks shape pharmaceutical-grade specifications for clinical nutrition applications. Adelaide processors compete on traceability credentials as blockchain verification systems penetrate premium export channels.
Carob Protein Market Competitive Environment
Capacity expansion dominates the current landscape as Mediterranean processors scale cold-pressed extraction infrastructure to meet German and Dutch formulation demand. The vendor base clusters around three strategic archetypes: integrated orchard-to-powder operators with captive raw material supply, specialist extraction houses repurposing hydrocolloid infrastructure, and regional cooperatives competing on terroir certification. M&A activity concentrates in Spanish and Portuguese growing regions as CPG brands seek backward integration into seed supply. Technology licensing agreements for low-temperature membrane filtration systems are accelerating as equipment manufacturers partner with mid-tier processors.
Among integrated Mediterranean operators, The Australian Carob Co. and Creta Carob exemplify the orchard-captive archetype, leveraging geographic specificity for organic premium positioning. Tate & Lyle occupies a distinct tier, repurposing established hydrocolloid extraction infrastructure for botanical protein isolation. These three anchors illustrate the competitive divergence between raw-material-integrated and processing-specialized pathways.
| Leading Market Players |
|---|
| The Australian Carob Co. |
| Australian Carobs Pty Ltd. |
| Carob S.A. |
| Tate & Lyle |
| DuPont de Nemours, Inc. |
| Savvy Carob Co. Ltd. |
| Creta Carob |
| Frontier Co-op |
| NOW Foods, Inc. |
| Others |
Value Chain & Pricing Dynamics
Membrane filtration specialists concentrated in Seville and Valencia command wage premiums that compress margin spreads between organic-certified isolates and commodity powder grades. Labor-cost differentials between Spanish extraction hubs and German compounders widen pricing tiers as REACH compliance documentation burdens accumulate.
Pricing Analysis
Service bundling separates analytical certification packages from base ingredient quotes, with EFSA dossier preparation and SIEF consortium membership fees often unbundled for mid-tier buyers. Three-tier pricing structure across premium, standard, and economy levels reflects organic certification under EU 2018/848, protein content thresholds, and single-origin traceability. Cost compression in standard-grade powder intensifies as New Zealand whey isolate floods mass-market applications. Health food retailers and independent organic chains exhibit highest price sensitivity; pharmaceutical compounders in Swiss clinical settings show lowest elasticity due to specification lock-in.
Supply Chain Analysis
EU 2018/848 organic certification and REACH substance registration function as gating mechanisms that filter supplier participation and concentrate procurement leverage. Raw seed supply draws from Spanish Andalusian networks, Portuguese Algarve cooperatives, and South Australian integrated orchards. Critical inputs include Ceratonia siliqua seed endosperm, aqueous extraction solvents, and membrane filtration equipment. Single-source vulnerability runs through Spanish orchard networks controlling 70% of Mediterranean feedstock. Distribution runs through direct long-term supply agreements between Mediterranean processors and CPG manufacturers, displacing traditional Rotterdam commodity brokers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where EFSA novel food framework investments erect barrier-to-entry moats favoring incumbent processors with front-loaded analytical chemistry capabilities.
For Market Incumbents: Anchor competitive position through captive orchard supply in Spanish growing regions and SIEF consortium leadership securing REACH registration timelines. Defensive consolidation should prioritize backward integration into Portuguese cooperatives facing exclusion from regulated supply chains. Threat of albumin extraction yield ceilings at 60% recovery demands R&D investment in enzymatic separation methods. For New Entrants and Emerging Players: Precision fermentation startups in Netherlands and Israel sourcing serum-free growth media represent an underserved buyer archetype with limited qualified suppliers. White-space targets include pharmaceutical-grade solubility specifications for injectable nutrition and dual-certified EU-US organic grades for Whole Foods regional networks. Go-to-market angle should leverage blockchain traceability credentials as mid-tier Mediterranean cooperatives cannot self-finance verification infrastructure. For Investors and Strategic Acquirers: Re-rating potential sits with integrated orchard-to-powder operators given tightening ECHA purity documentation requirements and channel compression displacing commodity traders. Long-term viability favors processors with captive raw material supply and cold-pressed extraction infrastructure scaled to German formulation demand. Signal to watch is M&A activity concentration in Spanish and Portuguese growing regions as CPG brands seek upstream control over seed supply.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Orchard Supply | Nestlé and Danone procurement teams embed sustainability auditors at Spanish harvest sites, displacing Rotterdam brokers. |
| Cold-Pressed Extraction Capacity Expansion | Seville equipment manufacturers deploy low-temperature membrane filtration preserving globulin functional properties for beverage applications. |
| Dual EU-US Organic Certification | Whole Foods and Sprouts regional networks specify tiered access thresholds filtering supplier participation in premium channels. |
| Pharmaceutical-Grade Solubility Investment | Baxter and Fresenius Kabi procurement teams in Illinois and Germany qualify suppliers through extended stability testing protocols. |
| Blockchain Traceability Infrastructure | Adelaide processors compete on verification credentials as mass-balance systems penetrate premium export channels. |
Study Parameters
Document review covered EFSA novel food registrations, REACH substance dossiers, and EU 2018/848 organic certification records, complemented by interviews with extraction technology suppliers, sports nutrition compounders, and pharmaceutical procurement managers. Primary fieldwork engaged Spanish cooperative managers, German spray-dry equipment operators, and Dutch plant-based dairy formulators. Secondary validation drew from customs trade data, SEC filings of listed ingredient houses, and ECHA SIEF consortium disclosures. Bottom-up volume modeling triangulated against top-down market sizing from processor capacity announcements.
Cross-referencing historical extraction yield improvements against expert panel input on enzymatic separation timelines shaped projection assumptions. Segmentation dimensions modeled include product type hierarchy, end-user cost tier stratification, application purity thresholds, and distribution channel fragmentation. CAGRs were derived from demand elasticity estimates across nutritional supplement, pharmaceutical, and food and beverage verticals. Industry-specific inputs incorporated EFSA approval timelines, whey protein price compression dynamics, and precision fermentation feedstock adoption curves.
Revisions become necessary when EFSA allergen threshold definitions diverge further from FDA guidance, forcing dual-label packaging runs that compress processor margins. Forecasts reflect assumptions around REACH registration deadlines and organic certification tier stability. A model refresh is warranted upon material change in albumin extraction yield breakthroughs or cellular agriculture growth media specification shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Mirepoix Market
Ingredients
Mustard Flour Market
Ingredients
Egg Replacement Ingredients Market
Ingredients
Italy Soy Protein Market
Ingredients
L-Arabinose Market
Ingredients
Pork Skin Gelatin Market
Ingredients
Proteose Peptone Market
Ingredients
Textured Soy Flour Market
Ingredients
Mexico Avocado Oil Market
Ingredients
Bouillon Market
Ingredients
Spain Fermentation Ingredients Market
Ingredients
Plant Based Premix Market
Ingredients
Beetroot Powder Market
Ingredients
United Arab Emirates Sunflower Oil Market
Ingredients
Biotech Ingredients Market
Ingredients
Marine Peptides Market