
 1 - 4 - Cyclohexanedimethanol Dibenzoate Market | 2026-2036
1 - 4 - Cyclohexanedimethanol Dibenzoate Market Size, Share, and Industry Trends Forecast 2026-2036
1 - 4 - Cyclohexanedimethanol Dibenzoate Market Outlook
Automotive interior formulation demand is shifting toward non-phthalate plasticizer systems as OEMs face tightening substance restrictions across major supply jurisdictions. Eastman Chemical Company leverages its integrated cyclohexane derivatives platform to sustain cost-competitive dibenzoate supply for Tier 1 compounders. BASF SE anchors European supply through its Ludwigshafen specialty esters network, while Evonik Industries AG differentiates via high-purity grades targeting medical-device-adjacent polymer specifications.
1 - 4 - Cyclohexanedimethanol dibenzoate functions as a cycloaliphatic diol-derived dibenzoate ester plasticizer, typically manufactured through esterification of 1,4-cyclohexanedimethanol with benzoic acid under catalytic conditions, valued for its low volatility, UV stability, and compatibility with polar polymers including PVC, polyurethane, and polyester systems. The plasticizers product type dominates current volume as processors substitute legacy phthalates in flexible compounds, while coatings applications represent the fastest-expanding structural segment driven by powder-coating resin demand for appliance and architectural metal finishes. Polyester resins maintain mature, margin-defensive positioning in saturated packaging film and industrial fiber applications where formulation switching costs deter substitution.
REACH Annex XVII phthalate restrictions and EPA TSCA Section 6 risk evaluations for conventional plasticizers are reshaping qualified supplier lists and testing burdens for compounders serving regulated end-uses. FDA indirect food contact clearances under 21 CFR 175.105 and 176.170 govern adhesive and paper-coating applications, creating segmented compliance pathways that fragment addressable market access. Stakeholders must monitor evolving state-level substance prohibitions and polymer recycling mandates that could redefine acceptable plasticizer chemistries in closed-loop material systems.
Market Dynamics
REACH Annex XVII phthalate restrictions and EPA TSCA Section 6 risk evaluations are forcing compounders to reformulate flexible PVC and TPU systems, redirecting procurement toward cycloaliphatic dibenzoate alternatives with established regulatory clearances.
Growth Catalysts
- Automotive interior mandates:OEMs in Germany and the U.S. Gulf Coast corridor are qualifying non-phthalate plasticizers for dashboard and seating applications ahead of 2025 substance restriction deadlines.
- Powder coating resin demand:Appliance manufacturers in China are specifying low-volatility plasticizers for high-temperature cure cycles in architectural metal finishes.
- REACH compliance pathways:The ECHA authorization process for legacy orthophthalates is accelerating technical validation of 1,4-cyclohexanedimethanol dibenzoate in medical-device-adjacent polymer specifications.
Market Restraints
- Benzoic acid feedstock volatility:Pricing pressure from toluene oxidation capacity constraints in the U.S. Gulf Coast and Ludwigshafen clusters compresses esterification margins.
- Cyclohexane derivative supply concentration:Three integrated petrochemical platforms control upstream 1,4-cyclohexanedimethanol availability, creating bottleneck risk for non-captive compounders.
- Performance ceiling in polar elastomers:Compatibility gaps with high-nitrile NBR and certain TPU grades limit addressable substitution volume against adipate and sebacate alternatives.
Strategic Opportunities
- Medical tubing qualification:USP Class VI and ISO 10993 biocompatibility pathways for high-purity grades open catheter and IV-set applications previously locked by DEHP dominance.
- India BIS standardization:Pending adoption of phthalate limits in flexible PVC for food contact and toys creates pre-standard positioning windows for qualified importers.
- Circular polymer integration:Recycling mandates under EU Packaging and Packaging Waste Regulation are driving R&D into plasticizer stability across multiple reprocessing cycles.
Industry Challenges
- Multijurisdictional testing burdens:Compounders must maintain parallel FDA 21 CFR, REACH SVHC, and state-level California Proposition 65 dossiers, extending qualification timelines.
- Esterification catalyst IP:Proprietary organotin and titanium alkoxide process technologies are concentrated among legacy patent holders, complicating new entrant process design.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 1 - 4 - Cyclohexanedimethanol Dibenzoate Market |
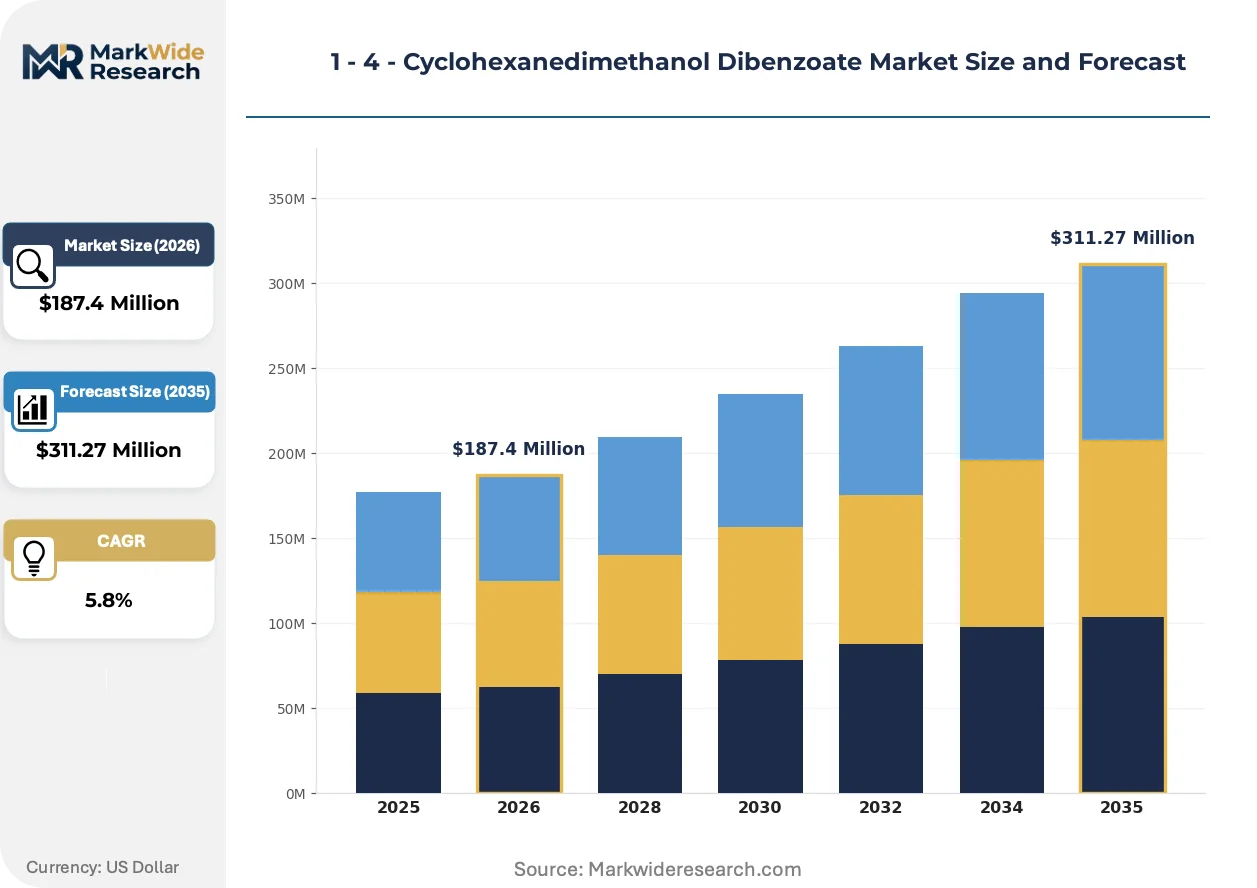
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyester Resins, Plasticizers, Coatings, Adhesives Application: Automotive, Consumer Electronics, Construction, Furniture End User: Manufacturers, Distributors, Retailers, Contractors Distribution Channel: Online Sales, Direct Sales, Wholesalers, Retail Outlets |
| Companies Covered | BASF SE, Eastman Chemical Company, Clariant AG, DuPont de Nemours, Evonik Industries AG, Solvay SA, SABIC, Huntsman Corporation, Merck KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
1 - 4 - Cyclohexanedimethanol Dibenzoate Market Strategic Shifts
Digital formulation platforms and closed-loop recycling requirements are compressing traditional plasticizer selection cycles while elevating traceability and lifecycle assessment capabilities among compounders.
Continuous esterification reactor technology is automating temperature and residence time control to reduce batch-to-batch viscosity variation. Tier 1 automotive compounders in Germany and Michigan are retrofitting semi-batch assets with inline NIR monitoring. This automation is compressing qualification sample rejection rates and accelerating OEM approval timelines.
EPA TSCA Section 6 risk evaluations for conventional plasticizers are expanding testing mandates for chronic toxicity endpoints. The industrial consequence is a bifurcation between large compounders with in-house toxicology capabilities and mid-tier processors dependent on external testing. Medical-device polymer specifications face the steepest compliance cost escalation.
Specification-driven procurement is consolidating qualified supplier lists around plasticizers with pre-submitted FDA master files and REACH registration completeness. Distributors in the U.S. Gulf Coast and Rotterdam are culling non-compliant inventory. This consolidation is most visible among automotive Tier 2 compounders serving German and U.S. OEMs with zero-defect supply agreements.
1 - 4 - Cyclohexanedimethanol Dibenzoate Market Segmentation
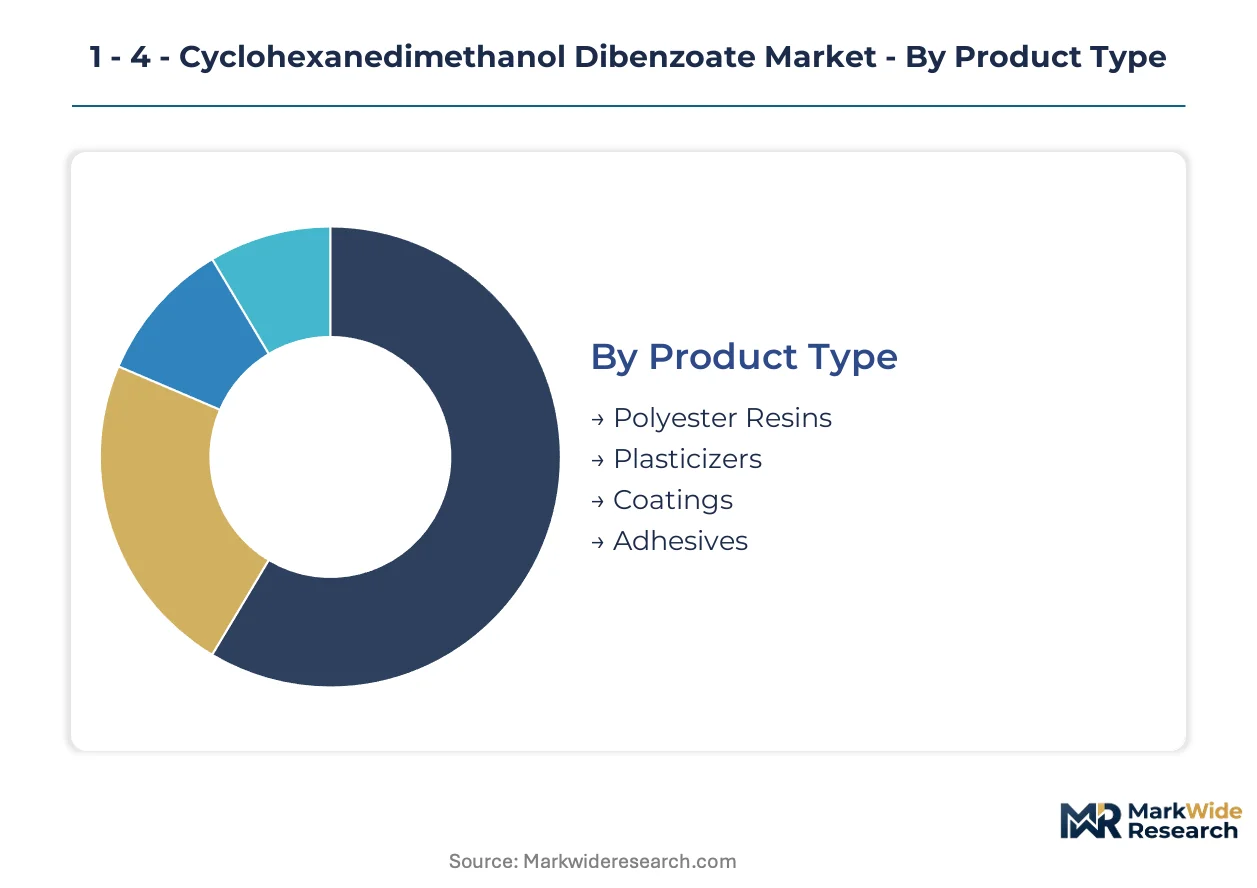
Segmentation in the 1,4-cyclohexanedimethanol dibenzoate market reflects how formulation chemistry, end-use performance requirements, and regulatory compliance pathways intersect. Understanding these divisions clarifies where substitution economics favor cycloaliphatic dibenzoates over legacy orthophthalates and competing plasticizer chemistries.
Product Type:
Integration depth varies sharply across product types, with some functioning as standalone additives while others embed into complex polymer matrices requiring multi-component formulation expertise.
- Plasticizers:These low-volatility ester compounds soften PVC, TPU, and polar elastomers for flexible applications. Demand concentrates in automotive interior compounds for German and U.S. Gulf Coast OEMs facing REACH Annex XVII and state-level phthalate prohibitions.
- Coatings:Powder-coating resin formulations leverage UV stability and thermal resistance during high-temperature cure cycles. Appliance manufacturers in China specify these grades for architectural metal finishes where volatility constraints are stringent.
- Polyester Resins:Saturated packaging film and industrial fiber applications maintain steady consumption with limited substitution incentive due to high formulation switching costs.
- Adhesives:FDA 21 CFR 175.105 compliant grades serve food-contact paper and packaging laminates requiring indirect food contact clearances.
Plasticizers lead volumes today; coatings are gaining share fastest.
Application:
Cost tier differentiation separates specification-driven automotive procurement from price-sensitive construction segments, with electronics occupying a mid-tier performance band.
- Automotive:Dashboard, seating, and interior trim applications dominate premium-grade consumption. Tier 1 compounders in Michigan and Germany qualify non-phthalate systems ahead of regulatory deadlines.
- Construction:Flooring, roofing membranes, and sealant applications prioritize cost efficiency over performance differentiation, limiting dibenzoate penetration against commodity adipates.
- Consumer Electronics:Cable jacketing and device housings require low-fogging, low-odor specifications for enclosed spaces.
- Furniture:Upholstery and synthetic leather applications face fragmented demand across residential and commercial contract segments.
Automotive commands premium pricing; consumer electronics shows steepest expansion trajectory.
End User:
Customer type determines technical service intensity, with manufacturers requiring formulation support while distributors manage inventory risk for standardized grades.
- Manufacturers:Polymer compounders and resin producers drive bulk volume through direct supply agreements with specified quality certificates.
- Distributors:Regional chemical distributors in Rotterdam and the U.S. Gulf Coast maintain qualified supplier lists around REACH registration completeness and FDA master file status.
- Retailers:Specialty chemical retailers serve small-batch processors and R&D laboratories with packaged quantities.
- Contractors:Application-specific contractors in flooring and adhesives represent fragmented, price-sensitive demand.
Manufacturers dominate current offtake; distributors are expanding fastest.
Distribution Channel:
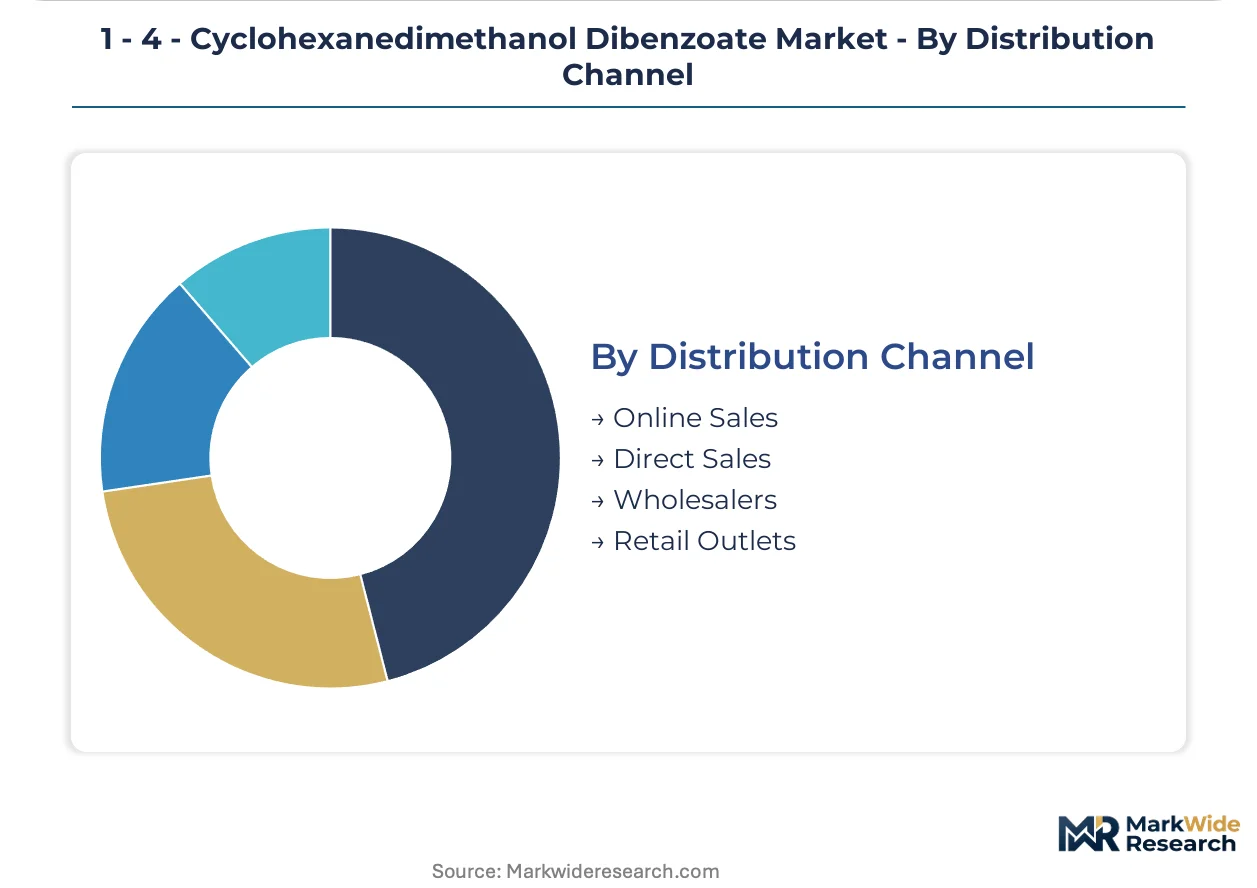
Supply chain configuration separates high-touch direct relationships for qualified automotive grades from low-margin wholesale movement of standard esters.
- Direct Sales:Captive supply agreements with German and U.S. automotive Tier 1 compounders include technical service, joint formulation development, and audit rights.
- Wholesalers:Bulk chemical wholesalers aggregate demand from mid-tier processors, managing inventory across multiple ester chemistries.
- Online Sales:E-procurement platforms serve small-volume buyers with standardized specifications and rapid delivery requirements.
- Retail Outlets:Physical specialty chemical distributors support regional construction and furniture manufacturers with immediate availability.
Direct sales anchor revenue today; online channels are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production geography as compounders relocate formulation activities to jurisdictions with streamlined substance authorization pathways. Cost-of-compliance gaps between REACH-registered European supply and emerging Asian capacity are redirecting investment toward integrated petrochemical corridors with captive upstream feedstock.
United States
Automotive interior reformulation drives demand as Michigan and Ohio-based Tier 1 compounders qualify non-phthalate systems for Detroit Three OEMs. EPA TSCA Section 6 risk evaluations for conventional plasticizers are compressing qualified supplier lists ahead of 2025 deadlines. The U.S. Gulf Coast petrochemical corridor anchors domestic supply through integrated cyclohexane derivative platforms serving regional compounders.
Germany
Dashboard and seating applications dominate premium-grade consumption as Volkswagen Group and BMW accelerate phthalate substitution timelines. REACH Annex XVII restrictions and ECHA authorization processes for legacy orthophthalates are forcing technical revalidation of alternative plasticizers. The Ludwigshafen chemical cluster maintains European supply concentration through specialty esters networks with backward integration into benzoic acid feedstock.
China
Powder-coating resin demand from appliance manufacturers is expanding fastest as Haier and Midea specify low-volatility plasticizers for architectural metal finishes. GB standards for food-contact materials and evolving substance restrictions under MEE oversight are fragmenting compliance pathways. The Yangtze River Delta concentration of polyester resin producers is absorbing growing dibenzoate volumes for high-temperature cure applications.
India
Flexible PVC compounders serving toy and food-contact packaging segments are pre-positioning for anticipated BIS phthalate limits. CDSCO medical device regulations and DGFT import monitoring are creating qualification windows for USP-grade material ahead of formal standard adoption. Maharashtra and Gujarat-based processors represent the primary demand concentration for technical-grade plasticizer substitution.
Japan
Consumer electronics cable jacketing requirements for low-fogging specifications sustain niche demand from Sony and Panasonic supply chains. METI chemical substance management frameworks and JIS standards for electrical materials govern plasticizer selection in enclosed device applications. The Kansai industrial belt maintains specialized compounding capacity for high-performance polar polymer systems.
1 - 4 - Cyclohexanedimethanol Dibenzoate Market Competitive Environment
Capacity expansion dominates the current landscape as integrated petrochemical operators extend cyclohexane derivative value chains into specialty esters. The market structure concentrates around three upstream feedstock controllers with captive 1,4-cyclohexanedimethanol supply, creating bottleneck exposure for non-integrated compounders. Strategic archetypes separate integrated petrochemical majors, specialty ester pure-plays, and regional formulation distributors. Competitive moves center on backward integration into benzoic acid supply and geographic expansion into emerging regulatory jurisdictions.
Among European-based integrated operators, BASF SE and Evonik Industries AG exemplify the specialty ester archetype with concentration in high-purity grades. Eastman Chemical Company occupies a position within the North American integrated tier, representing cyclohexane derivative platform control. These three anchors illustrate how feedstock integration separates margin-defensive positioning from distributor-dependent competitors.
| Leading Market Players |
|---|
| BASF SE |
| Eastman Chemical Company |
| Clariant AG |
| DuPont de Nemours |
| Evonik Industries AG |
| Solvay SA |
| SABIC |
| Huntsman Corporation |
| Merck KGaA |
| Others |
Value Chain & Pricing Dynamics
Specialized esterification chemists concentrated in Germany's Ludwigshafen cluster and the U.S. Gulf Coast petrochemical corridor create labor-cost differentials that widen pricing-tier spreads between pharmaceutical-grade and industrial-grade dibenzoate supply.
Pricing Analysis
Distributor margin layers separate standard industrial grades from pharmaceutical-certified material by certification tier and volume commitment. Three-tier pricing structure across pharmaceutical, automotive-specification, and industrial economy levels reflects FDA master file status and REACH registration completeness. Pricing pressure stems from benzoic acid feedstock volatility in toluene oxidation markets. Construction compounders exhibit highest price sensitivity; medical-device polymer suppliers accept premium positioning for biocompatibility documentation.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale automotive compounder demand while regional distributors manage mid-tier processor inventory. Manufacturing concentrates in Germany, the United States, and China across integrated cyclohexane derivative platforms. Upstream supply draws from captive 1,4-cyclohexanedimethanol production, benzoic acid from toluene oxidation, and specialty esterification catalysts. Single-source vulnerability in pharmaceutical-grade purification creates bottleneck exposure. Distribution runs through qualified supplier lists anchored by REACH registration and FDA master file status.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as automotive OEM procurement shifts toward pharmaceutical-grade plasticizer specifications with pre-submitted regulatory dossiers.
For Market Incumbents: Anchor backward integration into benzoic acid supply to defend margin compression from toluene oxidation capacity constraints. Expand high-purity esterification capacity in Ludwigshafen or the U.S. Gulf Coast to capture medical-device polymer qualification windows before CDSCO and BIS standard adoption closes.
For New Entrants and Emerging Players: Begin with powder-coating resin applications in China's Yangtze River Delta appliance manufacturing cluster, where low-volatility specifications create specification-driven entry points. Pursue distributor partnerships in Rotterdam and Mumbai to bypass direct automotive qualification barriers.
For Investors and Strategic Acquirers: Specialty ester pure-plays with REACH-registered asset bases are the most active acquirer targets in this space. Long-term viability hinges on circular polymer integration capabilities under EU Packaging and Packaging Waste Regulation mandates. Monitor India BIS phthalate limit adoption as inflection signal for qualified import demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Benzoic Acid | Captive toluene oxidation capacity insulates esterification margins from feedstock volatility in Ludwigshafen. |
| Pharmaceutical-Grade Capacity Expansion | USP Class VI certification opens catheter and IV-set applications previously locked by DEHP dominance. |
| REACH Registration Completeness Investment | Full SVHC dossier submission secures qualified supplier status with German automotive Tier 1 compounders. |
| India Pre-Standard Positioning | Technical-grade qualification ahead of BIS adoption creates first-mover advantage in flexible PVC substitution. |
| Circular Polymer R&D Partnership | Multi-cycle reprocessing stability validation aligns with EU Packaging and Packaging Waste Regulation requirements. |
Study Parameters
Bottom-up automotive and coatings formulation modeling reconciled against top-down cyclohexane derivative capacity tracking forms the analytical core. Primary interviews with polymer compounders, automotive Tier 1 procurement leads, specialty ester plant managers, and pharmaceutical-device regulatory affairs directors combined with secondary validation from ECHA registration databases, FDA 21 CFR master file repositories, customs trade data, and SEC chemical sector filings. Triangulation across supply-side capacity announcements and demand-side qualification timelines anchored volume estimates.
Historical trendline analysis of plasticizer substitution rates in automotive interior applications informed projection frameworks across the analysis window. Segmentation dimensions modeled include product grade tier, end-use industry vertical, regulatory compliance pathway, and regional production hub. CAGRs derived from elasticity-adjusted substitution curves against phthalate restriction implementation schedules. Forecast inputs incorporated REACH Annex XVII expansion scenarios and EPA TSCA Section 6 risk evaluation timelines.
Several conditions sit outside the modeled scope, including unforeseen polymer recycling technology disruptions and accelerated orthophthalate bans beyond current regulatory calendars. Forecasts reflect stated assumptions around feedstock cost trajectories and qualification timeline adherence. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Magnesium Gluconate Market
Specialty Chemicals
Optical Whitening Agents Market
Specialty Chemicals
Fatty Acid Methyl Ester Market
Specialty Chemicals
Fatty Alcohol Alkoxylates Market
Specialty Chemicals
Global Spray Polyurethanes Foam Market
Specialty Chemicals
Europe Non-Phthalate Plasticizers Market
Specialty Chemicals
Ferrous Gluconate Market
Specialty Chemicals
Global Mannosylerythritol Lipids Market
Specialty Chemicals
Fabric Softener and Conditioner Market
Specialty Chemicals
Toner Spray Market
Specialty Chemicals
Chromium Polynicotinate Market
Specialty Chemicals
Bio-Based Phenol Market
Specialty Chemicals
Ascorbic Acid Market
Specialty Chemicals
Micronized PTFE Market
Specialty Chemicals
Pegylated Lipids Market
Specialty Chemicals
Ubiquinone Market