
 Global Kraft Paper Market | 2026-2036
Global Kraft Paper Market Size, Share, and Industry Trends Forecast 2026-2036
Global Kraft Paper Market Foresight
E-commerce fulfillment centers are bifurcating demand away from traditional retail packaging buyers toward direct-to-consumer shippers. Mondi Group leverages its integrated pulp-to-paper operations across European mills to serve corrugated and flexible packaging converters. Smurfit Westrock anchors its competitive stance through containerboard and kraft linerboard scale in the Americas. Stora Enso differentiates via biomaterials R&D and renewable packaging certification programs.
Kraft paper is a high-strength paper produced by the sulfate pulping process, using sodium hydroxide and sodium sulfide to separate lignin from cellulose fibers, yielding tear-resistant sheets with basis weights typically ranging from 30 to 350 grams per square meter. Its primary commercial purpose centers on protective packaging, carrier bags, and industrial wrapping where tensile strength and printability matter. Brown kraft paper dominates volume shipments across the packaging application segment, while reinforced kraft paper commands margin pools in heavy-duty industrial wrapping. Bags and rolls lead the packaging type dimension, though sheets are gaining traction in automated fulfillment lines for dimensional consistency.
The EPA enforces recycled fiber standards under Comprehensive Procurement Guidelines that shape kraft paper sourcing for federal contractors. REACH and the EU Packaging and Packaging Waste Regulation constrain chemical additives and mandate minimum recycled content thresholds for packaging placed on European markets. India's BIS certifies kraft paper grades under IS 4664 for packaging applications, creating compliance gateways for imported rolls. Stakeholders must monitor how diverging recycled-content mandates across Washington, Brussels, and New Delhi reshape raw material procurement and cross-border trade flows.
Market Dynamics
E-commerce fulfillment networks are pulling kraft paper demand away from traditional retail packaging channels, while recycled-content mandates in Brussels, Washington, and New Delhi force simultaneous reformulation of furnish mixes across integrated mills.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Mandatory minimum recycled-content thresholds for packaging placed on European markets are compelling converters to secure certified kraft supply contracts.
- Quick-commerce grocery delivery:India’s rapid scaling of 10-minute delivery models is generating fresh demand for food-grade kraft bags and protective wraps.
- Sulfate pulping efficiency gains:Recovery boiler upgrades across Scandinavian mills are lowering per-unit energy intensity for unbleached kraft linerboard.
Market Restraints
- Recovered fiber cost volatility:Old corrugated container prices swing with Chinese import quota shifts, squeezing margin pools for recycled-content kraft grades.
- Bleached pulp substitution:White-top linerboard and coated alternatives capture premium print applications where visual presentation outweighs tear strength.
- REACH chemical compliance:Restrictions on wet-strength additives limit performance specifications for frozen-food kraft packaging in European markets.
Strategic Opportunities
- Automated fulfillment lines:Dimensional consistency requirements in robotic packing cells favor precision-cut kraft sheet formats over variable roll goods.
- India’s BIS IS 4664 certification:Compliance gateways for imported rolls create first-mover advantages for mills achieving early certification.
- Bio-based barrier coatings:Integration of cellulose nanofibril treatments with conventional kraft substrates opens oil-resistant food packaging applications.
Industry Challenges
- Recovered fiber sorting expertise:Mills struggle to source technicians capable of managing mixed-paper stream contamination at scale.
- Dual certification timelines:Simultaneous pursuit of FDA food-contact approvals and EU REACH compliance extends product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Kraft Paper Market |
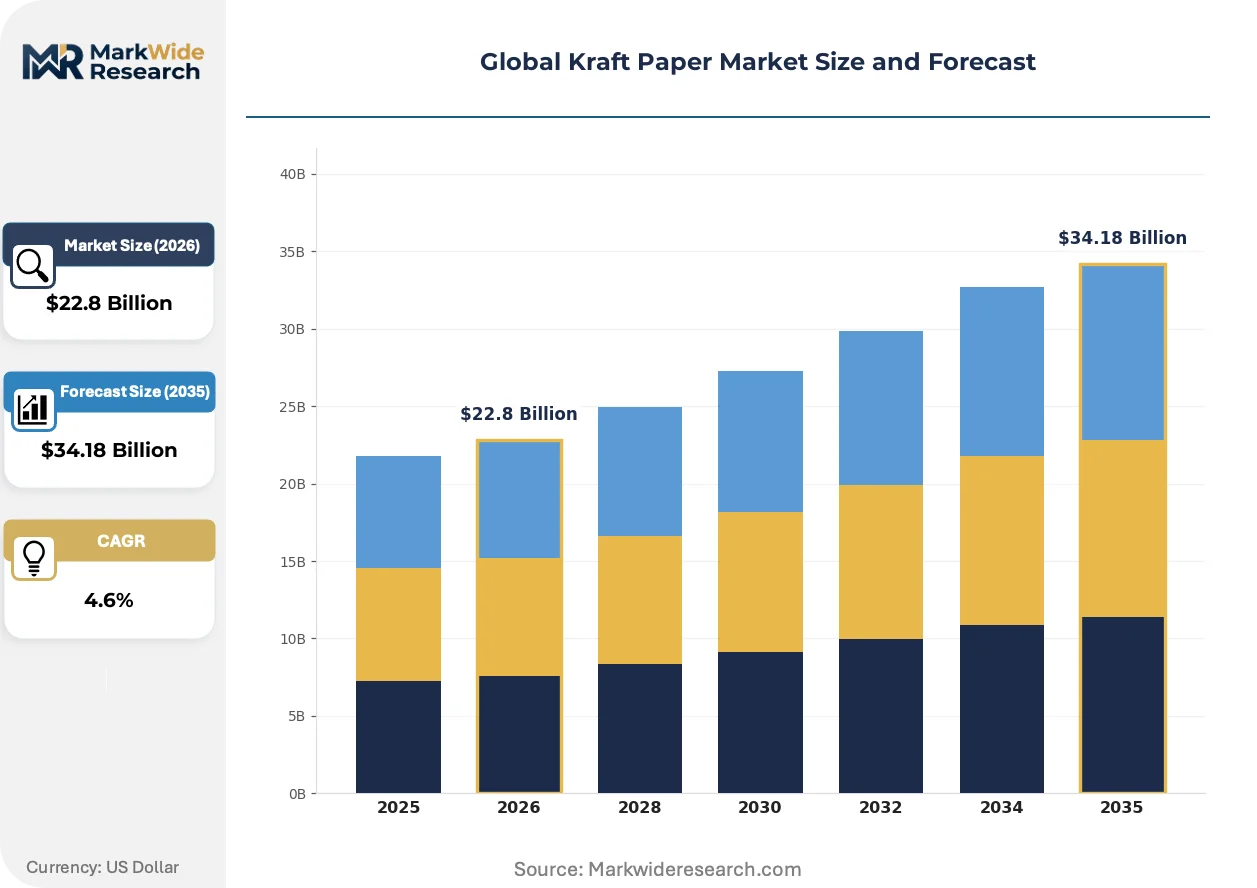
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $34.18 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Brown Kraft Paper, White Kraft Paper, Colored Kraft Paper, Reinforced Kraft Paper, Sulfate Kraft Paper Application: Packaging, Wrapping, Industrial, Consumer Goods, Arts & Crafts, Agriculture End User: Manufacturers, Wholesalers, Distributors, Retailers, Printing Companies Packaging Type: Bags, Rolls, Sheets, Tubes, Envelopes |
| Companies Covered | International Paper Company, Mondi Group, Smurfit Westrock, Stora Enso, Georgia-Pacific LLC, Billerud AB, Sappi Limited, Segezha Group, Canfor Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Kraft Paper Market Shifts & Advancements
Active reformulation of furnish recipes, regulatory harmonization pressures, and fulfillment automation are compressing legacy product lifecycles while opening specification white space for performance-differentiated grades.
Barrier-coated kraft variants incorporating cellulose nanofibril layers are fragmenting the traditional frozen-food packaging category. Quick-commerce operators in Mumbai and Bangalore are piloting these grades for moisture-resistant grocery bags. The technology is fragmenting established supply relationships by enabling non-integrated converters to bypass linerboard mills for direct substrate sourcing.
REACH restrictions on per- and polyfluoroalkyl substances are eliminating legacy grease-resistant chemistries from European food-contact kraft. Mills serving export markets are accelerating migration to fluorine-free barrier formulations. The regulation is compressing product development timelines for Asian suppliers seeking EU market access.
Buyer consolidation among third-party logistics providers is concentrating procurement leverage for void-fill kraft specifications. Mid-sized e-commerce enablers are ceding direct purchasing authority to fulfillment network operators. The shift is most visible in Germany’s Ruhr logistics cluster, where DHL and Amazon co-located facilities now dictate basis weight and roll width standards.
Global Kraft Paper Market Segmentation
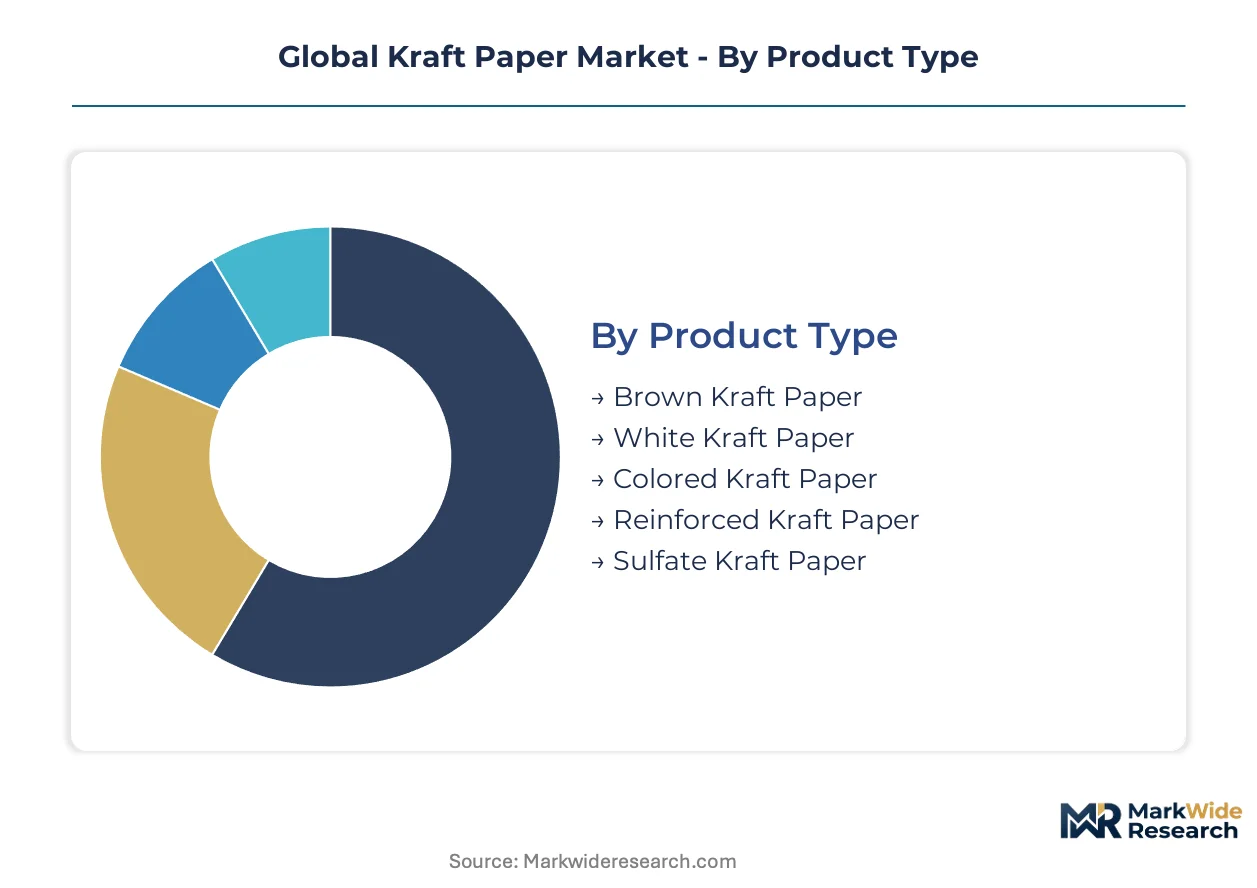
Segmentation reveals how kraft paper specifications diverge across protective packaging, food-contact wraps, and industrial applications. Each dimension—product chemistry, end-use performance, and format geometry—carries distinct margin structures and compliance requirements.
Product Type:
Margin pools concentrate in reinforced and specialty sulfate grades where tear strength justifies premium positioning over commodity brown volumes.
- Brown Kraft Paper:Unbleached sulfate pulp yields high tear resistance and printability for corrugated linerboard and void-fill applications. E-commerce fulfillment centers in Germany and the United States are standardizing basis weights between 80-120 gsm for automated packing lines.
- Reinforced Kraft Paper:Fiberglass or synthetic yarn interlayers boost tensile strength for heavy-duty industrial wrapping and steel coil protection. Demand concentrates in India’s metal processing clusters around Jamshedpur and Pune where export packaging must survive maritime handling.
- White Kraft Paper:Bleached pulp delivers visual clarity for premium retail bags and food-contact wraps where branding overrides cost minimization.
- Colored Kraft Paper:Dyed variants serve gift packaging and craft applications with shorter runs and higher per-ton pricing.
- Sulfate Kraft Paper:Virgin fiber construction meets FDA and EU food-contact specifications for grease-resistant bakery wraps and quick-commerce delivery bags.
The dominant share belongs to Brown Kraft Paper, while Reinforced Kraft Paper is closing the gap fastest.
Application:
Volume flows track the divergence between protective logistics packaging and food-grade presentation layers.
- Packaging:Carrier bags, void-fill dunnage, and corrugated medium consume the majority of tonnage. Quick-commerce operators in Mumbai and Bangalore are specifying 70-90 gsm food-grade kraft for 10-minute grocery delivery bags.
- Industrial:VCI-treated wraps and moisture-barrier laminations protect metal components during export shipment. REACH restrictions on chemical additives are forcing reformulation of European-sourced industrial grades.
- Wrapping:Decorative and protective layers for furniture and fragile goods favor lighter basis weights with print compatibility.
- Consumer Goods:Premium unboxing experiences drive specification of textured kraft with custom embossing.
- Arts & Crafts:Specialty retailers source colored and textured variants in sheet format for hobbyist markets.
- Agriculture:Seed bags and nursery wraps require biodegradable certification for soil-contact disposal.
Packaging commands the volume lead, though Industrial applications are expanding most quickly on export packaging demand.
End User:
Procurement authority is shifting from converters toward integrated fulfillment networks with specification-setting power.
- Manufacturers:Integrated paperboard mills and corrugated converters source roll stock directly for captive consumption. Mondi Group and Smurfit Westrock negotiate long-term furnish contracts tied to OCC price indices.
- Retailers:Quick-commerce platforms and grocery chains are bypassing converters to specify bag dimensions and barrier properties directly.
- Wholesalers:Regional distributors stock standard roll widths for small-to-mid converters without mill-direct purchasing power.
- Distributors:Logistics-focused intermediaries consolidate demand from fragmented packaging buyers.
- Printing Companies:Specialty converters add value through flexographic and digital print for branded retail packaging.
Manufacturers retain the dominant procurement volume, while Retailers are gaining specification authority fastest.
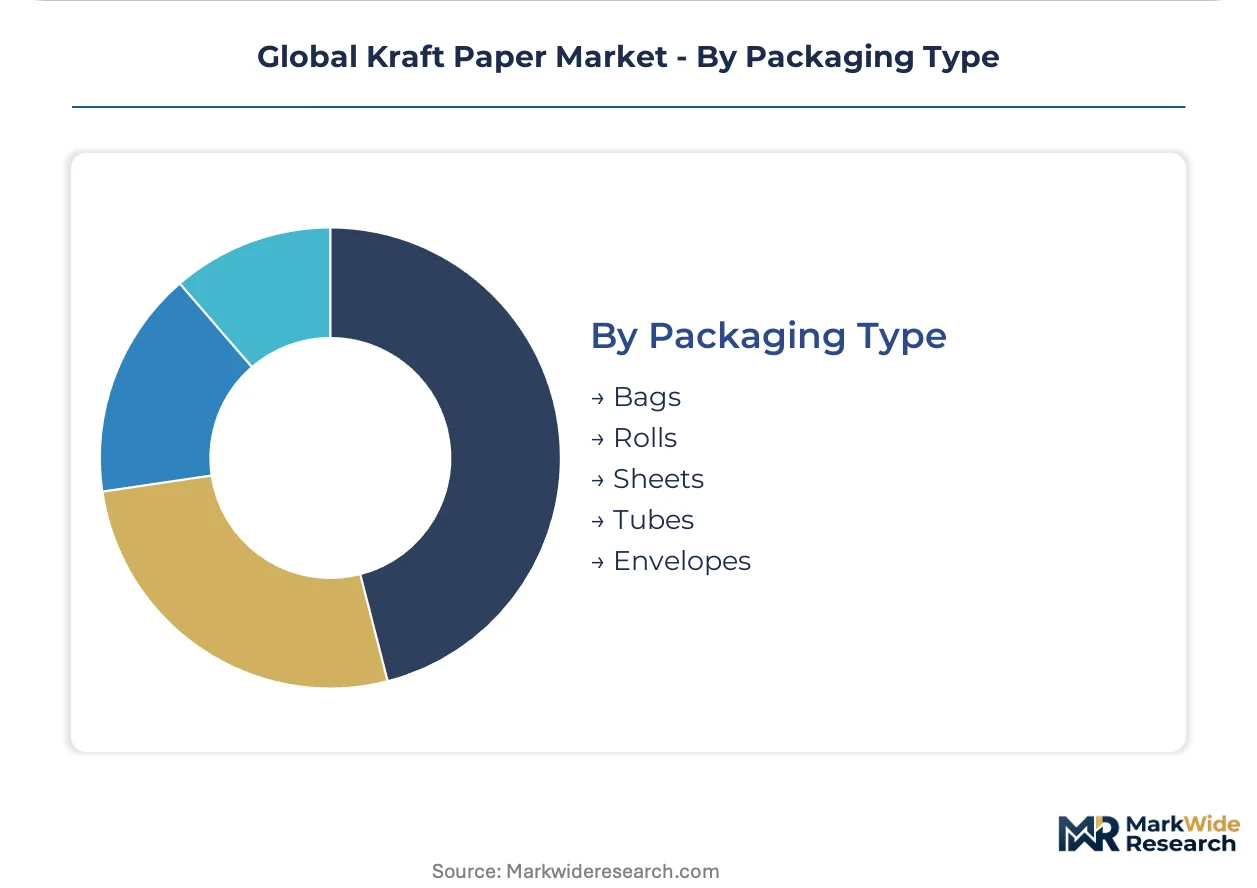
Packaging Type:
Format geometry determines automation compatibility and logistics efficiency across fulfillment networks.
- Rolls:Standard mill output format suits corrugated plants and large converters with slitting capacity. Basis weight and width specifications vary by regional machinery fleets.
- Sheets:Precision-cut dimensions enable robotic packing cells in automated e-commerce fulfillment centers. DHL and Amazon co-located facilities in Germany’s Ruhr cluster now dictate sheet size standards.
- Bags:Pre-formed sacks serve agriculture, chemicals, and food ingredients where filling speed matters.
- Tubes:Cylindrical cores and postal tubes protect rolled documents and textiles.
- Envelopes:Padded and rigid mailers capture premium shipping segments requiring dimensional stability.
Rolls maintain the dominant format share, though Sheets are climbing the fastest on automation penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Swedish mills export unbleached kraft linerboard to German corrugated converters serving e-commerce fulfillment networks. This trade corridor channels Scandinavian sulfate pulp capacity into Central European packaging demand.
United States
E-commerce fulfillment centers in Pennsylvania and Ohio are standardizing 80-120 gsm kraft specifications for automated packing lines. EPA Comprehensive Procurement Guidelines enforce recycled fiber standards for federal contractor sourcing. Integrated mills in the Southeast maintain captive pulp operations to serve Amazon and Walmart distribution networks.
Germany
The Ruhr logistics cluster concentrates procurement authority for void-fill kraft among DHL and Amazon co-located facilities. REACH restrictions on wet-strength additives constrain frozen-food packaging formulations. Corrugated converters in North Rhine-Westphalia negotiate long-term furnish contracts tied to old corrugated container price indices.
India
Quick-commerce operators in Mumbai and Bangalore are scaling 10-minute grocery delivery using 70-90 gsm food-grade kraft bags. BIS certifies kraft paper grades under IS 4664, creating compliance gateways for imported rolls. Metal processing clusters around Jamshedpur and Pune demand reinforced kraft for export steel coil protection.
China
Import quota shifts for recovered fiber generate price volatility that squeezes margin pools for recycled-content kraft grades. GB standards govern packaging material specifications for domestic food-contact applications. Yangtze River Delta converters supply Alibaba and JD.com fulfillment networks with void-fill specifications.
Finland
Recovery boiler upgrades across sulfate pulping operations lower per-unit energy intensity for unbleached kraft linerboard. EU Packaging and Packaging Waste Regulation mandates minimum recycled-content thresholds for European market access. Biomaterials R&D facilities near Helsinki develop cellulose nanofibril barrier coatings for oil-resistant food packaging.
Global Kraft Paper Market Competitive Landscape
Listed leaders compete with private specialists across integrated pulp-to-paper operations and regional conversion networks. The market structure tiers between scale-driven containerboard giants and specialty sulfate producers serving niche industrial applications. Three archetypes dominate: integrated forest products groups with captive pulp supply, corrugated converters with backward integration into linerboard, and specialty paper merchants focused on certified food-grade grades. Capacity expansion and strategic partnerships constitute the primary competitive moves as mills secure recovered fiber supply contracts.
Within the integrated forest products tier, Mondi Group and Stora Enso exemplify European-based operators with sulfate pulping capacity spanning multiple member states. Smurfit Westrock occupies a position representing transatlantic scale in containerboard and kraft linerboard. These three entities anchor the competitive structure by linking pulp production to converter networks across their respective geographies.
| Leading Market Players |
|---|
| International Paper Company |
| Mondi Group |
| Smurfit Westrock |
| Stora Enso |
| Georgia-Pacific LLC |
| Billerud AB |
| Sappi Limited |
| Segezha Group |
| Canfor Corporation |
| Others |
Supply & Pricing Matrix
Recovered fiber substitution for virgin sulfate pulp simultaneously redraws procurement geography and compresses margin pools across integrated mills. Chinese import quota shifts for old corrugated containers generate price volatility that ripples through furnish contracts in Germany and the United States, while Scandinavian recovery boiler upgrades lower energy intensity for unbleached kraft linerboard production.
Pricing Analysis
Barrier-coated kraft variants command premium positioning over commodity brown grades, while reinforced industrial wraps and bleached white kraft occupy mid-tier and economy positions respectively. Price differentiation centers on FDA and EU food-contact certification tiers plus volume scale commitments from Amazon and DHL fulfillment networks. Pricing pressure stems from recovered fiber cost volatility squeezing recycled-content grades. Small-to-mid converters exhibit highest price sensitivity, while integrated fulfillment networks with specification-setting power demonstrate lowest.
Supply Chain Analysis
Port congestion on Asia-Europe trade lanes elevates inbound logistics costs for Indian quick-commerce operators sourcing food-grade kraft from Finnish and Swedish mills. Supply concentrates in Finland, Sweden, and Germany for sulfate pulping capacity, while India and China dominate conversion and end-use consumption. Raw material flows draw from Scandinavian softwood pulp, recovered fiber streams from German retail networks, and cellulose nanofibril additives from Helsinki R&D facilities. Single-source vulnerability runs through Baltic Sea shipping routes for linerboard exports. Distribution feeds from mill-direct contracts to corrugated converters, with precision-cut sheets bypassing traditional roll channels for automated fulfillment lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment. REACH compliance and BIS IS 4664 certification create multi-year barriers that protect incumbent positions from rapid displacement.
For Market Incumbents: Secure long-term recovered fiber supply contracts tied to OCC price indices before Chinese quota shifts tighten availability. Extend backward integration into captive sulfate pulping capacity in Finland and Sweden to isolate margin pools from furnish volatility. Bleached pulp substitution and white-top linerboard alternatives threaten premium print applications.
For New Entrants and Emerging Players: BIS IS 4664 certification fast-tracks access to India's quick-commerce grocery delivery segment where 10-minute delivery models scale fastest. Target food-grade kraft bag specifications for Mumbai and Bangalore fulfillment networks. Partner with regional converters lacking mill-direct purchasing power to establish initial volume footholds.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated forest products groups with captive pulp supply and established converter relationships. Long-term viability over the next decade rests on biomaterials R&D capabilities and renewable packaging certification programs. Monitor cellulose nanofibril barrier coating adoption as inflection indicator for next-generation food packaging margins.
| Strategic Initiative | Industry Significance |
|---|---|
| Recovery Boiler Upgrade | Scandinavian mills lower per-unit energy intensity for unbleached kraft linerboard production. |
| Backward Integration into Sulfate Pulping | Integrated groups isolate margin pools from recovered fiber price volatility in German markets. |
| BIS IS 4664 Certification Investment | Early certification creates compliance gateways for imported rolls into Indian quick-commerce channels. |
| Cellulose Nanofibril R&D Partnership | Helsinki biomaterials facilities develop oil-resistant barrier coatings for frozen-food applications. |
| Long-term Furnish Contract | Converters lock in OCC-indexed supply terms ahead of Chinese import quota fluctuations. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of trade flow databases, EPA Comprehensive Procurement Guidelines, EU Packaging and Packaging Waste Regulation filings, and BIS certification records. Conversations with sulfate mill operations managers, corrugated converter procurement leads, quick-commerce supply chain directors, and logistics network operators informed demand-side validation. Customs data from German and Indian ports, SEC filings from integrated forest products groups, and recovery boiler upgrade announcements from Scandinavian producers supplied supply-side triangulation. Bottom-up volume builds across product grades and end-use applications were cross-checked against top-down macroeconomic indicators.
Segmentation dimensions modeled include product chemistry (brown, reinforced, white, sulfate grades), application category (packaging, industrial, food-contact), format geometry (rolls, sheets, bags), and end-user procurement authority (manufacturers, retailers, wholesalers). Growth trajectories across the projection horizon derive from elasticity modeling against e-commerce fulfillment expansion rates, recycled-content mandate compliance timelines, and quick-commerce grocery delivery scaling patterns. Energy intensity improvements from recovery boiler upgrades and barrier coating technology diffusion curves served as industry-specific forecast inputs.
Decision-makers should treat outputs as directional under assumptions of sustained e-commerce fulfillment growth and stable regulatory enforcement timelines; material deviation would warrant model refresh. Specific risks include Chinese recovered fiber import policy reversals, REACH additive restriction expansions, and automation penetration speed in fulfillment networks. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper Products
Hardwood Pulp Market
Paper Products
Asia-Pacific Thermal Paper Market
Paper Products
Paper Doilies Market
Paper Products
Softwood Pulp Market
Paper Products
Heat Transfer Paper Market
Paper Products
Thermal Paper Market
Paper Products
GCC Stone Paper Market
Paper Products
Decorative Plastic and Paper Laminates Market
Paper Products
Americas Stone Paper Market
Paper Products
Europe Coated Paper Market
Paper Products
Wood Paper and Paperboard Recycling Market
Paper Products
Tissue Paper Market
Paper Products
Decor Paper Market
Paper Products
North America Decor Paper Market
Paper Products
Specialty Paper Market
Paper Products
High-Speed Production Inkjet Printer Paper Market