
 US Essential Oil Market | 2026-2036
US Essential Oil Market Size, Share, and Industry Trends Forecast 2026-2036
US Essential Oil Market Outlook
Spa and wellness chain procurement is consolidating into fewer national accounts with standardized oil specifications. doTERRA International LLC leverages its direct sales network to sustain recurring revenue from wellness practitioners. Young Living Essential Oils anchors its position through vertically integrated farm operations in Utah and Idaho. Givaudan SA competes by supplying flavor-grade oils to multinational food and beverage manufacturers seeking clean-label ingredients.
Essential oils are concentrated hydrophobic liquids containing volatile aroma compounds extracted from plant materials through steam distillation, cold pressing, or solvent extraction, with typical concentrations requiring dilution ratios of 1-5% for topical application. These oils serve as functional inputs across fragrance formulation, therapeutic applications, and natural preservation systems. Lavender and peppermint dominate product type volumes due to established aromatherapy protocols and broad personal care compatibility. Food and beverage application growth outpaces other segments as manufacturers replace synthetic flavorants with plant-derived alternatives. Direct sales and online retail channels capture margin pools through subscription models that bypass traditional wholesale markups.
FDA cosmetic regulations and FTC advertising substantiation requirements govern therapeutic claims, while USDA organic certification shapes premium pricing tiers for domestically sourced botanicals. State-level California Proposition 65 compliance adds testing burdens for products distributed through West Coast retail channels. Stakeholders must monitor evolving EPA pesticide residue limits for imported raw botanicals and assess how state-level clean beauty legislation in New York and California will redefine permissible extraction solvents and disclosure thresholds.
Market Dynamics
Spa and wellness procurement consolidation is compressing supplier margins while FDA substantiation rules reshape therapeutic claim strategies. This structural tension between buyer concentration and regulatory stringency defines current competitive positioning.
Growth Catalysts
- Clean-label food reformulation:Manufacturers replace synthetic flavorants with plant-derived alternatives, expanding essential oil volumes in beverage and packaged food applications.
- USDA organic certification premiums:Domestically sourced botanicals command pricing tiers that incentivize domestic cultivation expansion in California and Pacific Northwest growing regions.
- Steam distillation efficiency gains:Advanced vapor-phase recovery systems reduce energy intensity per kilogram of oil extracted, improving unit economics for mid-scale processors.
Market Restraints
- Imported raw material pesticide residues:EPA tolerance limits for foreign-sourced lavender and peppermint create batch rejection risk at port of entry.
- California Proposition 65 testing burdens:West Coast distribution requires heavy metal and contaminant screening that adds fixed cost per SKU.
- Synthetic fragrance substitution:Fine fragrance houses increasingly deploy biotechnology-derived aroma molecules that replicate terpene profiles at lower input cost.
Strategic Opportunities
- Subscription direct-to-practitioner models:Wellness practitioners bypass wholesale tiers through recurring auto-ship arrangements that lock in volume commitments.
- Texas and Florida wellness corridor expansion:Underpenetrated Sun Belt metro areas present greenfield spa development with localized oil supply contracts.
- IRA bio-based manufacturing incentives:Domestic extraction facility construction qualifies for clean energy tax credits that improve project returns.
Industry Challenges
- Master distiller talent scarcity:Skilled operators capable of optimizing yield across variable botanical feedstock quality command premium compensation in tight labor markets.
- Organic certification timeline compression:USDA transition periods for newly converted farmland delay revenue recognition from premium-grade production.
- Multi-state labeling compliance:Divergent clean beauty disclosure thresholds between California and New York require SKU-specific packaging runs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Essential Oil Market |
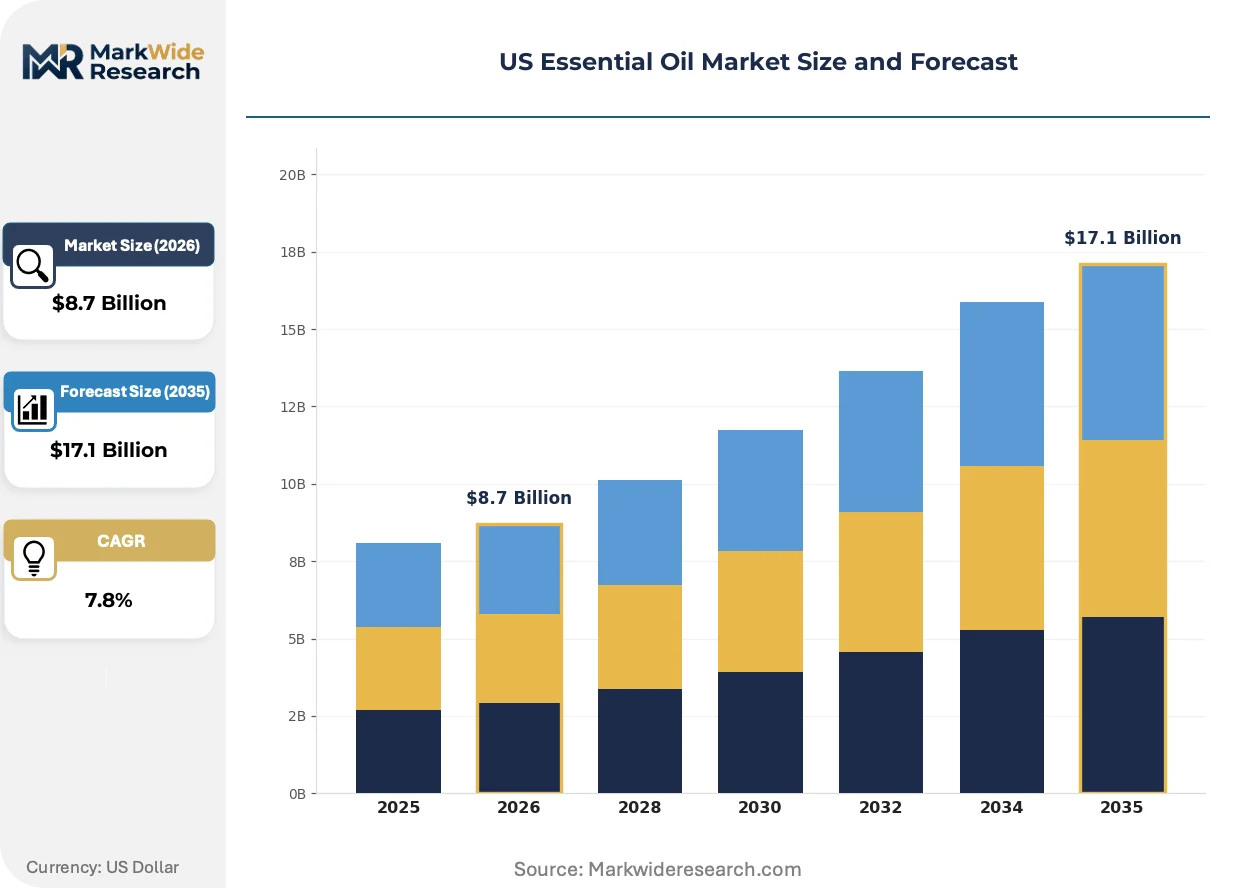
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $17.1 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lavender, Peppermint, Tea Tree, Eucalyptus Application: Aromatherapy, Personal Care, Household Cleaning, Food & Beverage Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Direct Sales End User: Consumers, Manufacturers, Healthcare Providers, Wellness Centers |
| Companies Covered | doTERRA International LLC, Young Living Essential Oils, NOW Foods, Rocky Mountain Oils, Mountain Rose Herbs, Givaudan SA, International Flavors & Fragrances Inc., Sensient Technologies Corporation, Lebermuth Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Essential Oil Market Strategic Shifts
Carbon dioxide supercritical extraction is reshaping quality benchmarks across therapeutic-grade applications. This technology shift intersects with tightening contaminant standards and evolving practitioner procurement habits.
Supercritical CO2 extraction systems deploy pressurized carbon dioxide as a tunable solvent that selectively captures volatile compounds without thermal degradation. Premium aromatherapy brands and clinical wellness practitioners are adopting CO2-extracted oils for topical and inhalation protocols. This precision is electrifying the separation between commodity steam-distilled grades and ultra-pure therapeutic positioning.
California Proposition 65 enforcement actions against undisclosed fragrance allergens are compelling reformulation of personal care products distributed through West Coast retail. The state's Office of Environmental Health Hazard Assessment maintains an expanding list of naturally occurring compounds requiring warning labels. Cosmetic formulators are responding with supply chain audits that trace terpene profiles back to specific harvest lots and extraction batches.
Wellness practitioners are consolidating purchasing through group procurement organizations that negotiate standardized specifications and volume pricing. These buying cooperatives displace individual account relationships that historically sustained fragmented distributor networks. The concentration is most visible in metropolitan Los Angeles and San Francisco, where multi-location spa chains centralize oil sourcing decisions at corporate headquarters.
US Essential Oil Market Segmentation
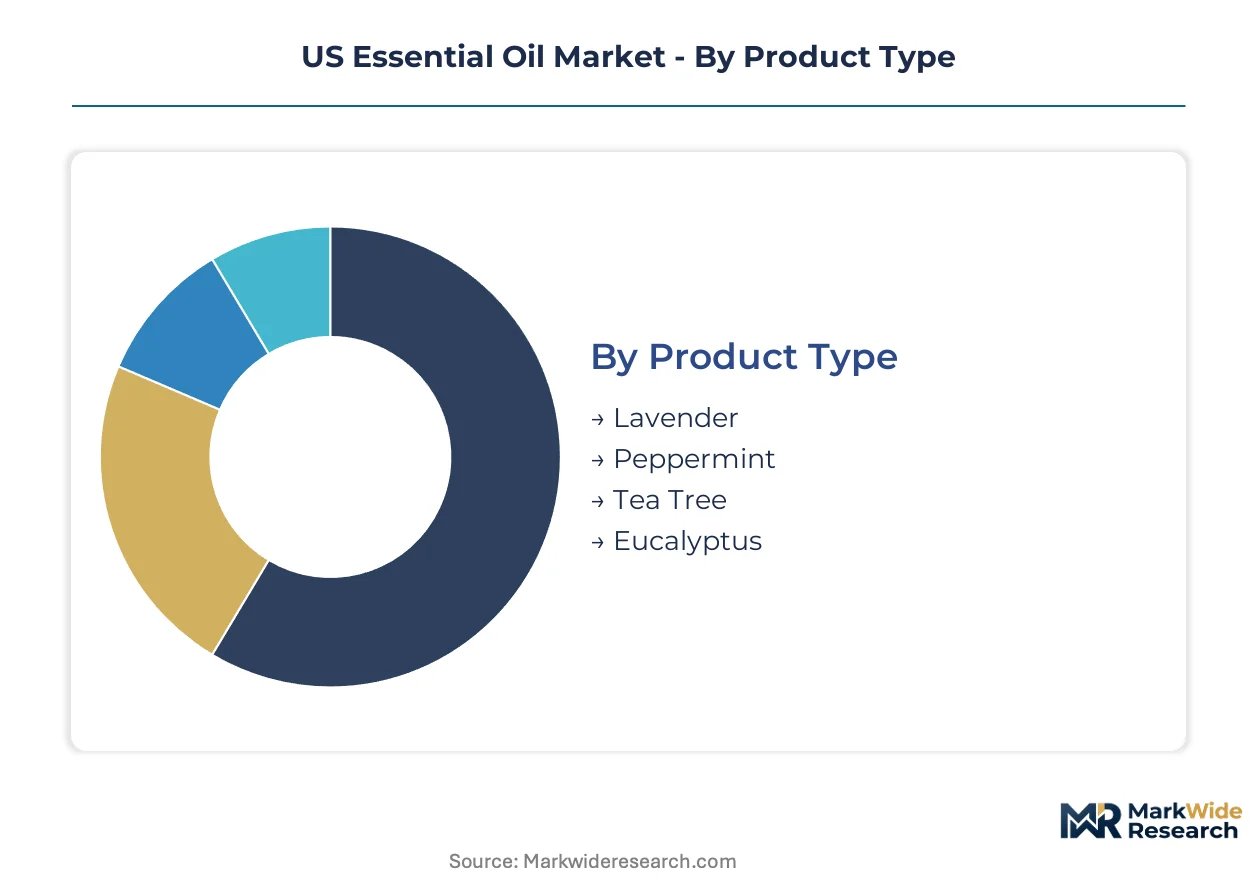
Essential oil procurement patterns diverge sharply across buyer types and use cases. Understanding these fault lines reveals where margin pools concentrate and which channels command pricing power.
Product Type:
Buyers in this category distinguish oils by terpene profile stability and harvest lot traceability.
- Lavender:High linalool and linalyl acetate content defines therapeutic-grade specifications. California wellness centers in Los Angeles and San Francisco metro areas drive volume through corporate procurement contracts that mandate organic certification and batch-level GC-MS testing documentation.
- Peppermint:Menthol concentration above 40% separates pharmaceutical-grade from fragrance-grade supply. Idaho and Washington state cultivation clusters serve domestic peppermint demand, with mint oil processors supplying flavor houses and oral care manufacturers seeking clean-label menthol sources.
- Tea Tree:Terpinen-4-ol levels determine antiseptic efficacy ratings for topical applications. Australian import dependence creates supply continuity risk managed through long-term offtake agreements.
- Eucalyptus:Cineole content variation splits pharmaceutical inhalation uses from industrial fragrance applications. Steam distillation yield volatility requires processors to maintain multi-origin sourcing portfolios.
Volume sits with lavender and peppermint; growth tilts toward tea tree as clinical wellness protocols expand.
Application:
End-use specifications range from cosmetic-grade purity to food-code compliance, reshaping supplier qualification requirements.
- Aromatherapy:Inhalation and topical protocols demand contaminant-free oils with documented terpene profiles. Wellness practitioners in California concentration zones specify CO2-extracted grades for clinical settings.
- Personal Care:Formulators face California Proposition 65 disclosure mandates for fragrance allergens. Clean beauty brands audit supply chains to trace terpenes to specific harvest lots.
- Household Cleaning:Antimicrobial claims trigger EPA registration requirements for surface disinfectant applications. Private label manufacturers favor lower-cost steam-distilled grades with standardized active compound ranges.
- Food & Beverage:Flavor-grade oils require FDA GRAS status and FEMA approval for specific use concentrations. Beverage manufacturers replacing synthetic flavorants drive fastest expansion in this application tier.
Personal care commands premium pricing; food and beverage applications expand most quickly as clean-label reformulation accelerates.
Distribution Channel:
Channel selection determines margin capture and customer relationship depth.
- Online Retail:Subscription auto-ship models lock in recurring revenue from individual practitioners and small spas. Direct-to-consumer brands bypass wholesale markups through proprietary e-commerce platforms.
- Specialty Stores:Curated assortments and staff expertise justify premium positioning. Independent apothecaries and natural product retailers concentrate in urban coastal markets.
- Supermarkets:Mass-market penetration requires price-competitive positioning and scaled packaging formats. Grocery channel growth lags as consumers shift toward specialized wellness retailers.
- Direct Sales:Multi-level marketing networks sustain recurring revenue through wellness practitioner downlines. Utah-based operations anchor this channel with vertically integrated supply chains.
Direct sales retains the highest margin structure; online retail gains share fastest as practitioner procurement digitizes.
End User:
User sophistication and volume scale create distinct service requirements.
- Consumers:Individual purchasers prioritize convenience and educational content over bulk pricing. Online reviews and influencer recommendations drive brand selection.
- Manufacturers:Food, beverage, and cosmetic formulators require certificate of analysis documentation and lot traceability. Procurement teams negotiate annual contracts with volume commitments.
- Healthcare Providers:Integrative medicine clinics and hospital wellness programs specify pharmaceutical-grade oils with USP monograph compliance. Clinical protocols demand consistent terpene profiles.
- Wellness Centers:Spa chains and independent studios consolidate purchasing through group procurement organizations. Corporate headquarters in Los Angeles and San Francisco centralize sourcing decisions for multi-location operations.
Manufacturers move the largest absolute volumes; wellness centers represent the steepest expansion trajectory as spa chain development accelerates in Texas and Florida corridors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for essential oils concentrates in California, where organic personal care formulators cluster around Los Angeles and San Francisco. Wellness centers and spa chains in these metro areas drive procurement volumes through centralized corporate contracts. FDA and FTC oversight of cosmetic and therapeutic claims continues to tighten product labeling requirements nationwide.
California
Los Angeles and San Francisco anchor the nation's largest concentration of organic personal care formulators. California Proposition 65 enforcement actions compel heavy metal and contaminant screening for products distributed through West Coast retail channels. Wellness practitioners in these metro areas specify CO2-extracted grades and mandate batch-level GC-MS testing documentation.
Utah and Idaho
Vertically integrated farm operations in these Mountain West states serve domestic peppermint and lavender cultivation demand. USDA organic certification programs incentivize premium-grade production from newly converted farmland. Idaho and Washington state mint oil processors supply flavor houses and oral care manufacturers seeking clean-label menthol sources.
Texas
Houston and Dallas-Fort Worth wellness corridors present underpenetrated greenfield spa development opportunities. Texas-based practitioners increasingly consolidate purchasing through group procurement organizations that negotiate standardized specifications. Localized oil supply contracts emerge as multi-location spa chains centralize sourcing decisions at corporate headquarters.
Florida
Miami and Tampa Bay metro areas drive Sun Belt expansion for wellness center development. Florida's clinical wellness protocols expand demand for tea tree and eucalyptus oils with documented terpene profiles. Integrative medicine clinics in these coastal markets specify pharmaceutical-grade oils with consistent active compound ranges.
Pacific Northwest
Oregon and Washington cultivation clusters support domestic botanical feedstock for mid-scale processors. Advanced vapor-phase recovery systems in this region reduce energy intensity per kilogram of oil extracted. Steam distillation facilities here supply fragrance-grade outputs to multinational food and beverage manufacturers replacing synthetic flavorants.
US Essential Oil Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue direct-to-practitioner subscription models and specialized therapeutic positioning. The vendor base spans multinational flavor houses, vertically integrated farm operations, and multi-level marketing networks with wellness practitioner downlines. Three archetypes dominate: agricultural integrators controlling cultivation through distillation, direct sales networks sustaining recurring revenue, and flavor-grade suppliers serving clean-label reformulation. Competitive moves concentrate on backward integration into captive botanical supply and geographic expansion into underpenetrated Sun Belt corridors.
Among Utah-based direct sales networks, doTERRA International LLC and Young Living Essential Oils exemplify the practitioner-focused archetype with vertically integrated supply chains. Givaudan SA represents the multinational flavor-grade tier supplying beverage and packaged food manufacturers. These three anchors illustrate how procurement consolidation and regulatory stringency reward scale in standardized specifications while creating openings for specialized therapeutic positioning.
| Leading Market Players |
|---|
| doTERRA International LLC |
| Young Living Essential Oils |
| NOW Foods |
| Rocky Mountain Oils |
| Mountain Rose Herbs |
| Givaudan SA |
| International Flavors & Fragrances Inc. |
| Sensient Technologies Corporation |
| Lebermuth Inc. |
| Others |
Value Chain & Pricing Dynamics
Master distiller scarcity in the Pacific Northwest and Mountain West widens labor-cost differentials that separate premium therapeutic grades from commodity fragrance tiers. This workforce concentration forces processors to bid up compensation for skilled vapor-phase recovery operators, compressing margins at the standard tier while organic-certified premiums absorb the cost pass-through.
Pricing Analysis
Volume concentrates in mass-market fragrance and household cleaning applications where price competition is most intense, while margin pools accumulate in clinical-grade aromatherapy and pharmaceutical specifications. Three-tier pricing structure across premium, standard, and economy levels separates CO2-extracted therapeutic batches with full GC-MS documentation from steam-distilled fragrance grades and bulk industrial inputs. Price differentiation rests on USDA organic certification status and batch-level contaminant testing depth. Cost compression in the standard tier is intensifying because spa chain procurement consolidation extracts volume discounts from mid-scale processors. Household cleaning manufacturers exhibit the highest price sensitivity, while integrative medicine clinics and hospital wellness programs demonstrate the lowest.
Supply Chain Analysis
Warehouse-distribution layers concentrate around Los Angeles and San Francisco regional distribution centers that serve West Coast personal care formulators with Prop 65-compliant inventory staging. Geographic supply concentrates in Australia for tea tree, India for jasmine and sandalwood, and Bulgaria for lavender. Raw material dependencies include botanical feedstock harvest timing, organic certification transition periods for domestic farmland, and EPA-registered pesticide residue testing for imported lots. Single-source vulnerability for Australian tea tree creates supply continuity risk managed through long-term offtake agreements. Distribution runs through direct sales networks with practitioner downlines, subscription auto-ship platforms, and group procurement organizations serving multi-location spa chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where captive botanical supply and in-house distillation capacity determine margin defense against synthetic fragrance substitution and buyer consolidation.
For Market Incumbents: Lock in practitioner relationships through subscription auto-ship platforms that preempt group procurement organization displacement. Deepen backward integration into Idaho and Washington peppermint cultivation to secure clean-label menthol supply for oral care and beverage manufacturers facing FDA GRAS documentation requirements. Prioritize CO2 extraction capacity expansion to maintain therapeutic-grade positioning against steam-distilled commodity competition. For New Entrants and Emerging Players: Direct-to-practitioner e-commerce routes offer the lowest barrier to customer acquisition in an underpenetrated Texas and Florida wellness corridor. Target Houston and Dallas-Fort Worth metro areas with localized supply contracts for multi-location spa development. Pursue white-space positioning in clinical-grade tea tree and eucalyptus for Florida integrative medicine clinics requiring USP monograph compliance. For Investors and Strategic Acquirers: Re-rating potential sits with mid-scale processors possessing USDA organic certification and CO2 extraction capability given IRA clean energy tax credit eligibility for domestic facility construction. Acquisition targets should demonstrate established practitioner relationships and harvest lot traceability systems. Watch for FDA enforcement actions on therapeutic claims as an inflection indicator that would accelerate consolidation toward substantiation-capable players.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cultivation | Captive Idaho and Washington peppermint supply secures clean-label menthol sourcing for oral care manufacturers. |
| CO2 Extraction Capacity Expansion | Ultra-pure therapeutic positioning commands premium pricing from California wellness practitioners specifying clinical protocols. |
| Subscription Platform Development | Recurring auto-ship arrangements lock in volume commitments from individual practitioners bypassing wholesale tiers. |
| IRA Tax Credit Monetization | Domestic extraction facility construction improves project returns through clean energy incentive capture. |
| Group Procurement Organization Partnership | Standardized specifications and volume pricing secure placement with Los Angeles and San Francisco spa chain headquarters. |
Study Parameters
Multi-period observation of spa chain procurement consolidation, FDA substantiation enforcement patterns, and organic certification expansion anchored the trend analysis, supplemented by interviews with master distillers, wellness center procurement directors, personal care formulators, and flavor house technical buyers. Secondary validation drew from USDA organic program data, EPA pesticide tolerance databases, California OEHHA Prop 65 enforcement records, and FEMA GRAS substance listings. Bottom-up volume estimates from cultivation acreage and distillation capacity triangulated against top-down expenditure flows from personal care and food manufacturer procurement disclosures.
Segment-weighting across product type, application, distribution channel, and end user dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from trend extrapolation adjusted for regulatory inflection points and buyer concentration trajectories. Modeled inputs included steam distillation yield efficiency curves, CO2 extraction adoption rates, and state-level clean beauty legislation implementation timelines.
The model holds under continued FDA and FTC enforcement of therapeutic claim substantiation; deviation in EPA pesticide tolerance revisions or California Prop 65 disclosure expansion would shift supply cost structures and pricing tier spreads. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Carvone Market
Flavorings and Food Additives
Citrus Flavonoid Complexes from Mediterranean Peels Market
Flavorings and Food Additives
Flavanones Market
Flavorings and Food Additives
Lecithin Oleoresin Market
Flavorings and Food Additives
Basil Oil Market
Flavorings and Food Additives
Lemon Oil Market
Flavorings and Food Additives
South America Food Flavor Market
Flavorings and Food Additives
Natural Flavor Extract Market
Flavorings and Food Additives
Sour Flavor Ingredient Market
Flavorings and Food Additives
Natural Flavors and Fragrances Market
Flavorings and Food Additives
Global Anthocyanin Market
Flavorings and Food Additives
Tangerine Peel Extract Market
Flavorings and Food Additives
Africa Food Colorants Market
Flavorings and Food Additives
Annatto Extract Market
Flavorings and Food Additives
North America Flavors and Fragrances Market
Flavorings and Food Additives
FTNF Flavors Market