
 Argentina Fruits & Vegetables Market | 2026-2036
Argentina Fruits & Vegetables Market Size, Share, and Industry Trends Forecast 2026-2036
Argentina Fruits & Vegetables Market Insights
Food manufacturing is broadening its share of vegetable offtake as Argentine processors expand frozen and pre-cut lines for institutional buyers. San Miguel S.A. leverages its citrus estates in Tucumán to supply export-grade lemons to European distributors. Grupo Los Grobo anchors grain and oilseed logistics networks that now extend into fruit consolidation for Mercosur trade corridors. Citrusvil S.A. dominates Valencia orange processing for juice concentrate bound for Brazilian and Chinese buyers.
Argentina Fruits & Vegetables encompasses fresh and minimally processed plant products cultivated across temperate and subtropical agro-climatic zones, with harvest cycles governed by varietal dormancy requirements and irrigation-dependent yield optimization. The category serves domestic consumption, foodservice procurement, export trade, and industrial processing into juices, preserves, and frozen preparations. Fresh fruits occupy the largest revenue pool due to perishable premiums and export-grade citrus pricing, while processed vegetables capture expanding margin pools as food manufacturers seek shelf-stable inputs with standardized brix and texture profiles. Organic-grade certification under Argentine organic standards commands price premiums in European retail channels, though conventional production still carries volume leadership in domestic supermarkets and wholesale mercados.
SENASA enforces phytosanitary protocols and export certification that determine market access for Argentine stone fruits and berries into the United States and European Union. BIRF and INTA technical standards govern irrigation efficiency and varietal registration, shaping grower investment in drip-system conversion and clonal selection. Provincial agricultural departments in Mendoza and Río Negro administer cold-chain compliance for export-quality table grapes and pears. Stakeholders must monitor SENASA-EU equivalence agreement negotiations and water-right allocations under federal basin management reforms to secure long-term export eligibility and production capacity.
Market Dynamics
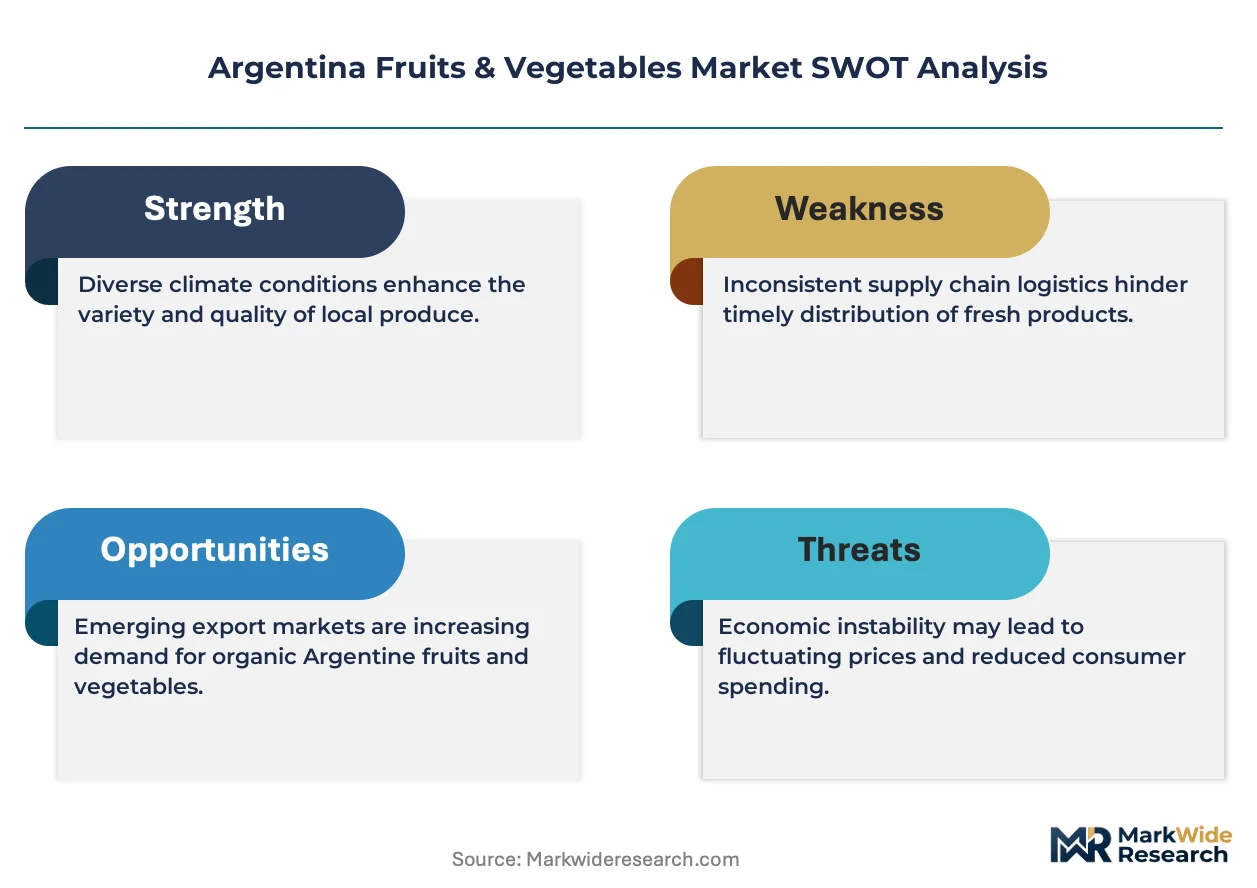
Argentina's fruits and vegetables sector is restructuring around cold-chain reliability and SENASA phytosanitary compliance as export-grade citrus and stone fruits command premium positioning in European and Asian markets. Water-right allocations under federal basin reforms are forcing growers toward drip-irrigation conversion and varietal clonal selection.
Growth Catalysts
- EU equivalence negotiations:SENASA-EU phytosanitary equivalence agreements are expanding market access for Argentine lemons and pears into Northern European retail channels.
- Foodservice procurement:Buenos Aires institutional buyers are expanding frozen and pre-cut vegetable offtake for ready-meal production lines.
- Mendoza cold-chain infrastructure:Provincial agricultural departments are certifying export-quality table grape consolidation facilities for Mercosur trade corridors.
Market Restraints
- Irrigation water scarcity:Federal basin management reforms in Río Negro are restricting surface water allocations for pear orchards.
- Input cost volatility:Argentine peso depreciation is amplifying fertilizer and agrochemical import costs for Tucumán citrus growers.
- Substitution pressure:Brazilian and Chilean citrus exporters are displacing Argentine Valencia orange concentrate in Chinese juice processing facilities.
Strategic Opportunities
- Organic certification premiums:Argentine organic standards compliance is unlocking price multiples in German and Dutch supermarket chains.
- Berry export expansion:INTA technical standards for blueberry and raspberry varietal registration are enabling new planting in Buenos Aires province.
- Direct-to-retail channels:E-commerce platforms are consolidating smallholder produce for urban delivery in Córdoba and Rosario metropolitan zones.
Industry Challenges
- Clonal selection expertise:Mendoza and Río Negro growers face shortages of certified nursery stock for drought-resistant rootstock varieties.
- Phytosanitary compliance timelines:SENASA export certification protocols for stone fruits bound for the United States require extended pre-harvest monitoring periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Argentina Fruits & Vegetables Market |
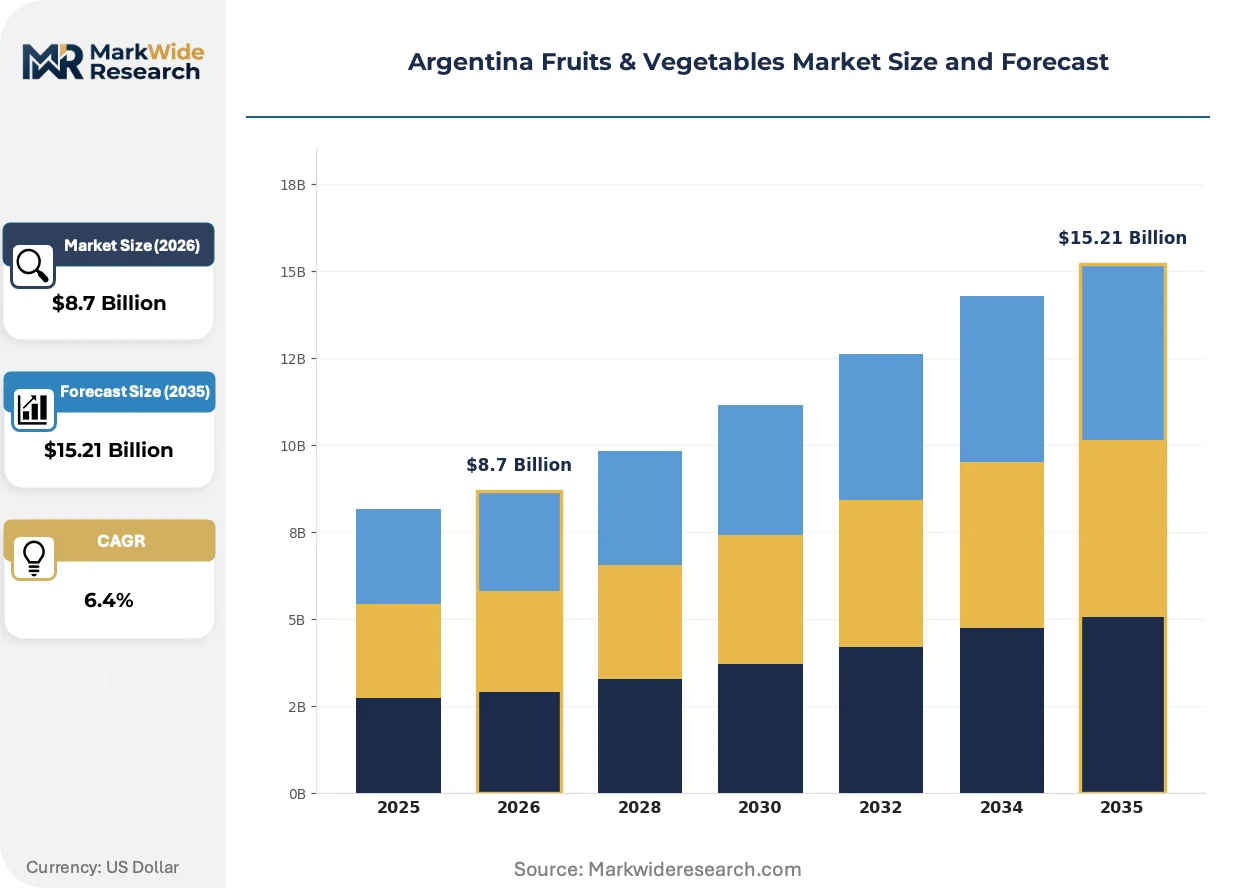
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fresh Fruits, Fresh Vegetables, Processed Fruits, Processed Vegetables Distribution Channel: Supermarkets, Local Markets, Online Retail, Wholesale Quality Grade: Organic, Conventional, Specialty, Export Quality End User: Households, Restaurants, Exporters, Food Manufacturers |
| Companies Covered | Grupo Los Grobo, San Miguel S.A., Patagonian Fruits S.A., Expofrut S.A., Tres Ases S.A., Kleppe S.A., Citrusvil S.A., Frutícola Ledesma S.A.A.I., Biomac SRL, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Argentina Fruits & Vegetables Market Trends and Innovations
Precision agriculture and post-harvest biotechnology are compressing spoilage windows and standardizing export-grade quality metrics across Argentina's fruit and vegetable value chain.
Drip-irrigation telemetry systems are integrating soil-moisture sensors with cloud-based analytics platforms. Mendoza table grape growers are adopting these systems at accelerating rates. This technology is integrating irrigation scheduling with real-time weather data to reduce water application rates while maintaining brix levels for export certification.
SENASA is tightening residue monitoring protocols for export-bound citrus under evolving EU MRL standards. Argentine lemon processors are restructuring pre-export washing and waxing lines to meet these thresholds. Tucumán packinghouses are most affected, with several facilities completing equipment upgrades ahead of the 2026 harvest cycle.
Consolidated procurement through wholesale mercados is fragmenting as supermarket chains establish direct contracting relationships with certified grower cooperatives. This disintermediation is replacing spot-market purchasing with multi-season supply agreements. Buenos Aires province exhibits the most visible shift, where Carrefour and Coto are bypassing traditional wholesale layers for organic-grade leafy greens.
Argentina Fruits & Vegetables Market Segmentation
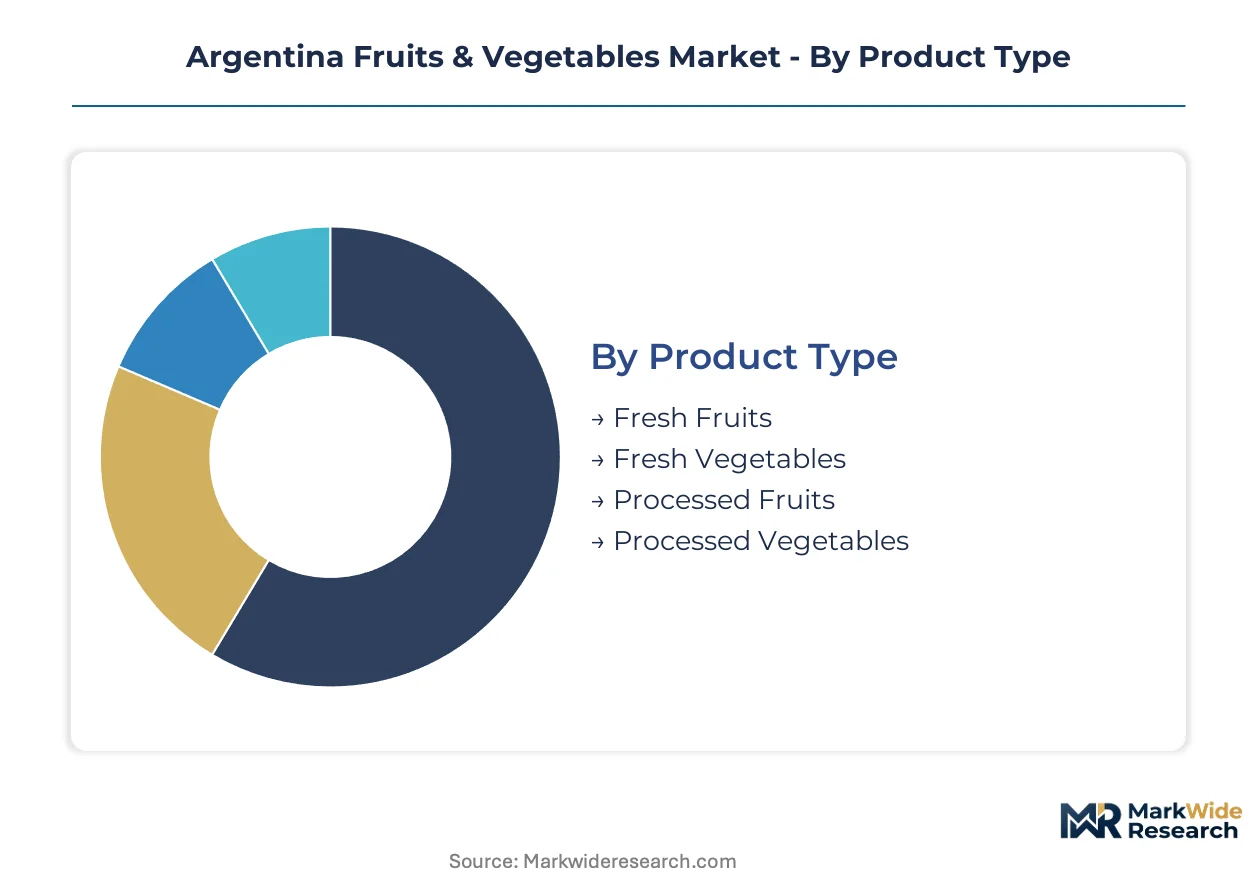
Segmentation in Argentina's fruits and vegetables sector reveals how capital intensity and regulatory compliance reshape competitive boundaries across product types, channels, and quality tiers. Cold-chain infrastructure investments and SENASA certification requirements create divergent margin structures that favor scaled operators in certain segments over fragmented smallholders in others.
Product Type:
Capital intensity varies sharply across this category, with processed lines demanding multi-million dollar pasteurization and aseptic filling equipment while fresh operations require refrigerated logistics networks.
- Fresh Fruits:Citrus, stone fruits, and berries harvested at physiological maturity for immediate consumption or short-term cold storage. Buenos Aires province and Mendoza concentrate export-grade lemon and table grape consolidation, where SENASA phytosanitary protocols govern EU market access.
- Fresh Vegetables:Leafy greens, tomatoes, and peppers distributed through rapid-turnover channels with minimal post-harvest handling. Demand clusters in Greater Buenos Aires foodservice procurement, driven by institutional buyers seeking daily delivery cadences for ready-meal production.
- Processed Fruits:Juice concentrates, purees, and dried preparations requiring enzymatic treatment and thermal processing. Tucumán citrus processors dominate Valencia orange concentrate output for Brazilian and Chinese buyers.
- Processed Vegetables:Frozen cuts, canned preparations, and IQF lines serving industrial offtake. Frozen and pre-cut vegetable volumes are climbing fastest as Argentine processors expand capacity for institutional supply contracts.
Most installed capacity flows through Fresh Fruits. Expansion is steepest in Processed Vegetables.
Distribution Channel:
Channel selection determines working capital cycles and receivables risk, with direct retail contracting shortening payment terms versus wholesale spot markets.
- Supermarkets:Carrefour, Coto, and Disco chains operating centralized distribution centers with temperature-controlled receiving. Direct contracting with certified grower cooperatives is displacing traditional wholesale layers in Buenos Aires province organic-grade procurement.
- Local Markets:Traditional mercados and ferias serving price-sensitive household segments with minimal cold-chain intermediation. Rosario and Córdoba metropolitan zones sustain high throughput via smallholder consolidation.
- Online Retail:E-commerce platforms aggregating smallholder produce for urban delivery with last-mile refrigeration. Córdoba and Rosario zones exhibit the most visible platform penetration.
- Wholesale:Centralized fruit terminals and vegetable auction halls linking production basins to export packers and domestic redistributors. Mendoza cold-chain infrastructure supports premium-grade consolidation for Mercosur trade corridors.
Volume leadership sits with Wholesale. Online Retail is gaining share fastest.
Quality Grade:
Grade stratification creates price multiples that reward certification investments, with organic and export tiers commanding premiums that offset compliance costs.
- Organic:Certified under Argentine organic standards with third-party audit trails for EU and US market eligibility. German and Dutch supermarket chains pay price multiples for compliant lemon and pear shipments.
- Conventional:Standard pesticide protocols serving domestic supermarkets and food manufacturers with cost-optimized production. Volume leadership persists in domestic mercados despite margin compression.
- Specialty:Heritage varietals, regional appellations, and limited-batch productions targeting gourmet retail. Mendoza and Río Negro growers cultivate niche grape and pear lines for premium positioning.
- Export Quality:SENASA-certified grades meeting EU MRL standards and US pre-harvest monitoring requirements. Tucumán packinghouses completed equipment upgrades to satisfy tightening residue protocols.
Conventional grade moves the largest tonnage. Organic certification is climbing the fastest.
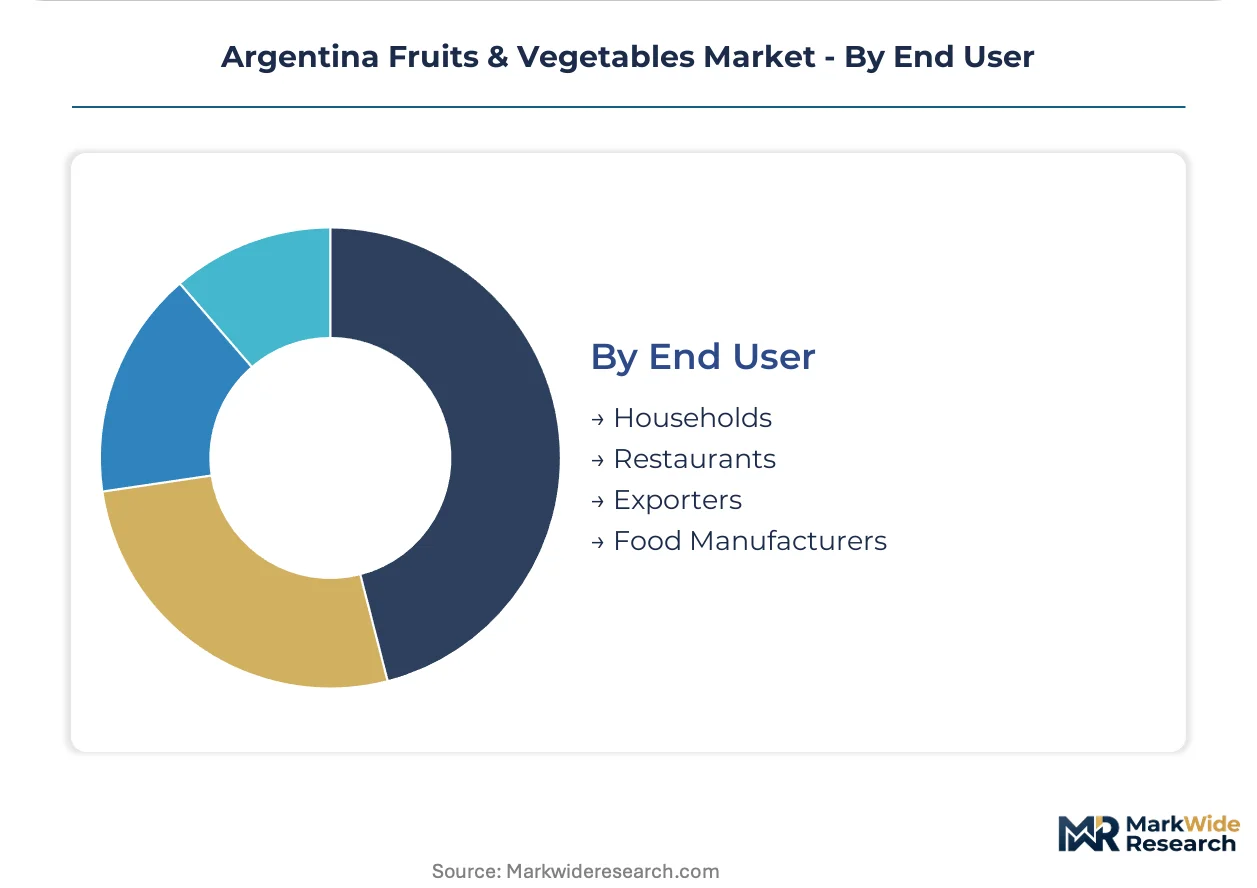
End User:
End-user concentration shapes procurement scale and specification rigor, with exporters and food manufacturers imposing stricter quality protocols than household segments.
- Households:Individual consumers purchasing through retail and traditional market channels with price elasticity varying by income tier. Fresh fruit dominates household basket composition.
- Restaurants:Foodservice operators in Buenos Aires demanding pre-cut vegetables and consistent sizing for kitchen efficiency. Frozen vegetable offtake is broadening as processors expand ready-meal ingredient lines.
- Exporters:Consolidators and trading houses shipping SENASA-certified produce to EU, US, and Chinese destinations. Phytosanitary equivalence agreements are expanding lemon and pear access to Northern European retail.
- Food Manufacturers:Industrial processors sourcing standardized brix and texture profiles for juice, preserve, and frozen product lines. Procurement is shifting toward multi-season supply agreements with certified cooperatives.
Households absorb the greatest volume. Food Manufacturers are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buenos Aires province anchors Argentina's fruit and vegetable trade through its concentration of cold-chain infrastructure and export-grade consolidation facilities serving Mercosur corridors.
Buenos Aires Province
Institutional foodservice buyers in Greater Buenos Aires drive frozen and pre-cut vegetable procurement for ready-meal production lines. SENASA phytosanitary protocols govern export certification for stone fruits bound for United States markets. La Plata and Mar del Plata host the densest packinghouse clusters, where direct-to-retail contracting is displacing traditional wholesale layers.
Mendoza
Table grape and pear exporters command premium positioning in Northern European retail channels through EU equivalence negotiations. Provincial agricultural departments administer cold-chain compliance certifications under federal basin management reforms. Luján de Cuyo concentrates drip-irrigation telemetry adoption, integrating soil-moisture sensors with cloud-based analytics platforms.
Tucumán
Citrus processors supply Valencia orange concentrate to Brazilian and Chinese juice facilities amid tightening residue monitoring protocols. SENASA export certification requirements are accelerating pre-export washing and waxing line upgrades. San Miguel de Tucumán packinghouses completed equipment retrofits ahead of the 2026 harvest cycle.
Río Negro
Pear orchard operators face surface water allocation restrictions under federal basin management reforms. INTA technical standards for clonal selection are shaping grower investment in drought-resistant rootstock varieties. General Roca and Cipolletti sustain heritage varietal cultivation for specialty-grade export positioning.
Córdoba and Rosario Metropolitan Zones
E-commerce platforms aggregate smallholder produce for urban delivery with last-mile refrigeration. Provincial agricultural extension services support organic certification compliance for German and Dutch supermarket chains. Córdoba city exhibits the most visible platform penetration, bypassing traditional mercado intermediation.
Argentina Fruits & Vegetables Market Competitive Landscape
Capacity expansion dominates the current landscape as operators retrofit packinghouses and consolidate cold-chain assets to meet SENASA-EU equivalence requirements. The vendor base spans integrated agro-industrial conglomerates, citrus estate specialists, and regional fruit consolidators with varying degrees of backward integration into cultivation. Three archetypes prevail: scale-driven exporters with captive logistics networks, technology-forward operators deploying precision agriculture systems, and cooperative-based consolidators serving direct-to-retail channels. Geographic expansion into Mercosur trade corridors and portfolio diversification into processed vegetable lines represent the dominant competitive moves.
Among Argentine S.A.-structured operators, San Miguel S.A., Citrusvil S.A., and Grupo Los Grobo exemplify distinct strategic positions within the value chain. San Miguel S.A. represents the citrus estate specialist archetype, anchoring premium lemon supply relationships through Tucumán-based cultivation assets. Citrusvil S.A. occupies a position within the scale-driven processing tier, concentrating Valencia orange concentrate output for industrial offtake. Grupo Los Grobo sits within the diversified agro-industrial category, extending grain and oilseed logistics networks into fruit consolidation for cross-border trade corridors.
| Leading Market Players |
|---|
| Grupo Los Grobo |
| San Miguel S.A. |
| Patagonian Fruits S.A. |
| Expofrut S.A. |
| Tres Ases S.A. |
| Kleppe S.A. |
| Citrusvil S.A. |
| Frutícola Ledesma S.A.A.I. |
| Biomac SRL |
| Others |
Pricing and Supply Chain Analysis
Argentine peso depreciation against fertilizer import benchmarks cascades through citrus and vegetable supply chains, compressing margins at farmgate tiers while amplifying price spreads between SENASA-certified export grades and conventional domestic lots. Input cost pass-through intensity varies by buyer archetype, with frozen vegetable processors absorbing sharper shocks than fresh fruit exporters commanding dollar-denominated contracts.
Pricing Analysis
Input-cost pass-through operates asymmetrically across Argentine fruit and vegetable tiers, with agrochemical and fuel surcharges flowing fastest into processed vegetable contracts. Three-tier pricing structure across premium, standard, and economy levels separates SENASA-certified organic lemon shipments from conventional table grapes and ungraded mercado produce. Pricing pressure stems from peso volatility amplifying imported input costs for Tucumán citrus growers. Smallholder consolidators serving Rosario metropolitan markets exhibit highest price sensitivity, while EU-bound pear exporters demonstrate lowest elasticity due to fixed-term offtake agreements.
Supply Chain Analysis
Regional distribution centers in Buenos Aires province and Mendoza anchor hub-and-spoke patterns radiating toward Mercosur export corridors and domestic supermarket chains. Geographic supply concentration centers on Argentina's Tucumán citrus belt, Mendoza table grape valleys, and Río Negro pear orchards. Raw material dependencies rest on imported fertilizers, agrochemicals, and refrigerated container capacity. Single-source vulnerability runs through SENASA certification bottlenecks for US-bound stone fruit. Distribution runs through wholesale mercados fragmenting as Carrefour and Coto establish direct grower contracting.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Argentina's fruits and vegetables sector functions as a stable compounder anchored by irreversible cold-chain infrastructure investments and SENASA-EU equivalence negotiations that lock in premium export access regardless of currency cycles.
For Market Incumbents: Anchor defensible positioning through backward integration into drip-irrigation telemetry and certified nursery stock production in Mendoza and Río Negro. Consolidate packinghouse capacity ahead of tightening EU MRL enforcement to capture stranded competitor volume. Defend against Brazilian citrus substitution in Chinese juice concentrate markets by locking multi-season supply agreements with Tucumán processors. For New Entrants and Emerging Players: E-commerce platform routes offer lowest friction entry into Córdoba and Rosario metropolitan zones, where last-mile refrigeration infrastructure gaps persist. Target organic-certified blueberry expansion in Buenos Aires province under INTA varietal registration protocols. Pursue cooperative-based consolidation models bypassing traditional wholesale layers for direct supermarket contracting. For Investors and Strategic Acquirers: Asymmetric upside sits with technology-forward operators deploying precision agriculture systems and cloud-based irrigation analytics. Long-term viability hinges on water-right security under federal basin reforms and SENASA certification scalability. Monitor SENASA-EU equivalence agreement ratification as inflection signal for premium export tier expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Chain Infrastructure Expansion | Mendoza provincial certifications enable EU-grade table grape consolidation for Mercosur corridors. |
| Precision Agriculture Adoption | Drip-irrigation telemetry integration reduces water application rates while maintaining SENASA brix thresholds. |
| Organic Certification Investment | Argentine organic standards compliance unlocks price multiples in German and Dutch retail chains. |
| Direct-to-Retail Channel Development | Supermarket bypass of wholesale mercados shortens payment cycles for certified grower cooperatives. |
| Export Certification Upgrades | Tucumán packinghouse retrofits satisfy tightening SENASA residue protocols for EU MRL compliance. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with citrus estate managers, SENASA certification officers, supermarket category buyers, cold-chain logistics operators, and food manufacturing procurement leads with secondary validation. Data sources included SENASA export certification records, INTA technical bulletins, provincial agricultural department filings, and customs trade documentation. Bottom-up grower surveys and top-down sector aggregation were cross-referenced for triangulation.
Comparable-period anchoring established baseline growth patterns across historical harvest cycles before extending projections over the forecast horizon. Segmentation modeling incorporated product type, distribution channel, quality grade, and end-user archetype dimensions. CAGRs were derived from volume trajectory analysis calibrated against irrigation infrastructure deployment rates and phytosanitary equivalence negotiation timelines.
Currency devaluation, water-right allocation rulings, and EU MRL standard revisions are the dominant revision risks that could compress or extend projected value expansion. Forecasts reflect documented assumptions regarding SENASA certification throughput capacity and cold-chain infrastructure completion schedules. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Mango Puree Market
Fruits and Vegetables
Global Papaya Puree Market
Fruits and Vegetables
Guava Puree Market
Fruits and Vegetables
Vegetable Puree Market
Fruits and Vegetables
United States Guacamole Market
Fruits and Vegetables
Dried Blueberries Market
Fruits and Vegetables
Bamboo Shoots Market
Fruits and Vegetables
Dried Apple Peel Market
Fruits and Vegetables
Vaccinium Myrtillus Market
Fruits and Vegetables
Fresh Cherries Market
Fruits and Vegetables
Japan Fresh Fruits Market
Fruits and Vegetables
Frozen Vegetables Market
Fruits and Vegetables
Plums and Sloes Market
Fruits and Vegetables
Aegle Marmelos Market
Fruits and Vegetables
Dehydrated Green Beans Market
Fruits and Vegetables
Global Fruit Pomace Market