
 Cesium Salts Market | 2026-2036
Cesium Salts Market Size, Share, and Industry Trends Forecast 2026-2036
Cesium Salts Market Outlook
Specialty chemical distribution channels serving oilfield operators is reshaping procurement patterns for high-density drilling fluids. Albemarle Corporation leverages its vertically integrated position from brine extraction to formulated cesium formate products. Sinomine Resource Group anchors supply security through direct ownership of the Tanco mine in Canada and Bikita deposits in Zimbabwe. Cabot Corporation differentiates via technical service bundling that pairs salt delivery with on-site density management support.
Cesium salts comprise inorganic compounds derived from cesium, an alkali metal with atomic number 55, typically manufactured through acid digestion of pollucite ore followed by fractional crystallization or ion exchange purification to achieve grades exceeding 99.9 percent purity. These salts serve primarily as precursors for cesium formate brines in oil and gas drilling, as reagents in organic synthesis, and as dopants in photoelectric cells. Cesium chloride and cesium carbonate dominate current volume flows due to their established conversion pathways into formate and nitrate derivatives. Ultra high purity grades command concentrated margin pools from pharmaceutical and electronics manufacturers where trace metal specifications determine qualification status.
EPA regulations governing drilling fluid disposal on U.S. federal lands constrain formulation choices and elevate demand for biodegradable high-density alternatives. REACH registration requirements in Europe mandate full toxicological dossiers for cesium salt imports, creating compliance barriers for non-EU producers. China's GB standards for chemical purity and the Ministry of Ecology and Environment discharge rules shape domestic manufacturing investment. Stakeholders must monitor regulatory divergence between jurisdictions as qualification protocols fragment and certification costs escalate.
Market Dynamics
Oilfield operators are consolidating drilling fluid procurement around cesium formate brines as EPA disposal rules on federal lands render conventional barite-weighted muds uneconomical for complex well architectures.
Growth Catalysts
- High-pressure high-temperature drilling:Deepwater and ultra-deepwater exploration programs in the Gulf of Mexico and offshore Brazil require non-damaging brine systems that conventional alternatives cannot match.
- REACH registration completion:ECHA dossier acceptance for pharmaceutical-grade cesium salts has unlocked European pharmaceutical manufacturing qualification pathways.
- Pollucite processing expansion:Zimbabwean and Canadian mine output growth is feeding downstream chemical conversion capacity in Chinese industrial clusters.
Market Restraints
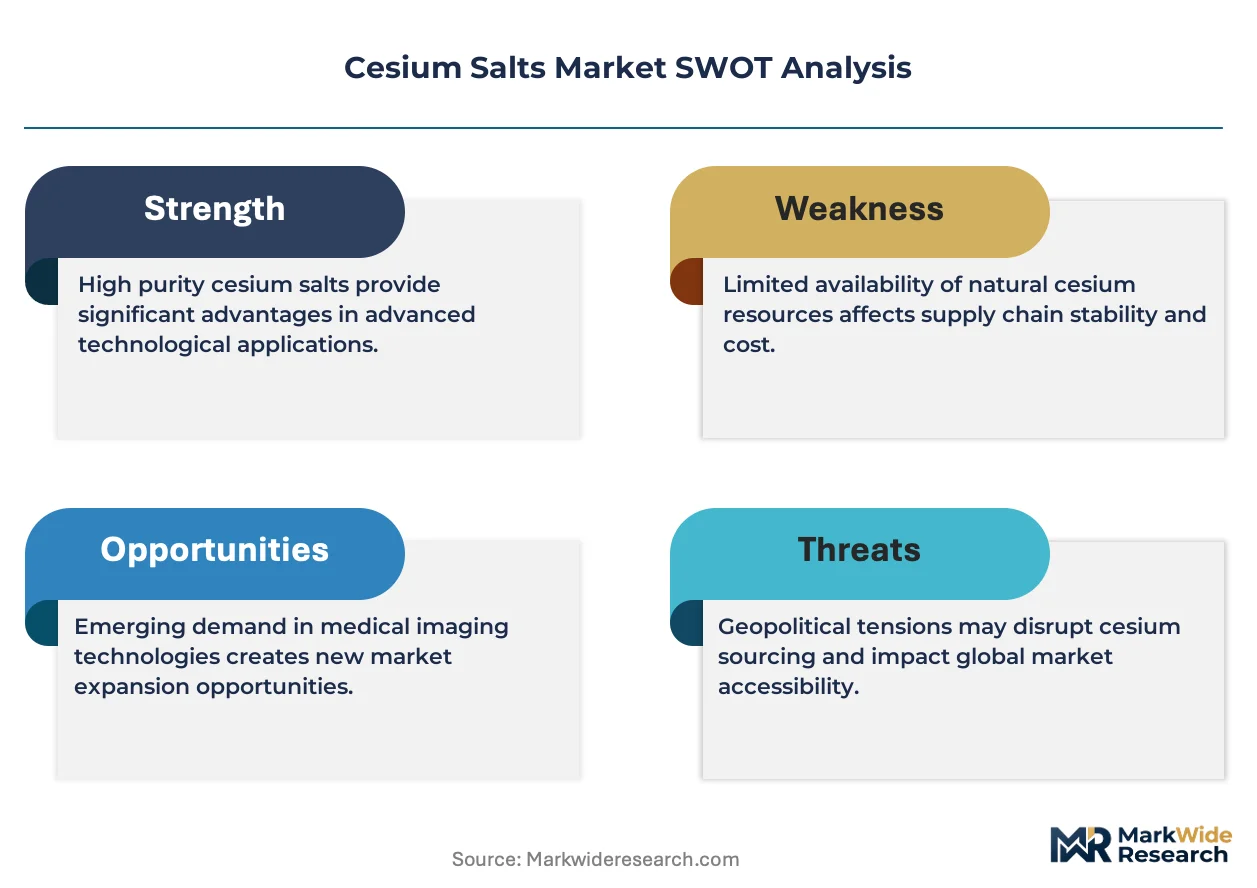
- Single-source ore dependency:Over 80 percent of pollucite reserves concentrate in three deposits, creating geopolitical concentration risk for supply security planning.
- Lithium-cesium-tantalum price correlation:Spodumene market volatility transmits directly to cesium salt input costs through shared mining economics.
- Formic acid supply tightness:Cesium formate production competes with agricultural and leather chemical demand for formic acid feedstock.
Strategic Opportunities
- Pharmaceutical API manufacturing:CDMOs in India and Ireland are qualifying ultra-high-purity cesium carbonate for contrast agent synthesis.
- Photovoltaic dopant applications:Perovskite solar cell researchers are testing cesium halide incorporation for thermal stability enhancement.
- Specialty chemical distributor consolidation:Regional oilfield service distributors are building captive cesium formate blending capacity to capture margin from integrated producers.
Industry Challenges
- Analytical chemistry talent scarcity:ICP-MS trace metal analysis expertise required for 99.99 percent purity certification commands premium compensation in tight labor markets.
- Multi-jurisdiction qualification timelines:Pharmaceutical manufacturers face 18-24 month stability study requirements to satisfy FDA, EMA, and NMPA filing standards simultaneously.
- Legacy drilling fluid infrastructure retrofit:Onshore rig fleets require density management system upgrades to handle cesium formate's distinct rheological properties.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cesium Salts Market |
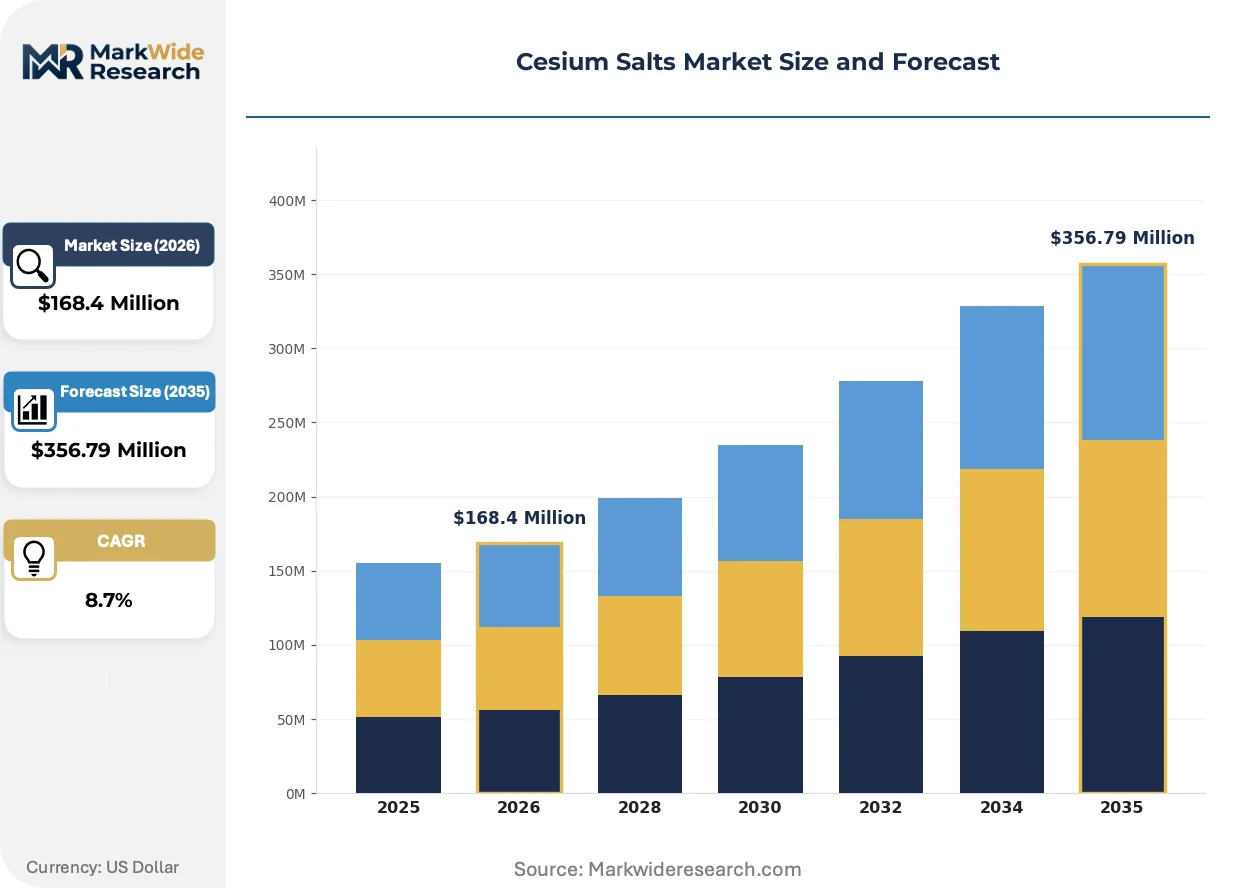
| Market Size in 2026 | $168.4 Million |
| Market Size in 2035 | $356.79 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cesium Chloride, Cesium Nitrate, Cesium Carbonate, Cesium Bromide Application: Oilfield Services, Medical Imaging, Chemical Synthesis, Electronics End User: Pharmaceuticals, Petrochemicals, Research Laboratories, Electronics Manufacturers Purity Grade: Technical Grade, Reagent Grade, High Purity, Ultra High Purity |
| Companies Covered | Albemarle Corporation, Sinomine Resource Group, Cabot Corporation, Merck KGaA, American Elements, Sichuan Brivo Lithium Materials, Nanjing Taiye Chemical Industry, Jiangxi Dongpeng New Materials, Ganfeng Lithium Co. Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cesium Salts Market Strategic Shifts
Digital density monitoring systems and automated brine blending platforms are compressing the technical service component of cesium formate supply contracts while elevating specification precision requirements.
Automated closed-loop density control systems are digitizing real-time drilling fluid weight management on offshore platforms. Deepwater operators in Angola and Norway are deploying these systems to reduce manual sampling frequency and cut non-productive time. The technology is digitizing service contract structures by shifting revenue from volume-based salt sales to performance-guaranteed density maintenance fees.
EPA's revised drilling waste management rules for federal lands are mandating biodegradable base fluid formulations for exploration permits. Oilfield service companies are reformulating synthetic-based muds around cesium formate carriers to meet toxicity testing protocols. Onshore US operators in the Permian and DJ basins are absorbing 15-20 percent fluid cost premiums to secure permit approval timelines.
Integrated supply agreements are compressing traditional distributor layers between cesium salt producers and end-use blenders. Major oilfield service providers are negotiating direct tolling arrangements with Tanco and Bikita mine operators to secure volume commitments and price predictability. This channel restructuring is most advanced in North Sea and West African offshore markets where operator consolidation has concentrated buying power.
Cesium Salts Market Segmentation
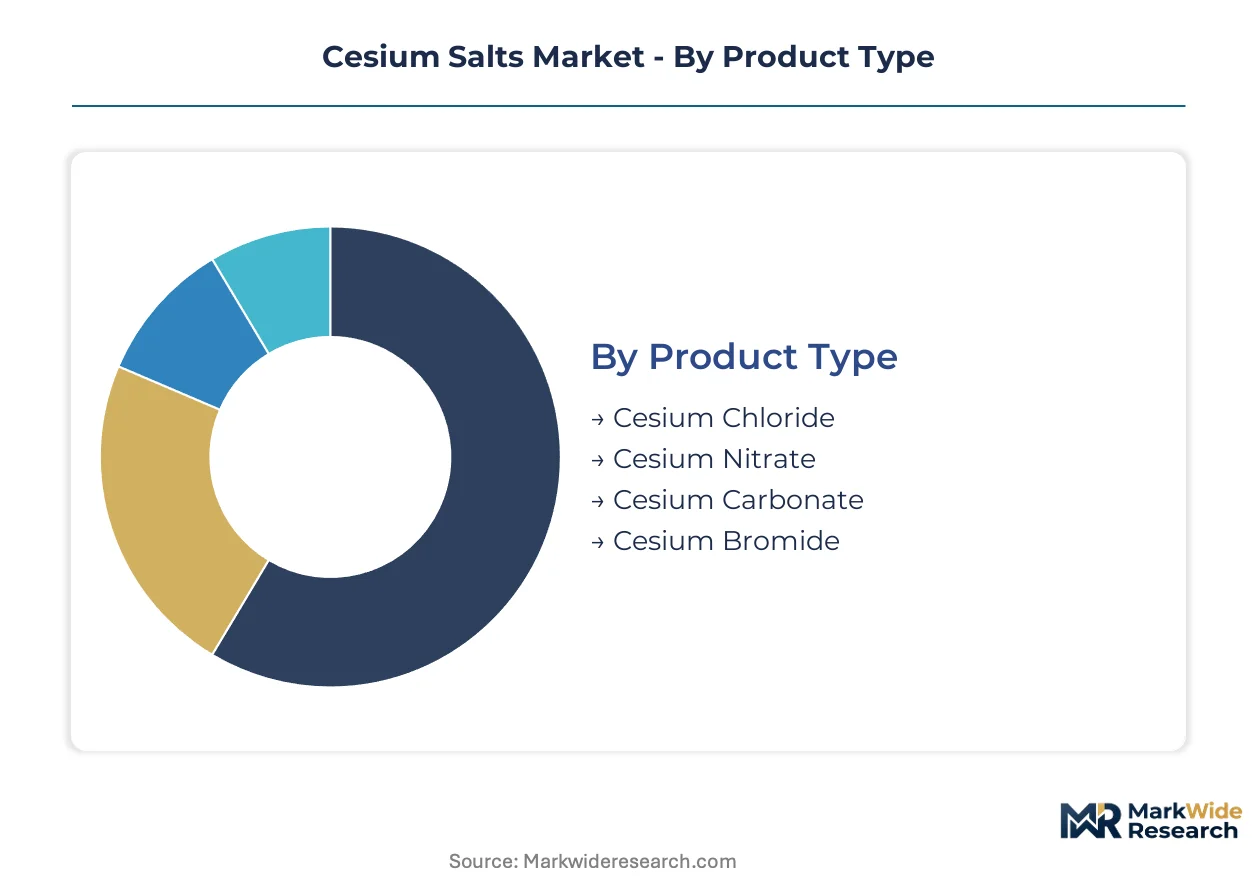
Cesium salt procurement patterns diverge sharply across product chemistry and application specifications. Pharmaceutical qualification pathways impose purity thresholds that fragment pricing structures away from technical-grade bulk chemistry. Understanding these segment boundaries clarifies where margin pools concentrate versus where volume flows commoditize.
Product Type:
Cost tier differentiation separates commodity chlorides from specialty nitrates and carbonates commanding formulation premiums.
- Cesium Chloride:Manufactured through acid digestion of pollucite ore followed by fractional crystallization, this salt serves as the primary feedstock for cesium formate brine conversion. Oilfield service blenders in the Gulf of Mexico and offshore Brazil absorb the majority of technical-grade chloride volume for high-pressure drilling applications.
- Cesium Carbonate:Produced via thermal decomposition of cesium oxalate or direct carbonation routes, this intermediate enables organic synthesis pathways for pharmaceutical active ingredients. CDMOs in India and Ireland are qualifying ultra-high-purity carbonate grades for contrast agent manufacturing under EMA and FDA dossier requirements.
- Cesium Nitrate:Crystalline oxidizer used in specialty pyrotechnic formulations and as a dopant precursor in photoelectric cell manufacturing. Research laboratories represent the primary offtake channel.
- Cesium Bromide:Halide salt employed in optical crystal growth and scintillation detector fabrication. Electronics manufacturers in Japan and Germany source reagent-grade material for radiation detection instruments.
Cesium chloride holds installed capacity. Cesium carbonate is rotating up the share rankings.
Application:
Volume concentration tracks oilfield drilling intensity while margin concentration follows pharmaceutical qualification timelines.
- Oilfield Services:Cesium formate brines displace barite-weighted muds in high-pressure high-temperature well architectures where formation damage risks render conventional fluids uneconomical. Deepwater operators in Angola and Norway are deploying automated density control systems that digitize real-time weight management and reduce manual sampling frequency.
- Medical Imaging:Cesium salts serve as precursors for iodinated contrast agents and radiopharmaceutical synthesis where trace metal specifications determine regulatory qualification status. Multi-jurisdiction filing requirements spanning FDA, EMA, and NMPA impose 18-24 month stability study timelines.
- Chemical Synthesis:Base-catalyzed condensation reactions and phase-transfer catalysis applications consume technical-grade material. Petrochemical manufacturers in China leverage domestic pollucite processing clusters for cost-advantaged feedstock access.
- Electronics:Photovoltaic researchers are testing cesium halide incorporation in perovskite solar cells for thermal stability enhancement. Photoelectric cell manufacturers specify dopant grades with sub-ppm trace metal limits.
Oilfield services holds installed capacity. Medical imaging is rotating up the share rankings.
End User:
Customer type determines specification stringency, with pharmaceutical and electronics manufacturers imposing purity premiums that technical-grade buyers refuse.
- Pharmaceuticals:Ultra-high-purity cesium carbonate and chloride feed into contrast agent synthesis and active pharmaceutical ingredient manufacturing. CDMO qualification protocols require ICP-MS trace metal certification that commands analytical chemistry talent premiums in tight labor markets.
- Petrochemicals:Integrated oilfield service providers negotiate direct tolling arrangements with mine operators to secure volume commitments and price predictability for cesium formate brine production. This channel restructuring concentrates buying power in North Sea and West African offshore markets.
- Research Laboratories:Academic and government institutions procure reagent-grade material for materials science and catalysis studies. Smaller lot sizes and irregular ordering patterns differentiate procurement from industrial buyers.
- Electronics Manufacturers:Photoelectric cell and radiation detector fabricators specify dopant grades with exacting trace metal controls. Japanese and German producers anchor demand for bromide and halide salts in scintillation crystal growth.
Petrochemicals holds installed capacity. Pharmaceuticals is rotating up the share rankings.
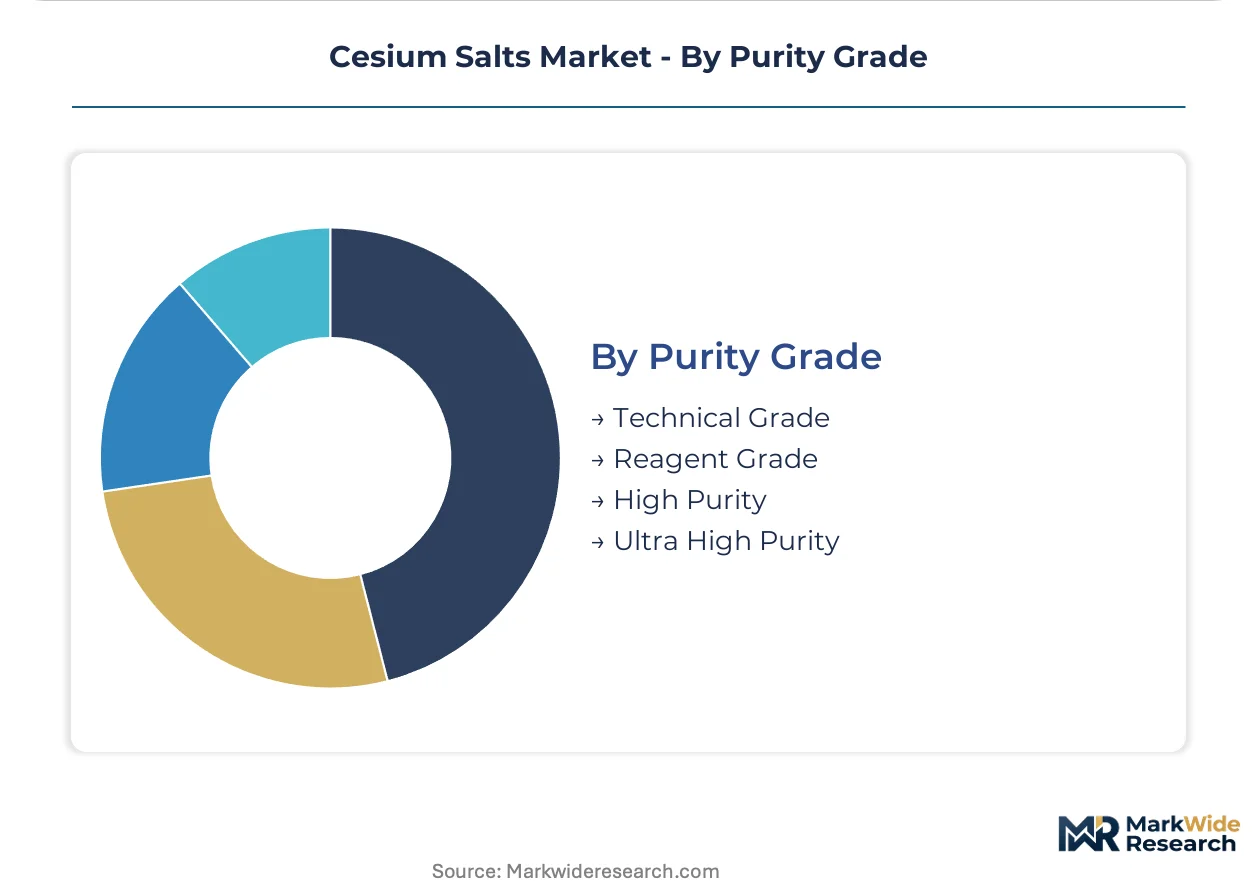
Purity Grade:
Specification tier creates margin stratification, with each ascending grade commanding exponential price premiums for equivalent mass.
- Technical Grade:95-99 percent purity material serves bulk oilfield applications where functional density and rheology matter more than trace metal content. Chinese industrial clusters process domestic pollucite output into technical-grade chloride for regional drilling fluid blenders.
- Reagent Grade:99-99.9 percent purity satisfies laboratory and analytical chemistry applications with moderate contamination tolerance. Research institutions represent the primary demand channel.
- High Purity:99.9-99.99 percent material meets electronics manufacturing specifications where alkali metal impurities degrade device performance. Photovoltaic researchers testing perovskite formulations require this tier for reproducible results.
- Ultra High Purity:Exceeding 99.99 percent purity with sub-ppm trace metal certification, this grade unlocks pharmaceutical manufacturing qualification under REACH registration and FDA drug master file requirements. Analytical chemistry talent scarcity for ICP-MS verification limits producer capacity expansion.
Technical grade holds installed capacity. Ultra high purity is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Houston's petrochemical corridor underwrites North American cesium formate distribution, channeling Canadian pollucite-derived salts to Gulf of Mexico drilling contractors. Rail links from Manitoba's Tanco mine complex feed this maritime nexus, creating a continent-spanning supply artery for high-density drilling fluid manufacturers.
United States
Deepwater operators in the Gulf of Mexico deploy cesium formate brines for high-pressure well architectures where barite-weighted alternatives fail. EPA drilling waste management rules for federal lands mandate biodegradable base fluids, accelerating formate adoption in Permian and DJ basin onshore programs. Houston's specialty chemical blending clusters process technical-grade chloride into formulated brines for regional oilfield service providers.
China
Domestic lithium-cesium-tantalum mining expansion in Jiangxi and Sichuan provinces feeds downstream chemical processing in the Yangtze River Delta. NMPA pharmaceutical-grade certification requirements and MEE discharge regulations shape manufacturing investment in ultra-high-purity carbonate production. Shanghai's contract development and manufacturing organizations qualify cesium salts for contrast agent synthesis under dual carbon compliance frameworks.
Germany
Photoelectric cell manufacturers in Baden-Württemberg source reagent-grade cesium bromide for scintillation detector fabrication. ECHA REACH registration dossiers for pharmaceutical-grade salts unlock European Union qualification pathways under MDR traceability requirements. Frankfurt's specialty chemical distributors consolidate procurement for regional electronics fabricators serving radiation instrumentation markets.
Canada
The Tanco mine in Manitoba anchors Western hemisphere pollucite supply, with rail connections to Vancouver enabling Pacific Rim export. Health Canada and PMRA environmental standards govern tailings management and brine disposal protocols for mining operations. Toronto's financial institutions structure offtake agreements linking mine output to Chinese chemical conversion facilities.
Norway
North Sea offshore platforms deploy automated density control systems for cesium formate brine management in subsea well completions. Norwegian Petroleum Directorate regulations mandate non-damaging drilling fluids for reservoir preservation in mature field redevelopment. Stavanger's oilfield service engineering clusters integrate digital monitoring technology with salt supply logistics for North Atlantic drilling campaigns.
Cesium Salts Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream with ore access and purification technology. The market structure concentrates around vertically integrated mining-to-chemical processors and tolling-dependent blenders. Three archetypes dominate: pollucite mine owners with captive chemical conversion, specialty salt refiners serving pharmaceutical qualification pathways, and oilfield service integrators bundling brine supply with density management. Capacity expansion and direct tolling arrangements represent the prevailing competitive moves, compressing traditional distributor layers.
Among North American resource-integrated players, Albemarle Corporation exemplifies the mine-to-formulated-product archetype through brine extraction and downstream chemical processing. Sinomarle Corporation anchors supply security through direct mineral asset ownership spanning Canadian and African deposits. Cabot Corporation occupies a position emphasizing technical service bundling rather than raw material control. These three entities represent distinct strategic postures: backward integration into ore sources, geographic diversification of mineral reserves, and forward integration into application engineering.
| Leading Market Players |
|---|
| Albemarle Corporation |
| Sinomine Resource Group |
| Cabot Corporation |
| Merck KGaA |
| American Elements |
| Sichuan Brivo Lithium Materials |
| Nanjing Taiye Chemical Industry |
| Jiangxi Dongpeng New Materials |
| Ganfeng Lithium Co. Ltd |
| Others |
Value Chain & Pricing Dynamics
Jiangxi province's lithium-cesium-tantalum mining clusters command upstream leverage that transmits directly to downstream cesium salt pricing power. Concentrated pollucite processing capacity in Chinese industrial corridors enables volume-tiered negotiations with oilfield service blenders seeking formate brine security.
Pricing Analysis
Three-tier pricing structure across ultra-high-purity, high-purity, and technical grades separates pharmaceutical qualification premiums from bulk oilfield contracts. Price differentiation hinges on ICP-MS certification costs and REACH registration status for European pharmaceutical access. Pricing pressure stems from formic acid feedstock competition with agricultural chemical demand. Petrochemical blenders exhibit highest price sensitivity due to commoditized drilling fluid procurement, while pharmaceutical CDMOs absorb purity premiums for regulatory qualification.
Supply Chain Analysis
Tariff exposure between Zimbabwe and Chinese processing hubs dominates supply chain risk planning for pollucite-derived cesium salts. Geographic supply concentrates in Canada, Zimbabwe, and Chinese domestic mining districts. Raw material dependencies include pollucite ore, sulfuric acid for digestion, and formic acid for formate conversion. Single-source ore vulnerability from three dominant deposits creates geopolitical concentration exposure. Distribution runs through specialty chemical distributors serving oilfield operators and direct tolling arrangements with mine operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ICP-MS analytical chemistry expertise scarcity constrains ultra-high-purity grade expansion and concentrates margin capture among qualified producers. This capability gap shapes competitive positioning across pharmaceutical and electronics qualification pathways.
For Market Incumbents: Entrench supply security through captive mine offtake agreements with Tanco or Bikita operators, insulating against lithium-cesium-tantalum price volatility. Invest in automated density control system integration to bundle technical service with salt supply and defend margin position against distributor consolidation threats. For New Entrants and Emerging Players: Establish a beachhead in pharmaceutical-grade carbonate production for Indian and Irish CDMO contrast agent programs, where 18-24 month qualification timelines deter incumbent switching. Pursue tolling partnerships with Zimbabwean mine developers to bypass upstream capital intensity. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified mining conglomerates with non-core cesium assets lacking downstream chemical conversion capacity. Long-term viability favors integrated mine-to-salt processors with REACH-registered pharmaceutical pathways. Watch perovskite solar cell commercialization timelines as cesium halide demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pollucite Mining | Direct Tanco or Bikita mine access secures feedstock against spodumene market volatility. |
| REACH Registration Investment | ECHA dossier completion unlocks European pharmaceutical manufacturing qualification pathways. |
| Automated Density Control Deployment | Real-time brine management systems shift revenue from volume sales to performance fees. |
| Pharmaceutical CDMO Partnership | Ultra-high-purity carbonate supply agreements with Indian and Irish contrast agent manufacturers. |
| Perovskite Solar Cell R&D Collaboration | Cesium halide incorporation testing with photovoltaic researchers builds optionality on thermal stability applications. |
Study Parameters
Desk research of customs trade databases, SEC 10-K filings, and ECHA registration dossiers preceded structured interviews with oilfield service procurement directors, pharmaceutical CDMO regulatory affairs leads, and specialty chemical distribution channel managers. Primary fieldwork captured tolling arrangement structures and qualification timeline benchmarks. Secondary validation drew from mining industry reports and chemical processing capacity databases. Bottom-up segment sizing triangulated against top-down market consolidation estimates.
Assumptions around oilfield drilling intensity, REACH registration completion rates, and perovskite solar cell commercialization timelines were held fixed across baseline scenarios while lithium-cesium-tantalum price volatility and formic acid supply tightness were stress-tested. Segmentation modeling incorporated purity grade tiers, end-use applications spanning oilfield services through medical imaging, and geographic production clusters. CAGRs were derived from regression analysis of historical volume flows and projected substitution dynamics for high-pressure drilling applications.
Stress conditions across pollucite ore availability, EPA drilling waste rule enforcement stringency, and pharmaceutical qualification timeline compression were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory divergence and substitution technology maturation. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
North America Calcium Chloride Market
Bulk Chemicals
Sodium Permanganate Market
Bulk Chemicals
Global Butyric Acid Market
Bulk Chemicals
Phosphorus Market
Bulk Chemicals
Powdered Cellulose Market
Bulk Chemicals
Calcium Hypophosphite Market
Bulk Chemicals
Bulk Chemical Packaging Market
Bulk Chemicals
Isobutene Market
Bulk Chemicals
Oman Sodium Hydroxide Market
Bulk Chemicals
Bulk Liquid Containers Market
Bulk Chemicals
Magnesium Phosphate Market
Bulk Chemicals
Mangiferin Market
Bulk Chemicals
Global Crude Sulfate Turpentine Market
Bulk Chemicals
Global Quinine Sulphate Market
Bulk Chemicals
Mesifurane Market
Bulk Chemicals
Europe Lipids Market