
 Certificate Authority Market | 2026-2036
Certificate Authority Market Size, Share, and Industry Trends Forecast 2026-2036
Certificate Authority Market Intelligence
The proliferation of small to medium-sized enterprises and individual developers entering the digital economy is rebalancing customer concentration away from solely large enterprises. DigiCert Inc. specializes in high-assurance certificates for complex enterprise environments. In contrast, Cloudflare Inc. leverages its content delivery network to provide automated and integrated certificate management. GoDaddy Inc. dominates the high-volume, low-cost segment catering to web hosting and small business clients.
A Certificate Authority is a trusted entity that issues digital certificates to verify the identity of a subject. These certificates utilize public key cryptography to bind an identity to a public key, enabling secure, encrypted communication channels like TLS. While SSL Certificates for website authentication represent the largest product category, demand for cloud-based deployment models is accelerating. This shift is driven by the ease of management and integration offered by major cloud providers for their ecosystem services.
Regulatory frameworks establish the trust and operational standards for certificate issuance. In Europe, the eIDAS regulation provides a legal framework for electronic identification, while GDPR influences data protection requirements for websites. In the United States, guidelines from NIST inform best practices for cryptographic standards and identity verification. Stakeholders must now navigate the trade-offs between certificate lifecycle automation and the stringent verification requirements for higher-trust credentials.
Market Dynamics
The central structural force shaping the market is the industry-wide compression of certificate validity periods. Mandates from major browser root programs require more frequent renewals, which in turn necessitates a fundamental shift towards automated certificate lifecycle management to maintain operational security.
Growth Catalysts
- Regulatory Frameworks:Europe's eIDAS regulation provides a legal basis for electronic signatures and trust services, creating standardized demand for qualified digital certificates across the European Union.
- E-commerce Expansion:The continued growth of online retail platforms necessitates TLS certificates to secure customer data, build trust, and comply with Payment Card Industry Data Security Standard (PCI DSS) requirements.
- Internet of Things (IoT):Proliferation of connected devices in sectors like industrial manufacturing and smart home technology requires device-level certificates to establish unique identities and secure machine-to-machine communication.
Market Restraints
- Open-Source Alternatives:The availability of free, automated Domain Validation (DV) certificates from providers like Let's Encrypt exerts significant price pressure on the low-assurance segment of the commercial market.
- High-Assurance Validation Burden:The rigorous and often manual identity verification processes required for Extended Validation (EV) certificates create a cost and complexity barrier that deters adoption by many organizations.
- Root Program Dependency:Certificate Authorities are heavily dependent on the policies of a few dominant browser and operating system vendors, whose decisions can unilaterally alter market rules and technical requirements.
Strategic Opportunities
- Post-Quantum Cryptography (PQC):Developing and offering certificates based on PQC algorithms presents an opportunity to secure critical infrastructure against future threats from quantum computers, creating a new premium service category.
- Verified Digital Identity:Expanding services beyond website encryption to include verifiable credentials for individuals and legal entities aligns with emerging digital identity ecosystems in jurisdictions like Canada and Australia.
- Managed PKI for OT:Providing specialized, scalable certificate management services for operational technology (OT) environments, such as industrial control systems and utilities, addresses a critical security gap.
Industry Challenges
- Cryptographic Expertise Shortage:A limited talent pool of security engineers with deep knowledge of Public Key Infrastructure (PKI) and applied cryptography constrains product development and secure operations for all providers.
- Automation and Verification Conflict:CAs face the operational challenge of balancing the demand for rapid, automated certificate issuance with the stringent verification requirements needed to prevent mis-issuance and maintain trust.
- Legacy System Integration:Integrating modern, API-driven certificate lifecycle management tools with older enterprise IT environments that lack modern interfaces creates significant deployment friction and implementation costs for customers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Certificate Authority Market |
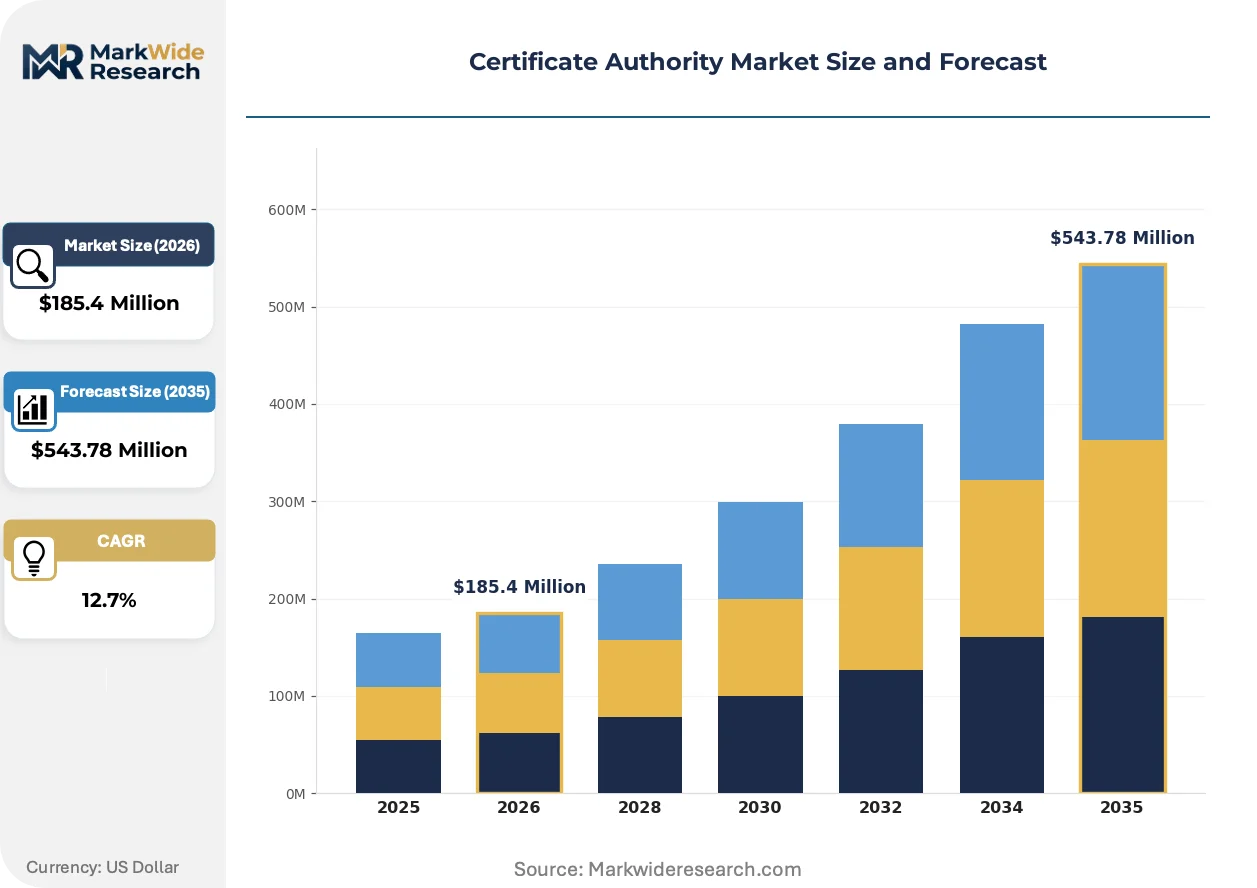
| Market Size in 2026 | $185.4 Million |
| Market Size in 2035 | $543.78 Million |
| CAGR (2026 – 2036) | 12.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: SSL Certificates, Code Signing Certificates, Email Certificates, Document Signing Certificates, Client Certificates Deployment Model: Cloud-Based, On-Premises, Hybrid, Managed Services Application: Website Authentication, Software Validation, Secure Email, Digital Signature, Two-Factor Authentication End User: Financial Institutions, E-Commerce Platforms, Government Agencies, Technology Firms, Educational Institutions |
| Companies Covered | GoDaddy Inc., Entrust Corp., DigiCert Inc., Asseco Data Systems SA, IdenTrust Inc., Sectigo Limited, Amazon Web Services Inc., Cloudflare Inc., GlobalSign, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Certificate Authority Market Strategic Shifts & Innovations
The market's evolution is defined by a transition from manual, periodic certificate management to a model of continuous, automated, and integrated identity assurance. This shift is driven by the dual pressures of compressed certificate lifecycles and the integration of PKI into cloud-native development workflows.
Certificate Lifecycle Management (CLM) platforms automate the discovery, issuance, renewal, and revocation of digital certificates across an enterprise. DevOps and IT security teams are the primary adopters, driven by the need to manage certificate sprawl in complex, multi-cloud environments. This technology is modularizing PKI services, enabling organizations to consume certificate management as a discrete, API-driven function rather than a monolithic, manually-intensive process.
Industry self-regulation, primarily through the CA/Browser Forum's Baseline Requirements, mandates progressively shorter certificate validity periods. This policy forces enterprises to abandon manual renewal tracking, which is prone to human error, and adopt automated solutions to prevent service outages. Large enterprises managing thousands of public-facing web servers are the most affected segment, accelerating their investment in centralized CLM platforms.
Consumption patterns are moving away from traditional direct sales and reseller channels toward integrated procurement within cloud service provider marketplaces. This disintermediates legacy sales models for basic certificate types, with providers like AWS and Azure becoming dominant distribution points for their captive developer ecosystems. The trend is most pronounced in the United States, where cloud-native business models and rapid development cycles are standard.
Certificate Authority Market Segmentation
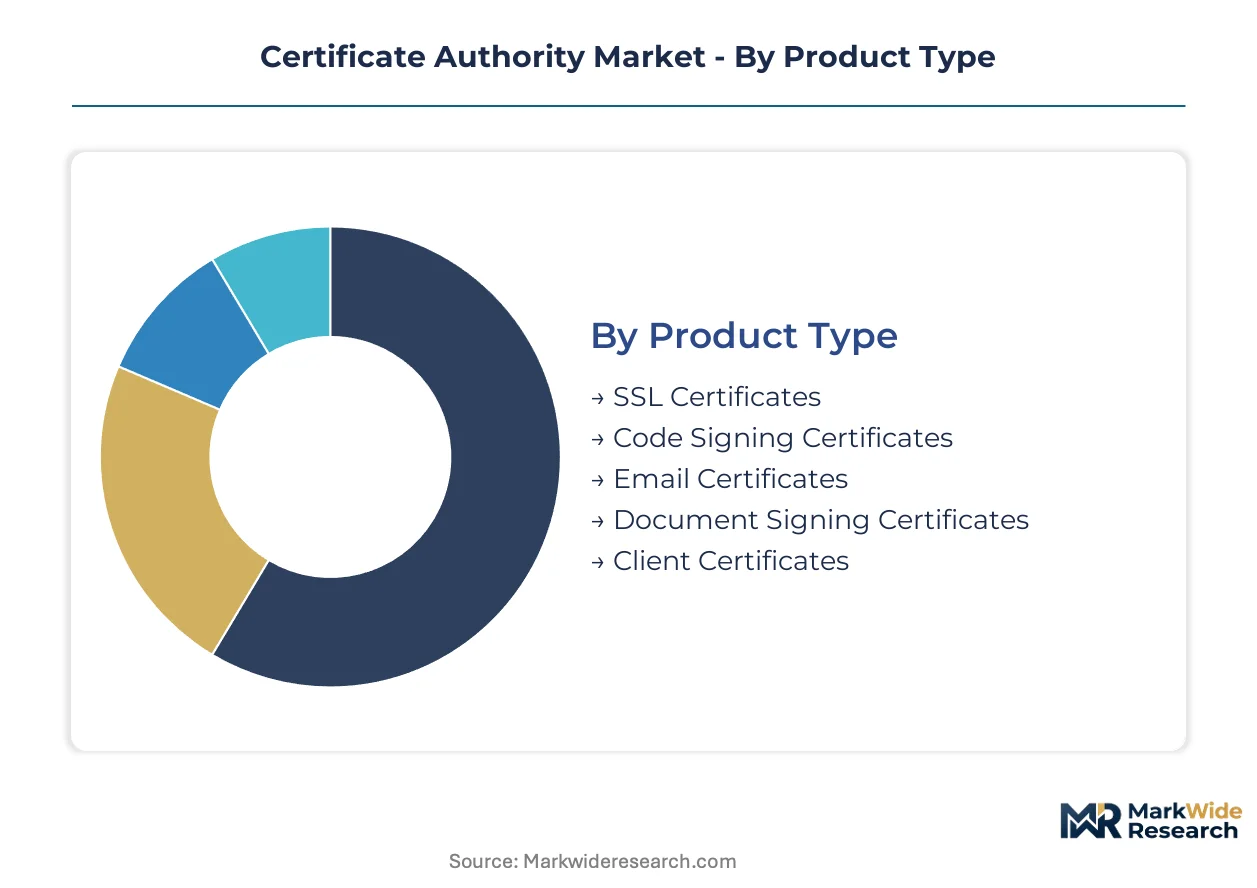
Market segmentation clarifies the diverse requirements driving demand for Certificate Authority services across various industries and technological applications. Understanding these distinctions enables providers to tailor solutions that meet specific security, compliance, and operational needs for different customer profiles.
Product Type:
Certification authorities issue various product types, each requiring distinct validation processes and trust levels for their specific use cases.
- SSL Certificates:These certificates establish encrypted connections and verify server identities, primarily securing web traffic through TLS. Demand concentrates heavily from e-commerce platforms and global digital infrastructure providers requiring robust website security.
- Code Signing Certificates:Digital certificates verify software publisher identity and ensure code integrity, preventing tampering. Software development firms across the United States increasingly adopt these for secure application distribution.
- Email Certificates:These certificates enable secure, encrypted email communication and verify sender identity.
- Document Signing Certificates:Digital certificates authenticate the origin and integrity of electronic documents, ensuring non-repudiation.
- Client Certificates:These provide strong authentication for individual users and devices accessing network resources or applications.
Leading the category by volume: SSL Certificates. Growing fastest: Code Signing Certificates.
Deployment Model:
Deployment models reflect diverse organizational preferences for infrastructure control and operational flexibility in managing digital certificates.
- Cloud-Based:Certificates are managed and issued through third-party cloud providers, offering scalability and ease of integration via APIs. Technology firms and multi-cloud environments globally increasingly prefer this model for its agility.
- Managed Services:Specialized third-party providers handle all aspects of PKI operations and certificate lifecycle management for an organization. Large enterprises, particularly European financial institutions, leverage these services to offload complex security tasks.
- On-Premises:Organizations host and manage their entire certificate authority infrastructure within their own data centers.
- Hybrid:This model combines elements of both on-premises and cloud-based certificate management for tailored solutions.
Cloud-Based models offer enhanced scalability, while Managed Services streamline complex PKI operations.
Application:
Each application category addresses a specific security objective, ranging from verifying digital identities to securing communication channels.
- Website Authentication:This application secures web traffic and verifies server identity using TLS/SSL certificates, building user trust. E-commerce platforms globally depend on this for securing customer data and transactions.
- Digital Signature:Certificates enable the creation of legally binding digital signatures, ensuring document integrity and sender non-repudiation. Government agencies and European legal frameworks like eIDAS drive demand for this application.
- Software Validation:This confirms the authenticity and integrity of software executables before installation.
- Secure Email:Certificates encrypt and digitally sign email communications, protecting message privacy and sender identity.
- Two-Factor Authentication:Certificates enhance user login security by providing a strong second factor for identity verification.
Website Authentication commands the largest market share, with Digital Signature applications expanding quickly due to regulatory mandates.
End User:
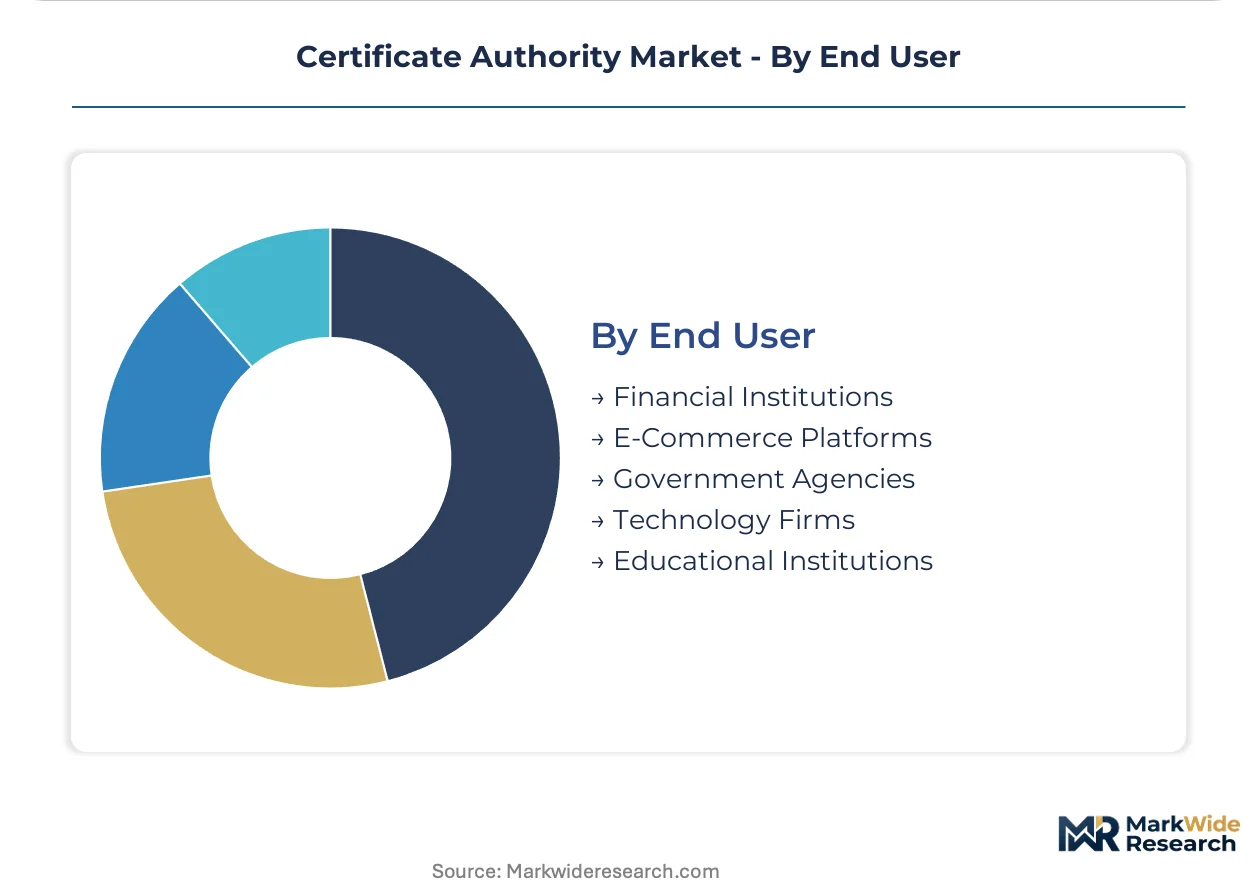
End-user segments exhibit varying security requirements and compliance needs, driving distinct demands for certificate types and management solutions.
- Financial Institutions:These entities require high-assurance certificates for transaction security, data protection, and adherence to regulations like PCI DSS. The global banking sector is a primary consumer, driven by stringent security mandates.
- E-Commerce Platforms:Online retail businesses rely on TLS certificates to secure customer data, build trust, and comply with payment industry standards. This segment drives significant demand across all global markets.
- Government Agencies:Public sector entities utilize certificates for secure internal communications, citizen services, and digital identity verification.
- Technology Firms:These companies require certificates for software signing, device authentication, and securing extensive cloud infrastructure deployments.
- Educational Institutions:Universities and schools deploy certificates for secure campus networks, online learning platforms, and staff/student authentication.
Financial Institutions prioritize robust identity verification, while Technology Firms drive innovation in automated certificate management.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand-side concentration for Certificate Authority services is pronounced in digitally advanced economies. The United States leads this adoption, fueled by its extensive digital infrastructure and a high density of technology firms. This trend reflects the global push for enhanced online security and identity verification across diverse sectors.
United States
The United States drives significant demand for Certificate Authority solutions, particularly from its vast e-commerce sector and technology firms. Guidelines from NIST inform best practices for cryptographic standards and identity verification across federal agencies. Silicon Valley and other tech hubs in California continue to innovate in automated certificate lifecycle management.
Germany
Germany exhibits strong demand for high-assurance certificates, driven by its robust industrial base and stringent data protection requirements. The eIDAS regulation provides a legal framework for electronic identification and trust services across the European Union, influencing German enterprises. Financial centers like Frankfurt adopt advanced digital signature solutions for secure transactions.
United Kingdom
The United Kingdom's expanding digital economy and financial services sector generate substantial demand for secure website authentication. GDPR influences data protection requirements for UK websites, necessitating frequent certificate renewals. London's vibrant tech ecosystem focuses on cloud-based deployment models for agile certificate management.
India
India's rapid digital transformation and burgeoning e-commerce platforms create a growing need for TLS certificates. The country's national cybersecurity policies encourage secure digital transactions and data protection for its large online user base. Technology hubs such as Bengaluru are seeing increased adoption of code signing certificates for software distribution.
Japan
Japan's advanced manufacturing and technology sectors require robust digital certificates for secure machine-to-machine communication. METI guidelines promote the adoption of secure IoT devices and digital transformation initiatives across industries. Tokyo's financial institutions prioritize client certificates for strong user authentication in their digital services.
Certificate Authority Market Key Industry Players
Established producers occupy the standard tier, focusing on foundational certificate issuance; emerging entrants pursue integrated certificate lifecycle management. The market structure segments into providers offering high-assurance credentials and those specializing in automated, high-volume solutions. Strategic archetypes include enterprise PKI specialists, cloud-native integrators, and mass-market certificate vendors. Portfolio diversification and strategic partnerships represent dominant competitive moves among market participants.
Enterprise PKI specialists like DigiCert Inc. exemplify providers focused on high-assurance certificates for complex organizational environments. Cloudflare Inc. represents a significant player leveraging network infrastructure to deliver automated and integrated certificate management solutions. GoDaddy Inc. occupies a position as a mass-market vendor, catering to the high-volume, low-cost segment for web hosting and small business clients.
| Leading Market Players |
|---|
| GoDaddy Inc. |
| Entrust Corp. |
| DigiCert Inc. |
| Asseco Data Systems SA |
| IdenTrust Inc. |
| Sectigo Limited |
| Amazon Web Services Inc. |
| Cloudflare Inc. |
| GlobalSign |
| Others |
Cost & Logistics Intelligence
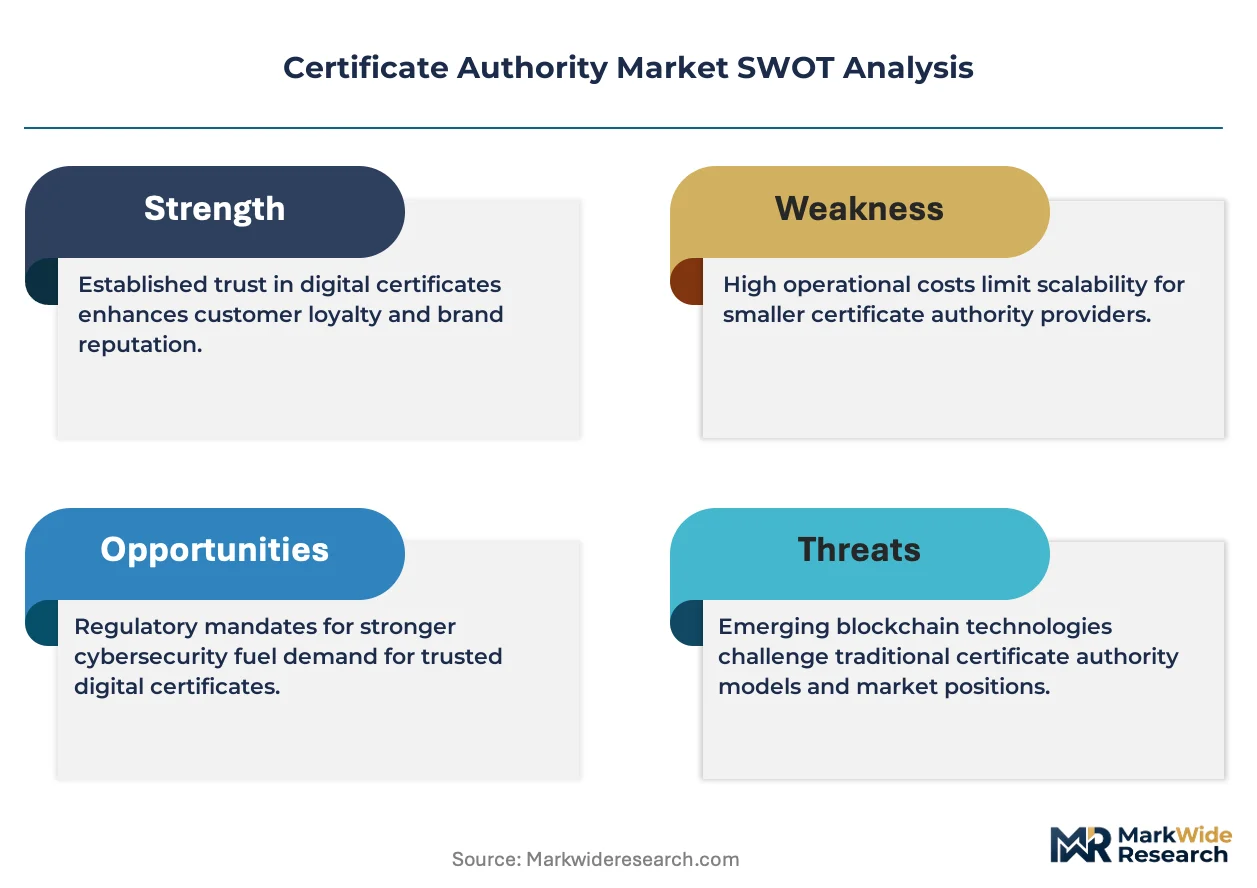
Mandates from major browser root programs, requiring more frequent renewals, necessitate a fundamental shift towards automated certificate lifecycle management, impacting service pricing for enterprises.
Pricing Analysis
Volume-driven certificates, such as those for domain validation, operate on thin margins, while high-assurance Extended Validation certificates command premium pricing. The dominant pricing structure involves SaaS-tiered subscriptions for Certificate Lifecycle Management platforms and transactional fees for individual certificates. Price differentiation stems from assurance levels (DV versus EV) and bundled managed services. Pricing softness affects the low-assurance segment due to free alternatives like Let's Encrypt. Small businesses exhibit high price sensitivity, whereas large enterprises prioritize reliability and feature sets.
Supply Chain Analysis
Certificate issuance rests heavily on the technical infrastructure provided by major browser and operating system vendors, who define root program policies. Geographic supply concentration for Certificate Authorities primarily involves the United States, with significant players also in Europe. Key dependencies include adherence to root program policies from entities like Mozilla, Google, and Apple, alongside cryptographic standards from NIST. Unilateral policy changes by browser vendors represent a structural supply chain risk. Distribution increasingly runs through cloud service provider marketplaces and direct API integrations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Certificate Authority market is constrained by a severe shortage of cryptographic expertise, limiting innovation and driving up the cost of specialized PKI services.
For Market Incumbents:Acquire specialized CLM technology firms to integrate advanced automation capabilities and bolster API-driven certificate management solutions. Diversify portfolios into Post-Quantum Cryptography development to pre-empt future security threats. This proactive investment in R&D helps counter the long-term threat posed by quantum computing. Strengthen relationships with browser root programs to influence policy decisions and maintain market stability against disruptive shifts.
For New Entrants and Emerging Players:Post-quantum cryptography solutions offer a technology-first wedge for new entrants to establish a premium service category in secure digital identity. Target underpenetrated operational technology (OT) environments, such as industrial control systems, with managed PKI services. Develop specialized device-level certificates for IoT manufacturers in sectors like smart home technology. A focused go-to-market angle emphasizes ease of integration and compliance with emerging device security standards.
For Investors and Strategic Acquirers:The window for entry favors strategic investors targeting niche PKI automation providers with strong cloud integration capabilities over the next decade. Focus on companies that offer scalable, API-driven solutions for complex multi-cloud environments. Acquisition targets should demonstrate robust intellectual property in certificate lifecycle automation and strong customer retention. A significant signal to watch is the increasing investment by major cloud providers into integrated certificate management offerings.
| Strategic Initiative | Industry Significance |
|---|---|
| Product Launch (PQC Certificates) | Secures critical infrastructure against future quantum threats. |
| Platform Integration (API-driven CLM) | Streamlines certificate management for multi-cloud environments. |
| Acquisition of Specialist Firm (OT PKI Vendor) | Addresses critical security gaps in industrial control systems. |
| Strategic Partnership (Browser Vendors) | Influences root program policies and technical standards. |
| Geographic Expansion (Emerging Markets) | Captures demand from India's e-commerce growth. |
Research Approach
Industry association reports, regulatory guidelines from NIST and eIDAS, and public company financial disclosures anchored secondary inputs for this study. Primary research involved interviews with Chief Technology Officers, Chief Security Officers, IT procurement managers, and compliance officers across various industries. This approach combined bottom-up and top-down triangulation to ensure comprehensive data validation.
Market size and growth were modeled across product type, deployment model, application, and end-user segments at a country level over the projection horizon. The analytical framework integrated historical data with future growth projections, deriving Compound Annual Growth Rates through rigorous statistical analysis. Key forecast inputs included anticipated changes in browser policy and projected e-commerce expansion rates across regions.
Several conditions sit outside the modeled scope, including specific vendor-level market shares and short-term macroeconomic volatility. Forecasts reflect assumptions regarding technological stability and regulatory continuity. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security Software
Secaas Market
Security Software
Online Background Check Market
Security Software
GDPR Software and Tools Market
Security Software
Cloud Data Loss Prevention Solution Market
Security Software
BYOD Security Market
Security Software
Global User Provisioning Market
Security Software
Global Background Check Software Market
Security Software
Global Digital Vehicle Forensics Market
Security Software
Global Secure Access Service Edge Market
Security Software
Global User Activity Monitoring Market
Security Software
Mobile Threat Management Security Software Market
Security Software
Global Data Privacy Management Software Tools Market
Security Software
Privileged Identity Management Market
Security Software
Global Optical Encryption Market
Security Software
VPN Software Market
Security Software
Consumer Endpoint Security Market