
 Global Development Analytics Tools Market | 2026-2036
Global Development Analytics Tools Market Size, Share, and Industry Trends Forecast 2026-2036
Global Development Analytics Tools Market Foresight
The capital-intensity divergence between hyperscale cloud providers and specialized analytics vendors is rotating competitive dynamics toward platform consolidation. Microsoft Corporation leverages its Azure-integrated Power BI ecosystem to anchor enterprise deployments across North America and Western Europe. Amazon Web Services sustains momentum through SageMaker and QuickSight bundling with infrastructure contracts. Google LLC differentiates via BigQuery's serverless architecture and AI-ready data pipelines.
Development analytics tools encompass software platforms that ingest, process, and visualize code repositories, application performance metrics, and software delivery pipelines to optimize engineering throughput and product quality. These systems typically integrate with CI/CD environments, issue trackers, and version control systems to generate actionable intelligence on deployment frequency, lead time for changes, and failure recovery rates. Cloud-based deployment models now dominate new procurement as organizations prioritize elastic scaling and reduced infrastructure overhead over on-premises control. Predictive analytics capabilities represent the fastest-expanding tool type, capturing margin pools from financial services and telecommunications buyers seeking anticipatory failure detection and capacity planning.
The EU AI Act, FedRAMP authorization requirements, and ISO/IEC 27001 certification frameworks collectively shape product roadmaps and market access conditions for vendors serving regulated industries. GDPR data residency provisions and the SEC's cybersecurity disclosure rules further constrain cross-border data architectures, compelling platform providers to regionalize cloud infrastructure and audit trails. Stakeholders must monitor evolving algorithmic accountability standards and procurement pre-qualification criteria that increasingly mandate explainable analytics outputs and third-party security attestations.
Market Dynamics
Cloud migration mandates under the EU AI Act and FedRAMP authorization requirements are compressing vendor qualification timelines while redistributing procurement budgets toward compliance-certified platforms.
Growth Catalysts
- EU AI Act cloud mandates:Compliance-driven procurement accelerates across Germany, France, and the United Kingdom as enterprises regionalize infrastructure to satisfy data residency provisions.
- Financial services predictive modeling:Real-time risk analytics platforms capture expanded budgets from banking and insurance buyers seeking anticipatory failure detection capabilities.
- Federal digital modernization:United States public-sector deployments reshape vendor selection criteria through FedRAMP authorization requirements and cybersecurity disclosure rules.
Market Restraints
- GDPR data residency compliance costs:Regionalized cloud infrastructure and audit trail localization inflate platform operational overhead for cross-border deployments.
- Algorithmic accountability standards:Explainable analytics output mandates under emerging ISO/IEC frameworks extend product development cycles and certification timelines.
- Specialized talent scarcity:Shortage of engineers proficient in both CI/CD pipeline architecture and statistical modeling constrains enterprise implementation velocity.
Strategic Opportunities
- Telecommunications capacity planning:Predictive analytics for network infrastructure optimization represents underpenetrated white space among 5G operators in South Korea and Japan.
- Edge-to-cloud pipeline convergence:Integration of serverless data pipelines with distributed version control systems creates new platform bundling potential for DevOps toolchains.
- SEC cybersecurity disclosure alignment:Automated compliance reporting modules for publicly traded software vendors open adjacent revenue streams in audit automation.
Industry Challenges
- Legacy system integration complexity:On-premises version control and issue tracker architectures resist seamless API connectivity with cloud-native analytics platforms.
- Cross-functional skill gaps:Shortage of product managers fluent in both DORA metrics and executive risk communication impedes enterprise sales cycle progression.
- Third-party security attestation backlog:ISO/IEC 27001 and SOC 2 certification queue delays stall procurement approvals at regulated healthcare and financial institutions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Development Analytics Tools Market |
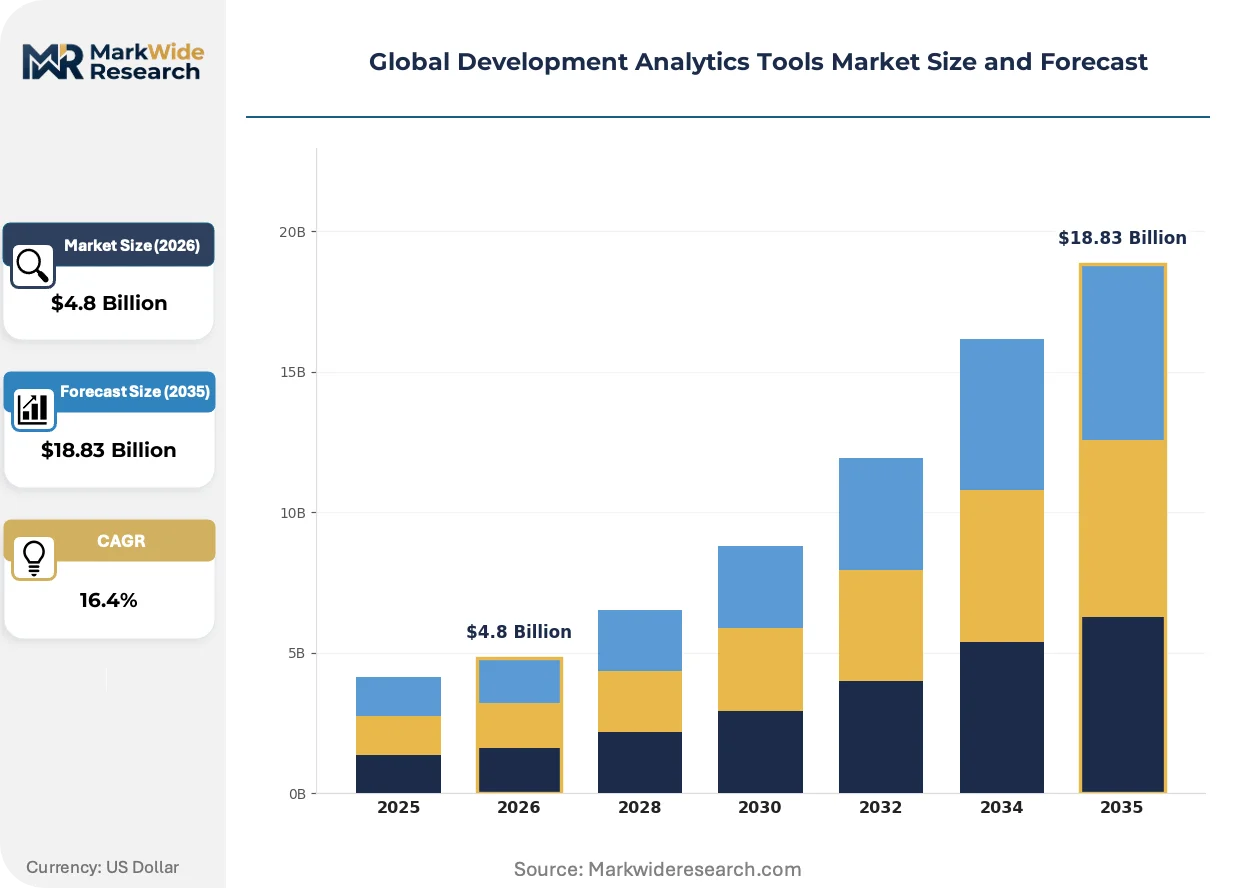
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $18.83 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Cloud-Based, On-Premises, Hybrid, Edge Tool Type: Data Visualization, Predictive Analytics, Data Mining, Performance Monitoring, Statistical Analysis Industry Application: Financial Services, Telecommunications, Manufacturing, Public Sector, Transportation End User Type: Software Developers, Data Scientists, Business Analysts, Consultants, Academic Researchers |
| Companies Covered | Microsoft Corporation, Amazon Web Services, Google LLC, Oracle Corporation, IBM Corporation, SAS Institute, SAP SE, Tableau Software, Databricks, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Development Analytics Tools Market Shifts & Advancements
Development analytics platforms are converging with infrastructure-as-code workflows, compressing the traditional separation between observability tooling and deployment automation. This integration is reshaping how engineering organizations instrument, measure, and optimize software delivery performance.
Embedded observability agents within container orchestration layers are miniaturizing the footprint required for real-time pipeline telemetry. Platform engineering teams at scale software enterprises are adopting these lightweight instrumentation packages to reduce overhead on build systems. This compression is miniaturizing the historical trade-off between granular visibility and runtime performance, enabling sub-second latency in deployment frequency tracking.
The EU AI Act's algorithmic accountability provisions are mandating explainable output documentation for automated decision-support systems. Vendors serving European financial services and telecommunications buyers must now embed interpretability layers into predictive failure models. Germany's BSI and France's CNIL enforcement patterns are pushing providers to regionalize model training data and inference endpoints.
Enterprise buyers are consolidating vendor relationships through platform bundling rather than point-solution procurement. Engineering leaders at United States technology firms are prioritizing unified contracts spanning CI/CD, observability, and analytics capabilities. This concentration is most visible among Series C and public software companies seeking to rationalize toolchain sprawl and reduce security review overhead.
Global Development Analytics Tools Market Segmentation
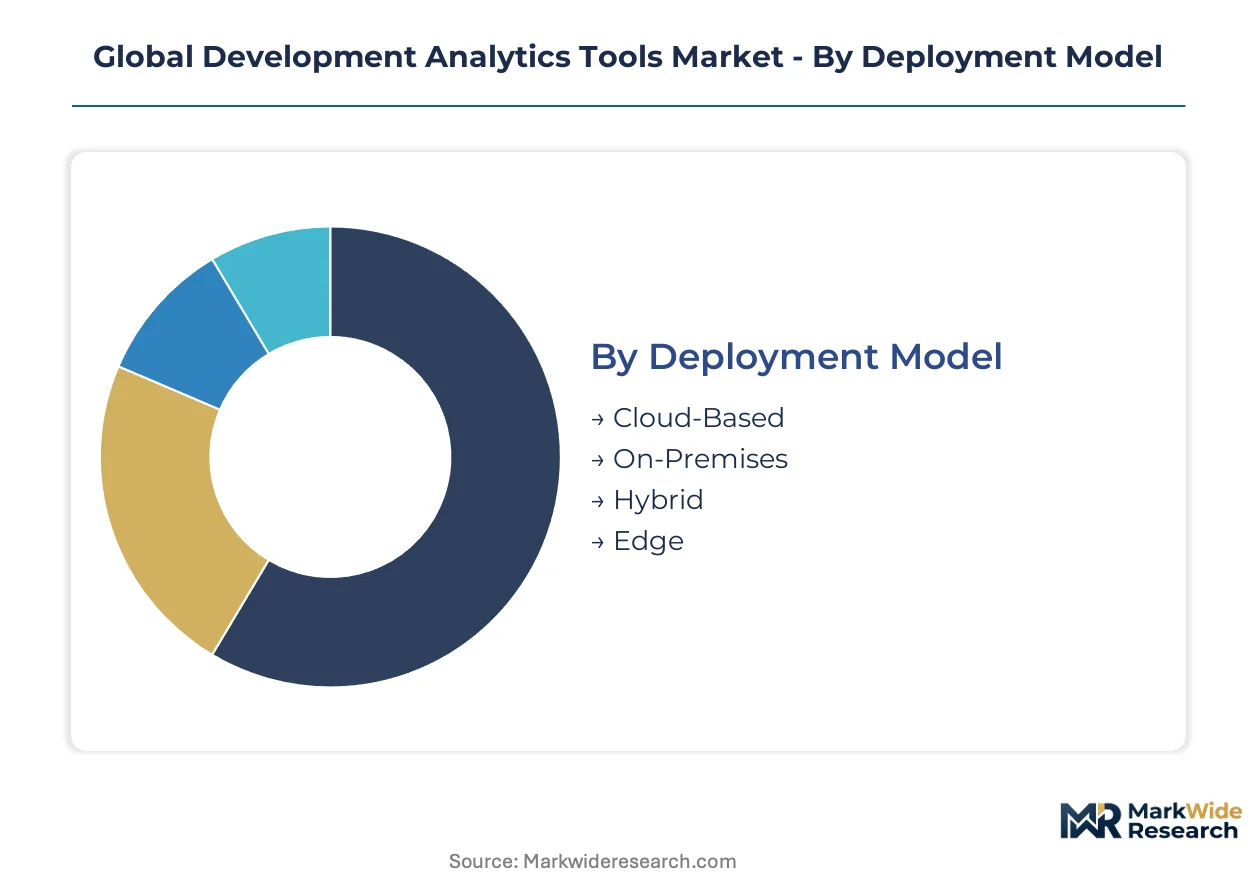
Development analytics tools segment across deployment architectures, analytical capabilities, and professional user bases. Procurement patterns diverge sharply between regulated industries requiring on-premises control and cloud-native enterprises prioritizing elastic scaling.
Deployment Model:
Regulatory frameworks fragment procurement by mandating data residency controls that disqualify certain architectures from specific geographies.
- Cloud-Based:Elastic infrastructure provisioning dominates new enterprise procurement, with multi-tenant architectures reducing operational overhead. Financial services firms in Germany and France accelerate adoption under EU AI Act cloud migration mandates, though FedRAMP authorization requirements constrain vendor pools for United States public-sector buyers.
- Hybrid:Split architectures segregate sensitive model training data on-premises while pushing inference workloads to regional cloud zones. Manufacturing enterprises in Japan and South Korea favor this model for intellectual property protection alongside computational scalability.
- On-Premises:Air-gapped installations persist in defense and intelligence applications requiring physical network isolation. Germany's BSI certification frameworks and classified facility requirements sustain demand despite higher total cost of ownership.
- Edge:Distributed processing nodes embed analytics capabilities directly into manufacturing floors and telecommunications base stations. 5G infrastructure operators deploy lightweight inference engines for sub-millisecond failure detection without cloud roundtrips.
Established volume favors Cloud-Based deployments; emerging adoption favors Edge architectures.
Tool Type:
Functional specialization determines integration depth with CI/CD pipelines and observability stacks.
- Predictive Analytics:Machine learning models forecast deployment failures, capacity bottlenecks, and security vulnerabilities before production impact. Banking and insurance buyers in the United States and United Kingdom capture margin pools through anticipatory risk modeling, though algorithmic accountability standards under ISO/IEC frameworks extend certification timelines.
- Data Visualization:Interactive dashboards translate DORA metrics and pipeline telemetry into executive-facing intelligence. Business analysts at technology firms consolidate vendor relationships through Power BI and QuickSight bundling rather than standalone procurement.
- Performance Monitoring:Real-time ingestion of application traces and infrastructure metrics enables sub-second anomaly detection. Container orchestration layers miniaturize agent footprints for runtime efficiency.
- Data Mining:Pattern extraction across historical code repositories identifies technical debt accumulation and refactoring priorities. Engineering leaders leverage these insights for sprint planning and resource allocation.
- Statistical Analysis:Hypothesis testing frameworks validate A/B experiments and feature flag outcomes with rigorous confidence intervals. Academic researchers and quantitative consultants maintain specialized demand for classical inference methods.
Predictive Analytics is climbing the fastest as financial services procurement budgets reallocate toward anticipatory capabilities.
Industry Application:
Sector-specific compliance regimes dictate feature requirements and security attestation thresholds.
- Financial Services:Real-time risk modeling platforms integrate with trading systems and fraud detection pipelines. SEC cybersecurity disclosure rules and GDPR data residency provisions compel regionalized cloud infrastructure with auditable model lineage.
- Telecommunications:Network capacity planning tools optimize 5G spectrum allocation and edge computing deployments. South Korean and Japanese operators represent underpenetrated white space for predictive infrastructure analytics.
- Public Sector:Federal digital modernization initiatives reshape vendor selection through FedRAMP authorization requirements. United States agencies prioritize explainable outputs and third-party security attestations.
- Manufacturing:Industrial IoT analytics correlate equipment sensor streams with quality control metrics. Germany's automotive clusters drive demand for ISO/IEC 27001-certified platforms with on-premises data sovereignty.
- Transportation:Logistics optimization engines model route efficiency and predictive maintenance for fleet operations. Aviation regulators impose stringent documentation requirements on automated decision-support systems.
Financial Services concentrates current revenue; Telecommunications offers the steepest expansion trajectory for predictive capacity planning tools.
End User Type:
Professional role determines interface complexity, statistical sophistication, and integration workflow requirements.
- Software Developers:IDE-embedded analytics surfaces code complexity metrics and review cycle bottlenecks directly within engineering workflows. GitHub and GitLab native integrations dominate procurement preferences.
- Data Scientists:Notebook-compatible APIs enable custom model development against pipeline telemetry stores. Python and R library support is non-negotiable for this segment.
- Business Analysts:Low-code dashboard builders translate technical metrics into executive presentations without engineering dependency. Self-service configuration reduces ticket burden on platform engineering teams.
- Consultants:Multi-tenant client workspaces with data isolation controls support advisory engagements across competing enterprises. Exportable compliance documentation accelerates audit deliverables.
- Academic Researchers:Educational licensing and publication-grade reproducibility features sustain niche demand. Open-source interoperability and citation tooling influence procurement decisions.
Software Developers anchor platform engagement metrics; Data Scientists drive predictive analytics feature roadmaps.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Financial services firms in the United States deploy predictive analytics for real-time risk modeling, while German automotive clusters and Japanese telecommunications operators prioritize on-premises data sovereignty and edge inference capabilities respectively.
United States
Federal digital modernization initiatives and FedRAMP authorization requirements reshape vendor selection criteria for public-sector analytics deployments. SEC cybersecurity disclosure rules compel regionalized cloud infrastructure with auditable model lineage. Silicon Valley technology firms and Wall Street banking clusters anchor enterprise procurement of CI/CD-integrated platforms.
Germany
BSI certification frameworks and EU AI Act cloud migration mandates accelerate compliance-driven procurement across automotive and industrial sectors. GDPR data residency provisions inflate operational overhead for cross-border deployments. Munich and Stuttgart engineering clusters drive demand for ISO/IEC 27001-certified platforms with hybrid deployment architectures.
United Kingdom
Financial services regulators emphasize algorithmic accountability standards for automated decision-support systems in trading and fraud detection pipelines. CNIL-aligned enforcement patterns push providers toward explainable output documentation. London fintech clusters concentrate procurement budgets for anticipatory risk modeling capabilities.
Japan
Telecommunications operators deploy predictive capacity planning tools for 5G spectrum allocation and edge computing optimization. METI industrial policy supports manufacturing IoT analytics with intellectual property protection requirements. Tokyo and Osaka technology corridors favor hybrid architectures segregating sensitive training data on-premises.
South Korea
Network infrastructure operators represent underpenetrated white space for predictive analytics in telecommunications capacity planning. MFDS-aligned data governance frameworks constrain cross-border model training architectures. Seoul Capital Area technology firms accelerate adoption of lightweight edge inference engines for sub-millisecond failure detection.
Global Development Analytics Tools Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with hyperscale cloud providers leveraging infrastructure bundling to compress point-solution margins. Microsoft Corporation, Amazon Web Services, and Google LLC anchor the upper tier through platform consolidation. Mid-scale specialists differentiate through CI/CD-native integrations and sector-specific compliance certifications. Dominant competitive moves include strategic partnerships with container orchestration vendors and geographic expansion through regional cloud infrastructure deployment.
Within the integrated platform tier, Microsoft Corporation exemplifies the Azure-anchored ecosystem play, while Amazon Web Services occupies a position defined by SageMaker and QuickSight bundling with infrastructure contracts. Google LLC represents the serverless architecture vector through BigQuery's AI-ready data pipelines.
| Leading Market Players |
|---|
| Microsoft Corporation |
| Amazon Web Services |
| Google LLC |
| Oracle Corporation |
| IBM Corporation |
| SAS Institute |
| SAP SE |
| Tableau Software |
| Databricks |
| Others |
Supply & Pricing Matrix
Capacity reservation contracts with hyperscale cloud providers anchor procurement visibility for enterprise buyers, locking in multi-year compute access while constraining price volatility exposure across EU AI Act compliance windows. These structures concentrate negotiating leverage with Microsoft Azure, Amazon Web Services, and Google Cloud Platform, compressing margins for independent analytics vendors unable to match infrastructure bundling scale.
Pricing Analysis
Subscription renewals and professional services tiers drive lifetime value capture, with annual recurring revenue models dominating procurement across North American and Western European enterprises. Three-tier pricing structure across premium, standard, and economy levels segments by FedRAMP authorization status and ISO/IEC 27001 certification grade. Pricing pressure stems from hyperscaler bundling of SageMaker, QuickSight, and Power BI with infrastructure contracts, eroding standalone analytics margins. Small and mid-market software vendors exhibit highest price sensitivity, while regulated financial institutions prioritize compliance certification over cost.
Supply Chain Analysis
GPU and specialized AI accelerator availability through Taiwan Semiconductor Manufacturing and Samsung Foundry anchors model training capacity for predictive analytics platforms. Cloud infrastructure draws from concentrated data center buildouts in the United States, Ireland, and Singapore, with NVIDIA H100 and AMD MI300X chips as critical inputs. Single-source vulnerability in advanced semiconductor fabrication threatens platform scaling timelines for European vendors under GDPR data residency mandates. Distribution runs through direct enterprise sales teams and hyperscaler marketplace listings, with channel partners serving mid-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Development Analytics Tools Market sits in early-cycle expansion, with EU AI Act cloud migration mandates and FedRAMP authorization requirements accelerating compliance-driven procurement velocity beyond historical SaaS adoption curves.
For Market Incumbents: Consolidate platform engineering capabilities through acquisition of CI/CD-native tooling specialists, neutralizing the threat from DevOps toolchain unification plays. Expand FedRAMP Moderate and High authorization coverage to defend public-sector market access, while embedding explainable AI interpretability layers to satisfy emerging ISO/IEC algorithmic accountability standards before certification backlogs stall procurement approvals. For New Entrants and Emerging Players: Differentiate on edge-to-cloud pipeline convergence for telecommunications operators in South Korea and Japan, where predictive capacity planning for 5G infrastructure remains underpenetrated. Target hybrid deployment architectures for German automotive and industrial clusters seeking BSI-certified platforms with on-premises data sovereignty. Lead with lightweight inference engines and sub-millisecond latency guarantees to bypass hyperscaler infrastructure bundling dominance. For Investors and Strategic Acquirers: Capital is best deployed toward mid-scale specialists possessing CI/CD-native integrations and sector-specific compliance certifications, positioned for platform consolidation by hyperscalers seeking vertical depth. Long-term viability hinges on sustained differentiation through regulatory moats rather than feature velocity alone. Monitor ISO/IEC 27001 and SOC 2 certification queue lengths as inflection indicators for procurement velocity at regulated healthcare and financial institutions.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifying CI/CD, observability, and analytics compresses vendor sprawl for Series C software enterprises. |
| Strategic Partnership | Container orchestration vendor alliances embed analytics agents directly into Kubernetes and OpenShift layers. |
| Geographic Expansion | Regional cloud infrastructure deployment satisfies GDPR data residency for German and French financial services buyers. |
| Acquisition of Specialist Firm | CI/CD-native tooling targets fill platform gaps without multi-year organic development cycles. |
| Product Launch | Automated SEC cybersecurity disclosure modules open adjacent revenue streams in audit automation for public software vendors. |
Research Methodology
Cross-validation between primary interviews with platform engineering directors, IT procurement officers, and DevOps team leads and secondary validation through SEC filings, hyperscaler capex disclosures, and EU regulatory implementation notices anchors the qualitative findings. Bottom-up triangulation against cloud infrastructure spending patterns and top-down reconciliation with enterprise software market sizing ensures dimensional consistency. Conversations spanned financial services technology clusters in New York and London, automotive engineering centers in Munich and Stuttgart, and telecommunications operators in Seoul and Tokyo.
Sensitivity analysis around EU AI Act enforcement timelines and FedRAMP authorization velocity shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include deployment architecture, analytical capability type, industry vertical, and professional user role. CAGRs derive from elasticity-adjusted adoption curves incorporating compliance mandate effective dates and infrastructure migration patterns. Model inputs incorporate cloud spend trajectory disclosures, regulatory pre-qualification criteria evolution, and talent scarcity indicators for CI/CD-statistics hybrid skill sets.
Material uncertainties — algorithmic accountability standard finalization, semiconductor supply constraints, and cross-border data architecture rulings — sit outside the modeled envelope. Forecasts reflect assumptions around sustained regulatory enforcement intensity and hyperscaler bundling persistence. Practitioners should keep alternative scenarios live as BSI, CNIL, and SEC enforcement patterns evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
IT Operation Analytics (ITOA) Software Market
Analytics
Data Mining Tools Market
Analytics
Europe Edge Analytics Market
Analytics
Imagery Analytics Market
Analytics
Global Visual Analytics Market
Analytics
Descriptive Analytics (Descriptive Statistics) Market
Analytics
Asia-Pacific Contact Center Analytics Market
Analytics
IT Operation Analytics (ITOA) Market
Analytics
Retail Analytics Market
Analytics
Asia-Pacific Edge Analytics Market
Analytics
Data Preparation Market
Analytics
India Big Data Technology and Service Market
Analytics
Face Analytics Market
Analytics
Mobile App Attribution Tool Market
Analytics
Europe Network and Location Analytics Market
Analytics
France Contact Center Analytics Market