
 Silanes and Silicones Market | 2026-2036
Silanes and Silicones Market Size, Share, and Industry Trends Forecast 2026-2036
Silanes and Silicones Market Outlook
China is fragmenting the silanes and silicones supply base as domestic producers add organosilicon monomer capacity at scale. Dow Inc. leverages its integrated silicone intermediates network across North American and European manufacturing sites. Wacker Chemie AG anchors high-purity silicone production for semiconductor and photovoltaic applications. Shin-Etsu Chemical Co., Ltd. dominates advanced silicone rubber compounding for automotive and electronics customers.
Silanes and silicones comprise silicon-based compounds where silanes feature silicon-hydrogen or silicon-carbon bonds used as coupling agents and surface modifiers, while silicones contain repeating siloxane (Si-O-Si) backbones delivering thermal stability, electrical insulation, and weather resistance across temperatures from -60°C to 250°C. These materials serve as essential inputs for adhesion, sealing, coating, and elastomer formulation in manufacturing industries. Silicones lead product type demand due to their versatility across automotive gasketing, electronics encapsulation, and construction sealant applications. Coatings and adhesives applications command premium formulations as OEMs specify low-VOC, high-durability silicone systems for electric vehicle battery packs and 5G infrastructure. Liquid and gel forms capture the majority volume as processing efficiency favors pumpable, sprayable delivery systems in automated manufacturing lines.
EPA regulations in the United States govern volatile organic compound emissions from silicone coating and adhesive formulations, pushing manufacturers toward solvent-free and water-based product development. REACH compliance in Europe mandates comprehensive organosilicon substance registration and safety assessment, creating entry barriers for non-compliant suppliers. China's GB standards and MEE oversight on chemical manufacturing emissions shape domestic production economics and export qualification protocols. Stakeholders must monitor regulatory divergence across these jurisdictions to anticipate reformulation costs and supply chain requalification timelines.
Market Dynamics
China's aggressive capacity expansion in organosilicon monomers is fragmenting supply concentration while automotive electrification pulls silicone thermal management materials into battery pack architectures at unprecedented scale.
Growth Catalysts
- EV battery thermal regulation:Electric vehicle manufacturers specify silicone gap fillers and potting compounds for cell-to-cell thermal management, creating material demand that outpaces traditional automotive sealing applications.
- REACH substance registration:The EU's tightening compliance thresholds for organosilicon imports favor established registrants with complete safety dossiers, concentrating import share among pre-qualified suppliers.
- Photovoltaic encapsulant demand:Solar module producers specify high-purity silicone rubbers for junction box sealing and frame bonding as installation volumes accelerate.
Market Restraints
- Methyl chloride feedstock volatility:Silane production economics hinge on chloromethane pricing from methanol-chlorine chemistry, exposing margins to energy and chlorine supply shocks.
- Chinese domestic oversupply:State-supported capacity additions in Jiangsu and Zhejiang provinces threaten export pricing discipline as producers prioritize volume utilization over margin preservation.
- Fluoropolymer substitution in high-heat electronics:PTFE and FEP materials displace silicone wire insulation in aerospace and military applications where temperature excursions exceed 300°C.
Strategic Opportunities
- India specialty silicone localization:The country's PLI scheme for advanced chemistry manufacturing offers tariff and tax incentives for domestic silicone emulsion and sealant production.
- Medical-grade liquid silicone rubber:Long-term implantable device manufacturers seek ISO 10993-certified LSR suppliers as healthcare outsourcing accelerates in Southeast Asia.
- 5G infrastructure weatherproofing:Base station OEMs specify low-dielectric silicone gels for antenna sealing and fiber optic cable flooding compounds as network densification proceeds.
Industry Challenges
- Organosilicon process engineering expertise:Direct process operators with experience in Rochow synthesis and hydrolysis-condensation kinetics command premium compensation as Chinese capacity expansion depletes regional talent pools.
- Multi-jurisdiction REACH-GB standard reconciliation:Formulators must maintain parallel substance inventories and safety data sheet protocols to serve EU and Chinese markets simultaneously.
- Legacy chlorosilane asset retrofit costs:Brownfield sites face capital-intensive environmental compliance upgrades to meet MEE emissions standards on hydrogen chloride recovery and wastewater treatment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Silanes and Silicones Market |
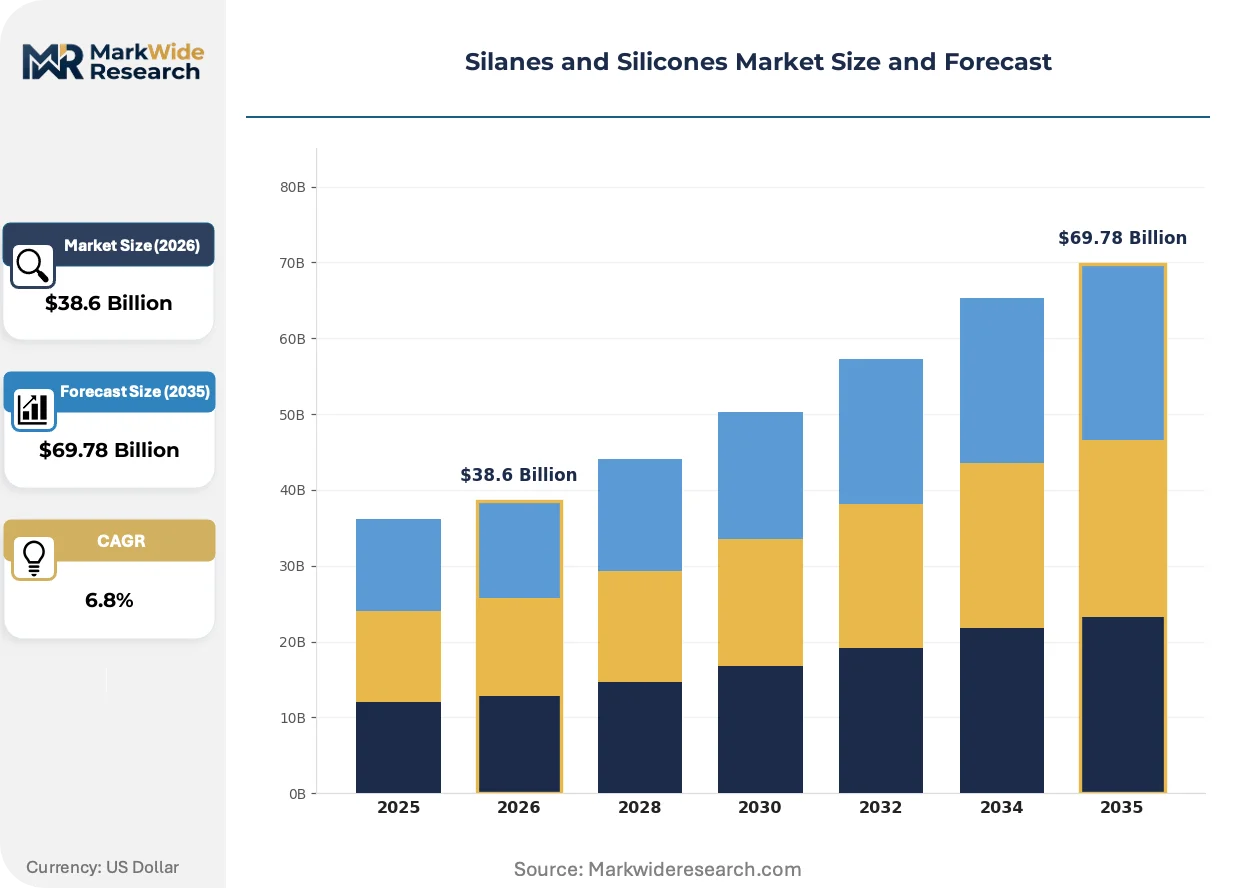
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $69.78 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silanes, Silicones, Organosilicon Compounds, Coupling Agents End Use Industry: Automotive, Electronics, Construction, Healthcare Application: Coatings, Adhesives, Sealants, Rubber Compounding Form: Liquid, Gel, Powder, Emulsion |
| Companies Covered | Evonik Industries AG, KCC Corporation, Dow Inc., Gelest, Inc., Elkem ASA, Wacker Chemie AG, Momentive Performance Materials Inc., China National Bluestar Co., Shin-Etsu Chemical Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Silanes and Silicones Market Strategic Shifts
Silicone chemistry is hybridizing with adjacent material classes as formulators pursue property combinations unattainable through conventional siloxane architectures alone.
Hybrid silicone-urethane systems are hybridizing at the molecular level through isocyanate-terminated silane coupling agents. Automotive seating and interior trim suppliers adopt these materials to merge silicone weatherability with polyurethane processing speed and cost structure. The resulting elastomers compress formulation timelines for tier suppliers serving just-in-sequence assembly contracts.
EPA volatile organic compound rules for adhesive and sealant categories are tightening permissible solvent content thresholds in industrial maintenance and construction applications. Manufacturers respond with high-solids and water-based silicone emulsion platforms that sacrifice some application latitude for compliance assurance. Southern California air quality management districts enforce the strictest interpretations, forcing reformulation for regional distribution.
Specification authority is migrating from distributor sales organizations to OEM material engineering departments armed with thermal modeling software and accelerated aging protocols. Tier suppliers now submit silicone candidates for finite element analysis validation before purchase order release. This pattern concentrates supplier rosters in Germany and Japan where automotive and electronics material databases are most extensively documented.
Silanes and Silicones Market Segmentation
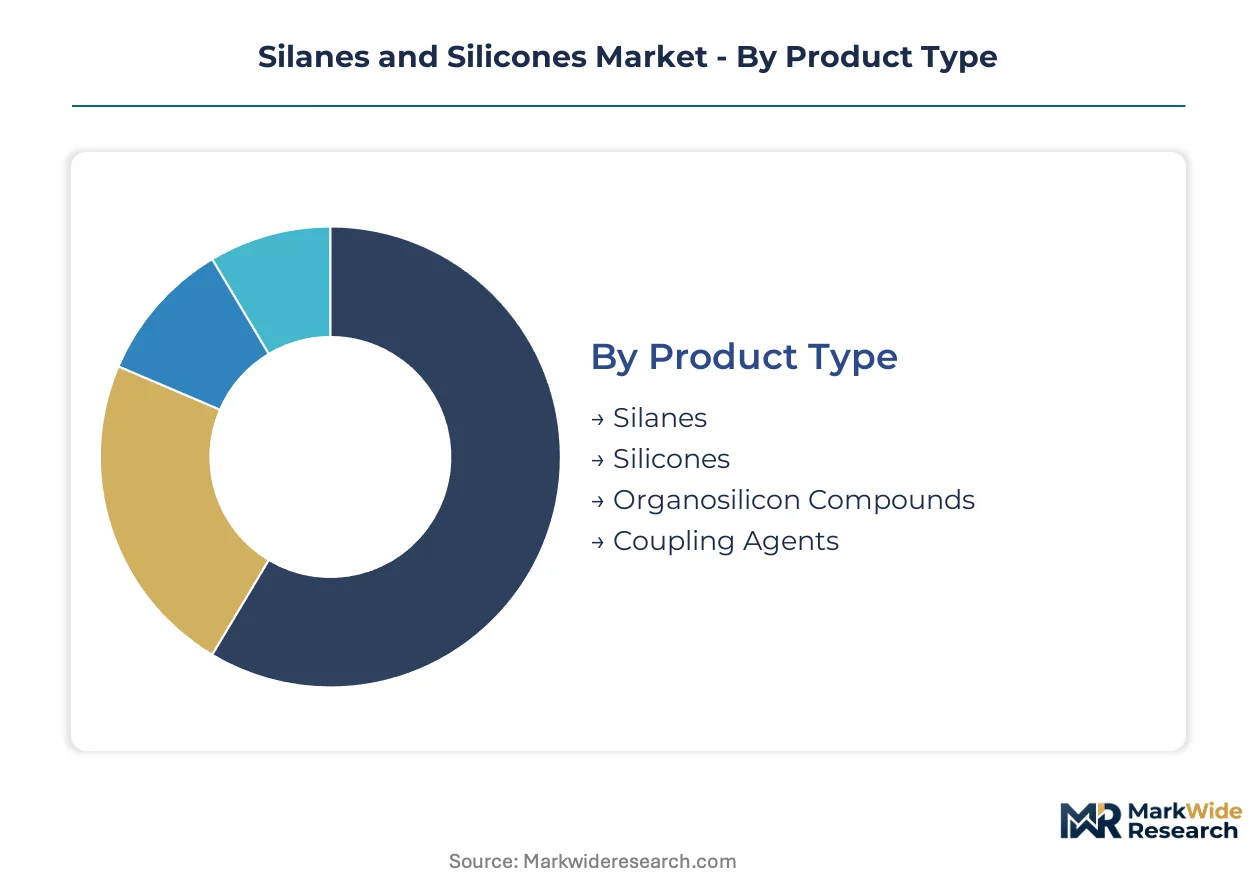
Silanes and silicones serve divergent technical specifications across product architectures, forcing suppliers to maintain parallel formulation pipelines. Segmentation discipline separates commodity chlorosilane feedstocks from specialty silicone elastomers with order-of-magnitude margin differentials.
Product Type:
Cost tier stratification distinguishes bulk organosilicon intermediates from functionalized specialty grades commanding formulation premiums.
- Silanes:Silicon-hydrogen and silicon-carbon bonded compounds function as coupling agents and surface modifiers. Electronics substrate manufacturers in Germany and Japan specify ultra-high-purity chlorosilane grades for semiconductor epitaxy, tightening impurity thresholds below 10 parts per billion.
- Silicones:Repeating siloxane backbone polymers deliver thermal stability from -60°C to 250°C. Automotive OEMs in Michigan and Stuttgart specify these for EV battery thermal interface materials as cell energy densities climb.
- Organosilicon Compounds:Intermediate monomers and oligomers bridge silane precursors to finished silicone polymers.
- Coupling Agents:Bifunctional molecules bond inorganic substrates to organic matrices in composite manufacturing.
Silicones hold installed capacity. Organosilicon compounds are rotating up the share rankings.
End Use Industry:
Application maturity varies sharply across customer verticals, with automotive electrification rewriting material specifications faster than construction or healthcare certification cycles.
- Automotive:Gasketing, sealing, and thermal management applications dominate silicone consumption. Battery pack engineers specify gap fillers and potting compounds as OEMs pursue 800-volt architectures and faster charging protocols.
- Electronics:Encapsulation, conformal coating, and dielectric insulation protect sensitive components. 5G infrastructure OEMs specify low-dielectric silicone gels for antenna sealing as network densification accelerates.
- Construction:Weatherproofing sealants and structural glazing adhesives specify high-movement-capability silicones.
- Healthcare:ISO 10993-certified liquid silicone rubber serves long-term implantable devices and drug delivery systems.
Automotive commands volume leadership. Electronics is climbing the fastest on thermal management pull-through.
Application:
Functional performance requirements dictate formulation complexity, with coatings and adhesives commanding premium specifications over commodity sealant bases.
- Coatings:Protective and decorative films leverage silicone weatherability and UV resistance. EPA volatile organic compound rules are pushing manufacturers toward solvent-free and water-based platforms, particularly in Southern California air quality districts.
- Adhesives:Structural bonding applications merge silicone flexibility with substrate-specific adhesion promoters. Tier suppliers now submit candidates for finite element analysis validation before OEM purchase order release.
- Sealants:Joint-filling formulations accommodate thermal expansion in building envelopes and transportation assemblies.
- Rubber Compounding:Silicone elastomer masterbatches feed extrusion and molding operations for automotive and industrial hoses.
Coatings hold formulation patent density. Adhesives is rotating up the share rankings.
Form:
Processing efficiency favors pumpable and sprayable delivery systems in automated manufacturing lines, disadvantaging powder handling where dust control adds cost.
- Liquid:Pumpable neat polymers and oligomers feed metering equipment in high-volume extrusion and coating operations. Automated lines in automotive seating and electronics encapsulation favor this form for precise deposition control.
- Gel:Soft, compliant materials conform to irregular geometries for thermal interface and potting applications. EV battery manufacturers specify these for cell-to-cell thermal management where compression set resistance matters.
- Powder:Solid particulate grades serve niche applications where solvent-free handling is mandatory.
- Emulsion:Water-dispersed silicones enable low-VOC coating and textile treatment formulations.
Liquid holds installed capacity. Gel is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Organosilicon monomer capacity clusters in Jiangsu and Zhejiang provinces have tilted supply-side leverage toward Chinese producers. This geographic shift forces multinational formulators to recalibrate procurement footprints and regional inventory positioning.
China
Domestic producers in Jiangsu and Zhejiang are scaling methyl chlorosilane capacity at state-backed pace. MEE emissions standards on hydrogen chloride recovery tighten compliance costs for brownfield operators. The Yangtze River Delta concentration now supplies both domestic EV battery manufacturers and export-oriented sealant compounders.
Germany
Automotive OEMs in Stuttgart and Munich specify high-purity silicone thermal interface materials for 800-volt battery architectures. ECHA REACH compliance dossiers for organosilicon imports favor established registrants with complete safety data. The Bavarian chemical corridor anchors specialty silicone compounding for semiconductor and photovoltaic customers.
United States
EPA volatile organic compound rules for adhesive and sealant categories push manufacturers toward solvent-free silicone emulsion platforms. Automotive battery pack assembly in Michigan and the Southeast pulls demand for gap fillers and potting compounds. The Gulf Coast chlorosilane complex feeds integrated silicone intermediates production.
Japan
Electronics substrate manufacturers specify ultra-high-purity chlorosilane grades for semiconductor epitaxy with impurity thresholds below ten parts per billion. METI industrial policy supports advanced materials R&D consortia. The Kanto and Kansai industrial belts concentrate silicone rubber compounding expertise for automotive and electronics customers.
India
The PLI scheme for advanced chemistry manufacturing offers tariff and tax incentives for domestic silicone emulsion and sealant production. CDSCO medical device regulations shape qualification protocols for healthcare-grade liquid silicone rubber. Maharashtra and Gujarat industrial zones attract specialty silicone localization investments.
Silanes and Silicones Market Competitive Environment
Integrated petrochemical conglomerates and specialty chemical pure-plays split the market into contrasting strategic postures. The structure tilts toward consolidation at the monomer and intermediates tier while fragmenting across formulated specialties. Three archetypes dominate: backward-integrated chlorosilane producers with captive siloxane supply, formulation specialists with deep customer application expertise, and regional compounders serving construction and automotive tiers with price-competitive catalog offerings. Capacity expansion and portfolio diversification represent the dominant competitive moves as players defend margin position against Chinese oversupply.
Within the integrated-producer tier, Dow Inc. and Wacker Chemie AG exemplify backward-integrated models with siloxane network control across multiple manufacturing geographies. Shin-Etsu Chemical Co., Ltd. occupies a position as a Japanese specialist in advanced silicone rubber compounding. These three anchors demonstrate how geographic diversification and application depth serve as defensive bulwarks against commodity cycle pressure from Chinese capacity additions.
| Leading Market Players |
|---|
| Evonik Industries AG |
| KCC Corporation |
| Dow Inc. |
| Gelest, Inc. |
| Elkem ASA |
| Wacker Chemie AG |
| Momentive Performance Materials Inc. |
| China National Bluestar Co. |
| Shin-Etsu Chemical Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Jiangsu and Zhejiang province methyl chlorosilane plants compresses utilization rates below break-even thresholds, forcing Chinese producers to prioritize volume utilization over margin preservation while European and North American incumbents retreat to premium formulation tiers.
Pricing Analysis
EU REACH substance registration dictates the pricing tier structure across import-dependent European markets, separating pre-qualified registrants with complete safety dossiers from non-compliant suppliers facing exclusion. Three-tier pricing structure across REACH-certified, transitional-grade, and spot-market material levels reflects compliance investment amortization. Cost compression in standard-grade siloxane intermediates is intensifying because Chinese state-backed capacity additions prioritize utilization over returns. Automotive OEM procurement teams exhibit lowest price sensitivity due to thermal management material qualification timelines, while construction sealant distributors face highest sensitivity as they pass through spot-indexed raw material costs.
Supply Chain Analysis
Export control regimes on semiconductor-grade chlorosilane purification technology limit technology transfer to Chinese producers, constraining their ascent into ultra-high-purity tiers despite raw material abundance. Supply concentrates in China for organosilicon monomers, Germany for specialty silicone compounding, and Japan for electronics-grade materials. The network draws from methyl chloride feedstock from methanol-chlorine chemistry, silicon metal from quartz reduction, and platinum catalyst systems for hydrosilylation. Single-source vulnerability runs through Jiangsu province concentration where environmental compliance shutdowns cascade through global availability. Distribution runs through integrated chemical distributors with technical service capabilities for formulated product qualification support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward automotive OEM material engineering departments as finite element analysis validation requirements concentrate supplier rosters among pre-qualified registrants with documented thermal performance databases.
For Market Incumbents: Harden formulation patent positions in EV battery thermal interface materials as 800-volt architectures proliferate. Deepen backward integration into methyl chlorosilane production in North American and European manufacturing sites to insulate margins from Chinese spot-price volatility. Prioritize REACH registration maintenance investment as ECHA tightens compliance thresholds for organosilicon imports. For New Entrants and Emerging Players: India's underpenetrated specialty silicone emulsion market offers tariff-protected entry through PLI scheme qualification for domestic manufacturing. Target medical-grade liquid silicone rubber production in Maharashtra and Gujarat industrial zones where CDSCO regulations create qualification barriers for unregistered imports. Pursue joint development agreements with 5G infrastructure OEMs seeking low-dielectric silicone gel suppliers for antenna sealing applications. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across semiconductor-grade chlorosilane purification assets as export controls extend equipment lead times. Five-to-ten year viability favors backward-integrated producers with captive siloxane supply and established REACH registration portfolios. Monitor methyl chloride feedstock pricing volatility as the inflection indicator for margin compression timing across standard-grade silicone intermediates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Methyl Chlorosilane | Captive supply of organosilicon monomers insulates margin from Chinese spot-price volatility. |
| REACH Registration Portfolio Expansion | Complete safety dossiers secure import share as ECHA tightens compliance thresholds. |
| Medical-Grade LSR Certification Investment | ISO 10993 certification opens long-term implantable device supply contracts in Southeast Asia. |
| Hybrid Silicone-Urethane R&D Program | Molecular-level hybridization merges silicone weatherability with polyurethane processing economics. |
| India PLI Scheme Manufacturing Localization | Domestic silicone emulsion production qualifies for tariff and tax incentives under advanced chemistry manufacturing scheme. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with silicone plant managers, automotive OEM material engineers, procurement leads at Tier 1 suppliers, and distribution channel partners; and secondary validation through customs/trade data, SEC 10-K filings, ECHA registration databases, and ACC/Cefic industry reports. Bottom-up volume modeling triangulated against top-down market sizing across product type, end-use industry, application, and form segmentation dimensions.
Forecast inputs considered EV battery thermal management material specification trends, REACH compliance threshold evolution, Chinese methyl chlorosilane capacity utilization trajectories, and 5G infrastructure deployment pace. Segmentation modeling captured grade tier, end-use industry, packaging format, and regional production hub variations. CAGRs derived from slope-log regression across the projection horizon, calibrated to disclosed capacity expansion timelines and OEM platform launch schedules.
Practitioners should monitor Chinese environmental compliance enforcement intensity, EU REACH substance list expansion, and fluoropolymer substitution rates in high-heat electronics for early signals of forecast deviation. Material shifts in methyl chloride feedstock pricing volatility or semiconductor-grade purity threshold tightening would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Croscarmellose Sodium Market
Specialty Chemicals
Metal Biocide Market
Specialty Chemicals
Taurine Market
Specialty Chemicals
Naphthol AS-IRG Market
Specialty Chemicals
Dimethyl Succinyl Succinate Market
Specialty Chemicals
Europe Squalene Market
Specialty Chemicals
High-K and CVD ALD Metal Precursors Market
Specialty Chemicals
4-Benzoylbutyric Acid Market
Specialty Chemicals
Global Mandelic Acid Market
Specialty Chemicals
Magnesium Gluconate Market
Specialty Chemicals
Bio-Ketones Market
Specialty Chemicals
South Korea Cleanroom Disposable Gloves Market
Specialty Chemicals
Fluoroethylene Carbonate (FEC) Market
Specialty Chemicals
13X Molecular Sieve Activated Powder Market
Specialty Chemicals
Cellulose Ether and Derivatives Market
Specialty Chemicals
Acetyl Isovaleryl Market