
 Cellular Vehicle-To-Everything (C-V2X) Market | 2026-2036
Cellular Vehicle-To-Everything (C-V2X) Market Size, Share, and Industry Trends Forecast 2026-2036
Cellular Vehicle-To-Everything (C-V2X) Market Analysis
Platform licensing revenue is reshaping competitive economics as chipset vendors monetize recurring software stacks alongside hardware sales. Qualcomm Technologies Inc. leverages its Snapdragon Automotive portfolio to dominate modem integration for 5G-V2X deployments. Continental AG anchors European supply relationships through its roadside unit manufacturing scale in Stuttgart and Ingolstadt. Robert Bosch GmbH competes via sensor fusion capabilities that combine C-V2X with radar and camera systems for collision avoidance.
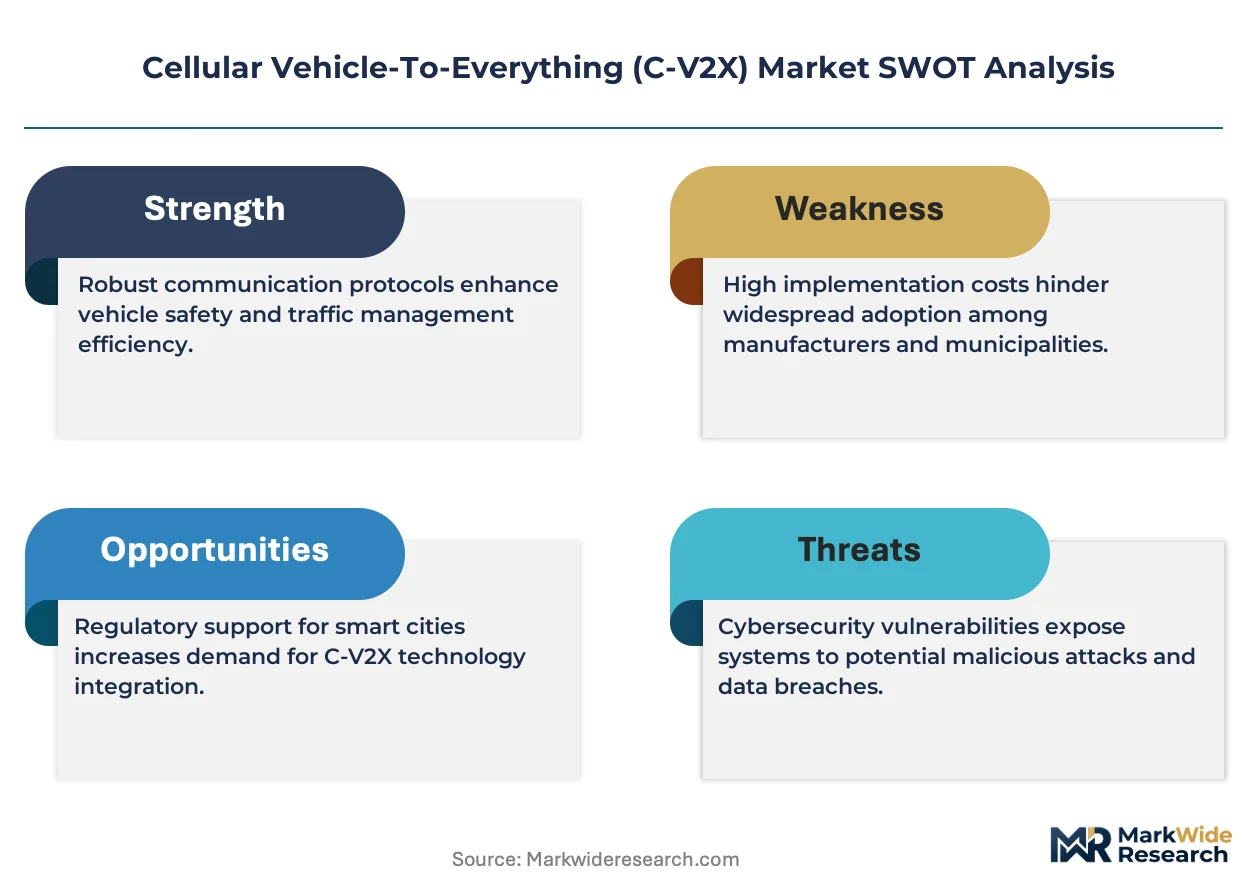
Cellular Vehicle-To-Everything technology constitutes a wireless communication framework enabling direct exchange between vehicles, infrastructure, pedestrians, and networks using cellular protocols in licensed spectrum, with LTE-V2X supporting 10-20 millisecond latency and 5G-V2X targeting sub-1 millisecond responsiveness for safety-critical messaging. Its primary commercial purpose centers on reducing traffic fatalities and enabling cooperative intelligent transport systems through real-time hazard warnings and traffic signal prioritization. Fleet management applications currently lead solution deployment as logistics operators seek fuel savings and liability reduction, while autonomous driving represents the fastest-growing application segment due to its dependency on beyond-line-of-sight perception. Roadside units concentrate margin pools because municipal procurement cycles create sticky installation contracts and multi-year maintenance obligations.
The FCC governs spectrum access and device certification for C-V2X deployments in the United States, with NHTSA mandating vehicle-to-vehicle communication capabilities in forthcoming safety rulemakings that will compel OEM integration. The EU AI Act and CE marking requirements under the Radio Equipment Directive shape product compliance trajectories for European market entry, particularly for AI-enabled autonomous driving functions. Stakeholders must monitor regulatory divergence between FCC and EU spectrum allocation approaches, as incompatible channel configurations would fragment chipset design requirements and inflate R&D duplication costs.
Market Dynamics
Platform licensing economics are compressing hardware margins as chipset vendors extract recurring revenue from software stacks, forcing OEMs to renegotiate procurement terms and accelerating consolidation among Tier-2 module suppliers.
Growth Catalysts
- FCC 5.9 GHz spectrum allocation:The Commission's channel restructuring eliminates legacy DSRC interference, enabling single-mode C-V2X chipsets that reduce BOM complexity for Detroit automakers.
- Fleet liability reduction:Commercial vehicle operators deploy vehicle-to-network systems to cut collision-related insurance premiums and satisfy shipper safety scorecard requirements.
- Pedestrian safety mandates:EU member states are incorporating C-V2X into urban mobility masterplans, with Stuttgart and Ingolstadt requiring roadside unit integration in new infrastructure bids.
Market Restraints
- Semiconductor supply concentration:Advanced modem fabrication depends on Taiwan-based foundry capacity, exposing procurement timelines to geopolitical disruption risks.
- Dual-mode hardware legacy:Early DSRC-C-V2X hybrid units inflate unit costs and complicate firmware update cycles for municipal procurement departments.
- Spectrum fragmentation:Divergent FCC and EU channel configurations force chipset vendors to maintain parallel silicon designs, inflating R&D overhead without volume scaling benefits.
Strategic Opportunities
- India PLI scheme extension:The production-linked incentive framework for automotive electronics creates localized manufacturing capacity for export to Southeast Asian markets.
- 5G-V2X sensor fusion:Integration with radar and camera systems enables sub-1 millisecond hazard response for autonomous shuttle deployments in German manufacturing corridors.
- Subscription-based roadside unit maintenance:Municipalities are shifting from capital procurement to multi-year service contracts, locking in recurring revenue for infrastructure vendors.
Industry Challenges
- V2X cybersecurity certification:UN R155 vehicle cybersecurity regulations impose 18-24 month validation timelines that delay platform launches.
- Cross-border interoperability testing:OEMs must replicate certification protocols across FCC, CE marking, and MIIT regimes, fragmenting engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cellular Vehicle-To-Everything (C-V2X) Market |
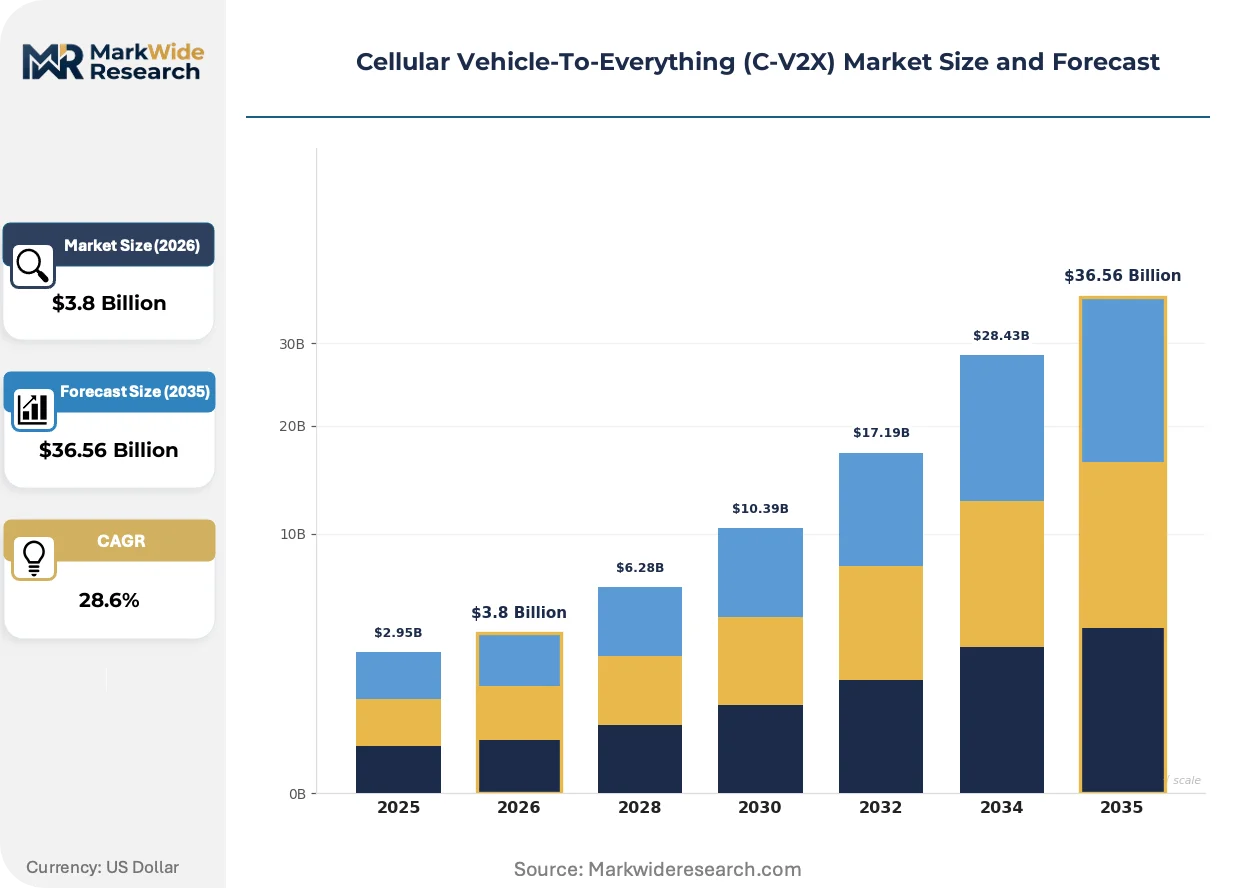
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $36.56 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Traffic Management, Collision Avoidance, Autonomous Driving, Fleet Management Technology: LTE-V2X, 5G-V2X, DSRC, C-V2X End User: OEMs, Fleet Operators, Local Governments, Insurance Companies Solution: Vehicle Communication Systems, Roadside Units, Backend Infrastructure, Data Analytics |
| Companies Covered | Qualcomm Technologies Inc., Autotalks Ltd., Continental AG, Robert Bosch GmbH, Huawei Technologies Co., Ltd., NXP Semiconductors, Intel Corporation, Nokia Corporation, Infineon Technologies AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cellular Vehicle-To-Everything (C-V2X) Market Emerging Trajectories
Edge computing architectures are displacing centralized traffic management, enabling real-time hazard processing at roadside units rather than cloud relays. This shift compresses latency budgets and rewires supplier relationships toward compute-module vendors.
5G-V2X sidelink communication is digitizing direct vehicle-to-vehicle messaging without network infrastructure dependency. German automakers are integrating this capability into 2026 model year platforms for highway platooning applications. The technology is digitizing cooperative perception architectures, allowing trucks to share sensor data beyond line-of-sight.
NHTSA's forthcoming V2V communication mandate is compelling OEMs to pre-certify modem modules ahead of rule finalization. The proposed rule would phase in vehicle-to-vehicle capabilities across light-duty fleets, with compliance timelines tied to model year cycles. Passenger vehicle segments face the steepest engineering compression as they retrofit existing electrical architectures.
Logistics operators are consolidating procurement authority at fleet headquarters rather than regional depots, centralizing vendor negotiations and standardizing hardware specifications across North American operations. This concentration is shifting margin capture toward direct OEM relationships and away from distribution intermediaries. The pattern is most visible in long-haul trucking segments where fuel efficiency and liability exposure dominate capital allocation decisions.
Cellular Vehicle-To-Everything (C-V2X) Market Segmentation
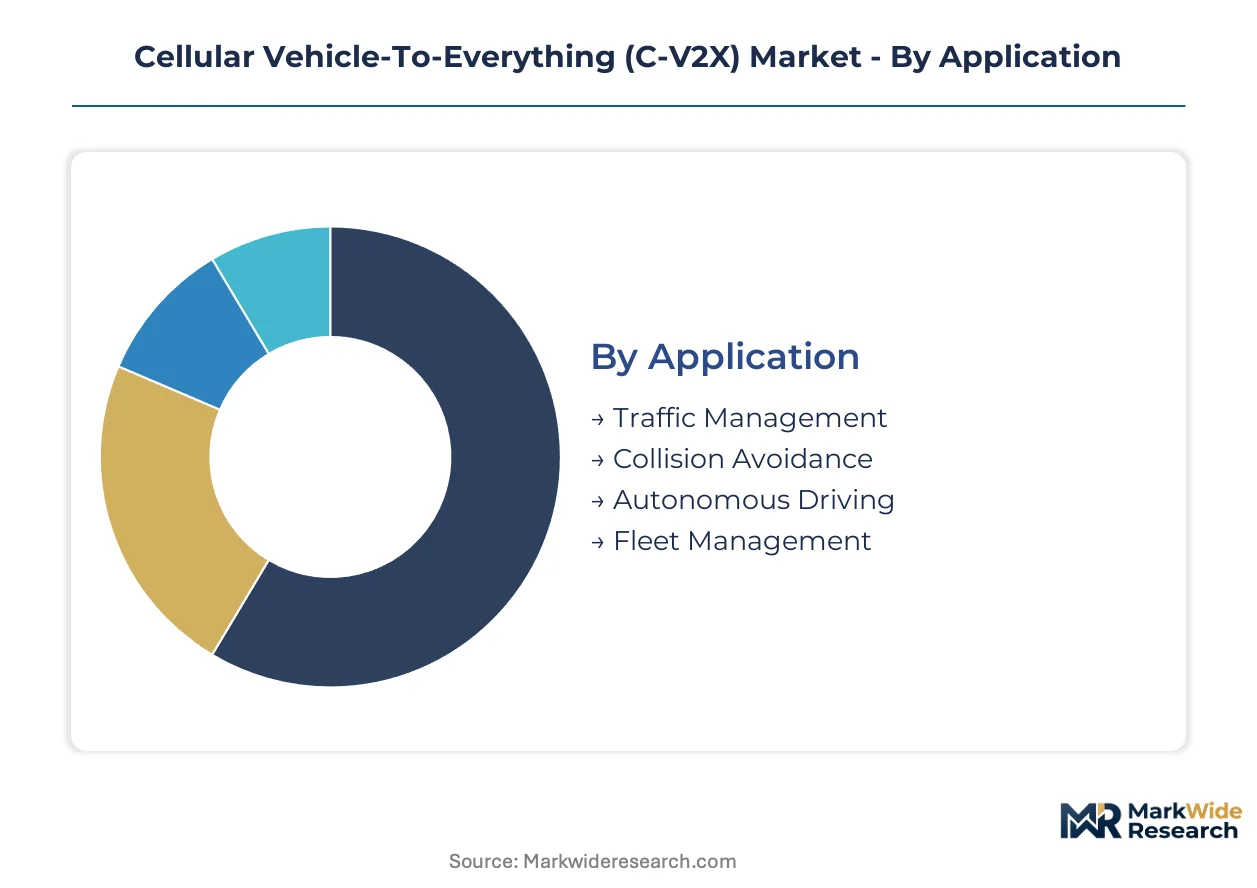
C-V2X market segmentation reveals distinct procurement patterns across application types and technology generations. Each dimension carries specific margin structures and regulatory dependencies that shape vendor positioning.
Application:
Application segmentation captures how end-use requirements vary by latency tolerance, safety criticality, and infrastructure dependency.
- Traffic Management:Municipal signal prioritization and congestion routing systems operate at 100-300 millisecond latency thresholds. German cities including Stuttgart and Ingolstadt mandate roadside unit integration in new infrastructure procurement.
- Autonomous Driving:Beyond-line-of-sight perception and cooperative maneuvering demand sub-1 millisecond responsiveness. This segment is gaining share fastest as OEMs integrate 5G-V2X modems into production platforms for highway platooning.
- Collision Avoidance:Direct vehicle-to-vehicle hazard warnings using LTE-V2X protocols target intersection and blind-spot scenarios.
- Fleet Management:Logistics operators deploy vehicle-to-network systems for route optimization and fuel consumption monitoring across North American long-haul corridors.
Fleet Management holds installed capacity. Autonomous Driving is rotating up the share rankings.
Technology:
Technology segmentation reflects the transition from legacy radio protocols to cellular-based architectures and their coexistence requirements.
- 5G-V2X:NR sidelink enables direct device-to-device communication without network infrastructure dependency. Qualcomm Snapdragon Automotive platforms dominate modem integration for Detroit automakers targeting 2026 model year compliance.
- LTE-V2X:PC5 interface supports 10-20 millisecond latency for basic safety messaging. This technology anchors current municipal deployments where infrastructure upgrade cycles extend across multiple budget years.
- DSRC:IEEE 802.11p-based systems face phase-out pressure following FCC spectrum reallocation decisions.
- C-V2X:Umbrella term encompassing both LTE-V2X and 5G-V2X variants under 3GPP standards.
LTE-V2X holds installed capacity. 5G-V2X is rotating up the share rankings.
End User:
End user segmentation distinguishes between vehicle-integrated procurement and infrastructure-side purchasing authorities.
- OEMs:Automakers integrate modem modules during electrical architecture design phases. NHTSA's forthcoming V2V mandate compels pre-certification timelines tied to model year cycles.
- Fleet Operators:Commercial vehicle buyers centralize procurement decisions at headquarters to standardize specifications across regional depots.
- Local Governments:Municipal transportation departments procure roadside units through multi-year maintenance contracts rather than capital expenditure programs.
- Insurance Companies:Liability underwriters sponsor telematics deployments to reduce collision-related premium exposure.
OEMs hold installed capacity. Fleet Operators is rotating up the share rankings.
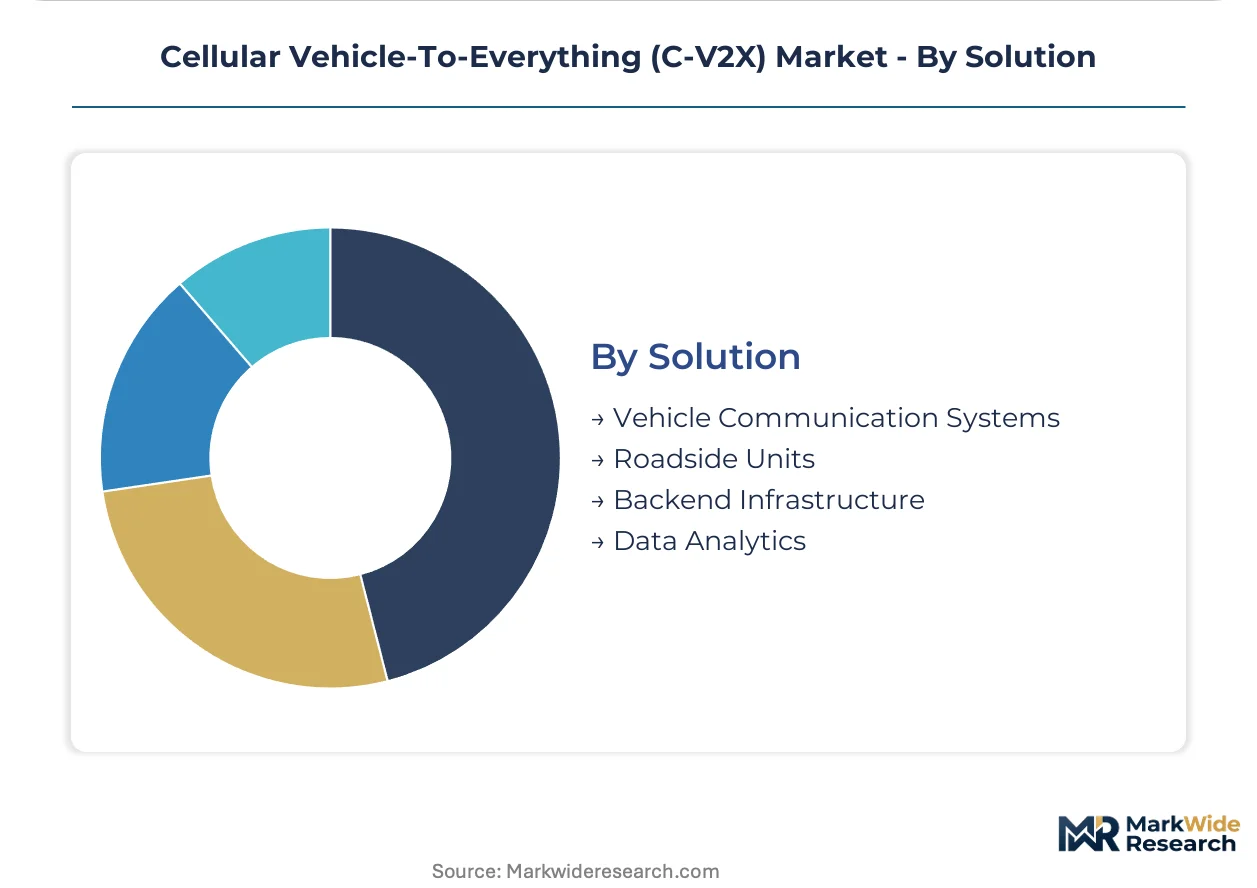
Solution:
Solution segmentation separates hardware components from software and service layers with divergent margin profiles.
- Roadside Units:Infrastructure-mounted communication devices concentrate margin pools through sticky municipal installation contracts. Continental AG manufacturing scale in Stuttgart and Ingolstadt anchors European supply relationships.
- Vehicle Communication Systems:Onboard units combine cellular modems with antenna arrays and processing modules. Platform licensing economics compress hardware margins as chipset vendors extract recurring software revenue.
- Backend Infrastructure:Cloud-based traffic management and certificate provisioning systems support network-dependent applications.
- Data Analytics:Subscription services processing V2X message streams for fleet optimization and predictive maintenance.
Roadside Units hold installed capacity. Vehicle Communication Systems is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fleet operators in Germany absorb premium pricing for integrated C-V2X systems without volume elasticity, while municipal buyers in India and Brazil remain acutely price-sensitive on roadside unit procurement. This demand bifurcation shapes vendor pricing architectures and localization strategies across markets.
United States
Detroit automakers drive modem integration for 2026 model year compliance ahead of anticipated NHTSA mandates. FCC spectrum reallocation at 5.9 GHz eliminates DSRC interference, enabling single-mode chipset designs. Testing corridors in Michigan and Arizona concentrate validation partnerships between OEMs and infrastructure vendors.
Germany
Tier-1 suppliers embed C-V2X modules directly into production lines across Stuttgart and Ingolstadt manufacturing clusters. EU AI Act compliance requirements extend certification timelines for autonomous driving functions. The KBA oversees type approval for V2X cybersecurity under UN R155 protocols.
China
MIIT governs spectrum allocation and device certification for cellular vehicle communication systems. MIIT channel configurations diverge from FCC and EU standards, forcing parallel silicon design tracks. Yangtze River Delta automotive electronics clusters absorb domestic chipset production for fleet management deployments.
India
Production-linked incentive schemes for automotive electronics attract module assembly investment targeting Southeast Asian export markets. TRAI consultations on intelligent transport spectrum remain pending. Tamil Nadu and Gujarat manufacturing corridors host pilot roadside unit installations for port logistics automation.
Japan
METI coordinates cross-ministry standards alignment for 5G-V2X deployment in dense urban corridors. Kanto region OEMs integrate sensor fusion architectures combining cellular communication with radar systems. Nagoya manufacturing belt concentrates Tier-1 supplier engineering resources for highway platooning applications.
Cellular Vehicle-To-Everything (C-V2X) Market Vendor Landscape
Capability concentration sits with semiconductor designers possessing modem integration expertise; scale advantage sits with automotive Tier-1 suppliers controlling manufacturing throughput. The structure bifurcates between chipset vendors extracting platform licensing revenue and infrastructure specialists capturing municipal installation contracts. Three archetypes dominate: cellular modem specialists, automotive electronics integrators, and roadside unit fabricators. Competitive moves center on sensor fusion partnerships and multi-year municipal maintenance contract capture.
Among modem specialists, Qualcomm Technologies Inc. and Huawei Technologies Co., Ltd. occupy positions at opposite ends of geographic market access, with each representing distinct regulatory compliance pathways. Continental AG exemplifies the Tier-1 integrator archetype through its European manufacturing scale. These three anchors illustrate how competitive positioning fragments across technology licensing, automotive supply relationships, and infrastructure procurement channels.
| Leading Market Players |
|---|
| Qualcomm Technologies Inc. |
| Autotalks Ltd. |
| Continental AG |
| Robert Bosch GmbH |
| Huawei Technologies Co., Ltd. |
| NXP Semiconductors |
| Intel Corporation |
| Nokia Corporation |
| Infineon Technologies AG |
| Others |
Supply Flow & Price Mechanics
The Yangtze River Delta automotive electronics corridor feeds cost dynamics through Taiwan-based foundry pricing into downstream tiering across OEM, fleet, and municipal buyer archetypes. Semiconductor wafer costs and 5G modem licensing fees concentrate margin pressure at chipset vendors, forcing three-tier pricing stratification across premium safety-critical modules, standard fleet management units, and economy-grade roadside hardware.
Pricing Analysis
Extended software maintenance contracts and multi-year roadside unit service agreements drive lifetime value capture for infrastructure vendors. Three-tier pricing structure across premium, standard, and economy levels separates autonomous-grade sensor fusion modules from basic LTE-V2X fleet trackers and entry-level DSRC-transition hardware. Cost compression in standard-tier vehicle communication systems is intensifying because Qualcomm's Snapdragon licensing economics squeeze Tier-2 module suppliers. Fleet operators in North America show least price sensitivity due to liability reduction ROI, while Indian municipal buyers exhibit acute elasticity on roadside unit procurement.
Supply Chain Analysis
Advanced modem silicon draws from Taiwan, South Korea, and USA fabrication capacity, with 5G-V2X chipsets resting on EUV lithography nodes and automotive-grade substrate materials. GaAs power amplifiers, ceramic antenna substrates, and precision RF filters anchor bill-of-material dependencies. Single-source vulnerability concentrates at Taiwan-based foundry operations exposed to geopolitical disruption. Distribution runs through Tier-1 automotive electronics integrators controlling OEM qualification pathways and direct municipal procurement channels for roadside infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet operator procurement consolidation at North American headquarters has shifted buyer power toward direct OEM relationships, fragmenting distribution intermediary margins. This concentration pattern favors vendors with captive manufacturing scale and multi-year service contract capabilities.
For Market Incumbents: Build switching-cost moats through embedded roadside unit maintenance subscriptions that lock municipalities into decade-long renewal cycles. Deepen sensor fusion partnerships with radar and camera suppliers to defend against pure-play modem specialists. Add certification capacity in Germany under UN R155 protocols to preempt regulatory fragmentation risks. For New Entrants and Emerging Players: Mid-market fleet operators in Southeast Asia represent the most penetrable entry point given India's PLI scheme extension and underdeveloped local module assembly. Target subscription-based data analytics for logistics optimization as the go-to-market angle, bypassing capital-intensive hardware manufacturing. For Investors and Strategic Acquirers: Roadside unit fabricators with sticky municipal installation contracts and multi-year maintenance obligations offer the strongest acquisition profile for infrastructure roll-out exposure. Monitor FCC-EU spectrum alignment negotiations as the inflection signal; incompatible channel configurations would fragment chipset design requirements and inflate R&D duplication costs across portfolio companies.| Strategic Initiative | Industry Significance |
|---|---|
| 5G-V2X Modem Integration Partnership | Qualcomm Snapdragon platforms anchor Detroit automaker compliance timelines for NHTSA mandates. |
| Roadside Unit Maintenance Subscription | Continental AG locks recurring revenue through Stuttgart municipal infrastructure contracts. |
| Sensor Fusion Architecture Development | Robert Bosch GmbH combines C-V2X with radar systems for sub-1 millisecond hazard response. |
| India PLI Manufacturing Localization | Tamil Nadu corridor assembly targets Southeast Asian export markets with cost-advantaged modules. |
| UN R155 Cybersecurity Certification | KBA type approval extends product launch timelines but creates regulatory barrier for competitors. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with OEM platform engineers, Tier-1 supplier procurement leads, municipal transportation department officials, and fleet operations directors. Secondary validation drew from FCC spectrum allocation filings, NHTSA rulemaking dockets, EU AI Act implementation guidance, MIIT device certification records, and automotive production databases. Bottom-up unit deployment estimates triangulated against top-down market sizing across technology generation and application segments.
Calibration anchored installed base projections to OEM model year cycles and municipal budget appropriation timelines across the analysis window. Segmentation dimensions modeled include technology generation (LTE-V2X, 5G-V2X), application type (fleet management, autonomous driving, collision avoidance, traffic management), end-user procurement authority (OEM, fleet operator, local government), and regional regulatory cluster. CAGRs derived from S-curve adoption modeling for connected vehicle penetration and infrastructure deployment rates, with cross-checks against semiconductor foundry capacity expansion announcements and automotive electronics content forecasts.
Macroeconomic conditions sit as an overlay; deviation in semiconductor capital expenditure cycles, automotive production volumes, or municipal infrastructure spending would shift the trajectory. Forecasts reflect assumptions regarding regulatory mandate timing, spectrum allocation stability, and foundry capacity availability. Cross-checking against IHS Markit vehicle registration data and FCC equipment authorization databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Transportation Solutions
Mobility As a Service Market
Smart Transportation Solutions
Global IoT in Transportation Market
Smart Transportation Solutions
Europe Car Parking Market
Smart Transportation Solutions
Big Data Analytics in Transportation Market
Smart Transportation Solutions
Rail Internet of Things (IoT) Market
Smart Transportation Solutions
Traffic Management System Market
Smart Transportation Solutions
US Smart Highway Market
Smart Transportation Solutions
Europe Smart Transportation Market
Smart Transportation Solutions
Autonomous Warehouse Charging Infrastructure Market
Smart Transportation Solutions
Parking Finder Apps Market
Smart Transportation Solutions
Electric Kick Scooters Market
Smart Transportation Solutions
Global Ridesharing Market
Smart Transportation Solutions
Automated Parking Systems Market
Smart Transportation Solutions
Personal Transporter Market
Smart Transportation Solutions
Traffic Signal Controller Market
Smart Transportation Solutions
Thailand Ride Hailing Market