
 US Smart Highway Market | 2026-2036
US Smart Highway Market Size, Share, and Industry Trends Forecast 2026-2036
US Smart Highway Market Insights
The Infrastructure Investment and Jobs Act is broadening the cost-of-entry calculus for smart highway vendors by mandating interoperable connected-vehicle standards and dedicated funding pools. Cisco Systems, Inc. leverages its networking backbone to dominate roadside unit deployments across multiple state pilot zones. IBM Corporation sustains competitive position through AI-powered traffic analytics platforms that integrate with legacy DOT systems. Siemens anchors its presence with hardware-software bundles for adaptive signal control.
Smart highways integrate IoT sensors, edge computing nodes, and fiber-optic communication backbones to enable real-time vehicle-to-infrastructure data exchange, with typical roadside units operating on sub-50-millisecond latency thresholds to support collision avoidance and signal preemption. The primary commercial purpose centers on optimizing throughput while reducing fatalities through predictive hazard detection. IoT Sensors and Vehicle-to-Infrastructure technologies command the deepest margin pools due to specialized component requirements and installation complexity. Deployment in Urban Areas leads absolute spending as municipalities retrofit existing corridors, while Toll Booths represent the fastest-growing segment as all-electronic tolling mandates eliminate cash collection infrastructure.
The Federal Highway Administration, NHTSA, and FCC collectively shape market access by setting DSRC and C-V2X spectrum rules, vehicle safety performance benchmarks, and infrastructure grant eligibility criteria that determine which vendors qualify for federal co-funding. State DOTs must align procurement with these overlapping standards, creating compliance layers that favor established suppliers with dedicated regulatory affairs teams. Stakeholders should monitor pending FCC rulings on 5.9 GHz spectrum reallocation, as these decisions will determine technology refresh cycles and stranded asset risk across installed roadside communication hardware.
Market Dynamics
The Infrastructure Investment and Jobs Act is reshaping vendor economics by mandating interoperable connected-vehicle standards and creating dedicated funding pools that favor suppliers with proven DOT integration capabilities.
Growth Catalysts
- Federal Infrastructure Investment and Jobs Act:The legislation allocates dedicated funding pools for digital road infrastructure, accelerating state DOT procurement cycles for intelligent corridor systems.
- California congestion pricing mandates:Urban toll-road modernization programs in Los Angeles and San Francisco Bay Area corridors are driving intensive deployment of vehicle-to-infrastructure communication nodes.
- Edge computing latency thresholds:Sub-50-millisecond roadside unit performance requirements are pulling fiber-optic backbone upgrades and distributed computing hardware into highway rights-of-way.
Market Restraints
- DSRC-C-V2X spectrum uncertainty:Pending FCC rulings on 5.9 GHz reallocation create stranded asset risk for installed roadside communication hardware and compress technology refresh planning horizons.
- Specialized component supply concentration:IoT sensor and edge computing node manufacturing concentrates among limited semiconductor fabrication facilities, exposing deployment timelines to input volatility.
- Legacy DOT system integration friction:State transportation departments operate heterogeneous traffic management platforms that resist standardized API connectivity, extending implementation cycles.
Strategic Opportunities
- Texas toll corridor expansion:The state's all-electronic tolling mandate eliminates cash collection infrastructure, creating replacement demand for integrated payment and vehicle identification systems.
- AI-powered predictive maintenance:Machine learning analytics platforms are converging with IoT sensor networks to enable condition-based highway asset management, opening recurring software revenue streams.
- Florida hurricane resilience programs:State emergency management priorities are channeling funds toward intelligent evacuation routing and real-time flood monitoring along coastal highway corridors.
Industry Challenges
- Cyber-physical systems engineering talent scarcity:The intersection of civil infrastructure, wireless communications, and real-time software development demands skill sets that remain concentrated in defense and aerospace sectors.
- Multi-agency certification complexity:Federal Highway Administration safety benchmarks, NHTSA vehicle performance standards, and FCC spectrum compliance create overlapping approval timelines that extend vendor qualification periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Smart Highway Market |
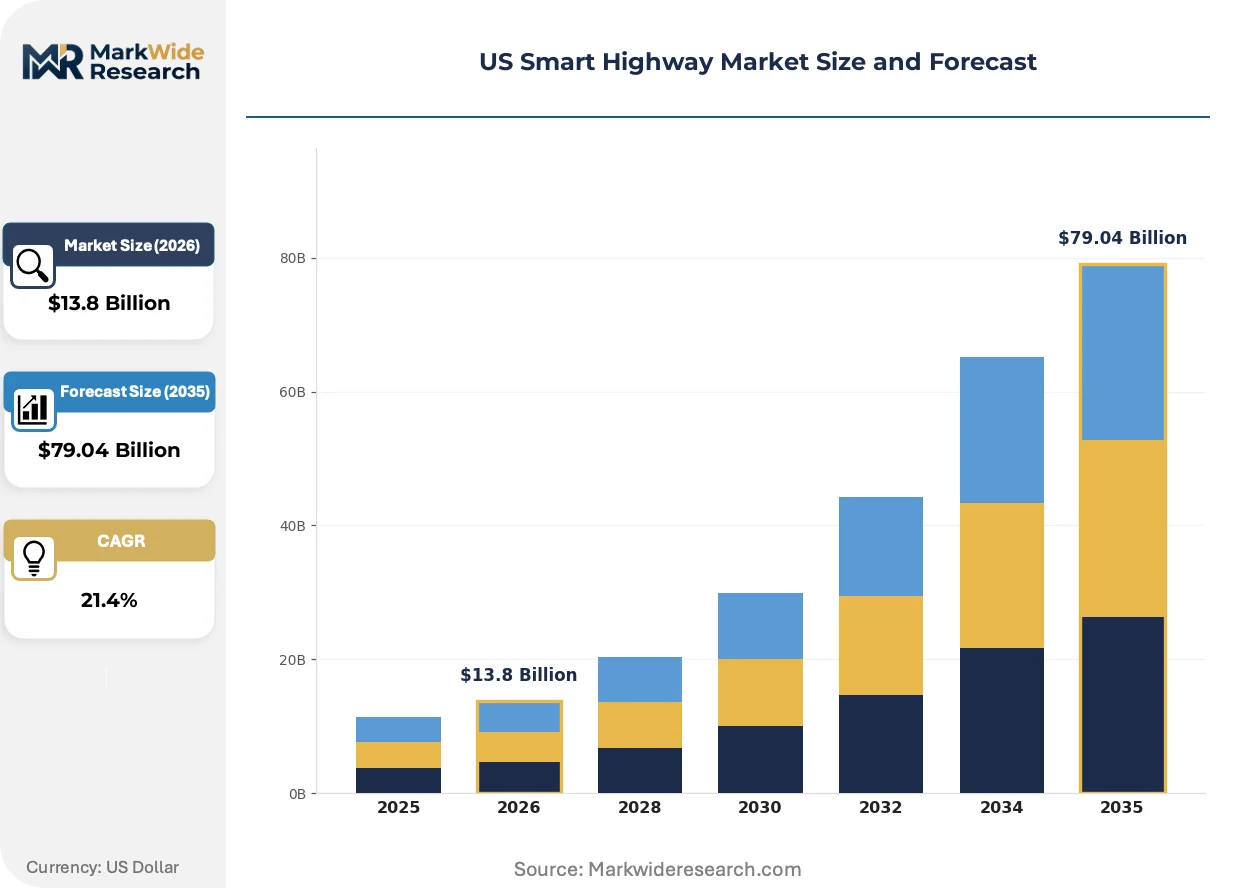
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $79.04 Billion |
| CAGR (2026 – 2036) | 21.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: IoT Sensors, Smart Traffic Signals, Vehicle-to-Infrastructure, Connected Vehicles Deployment: Urban Areas, Highways, Toll Booths, Rest Areas Application: Traffic Management, Road Safety, Environmental Monitoring, Smart Parking End User: Government Agencies, Transportation Authorities, Contractors, Automotive Manufacturers |
| Companies Covered | Cisco Systems, Inc., IBM Corporation, Siemens, Kapsch TrafficCom AG, Infineon Technologies AG, Indra, Schneider Electric, Iteris, Inc., Cubic Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Smart Highway Market Trends and Innovations
Real-time vehicle-to-infrastructure data exchange is becoming the default architecture for highway operations, compressing the window between sensor deployment and actionable traffic management intervention.
Edge computing nodes are integrating distributed processing capabilities directly into roadside unit enclosures, eliminating round-trip latency to centralized data centers. State DOTs in Texas and Florida are deploying these systems at scale along priority freight corridors. The technology is integrating collision avoidance algorithms with adaptive signal control, enabling sub-100-millisecond hazard response that legacy centralized architectures cannot match.
NHTSA and FCC coordinated rulemaking on C-V2X spectrum allocation is forcing hardware refresh cycles across installed DSRC infrastructure. Equipment vendors must maintain dual-protocol compatibility through the transition period, inflating engineering overhead. California transportation agencies are most exposed due to early DSRC pilot investments in Los Angeles and San Francisco Bay Area corridors.
Performance-based service contracts are displacing capital-heavy equipment purchases as the dominant procurement model among municipal transportation departments. Texas DOT and Florida Turnpike Enterprise are leading this shift, contracting for guaranteed throughput improvements and fatality reduction metrics rather than hardware specifications. The model concentrates vendor risk but extends contract durations and creates recurring revenue visibility.
US Smart Highway Market Segmentation
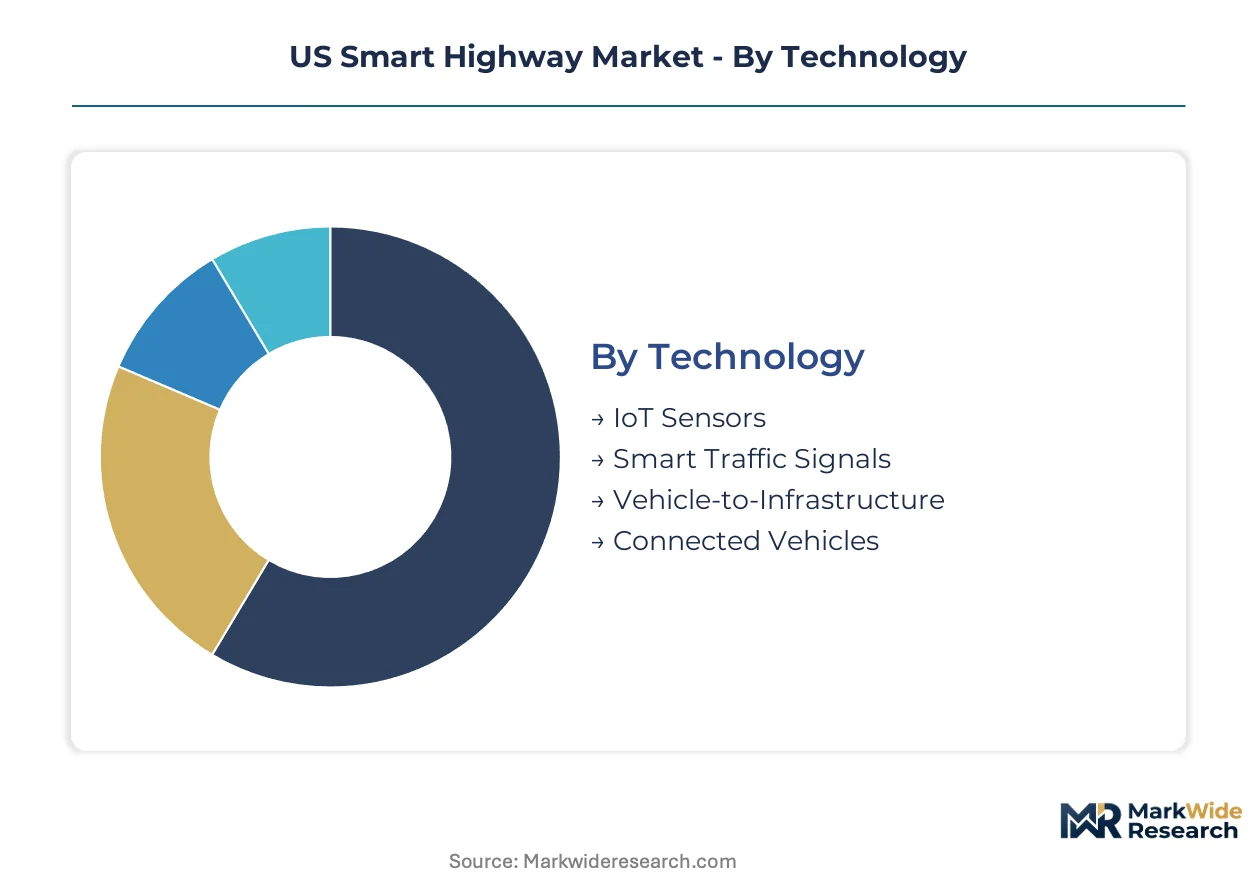
Technology deployment patterns across US smart highway infrastructure follow distinct procurement rhythms. Federal funding eligibility criteria and state DOT technical specifications fragment vendor addressable markets along capability and integration axes.
Technology:
Technical performance specifications determine hardware refresh cycles and interoperability compliance burdens across installed infrastructure bases.
- IoT Sensors:Fiber-optic and wireless sensor arrays embedded in pavement and bridge structures monitor load stress, surface temperature, and traffic density. California DOT and Texas DOT procurement concentrates demand for multi-parameter environmental sensing nodes that withstand freeze-thaw cycling and salt corrosion.
- Vehicle-to-Infrastructure:DSRC and C-V2X roadside units enable sub-50-millisecond latency vehicle communication for collision avoidance and signal preemption. Pending FCC spectrum rulings compress planning horizons for state transportation departments weighing protocol commitments.
- Smart Traffic Signals:Adaptive signal control systems adjust timing based on real-time queue detection and priority vehicle identification.
- Connected Vehicles:Onboard units and aftermarket devices that interface with roadside infrastructure for navigation and safety alerts.
IoT Sensors lead on scale; Vehicle-to-Infrastructure leads on momentum.
Deployment:
Right-of-way characteristics and traffic density shape equipment specification requirements and installation cost structures.
- Urban Areas:Dense intersection networks and mixed-mode traffic demand granular signal coordination and pedestrian detection integration. Los Angeles and San Francisco Bay Area corridors drive intensive retrofit spending as municipalities modernize legacy corridor systems.
- Toll Booths:All-electronic tolling mandates eliminate cash collection infrastructure, creating replacement demand for integrated payment and vehicle identification systems. Texas and Florida turnpike authorities accelerate deployment timelines.
- Highways:Long-distance freight corridors prioritize weather monitoring and truck-specific routing optimization.
- Rest Areas:Limited deployment scope centers on traveler information systems and electric vehicle charging coordination.
Urban Areas dominate installed base; Toll Booths climb the fastest.
Application:
Functional use cases determine software architecture requirements and data integration complexity with legacy transportation management platforms.
- Traffic Management:Centralized platforms aggregate sensor feeds and execute signal timing algorithms to optimize corridor throughput. State DOTs in California and Texas contract for guaranteed congestion reduction metrics rather than equipment specifications.
- Road Safety:Predictive hazard detection and automated incident response systems target fatality reduction mandates. Florida hurricane resilience programs channel funds toward intelligent evacuation routing along coastal corridors.
- Environmental Monitoring:Air quality and noise sensors support regulatory compliance reporting for transportation emissions.
- Smart Parking:Curb availability detection and dynamic pricing integration address urban delivery and passenger pickup demand.
Traffic Management leads on scale; Road Safety leads on momentum.
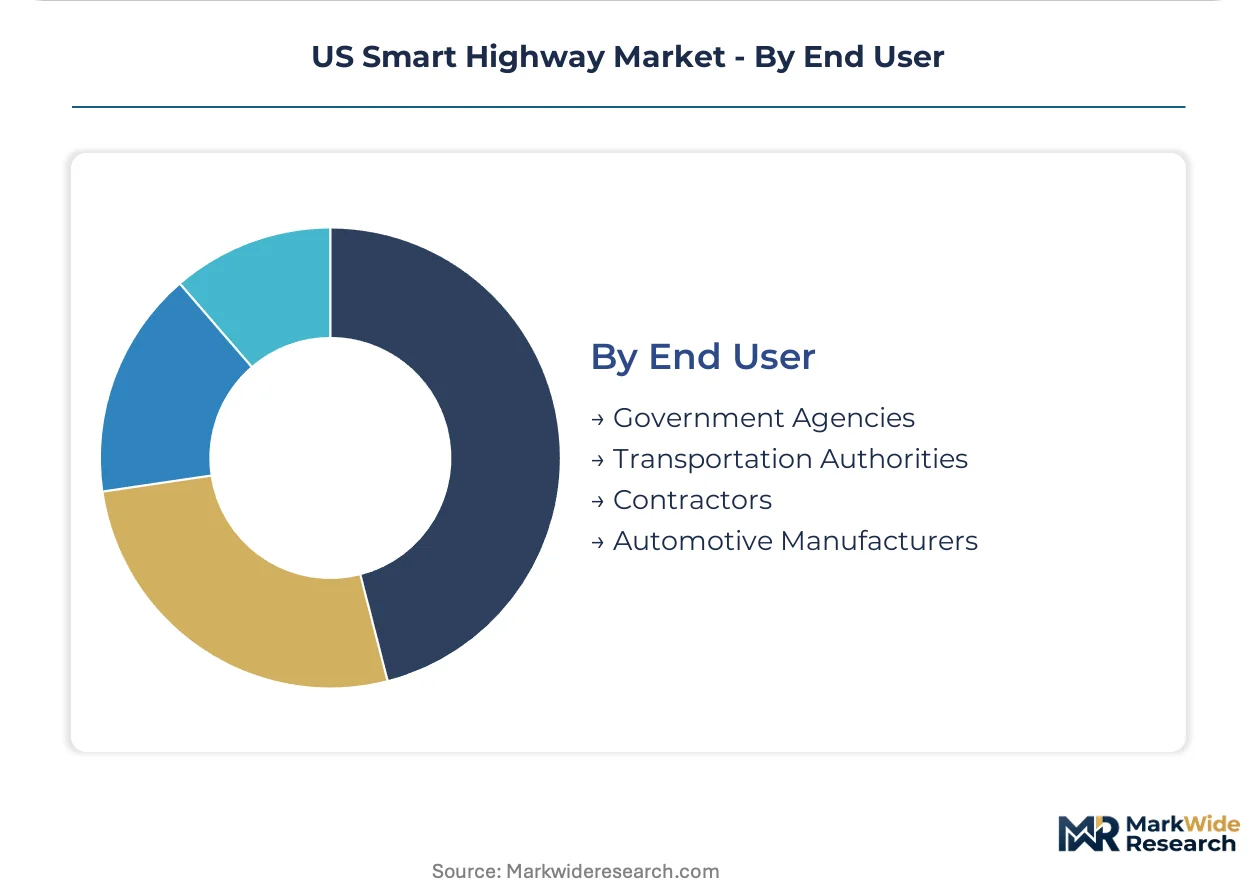
End User:
Procurement authority and funding source fragmentation create distinct sales cycle patterns and technical qualification requirements.
- Government Agencies:Federal Highway Administration and state DOTs control capital allocation through competitive grant programs and formula funding distributions. Infrastructure Investment and Jobs Act eligibility criteria favor vendors with proven interoperability certifications.
- Transportation Authorities:Turnpike enterprises and regional mobility agencies operate with dedicated revenue streams that accelerate procurement decisions. Texas and Florida authorities pioneer performance-based service contracts.
- Contractors:Design-build firms and systems integrators intermediate between equipment vendors and public agency specifications.
- Automotive Manufacturers:OEMs invest in onboard unit development and pilot fleet deployments to validate V2X protocol performance.
Government Agencies lead on scale; Transportation Authorities lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Transportation engineering talent clusters in California, Texas, and Florida anchor smart highway deployment velocity. State DOT procurement teams in these regions accelerate intelligent corridor investments ahead of federal funding windows.
California
Los Angeles and San Francisco Bay Area congestion pricing mandates drive intensive vehicle-to-infrastructure node deployment. The California Department of Transportation aligns procurement with NHTSA safety benchmarks and FCC spectrum rules. Silicon Valley technology corridors integrate edge computing roadside units along Interstate 280 and Highway 101 freight routes.
Texas
All-electronic tolling mandates eliminate cash collection infrastructure across turnpike networks. Texas DOT channels Infrastructure Investment and Jobs Act funds toward integrated payment systems and adaptive signal control. Houston and Dallas-Fort Worth metroplexes deploy fiber-optic backbones along priority freight corridors.
Florida
Hurricane resilience programs channel emergency management funds toward intelligent evacuation routing systems. Florida Turnpike Enterprise contracts for performance-based throughput guarantees rather than equipment specifications. Miami and Tampa Bay coastal corridors install real-time flood monitoring sensors along evacuation routes.
Illinois and Michigan
Midwest freight corridor modernization targets truck-specific routing optimization and weather monitoring infrastructure. Illinois DOT and Michigan DOT coordinate with the Federal Highway Administration on DSRC-C-V2X protocol transition planning. Chicago and Detroit industrial belts test connected vehicle pilot zones along interstate freight arteries.
Washington and Oregon
Pacific Northwest states prioritize environmental monitoring integration with traffic management platforms. Washington State DOT deploys air quality sensors along Interstate 5 corridors to support emissions compliance reporting. Seattle and Portland urban cores retrofit legacy signal systems with pedestrian detection and multimodal coordination capabilities.
US Smart Highway Market Competitive Landscape
The competitive structure tilts toward networking and industrial automation conglomerates with established DOT integration capabilities. Established suppliers with dedicated regulatory affairs teams capture federal co-funding eligibility advantages. Three archetypes dominate: telecommunications infrastructure providers, industrial control system manufacturers, and traffic management software specialists. Strategic partnerships and portfolio diversification into edge computing hardware represent the dominant competitive moves.
Among networking and IT infrastructure providers, Cisco Systems, Inc. and IBM Corporation occupy positions shaped by federal interoperability mandates. Siemens anchors the industrial control tier with hardware-software bundles for adaptive signal systems. These three exemplify how vendors with proven DOT system integration capabilities capture Infrastructure Investment and Jobs Act funding pools.
| Leading Market Players |
|---|
| Cisco Systems, Inc. |
| IBM Corporation |
| Siemens |
| Kapsch TrafficCom AG |
| Infineon Technologies AG |
| Indra |
| Schneider Electric |
| Iteris, Inc. |
| Cubic Corporation |
| Others |
Pricing and Supply Chain Analysis
Fiber-optic cable pricing indices and semiconductor wafer costs cascade through smart highway equipment tiers, compressing margins on standardized roadside units while preserving premium pricing for integrated edge-computing bundles with sub-50-millisecond latency guarantees.
Pricing Analysis
The bundled-versus-unbundled service split defines vendor economics. Hardware-only roadside unit sales face commodity pressure as Chinese and Taiwanese component suppliers expand capacity, while integrated software-hardware-service contracts command 40-60% lifetime value premiums through guaranteed throughput and uptime SLAs. Price differentiation hinges on FCC certification tier and NHTSA safety validation depth, with California DOT and Texas Turnpike Enterprise showing lowest sensitivity due to federal co-funding eligibility requirements. Cost compression in sensor arrays is intensifying because foundry capacity expansion outpaces specialized edge-computing node supply.
Supply Chain Analysis
Edge-computing hardware supply rests on Taiwanese semiconductor fabrication, South Korean memory module production, and Chinese printed circuit board assembly. Critical inputs span silicon wafers, gallium nitride RF components, and precision optical transceivers. Single-source vulnerability concentrates in 5G modem chipsets from Qualcomm and MediaTek, where geopolitical export restrictions threaten deployment timelines. Distribution runs through Tier 1 systems integrators like Cubic and Kapsch TrafficCom that bundle hardware with installation and maintenance services for state DOT procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart highway deployment offers geographic-arbitrage returns: Texas and Florida procurement cycles run 8-12 months faster than California due to streamlined environmental review waivers for toll-road expansions, compressing vendor cash conversion.
For Market Incumbents: Extend performance-based service contract portfolios into hurricane resilience and freight corridor segments before FCC spectrum rulings strand DSRC investments. Deepen backward integration into edge-computing hardware design to capture margin pools migrating from Cisco and IBM toward specialized roadside unit manufacturers. Lock in Texas Turnpike Enterprise and Florida DOT through 10-year throughput guarantees that block challenger entry.
For New Entrants and Emerging Players: Begin with AI-powered predictive maintenance software that layers atop existing IoT sensor networks without requiring roadside unit hardware certification. Target Illinois and Michigan DOT pilot zones where federal freight corridor funds exceed established vendor deployment capacity. Lead with condition-based highway asset management platforms that convert capital-averse municipal transportation departments to SaaS subscriptions.
For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap edge-computing hardware specialists holding NHTSA safety certifications and active DOT pilot deployments. Long-term viability favors vendors with recurring software revenue exceeding 35% of total contract value. Watch FCC 5.9 GHz spectrum reallocation timing as the inflection trigger determining DSRC hardware obsolescence risk and C-V2X replacement demand velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Protocol Hardware Compatibility | Maintains NHTSA certification through DSRC-C-V2X transition period without California DOT pilot stranding. |
| Performance-Based Service Contracting | Texas DOT and Florida Turnpike Enterprise now require guaranteed throughput metrics over equipment specifications. |
| Edge Computing Node Integration | Sub-50-millisecond latency roadside units eliminate round-trip dependency on centralized data centers. |
| FCC Regulatory Affairs Investment | Dedicated compliance teams capture Infrastructure Investment and Jobs Act co-funding eligibility. |
| Hurricane Resilience Specialization | Florida emergency management funds channel toward intelligent evacuation routing and flood monitoring systems. |
Research Methodology
Multiple input streams — state DOT procurement officers, turnpike enterprise technology directors, federal highway administration grant administrators, and roadside unit engineering leads — were reconciled against Infrastructure Investment and Jobs Act funding disclosure databases, FCC equipment authorization filings, and NHTSA vehicle safety performance reports. Secondary validation drew from US DOT budget justifications, state transportation improvement program documents, and Congressional Research Service infrastructure analyses. Bottom-up deployment tallies across California, Texas, and Florida corridors were triangulated with top-down federal funding allocation models.
Segmentation outputs across technology type, deployment setting, application function, and end-user authority were reconciled through the projection horizon. Technology refresh cycles, spectrum allocation uncertainty, and federal grant eligibility windows shaped CAGR derivation. Modeled dimensions included roadside unit protocol generation, fiber-optic backbone upgrade wave timing, and performance-based versus capital procurement mix shifts.
Several conditions sit outside the modeled scope, including pending FCC 5.9 GHz reallocation rulings, state-level congestion pricing mandate adoption timelines, and semiconductor fabrication capacity expansion trajectories. Forecasts embed assumptions about federal funding continuity and NHTSA-C-V2X rulemaking coordination. A small set of named triggers — spectrum reallocation timing, DSRC asset stranding magnitude, and Texas toll corridor expansion acceleration — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Transportation Solutions
Europe Passenger Information System Market
Smart Transportation Solutions
Electric Kick Scooters Market
Smart Transportation Solutions
Smart Parking Systems Market
Smart Transportation Solutions
North America Smart Transportation Market
Smart Transportation Solutions
Cellular Vehicle-To-Everything (C-V2X) Market
Smart Transportation Solutions
Intermodal Corridor Performance Monitoring Dashboards Market
Smart Transportation Solutions
Automotive Platooning Systems Market
Smart Transportation Solutions
Monorail System Market
Smart Transportation Solutions
Smart Ports Market
Smart Transportation Solutions
Transportation for Smart Cities Market
Smart Transportation Solutions
Automatic Identification Systems (AIS) Market
Smart Transportation Solutions
North America Traffic Signal Recognition Market
Smart Transportation Solutions
Asia-Pacific Smart Transportation Market
Smart Transportation Solutions
Transportation Analytics Market
Smart Transportation Solutions
Contactless Ticketing Market
Smart Transportation Solutions
Mexico Ride Hailing Market