
 Europe Smart Transportation Market | 2026-2036
Europe Smart Transportation Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Smart Transportation Market Analytics
Public-private partnership frameworks for urban mobility infrastructure is rewriting procurement rules across European metropolitan networks. Siemens AG leverages its digital rail and traffic management portfolio to anchor large-scale smart city deployments in German and Austrian transit zones. Kapsch TrafficCom AG specializes in electronic toll collection and intelligent intersection systems, competing directly with Thales Group, which dominates signaling and communications layers for multimodal transport operators.
Europe Smart Transportation encompasses integrated hardware-software ecosystems that orchestrate vehicle-to-infrastructure data exchange, real-time traffic analytics, and automated fare collection across road, rail, and urban transit modes. Core functional parameters include sub-100 millisecond V2X communication latency, 99.99% uptime requirements for safety-critical signaling, and cloud-native architectures processing petabyte-scale telemetry streams from distributed sensor networks. Connected Vehicles represents the most capital-intensive segment, absorbing disproportionate R&D allocation as OEMs and infrastructure vendors converge on interoperable standards. Fleet Management Systems is expanding fastest among logistics providers facing EU emissions trading compliance deadlines, while Smart Traffic Signals retains mature margin pools in municipal retrofit cycles across Southern and Eastern Europe.
EU Green Deal mobility targets, ETSI V2X standards, and national implementations of the EU AI Act are collectively mandating algorithmic transparency in automated traffic decision systems and carbon-accounting traceability for public procurement. EMA and national regulators do not directly govern this sector, but CE marking requirements under the Machinery Directive and emerging EU Cyber Resilience Act certifications are reshaping product access conditions for non-European component suppliers. Stakeholders must monitor interoperability certification timelines and subsidy qualification criteria tied to the EU's Alternative Fuels Infrastructure Regulation deployment corridors.
Market Dynamics
The EU Green Deal's mobility decarbonization mandates are forcing infrastructure operators across Germany, France, and the Netherlands to replace legacy signal networks with connected vehicle-ready systems, compressing procurement cycles and rewiring vendor qualification criteria.
Growth Catalysts
- EU Alternative Fuels Infrastructure Regulation:Deployment corridor subsidies are accelerating charging and hydrogen refueling infrastructure buildouts along Rhine-Ruhr and Paris-Lyon transit axes.
- Fleet operators:Logistics providers facing EU emissions trading compliance deadlines are absorbing fleet management systems at unprecedented velocity.
- AI-powered traffic management:Urban transit authorities are deploying real-time intersection optimization platforms to cut congestion-related emissions.
Market Restraints
- Semiconductor supply concentration:V2X chipset fabrication depends on Taiwanese and South Korean foundry capacity, exposing European system integrators to allocation volatility.
- CE marking complexity:Machinery Directive compliance timelines for safety-critical signaling components stretch 18-24 months, gating product launches.
- Copper and rare earth input costs:Sensor network cabling and magnet materials face price instability from concentrated extraction geographies.
Strategic Opportunities
- Poland and Czech Republic:Eastern European municipal retrofit cycles for smart traffic signals remain underpenetrated relative to Western European deployment density.
- Multimodal integration platforms:Convergence of rail signaling, road V2X, and urban transit fare collection creates white space for unified orchestration layers.
- EU Cyber Resilience Act:Certification requirements for connected vehicle components will favor early-compliant vendors in public procurement scoring.
Industry Challenges
- V2X protocol engineering talent:Shortage of engineers proficient in ETSI standards and sub-100 millisecond latency optimization constrains R&D throughput.
- Legacy signal system integration:Retrofitting 1980s-era electromechanical interlockings with IP-native architectures demands bespoke middleware development.
- Interoperability certification backlogs:National type approval queues for cross-border rail signaling equipment extend project timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Smart Transportation Market |
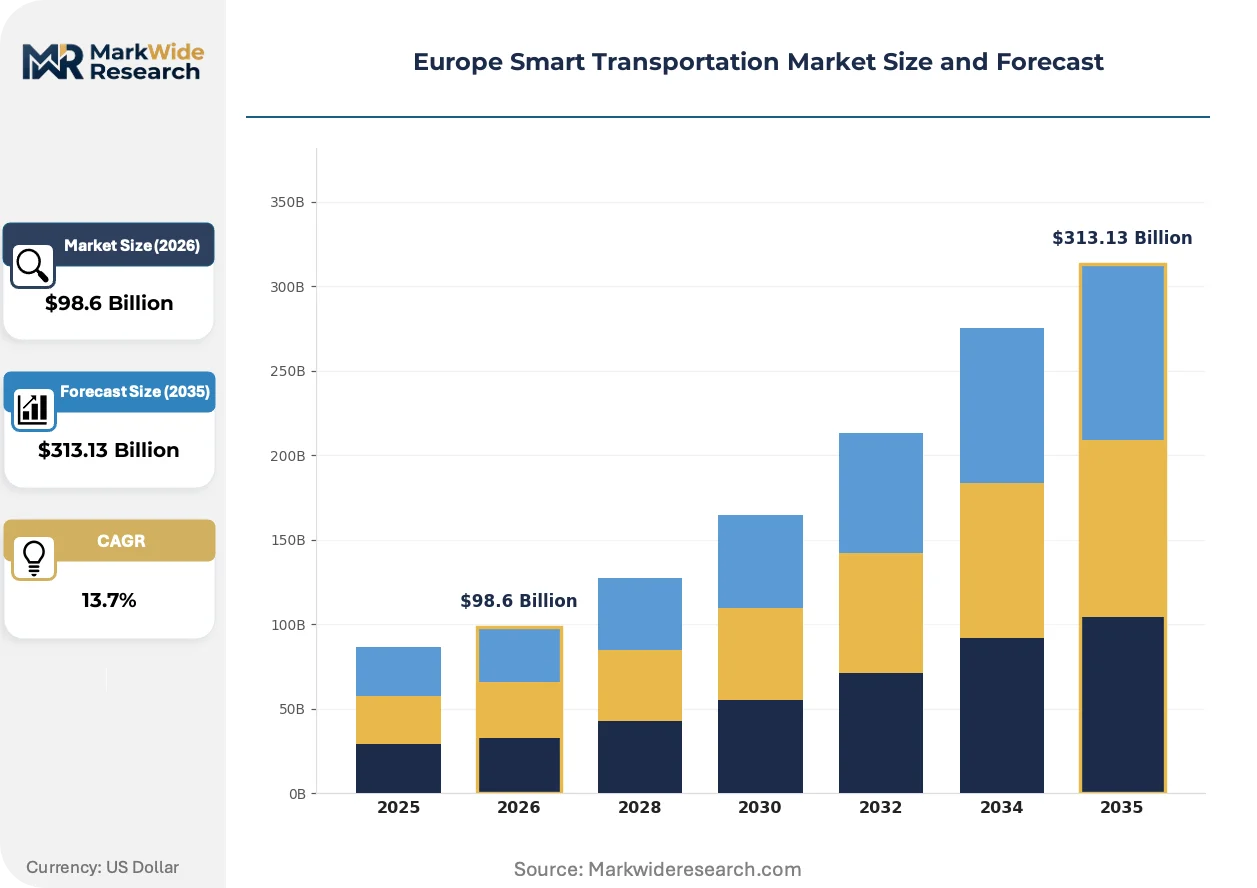
| Market Size in 2026 | $98.6 Billion |
| Market Size in 2035 | $313.13 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Connected Vehicles, Smart Traffic Signals, Fleet Management Systems, Electronic Toll Collection Technology: IoT, AI, Cloud Computing, V2X Communication End User: Government Agencies, Transportation Operators, Logistics Providers, Private Users Application: Traffic Management, Public Transport Systems, Travel Information Services, Emergency Response Management |
| Companies Covered | Siemens AG, Kapsch TrafficCom AG, Thales Group, Alstom, Schneider Electric, TomTom International BV, MSR-Traffic GmbH, Cubic Corporation, SWARCO, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Smart Transportation Market Evolving Landscape
Cloud-native traffic management architectures are rendering obsolete on-premise signal control rooms, while edge computing deployments and AI inference at the intersection level are compressing decision latencies below human reaction thresholds.
Edge AI inference engines embedded directly in smart intersection controllers are rendering obsolete centralized traffic management centers that rely on round-trip data flows to distant servers. German and Dutch municipal operators are deploying these systems at pilot scale across Rotterdam and Düsseldorf corridors. The shift is compressing emergency vehicle preemption response times from seconds to milliseconds while eliminating single-point-of-failure vulnerabilities in legacy hub-and-spoke architectures.
EU AI Act algorithmic transparency mandates are forcing traffic signal vendors to document decision logic for automated priority allocation systems. Infrastructure operators must now maintain audit trails for AI-driven signal timing adjustments. France's national road operator is piloting explainable AI dashboards for public accountability, setting precedent for procurement specifications across Benelux and Alpine transit zones.
Logistics procurement teams are bundling fleet telematics with carbon accounting software to meet EU emissions trading verification requirements. Third-party fleet management platforms are displacing in-house dispatch systems among mid-sized freight operators. This pattern concentrates most visibly in Germany's Rhine-Ruhr corridor, where multimodal freight hubs demand unified visibility across road, rail, and inland waterway legs.
Europe Smart Transportation Market Segmentation
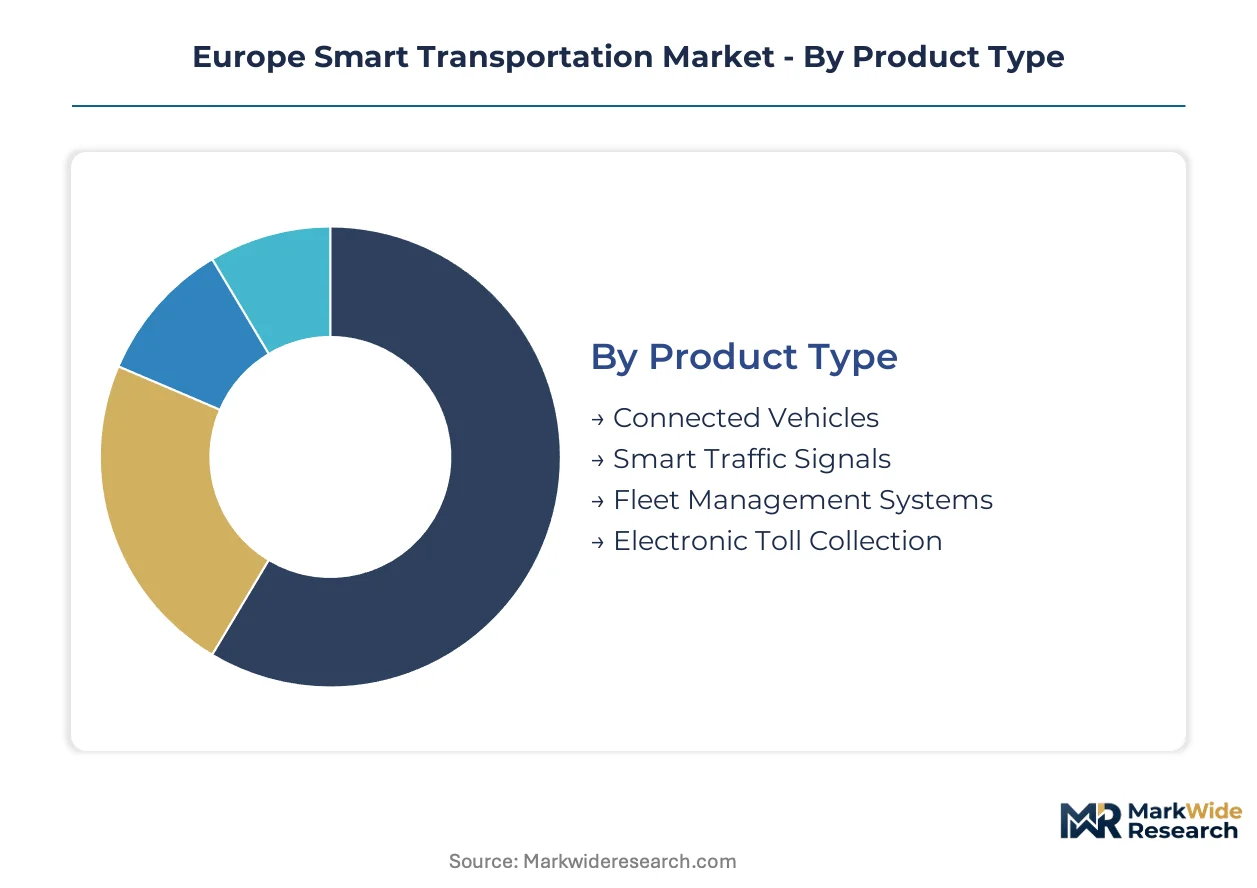
Smart transportation infrastructure investment flows unevenly across product categories, with municipal procurement cycles for physical hardware running 5-7 years while software refresh rates compress toward 18-24 months. Understanding these velocity differentials shapes vendor portfolio allocation and R&D prioritization across European transit authorities.
Product Type:
Connected Vehicles and Fleet Management Systems turn over fastest as logistics operators cycle telematics hardware on 3-year depreciation schedules, while Smart Traffic Signals and Electronic Toll Collection infrastructure endure 15-20 year asset lifecycles.
- Connected Vehicles:Onboard units and OBU-integrated telematics platforms process V2X message sets for cooperative awareness and collision avoidance. German OEMs and Dutch fleet operators are absorbing the largest deployment volumes as EU Green Deal compliance deadlines harden. Semiconductor allocation bottlenecks for DSRC and C-V2X chipsets constrain near-term rollout velocity.
- Fleet Management Systems:Cloud-native dispatch optimization and carbon accounting dashboards displace legacy on-premise logistics software. Rhine-Ruhr freight hubs and Paris-Lyon corridor operators are consolidating multi-modal visibility platforms to meet EU emissions trading verification requirements. Third-party SaaS providers are capturing mid-sized logistics operators previously running in-house systems.
- Smart Traffic Signals:Adaptive intersection controllers with edge AI inference engines replace electromechanical relay systems.
- Electronic Toll Collection:Multi-lane free-flow gantries and GNSS-based distance charging systems replace barrier toll plazas.
Smart Traffic Signals dominates installed base across Southern and Eastern European retrofit markets. Fleet Management Systems is where expansion concentrates among logistics providers facing compliance deadlines.
Technology:
Cost tier separation runs widest here, with V2X Communication hardware carrying 40-60% gross margins against commodity Cloud Computing infrastructure services.
- V2X Communication:DSRC and C-V2X radio modules enable sub-100 millisecond vehicle-to-infrastructure data exchange for safety-critical applications. ETSI standards compliance and CE marking under the Machinery Directive gate market access for non-European component suppliers. Foundry concentration in Taiwan and South Korea exposes European system integrators to allocation volatility.
- AI:Real-time traffic flow prediction and automated signal timing optimization algorithms run on edge inference engines. French national road operators are piloting explainable AI dashboards to satisfy EU AI Act transparency mandates for public accountability. Algorithm audit trail requirements are rewriting procurement specifications across Benelux transit zones.
- IoT:Distributed sensor networks for traffic volume detection and environmental monitoring.
- Cloud Computing:Centralized telemetry aggregation and historical analytics platforms for municipal traffic authorities.
V2X Communication captures premium pricing in safety-critical signaling layers. Cloud Computing is climbing fastest as municipal operators abandon on-premise control rooms.
End User:
Application maturity separates government-funded infrastructure from commercial operator procurement, with Transportation Operators running the most advanced multi-modal integration pilots.
- Transportation Operators:Rail signaling authorities and urban transit agencies orchestrate cross-modal fare collection and real-time passenger information systems. German Rhine-Ruhr and Dutch Randstad corridors are absorbing the largest public investment shares for multimodal integration platforms. Legacy electromechanical interlocking retrofit demands constrain deployment velocity.
- Logistics Providers:Freight operators bundle telematics with carbon accounting software to satisfy EU emissions trading compliance. Mid-sized German and Polish fleet operators are displacing in-house dispatch systems with third-party platforms at unprecedented velocity. Procurement teams prioritize unified visibility across road, rail, and inland waterway legs.
- Government Agencies:Municipal traffic departments and national road operators fund smart intersection and corridor management deployments.
- Private Users:Individual motorists access real-time navigation and parking availability services through smartphone applications.
Government Agencies anchor infrastructure procurement volumes. Logistics Providers are gaining share fastest as emissions compliance hardens.
Application:
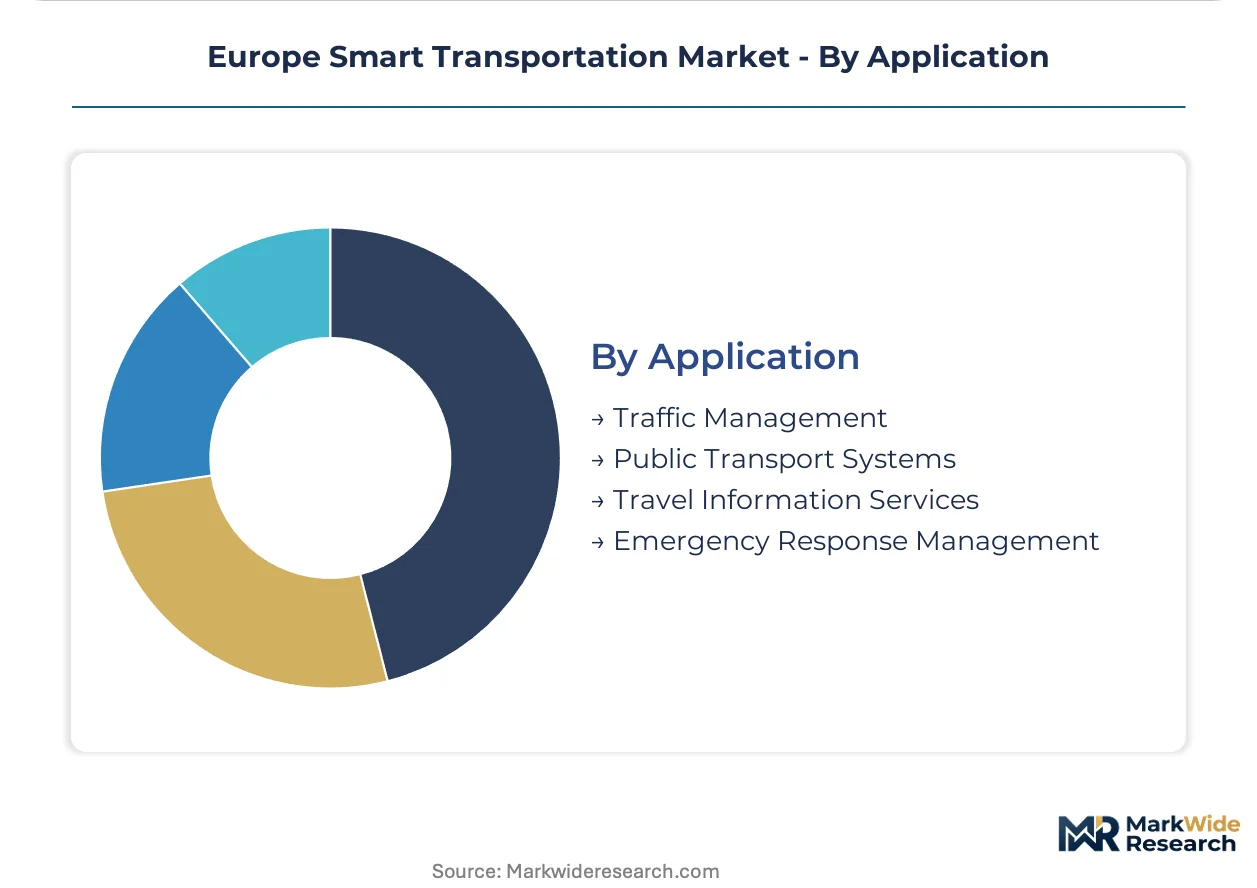
Volume concentration clusters on Traffic Management and Public Transport Systems, with Travel Information Services and Emergency Response Management occupying narrower deployment niches.
- Traffic Management:Real-time intersection optimization and corridor signal coordination platforms cut congestion-related emissions. Rotterdam and Düsseldorf municipal operators are deploying edge AI inference engines at pilot scale to compress emergency vehicle preemption response times. Cloud-native architectures are displacing centralized control rooms.
- Public Transport Systems:Automated fare collection and real-time passenger information displays integrate bus, rail, and metro modes. German and Austrian transit zones are consolidating account-based ticketing across regional operator boundaries. Interoperability certification backlogs for cross-border rail signaling extend project timelines.
- Travel Information Services:Multi-modal journey planners and predictive arrival time applications for end consumers.
- Emergency Response Management:Automated incident detection and priority vehicle preemption systems for fire and ambulance services.
Traffic Management dominates current procurement cycles. Public Transport Systems shows the steepest expansion trajectory as multimodal integration mandates proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Ruhr metropolitan corridor anchors European smart transportation infrastructure investment, with Rotterdam's port complex and the Alpine transit tunnels underwriting north-south freight digitization across the continent.
Germany
Rhine-Ruhr freight hubs demand unified multimodal visibility across road, rail, and inland waterway legs. The EU Green Deal's mobility decarbonization mandates are compressing procurement cycles for connected vehicle-ready signal networks. Bavaria's Munich-Stuttgart corridor is deploying edge AI inference engines for real-time intersection optimization.
Netherlands
Randstad metropolitan operators are piloting cloud-native traffic management architectures that displace centralized control rooms. ETSI V2X standards compliance requirements are reshaping vendor qualification criteria for public procurement. Rotterdam municipal authorities are deploying sub-100 millisecond emergency vehicle preemption systems at scale.
France
Paris-Lyon transit axis operators are consolidating account-based ticketing across regional rail boundaries. The EU AI Act's algorithmic transparency mandates are forcing traffic signal vendors to document automated priority allocation decision logic. Île-de-France is piloting explainable AI dashboards for public accountability in automated traffic systems.
Poland
Eastern European municipal retrofit cycles for smart traffic signals remain underpenetrated relative to Western European deployment density. CE marking requirements under the Machinery Directive are gating product launches with 18-24 month compliance timelines. Warsaw and Kraków metropolitan zones are absorbing fleet management systems from mid-sized logistics operators facing EU emissions trading deadlines.
United Kingdom
London-Southeast corridor authorities are integrating automated fare collection with real-time passenger information displays across bus and metro modes. National road operators are replacing barrier toll plazas with multi-lane free-flow gantries. The Midlands region is concentrating logistics procurement of carbon accounting software bundled with fleet telematics.
Europe Smart Transportation Market Competitive Landscape
On the supply side, the industry is consolidating around integrated hardware-software ecosystems that orchestrate vehicle-to-infrastructure data exchange. Tiered competitive positioning separates full-stack infrastructure vendors from component specialists and regional system integrators. Dominant competitive moves include strategic partnerships for interoperability certification and portfolio diversification into cloud-native traffic management architectures.
Among Germany-based industrial conglomerates, Siemens AG anchors the digital rail and traffic management portfolio tier, while Austria-headquartered Kapsch TrafficCom AG occupies a position within electronic toll collection and intelligent intersection systems. France-based Thales Group exemplifies the signaling and communications layer specialization for multimodal transport operators. These three entities represent distinct strategic archetypes: integrated infrastructure platforms, tolling and intersection specialists, and rail-centric signaling authorities.
| Leading Market Players |
|---|
| Siemens AG |
| Kapsch TrafficCom AG |
| Thales Group |
| Alstom |
| Schneider Electric |
| TomTom International BV |
| MSR-Traffic GmbH |
| Cubic Corporation |
| SWARCO |
| Others |
Value Network & Pricing Analysis
Undercapacity in Taiwanese and South Korean semiconductor foundries is compressing allocation timelines for European system integrators while simultaneously hardening pricing posture for V2X chipset suppliers serving German and Dutch traffic management deployments.
Pricing Analysis
Volume-discount tiering separates municipal procurement consortia from single-city deployments, with Rhine-Ruhr metropolitan authorities extracting 15-20% unit cost advantages through multi-year framework agreements. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade under the EU Cyber Resilience Act and Machinery Directive, with CE-marked safety-critical components commanding substantial premia over uncertified alternatives. Cost compression in edge AI inference hardware is intensifying because cloud-native traffic management architectures are displacing proprietary on-premise systems, eroding vendor lock-in power. Mid-sized Eastern European municipalities exhibit highest price sensitivity due to constrained national co-funding ratios, while German federal infrastructure programs demonstrate lowest sensitivity given Green Deal compliance mandates.
Supply Chain Analysis
Tariff exposure between Taiwan and Germany dominates risk calculus for DSRC and C-V2X radio module procurement, with customs delays now extending component lead times unpredictably. Semiconductor fabrication concentrates in Taiwan and South Korea, while rare earth magnet processing for sensor networks rests on Chinese and Vietnamese refining capacity. Copper cabling and lithium-ion backup power systems for intersection controllers face commodity price volatility from concentrated extraction geographies. Single-source vulnerability in 5G-NR V2X chipset supply constrains European system integrators' procurement flexibility. Distribution runs through authorized distributor networks serving national rail signaling authorities and municipal traffic departments, with direct OEM relationships reserved for largest infrastructure consortia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across Eastern European retrofit markets and multimodal integration white spaces creates niche entry opportunities as EU emissions trading deadlines force logistics operators toward specialized fleet management platforms.
For Market Incumbents: Build certification moats around EU Cyber Resilience Act pre-compliance to capture procurement scoring advantages as algorithmic transparency mandates harden under the EU AI Act. Deepen backward integration into edge AI inference engine design to defend margin position against cloud-native software entrants. Anchor capacity expansion in Poland and Czech Republic municipal markets before subsidy windows close. Threat substitution from Chinese V2X component suppliers demands proactive CE marking investment to maintain vendor qualification status. For New Entrants and Emerging Players: Build out multimodal integration platform capabilities targeting underpenetrated Polish and Czech Republic smart traffic signal retrofit cycles where Western European deployment density remains distant. Bundle carbon accounting software with fleet telematics to capture mid-sized German and Polish logistics operators displacing in-house dispatch systems. White space concentrates in unified orchestration layers converging rail signaling, road V2X, and urban transit fare collection. Go-to-market angle: EU Green Deal subsidy qualification consulting bundled with SaaS deployment. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across connected vehicle infrastructure segments as V2X protocol engineering talent scarcity forces premium compensation structures. Long-term viability favors vendors with demonstrated ETSI standards compliance and national type approval track records. Target acquisition archetype: regional system integrators holding interoperability certification relationships with German and Dutch transit authorities. Signal to watch: CE marking queue lengths at notified bodies as leading indicator of product launch velocity compression.| Strategic Initiative | Industry Significance |
|---|---|
| EU Cyber Resilience Act Pre-Compliance | Early certification captures procurement scoring advantages in German and Dutch municipal tenders. |
| Edge AI Inference Engine Development | Sub-100 millisecond latency capabilities differentiate vendors in Rotterdam and Düsseldorf pilot deployments. |
| Eastern European Market Expansion | Poland and Czech Republic retrofit cycles absorb capital before Western European saturation hardens. |
| Multimodal Integration Platform Launch | Unified orchestration layers address white space between rail signaling and road V2X systems. |
| Carbon Accounting Software Bundling | EU emissions trading verification requirements drive displacement of in-house logistics dispatch systems. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EU regulatory filings, ETSI standards documentation, and national procurement databases. Primary interviews engaged traffic management system procurement officers at German and Dutch transit authorities, fleet operations directors at Rhine-Ruhr logistics hubs, and regulatory affairs leads at V2X component suppliers. Secondary validation drew from EU Alternative Fuels Infrastructure Regulation deployment corridor disclosures, CE marking notified body registries, and municipal budget appropriation records. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators across the European smart transportation value chain.
Forecast inputs incorporate technology adoption curves for V2X communication hardware, software refresh rates for cloud-native traffic management platforms, and municipal procurement cycle velocities varying by country. Segmentation dimensions span product type, technology tier, end-user category, and application area, with additional modeling of interoperability certification timelines as industry-specific constraint. CAGRs derive from fitted growth curves against historical deployment data, adjusted for EU Green Deal subsidy phase-in schedules and emissions trading compliance deadline clustering. V2X chipset foundry allocation forecasts and rare earth supply elasticity assumptions inform hardware segment projections.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Taiwanese semiconductor foundries or accelerated EU Cyber Resilience Act enforcement timelines would shift outcomes meaningfully. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Transportation Solutions
Smart Fleet Management Market
Smart Transportation Solutions
Automotive V2X Market
Smart Transportation Solutions
Smart Rail Suite Solutions Market
Smart Transportation Solutions
Parking Finder Apps Market
Smart Transportation Solutions
Monorail System Market
Smart Transportation Solutions
Smart Transportation Solution Market
Smart Transportation Solutions
Global Integrated Traffic System Market
Smart Transportation Solutions
North America Smart Transportation Market
Smart Transportation Solutions
Vehicle Parking Meter Market
Smart Transportation Solutions
Road Weather Information Systems (RWIS) Market
Smart Transportation Solutions
Europe Electronic Toll Collection Market
Smart Transportation Solutions
Closed Platform Screen Doors Market
Smart Transportation Solutions
Shared Vehicles Market
Smart Transportation Solutions
Global Ridesharing Market
Smart Transportation Solutions
Micro Mobility Market
Smart Transportation Solutions
Smart Bus Shelters Market