
 Global Mannosylerythritol Lipids Market | 2026-2036
Global Mannosylerythritol Lipids Market Size, Share, and Industry Trends Forecast 2026-2036
Global Mannosylerythritol Lipids Market Analysis
Pharmaceutical-grade purity specifications are rotating toward the center of supplier strategy as formulators seek glycolipids with endotoxin profiles suitable for parenteral and dermatological applications. Soliance leverages its fermentation expertise to sustain European supply chains for cosmetic-grade mannosylerythritol lipids. Toyobo Co., Ltd. anchors Japanese production capacity through proprietary yeast strain development. Kaneka Corporation differentiates via backward integration into feedstock carbohydrates and downstream purification.
Mannosylerythritol lipids comprise a class of microbial glycolipid biosurfactants produced by Pseudozyma and Ustilago fungal species through aerobic fermentation of vegetable oils and carbohydrates, typically yielding CMC values between 10⁻⁵ and 10⁻⁶ mol/L and interfacial tension reduction to below 1 mN/m. Their primary industrial purpose centers on replacing synthetic surfactants in applications demanding biocompatibility, biodegradability, and low ecotoxicity profiles. The natural product type segment leads current volume owing to established fermentation protocols and clean-label positioning in cosmetics and food additives, while modified variants exhibit the fastest trajectory as pharmaceutical sponsors explore structure-activity relationships for targeted drug delivery. Surfactant applications concentrate margin pools through technical specification premiums, whereas personal care end users drive baseline volume through steady reformulation cycles.
EMA guidelines on excipient biocompatibility and REACH Annex XIV restrictions on persistent organic surfactants are elevating documentation burdens for synthetic alternatives while creating streamlined pathways for microbial-derived glycolipids. EPA Safer Choice program criteria and FDA inactive ingredient database listings for biosurfactants are reshaping qualification protocols for suppliers targeting North American pharmaceutical and personal care markets. Stakeholders must monitor evolving pharmacopeial monograph developments for glycolipid excipients and align manufacturing investments with dual-certification strategies spanning cosmetic and pharmaceutical quality tiers.
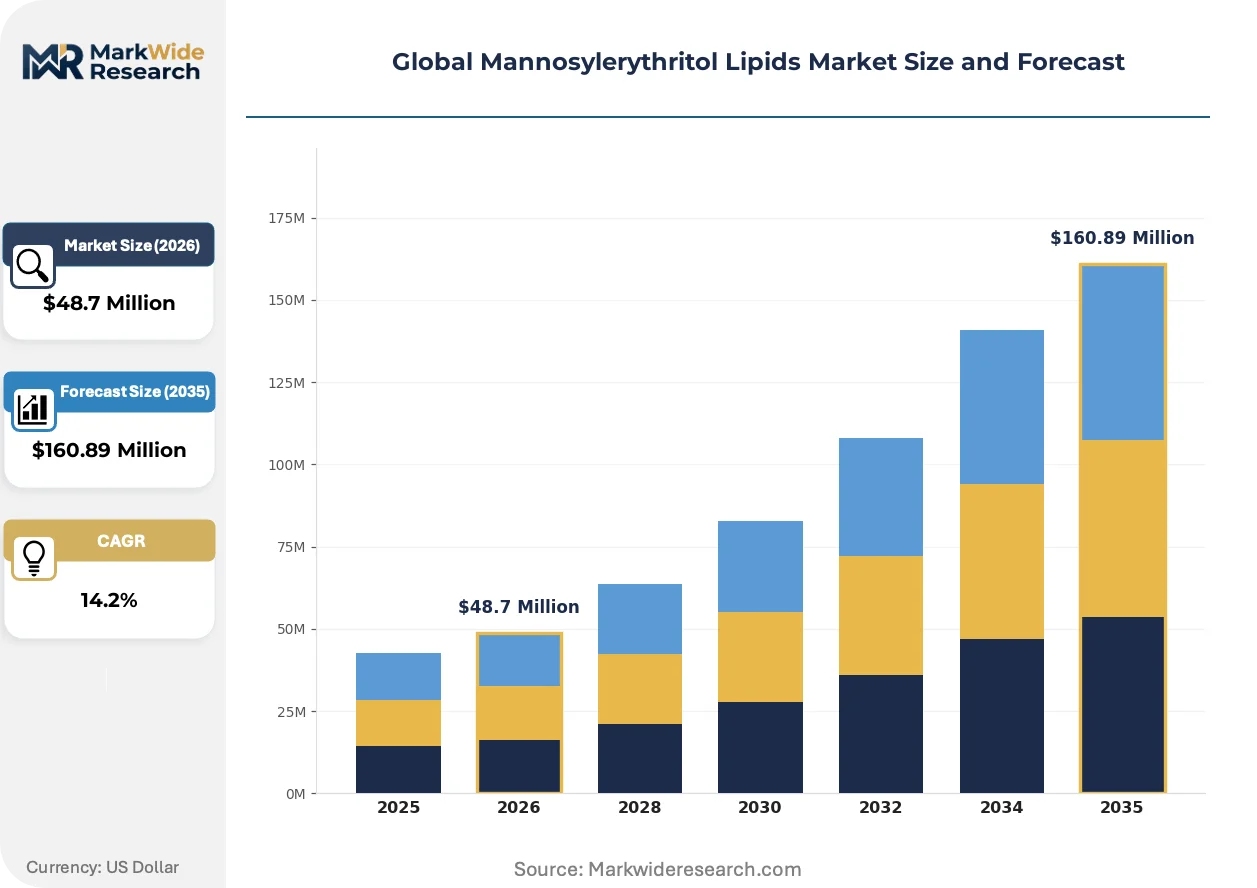
Market Dynamics
REACH Annex XIV restrictions on persistent organic surfactants and EPA Safer Choice criteria are redirecting procurement toward microbial glycolipids, compressing qualification timelines for synthetic alternatives while elevating documentation burdens for biomanufactured replacements.
Growth Catalysts
- EMA Excipient Biocompatibility Guidelines:Pharmaceutical formulators now demand endotoxin-profile documentation that microbial glycolipids satisfy more readily than petrochemical surfactants, opening parenteral applications.
- Japan METI Biomanufacturing Clusters:Concentrated public-private investment in fermentation infrastructure creates captive offtake agreements for high-purity MEL grades serving cosmetic supply chains.
- Fermentation Protocol Maturation:Established aerobic processes using Pseudozyma and Ustilago species achieve CMC values between 10⁻⁵ and 10⁻⁶ mol/L, delivering technical performance parity with synthetics.
Market Restraints
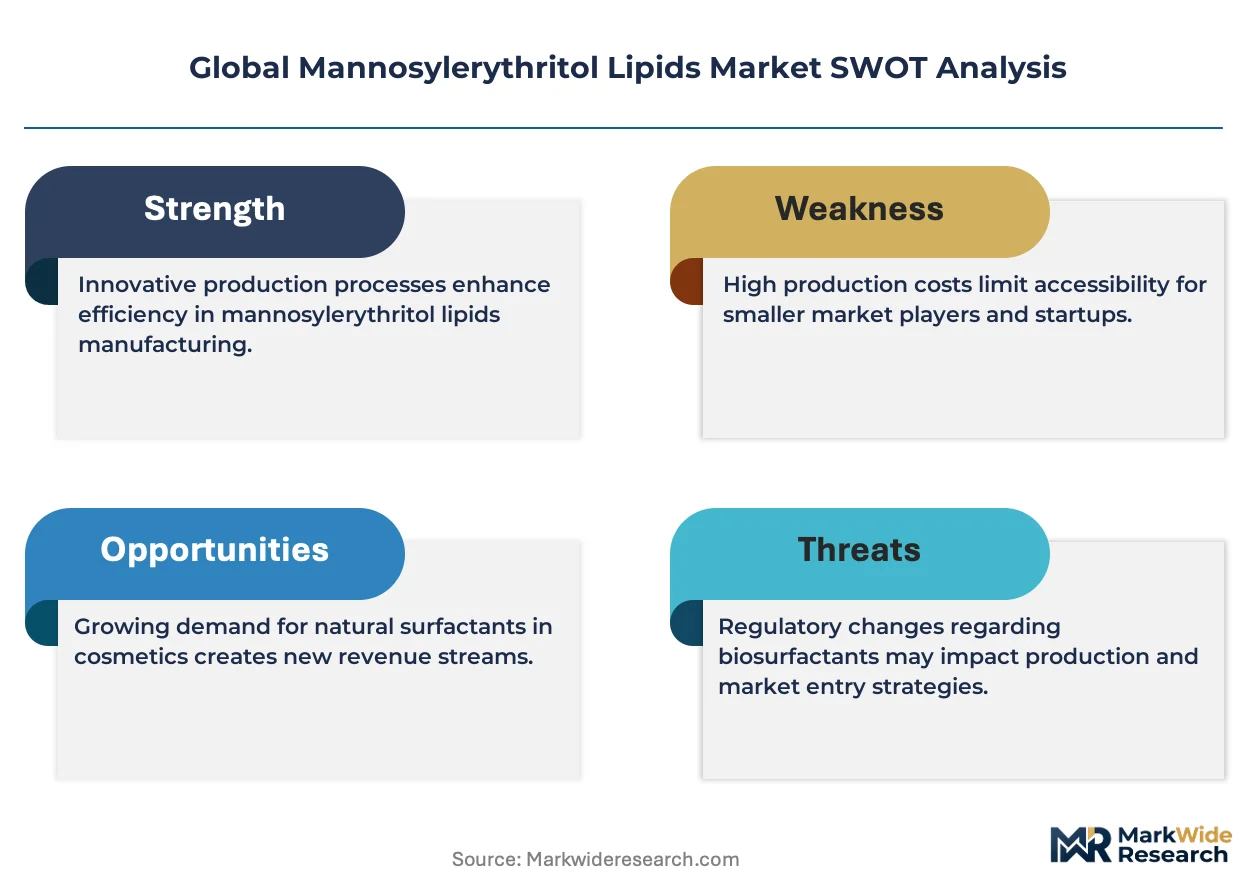
- Feedstock Carbohydrate Volatility:Vegetable oil and carbohydrate input costs fluctuate with agricultural commodity cycles, compressing margin predictability for batch fermentation operations.
- Japanese Production Concentration:Toyobo and Kaneka anchor disproportionate global capacity, creating geographic supply risk for buyers requiring pharmaceutical-grade certification.
- Pharmacopeial Monograph Gaps:Absence of unified glycolipid excipient standards across USP, EP, and JP compendia forces redundant qualification testing for multi-market suppliers.
Strategic Opportunities
- India CDSCO Pathway Expansion:The country's national pharmaceutical regulator is streamlining biosurfactant excipient approvals, creating first-mover advantage for suppliers establishing local analytical partnerships.
- Targeted Drug Delivery Convergence:Modified MEL variants explored for structure-activity relationships pair with liposomal formulation technologies in oncology and dermatology pipelines.
- Direct Sourcing Platforms:Cosmetic manufacturers are bypassing traditional distributors to contract fermentation capacity directly, compressing channel margins and capturing traceability documentation.
Industry Challenges
- Dual-Certification Talent Scarcity:Quality assurance personnel capable of navigating both cosmetic ISO 22716 and pharmaceutical ICH Q7 standards command premium compensation, constraining mid-cap facility expansion.
- Purification Capex Intensity:Downstream chromatography and membrane filtration systems required for endotoxin reduction represent substantial capital commitments with extended depreciation horizons.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Mannosylerythritol Lipids Market |
| Market Size in 2026 | $48.7 Million |
| Market Size in 2035 | $160.89 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural, Synthetic, Modified, Others Application: Cosmetics, Pharmaceuticals, Food Additives, Surfactants End User: Personal Care, Healthcare, Food Industry, Industrial Form: Liquid, Powder, Granules, Paste |
| Companies Covered | Soliance, Jeneil Biotech, Inc., Toyobo Co., Ltd., Damy Chemicals Co., Ltd., Ecover Belgium NV, Kaneka Corporation, Biotopia Co., Ltd., Riken Vitamin Co., Ltd., Kanebo Cosmetics Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Mannosylerythritol Lipids Market Emerging Trajectories
Continuous processing technologies and strain engineering advances are compressing batch cycle times while regulatory harmonization efforts reshape qualification protocols across pharmaceutical and personal care supply chains.
Structure-modified mannosylerythritol lipids with tailored hydrophilic-lipophilic balance values are supplanting conventional glycolipids in parenteral formulation development. Sponsors in oncology and dermatology therapeutic areas are accelerating adoption timelines as these variants demonstrate enhanced encapsulation efficiency for hydrophobic APIs. The shift is compressing R&D cycles for lipid-based drug delivery systems while elevating purity specification premiums.
REACH Annex XIV authorization requirements for nonylphenol ethoxylates and perfluorinated surfactants are eliminating legacy emulsifiers from European cosmetic and industrial formulations. ECHA's restriction timeline forces reformulation commitments by 2026, redirecting procurement budgets toward microbial biosurfactants with established biodegradability profiles. Personal care manufacturers with pan-European distribution networks face the most acute compliance pressure and are consolidating supplier relationships early.
Certification-driven preference shifts now dominate ingredient selection workflows for multinational cosmetic brands. Buyers are unbundling technical service from material supply, contracting independent laboratories for endotoxin and heavy metal verification rather than relying on manufacturer certificates of analysis. This disintermediation is most visible in Japan, where METI-backed cluster participants and established cosmetic houses maintain stringent internal quality protocols that exceed baseline regulatory requirements.
Global Mannosylerythritol Lipids Market Segmentation
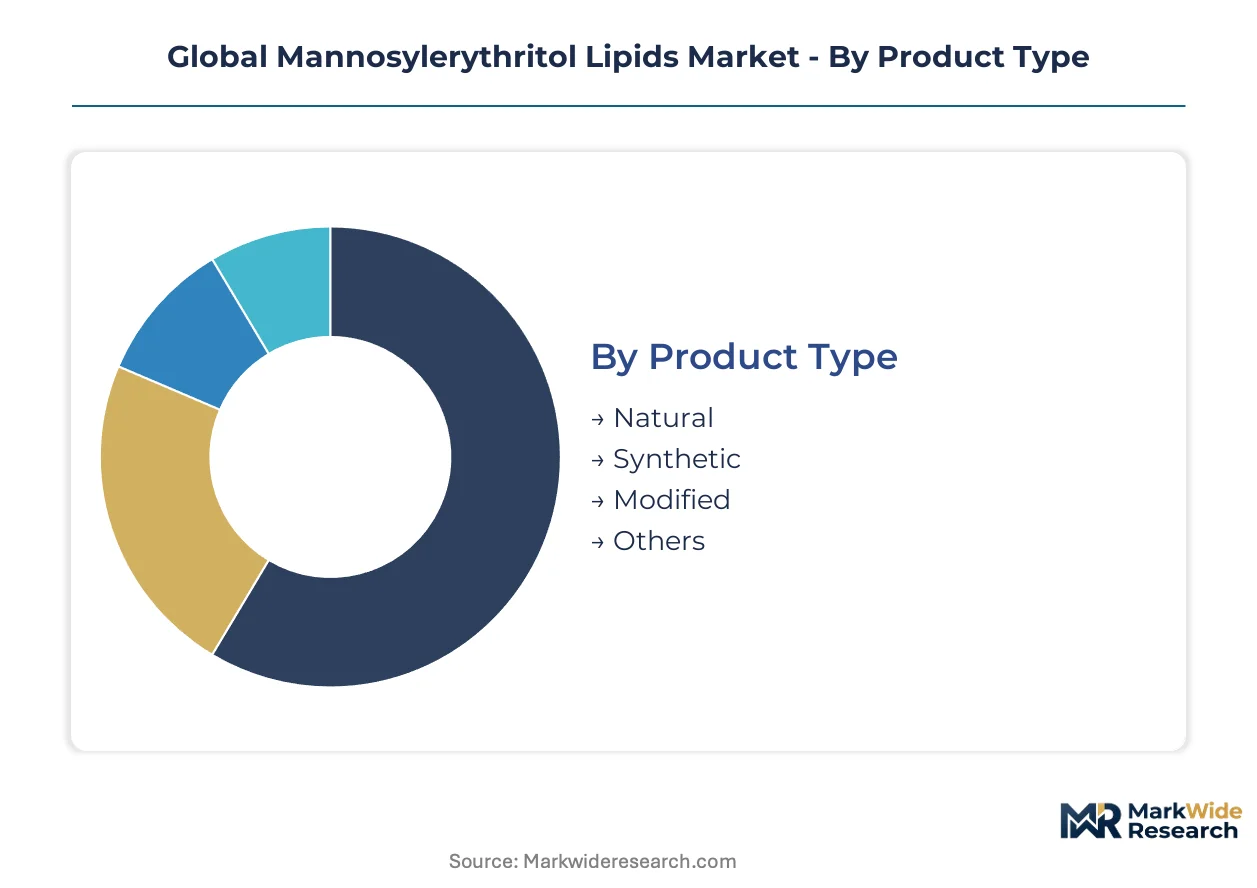
Mannosylerythritol lipids exhibit divergent qualification pathways across product grades and application specifications. Regulatory frameworks in Europe, Japan, and North America enforce distinct purity thresholds that reshape supplier positioning within each segment tier.
Product Type:
REACH Annex XIV authorization timelines and EMA excipient biocompatibility documentation create divergent commercial trajectories across fermentation-derived grades.
- Natural:Established aerobic fermentation protocols using Pseudozyma and Ustilago species yield CMC values between 10⁻⁵ and 10⁻⁶ mol/L. Cosmetic formulators in Japan's METI-backed biomanufacturing clusters absorb the majority of high-purity offtake for clean-label positioning.
- Modified:Structure-activity relationship engineering enables tailored hydrophilic-lipophilic balance values for liposomal drug delivery. Oncology and dermatology sponsors in the US FDA pipeline are accelerating qualification timelines as encapsulation efficiency for hydrophobic APIs improves.
- Synthetic:Petrochemical-derived analogs face compression from EPA Safer Choice criteria and biodegradability mandates.
- Others:Hybrid glycolipid constructs and semi-synthetic variants occupy niche industrial cleaning applications.
Natural MEL handles the majority of throughput; Modified is expanding most quickly on share as pharmaceutical sponsors advance parenteral formulations.
Application:
End-use concentration in Japan and regulatory phase-outs across Europe restructure procurement priorities by technical specification tier.
- Surfactants:Technical-grade specifications command margin premiums through interfacial tension reduction below 1 mN/m. Industrial buyers in Germany's chemical manufacturing corridor are consolidating supplier relationships ahead of REACH nonylphenol ethoxylate restrictions.
- Cosmetics:Personal care manufacturers with pan-European distribution networks face acute ECHA compliance pressure. Reformulation commitments by 2026 are redirecting budgets toward microbial biosurfactants with established biodegradability profiles.
- Pharmaceuticals:Endotoxin documentation requirements for parenteral applications favor microbial glycolipids over petrochemical alternatives.
- Food Additives:EFSA and FDA food contact approvals limit viable supplier pools to fermentation-based production.
Surfactants capture the widest margin pools; Pharmaceuticals is climbing the fastest as EMA guidelines open parenteral applications.
End User:
Customer-type differentiation separates ISO 22716 cosmetic certification from ICH Q7 pharmaceutical quality tiers, constraining mid-cap facility expansion.
- Personal Care:Multinational cosmetic brands in Japan and France are unbundling technical service from material supply, contracting independent laboratories for endotoxin verification rather than relying on manufacturer certificates of analysis.
- Healthcare:Hospital procurement and medical device manufacturers demand USP-grade documentation for topical and injectable formulations.
- Food Industry:Clean-label positioning drives adoption in premium food emulsification applications.
- Industrial:EPA Safer Choice program criteria reshape qualification protocols for North American manufacturing sectors.
Personal Care dominates baseline volume; Healthcare is gaining share fastest through parenteral-grade specification premiums.
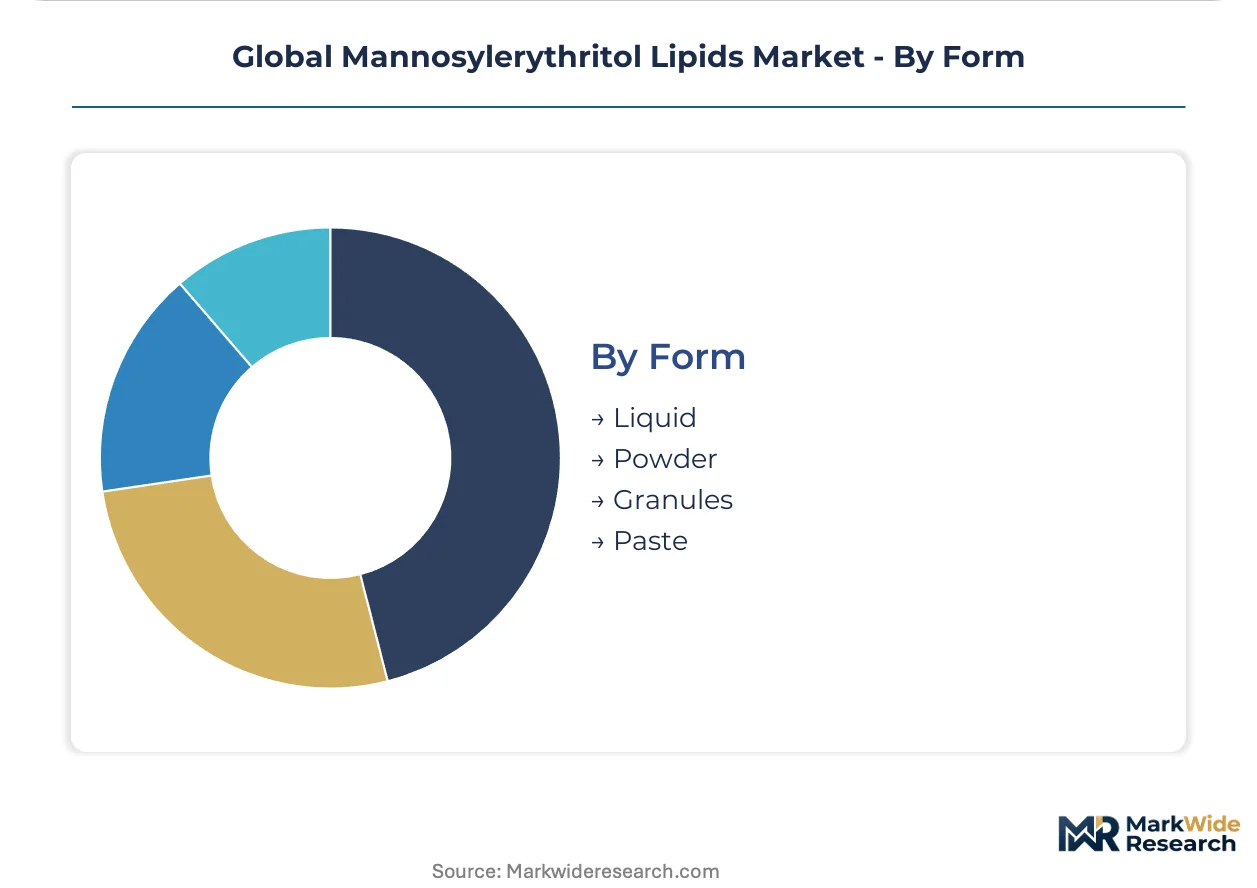
Form:
Downstream processing intensity and purification capex requirements stratify supplier capabilities across physical presentation formats.
- Liquid:Standard fermentation broth concentration serves bulk surfactant applications with minimal downstream processing. Industrial buyers in the US Gulf Coast chemical corridor prefer liquid delivery for formulation integration efficiency.
- Powder:Spray-dried and lyophilized grades require chromatography and membrane filtration systems for endotoxin reduction. Pharmaceutical sponsors in Switzerland and Germany absorb capacity for parenteral and dermatological applications.
- Granules:Intermediate moisture content supports food additive dispersion requirements.
- Paste:High-viscosity concentrates serve specialized cosmetic emulsion formulations.
Liquid handles the majority of throughput; Powder is the fastest mover on share as pharmaceutical-grade demand intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan maintains a persistent trade surplus in high-purity mannosylerythritol lipids while the United States and Germany absorb the majority of pharmaceutical-grade imports. Export flows concentrate through established cosmetic supply chains in East Asia, with European buyers paying premiums for endotoxin-certified material.
Japan
Domestic cosmetic manufacturers command captive offtake from METI-backed biomanufacturing clusters in the Kanto region. PMDA guidance on excipient biocompatibility aligns with EMA standards, streamlining dual-market qualification for fermentation-derived glycolipids. Toyobo and Kaneka anchor production capacity in Osaka and Hyogo prefectures, supplying high-purity grades to Shiseido and Kao formulations.
United States
Pharmaceutical sponsors in Massachusetts and New Jersey drive demand for parenteral-grade MEL variants with documented endotoxin profiles. EPA Safer Choice program criteria redirect procurement away from petrochemical surfactants toward microbial alternatives. The New Jersey pharmaceutical corridor hosts formulation development for liposomal drug delivery systems incorporating structure-modified glycolipids.
Germany
REACH Annex XIV restrictions on nonylphenol ethoxylates force reformulation commitments across the Rhine-Ruhr chemical manufacturing belt. ECHA authorization timelines compress supplier qualification windows for biodegradable replacements. BASF and Evonik distribution networks in Ludwigshafen consolidate sourcing relationships with Japanese fermentation specialists ahead of 2026 compliance deadlines.
India
CDSCO pathway expansion for biosurfactant excipients creates first-mover advantage for suppliers establishing analytical partnerships in Hyderabad and Mumbai. The country's national pharmaceutical regulator streamlines documentation requirements for microbial-derived glycolipids. Maharashtra-based formulation developers contract directly with fermentation capacity to bypass traditional distributor markups.
Switzerland
Swissmedic oversight of parenteral excipients elevates purity specifications for MEL grades used in oncology and dermatology pipelines. Basel-based pharmaceutical sponsors demand USP-grade documentation with independent endotoxin verification. The country's precision manufacturing ecosystem supports downstream chromatography and membrane filtration for pharmaceutical-grade purification.
Global Mannosylerythritol Lipids Market Vendor Landscape
Listed leaders compete with private specialists across certification tiers, with publicly traded entities dominating scale-driven supply and family-held operations capturing premium-grade niches. The vendor base stratifies into three concentration levels: integrated fermentation specialists with captive carbohydrate feedstock, mid-cap purification houses serving dual cosmetic-pharmaceutical markets, and regional distributors handling technical-grade bulk. Strategic moves center on backward integration into agricultural carbohydrate sourcing and direct contracting platforms that disintermediate traditional distribution.
Within the integrated fermentation tier, Toyobo Co., Ltd. and Kaneka Corporation exemplify Japanese production concentration through proprietary yeast strain development and in-house purification infrastructure. Soliance occupies a position among European specialists leveraging fermentation expertise for cosmetic-grade supply chains. Jeneil Biotech, Inc. represents North American capacity focused on biosurfactant diversification beyond conventional glycolipid classes. These anchors illustrate how geographic clustering around METI-backed infrastructure, REACH compliance pressure, and FDA qualification pathways shapes competitive positioning without requiring uniform scale or certification scope.
| Leading Market Players |
|---|
| Soliance |
| Jeneil Biotech, Inc. |
| Toyobo Co., Ltd. |
| Damy Chemicals Co., Ltd. |
| Ecover Belgium NV |
| Kaneka Corporation |
| Biotopia Co., Ltd. |
| Riken Vitamin Co., Ltd. |
| Kanebo Cosmetics Inc. |
| Others |
Supply Flow & Price Mechanics
EMA excipient biocompatibility guidelines and REACH Annex XIV authorization timelines simultaneously gate supply qualification and stratify price tiers across pharmaceutical and cosmetic grades. Buyers face dual certification costs that suppliers pass through as tiered premiums, while feedstock volatility compresses margin predictability for batch fermentation operations.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Pharmaceutical-grade MEL with endotoxin documentation commands substantial premiums over cosmetic-grade material, while technical-grade surfactants trade at commodity-adjacent levels. Pricing pressure stems from carbohydrate feedstock volatility and purification capex intensity. Personal care manufacturers exhibit highest price sensitivity due to reformulation volume requirements, whereas parenteral pharmaceutical sponsors prioritize certification reliability over unit cost.
Supply Chain Analysis
Japan and Germany anchor high-purity MEL production and downstream formulation capacity respectively. Fermentation operations draw from vegetable oil and carbohydrate feedstocks sourced through agricultural commodity markets. Single-source vulnerability concentrates in Japanese yeast strain IP held by Toyobo and Kaneka. Distribution runs through direct contracting platforms that disintermediate traditional chemical distributors, particularly for cosmetic manufacturers seeking traceability documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated personal care multinationals with pan-European distribution networks, fragmenting supplier pricing leverage as direct sourcing platforms proliferate.
For Market Incumbents: Shield market position by deepening backward integration into carbohydrate feedstock sourcing and expanding pharmaceutical-grade purification capacity in Switzerland or Germany. Synthetic surfactant phase-outs under REACH Annex XIV threaten technical-grade revenue streams; counter by accelerating dual-certification investments spanning ISO 22716 and ICH Q7 standards. For New Entrants and Emerging Players: CDSCO fast-track pathways for biosurfactant excipients in India offer lowest regulatory friction for initial market entry. Target parenteral-grade powder MEL supply to Swiss and German pharmaceutical sponsors underserved by incumbent capacity constraints. Establish analytical partnerships with Hyderabad-based laboratories to bypass redundant qualification testing. For Investors and Strategic Acquirers: ECHA's 2026 nonylphenol ethoxylate restriction deadline reshapes the acquisition landscape toward fermentation-derived glycolipid specialists. Five-to-ten year viability favors mid-cap purification houses with existing cosmetic revenue and pharmaceutical certification runway. Monitor pharmacopeial monograph harmonization progress across USP, EP, and JP compendia as inflection indicator for multi-market supplier scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Carbohydrates | Kaneka's captive agricultural sourcing insulates margin predictability from commodity volatility. |
| Pharmaceutical-Grade Purification Scale-Up | Swiss chromatography infrastructure captures parenteral formulation premiums from Basel sponsors. |
| Direct Sourcing Platform Development | Shiseido and Kao contract fermentation capacity directly, compressing distributor markups. |
| CDSCO Analytical Partnership Establishment | Hyderabad laboratories streamline biosurfactant excipient approvals for first-mover advantage. |
| Dual-Certification Quality Investment | Simultaneous ISO 22716 and ICH Q7 compliance opens cosmetic-pharmaceutical cross-selling. |
Methodological Framework
Initial hypotheses were tested against primary input from fermentation plant managers, cosmetic procurement leads at multinational brands, pharmaceutical formulation scientists, and distribution channel partners, then refined through secondary validation against ECHA restriction timelines, FDA inactive ingredient database listings, Japanese customs trade data, and SEC filings from listed biosurfactant producers. Bottom-up volume estimates triangulated with top-down market sizing across natural, modified, and synthetic product grades.
Variance decomposition separated volume growth from price-mix effects across the projection horizon. Segmentation dimensions modeled include product type, application tier, end-user certification requirements, and physical form. CAGRs were derived from fitted growth curves incorporating fermentation capacity expansion schedules, regulatory phase-out timelines, and sponsor pipeline progression for liposomal drug delivery systems.
Decision-makers should treat outputs as directional under sustained REACH enforcement and stable agricultural commodity supply; material deviation in regulatory harmonization or feedstock disruption would warrant model refresh. Recalibration cycles align with material shifts in pharmacopeial monograph developments and biomanufacturing cluster investment announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Magnesium Gluconate Market
Specialty Chemicals
Structure Directing Agents Market
Specialty Chemicals
Metal Biocide Market
Specialty Chemicals
Europe Malic Acid Market
Specialty Chemicals
US Antimicrobial Plastics Market
Specialty Chemicals
Perfluoropolyether (PFPE) Market
Specialty Chemicals
Cellulose Esters and Ethers Market
Specialty Chemicals
Global Metal Chelates Market
Specialty Chemicals
Global Non-Phthalate Plasticizers Market
Specialty Chemicals
Cellulose Ether and Derivatives Market
Specialty Chemicals
India Prussian Blue Market
Specialty Chemicals
Superoxide Dismutase Market
Specialty Chemicals
Glucono Delta Lactone Market
Specialty Chemicals
Salicylate Market
Specialty Chemicals
Electrical Insulating Varnish for Motor Vehicle Market
Specialty Chemicals
Barium Derivatives Market