
 Cat Shampoo Market | 2026-2036
Cat Shampoo Market Size, Share, and Industry Trends Forecast 2026-2036
Cat Shampoo Market Analytics
Direct-to-consumer subscription financing is fragmenting competitive barriers in cat shampoo, allowing niche brands to bypass traditional retail slotting fees and build recurring revenue streams. Earthbath leverages its organic ingredient sourcing to sustain premium positioning across independent pet channels. Wahl Clipper Corporation anchors its grooming portfolio with manufacturing scale that competes on cost in mass-market distribution. Bio-Groom specializes in show-grade formulations that differentiate within the breeder and exhibition segments.
Cat shampoo comprises surfactant-based cleansing formulations engineered for feline dermal pH balance, typically ranging from 6.2 to 7.5 to avoid epidermal disruption, with primary commercial purpose centered on coat maintenance, parasite management, and dermatological symptom relief. Medicated and hypoallergenic product types command the deepest margin pools due to veterinary endorsement requirements and ingredient certification costs. Liquid formulations still dominate volume, though foam and dry shampoo alternatives are capturing share among urban owners with space-constrained bathing environments.
The US Food and Drug Administration oversees veterinary medicated claims, while the EPA regulates flea-control actives such as pyrethrins, and the EU REACH framework restricts certain preservative chemistries from cross-border formulations. These overlapping compliance requirements elevate R&D expenditure for multi-market entrants and create regulatory moats around established players with dedicated toxicology and registration staff. Stakeholders must monitor pending ingredient disclosure mandates and state-level packaging sustainability laws that could force rapid reformulation cycles.
Market Dynamics
Pet humanization is restructuring the cat shampoo market, as owners now treat grooming purchases with the same scrutiny applied to personal cosmetics, forcing ingredient transparency and veterinary-grade efficacy claims into mass-market formulations.
Growth Catalysts
- Veterinary clinic channel expansion:Clinics now stock retail grooming products for post-treatment maintenance, creating a prescription-adjacent revenue stream that validates premium pricing through professional endorsement.
- REACH ingredient disclosure mandates:The European Union's tightening cosmetic safety standards are accelerating clean-label innovation, pushing manufacturers toward biodegradable surfactants and natural preservative systems.
- Subscription commerce infrastructure:Direct-to-consumer platforms are digitizing replenishment cycles, locking in recurring revenue that funds sustained R&D investment without retail slotting fee burdens.
Market Restraints
- Surfactant feedstock volatility:Coconut-derived and palm-based cleansing agents face price instability tied to Southeast Asian agricultural output swings, compressing margin predictability for natural-positioned brands.
- Regulatory fragmentation:The US EPA's pyrethrin registration requirements diverge from EU REACH restrictions on flea-control actives, forcing parallel formulation tracks that duplicate toxicology testing expenditure.
- Dry shampoo substitution:Waterless foam and powder alternatives are capturing urban apartment-dwelling owners, threatening volume in traditional liquid categories.
Strategic Opportunities
- Senior cat dermatology segment:Aging feline populations in Japan and Western Europe create demand for medicated formulations addressing seborrhea and pruritus, segments where veterinary co-development justifies 40-60% price premiums.
- State-level packaging mandates:California's extended producer responsibility laws are forcing recyclable mono-material designs that early adopters can leverage for shelf differentiation.
- AI-driven formulation matching:Diagnostic apps that photograph coat condition and recommend specific actives are converging with e-commerce fulfillment, collapsing the trial-and-error purchase cycle.
Industry Challenges
- Veterinary toxicology expertise scarcity:Feline-specific dermal safety testing requires specialized pharmacokinetic knowledge that contract research organizations struggle to staff, extending new product timelines.
- Cold-chain ingredient integrity:Temperature-sensitive botanical extracts demand refrigerated logistics that conflict with mass-market distribution economics, forcing hard choices between efficacy claims and channel reach.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cat Shampoo Market |
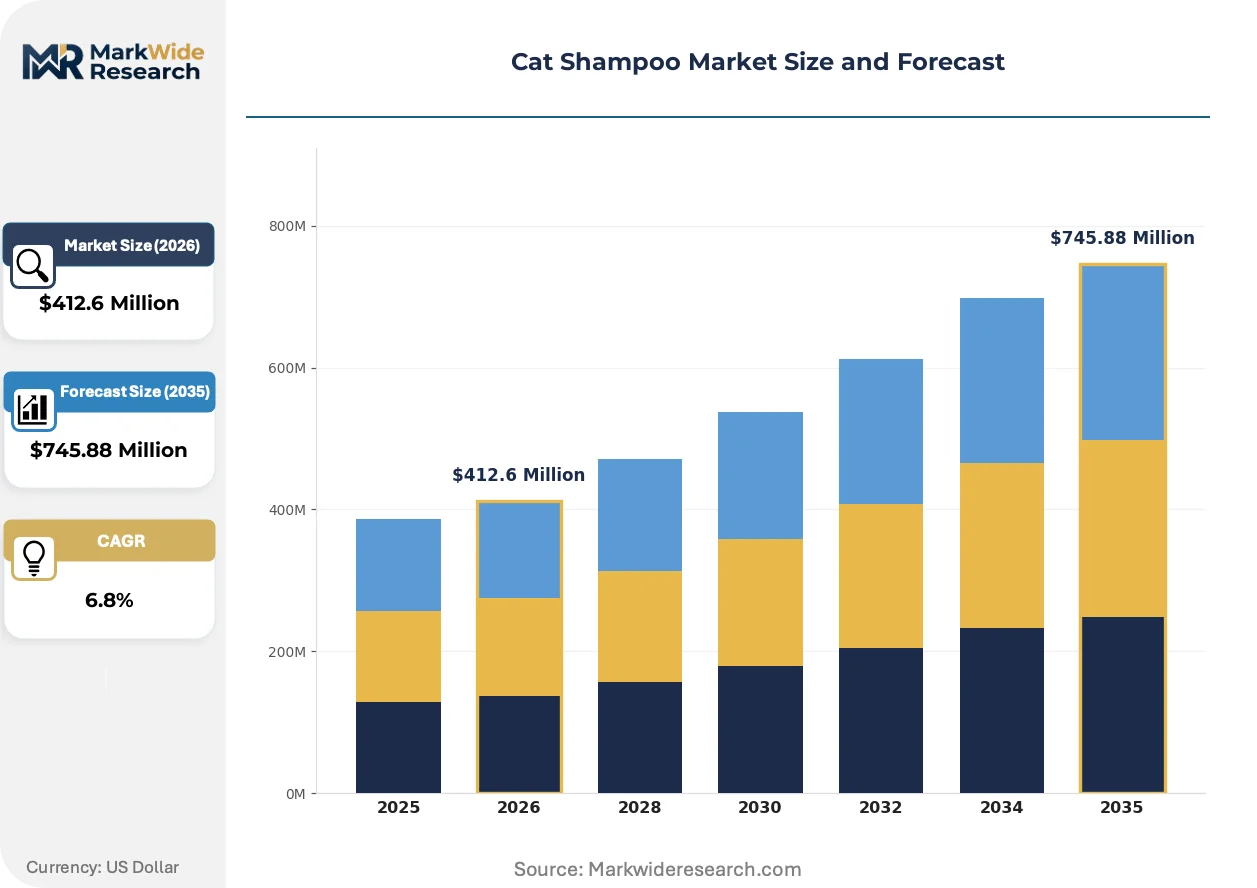
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $745.88 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medicated, Hypoallergenic, Organic, Deodorizing Application: Flea Control, Skin Condition, General Hygiene, Shedding Reduction Form: Liquid, Foam, Spray, Dry Shampoo Packaging Type: Bottle, Tube, Sachet, Refill |
| Companies Covered | Vet's Best, 4-Legger, Earthbath, SynergyLabs, John Paul Pet, TropiClean, Burt's Bees, Wahl Clipper Corporation, Bio-Groom, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cat Shampoo Market Evolving Landscape
Formulation science and channel economics are converging to compress product development cycles while fragmenting how owners discover and purchase grooming solutions.
pH-buffered surfactant systems are digitizing quality assurance protocols, enabling real-time batch consistency monitoring through inline spectroscopy. Specialty breeders and exhibition handlers are adopting these instrument-verified formulations fastest, as credentialing requirements for show eligibility tighten. This instrumentation is digitizing the traditional master-formulator craft, compressing artisanal production timelines toward pharmaceutical-grade repeatability.
REACH Annex XIV authorization lists are restricting isothiazolinone preservatives across EU-bound formulations, forcing manufacturers toward phenoxyethanol and organic acid alternatives with shorter shelf stability. The industrial consequence is accelerated reformulation cycles and elevated stability testing budgets. Hypoallergenic product lines face the steepest compliance burden, as their positioning depends on the absence of flagged chemistries.
Subscription bundling is consolidating the discovery-to-purchase pathway, with curated boxes introducing trial sizes before committing to full-size replenishment. Urban millennial owners in dense metropolitan markets are displacing supermarket impulse purchases with algorithmic recommendations. This pattern concentrates most visibly in US coastal cities, where same-day delivery infrastructure supports just-in-time grooming supply management.
Cat Shampoo Market Segmentation
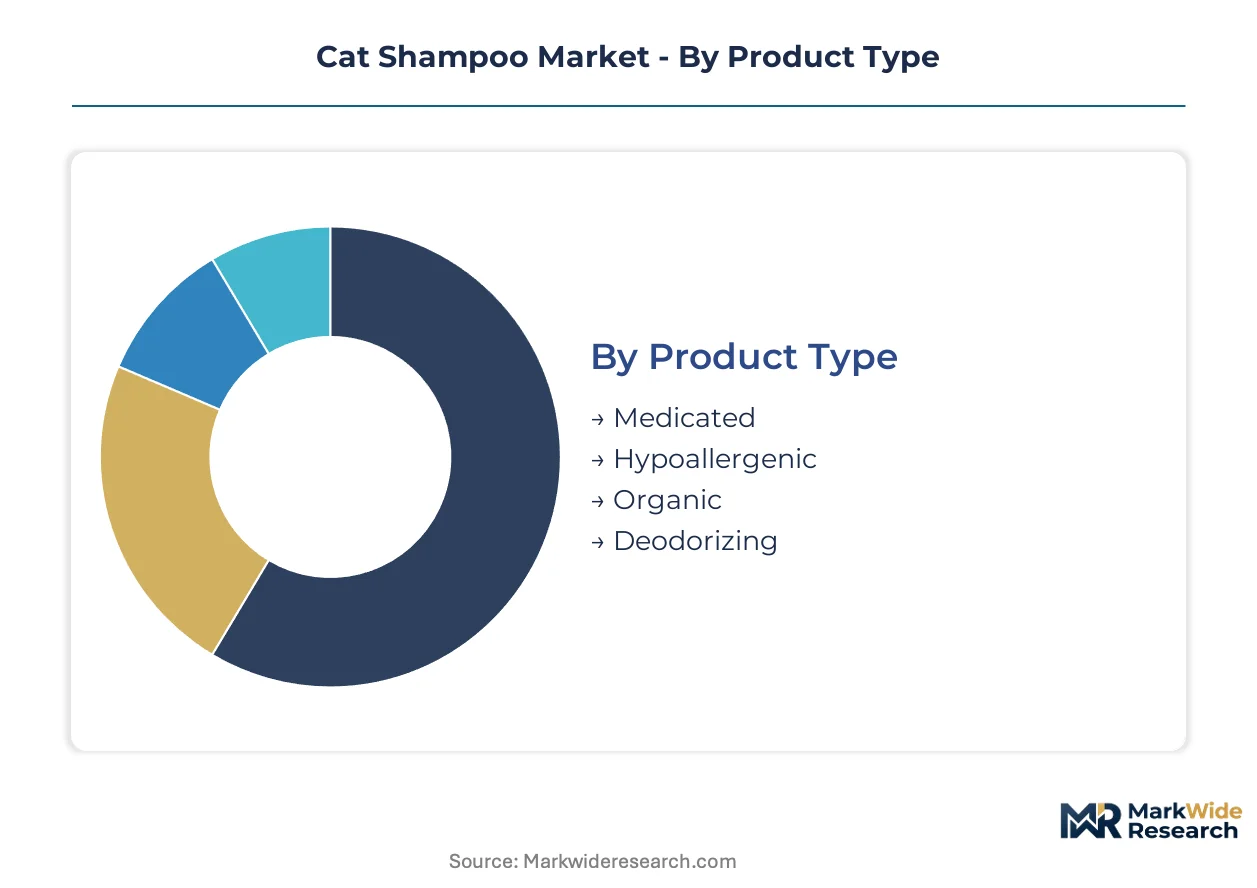
Cat shampoo segmentation reveals how formulation science, application urgency, and owner lifestyle constraints fragment purchasing behavior across distinct margin tiers. Each dimension carries unique regulatory burdens and channel economics that reshape competitive positioning.
Product Type:
Cost tier stratification separates veterinary-endorsed formulations from mass-market alternatives, with ingredient certification requirements dictating pricing architecture.
- Medicated:Prescription-adjacent formulations containing chlorhexidine or miconazole target dermatological conditions. Veterinary clinic channels in the United States validate premium positioning through professional endorsement, with FDA oversight of therapeutic claims extending development timelines.
- Hypoallergenic:Elimination diets for dermal sensitivity exclude flagged chemistries under EU REACH Annex XIV. Breeders and exhibition handlers in Western Europe adopt these formulations fastest as credentialing requirements tighten.
- Organic:Botanical-derived surfactant systems rely on coconut and palm feedstocks vulnerable to Southeast Asian agricultural volatility.
- Deodorizing:Fragrance-forward formulations compete on sensory appeal in mass retail channels with lower barrier to entry.
Medicated commands the established base. The steepest expansion runs through Hypoallergenic.
Application:
Functional urgency determines price elasticity, with parasite management justifying immediate purchase against discretionary grooming routines.
- Flea Control:Pyrethrin-based actives face divergent regulatory tracks — EPA registration in the United States versus REACH restrictions in the European Union — forcing parallel toxicology expenditure. Urban apartment dwellers in dense metropolitan markets drive replenishment frequency.
- Skin Condition:Seborrhea and pruritus formulations target aging feline populations in Japan and Western Europe, where veterinary co-development justifies substantial price premiums.
- General Hygiene:Routine cleansing represents volume base with compressed margins and supermarket impulse purchase dynamics.
- Shedding Reduction:Seasonal demand concentration challenges inventory planning for specialty retailers.
General Hygiene anchors volume throughput. The fastest growth trajectory belongs to Skin Condition.
Form:
Physical format selection reflects urban spatial constraints and owner time scarcity, with waterless alternatives capturing share from traditional liquid applications.
- Liquid:Conventional surfactant-based formulations dominate manufacturing scale and veterinary endorsement heritage.
- Foam:Waterless application eliminates rinsing requirements, resonating with space-constrained owners in US coastal cities where same-day delivery infrastructure supports just-in-time replenishment.
- Spray:Targeted application reduces product waste for spot-treatment scenarios.
- Dry Shampoo:Powder and aerosol formats minimize water contact for stress-sensitive felines, expanding fastest among millennial owners in dense metropolitan markets.
Liquid retains manufacturing concentration. The steepest adoption curve tracks Dry Shampoo.
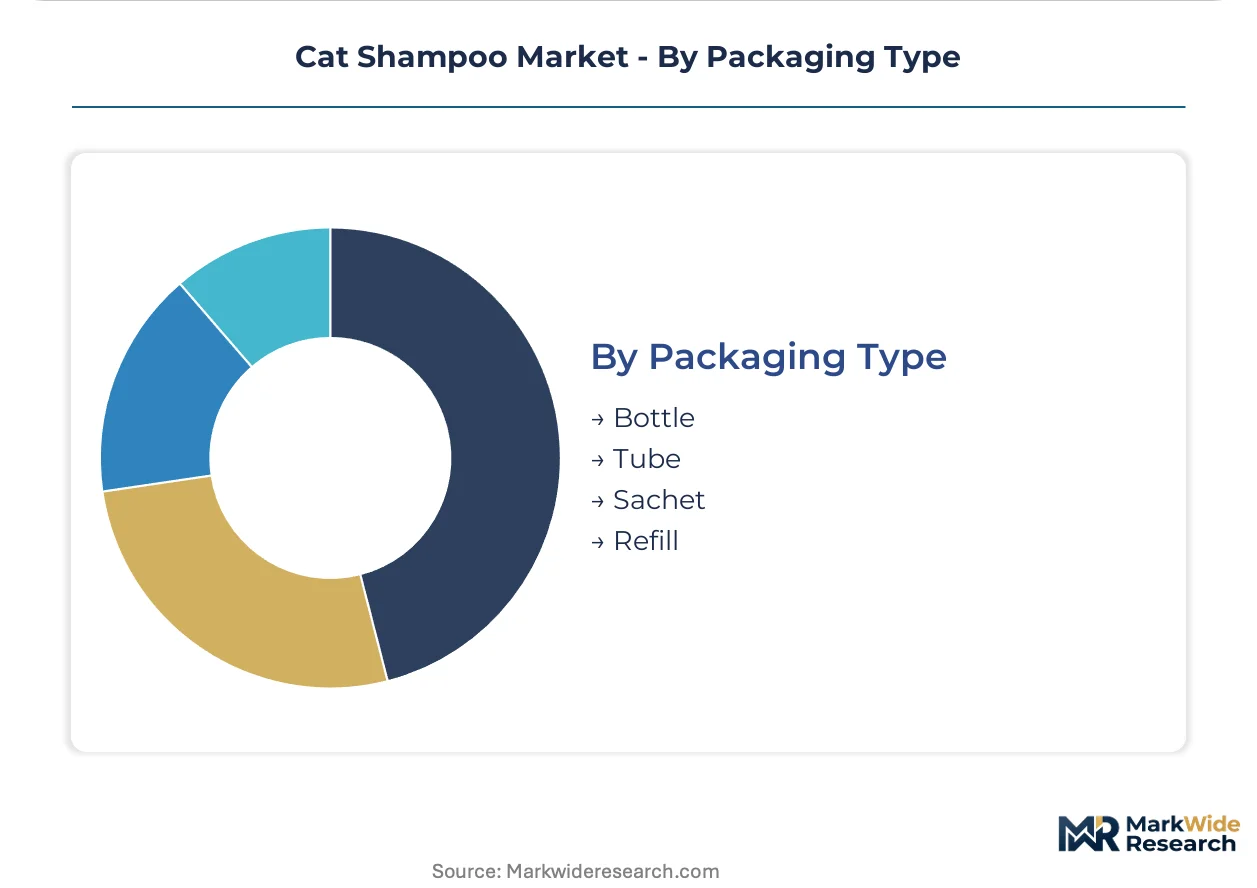
Packaging Type:
Packaging economics intersect with sustainability mandates and channel logistics, with California's extended producer responsibility laws forcing recyclable mono-material redesigns.
- Bottle:Standard HDPE and PET containers face state-level recycling content mandates requiring reformulation of closure systems.
- Tube:Flexible aluminum and laminate structures suit travel-size and veterinary sample distribution.
- Sachet:Single-use pouches enable trial-size introduction in subscription box curation, lowering commitment barriers for algorithmic discovery.
- Refill:Concentrate and bulk formats reduce per-unit plastic intensity, aligning with sustainability-positioned direct-to-consumer brands.
Bottle commands shelf presence. The most rapid format innovation concentrates in Refill.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in cat shampoo flow predominantly from US and European formulation centers toward Asian retail markets, with regulatory divergence creating parallel supply chains that complicate cross-border shipment economics.
United States
Specialty pet retail chains and veterinary clinic networks drive premium formulation demand across metropolitan corridors. FDA oversight of medicated therapeutic claims and EPA pyrethrin registration requirements create dual-track compliance burdens for flea-control actives. Los Angeles and New York City anchor direct-to-consumer subscription fulfillment infrastructure, with same-day delivery networks supporting just-in-time replenishment cycles among urban millennial owners.
Germany
REACH Annex XIV authorization lists are accelerating clean-label innovation among domestic formulators serving Western European markets. ECHA restrictions on isothiazolinone preservatives force rapid shifts toward phenoxyethanol and organic acid alternatives with compressed shelf stability windows. The Rhine-Ruhr industrial cluster hosts concentrated toxicology testing capacity that multi-market entrants leverage for EU market access compliance.
Japan
Aging feline populations generate sustained demand for dermatological formulations addressing seborrhea and pruritus, with veterinary co-development partnerships justifying substantial price premiums. METI guidelines on cosmetic ingredient safety align with broader Asian regulatory harmonization efforts. Tokyo and Osaka metropolitan areas concentrate specialty breeder and exhibition handler communities that adopt instrument-verified pH-buffered formulations fastest.
United Kingdom
Post-Brexit regulatory divergence from EU REACH frameworks creates parallel registration requirements for cross-channel formulations, elevating compliance expenditure for multi-market brands. Independent pet retail channels and subscription box curation services displace traditional supermarket impulse purchases. Greater London hosts the densest concentration of algorithmic recommendation platforms that collapse trial-and-error purchase cycles through diagnostic app integration.
Australia
TGA oversight of veterinary therapeutic claims intersects with state-level packaging sustainability mandates that force recyclable mono-material redesigns. Urban apartment-dwelling owners in Sydney and Melbourne drive rapid adoption of waterless foam and dry shampoo alternatives that eliminate rinsing requirements. Temperature-sensitive botanical extract distribution faces cold-chain logistics constraints that conflict with mass-market channel economics.
Cat Shampoo Market Competitive Landscape
On the supply side, the industry is structured around three distinct tiers: mass-market manufacturers competing on production scale, premium-positioned specialists leveraging organic certification and veterinary endorsement, and direct-to-consumer insurgents bypassing retail slotting fees through subscription infrastructure. Strategic archetypes include formulation-scaled incumbents with captive toxicology expertise, clean-label challengers sourcing temperature-sensitive botanical extracts, and algorithmic-commerce natives integrating diagnostic apps with fulfillment. Dominant competitive moves concentrate on portfolio diversification across medicated-hypoallergenic-organic positioning vectors and geographic expansion through regulatory-staffed market entry rather than acquisition-heavy consolidation.
Within the premium-tier vector, Earthbath and Bio-Groom occupy positions defined by ingredient sourcing credentials and show-grade formulation heritage respectively. Wahl Clipper Corporation anchors the scale-driven end with manufacturing breadth that competes on cost in mass-market distribution. These three entities exemplify how competitive positioning fragments across certification-grade differentiation, channel-specific endorsement requirements, and production economics that favor either artisanal batch consistency or pharmaceutical-grade repeatability.
| Leading Market Players |
|---|
| Vet's Best |
| 4-Legger |
| Earthbath |
| SynergyLabs |
| John Paul Pet |
| TropiClean |
| Burt's Bees |
| Wahl Clipper Corporation |
| Bio-Groom |
| Others |
Value Network & Pricing Analysis
The Rhine-Ruhr industrial cluster anchors European formulation capacity for REACH-compliant surfactant systems, with batch-scale flexibility translating into premium pricing power for hypoallergenic and medicated tiers that mass-market manufacturers cannot replicate. Coconut-derived feedstock volatility in Southeast Asia compresses margin predictability for organic-positioned brands, forcing hard choices between certification maintenance and cost competitiveness.
Pricing Analysis
Premium pet retailers and veterinary clinics anchor a three-tier pricing structure across premium, standard, and economy levels, with certification grade under EU REACH Annex XIV and veterinary endorsement status driving substantial price differentiation. Cost compression in the organic tier is intensifying because palm and coconut agricultural output swings in Malaysia and Indonesia destabilize surfactant feedstock economics. Mass-market supermarket buyers exhibit the highest price sensitivity, while specialty breeders and exhibition handlers demonstrate minimal elasticity for instrument-verified pH-buffered formulations.
Supply Chain Analysis
EU REACH restrictions on isothiazolinone preservatives and US EPA pyrethrin registration requirements limit cross-border formulation flows, forcing parallel production tracks that fragment supply chain efficiency. Manufacturing concentrates in Germany, the United States, and Japan, with each hub serving distinct regulatory jurisdictions. Raw material dependencies center on Southeast Asian coconut and palm derivatives, synthetic surfactant precursors from Chinese petrochemical complexes, and temperature-sensitive botanical extracts requiring cold-chain integrity. Single-source vulnerability in Southeast Asian agricultural output creates supply risk. Distribution runs through specialty pet retail chains, veterinary clinic networks, and direct-to-consumer subscription platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story because regulatory entrenchment through FDA-medicated claim oversight and EPA pyrethrin registration creates substantial barriers that favor incumbents with dedicated toxicology staff.
For Market Incumbents: Harden formulation-scaled positions by deepening captive toxicology expertise for multi-jurisdiction registration, insulating against contract research organization capacity constraints that delay competitor timelines. Expand backward integration into temperature-sensitive botanical extract sourcing to resolve cold-chain logistics conflicts with mass-market distribution economics. Prioritize certification investment in California extended producer responsibility compliance to capture shelf differentiation from late-adopting rivals.
For New Entrants and Emerging Players: Establish a beachhead in the senior cat dermatology segment across Japan and Western Europe, where veterinary co-development partnerships justify substantial price premiums and incumbent presence remains fragmented. Target waterless foam and dry shampoo formats for urban millennial owners in dense US coastal metropolitan markets, leveraging same-day delivery infrastructure that algorithmic recommendation platforms have already activated. Pursue direct-to-consumer subscription bundling as the primary go-to-market angle, bypassing retail slotting fees that constrain capital-light entrants.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-entrenchment play because overlapping FDA, EPA, and REACH compliance requirements elevate R&D expenditure for multi-market entrants, concentrating returns among established players with dedicated registration staff. Acquisition targets should emphasize formulators with existing toxicology infrastructure and veterinary clinic channel relationships. Monitor state-level packaging sustainability mandates as the inflection signal, as early compliance with recyclable mono-material designs will separate consolidatable assets from stranded capacity.
| Strategic Initiative | Industry Significance |
|---|---|
| Veterinary Clinic Channel Expansion | Professional endorsement validates premium pricing through prescription-adjacent positioning in post-treatment maintenance. |
| REACH-Compliant Reformulation | Clean-label innovation toward biodegradable surfactants captures Western European market access under tightening ECHA restrictions. |
| Subscription Commerce Infrastructure | Direct-to-consumer platforms lock recurring revenue that funds sustained R&D without retail slotting fee burdens. |
| AI-Driven Formulation Matching | Diagnostic apps that photograph coat condition collapse trial-and-error purchase cycles through algorithmic recommendation integration. |
| Mono-Material Packaging Redesign | California extended producer responsibility compliance creates shelf differentiation against competitors with multi-component legacy formats. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with veterinary dermatologists, specialty pet retail category managers, formulation chemists at contract manufacturers, and subscription platform operators; and secondary validation through FDA veterinary drug approvals, EPA pesticide registrations, ECHA REACH Annex XIV authorization lists, and customs trade data for surfactant feedstock flows. Bottom-up segmentation modeling triangulated against top-down market sizing from pet industry association membership and veterinary clinic network expansion metrics.
Forecast inputs included product type segmentation across medicated, hypoallergenic, organic, and deodorizing tiers; application segmentation spanning flea control, skin condition, general hygiene, and shedding reduction; and form segmentation across liquid, foam, spray, and dry shampoo alternatives. CAGRs were derived from regression analysis against pet humanization indices, veterinary clinic channel penetration rates, and subscription commerce adoption curves. Industry-specific forecast inputs incorporated REACH reformulation cycle timelines and EPA registration backlog durations.
Stress conditions across surfactant feedstock price volatility, regulatory registration delays, and dry shampoo substitution rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions about continued pet humanization trajectory and veterinary clinic retail expansion. Material shifts in EU REACH authorization timelines or state-level packaging mandate enforcement would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Fish Based Pet Food Market
Pet Care Products
Pet Molar Bite Toy Market
Pet Care Products
Europe Cat Food Market
Pet Care Products
Smart Connected Pet Collar Market
Pet Care Products
Brazil Pet Food Market
Pet Care Products
Australia Pet Boarding Market
Pet Care Products
Pet Feeder Market
Pet Care Products
Cat Food Toppers Market
Pet Care Products
Pet Oral Care Products Market
Pet Care Products
Netherlands Pet Boarding Market
Pet Care Products
Australia Pet Food Market
Pet Care Products
Pet Car Seat Protectors Market
Pet Care Products
Fresh and Frozen Dog Food Market
Pet Care Products
Dog Boot for Winters Market
Pet Care Products
UAE Pet Boarding Market
Pet Care Products
Dog Treats Market