
 Smart Connected Pet Collar Market | 2026-2036
Smart Connected Pet Collar Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Connected Pet Collar Market Intelligence
Multi-source component procurement is consolidating around vertically integrated electronics suppliers as collar manufacturers seek supply chain resilience. Garmin leverages in-house GPS chipset development to control hardware-software integration. Tractive sustains European manufacturing partnerships while expanding direct-to-consumer channels. Whistle Labs anchors its position through subscription-based location services that generate recurring revenue.
A smart connected pet collar integrates sensors for geolocation, biometrics, and activity telemetry with wireless transceivers in a wearable form factor rated for animal movement and environmental exposure. These devices transmit real-time data to mobile applications, enabling remote monitoring of pet location and physiological status. GPS collars command premium positioning due to satellite chipset costs and continuous connectivity requirements. Bluetooth-based basic collars occupy high-volume, low-margin retail channels. Cellular connectivity segments carry elevated service-attach revenue potential through carrier partnerships.
The FCC mandates SAR testing and equipment authorization for cellular-enabled collars sold in the United States, while the EU Radio Equipment Directive imposes CE marking and spectrum compliance across European markets. Japan's MIC sets additional technical standards for 920 MHz and 2.4 GHz bands used in pet wearables. Stakeholders must monitor evolving spectrum allocation decisions and cybersecurity certification requirements as biometric data collection expands.
Market Dynamics
Cellular-enabled biometric monitoring is compressing product refresh cycles as pet owners expect continuous connectivity upgrades comparable to consumer electronics. This technology pull forces manufacturers to synchronize hardware releases with carrier network evolution.
Growth Catalysts
- Pet care service fleet deployment:Commercial operators managing multiple animals drive volume procurement of GPS-enabled collars with centralized dashboard access.
- FCC equipment authorization pathways:Clear certification timelines for cellular and GPS devices reduce regulatory uncertainty for US market entry.
- Subscription revenue models:Recurring location service fees create predictable cash flows that fund R&D for next-generation sensor integration.
Market Restraints
- Satellite chipset cost concentration:GPS module pricing remains elevated due to limited qualified suppliers in semiconductor fabrication.
- SAR testing compliance burden:FCC-mandated specific absorption rate testing adds certification expense and timeline risk for cellular-enabled models.
- Bluetooth collar substitution:Low-cost proximity trackers satisfy basic location needs for indoor pets, constraining premium GPS adoption in price-sensitive segments.
Strategic Opportunities
- Veterinary telemedicine integration:Biometric data streams from collars enable remote health monitoring partnerships with animal hospitals.
- EU Radio Equipment Directive harmonization:CE marking alignment across member states simplifies multi-country distribution for European expansion.
- Agricultural livestock extension:Ruggedized collar platforms adapt to cattle and sheep monitoring in ranching operations beyond companion animals.
Industry Challenges
- RF engineering talent scarcity:Cellular antenna design expertise for wearable form factors commands premium compensation and extended hiring timelines.
- Multi-band certification complexity:Simultaneous FCC, CE, and MIC approvals for 920 MHz and 2.4 GHz operation strain quality assurance resources.
- Waterproofing durability validation:IP67 and IP68 testing for animal environmental exposure requires specialized equipment and extended protocol development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Connected Pet Collar Market |
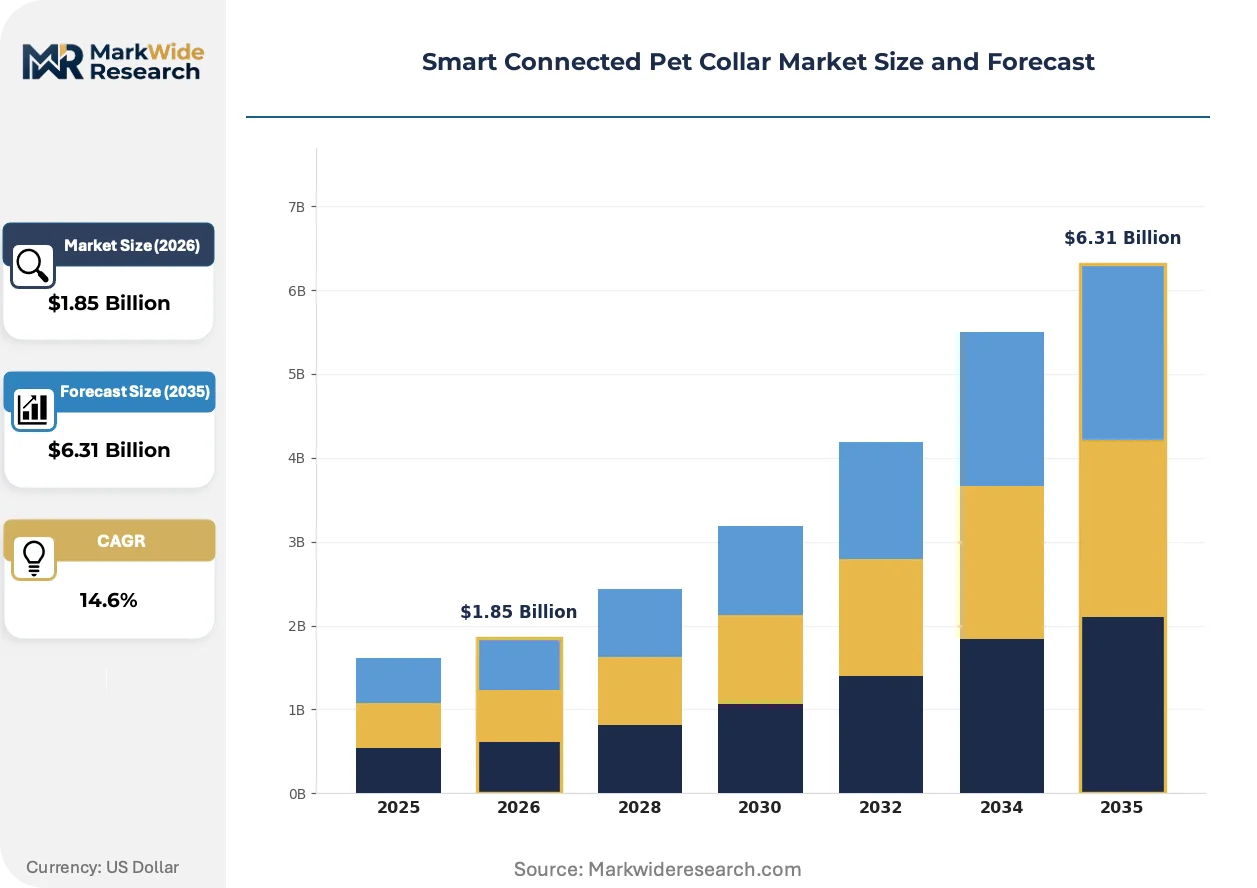
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $6.31 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Basic Collars, GPS Collars, Activity Trackers, Health Monitors Connectivity: Bluetooth, Wi-Fi, Cellular, RFID End User: Pet Owners, Veterinarians, Pet Care Services, Retailers Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Pet Expos |
| Companies Covered | Garmin, Radio Systems Corporation, FitBark, Scollar, Wagz, Tractive, Whistle Labs, Eureka Technology Partners, PetPace, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Connected Pet Collar Market Strategic Shifts & Innovations
Edge computing architectures are migrating biometric processing from cloud servers to collar-mounted chipsets, reducing latency for critical health alerts. This shift reshapes power management priorities and semiconductor selection criteria.
Ultra-wideband positioning chips are decentralizing location accuracy away from GPS dependency for indoor and dense urban environments. Premium collar manufacturers integrate UWB alongside satellite receivers to eliminate dead zones in multi-story buildings. Pet owners in metropolitan apartment complexes now demand sub-meter precision that cellular triangulation cannot deliver.
Japan's MIC spectrum reallocation for 920 MHz LPWAN devices is expanding low-power connectivity options for lightweight collar designs. Manufacturers targeting the Japanese market must recertify existing products under revised technical standards. This regulatory shift favors newer entrants with fresh hardware architectures over legacy platforms requiring redesign.
Direct-to-consumer subscription bundling is displacing retail channel dependency for recurring revenue capture. Whistle Labs and Tractive bypass pet store distribution to own customer relationships and data analytics pipelines. This channel pivot concentrates in North American and Western European markets where e-commerce penetration in pet supplies exceeds 40 percent.
Smart Connected Pet Collar Market Segmentation
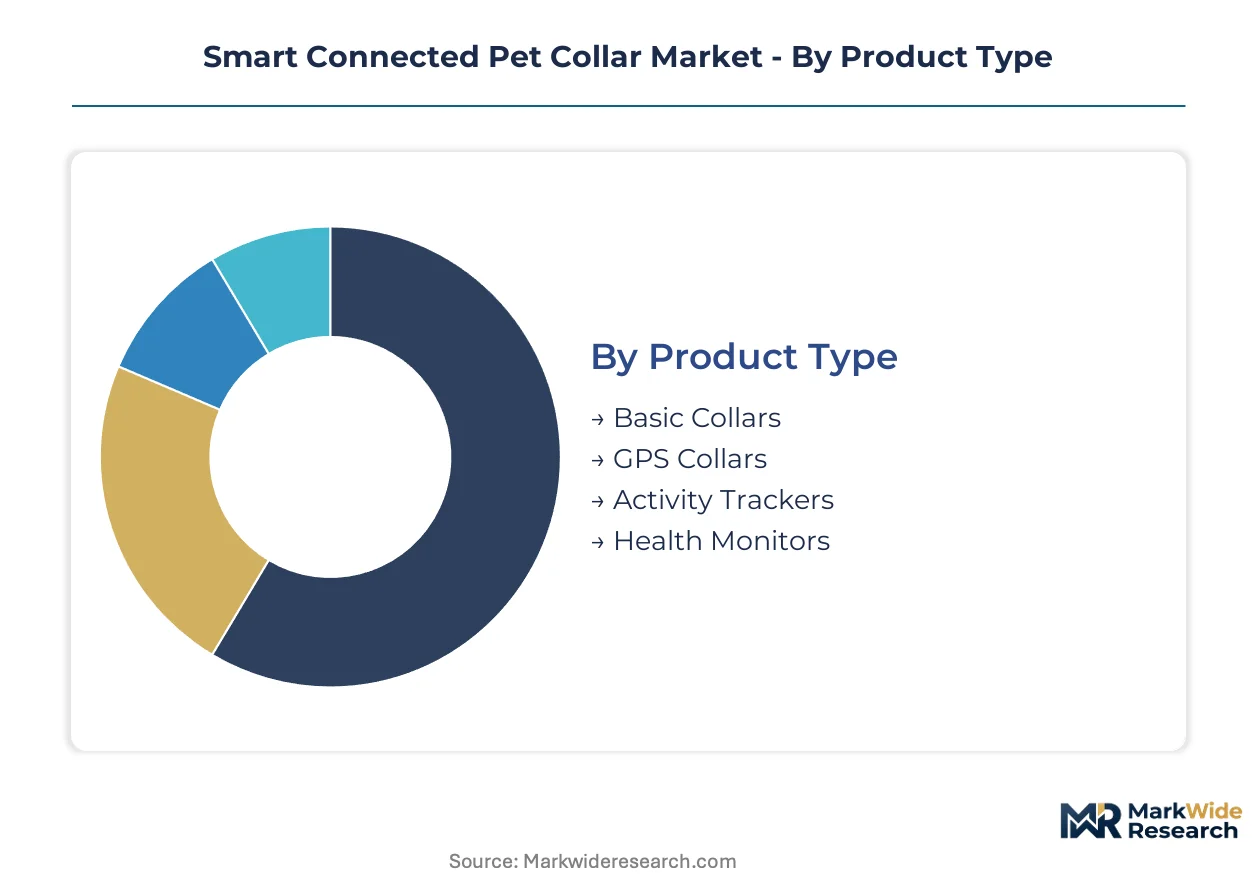
Smart connected pet collar buyers exhibit sharply divergent technical requirements based on use intensity, animal mobility patterns, and data latency tolerance. Understanding these fault lines enables manufacturers to align sensor configurations, connectivity modules, and pricing architectures with distinct purchasing logics rather than forcing uniform product-market fits.
Product Type:
Buyers in this category separate by the depth of biometric insight they require versus their willingness to absorb hardware premiums and recurring service fees.
- Basic Collars:Proximity-only devices using Bluetooth Low Energy for indoor location tracking within 30-meter ranges. Pet owners with strictly indoor cats and apartment-dwelling small dogs concentrate demand here, constrained by price sensitivity that limits attach rates for subscription services.
- GPS Collars:Satellite-receiver-equipped wearables enabling real-time geofencing and escape alerts across unlimited ranges. Rural property owners with hunting dogs and livestock guardian breeds drive procurement, prioritizing ruggedized IP68 enclosures and multi-carrier cellular failover over biometric sensors.
- Activity Trackers:Accelerometer-based devices quantifying step counts, sleep duration, and movement intensity for fitness-conscious pet owners. Urban millennials with companion breeds represent the core demographic, accepting Bluetooth-only models for cost containment.
- Health Monitors:Advanced sensor arrays capturing heart rate variability, respiratory patterns, and temperature fluctuations for early illness detection. Veterinary telemedicine partnerships and insured pet households in North America concentrate adoption, requiring FDA-equivalent data validation for clinical credibility.
Basic collars lead volumes today; health monitors are gaining share fastest.
Connectivity:
Module selection hinges on the trade-off between tracking precision, battery longevity, and total cost of ownership across deployment scenarios.
- Bluetooth:Short-range protocols dominating indoor proximity applications with 6-12 month battery life. Mass-market retail channels in price-sensitive segments sustain volume despite range limitations that disqualify outdoor use cases.
- Wi-Fi:Home-network-dependent tracking for pets confined to residential environments. Smart home integration enthusiasts and multi-pet households seeking consolidated device management drive niche adoption.
- Cellular:LTE-M and NB-IoT modules enabling continuous outdoor tracking independent of paired smartphones. Pet care services managing distributed animal fleets mandate this connectivity tier, accepting monthly carrier fees for centralized dashboard access.
- RFID:Passive tag systems for automated feeding stations and kennel access control. Commercial boarding facilities and automated pet care infrastructure deployments sustain demand despite absence of real-time location capability.
Bluetooth dominates unit economics; cellular is climbing the fastest as fleet deployments scale.
End User:
Procurement authority and data utilization depth vary dramatically across stakeholder types with incompatible purchasing rhythms.
- Pet Owners:Individual consumers making discretionary purchases through retail and direct-to-consumer channels. Emotional attachment to companion animals drives premium willingness for GPS and health monitoring tiers.
- Veterinarians:Clinical practices integrating collar-derived biometric streams into remote patient monitoring protocols. Data interoperability with practice management software and liability considerations shape vendor selection.
- Pet Care Services:Commercial operators including dog walkers, daycare facilities, and boarding kennels deploying collar fleets at scale. Centralized billing, bulk device management APIs, and volume pricing determine procurement outcomes.
- Retailers:Pet supply chains and big-box electronics merchants curating assortment for resale. Margin structure, return rates, and brand marketing support dominate negotiations with manufacturers.
Pet owners generate the revenue base; pet care services are expanding most quickly through fleet standardization.
Distribution Channel:
Channel selection reflects customer acquisition cost tolerance and the strategic priority of owning versus renting customer relationships.
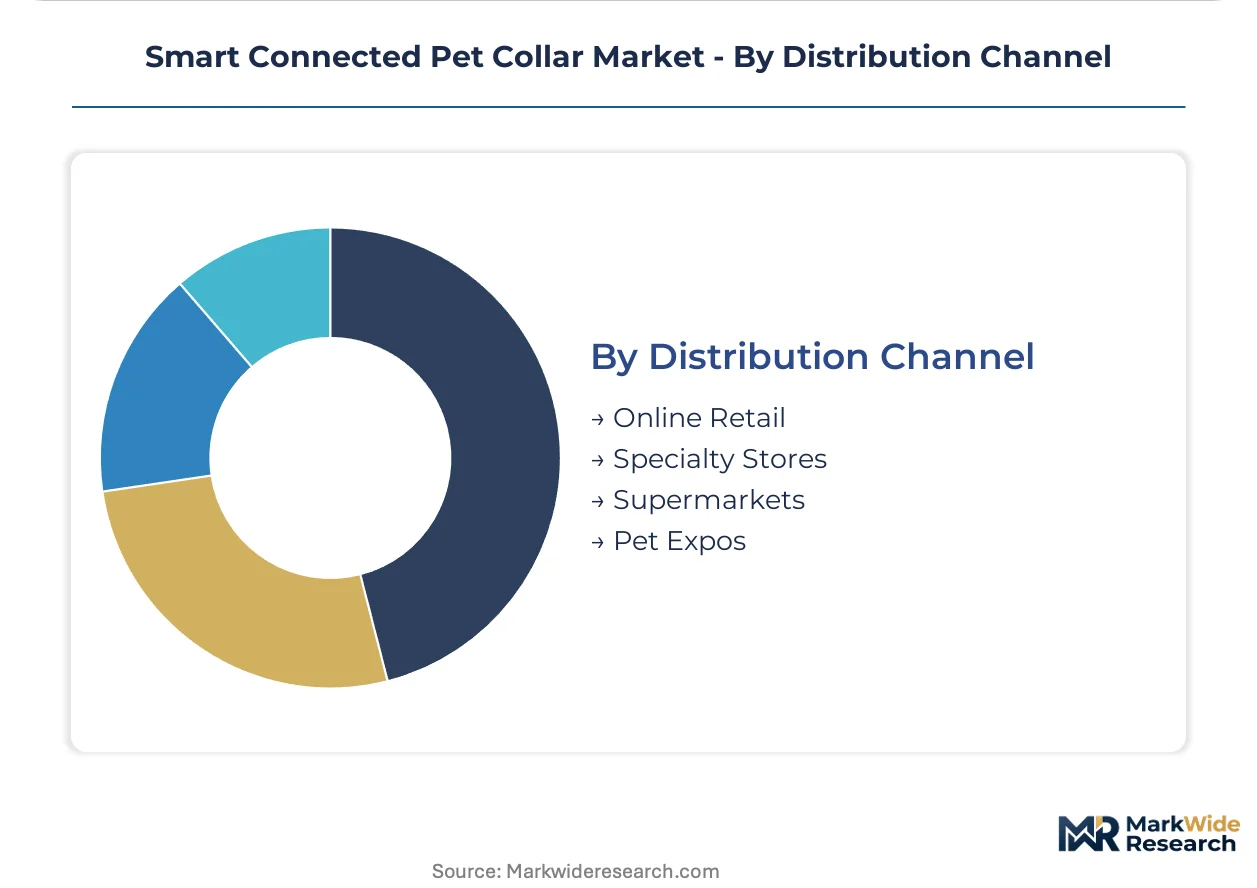
- Online Retail:E-commerce platforms capturing subscription bundling and direct data relationships. North American and Western European markets with 40%+ pet supply digital penetration favor this channel for recurring revenue capture.
- Specialty Stores:Independent pet retailers and veterinary clinic dispensaries providing hands-on fitting and technical support. High-touch service requirements for GPS collar activation sustain this channel's relevance.
- Supermarkets:Mass merchandisers moving basic Bluetooth trackers as impulse purchases alongside pet food. Price compression and limited shelf space constrain premium product placement.
- Pet Expos:Trade show and exhibition circuits enabling product demonstration and breeder network penetration. Working dog communities and breed-specific clubs concentrate attendance for high-performance collar trials.
Online retail commands revenue concentration; pet expos are expanding most quickly for specialized working dog segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley anchors hardware-software integration for collar manufacturers, with venture-backed startups clustering around San Jose and Mountain View to access RF engineering talent pools. Premium pet ownership rates in coastal metropolitan areas sustain early technology adoption curves.
United States
Pet care service fleet operators in Texas and Florida drive volume procurement of GPS-enabled collars for centralized animal management. FCC equipment authorization requirements for cellular and GPS devices create predictable certification timelines that reduce regulatory friction for hardware entrants. Austin and Denver host emerging collar manufacturers leveraging local semiconductor supply chains for rapid prototyping cycles.
Germany
Precision engineering traditions in Bavaria support manufacturing partnerships for European-market collar assembly. EU Radio Equipment Directive harmonization through CE marking simplifies multi-country distribution across member states. Munich engineering firms supply antenna design expertise for wearable form factors requiring multi-band certification.
Japan
Urban apartment dwellers in Tokyo and Osaka demand sub-meter indoor positioning accuracy that drives ultra-wideband chip integration. METI spectrum reallocation for 920 MHz LPWAN devices expands connectivity options for lightweight collar designs. Yokohama electronics clusters host testing facilities for MIC technical standard compliance.
United Kingdom
Insured pet households in London and Southeast England concentrate demand for veterinary telemedicine-integrated health monitors. Post-Brexit regulatory alignment with EU CE marking maintains export pathway continuity for collar manufacturers. Cambridge wearables startups access university research partnerships for biometric sensor development.
Australia
Rural property owners in Queensland and Western Australia prioritize ruggedized GPS collars for working dog and livestock guardian breeds. TGA-equivalent data validation requirements shape clinical credibility standards for health monitoring tier entry. Sydney hosts distribution hubs serving Asia-Pacific expansion for direct-to-consumer subscription models.
Smart Connected Pet Collar Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue veterinary telemedicine integration and agricultural livestock extensions. The vendor base stratifies across three archetypes: vertically integrated electronics suppliers controlling hardware-software integration, subscription service platforms capturing recurring revenue through location services, and specialized biometric sensor developers targeting clinical validation pathways. Competitive positioning hinges on M&A activity consolidating component procurement capabilities and strategic partnerships with cellular carriers for service-attach revenue sharing.
Within the integrated hardware tier, Garmin exemplifies in-house GPS chipset development that compresses product refresh cycles. Tractive occupies a position among European manufacturing partnerships sustaining direct-to-consumer channel expansion. Whistle Labs anchors subscription-based location service models that generate predictable cash flows funding R&D for next-generation sensor integration.
| Leading Market Players |
|---|
| Garmin |
| Radio Systems Corporation |
| FitBark |
| Scollar |
| Wagz |
| Tractive |
| Whistle Labs |
| Eureka Technology Partners |
| PetPace |
| Others |
Cost & Logistics Intelligence
Certification-grade bifurcation between FCC-authorized cellular collars and uncertified Bluetooth proximity devices creates divergent margin structures that reshape component sourcing strategies. Premium GPS-enabled models absorb satellite chipset premiums through subscription bundling, while basic collar manufacturers squeeze supplier payment terms to maintain retail price points.
Pricing Analysis
Input-cost pass-through from GPS module suppliers concentrates in the cellular-enabled tier, where Qualcomm and u-blox chipset pricing directly determines hardware margins. Three-tier pricing structure across premium, standard, and economy levels separates veterinary-validated health monitors from consumer GPS trackers from basic Bluetooth proximity devices. Pricing pressure stems from low-cost Asian manufacturers flooding retail channels with unbranded Bluetooth alternatives. Pet care services exhibit lowest price sensitivity due to fleet-scale procurement and centralized billing economics.
Supply Chain Analysis
Direct-to-consumer channels handle hyperscale subscription bundling, while pet specialty retailers manage high-touch GPS activation support for individual buyers. Manufacturing concentrates in China for PCB assembly, Taiwan for GPS chipset fabrication, and Germany for precision antenna engineering. Raw material dependencies include lithium-polymer batteries, ceramic antenna substrates, and medical-grade silicone housings. Single-source vulnerability in satellite receiver modules poses the dominant structural risk. Distribution runs through vertically integrated electronics suppliers serving both OEM collar manufacturers and white-label assemblers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage opportunities emerge between FCC certification timelines in the United States and CE marking harmonization across European Union member states, where regulatory cost differentials favor early EU market entry before US authorization completion.
For Market Incumbents: Deepen captive supply arrangements for GPS chipsets to insulate margins from semiconductor allocation volatility. Lock in multi-year carrier partnership renewals before 5G network migration raises module recertification costs. Defensive positioning requires accelerating veterinary telemedicine software integration to preempt pure-play health monitoring entrants from capturing clinical data relationships. For New Entrants and Emerging Players: Direct-to-veterinarian digital platforms offer the most penetrable route for health monitor tier entry, bypassing saturated retail shelf competition. Target Australian and Japanese markets where TGA-equivalent and MIC compliance requirements have delayed incumbent product refresh cycles. Subscription-first customer acquisition through telemedicine partnerships reduces customer acquisition cost versus retail channel dependency. For Investors and Strategic Acquirers: Consolidation pressure builds where subscription revenue concentration meets hardware commoditization vulnerability. Long-term viability favors platforms owning recurring location service cash flows over pure hardware manufacturers exposed to chipset cost volatility. Acquisition target archetype: cellular-enabled collar vendors with established carrier billing integrations and 50,000+ active subscriber bases. Watch for FCC spectrum reallocation decisions affecting 920 MHz LPWAN device certification timelines as inflection indicators for hardware refresh cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Veterinary Telemedicine Partnership | Clinical data integration with animal hospital networks validates health monitor tier credibility. |
| Carrier Billing Integration | Direct subscription embedding with Verizon and AT&T reduces customer payment friction. |
| UWB Chipset Adoption | Ultra-wideband positioning addresses indoor accuracy gaps that GPS cannot resolve. |
| EU CE Marking Harmonization | Unified certification across member states accelerates multi-country distribution scaling. |
| Agricultural Livestock Extension | Ruggedized platform adaptation opens cattle and sheep monitoring beyond companion animals. |
Research Approach
Direct dialogue with collar hardware engineers, pet care service fleet operators, veterinary telemedicine platform executives, and cellular carrier IoT partnership managers grounded qualitative insights. Secondary validation drew from FCC equipment authorization databases, EU Radio Equipment Directive notification files, carrier IoT deployment disclosures, and pet insurance industry actuarial reports. Bottom-up unit shipment modeling triangulated against top-down service revenue estimates across the analysis window.
Segment-level projections incorporated connectivity module pricing trajectories, carrier subscription attach rate assumptions, and regional pet ownership density variations. The analytical framework modeled product type, connectivity protocol, end-user archetype, and distribution channel dimensions throughout the forecast period. CAGRs derived from logistic adoption curve fitting for cellular-enabled tiers and linear extrapolation for mature Bluetooth segments. Veterinary partnership penetration rates and agricultural livestock extension adoption curves served as industry-specific forecast inputs.
Spectrum reallocation decisions, carrier pricing plan restructuring, and veterinary regulatory data validation requirements are the dominant revision risks for forecast accuracy. Base case assumptions include stable FCC authorization timelines and continued CE marking mutual recognition. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
South America Dog Food Market
Pet Care Products
Europe Dog Food Market
Pet Care Products
Dog Vest Market
Pet Care Products
Animal-Based Pet Protein Market
Pet Care Products
Pet Perfume Market
Pet Care Products
United States Organic and Natural Pet Food Market
Pet Care Products
UK Pet Training Services Market
Pet Care Products
Cat Shampoo Market
Pet Care Products
China Pet Food Market
Pet Care Products
India Pet Clothing Market
Pet Care Products
Canada Pet Food Market
Pet Care Products
Dog Bowl Market
Pet Care Products
GCC Organic and Natural Pet Food Market
Pet Care Products
Australia Pet Boarding Market
Pet Care Products
Fresh and Frozen Dog Food Market
Pet Care Products
Pet Grooming Services Market