
 Dog Boot for Winters Market | 2026-2036
Dog Boot for Winters Market Size, Share, and Industry Trends Forecast 2026-2036
Dog Boot for Winters Market Analytics
Vietnam is narrowing its position as a contract manufacturing hub for winter dog footwear, with several factories near Ho Chi Minh City now serving North American and European brands. Ruffwear leverages vertical integration by controlling design and final assembly at its Oregon headquarters while sourcing components from Asian suppliers. Canada Pooch anchors its competitive stance through cold-weather specialization rooted in Toronto's climate conditions. Muttluks competes on heritage craftsmanship, sustaining decades of made-in-Canada production for premium fleece-lined models.
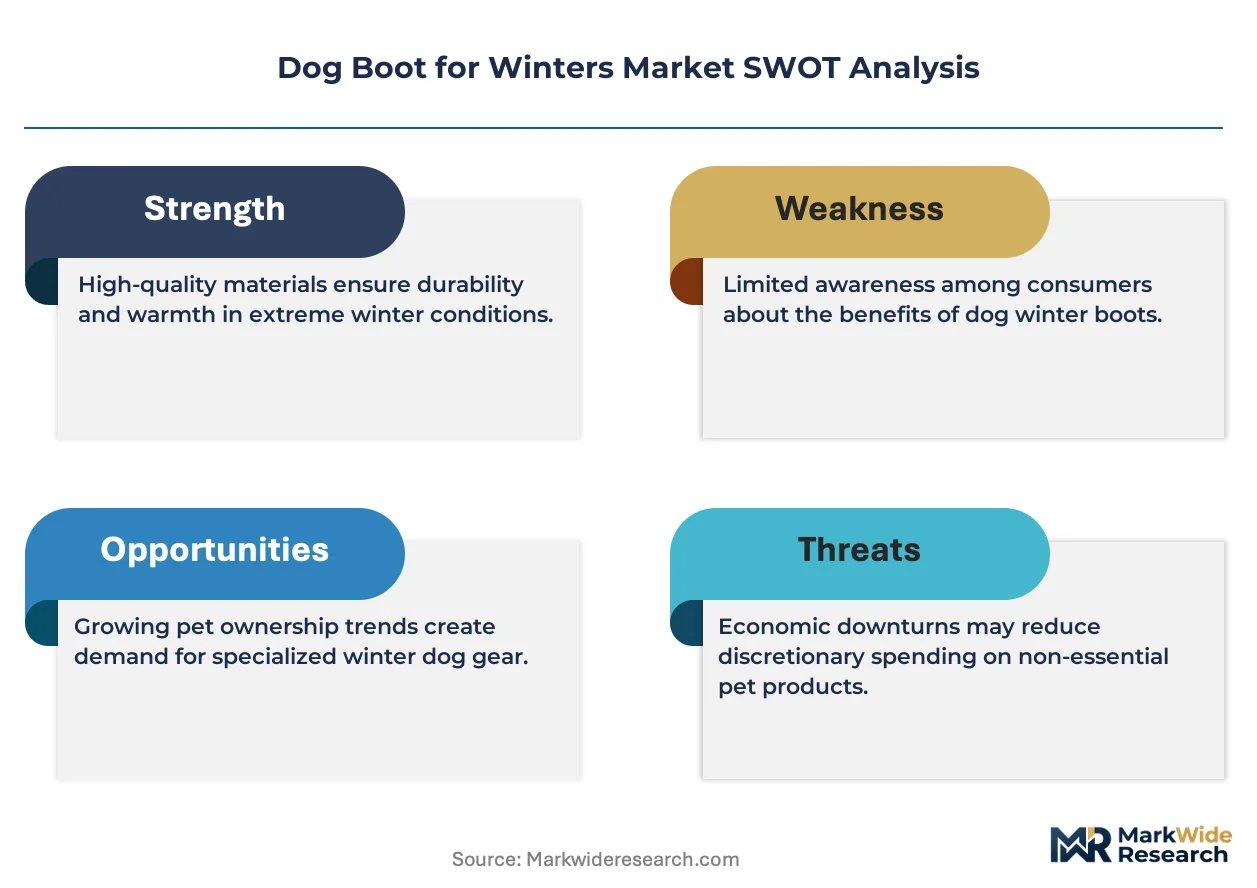
Dog boots for winters are protective footwear assemblies engineered to shield canine paws from ice, salt, chemical de-icers, and thermal loss, typically constructed with rubberized soles, neoprene uppers, and adjustable closure systems rated for sub-freezing temperatures. Their primary commercial purpose is injury prevention and mobility maintenance for working dogs, sporting breeds, and companion animals exposed to harsh winter environments. Waterproof product types currently lead volume shipments, though reflective variants are gaining traction among urban evening walkers seeking visibility compliance. Neoprene material segments command margin premiums due to superior cold-flex performance compared to standard rubber formulations, while the pet owner end-user category dominates direct-to-consumer channel economics.
The US Consumer Product Safety Commission monitors choking and chemical exposure risks in pet accessories, while the EU's REACH regulation governs restricted substances in rubber and synthetic components entering European markets. Health Canada and the EPA jointly influence material standards through chemical safety assessments and environmental discharge rules affecting neoprene processing facilities. Stakeholders must monitor evolving state-level pet product safety bills and biodegradable material mandates that could reshape sourcing requirements and reformulation timelines.
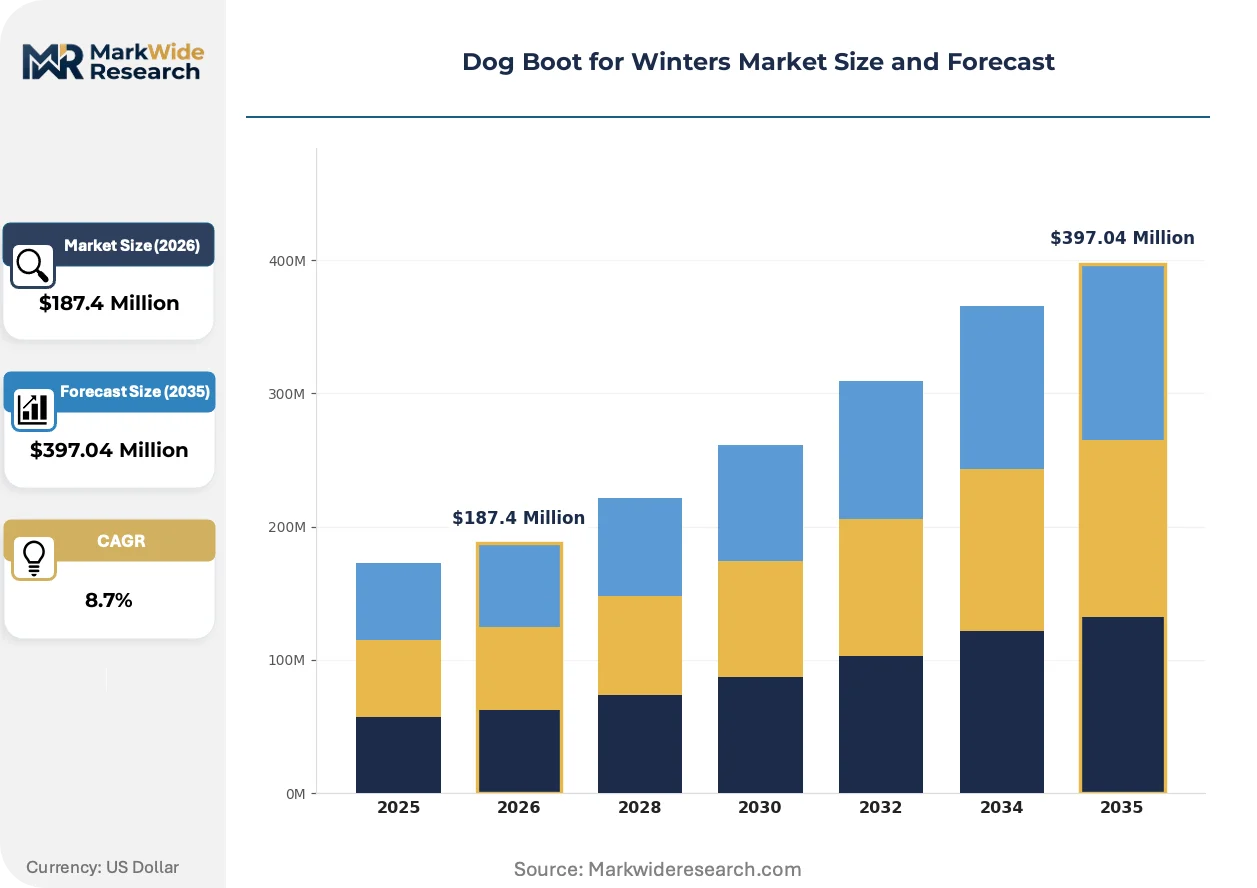
Market Dynamics
Neoprene's displacement of rubber formulations under REACH chemical restrictions is restructuring material procurement and supplier qualification timelines across winter dog footwear manufacturing.
Growth Catalysts
- REACH chemical safety framework:The EU's restriction of certain rubber additives accelerates neoprene adoption, creating premium positioning opportunities for compliant manufacturers.
- Cold-climate suburban pet owners:This demographic segment drives sustained replacement demand through active outdoor dog culture and year-round boot usage patterns.
- Reflective visibility technology:Urban evening walkers seeking safety compliance generate incremental demand for specialized reflective boot variants.
Market Restraints
- Neoprene supply concentration:Asian processing facilities face EPA discharge scrutiny, creating input volatility for North American and European brands.
- REACH reformulation costs:Chemical safety testing and material requalification impose structural cost burdens on smaller manufacturers.
- DIY paw protection alternatives:Petroleum jelly and disposable sock solutions constrain price elasticity at the economy tier.
Strategic Opportunities
- Biodegradable material mandates:Anticipated state-level pet product safety legislation creates first-mover advantage for bio-based sole formulations.
- Vietnam contract manufacturing expansion:Ho Chi Minh City factories offer cost-competitive production capacity for North American brand outsourcing.
- Direct-to-consumer channel maturation:E-commerce platforms enable margin capture previously lost to specialty pet retail intermediaries.
Industry Challenges
- Canine biomechanics expertise shortage:Veterinary orthopedic consultation for proper boot fit remains scarce, elevating return rates.
- Multi-regulatory certification timelines:Simultaneous US CPSC, EPA, and REACH compliance stretches product development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dog Boot for Winters Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Waterproof, Insulated, Non-slip, Reflective Material: Rubber, Neoprene, Cordura, Fleece Size: Small, Medium, Large, Extra Large End User: Pet Owners, Dog Trainers, Veterinarians, Shelters |
| Companies Covered | Ruffwear, Canada Pooch, Qumy, Non-stop Dogwear, Walkee Paws, Wagwear, Muttluks, Wilderdog, Kurgo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dog Boot for Winters Market Evolving Landscape
Material science advances and regulatory chemistry constraints are converging to transform how winter dog boots are engineered, tested, and brought to market across temperate climate zones.
Smart temperature-sensing insoles embedded with flexible electronics is virtualizing the traditional passive insulation model. Sporting breed owners and working dog handlers in Minnesota and Michigan are piloting these connected variants. The technology is virtualizing quality assurance by enabling real-time thermal performance verification rather than post-manufacture batch testing.
REACH's evolving restricted substances list continues tightening allowable rubber additives in pet products entering European markets. Manufacturers reformulating with neoprene alternatives face extended ECHA notification periods. Premium fleece-lined models bear disproportionate compliance burden due to multi-material construction complexity.
Subscription-based replacement programs are displacing transactional retail purchasing among dedicated outdoor dog enthusiasts. Specialty pet retailers in Toronto and Vancouver are unbundling after-sales fit consultation from product margin. Northern United States metropolitan areas show highest adoption velocity for this recurring revenue model.
Dog Boot for Winters Market Segmentation
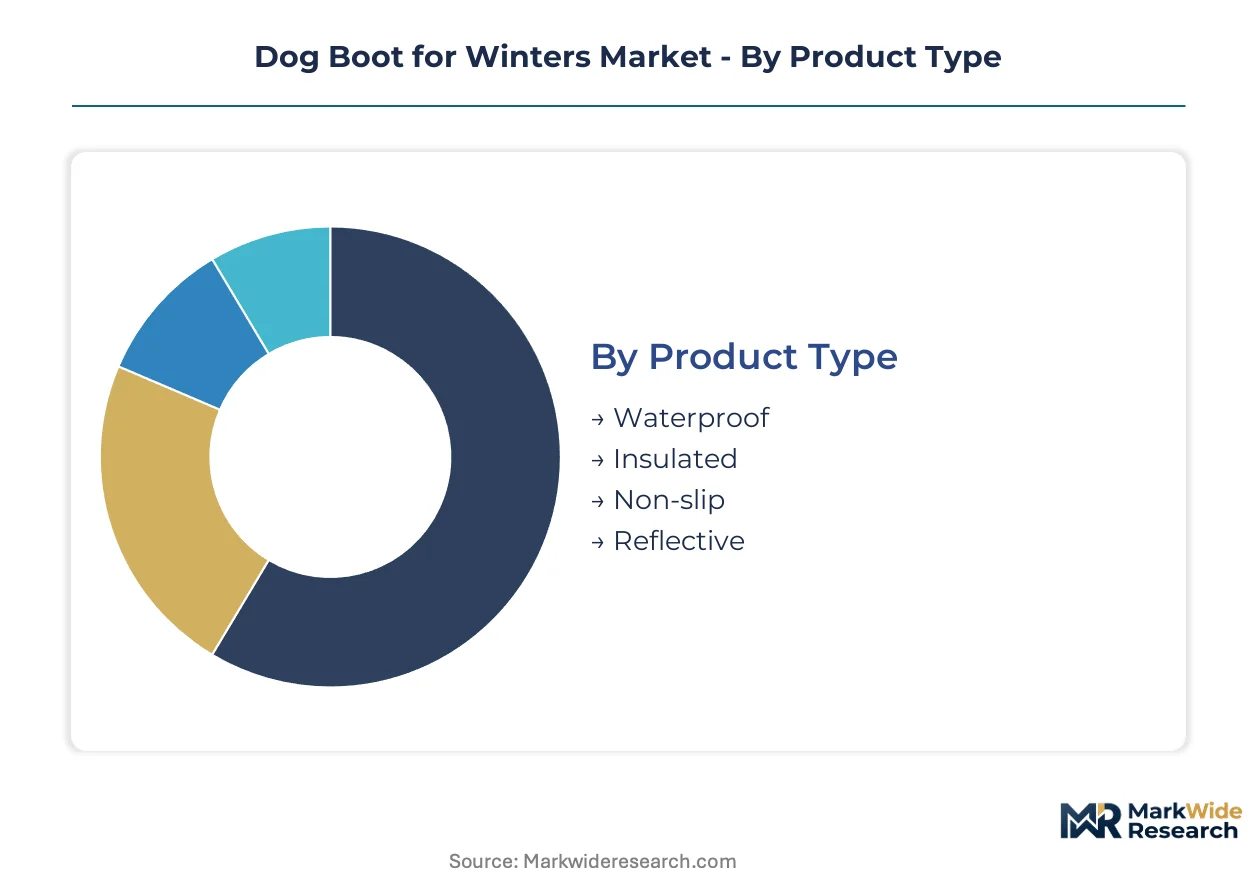
Dog boot segmentation reflects divergent performance requirements across climate severity, activity intensity, and owner compliance obligations. Material chemistry and closure engineering create distinct value tiers that reshape procurement patterns among cold-climate suburban households.
Product Type:
Use-case spectrum spans passive protection for urban sidewalk walks to active thermal management for working dogs in sub-zero field conditions.
- Waterproof:Laminated membrane construction with sealed seams blocks melted snow and salt slurry penetration. Demand concentrates in Minnesota and Michigan where municipal de-icer exposure is highest, driven by paw pad chemical burn prevention.
- Reflective:Retroreflective striping integrated into upper panels and closure straps enhances twilight visibility for urban evening walkers. Toronto and Vancouver metropolitan areas show steepest adoption velocity among safety-conscious owners navigating dimly lit winter streets.
- Insulated:Synthetic loft or thermal batting layers rated for extended sub-freezing exposure.
- Non-slip:Tread pattern engineering prioritizes ice grip over deep snow flotation.
The dominant share belongs to Waterproof, while Reflective is closing the gap fastest.
Material:
Cost tier stratification separates REACH-compliant premium formulations from commodity rubber alternatives facing regulatory displacement.
- Neoprene:Closed-cell synthetic rubber delivers superior cold-flex performance without cracking at temperatures below negative twenty degrees Fahrenheit. Cold-climate suburban pet owners in northern United States drive margin premiums, compelled by EU chemical safety frameworks restricting traditional rubber additives.
- Rubber:Natural and synthetic vulcanized compounds face ECHA notification burdens under evolving restricted substances lists. Reformulation timelines and testing costs concentrate burden on smaller manufacturers lacking dedicated compliance infrastructure.
- Cordura:Ballistic nylon weave provides abrasion resistance for active sporting breeds.
- Fleece:Synthetic pile lining enhances thermal retention in premium fleece-lined models.
Neoprene commands the pricing premium, while Fleece is gaining share fastest among heritage craftsmanship positioning.
Size:
Volume distribution tracks breed ownership demographics across working dog, sporting, and companion animal categories.
- Large:Engineered for German Shepherds, Huskies, and Labrador Retrievers with paw width exceeding three inches. Demand clusters in Michigan and Minnesota where large-breed active outdoor dog culture sustains year-round replacement cycles.
- Medium:Serves Border Collies, Australian Shepherds, and mid-size sporting breeds with standardized fit protocols.
- Small:Addresses Terrier breeds and companion animals under twenty-five pounds.
- Extra Large:Custom patterning for Great Danes, Mastiffs, and giant breed working dogs.
Large holds the dominant share, while Extra Large is expanding most quickly through specialized veterinary orthopedic consultation channels.
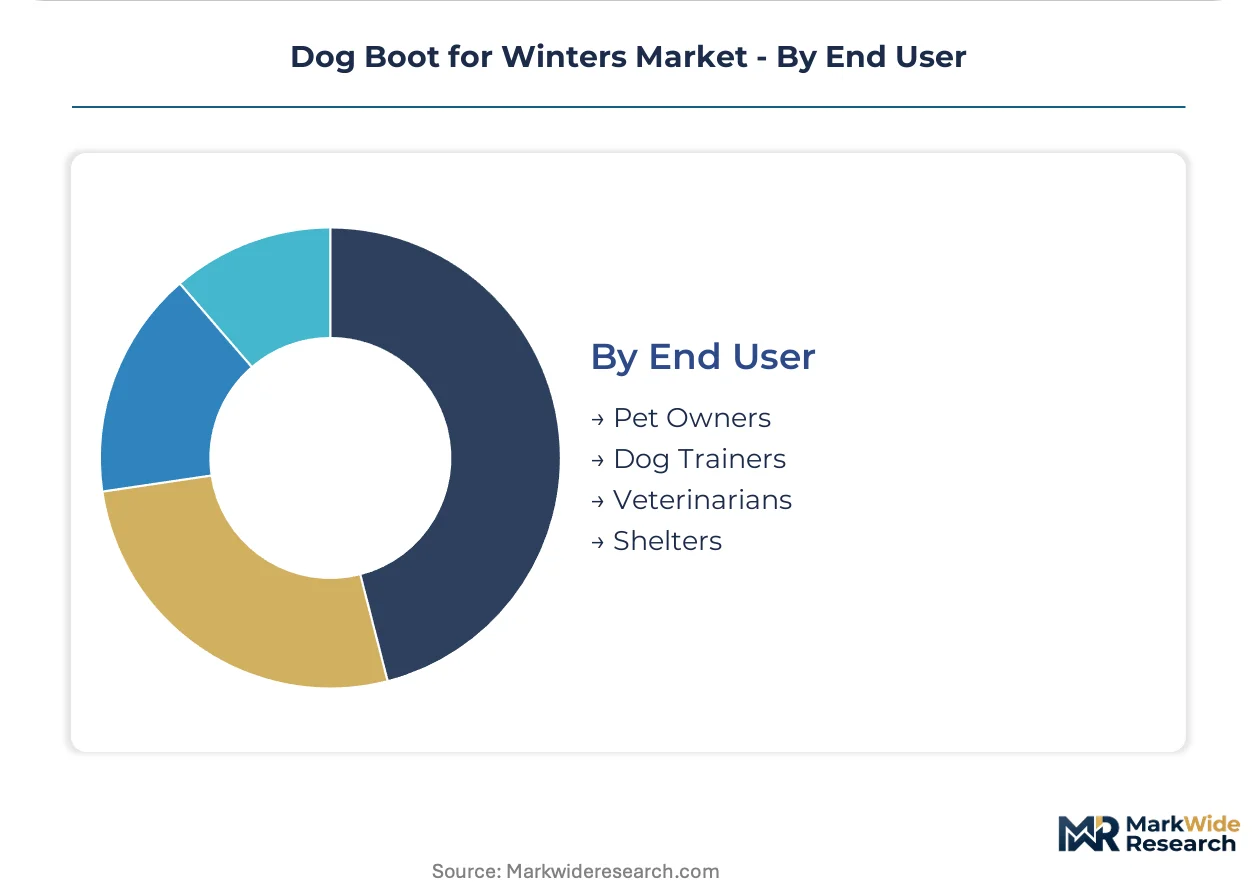
End User:
Customer type determines channel economics and after-sales service intensity, from transactional retail to subscription-based replacement programs.
- Pet Owners:Direct-to-consumer purchasers prioritize fit consultation and return policy flexibility. Subscription-based replacement programs are displacing transactional retail among dedicated outdoor dog enthusiasts in northern United States metropolitan areas.
- Dog Trainers:Professional handlers require standardized fleet sizing for multiple animals with consistent performance specifications.
- Veterinarians:Clinical recommendation drives therapeutic boot adoption for post-surgical recovery and mobility maintenance.
- Shelters:Volume procurement of economy-tier disposable solutions for temporary protection during transport.
Pet Owners dominate channel economics, while Dog Trainers are climbing the fastest through professional handler certification expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EPA and US CPSC jointly govern material safety standards for pet accessories entering the North American market, creating compliance baselines that ripple through manufacturing decisions in Asia and Europe.
United States
Minnesota and Michigan metropolitan areas sustain the highest per-capita consumption rates due to sub-zero winter conditions and active outdoor dog culture. The EPA monitors neoprene processing discharge from facilities supplying North American brands. Oregon hosts Ruffwear's design and final assembly operations, anchoring domestic production control while Asian suppliers provide components.
Canada
Toronto's climate conditions anchor Canada Pooch's cold-weather specialization heritage, while Vancouver and Toronto drive reflective boot adoption among urban evening walkers. Health Canada and the EPA jointly influence material standards through chemical safety assessments. Ontario-based Muttluks sustains decades of made-in-Canada production for premium fleece-lined models.
Germany
ECHA notification periods under REACH's evolving restricted substances list burden manufacturers reformulating rubber additives toward neoprene alternatives. The EU's chemical safety framework accelerates premium positioning for compliant producers. Berlin and Munich metropolitan clusters concentrate distribution logistics for Central European cold-climate pet owner demand.
Vietnam
Factories near Ho Chi Minh City now serve North American and European brands seeking cost-competitive contract manufacturing capacity. The country's processing facilities face indirect EPA scrutiny through environmental discharge rules affecting neoprene supply chains. Vietnamese production capacity is narrowing the region's position as an alternative to Chinese manufacturing concentration.
United Kingdom
Urban dog ownership in London and Manchester generates steady demand for waterproof variants addressing salt and chemical de-icer exposure. REACH compliance requirements govern all rubber and synthetic components entering British markets through post-Brexit retained EU law. Specialist retailers in Edinburgh and Glasgow concentrate heritage craftsmanship positioning for premium thermal models.
Dog Boot for Winters Market Competitive Landscape
Capability concentration sits with heritage craftsmanship specialists; scale advantage sits with vertically integrated outdoor equipment brands. The vendor base separates into three functional tiers: design-anchored premium specialists, contract-manufacturing-dependent direct-to-consumer brands, and diversified pet accessory portfolios. Two dominant competitive moves are reshaping positioning: backward integration into component sourcing control and geographic expansion through Vietnam-based production partnerships.
Within the heritage craftsmanship tier, Muttluks and Canada Pooch occupy positions defined by decades-long domestic production continuity and climate-rooted specialization. Among outdoor equipment specialists, Ruffwear exemplifies the vertically integrated model controlling design and final assembly while managing Asian supplier relationships. These three named entities anchor the competitive spectrum from boutique heritage positioning to scaled multi-channel distribution.
| Leading Market Players |
|---|
| Ruffwear |
| Canada Pooch |
| Qumy |
| Non-stop Dogwear |
| Walkee Paws |
| Wagwear |
| Muttluks |
| Wilderdog |
| Kurgo |
| Others |
Value Network & Pricing Analysis
Ho Chi Minh City factory overcapacity is compressing contract manufacturing quotes while simultaneously elevating pricing power for REACH-compliant neoprene suppliers facing EPA discharge scrutiny. This utilization asymmetry rewards brands with dual-source qualification capabilities and squeezes single-source dependent competitors.
Pricing Analysis
Geographic price spreads separate Vietnam-assembled economy tiers from Oregon-finished premium lines by roughly two-to-one multiples. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification burden and after-sales bundling intensity. Pricing pressure stems from DIY petroleum jelly alternatives constraining ceiling elasticity at the entry tier. Cold-climate suburban pet owners show lowest price sensitivity, while shelter procurement managers operate at highest elasticity.
Supply Chain Analysis
Contract manufacturing concentration sits with Ho Chi Minh City factories serving North American and European brand outsourcing. Vietnam, China, and Canada anchor geographic supply concentration for assembly, component molding, and heritage finishing respectively. Raw material dependencies center on neoprene sheet stock, reflective striping polymers, and fleece thermal batting. Single-source vulnerability runs through Asian neoprene processors facing EPA environmental discharge rules. Distribution runs through specialty pet retail intermediaries and direct-to-consumer e-commerce platforms in parallel channel structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Veterinary orthopedic consultation scarcity elevates return rates and erodes lifetime customer value, making fit-technology ownership a decisive competitive moat rather than a service add-on.
For Market Incumbents: Entrench through backward integration into neoprene component sourcing and captive supply of smart insole electronics. REACH reformulation cost burdens threaten smaller competitors lacking dedicated ECHA notification infrastructure. Certification investment in biodegradable sole pre-qualification creates regulatory optionality against pending state-level mandates. For New Entrants and Emerging Players: German metropolitan clusters show underpenetration relative to their cold-climate pet ownership density and REACH compliance sophistication. White-space targets include subscription-based replacement programs for urban evening walkers and veterinary orthopedic channel partnerships for post-surgical recovery applications. Go-to-market through Berlin and Munich specialty retailers unbundles fit consultation from product margin. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among direct-to-consumer brands with subscription replacement programs serving northern United States metropolitan areas. Long-term viability across the analysis window favors acquisition targets with Vietnam production partnerships and REACH-compliant material qualification already embedded. The signal to watch is EPA enforcement intensity against neoprene discharge facilities as inflection indicator for input cost volatility.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Neoprene Sourcing | REACH compliance timelines compress for brands controlling upstream material qualification. |
| Smart Temperature-Sensing Insole Launch | Minnesota and Michigan sporting breed owners pilot connected variants for thermal verification. |
| Subscription Replacement Program Rollout | Toronto and Vancouver retailers unbundle after-sales fit consultation from product margin. |
| Biodegradable Sole Pre-Qualification | State-level pet product safety legislation creates first-mover advantage for bio-based formulations. |
| Vietnam Manufacturing Partnership Expansion | Ho Chi Minh City factories offer cost-competitive capacity alternative to Chinese concentration. |
Research Methodology
A spread of perspectives from brand product managers, contract manufacturing procurement leads, veterinary orthopedic specialists, and specialty pet retail category buyers converged on the working assumptions. Primary interviews combined with secondary validation against EPA discharge records, ECHA notification databases, customs trade data, and specialty retail point-of-sale audits. Bottom-up unit economics triangulated against top-down cold-climate household penetration models.
Demand-supply-balance framing anchored volume projections across product type, material chemistry, size tier, and end-user channel dimensions throughout the forecast period. CAGRs derived from replacement cycle frequency analysis and subscription program adoption velocity curves. Industry-specific inputs included municipal de-icer exposure indices and active outdoor dog culture participation rates.
The forecast holds incumbent behavior within observed patterns; aggressive moves by vertically integrated outdoor equipment brands would shift outcomes through accelerated smart insole deployment. Forecasts reflect assumptions of stable REACH substance restriction timelines and moderate EPA enforcement intensity. Quarterly review of neoprene processor discharge compliance rates and state-level biodegradable mandate legislative progress is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Pet Collar Market
Pet Care Products
Dog Hoodies Market
Pet Care Products
India Pet Food Market
Pet Care Products
Dry Dog Food Market
Pet Care Products
Pet Grooming Products Market
Pet Care Products
Pet Grooming Services Market
Pet Care Products
Japan Pet Clothing Market
Pet Care Products
Pet Sitting Market
Pet Care Products
UK Pet Training Services Market
Pet Care Products
Outdoor Dog Bed Market
Pet Care Products
Thunder Jacket for Dogs Market
Pet Care Products
US Pet Food Market
Pet Care Products
Indonesia Pet Food Market
Pet Care Products
Outdoor Pet Backpack Market
Pet Care Products
Pet Fitness Care Market
Pet Care Products
Cat Litter Product Market