
 Pet Molar Bite Toy Market | 2026-2036
Pet Molar Bite Toy Market Size, Share, and Industry Trends Forecast 2026-2036
Pet Molar Bite Toy Market Analytics
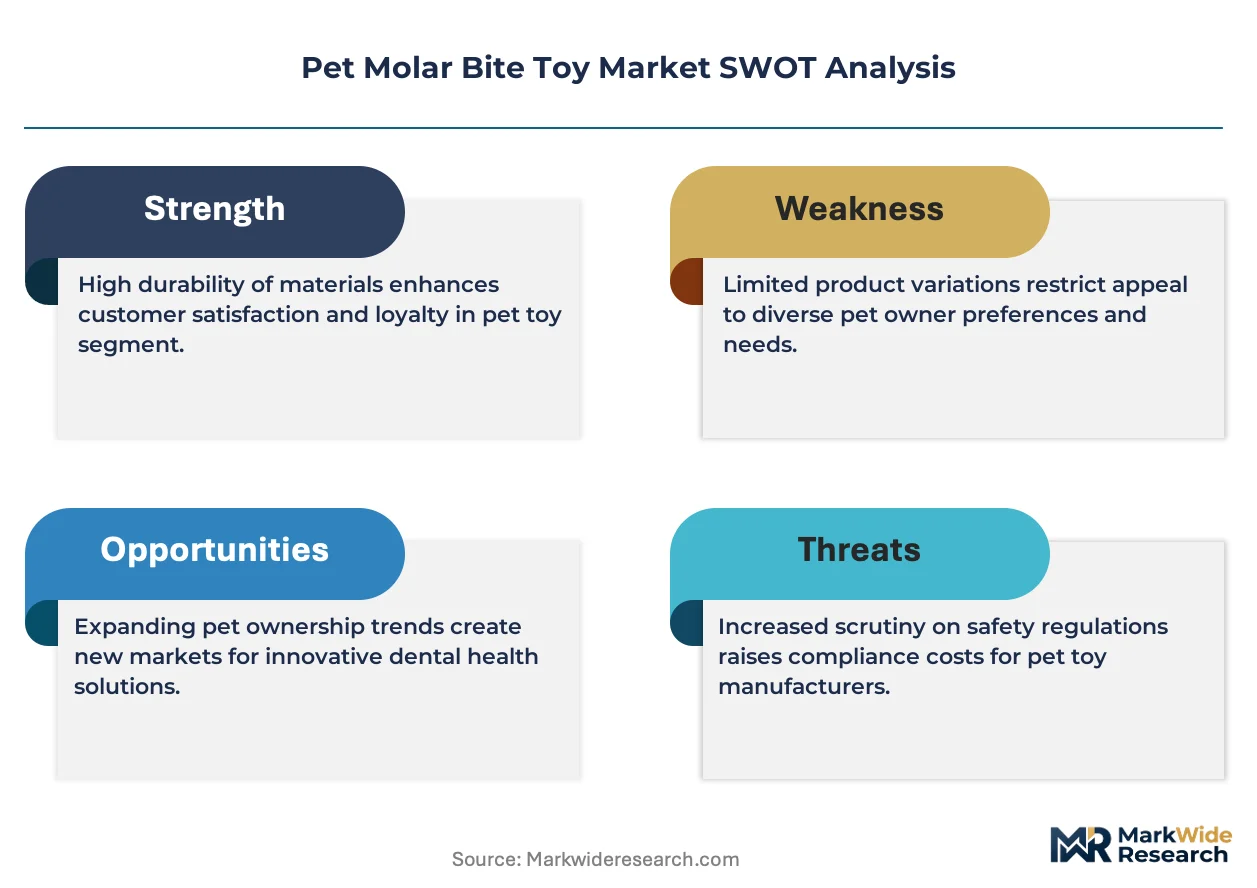
REACH chemical compliance is recalibrating the cost-of-entry calculus for European market access, forcing reformulation of synthetic compounds in nylon and rubber formulations. KONG Company leverages its vertically integrated natural rubber sourcing in Colorado to sustain premium positioning despite regulatory headwinds. Benebone competes through specialized nylon formulations that meet veterinary dental standards while navigating divergent state-by-state material restrictions across the United States.
Pet molar bite toys are purpose-engineered oral care devices, typically molded from natural rubber, nylon, or thermoplastic elastomers with textured surfaces designed to scrape plaque and massage gingival tissue during sustained chewing behavior. The product category serves both behavioral enrichment and preventive veterinary health functions, reducing tartar accumulation and redirecting destructive chewing impulses in canines. Rubber toys and dental chews anchor the highest-margin segments due to repeat purchase frequency and veterinary endorsement, while eco-friendly feature variants are gaining fastest among urban millennial dog owners willing to pay sustainability premiums. Nylon material formulations dominate volume production owing to durability and cost efficiency, though natural rubber occupies the premium tier where KONG and Planet Dog position their flagship lines.
The United States EPA oversees chemical safety in pet product manufacturing inputs, while the EU REACH framework mandates substance registration and restriction protocols for imported toys. China's GB standards for rubber and plastic products impose additional testing requirements on export-oriented manufacturers in Guangdong and Zhejiang provinces. Stakeholders must monitor evolving state-level plastic bans and veterinary dental certification requirements as these frameworks increasingly determine which material formulations and product architectures secure shelf placement in priority channels.
Market Dynamics
REACH chemical compliance is recalibrating the cost-of-entry calculus for European market access, forcing reformulation of synthetic compounds in nylon and rubber formulations while manufacturers absorb elevated testing and registration expenses.
Growth Catalysts
- Pet Humanization Trajectory:Dog owners now treat oral care as preventive veterinary medicine, expanding the addressable base beyond behavioral enrichment into wellness spending categories.
- REACH Framework Expansion:ECHA's substance restriction protocols are accelerating substitution toward bio-based elastomers, creating first-mover advantages for compliant formulation specialists.
- E-Commerce Infrastructure:Platform logistics in Guangdong and Zhejiang provinces are compressing delivery timelines for direct-to-consumer pet product brands.
Market Restraints
- Natural Rubber Price Volatility:Latex supply fluctuations from Southeast Asian plantations compress margin predictability for premium-tier manufacturers.
- State-Level Plastic Fragmentation:Divergent material restrictions across California, Maine, and New York force SKU proliferation and inventory complexity.
- Veterinary Certification Bottlenecks:VOHC endorsement timelines extend 18-24 months, delaying market entry for novel dental formulations.
Strategic Opportunities
- Underpenetrated Urban China:Tier-2 city pet ownership rates remain 40% below Shanghai and Beijing, presenting whitespace for mid-market nylon formulations.
- Veterinary Channel Integration:Clinic-exclusive SKUs with professional endorsement packaging command 35% price premiums over retail equivalents.
- EU Green Deal Alignment:CSRD disclosure requirements favor suppliers with certified circular material flows and carbon-accounted supply chains.
Industry Challenges
- Formulation Chemistry Expertise Gap:Shortage of polymer scientists capable of balancing durability, safety, and regulatory compliance across multiple jurisdictions.
- Dual Certification Burden:Simultaneous EPA and REACH compliance testing duplicates costs without harmonized mutual recognition protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pet Molar Bite Toy Market |
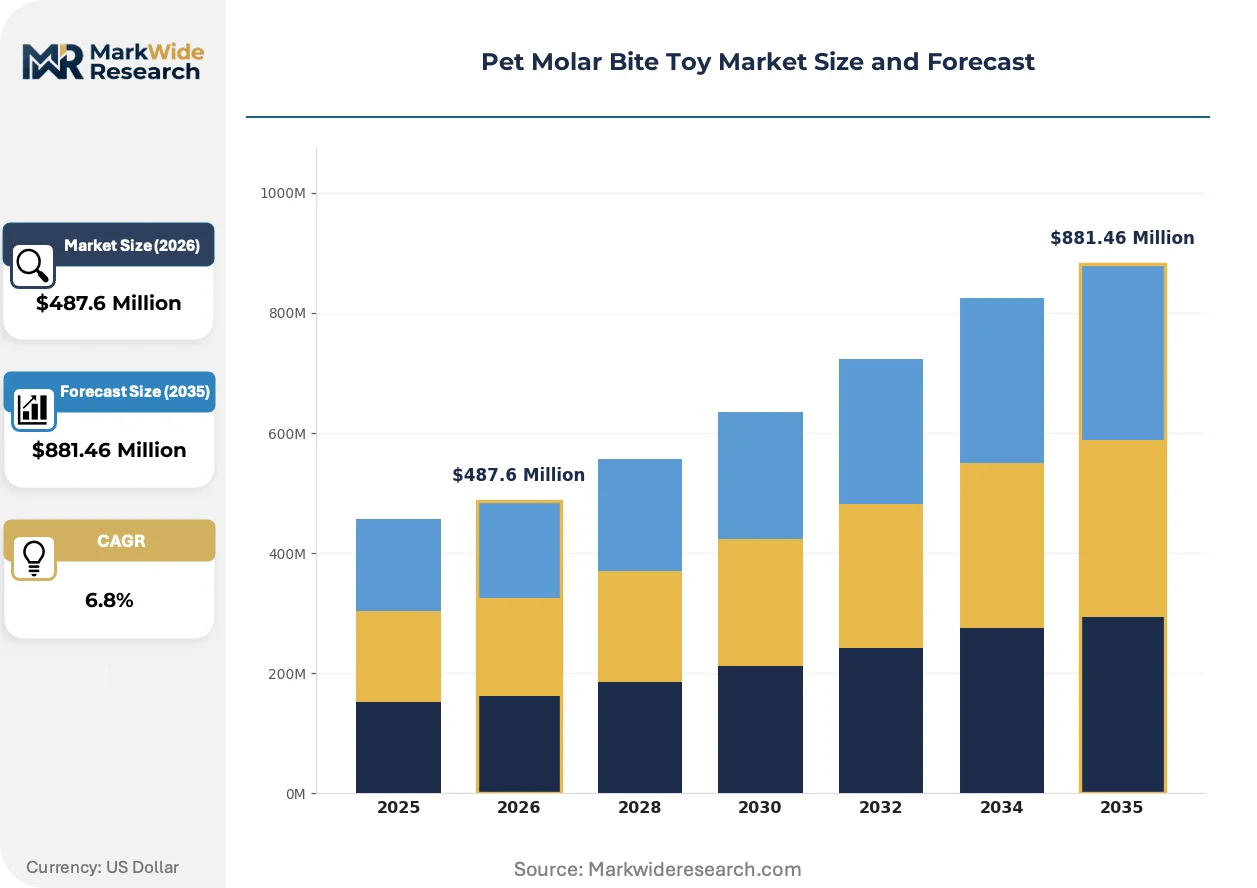
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rubber Toys, Chew Bones, Plush Toys, Dental Chews Material: Natural Rubber, Nylon, Cotton, EVA End User: Dog Owners, Cat Owners, Pet Stores, Veterinary Clinics Feature: Eco-Friendly, Interactive, Durable, Edible |
| Companies Covered | KONG Company, Nylabone, Benebone, Outward Hound, Chuckit!, JW Pet Company, Petmate, Planet Dog, ZippyPaws, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pet Molar Bite Toy Market Evolving Landscape
Material science advances are collapsing the performance gap between synthetic durability and bio-based safety credentials, while regulatory chemistry databases and veterinary telemedicine reshape how products gain market authorization and consumer trust.
Smart-textured thermoplastic elastomers with embedded enzymatic compounds are converging with precision-molding techniques to deliver plaque-scraping efficacy previously achievable only through rigid nylon architectures. Premium-positioned manufacturers in Germany and Japan are adopting these hybrid materials to satisfy both VOHC dental standards and ECHA substance restrictions. The technology is converging with subscription-based replenishment models, compressing replacement cycles from annual to quarterly purchases while locking in recurring revenue streams.
REACH SVHC candidate list expansion is forcing systematic substitution of phthalate plasticizers and certain rubber accelerators across all toy categories with oral contact. Manufacturers serving EU markets must now maintain dynamic substance tracking systems with 6-month update cycles to avoid non-compliance penalties. Small and mid-sized producers without dedicated regulatory affairs functions are outsourcing compliance verification to specialized testing laboratories in the Netherlands and Germany.
Veterinary telemedicine platforms are displacing traditional clinic-based product recommendations as the primary discovery channel for oral care devices. Millennial dog owners in urban US and UK markets now initiate purchases through app-integrated affiliate links rather than in-clinic displays. This channel rotation concentrates influence among a handful of telehealth platforms, compressing the number of stocking decision-makers while amplifying price transparency.
Pet Molar Bite Toy Market Segmentation
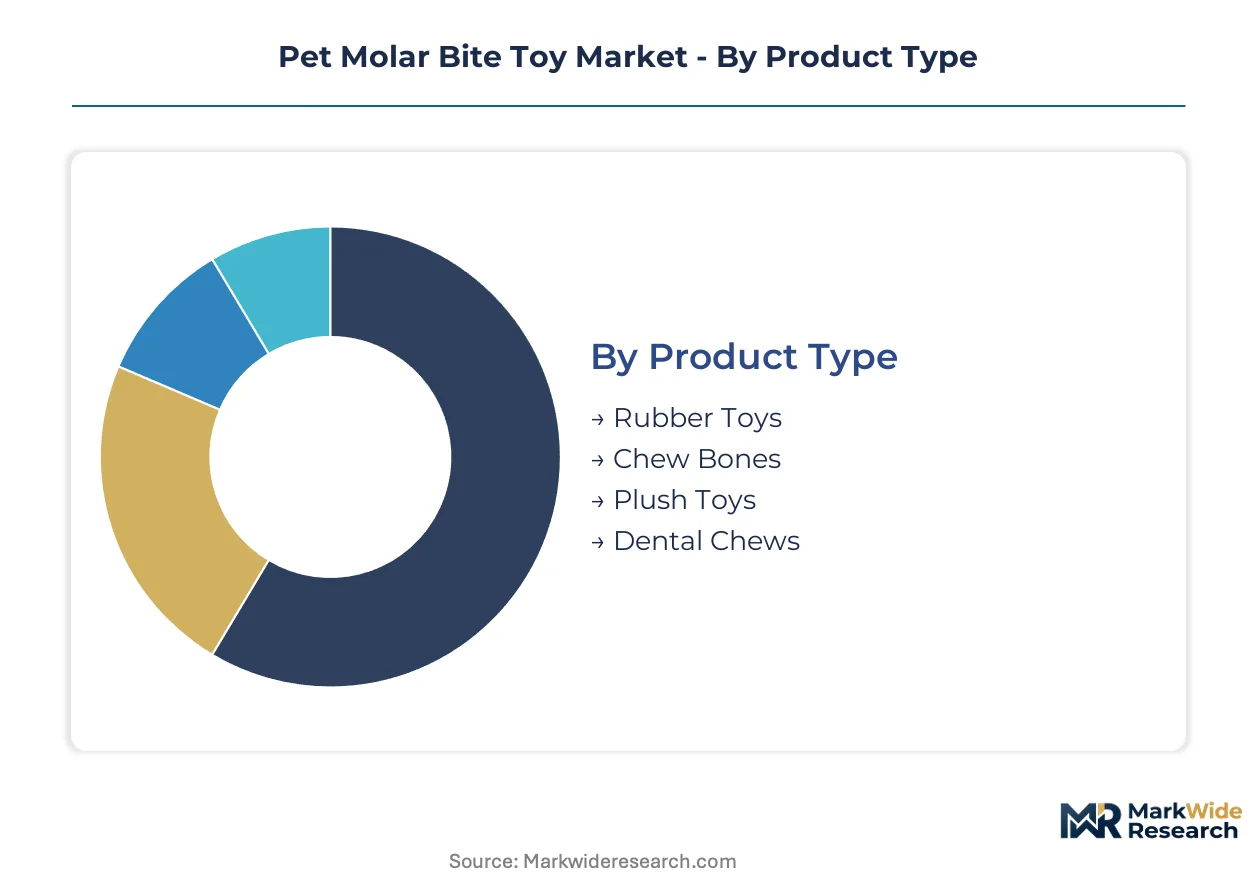
Pet molar bite toy segmentation reveals how functional purpose, material chemistry, and distribution channel create distinct margin profiles and regulatory exposure zones. Manufacturers configure product portfolios across these dimensions to balance volume scale against premium pricing power.
Product Type:
Rubber toys and chew bones function as standalone oral care systems with direct consumer purchase patterns, while plush toys and dental chews embed into broader pet wellness routines and subscription replenishment models.
- Rubber Toys:Molded from natural or synthetic elastomers with textured surfaces engineered for plaque scraping and gingival massage. Demand concentrates in Germany and Japan where VOHC dental certification commands retail shelf placement and veterinary endorsement drives repurchase frequency.
- Chew Bones:Rigid nylon or compressed rawhide architectures designed for extended gnawing sessions that redirect destructive chewing behavior. Urban millennial dog owners in Shanghai and Beijing purchase these through Tmall and JD.com platforms, prioritizing durability ratings over price sensitivity.
- Plush Toys:Fabric-based constructions with reinforced seams for moderate chewing intensity; less effective for dental efficacy but higher attachment-driven repurchase rates.
- Dental Chews:Consumable formulations with enzymatic coatings that dissolve during mastication; shorter replacement cycles generate recurring revenue streams for veterinary clinic channels.
Rubber toys lead volumes today; dental chews are gaining share fastest through subscription-model adoption.
Material:
Cost tier stratification separates captive supply chains from commodity procurement, with natural rubber commanding upstream integration investments and EVA representing lowest-threshold market entry.
- Natural Rubber:Sustainably tapped Hevea brasiliensis latex processed into high-tensile formulations. Colorado-based manufacturers leverage captive plantation partnerships to secure REACH-compliant supply chains while Southeast Asian price volatility compresses margin predictability for non-integrated producers.
- Nylon:Engineering-grade polyamides optimized for abrasion resistance and veterinary dental safety standards. Guangdong and Zhejiang manufacturing clusters dominate volume production, feeding both domestic Chinese consumption and export markets through cost-efficient injection molding scale.
- Cotton:Organic and conventional textile fibers for plush constructions; limited dental efficacy restricts positioning to behavioral enrichment segments.
- EVA:Ethylene-vinyl acetate foams offering lightweight, buoyant properties for water-play variants; lowest material cost enables economy-tier pricing but shorter product lifespans.
Nylon leads volumes today; natural rubber is climbing the fastest on pet humanization and sustainability premiums.
End User:
Customer type determines packaging specifications, certification requirements, and price realization, with veterinary channels demanding professional endorsement labeling and direct-to-consumer brands prioritizing aesthetic differentiation.
- Dog Owners:The primary demand engine across all geographies, with oral care expenditure now categorized as preventive veterinary spending rather than discretionary accessory purchase. California and New York state-level plastic restrictions are reshaping material preferences among environmentally conscious purchasers.
- Cat Owners:Smaller addressable base with distinct product architectures—softer textures and catnip infusion for feline-specific chewing stimulation.
- Pet Stores:Multi-brand retail channels requiring SKU breadth and competitive wholesale terms; inventory turnover pressure favors nylon formulations with broad appeal.
- Veterinary Clinics:Professional endorsement channels commanding 35% price premiums for VOHC-certified products; packaging must display clinical trial data and usage protocols.
Dog owners lead volumes today; veterinary clinics are expanding most quickly on wellness integration trends.
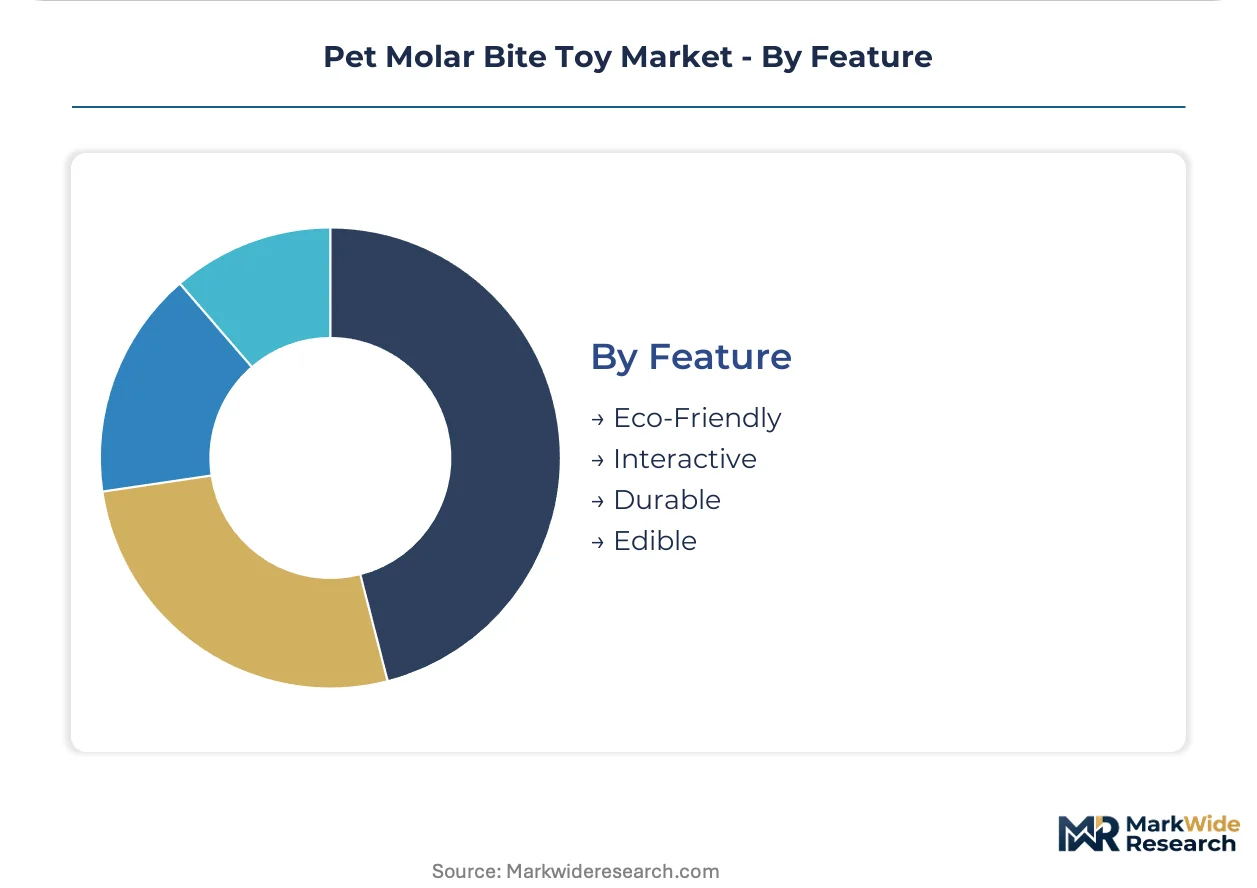
Feature:
Maturity differentiation separates established durability claims from emerging sustainability and smart-interactive positioning, with edible formulations representing the highest regulatory scrutiny tier.
- Eco-Friendly:Bio-based elastomers, recycled content, and carbon-accounted supply chains aligned with EU Green Deal and CSRD disclosure requirements. German and French retailers now mandate sustainability certifications for shelf placement, accelerating formulation substitution away from petroleum-derived inputs.
- Interactive:Embedded sensors, treat-dispensing mechanisms, and app-connected functionality converging with veterinary telemedicine platforms. Japanese manufacturers lead precision-molding integration of electronic components into chew-resistant housings.
- Durable:Traditional abrasion-resistance positioning; baseline expectation for nylon and natural rubber categories with limited differentiation power.
- Edible:Consumable formulations subject to FDA and EFSA feed additive regulations; 18-24 month approval timelines create entry barriers but lock in recurring purchase patterns.
Durable features lead volumes today; eco-friendly positioning is gaining share fastest on millennial purchasing priorities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polymer scientists and veterinary formulation specialists concentrate in Germany, the United States, and Japan, anchoring premium material innovation clusters that supply compliant elastomer technologies to manufacturers worldwide.
United States
Dog owners in California and New York now categorize oral care spending as preventive veterinary medicine rather than discretionary accessories. The EPA oversees chemical safety in manufacturing inputs while state-level plastic restrictions in Maine and California force SKU proliferation. Colorado-based natural rubber sourcing operations supply REACH-compliant feedstock to premium-tier producers.
Germany
German retailers now mandate sustainability certifications for shelf placement, accelerating demand for bio-based elastomers. ECHA's REACH SVHC candidate list expansion forces systematic substitution of phthalate plasticizers. Stuttgart and Munich host specialized testing laboratories that verify compliance for mid-sized producers lacking in-house regulatory functions.
China
Domestic pet ownership in Shanghai and Beijing has saturated, pushing manufacturers toward Tier-2 cities where rates remain 40% below coastal metros. GB standards for rubber and plastic products impose additional testing requirements on export-oriented producers. Guangdong and Zhejiang manufacturing clusters dominate volume production through cost-efficient injection molding scale.
Japan
Precision-molding integration of electronic components into chew-resistant housings positions Japanese manufacturers at the frontier of interactive toy development. METI industrial standards emphasize material traceability and carbon-accounted supply chains. Osaka-based fabricators supply hybrid thermoplastic elastomers that satisfy both VOHC dental standards and ECHA substance restrictions.
United Kingdom
Veterinary telemedicine platforms in London and Manchester now displace traditional clinic-based recommendations as the primary discovery channel for oral care devices. The UK's post-Brexit chemicals regulatory framework maintains alignment with REACH restriction protocols. Midlands-based distributors compress delivery timelines for direct-to-consumer brands through platform logistics integration.
Pet Molar Bite Toy Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base organizes around three strategic archetypes: vertically integrated natural rubber processors, specialized nylon formulation houses, and multi-category pet accessory conglomerates. Consolidation pressure intensifies as REACH compliance costs favor scaled regulatory affairs functions. Geographic expansion and portfolio diversification represent the dominant competitive moves, with manufacturers acquiring regional distributors to secure veterinary channel placement.
Within the premium natural rubber tier, KONG Company and Planet Dog exemplify upstream control strategies that insulate margin predictability against Southeast Asian latex price volatility. Among specialized nylon formulators, Benebone occupies a position calibrated to veterinary dental certification requirements. The mid-market volume segment includes Nylabone and Outward Hound, which represent scale-driven manufacturing archetypes serving mass retail channels through Guangdong and Zhejiang supplier networks.
| Leading Market Players |
|---|
| KONG Company |
| Nylabone |
| Benebone |
| Outward Hound |
| Chuckit! |
| JW Pet Company |
| Petmate |
| Planet Dog |
| ZippyPaws |
| Others |
Value Network & Pricing Analysis
ECHA REACH SVHC candidate list expansion gates qualified supply for European market access while simultaneously enabling premium-tier pricing power for compliant bio-based elastomer formulations. Manufacturers absorbing elevated registration and testing costs pass through selective price premiums to sustainability-conscious buyers in Germany and France, where retailer certification mandates now function as de facto market entry barriers.
Pricing Analysis
Subscription bundling versus standalone transactional purchase splits the market into divergent pricing architectures. Three-tier pricing structure across premium, standard, and economy levels separates VOHC-certified veterinary channel SKUs from mass retail nylon formulations and entry EVA variants. Price differentiation hinges on certification grade and captive natural rubber sourcing. Cost compression in economy tiers is intensifying because Guangdong injection molding scale advantages compress margin floors for non-integrated producers. Mass retail buyers exhibit highest price sensitivity; veterinary clinic procurement committees prioritize clinical trial documentation over unit cost.
Supply Chain Analysis
VOHC endorsement and REACH substance registration function as dual qualification gates that filter supplier participation. Manufacturing gravity centers on China, Thailand, and the United States. Formulation chemistry draws from Hevea brasiliensis latex, engineering-grade polyamides, and thermoplastic elastomer compounds. Single-source vulnerability concentrates in Southeast Asian plantation supply for premium natural rubber feedstock. Distribution runs through veterinary clinic networks, Tmall and JD.com platform logistics, and direct-to-consumer subscription infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between EU regulatory compliance costs and Chinese manufacturing scale economics, with REACH-driven reformulation expenses in Europe running three to four times above GB standards testing in Guangdong.
For Market Incumbents: Deploy captive natural rubber sourcing as a margin defense lever against Southeast Asian latex price volatility. Consolidate formulation chemistry expertise through targeted acquisition of polymer science specialists in Stuttgart and Munich testing laboratory clusters. Channel control investments in veterinary telemedicine platform affiliate partnerships counteract discovery channel displacement away from traditional clinic displays. For New Entrants and Emerging Players: Tier-2 Chinese city pet owners represent the most penetrable buyer archetype currently underserved by premium positioning strategies. Mid-market nylon formulations with localized packaging and Mandarin-language clinical trial documentation capture whitespace in Chengdu and Wuhan markets. Direct-to-consumer launch through Douyin and Xiaohongshu social commerce bypasses established Tmall incumbent saturation. For Investors and Strategic Acquirers: Roll-up economics work for specialized nylon formulation houses because REACH compliance cost concentration favors scaled regulatory affairs functions over fragmented producer bases. Five-to-ten year viability hinges on bio-based elastomer substitution trajectory acceleration. Acquisition target archetype: mid-sized German or Japanese manufacturers with existing VOHC certification and ECHA substance tracking infrastructure. Monitor ECHA SVHC candidate list expansion velocity as the primary inflection signal for compliance cost trajectory.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Natural Rubber Plantations | Colorado-based captive sourcing insulates KONG and Planet Dog from Southeast Asian latex volatility. |
| VOHC Certification Investment | Eighteen-to-twenty-four month endorsement timelines lock in veterinary channel exclusivity and thirty-five percent price premiums. |
| Platform Logistics Partnership | Guangdong and Zhejiang warehouse integration compresses delivery timelines for direct-to-consumer brands. |
| Bio-Based Elastomer Formulation Pivot | REACH SVHC substitution mandates accelerate first-mover advantages for compliant German and Japanese specialists. |
| Veterinary Telemedicine Affiliate Integration | App-linked discovery channels concentrate influence among millennial dog owners in London and Manchester markets. |
Research Methodology
Multiple input streams — regulatory filing analysis, trade flow databases, and veterinary endorsement registries — were reconciled against primary fieldwork. Interviews with polymer scientists, veterinary dental specialists, pet product procurement managers at Tmall and JD.com, and regulatory affairs directors at ECHA-registered laboratories informed demand and compliance cost assumptions. Secondary validation drew from EPA chemical safety guidance, ECHA SVHC candidate list updates, GB standards documentation, and VOHC clinical trial publication records. Bottom-up volume modeling across material tiers and top-down market sizing from pet ownership expenditure surveys were cross-referenced for convergence.
Historical elasticity patterns were cross-referenced against panel input from manufacturing executives and channel buyers. Segmentation dimensions modeled include material chemistry tier, distribution channel architecture, end-user type, product functional category, and geographic regulatory cluster. CAGRs were derived from trend extrapolation moderated by substitution elasticity estimates for bio-based versus petroleum-derived formulations. Forecast inputs incorporated REACH restriction timeline acceleration scenarios and veterinary telemedicine platform penetration curves.
Underlying measurement precision varies by segment; veterinary clinic channel volumes carry tighter precision than direct-to-consumer subscription flows due to GPO contract transparency. Forecasts embed assumptions regarding ECHA substance restriction enforcement intensity and Chinese domestic consumption growth trajectory. A model refresh is warranted upon material change in REACH SVHC candidate list expansion velocity or state-level plastic restriction adoption patterns in California and New York.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Pet Lodging Market
Pet Care Products
Organic and Natural Dog Foods Market
Pet Care Products
Therapeutic Diet for Pet Market
Pet Care Products
Plant-Based Dog Food Market
Pet Care Products
Smart Dog Collar Market
Pet Care Products
GCC Cat Food Market
Pet Care Products
Dog Vest Market
Pet Care Products
Freeze Dried Dog Food Market
Pet Care Products
Mexico Pet Food Market
Pet Care Products
Taiwan Pet Food Market
Pet Care Products
Elevated Dog Bowls Market
Pet Care Products
Cat Mat Market
Pet Care Products
Pet Collar Market
Pet Care Products
Global Pet Companion Robots Market
Pet Care Products
Pet Treats Market
Pet Care Products
Pet Grooming Gloves Market