
 Dog Treats Market | 2026-2036
Dog Treats Market Size, Share, and Industry Trends Forecast 2026-2036
Dog Treats Market Analytics
North American production capacity for premium pet nutrition is narrowing as co-manufacturers face ingredient sourcing constraints. Mars Petcare leverages its vertically integrated supply chain to secure consistent protein inputs across multiple facilities. Nestlé Purina PetCare anchors its competitive stance through dedicated R&D facilities focused on palatability science. General Mills differentiates via Blue Buffalo's grain-free positioning within specialty retail channels.
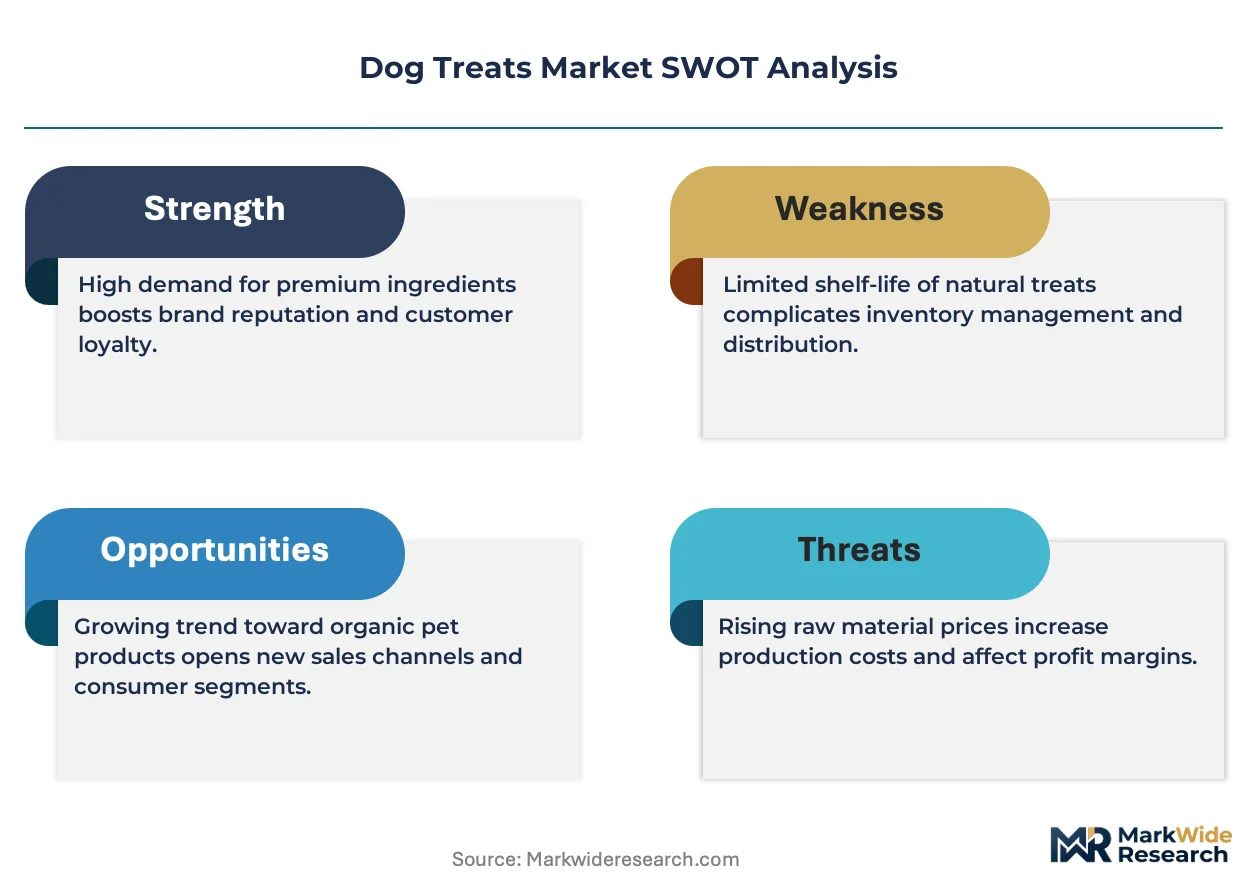
Dog treats comprise formulated edible products designed for intermittent feeding, typically containing protein meals, starches, humectants, and preservatives processed through extrusion, baking, or dehydration to achieve specified moisture content below 20 percent for shelf-stable storage. Soft treats command premium positioning due to their palatability advantage for senior dogs and medication administration, while jerky treats occupy the fastest-growing ingredient-led segment driven by clean-label meat sourcing claims. Functional ingredient types, including dental health and joint support formulations, concentrate margin pools through veterinary endorsement and subscription channel pricing power.
The FDA's Center for Veterinary Medicine enforces ingredient safety standards under the Federal Food, Drug, and Cosmetic Act, while the Association of American Feed Control Officials provides model labeling regulations that most US states adopt, creating a compliance baseline that shapes product development timelines and market access costs. USDA oversight of meat-derived ingredients adds a second regulatory layer for protein sourcing claims. Stakeholders must monitor evolving state-level animal feed regulations and veterinary channel credentialing requirements as distribution strategies diversify beyond conventional retail.
Market Dynamics
Pet humanization is compressing purchase cycles for premium dog treats as owners substitute human-grade ingredients for conventional formulations, forcing manufacturers to reconfigure protein sourcing and processing protocols to meet elevated safety expectations.
Growth Catalysts
- Clean-Label Mandates:FDA ingredient verification requirements under the Federal Food, Drug, and Cosmetic Act are accelerating reformulation toward recognizable protein sources and natural preservatives.
- Senior Dog Demographics:Soft treat palatability advantages for aging canine populations are expanding the addressable base for medication-compatible formulations.
- Veterinary Channel Expansion:Functional ingredient endorsements from veterinary professionals are unlocking subscription-based recurring revenue models.
Market Restraints
- Protein Input Volatility:Meat-derived ingredient costs fluctuate with USDA-inspected livestock markets, compressing margins for non-integrated manufacturers.
- Co-Manufacturer Concentration:North American production capacity bottlenecks limit rapid scaling for emerging brands seeking clean-label capacity.
- Dual Regulatory Burden:FDA Center for Veterinary Medicine and USDA oversight layers extend product development timelines and compliance costs.
Strategic Opportunities
- Subscription Channel Penetration:Direct-to-consumer platforms bypass traditional retail slotting fees while capturing recurring purchase data.
- Jerky Segment Positioning:Single-ingredient meat sourcing claims command price premiums in specialty pet retail channels.
- Functional Ingredient Convergence:Dental health and joint support formulations combine veterinary credibility with repeat purchase economics.
Industry Challenges
- Palatability Science Talent Scarcity:Formulation chemists with cross-species sensory expertise command premium compensation in competitive labor markets.
- Dehydration Equipment Capex:Low-moisture jerky production requires specialized drying infrastructure that strains emerging manufacturer balance sheets.
- State-Level Labeling Fragmentation:AAFCO model regulation adoption varies across jurisdictions, complicating national distribution strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dog Treats Market |
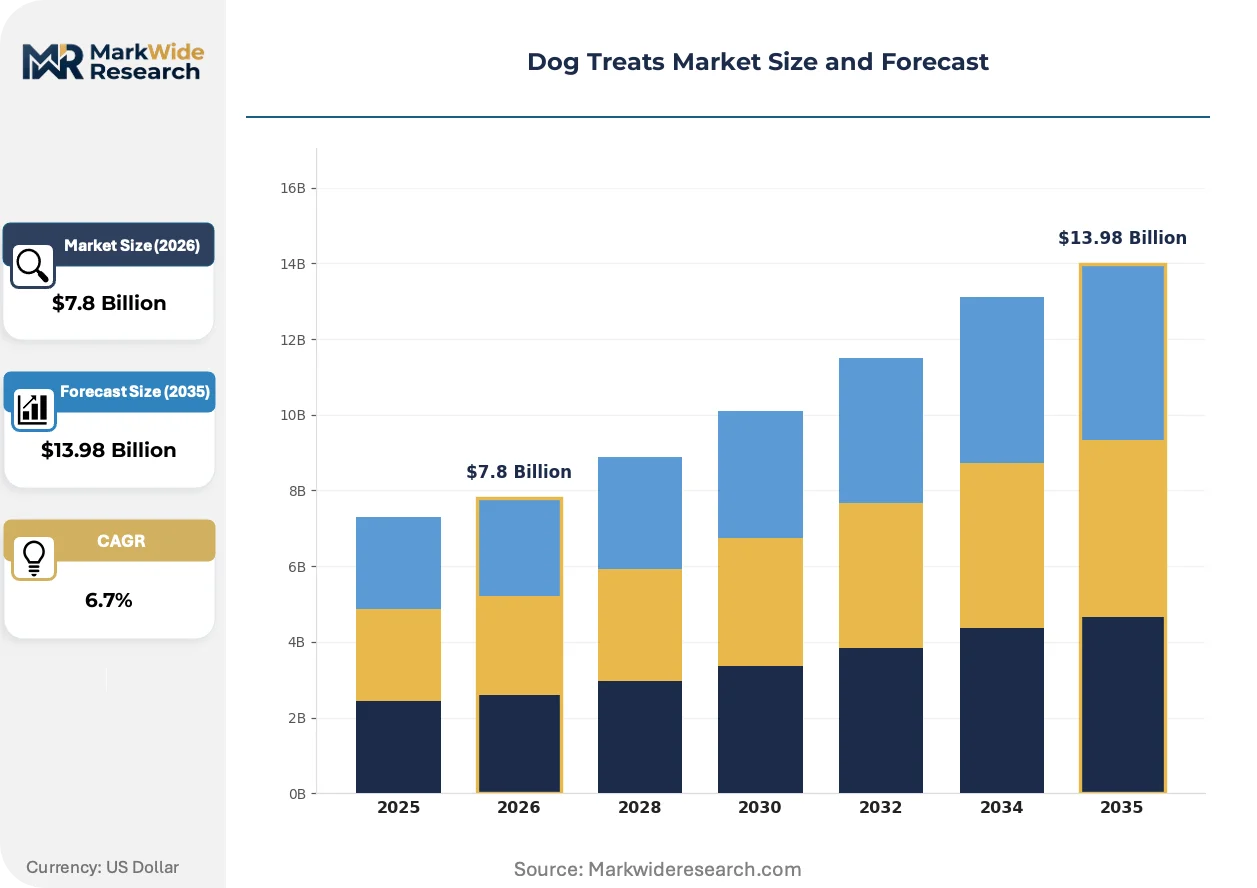
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $13.98 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soft Treats, Chewy Treats, Biscuit Treats, Jerky Treats Ingredient Type: Meat-Based, Grain-Free, Organic, Functional Size: Small, Medium, Large, Giant Distribution Channel: Online Retailers, Pet Specialty Stores, Supermarkets, Veterinarians |
| Companies Covered | Colgate-Palmolive (Hill's Pet Nutrition), Spectrum Brands, Mars Petcare, Diamond Pet Foods, Freshpet, Nestlé Purina PetCare, General Mills (Blue Buffalo), Redbarn Pet Products, J.M. Smucker Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dog Treats Market Evolving Landscape
Formulation science and distribution architecture are undergoing parallel transformation as treat manufacturers respond to ingredient transparency demands and channel fragmentation pressures.
Cold-pressed treat production is migrating from artisanal batch methods to scaled continuous processing systems. Mid-size manufacturers are adopting extrusion alternatives to preserve heat-sensitive functional ingredients like probiotics and omega fatty acids. This migration from conventional thermal processing is compressing the cost gap between premium nutrition claims and mass-market price points.
EFSA novel food ingredient pathways are shaping European clean-label development timelines while creating reference standards for export-oriented US manufacturers. The EU's evolving pet food additive regulations are forcing reformulation of artificial colorants and synthetic preservatives. Functional treat categories face the steepest compliance costs as veterinary health claims trigger pharmaceutical-adjacent scrutiny.
Pet specialty retailers are unbundling treat assortments from core nutrition sets to capture higher-margin impulse purchases. Independent pet stores and veterinary clinics are displacing mass-market shelf space for premium-positioned SKUs. This channel fragmentation is most visible in metropolitan United States markets where household treat spending per dog exceeds national baselines.
Dog Treats Market Segmentation
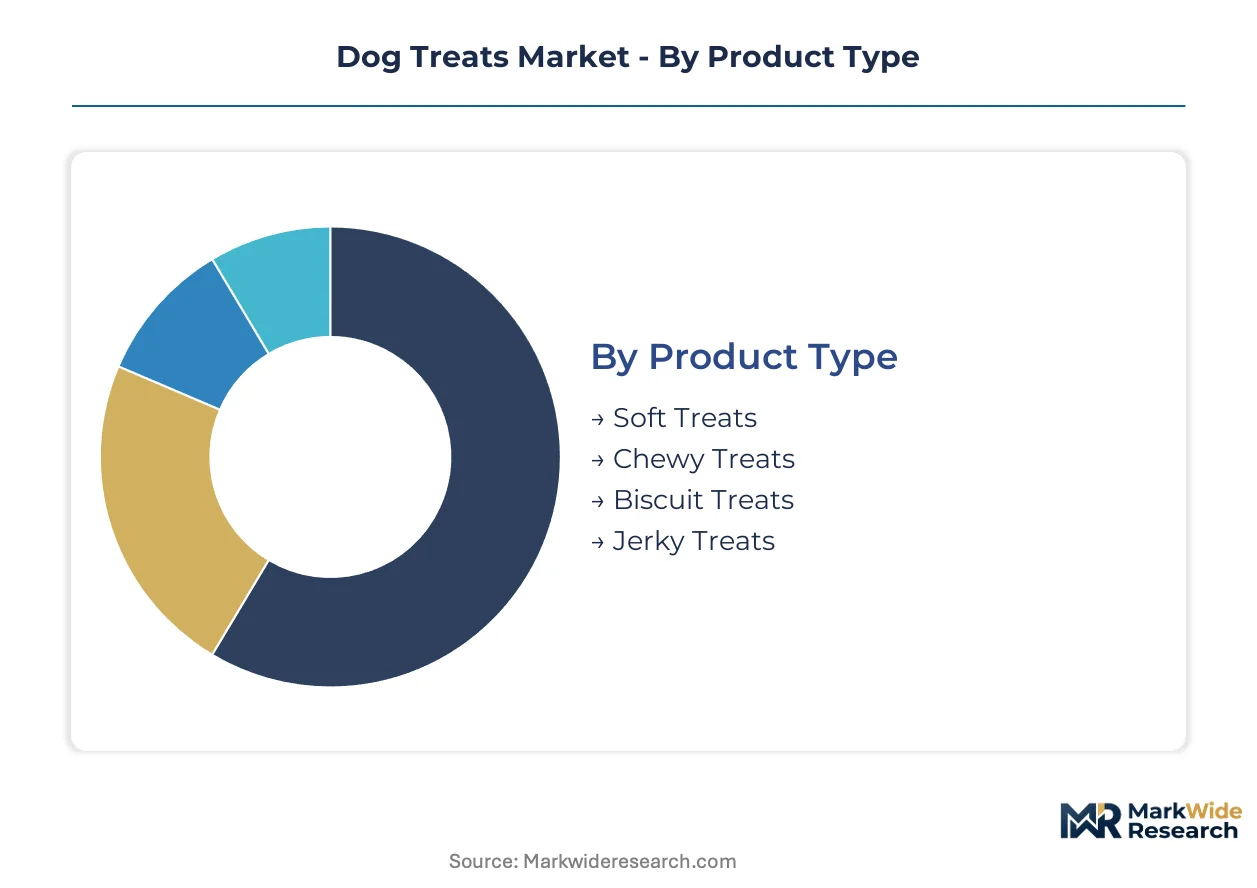
Segmentation in the dog treats market determines manufacturing scale, margin capture, and channel strategy. Product format drives equipment investment and moisture-control protocols. Ingredient positioning shapes regulatory compliance burden and pricing architecture.
Product Type:
After-sales service intensity varies sharply across product formats, with soft treats requiring veterinary consultation support for medication administration while jerky formats demand minimal post-purchase engagement.
- Soft Treats:Moisture content typically ranges 15-25 percent, producing pliable textures suited for senior dogs with dental limitations. Demand concentrates in United States metropolitan households with aging canine populations, where palatability advantages justify premium positioning for medication-compatible formulations.
- Jerky Treats:Dehydrated meat strips processed below 10 percent moisture achieve extended shelf stability without synthetic preservatives. United States specialty pet retailers report strongest velocity for single-ingredient sourcing claims, though dehydration equipment capital requirements strain emerging manufacturer balance sheets.
- Chewy Treats:Intermediate moisture formulations balance dental abrasion benefits with consumption duration.
- Biscuit Treats:Baked starch-protein matrices dominate mass-market price tiers with lowest per-unit production costs.
By volume, biscuit treats lead. By growth pace, jerky formats are climbing the fastest.
Ingredient Type:
Cost tier stratification separates commodity formulations from certified organic and functional positioning, with protein input quality driving 3-4x price multiples at shelf.
- Meat-Based:USDA-inspected protein meals and fresh meat slurries constitute the foundational input for conventional treat manufacturing. United States heartland states with integrated livestock processing maintain supply advantages, though input cost volatility compresses margins for non-integrated manufacturers during commodity price spikes.
- Functional:Dental health and joint support formulations incorporate glucosamine, omega fatty acids, or probiotic cultures validated through veterinary endorsement. Subscription channel penetration concentrates in United States coastal markets where household treat spending per dog exceeds national baselines by substantial margins.
- Grain-Free:Tapioca, pea, and potato starch substitutes replace corn and wheat for sensitivity-positioned SKUs.
- Organic:USDA Organic certification restricts synthetic inputs and mandates supply chain traceability documentation.
By volume, meat-based formulations dominate. By margin expansion, functional ingredients are gaining share fastest.
Size:
Customer type segmentation aligns treat dimensions with breed ownership patterns and per-household consumption velocity, influencing packaging format and channel placement decisions.
- Small:Bite-sized formulations calibrated for toy breeds and training reward frequency. United States urban apartment dwellers with limited-space companion animals drive repeat purchase cycles, with portability requirements favoring resealable pouch formats in convenience-oriented retail.
- Large:Substantial portion formats engineered for giant breeds and extended consumption duration. Rural United States markets with working dog populations and sporting breed ownership support value-oriented bulk packaging through farm supply and mass-market channels.
- Medium:Intermediate portioning targets the broadest breed ownership base.
- Giant:Specialized formats for mastiff, Great Dane, and similar breeds with elevated caloric requirements.
By volume, medium sizes lead. By premium positioning, small formats are expanding most quickly.
Distribution Channel:
Margin structure varies dramatically across channel architecture, with veterinary and specialty retail capturing 40-60 percent gross margins versus 20-30 percent in mass-market supermarkets.
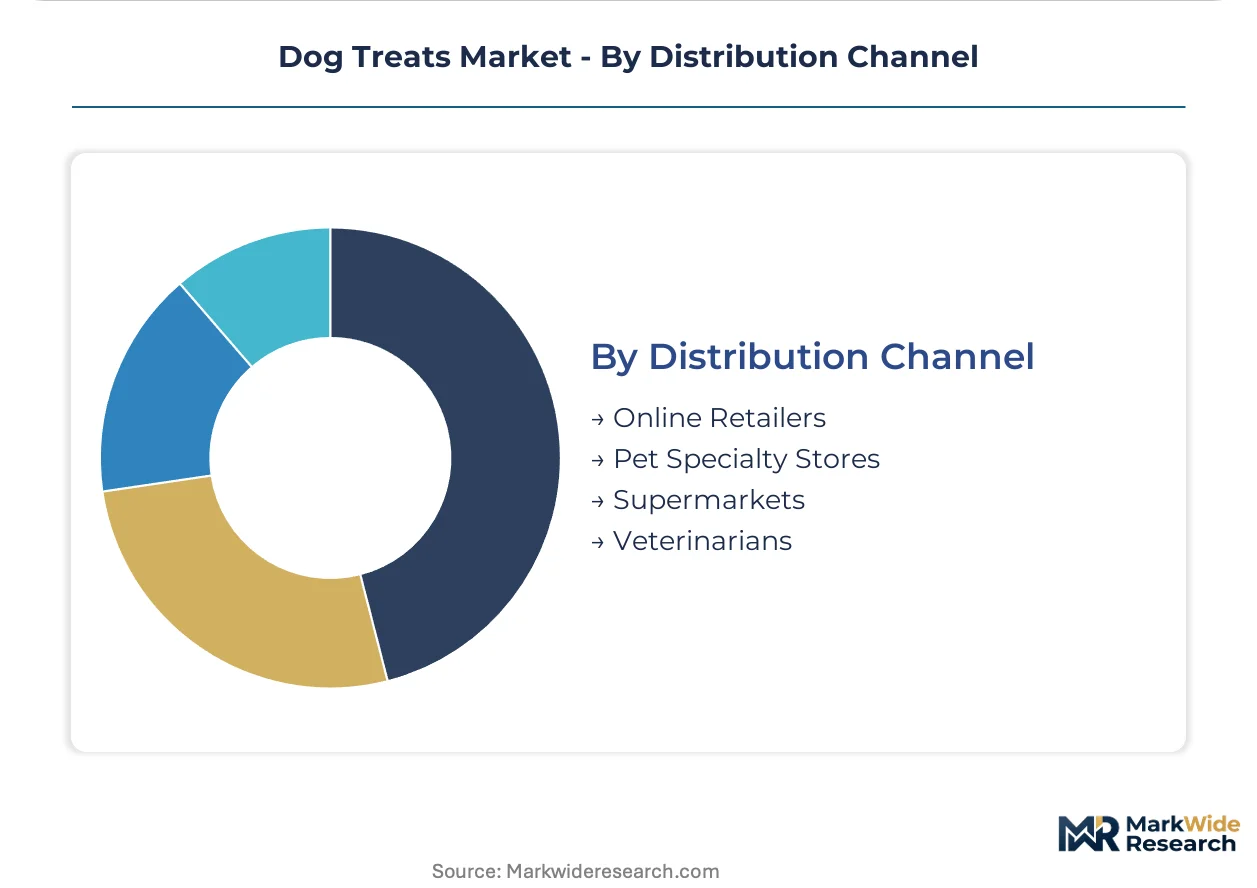
- Pet Specialty Stores:Curated assortments emphasizing premium ingredient claims and breed-specific formulations. United States independent retailers in metropolitan markets are displacing mass-market shelf space for functional and jerky SKUs, with unbundled treat sets capturing higher-margin impulse purchases adjacent to core nutrition.
- Veterinarians:Clinical endorsement channels for dental health, joint support, and prescription-compatible treat formats. United States veterinary clinic consolidation is expanding centralized purchasing power, with subscription-based recurring revenue models locking in household-level treat spending through practice loyalty programs.
- Online Retailers:Direct-to-consumer platforms bypass slotting fees while capturing purchase data for personalization.
- Supermarkets:Mass-market velocity centers on biscuit and conventional chewy formats at entry price points.
By volume, supermarkets lead. By growth pace, online retailers are ahead.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA Center for Veterinary Medicine oversight shapes the dominant geography, with ingredient verification requirements under the Federal Food, Drug, and Cosmetic Act creating compliance baselines that cascade into formulation standards elsewhere.
United States
Pet humanization trends in metropolitan households drive treat spending per dog above national baselines. USDA oversight of meat-derived ingredients adds a second regulatory layer for protein sourcing claims. Greater Boston and Pacific Northwest clusters concentrate subscription-channel functional treat startups leveraging veterinary endorsement models.
Germany
EFSA novel food ingredient pathways shape clean-label development timelines for export-oriented manufacturers. The EU's evolving pet food additive regulations force reformulation of artificial colorants and synthetic preservatives. Bavaria anchors premium pet nutrition production with integrated meat processing supply chains serving central European distribution.
United Kingdom
Veterinary channel consolidation expands centralized purchasing power for dental health and joint support formulations. UK-specific labeling requirements diverge from EU standards post-Brexit, complicating cross-border formulation strategies. London/Southeast retail corridors displace mass-market shelf space for premium-positioned jerky and functional SKUs.
Japan
Aging canine demographics expand demand for soft treat palatability advantages in medication administration. METI standards for pet food manufacturing facilities exceed baseline hygiene requirements, extending facility certification timelines. Kanto/Tokyo metropolitan households concentrate spending on imported single-ingredient jerky formats through specialty pet retailers.
Canada
Health Canada and PMRA joint oversight creates dual regulatory pathways for functional ingredient health claims. Cross-border supply chain integration with US heartland livestock processing maintains input cost advantages. Ontario and Quebec provinces concentrate co-manufacturing capacity serving private-label brands entering North American specialty retail.
Dog Treats Market Competitive Landscape
Capability concentration sits with one tier; scale advantage sits with another. Vertically integrated multinationals command protein sourcing security and R&D infrastructure, while emerging brands compete through clean-label positioning and direct-to-consumer channel agility. Three archetypes define competitive positioning: integrated nutrition conglomerates with captive supply chains, specialist treat manufacturers with palatability science depth, and digitally native brands with subscription-first distribution. Dominant competitive moves include backward integration into protein processing and strategic partnerships with veterinary clinic networks.
Within the integrated nutrition tier, Mars Petcare and Nestlé Purina PetCare exemplify scale-driven supply chain control. Among specialist-positioned players, Colgate-Palmolive's Hill's Pet Nutrition occupies a clinical endorsement position. General Mills' Blue Buffalo operation represents grain-free premium positioning within specialty retail channels.
| Leading Market Players |
|---|
| Colgate-Palmolive (Hill's Pet Nutrition) |
| Spectrum Brands |
| Mars Petcare |
| Diamond Pet Foods |
| Freshpet |
| Nestlé Purina PetCare |
| General Mills (Blue Buffalo) |
| Redbarn Pet Products |
| J.M. Smucker Company |
| Others |
Value Network & Pricing Analysis
Midwest United States co-manufacturing clusters in Kansas and Nebraska shape downstream pricing power through protein input proximity, with USDA-inspected livestock processing concentration allowing integrated players to compress per-unit costs while non-integrated brands absorb margin volatility from spot-market meat meal procurement.
Pricing Analysis
Metropolitan United States households pay 40-60 percent premiums over rural markets for identical SKUs, with three-tier pricing structure across premium, standard, and economy levels anchored by ingredient certification grade and veterinary endorsement status. Price differentiation separates functional formulations with glucosamine or probiotic claims from commodity biscuit tiers, while subscription-channel buyers show lowest price sensitivity due to practice loyalty lock-in. Cost compression in mass-market biscuits is intensifying because co-manufacturer capacity bottlenecks force emerging brands into unfavorable volume commitments.
Supply Chain Analysis
USDA-inspected beef and poultry processing facilities in Iowa, Nebraska, and Kansas anchor raw material flows, with meat meal and fresh meat slurries constituting 50-70 percent of formulation costs for conventional treats. Supply draws from corn and wheat starch inputs in the same heartland corridor, creating geographic clustering that amplifies drought and commodity price volatility risks. Distribution runs through pet specialty retailers and veterinary clinic networks for premium tiers, while mass-market supermarkets handle biscuit velocity at entry price points.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dog treats market fragmentation creates white-space opportunities as pet humanization splits demand across ingredient transparency, functional health claims, and channel convenience preferences that no single incumbent fully captures.
For Market Incumbents: Build captive protein sourcing moats through backward integration into Midwest livestock processing or long-term offtake agreements with USDA-inspected facilities, insulating margin structures from commodity volatility that threatens non-integrated competitors. Anchor veterinary channel control through exclusive formulation partnerships with consolidating clinic networks, defending against subscription-first entrants. For New Entrants and Emerging Players: Build out direct-to-consumer subscription platforms targeting coastal United States households with aging canine populations, bypassing slotting fee barriers that constrain specialty retail entry. Single-ingredient jerky formats with transparent meat sourcing claims offer the most penetrable premium tier, with cold-pressed production differentiation enabling palatability science positioning against mass-market thermal processing. For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue consumables play because treat purchase cycles compress under humanization trends while veterinary endorsement creates subscription stickiness comparable to pharmaceutical adjacencies. Acquisition targets should display clean-label formulation capability plus subscription channel traction; watch FDA ingredient verification enforcement intensity as the signal indicating margin pressure timing for non-compliant legacy portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Protein Processing | Captive USDA-inspected meat supply secures input cost stability against livestock market volatility. |
| Veterinary Clinic Network Partnership | Clinical endorsement unlocks subscription recurring revenue with household-level spending lock-in. |
| Cold-Pressed Production Scale-Up | Heat-sensitive functional ingredient preservation enables premium positioning against conventional extrusion. |
| Direct-to-Consumer Platform Launch | Bypasses pet specialty retailer slotting fees while capturing purchase data for personalization. |
| Clean-Label Certification Investment | USDA Organic or single-ingredient claims command price premiums in metropolitan specialty channels. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across pet treat brand managers, veterinary clinic procurement leads, co-manufacturing facility managers, and specialty retail category buyers, with secondary validation drawing from FDA Center for Veterinary Medicine enforcement records, USDA livestock market data, AAFCO model regulation adoption tracking, and Nielsen retail audit coverage. Bottom-up SKU-level volume triangulation against top-down household spending estimates anchored forecast confidence intervals.
Calibration across historical protein input cost cycles and channel shift velocities shaped the analytical framework, with segmentation dimensions spanning product format, ingredient positioning, size tier, and distribution channel across the analysis window. CAGRs derived from regression against pet ownership demographics, household treat spending intensity, and veterinary channel penetration curves, with palatability science R&D investment levels and co-manufacturer capacity utilization serving as industry-specific forecast inputs.
Stress conditions across meat commodity price spikes, FDA enforcement intensity escalation, and veterinary clinic consolidation pace were modeled; outcomes outside those bands fall beyond the analytical envelope. Cross-checking against USDA National Agricultural Statistics Service livestock price benchmarks and pet specialty retailer same-store sales trends is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Pet Car Seat Market
Pet Care Products
Automatic Cat Feeder Market
Pet Care Products
Interactive Dog Toys Market
Pet Care Products
Pet Smart Tracker Market
Pet Care Products
Pet Grooming Products Market
Pet Care Products
Cat Furniture and Scratchers Market
Pet Care Products
Fresh and Frozen Dog Food Market
Pet Care Products
India Pet Clothing Market
Pet Care Products
Pet Care Ingredients Market
Pet Care Products
South Korea Dog Food Market
Pet Care Products
North America Functional Pet Treat Market
Pet Care Products
Dog Crate Furniture Market
Pet Care Products
Pet Meal Kit Delivery Services Market
Pet Care Products
United Kingdom Pet Food Market
Pet Care Products
Cat Harness Market
Pet Care Products
Pet Fitness Care Market