
 Pet Oral Care Products Market | 2026-2036
Pet Oral Care Products Market Size, Share, and Industry Trends Forecast 2026-2036
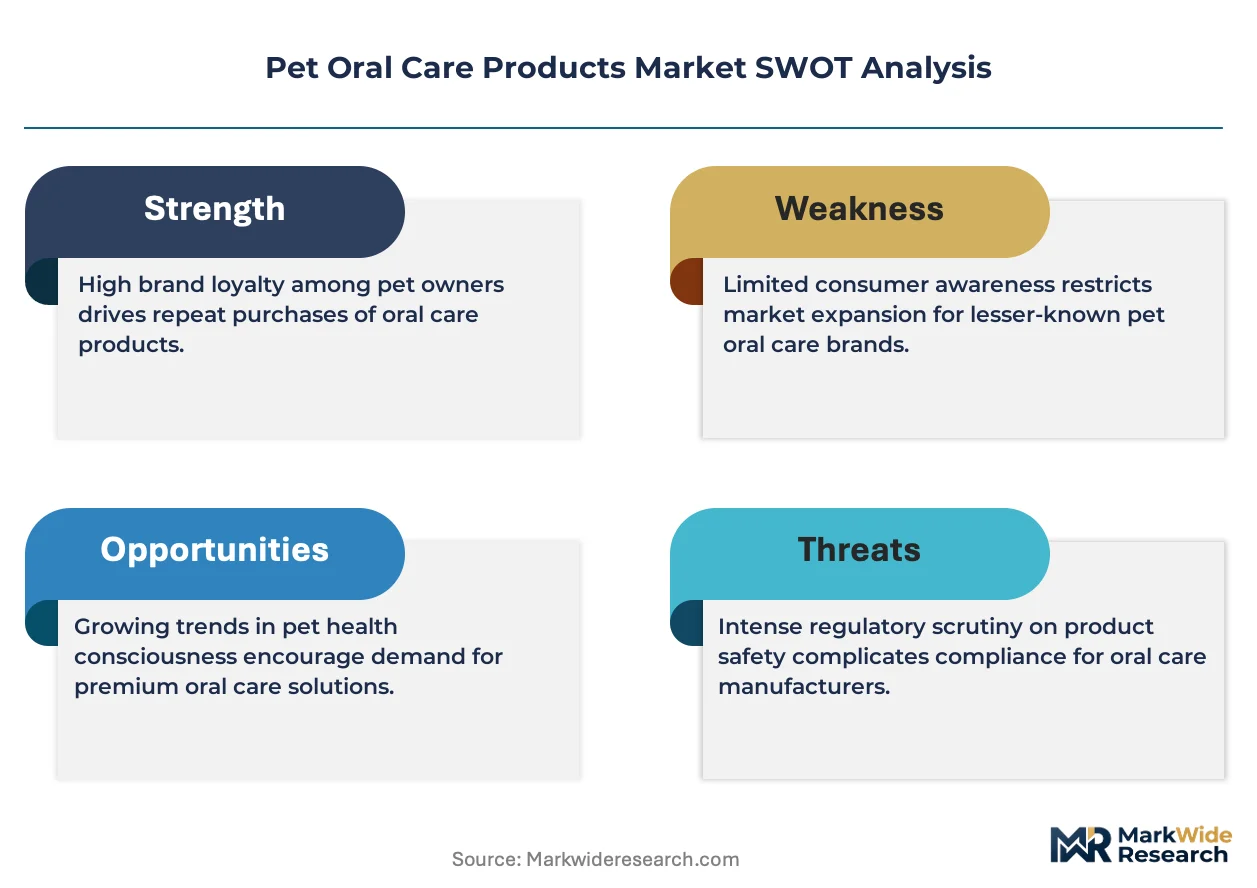
Pet Oral Care Products Market Analysis
Multi-source ingredient procurement is shifting toward vertically integrated supply chains among top manufacturers. Mars Incorporated leverages captive flavor-chemistry capabilities to secure proprietary poultry and beef palatants that drive pet acceptance rates. Virbac anchors its competitive position through European manufacturing scale and veterinary-exclusive distribution channels. Nestlé Purina PetCare Company dominates mass-retail shelf space with bundled dental treat and toothpaste portfolios.
Pet oral care products encompass enzymatic pastes, mechanical brushes, edible chews, and antiseptic rinses formulated to reduce plaque accumulation, calculus formation, and periodontal disease in companion animals. Active ingredients typically include glucose oxidase, lactoperoxidase, chlorhexidine, or zinc ascorbate in concentrations calibrated for species-specific safety thresholds, with pH buffering systems protecting enamel integrity during repeated application. Dental chews generate the highest absolute revenue within product-type segmentation due to convenience-driven purchasing from dog owners, while natural-ingredient formulations capture expanding margin pools as clean-label preferences migrate from human food into pet care. Veterinary clinics represent the fastest-growing end-user channel, with professional-grade prophylaxis kits and take-home maintenance systems creating recurring revenue streams.
The FDA Center for Veterinary Medicine regulates active pharmaceutical claims in enzymatic toothpastes, while the EPA exercises jurisdiction over antimicrobial mouthwash formulations containing chlorhexidine or zinc compounds. AAFCO model guidelines influence state-level ingredient permissible lists, creating a patchwork compliance environment that favors manufacturers with dedicated regulatory affairs teams. State veterinary practice acts in California, Texas, and New York increasingly mandate oral health assessments during annual examinations, funneling pet owners toward clinic-dispensed professional products. Stakeholders must monitor evolving state board interpretations of veterinary-client-patient relationship requirements for prescription-strength dental therapeutics.
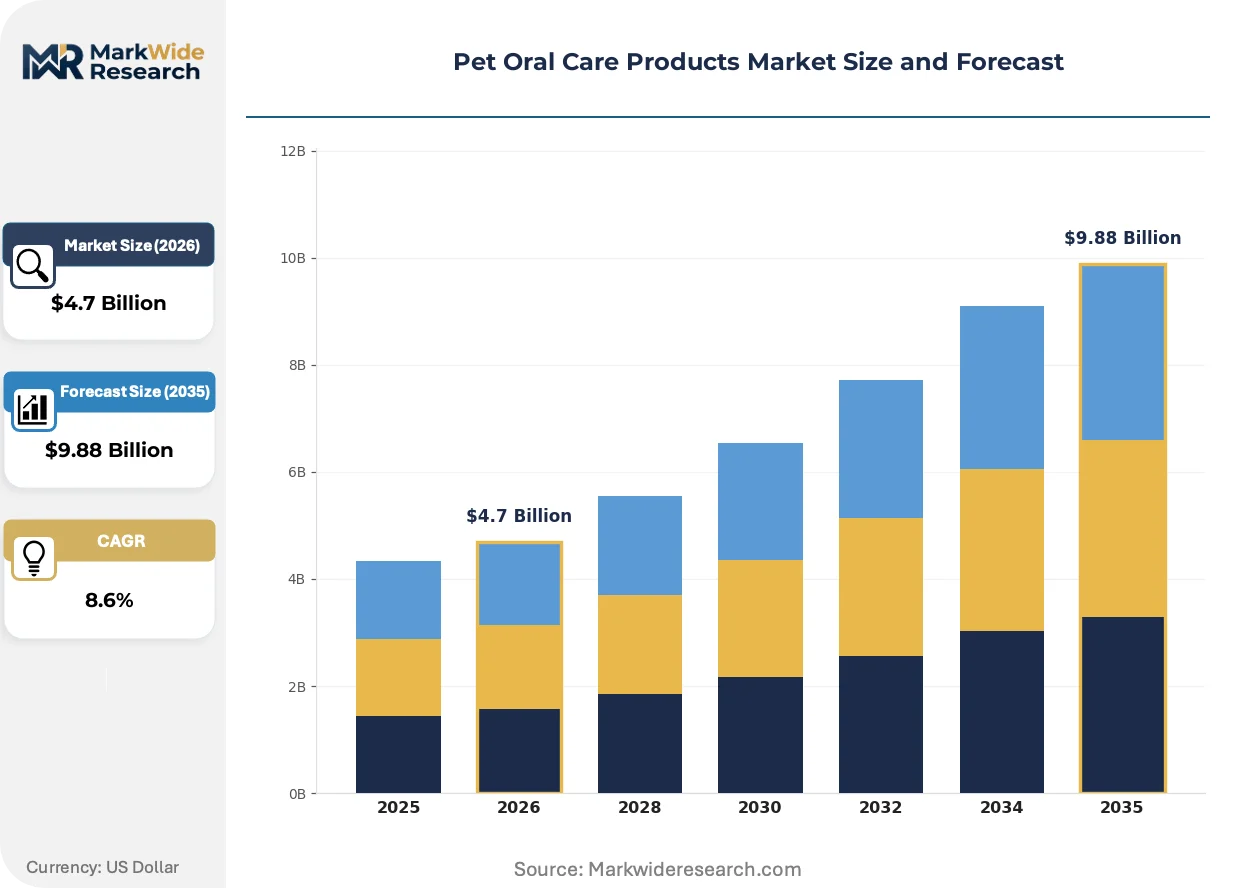
Market Dynamics
Veterinary clinics are consolidating their position as the primary channel for professional-grade oral care, driven by state-level mandates requiring oral health assessments during annual examinations and the resulting prescription-strength product dispensing authority this creates for licensed practitioners.
Growth Catalysts
- State Veterinary Practice Acts:California, Texas, and New York now mandate oral health assessments during annual examinations, funneling pet owners toward clinic-dispensed professional products and creating recurring revenue attachment points.
- Employer-Sponsored Pet Insurance:Corporate benefit plans in the United States now routinely include dental coverage riders, reducing price sensitivity for premium enzymatic pastes and professional prophylaxis kits.
- Enzymatic Formulation Advancement:Glucose oxidase-lactoperoxidase systems with species-calibrated pH buffering are achieving plaque reduction efficacy that rivals mechanical scaling, expanding the addressable market to preventive home care.
Market Restraints
- FDA Center for Veterinary Medicine Compliance:Active pharmaceutical claims in enzymatic toothpastes require extensive safety documentation and post-market surveillance, elevating fixed costs that disadvantage smaller manufacturers.
- Poultry and Beef Palant Supply Concentration:Captive flavor-chemistry capabilities reside with a limited number of integrated feedstock processors, creating input bottlenecks for palatability-critical dental chew formulations.
- Antimicrobial Mouthwash Jurisdictional Overlap:EPA jurisdiction over chlorhexidine and zinc compound formulations creates dual-agency compliance burdens that extend product development timelines.
Strategic Opportunities
- Clean-Label Ingredient Migration:Natural-ingredient formulations are capturing expanding margin pools as AAFCO model guidelines tighten permissible additive lists and pet owners reject synthetic preservatives.
- Veterinary-Exclusive Distribution Channel:Professional-grade prophylaxis kits and take-home maintenance systems create recurring revenue streams with higher switching costs than mass-retail alternatives.
- Mechanical Brush Automation:Ultrasonic and sonic vibration technologies are converging with species-appropriate bite-force engineering to reduce owner compliance burden in feline applications.
Industry Challenges
- Regulatory Affairs Talent Scarcity:The patchwork compliance environment across FDA, EPA, and fifty state veterinary boards requires specialized expertise that commands premium compensation and limits scaling velocity.
- Species-Specific Safety Threshold Calibration:Feline enzymatic tolerance differs substantially from canine physiology, necessitating separate formulation runs that fragment production economics.
- Veterinary-Client-Patient Relationship Documentation:State board interpretations of prescription-strength dental therapeutic dispensing requirements vary unpredictably, creating liability exposure for telehealth-adjacent distribution models.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pet Oral Care Products Market |
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $9.88 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Toothpaste, Toothbrushes, Dental Chews, Mouthwash End User: Dog Owners, Cat Owners, Veterinary Clinics, Pet Groomers Application: Preventive Care, Hygiene Maintenance, Dental Treatment, Freshening Breath Ingredient Type: Natural Ingredients, Antimicrobial Agents, Fluoride, Whiting Agents |
| Companies Covered | Dechra Pharmaceuticals plc, Elanco Animal Health Incorporated, Mars Incorporated, Ceva Santé Animale, Central Garden & Pet Company, Nestlé Purina PetCare Company, Colgate-Palmolive Company, Vetoquinol SA, Virbac, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pet Oral Care Products Market Emerging Trajectories
Formulation chemistry and distribution channel control are diverging sharply, with professional-grade efficacy claims becoming the primary axis of competition while mass-retail products compete on palatability engineering and convenience packaging.
Ultrasonic toothbrush systems with pressure-sensitive feedback mechanisms are overtaking manual brushing protocols in veterinary clinic recommendation hierarchies. Board-certified veterinary dentists in academic medical centers are adopting these devices for home-care patient discharge protocols. This technology is overtaking legacy enzymatic paste-only regimens by demonstrating measurable calculus reduction in controlled trials, compressing the market for basic paste formulations without mechanical adjuncts.
REACH registration requirements for antimicrobial active ingredients are tightening documentation obligations for chlorhexidine suppliers serving the European Union veterinary market. Manufacturers must now submit full substance dossiers including environmental fate studies, extending lead times for reformulation projects. Dental rinse producers with existing REACH-compliant supply chains are capturing shelf space from importers lacking pre-registered active substance portfolios.
Subscription-based replenishment models are displacing episodic retail purchasing among urban dog owners with employer-sponsored wellness benefits. Automated delivery of dental chews calibrated to breed-specific jaw mechanics is replacing quarterly bulk purchases at mass retailers. This pattern concentrates most visibly in United States metropolitan corridors where veterinary telehealth platforms bundle oral care products with remote consultation services.
Pet Oral Care Products Market Segmentation
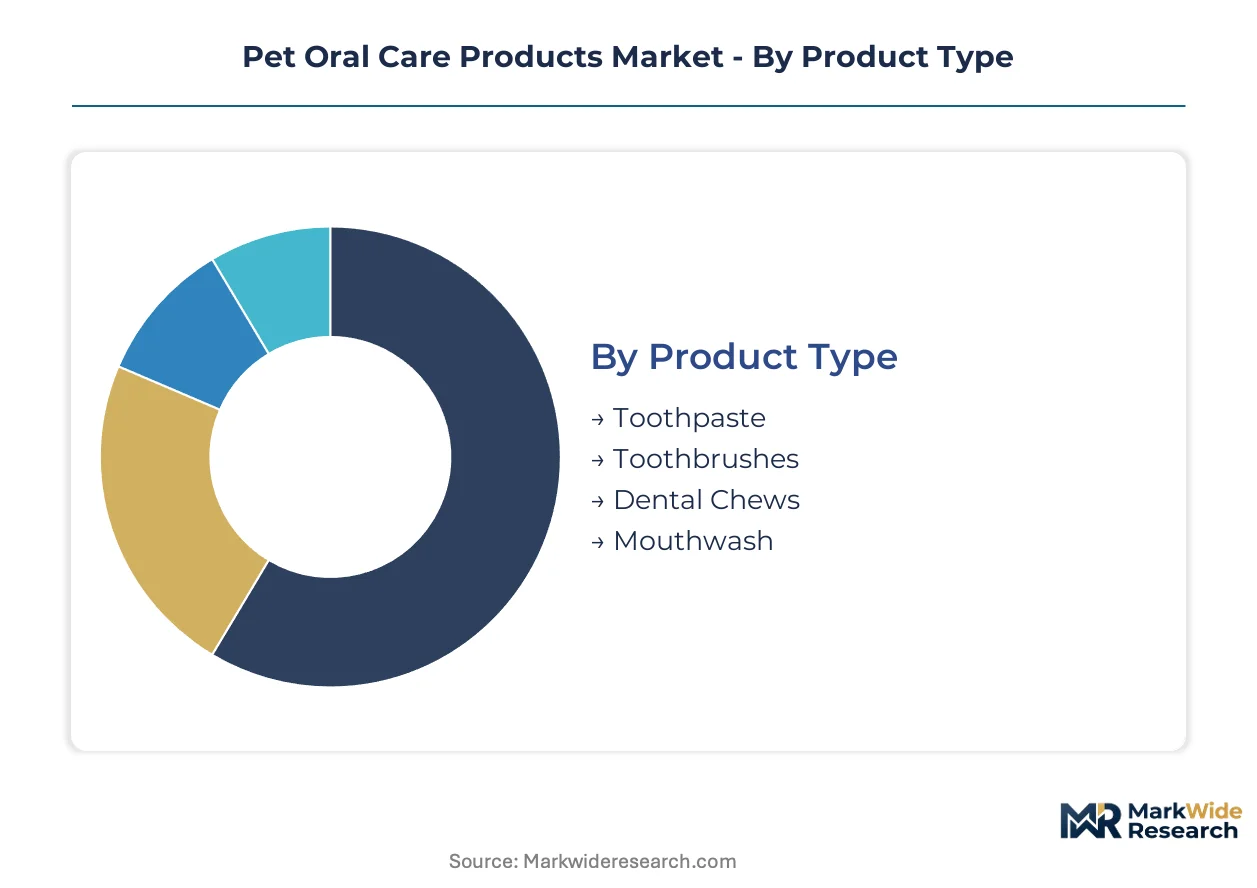
Pet oral care manufacturers configure production lines around distinct efficacy claims and dispensing formats. Each segment carries unique regulatory burdens and margin profiles that reshape competitive positioning across veterinary and retail channels.
Product Type:
Supply concentration in palatant chemistry and enzymatic formulation expertise determines which product formats achieve scale economics.
- Dental Chews:Edible matrices incorporate glucose oxidase-lactoperoxidase systems with species-calibrated pH buffering. Demand concentrates among dog owners in United States metropolitan corridors where employer-sponsored pet insurance reduces price sensitivity for premium formulations.
- Toothpaste:Enzymatic pastes containing chlorhexidine or zinc ascorbate require FDA Center for Veterinary Medicine compliance documentation that elevates fixed costs. Veterinary clinics in California, Texas, and New York drive dispensing volume through state-mandated oral health assessment protocols.
- Toothbrushes:Mechanical and ultrasonic variants with pressure-sensitive feedback mechanisms reduce owner compliance burden.
- Mouthwash:Antiseptic rinses face dual EPA and FDA jurisdiction over antimicrobial claims, extending development timelines.
Dental chews absorb the bulk of installed capacity; mouthwash is expanding most quickly as professional prophylaxis protocols gain adoption.
End User:
Channel economics diverge sharply between prescription-dispensing authorities and mass-retail purchasing patterns.
- Veterinary Clinics:Professional-grade prophylaxis kits and take-home maintenance systems generate recurring revenue streams. State veterinary practice acts in California, Texas, and New York mandate oral health assessments during annual examinations, funneling pet owners toward clinic-dispensed products with higher switching costs than retail alternatives.
- Dog Owners:Convenience-driven purchasing favors bundled dental treat and enzymatic paste portfolios distributed through mass retail and subscription replenishment models.
- Cat Owners:Feline-specific formulation requirements fragment production economics due to species-specific enzymatic tolerance thresholds.
- Pet Groomers:Non-prescription hygiene maintenance services create episodic demand for basic mechanical cleaning tools.
Veterinary clinics command the steepest expansion trajectory; dog owners retain the largest absolute volume base.
Application:
Clinical outcomes versus cosmetic benefits determine reimbursement eligibility and pricing power across the application spectrum.
- Preventive Care:Home-use enzymatic regimens and dental chews calibrated to breed-specific jaw mechanics dominate volume. United States pet owners with employer-sponsored wellness benefits increasingly adopt automated subscription delivery for preventive protocols.
- Dental Treatment:Prescription-strength therapeutics require veterinary-client-patient relationship documentation under varying state board interpretations, creating liability exposure for telehealth-adjacent distribution models.
- Hygiene Maintenance:Basic mechanical cleaning protocols serve price-sensitive segments without insurance coverage.
- Freshening Breath:Cosmetic claims face lighter regulatory scrutiny but command lower price premiums than therapeutic indications.
Preventive care captures the majority of unit economics; dental treatment is climbing the fastest as professional intervention protocols expand.
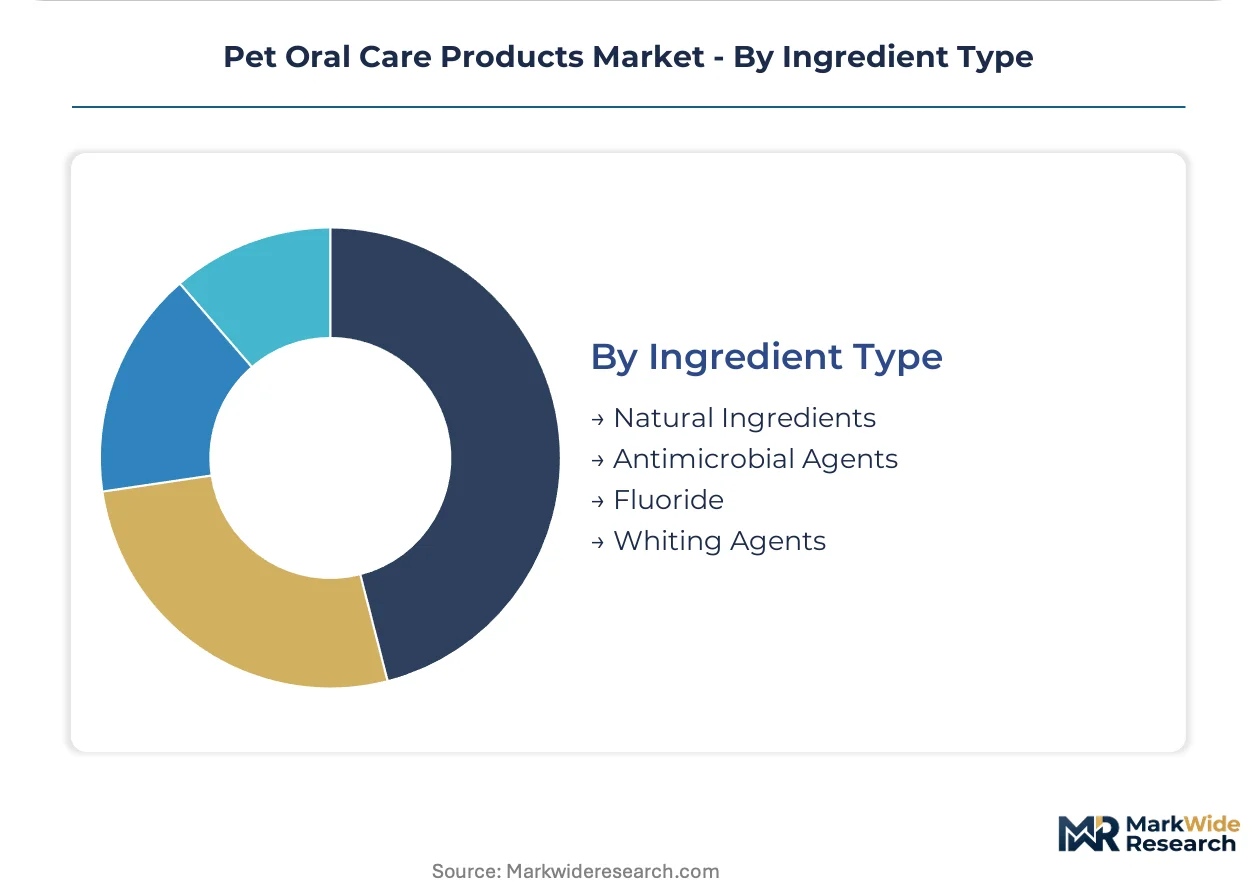
Ingredient Type:
Clean-label migration and antimicrobial registration requirements are restructuring supplier relationships and permissible additive lists.
- Natural Ingredients:Plant-derived formulations capture expanding margin pools as AAFCO model guidelines tighten synthetic preservative restrictions. REACH registration requirements for European Union suppliers now demand full substance dossiers including environmental fate studies.
- Antimicrobial Agents:Chlorhexidine and zinc compounds fall under EPA jurisdiction in addition to FDA oversight, creating dual-agency compliance burdens that disadvantage smaller manufacturers lacking dedicated regulatory affairs teams.
- Fluoride:Species-specific safety thresholds limit concentration ranges compared to human oral care products.
- Whitening Agents:Cosmetic efficacy claims face lighter documentation requirements than therapeutic antimicrobial indications.
Natural ingredients absorb disproportionate capacity investment; antimicrobial agents retain the largest revenue share despite regulatory headwinds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Poultry and beef flavor-chemistry feedstock concentration in the United States Midwest and Great Plains anchors North American supply security for palatability-critical dental chew formulations. This raw-material geography shapes manufacturing location decisions among integrated processors.
United States
Employer-sponsored pet insurance penetration in metropolitan corridors drives premium enzymatic paste demand. California, Texas, and New York state veterinary practice acts mandate oral health assessments during annual examinations, channeling dispensing authority toward licensed practitioners. Chicago and Kansas City clusters concentrate captive flavor-chemistry capabilities among integrated feedstock processors.
Germany
REACH registration requirements for chlorhexidine suppliers tighten documentation obligations for antimicrobial mouthwash producers. The country's national pharmaceutical regulator enforces environmental fate study submissions for active substance portfolios. Munich and Stuttgart veterinary equipment manufacturers scale ultrasonic toothbrush production for export markets.
United Kingdom
Veterinary telehealth platform adoption in London and Southeast England bundles subscription-based dental chew replenishment with remote consultation services. The national veterinary regulator monitors state board interpretations of prescription-strength therapeutic dispensing requirements. Cambridge biotech corridors develop species-specific pH buffering systems for feline enzymatic tolerance thresholds.
Japan
Metropolitan Tokyo and Osaka pet humanization trends elevate discretionary spending toward premium oral care solutions. The national pharmaceutical regulator calibrates safety thresholds for zinc ascorbate concentrations in companion animal formulations. Nagoya industrial clusters engineer pressure-sensitive feedback mechanisms for ultrasonic toothbrush systems.
Australia
Urban dog owner convenience-driven purchasing in Sydney and Melbourne favors automated delivery models for breed-specific dental chews. The national therapeutic goods regulator exercises jurisdiction over antimicrobial claims in veterinary mouthwash formulations. Queensland agricultural zones supply natural-ingredient feedstocks for clean-label formulation migration.
Pet Oral Care Products Market Vendor Landscape
Global majors compete with regional champions across regulatory compliance capabilities and veterinary-exclusive distribution channel control. Market structure tilts toward consolidation among manufacturers with dedicated FDA and EPA regulatory affairs teams, while mid-tier players fragment across palatant chemistry and natural-ingredient niches. Three archetypes dominate: integrated feedstock processors with captive flavor-chemistry capabilities, European-scale veterinary pharmaceutical specialists, and mass-retail consumer goods conglomerates with bundled portfolio strategies. Competitive moves concentrate on backward integration into poultry and beef palatant supply and strategic partnerships with veterinary clinic networks.
Within the veterinary pharmaceutical tier, Dechra Pharmaceuticals plc and Elanco Animal Health Incorporated occupy positions anchored by professional-grade prophylaxis kit development. Mars Incorporated and Nestlé Purina PetCare Company exemplify mass-retail archetypes with bundled dental treat and toothpaste portfolios distributed through consumer channels. Virbac represents the European manufacturing scale specialist with veterinary-exclusive distribution concentration.
| Leading Market Players |
|---|
| Dechra Pharmaceuticals plc |
| Elanco Animal Health Incorporated |
| Mars Incorporated |
| Ceva Santé Animale |
| Central Garden & Pet Company |
| Nestlé Purina PetCare Company |
| Colgate-Palmolive Company |
| Vetoquinol SA |
| Virbac |
| Others |
Supply Flow & Price Mechanics
Captive flavor-chemistry integration among Midwest feedstock processors anchors both supply security and premium pricing power for palatability-critical dental chew formulations. This backward integration into poultry and beef palatant production insulates integrated manufacturers from input volatility while enabling sustained margin capture in the United States veterinary channel.
Pricing Analysis
Warranty-bundled professional prophylaxis kits command premium positioning against unbundled retail alternatives. Three-tier pricing structure across premium enzymatic formulations, standard mechanical tools, and economy breath-freshening products reflects certification-grade differentiation and veterinary dispensing authority. Cost compression in mass-retail tiers intensifies due to employer-sponsored insurance channeling volume toward clinic-dispensed solutions. Dog owners with wellness benefits exhibit lowest price sensitivity; uninsured cat owners facing feline-specific formulation premiums show highest elasticity.
Supply Chain Analysis
Freight costs from Great Plains flavor-chemistry clusters to coastal veterinary distribution hubs elevate landed costs for non-integrated competitors. Raw material sourcing concentrates in United States Midwest agricultural zones, Brazilian beef processing corridors, and European enzymatic fermentation facilities. Single-source vulnerability in chlorhexidine active pharmaceutical ingredients creates exposure to REACH registration delays. Distribution runs through veterinary-exclusive wholesalers, mass-retail consolidation platforms, and direct-to-consumer subscription replenishment models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around regulatory compliance capabilities, with FDA and EPA dual-agency documentation burdens forcing sub-scale manufacturers toward exit or acquisition.
For Market Incumbents:Acquire captive palatant chemistry assets to secure proprietary flavor profiles that drive pet acceptance rates. Build dedicated regulatory affairs capacity in Washington DC corridors to navigate state veterinary board interpretation variance. Channel control through exclusive clinic network partnerships defends against mass-retail price erosion.
For New Entrants and Emerging Players:California state veterinary practice act mandates open a window for telehealth-adjacent distribution models bundling remote consultation with subscription replenishment. Target urban dog owners in employer-sponsored insurance corridors with automated breed-specific chew delivery. Clean-label natural ingredient positioning captures margin expansion as AAFCO guidelines tighten synthetic additive restrictions.
For Investors and Strategic Acquirers:Exit pathways concentrate in trade sales to integrated feedstock processors seeking downstream formulation capabilities. Mid-cap veterinary pharmaceutical specialists with established FDA Master Files offer durable five-to-ten year viability. Watch for state board harmonization of veterinary-client-patient relationship documentation requirements as inflection signal for telehealth distribution model legitimacy.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Palatant Chemistry | Captive flavor-chemistry capabilities secure proprietary poultry and beef profiles that drive pet acceptance rates. |
| Regulatory Affairs Capacity Expansion | Dedicated FDA and EPA compliance teams navigate dual-agency jurisdiction over antimicrobial enzymatic formulations. |
| Veterinary-Exclusive Distribution Partnerships | Exclusive clinic network control creates recurring revenue attachment points with higher switching costs than retail. |
| Clean-Label Formulation Migration | Natural ingredient portfolios capture margin expansion as AAFCO model guidelines tighten synthetic preservender restrictions. |
| Subscription Replenishment Platform Launch | Automated delivery models displace episodic retail purchasing among insured urban dog owners. |
Methodological Framework
Independent corroboration across veterinary practice administrators, regulatory affairs directors at enzymatic formulation manufacturers, procurement leads at veterinary distribution wholesalers, and state board licensing officers underwrites the qualitative findings. Primary interview data triangulates against FDA Center for Veterinary Medicine submission databases, EPA antimicrobial registration records, AAFCO model guideline proceedings, and state veterinary practice act legislative tracking. Bottom-up segment sizing and top-down macro validation converge across the analysis window.
Comparable-period anchoring to historical dispensing volume patterns in California, Texas, and New York veterinary channels establishes the forecast baseline. The projection framework models product type segmentation, end-user channel dynamics, ingredient regulatory classification, and species-specific formulation requirements. CAGRs derive from segment-level growth trajectory synthesis incorporating employer-sponsored insurance penetration curves and state mandate adoption timelines. Enzymatic efficacy trial outcomes and antimicrobial registration approval velocities inform scenario weighting.
The model assumes a particular technology adoption path; alternative pathways for ultrasonic toothbrush systems would alter the outlook if feline bite-force engineering achieves breakthrough compliance reduction. Forecasts incorporate assumptions regarding state veterinary board harmonization and REACH registration timelines that may shift with regulatory priority realignment. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Pet Smart Tracker Market
Pet Care Products
Outdoor Pet Backpack Market
Pet Care Products
Herbal Pet Shampoo Market
Pet Care Products
Saudi Arabia Pet Boarding Market
Pet Care Products
Pet Calming Products Market
Pet Care Products
Dog Boot for Winters Market
Pet Care Products
Indonesia Pet Care Market
Pet Care Products
Electric Pet Clippers Market
Pet Care Products
Pet Toys Market
Pet Care Products
Cat Cage Market
Pet Care Products
Inflatable Pet Collars Market
Pet Care Products
US Pet Treats Market
Pet Care Products
Paw Plunger Market
Pet Care Products
Europe Organic and Natural Pet Food Market
Pet Care Products
Dog Food for Small Breeds Dogs Market
Pet Care Products
Smart Pet Kennel Market