
 Australia Pet Food Market | 2026-2036
Australia Pet Food Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Pet Food Market Analysis
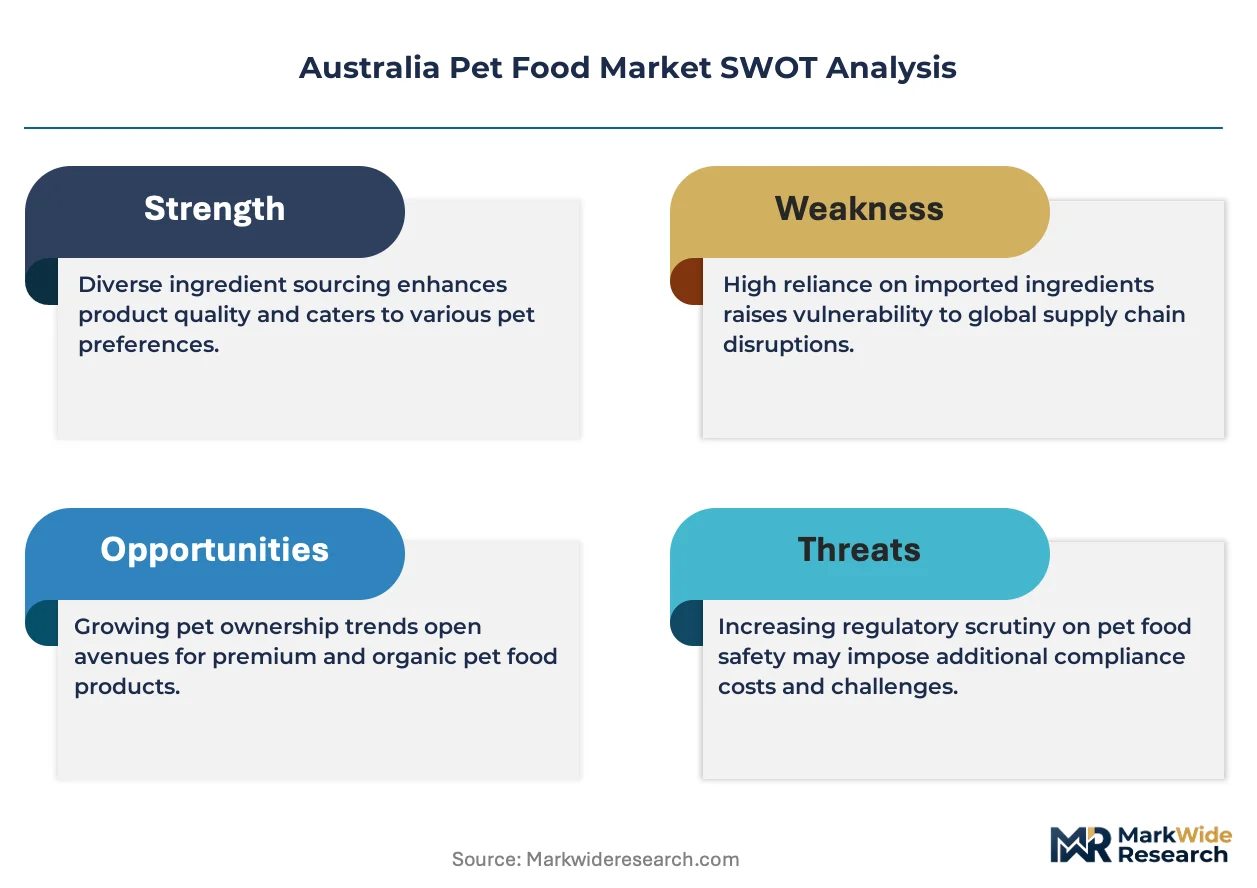
Capital-intensity divergence between multinational manufacturers and domestic boutique brands is reorganizing competitive dynamics across the Australian pet food sector. Mars, Incorporated leverages global procurement networks and captive R&D facilities to sustain cost advantages in mass-market dry food production. Ziwi Limited anchors its position through in-house air-drying operations and controlled sourcing from New Zealand pastoral suppliers. EBOS Group Limited competes via veterinary clinic distribution partnerships that lock in prescription diet channels.
Australia pet food comprises formulated nutritional products manufactured to AAFCO or FEDIAF nutrient profiles, with dry food typically extruded at temperatures exceeding 120 degrees Celsius to achieve shelf stability and pathogen reduction. The category serves commercial purposes spanning daily sustenance, therapeutic intervention, and behavioral reward for companion animals. Dry food occupies the largest volume share due to logistics efficiency and pantry-stocking habits among dog owners, while raw food segments attract the fastest value growth as cold-chain infrastructure expands. Wet food in pouches and cans commands premium shelf positioning in specialty stores, where margin pools concentrate around grain-free and limited-ingredient formulations.
FSANZ sets mandatory labeling and contaminant thresholds that all domestic manufacturers must satisfy before retail placement, while the Australian Pesticides and Veterinary Medicines Authority regulates therapeutic claims on prescription diets. TGA oversight of imported ingredients creates compliance friction for brands relying on offshore protein meal suppliers. Stakeholders must monitor evolving state-level animal welfare disclosure requirements and the potential extension of recycled-content mandates to flexible pet food packaging formats.
Market Dynamics
TGA-aligned nutritional standards are forcing reformulations across dry food portfolios while cold-chain infrastructure expansion unlocks raw food segments previously constrained by distribution economics. Manufacturers must simultaneously satisfy FSANZ contaminant thresholds and state-level animal welfare disclosure mandates.
Growth Catalysts
- Urban pet ownership density:New South Wales and Victoria exceed national averages for companion animal households, creating concentrated demand pools that justify specialty retail investment and localized distribution networks.
- FSANZ labeling modernization:Enhanced nutritional disclosure requirements are elevating consumer literacy around protein sourcing and caloric density, pulling buyers toward premium-positioned formulations with transparent ingredient decks.
- Cold-chain infrastructure:Refrigerated logistics capacity expansion across metropolitan Australia is enabling raw and fresh pet food segments to achieve shelf stability without extrusion-dependent processing methods.
Market Restraints
- Imported protein meal dependency:TGA oversight of offshore ingredient suppliers creates compliance friction and batch-release delays for brands lacking domestic rendering partnerships.
- Veterinary channel concentration:EBOS Group Limited's clinic distribution partnerships lock in prescription diet access, creating barrier-to-entry for new therapeutic claimants without veterinary salesforce investment.
- Grain-free formulation costs:Limited-ingredient diets require alternative carbohydrate sources and specialized extrusion parameters that elevate unit economics relative to conventional wheat- or corn-based recipes.
Strategic Opportunities
- Queensland and Western Australia penetration:Specialty retail density and premium product availability lag Sydney and Melbourne benchmarks, creating whitespace for regional distribution partnerships.
- Recycled-content packaging mandates:Potential extension of sustainability requirements to flexible pet food formats favors early movers with circular supply chain relationships and mono-material pouch development.
- Air-drying technology convergence:Integration of controlled-atmosphere processing with in-house pastoral sourcing enables shelf-stable raw nutrition claims without frozen distribution requirements.
Industry Challenges
- Extrusion engineering talent scarcity:High-temperature processing expertise for pathogen reduction at 120-plus degrees Celsius concentrates among legacy manufacturers, constraining boutique brand scale-up.
- Dual certification complexity:Therapeutic diet producers must satisfy both FSANZ contaminant thresholds and Australian Pesticides and Veterinary Medicines Authority claim substantiation, extending product development timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Pet Food Market |
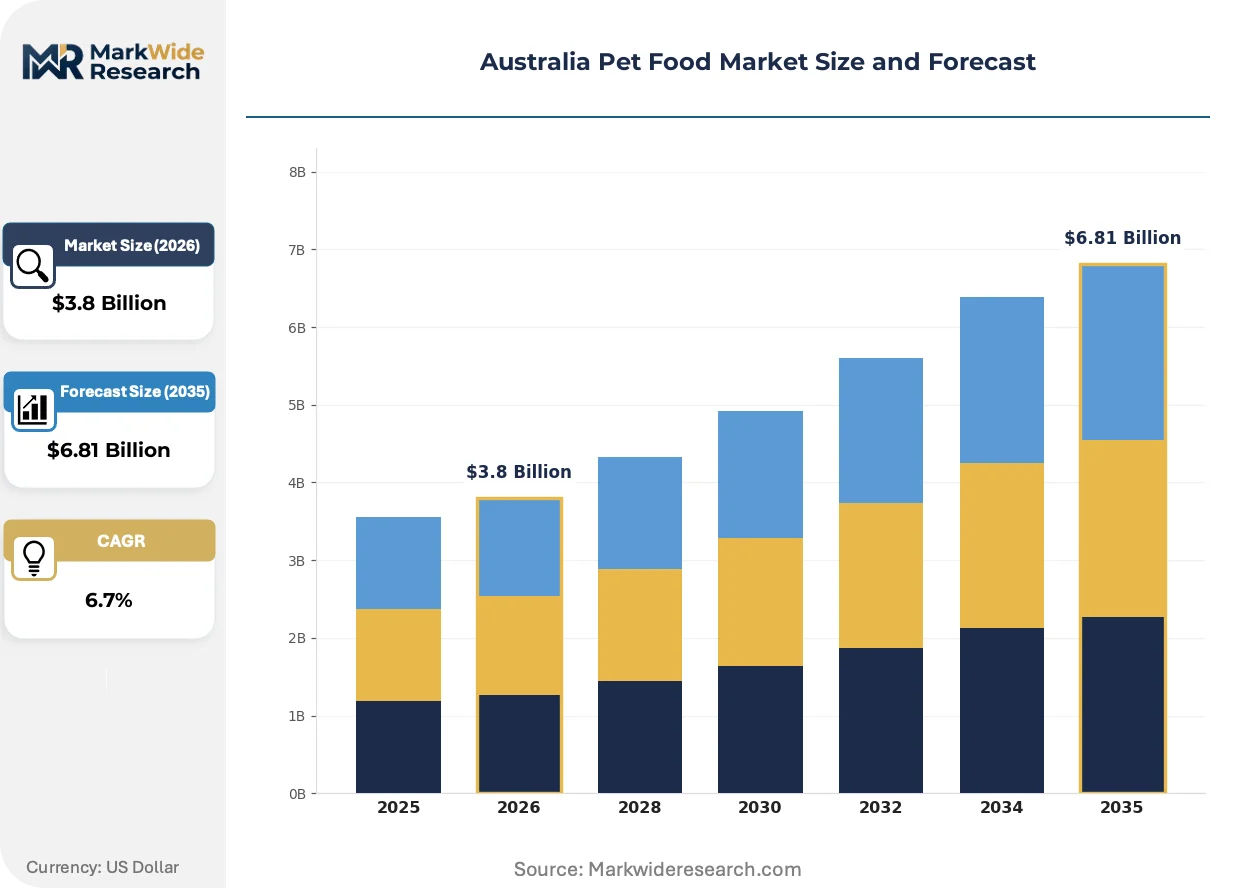
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Food, Wet Food, Treats, Raw Food Customer Type: Dog Owners, Cat Owners, Small Animal Owners, Exotic Pet Owners Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Veterinary Clinics Packaging Type: Bags, Cans, Pouches, Tubs |
| Companies Covered | EBOS Group Limited, Ziwi Limited, Mars, Incorporated, Hypro Pet Care Pty Ltd, Clearlake Capital Group (Wellness Pet Company), Nestle Purina Petcare, Real Pet Food Co., Drools Pet Food Pvt. Ltd., Colgate-Palmolive Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Pet Food Market Emerging Trajectories
Formulation science and distribution infrastructure are diverging along premium-mass market fault lines, with technology adoption patterns splitting between convenience-driven dry food optimization and nutrition-maximizing raw processing methods.
High-pressure processing and controlled-atmosphere drying are fragmenting the traditional extrusion-dominated manufacturing landscape. Boutique manufacturers in Victoria and New South Wales are adopting these methods to preserve enzymatic activity and raw nutritional claims without frozen logistics. The technology is fragmenting volume concentration among multinational dry food producers by enabling smaller-scale regional competitors to achieve differentiated shelf stability.
FSANZ is tightening contaminant thresholds for mycotoxins and heavy metals in imported protein meals, forcing brands with offshore supply dependencies to accelerate domestic rendering partnerships or absorb testing cost escalation. Therapeutic diet segments face the steepest compliance burden given their veterinary channel positioning and claim substantiation requirements under Australian Pesticides and Veterinary Medicines Authority oversight.
Subscription-based replenishment is displacing pantry-stocking purchase patterns among urban dog owners in Sydney and Melbourne. Direct-to-consumer platforms are capturing recurring revenue from premium-segment households while specialty retailers defend position through veterinary-adjacent consultation services. The shift is most visible in grain-free and limited-ingredient categories where purchase frequency and brand loyalty correlate with perceived formulation transparency.
Australia Pet Food Market Segmentation
FSANZ contaminant thresholds and TGA ingredient oversight create divergent compliance burdens across product formats, reshaping how manufacturers allocate capital between extrusion infrastructure and cold-chain logistics. Segmentation clarity reveals where regulatory friction concentrates and where margin pools shift toward premium-positioned formats.
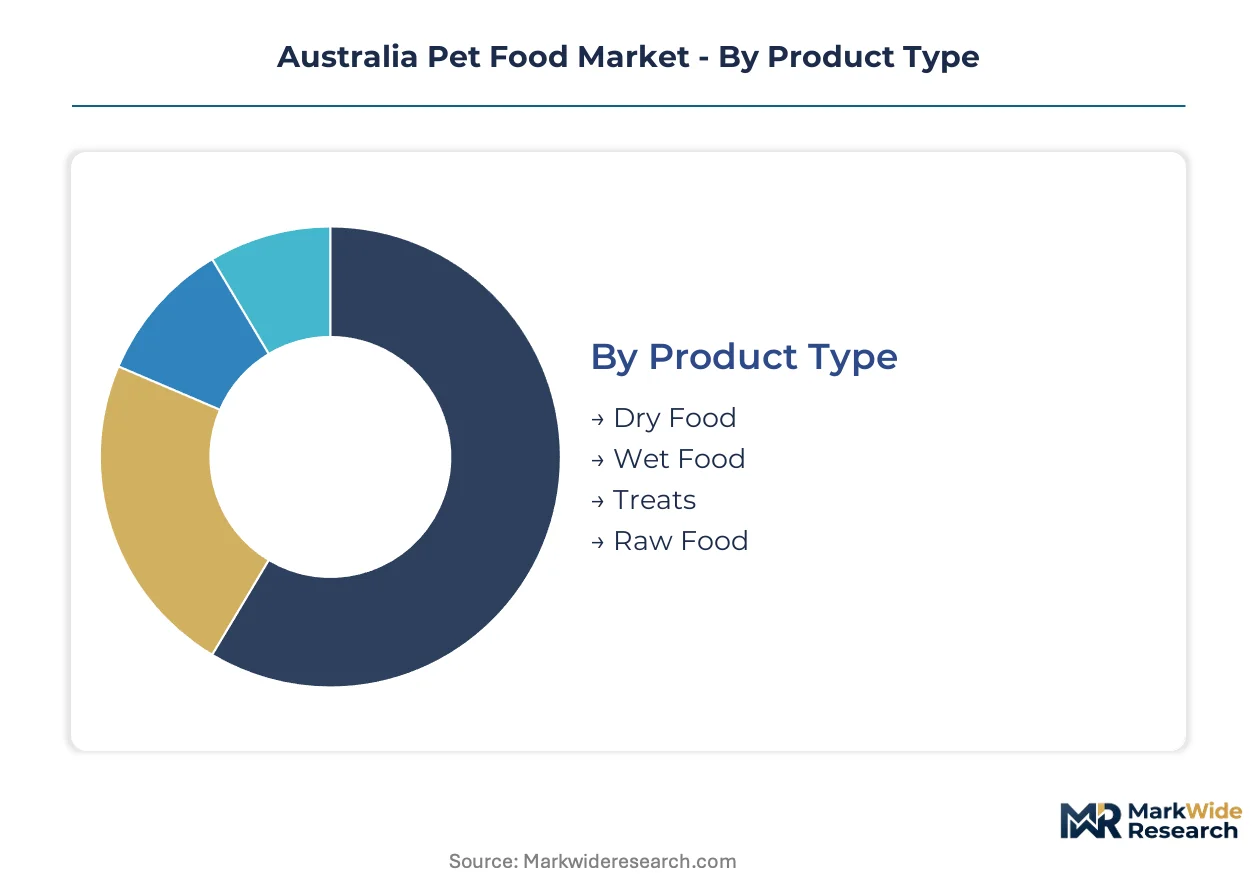
Product Type:
TGA-aligned nutritional standards impose distinct reformulation costs across processing methods, with thermal treatment requirements varying by moisture content and pathogen reduction protocols.
- Dry Food:Extruded at temperatures exceeding 120 degrees Celsius to achieve shelf stability and pathogen reduction. New South Wales and Victoria households favor bulk pantry-stocking formats, though grain-free recipes elevate unit economics through alternative carbohydrate sourcing.
- Raw Food:Cold-chain infrastructure expansion across metropolitan Australia enables shelf-stable distribution without extrusion-dependent processing. Sydney and Melbourne urban pet owners drive demand concentration as refrigerated logistics capacity deepens.
- Wet Food:Retort-processed or pasteurized formulations in cans and pouches serve therapeutic hydration needs and palatability preferences among aging companion animal populations.
- Treats:Limited-ingredient and functional formulations targeting behavioral reward and dental health applications, with specialty retail commanding premium positioning.
Dry Food handles the majority of throughput; Raw Food is gaining share fastest as cold-chain economics improve.
Customer Type:
Urban household density and dwelling size constraints shape species-specific formulation demand across Australian states.
- Dog Owners:Premiumization accelerates as TGA-aligned nutritional standards reshape dry food portfolios. New South Wales and Victoria exceed national averages for companion animal households, justifying specialty retail investment.
- Cat Owners:Wet food and grain-free formulations dominate given obligate carnivore nutritional requirements and smaller portion packaging preferences in metropolitan apartments.
- Small Animal Owners:Niche pellet and hay-based formulations for rabbits, guinea pigs, and rodents, with limited domestic manufacturing concentration.
- Exotic Pet Owners:Specialized live feed and species-specific nutritional products serving reptile, avian, and aquarium segments through veterinary and specialty channels.
Dog Owners represent the largest addressable base; Cat Owners show the steepest expansion trajectory in premium wet and grain-free categories.
Distribution Channel:
Channel economics fragment along consultation intensity and replenishment velocity dimensions, with veterinary partnerships creating locked-in prescription access.
- Online Retail:Subscription-based replenishment displaces pantry-stocking patterns among Sydney and Melbourne premium-segment households. Direct-to-consumer platforms capture recurring revenue through formulation transparency messaging.
- Supermarkets:Mass-market dry food volume concentrates in pantry-stocking formats with logistics efficiency driving margin compression.
- Specialty Stores:Grain-free and limited-ingredient formulations command premium shelf positioning where margin pools concentrate around transparent ingredient decks.
- Veterinary Clinics:EBOS Group Limited's distribution partnerships lock in prescription diet channels, creating barrier-to-entry for therapeutic claimants without dedicated salesforce investment.
Supermarkets move the highest volume; Online Retail is climbing the fastest on share as subscription models penetrate urban markets.
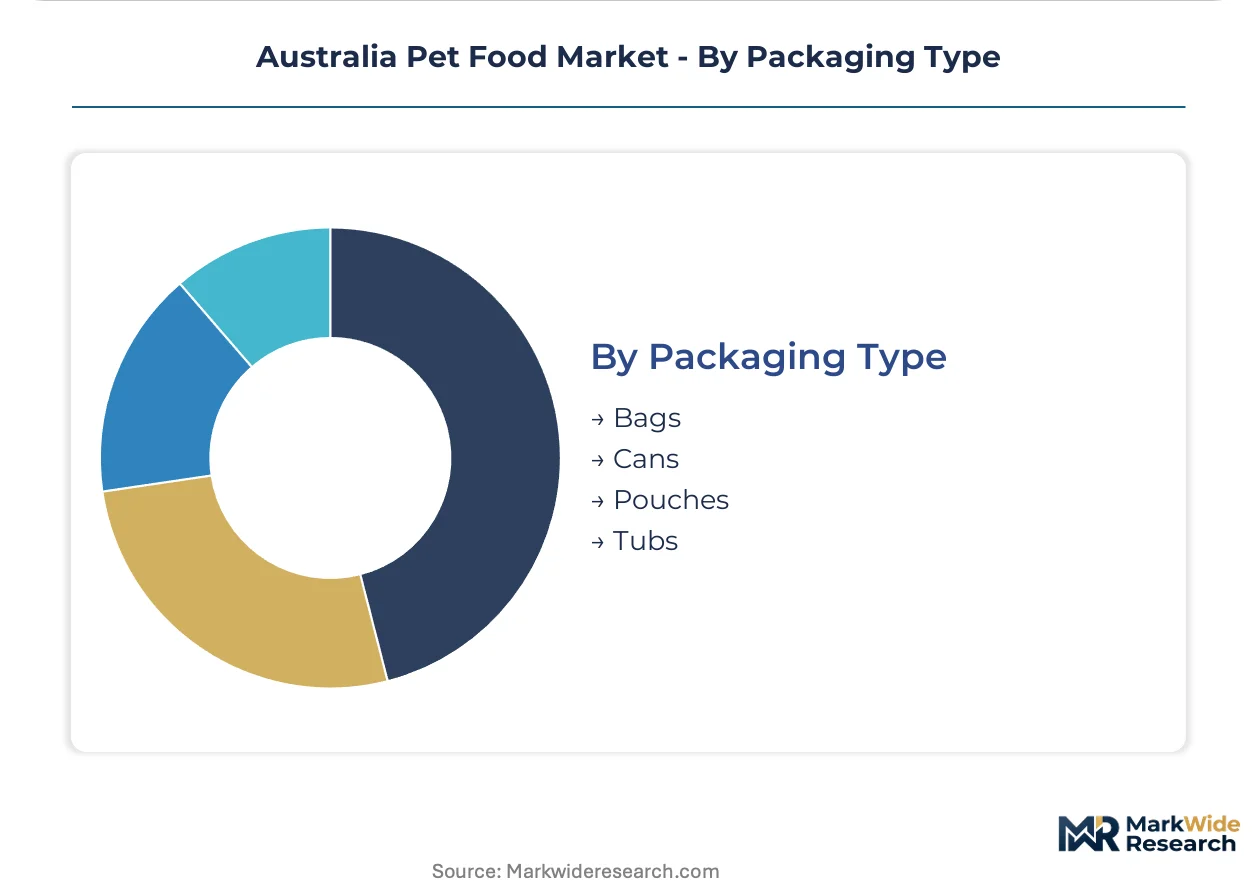
Packaging Type:
Recycled-content mandate exposure and shelf stability requirements drive material selection divergence across format tiers.
- Bags:Multi-layer flexible packaging dominates dry food logistics efficiency, though mono-material development accelerates in anticipation of sustainability regulation extension.
- Cans:Steel and aluminum formats for wet food and therapeutic diets, with established recycling infrastructure offsetting higher material costs.
- Pouches:Premium wet food and treat positioning in specialty retail, where flexible format convenience commands price premiums despite limited circular pathway maturity.
- Tubs:Refrigerated fresh and raw food segments leverage rigid plastic for cold-chain distribution, with resealability supporting portion-controlled feeding patterns.
Bags carry the greatest tonnage; Pouches are expanding most quickly in premium wet and treat applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pet owners in New South Wales and Victoria demonstrate the lowest price elasticity, absorbing premium formulation costs, while Queensland and Western Australia buyers remain more sensitive to unit economics. Metropolitan density and specialty retail penetration explain this divergence. The report maps five states where demand concentration, regulatory compliance burdens, and distribution infrastructure vary materially.
New South Wales
Sydney's apartment-dwelling cat owners drive wet food and grain-free premiumization, with TGA-aligned nutritional standards elevating reformulation costs. FSANZ labeling modernization tightens disclosure requirements for protein sourcing. Parramatta and North Shore retail clusters host the densest specialty store networks, where subscription-based replenishment now captures recurring revenue from transparency-focused households.
Victoria
Melbourne's dog ownership rates exceed national benchmarks, justifying cold-chain infrastructure investment for raw food distribution. State-level animal welfare disclosure mandates add compliance layers beyond federal FSANZ thresholds. The inner-north and bayside suburbs concentrate boutique manufacturer activity, with air-drying operations scaling to serve shelf-stable nutrition demand without frozen logistics.
Queensland
Brisbane and Gold Coast pet owners show higher price sensitivity, with mass-market dry food dominating pantry-stocking patterns. TGA oversight of imported protein meals creates batch-release friction for brands lacking domestic rendering partnerships. Southeast Queensland logistics hubs remain underdeveloped for refrigerated pet food distribution, constraining raw segment penetration relative to southern states.
Western Australia
Perth's geographic isolation elevates freight costs, compressing margins on premium-positioned imports. The state's veterinary channel concentration mirrors national patterns, with clinic distribution partnerships locking prescription diet access. Local manufacturing scarcity forces reliance on eastern states supply chains, delaying fresh format availability and sustaining dry food volume dominance.
South Australia
Adelaide's smaller metropolitan scale limits specialty retail density, though grain-free adoption accelerates among educated urban households. FSANZ contaminant thresholds for mycotoxins apply uniformly, but testing cost burdens fall harder on low-volume distributors. The state's rendering infrastructure gap forces protein meal dependency on interstate or offshore suppliers, amplifying TGA compliance exposure.
Australia Pet Food Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with capital-intensity divergence reorganizing competitive dynamics across the sector. Multinational manufacturers leverage global procurement networks and captive R&D facilities to sustain cost advantages in mass-market dry food production. Boutique brands anchor positions through controlled sourcing and specialized processing methods. The dominant competitive moves are veterinary channel partnerships that lock prescription diet access, and air-drying technology investments that enable shelf-stable raw nutrition claims.
Within the integrated multinational tier, Mars, Incorporated and Nestle Purina Petcare exemplify scale-driven positioning through mass-market dry food dominance and global supply chain leverage. Among domestic specialists, Ziwi Limited occupies a position defined by in-house air-drying operations and controlled New Zealand pastoral sourcing. EBOS Group Limited represents the veterinary channel archetype, with clinic distribution partnerships creating barrier-to-entry for therapeutic diet competitors. These three anchors illustrate how capital access, processing technology, and channel control separate strategic tiers.
| Leading Market Players |
|---|
| EBOS Group Limited |
| Ziwi Limited |
| Mars, Incorporated |
| Hypro Pet Care Pty Ltd |
| Clearlake Capital Group (Wellness Pet Company) |
| Nestle Purina Petcare |
| Real Pet Food Co. |
| Drools Pet Food Pvt. Ltd. |
| Colgate-Palmolive Company |
| Others |
Supply Flow & Price Mechanics
Sixty-to-ninety-day lead times for imported protein meals concentrate pricing power among domestic rendering partnerships while elevating compliance costs for brands tethered to offshore suppliers. Inventory buffers at Sydney and Melbourne distribution centers compress working capital cycles for mass-market dry food producers but strain boutique operators lacking scale economies.
Pricing Analysis
Subscription-based replenishment revenue drives lifetime value as Sydney and Melbourne households shift from pantry-stocking to recurring delivery models. Three-tier pricing structure across premium, standard, and economy levels separates air-dried raw formulations from conventional extruded products and private-label supermarket lines. Cost compression in mass-market dry food intensifies as Mars and Nestle Purina leverage global procurement networks. Price sensitivity concentrates among Queensland and Western Australia buyers, while New South Wales and Victoria households absorb premium positioning costs.
Supply Chain Analysis
Port congestion at Melbourne and Sydney elevates inbound logistics costs for New Zealand-sourced air-dried ingredients and Southeast Asian protein meals. Manufacturing concentration in Victoria and New South Wales draws from New Zealand pastoral suppliers, domestic grain processors, and offshore rendering facilities. Single-source vulnerability runs through TGA-regulated imported protein meal channels. Distribution runs through veterinary clinic partnerships, specialty retail clusters, and direct-to-consumer cold-chain platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as cold-chain infrastructure expansion fragments volume concentration among legacy extrusion-dependent manufacturers, creating niches for regional raw food specialists and air-drying technology adopters.
For Market Incumbents: Shield prescription diet margins by deepening EBOS Group-style veterinary clinic distribution partnerships against emerging therapeutic claimants. Accelerate backward integration into domestic rendering capacity to offset TGA compliance friction on offshore protein meals. Prioritize mono-material pouch development ahead of recycled-content mandate extensions. For New Entrants and Emerging Players: Lead with air-drying technology convergence in Queensland and Western Australia, where specialty retail density lags southern state benchmarks. Target Brisbane and Perth suburban corridors for refrigerated logistics partnerships. Penetrate through subscription-based replenishment platforms emphasizing formulation transparency. For Investors and Strategic Acquirers: Carve-out targets emerge from multinational pet care divisions seeking portfolio simplification; boutique air-drying specialists with controlled New Zealand sourcing command scarcity premiums. Five-to-ten-year viability favors brands with dual FSANZ-APVMA certification capabilities and cold-chain distribution assets. Watch for TGA import policy tightening as inflection signal for domestic rendering capacity valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Veterinary Channel Partnership | EBOS Group's clinic distribution model locks prescription diet access against therapeutic competitors. |
| Air-Drying Technology Investment | Ziwi Limited's controlled-atmosphere operations enable shelf-stable raw claims without frozen logistics. |
| Domestic Rendering Integration | Backward integration into protein meal production reduces TGA batch-release delays and compliance costs. |
| Mono-Material Packaging Development | Early movers on recyclable pouch formats position ahead of FSANZ sustainability mandate extensions. |
| Subscription Platform Launch | Direct-to-consumer replenishment captures recurring revenue from transparency-focused Sydney and Melbourne households. |
Methodological Framework
A standing panel of veterinary clinic procurement managers, specialty retail category buyers, cold-chain logistics operators, and FSANZ regulatory affairs specialists provided ongoing calibration throughout the study. Primary interviews with Mars and Ziwi supply chain executives, EBOS Group distribution leads, and New South Wales rendering facility operators combined with secondary validation against APVMA therapeutic claim registrations, FSANZ labeling databases, and Australian Bureau of Statistics companion animal household surveys. Bottom-up volume builds across product formats and distribution channels triangulated against top-down value estimates derived from retail audit data.
Consistency checks against external benchmarks validated volume and value outputs across the modeling period. Segmentation dimensions included processing method, species-specific formulation, distribution channel intensity, and state-level regulatory burden. CAGRs emerged from trend extrapolation of historical penetration rates adjusted for cold-chain infrastructure buildout timelines and TGA compliance cost trajectories. Forecast inputs incorporated protein meal price volatility indices and specialty retail square footage expansion in metropolitan Australia.
Forecasts assume regulatory continuity in FSANZ contaminant thresholds and TGA import oversight regimes; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Organic Dog Food Market
Pet Care Products
Pet Sitting Market
Pet Care Products
Pet Tick and Flea Prevention Market
Pet Care Products
Mexico Pet Food Market
Pet Care Products
Natural Dog Treat Market
Pet Care Products
Dog Muzzle Market
Pet Care Products
Pet GPS Tracker Market
Pet Care Products
Dog Clippers Market
Pet Care Products
Asia-Pacific Pet Travel Services Market
Pet Care Products
Gcc Pet Food Market
Pet Care Products
Dog Brush Market
Pet Care Products
Global Cat Trees and Towers Market
Pet Care Products
Europe Dog Food Market
Pet Care Products
Cat Litter Product Market
Pet Care Products
PET Market
Pet Care Products
US Dog Food Market