
 Fresh and Frozen Dog Food Market | 2026-2036
Fresh and Frozen Dog Food Market Size, Share, and Industry Trends Forecast 2026-2036
Fresh and Frozen Dog Food Market Foresight
Urban millennial pet owners is rotating toward subscription-based fresh food models, displacing conventional kibble purchasing in higher-income zip codes. Freshpet dominates refrigerated retail distribution through dedicated cooler placements in grocery chains. JustFoodForDogs sustains veterinary channel credibility with open-kitchen formulations and clinic partnerships. The Farmer's Dog leverages direct-to-consumer logistics to control subscription pricing and reduce retail margin leakage.
Fresh and frozen dog food comprises minimally processed animal proteins, vegetables, and supplements stored at or below refrigeration temperatures to preserve enzymatic activity and nutrient bioavailability; the category serves commercial pet nutrition by bridging the gap between raw ancestral diets and convenience-oriented prepared feeding. Frozen meals and raw diet formulations command premium positioning due to perceived digestibility advantages and shorter ingredient decks, while refrigerated snacks represent an emerging margin pool as pet owners seek functional add-ons to core feeding routines. Grain-free and limited-ingredient formulations address the fastest-growing allergy-management segment, though regulatory scrutiny on grain-free cardiac links has redirected some R&D toward ancient-grain alternatives.
FDA Center for Veterinary Medicine and AAFCO model regulations govern ingredient safety and nutritional adequacy claims, while state-level feed control officials inspect cold-chain facilities for pathogen compliance. USDA-FSIS oversight applies to human-grade production facilities, creating a dual-track compliance environment that elevates costs for smaller entrants. Stakeholders must monitor evolving refrigerated pet food labeling standards and cold-chain liability frameworks as the category scales beyond specialty retail into mass grocery distribution.
Market Dynamics
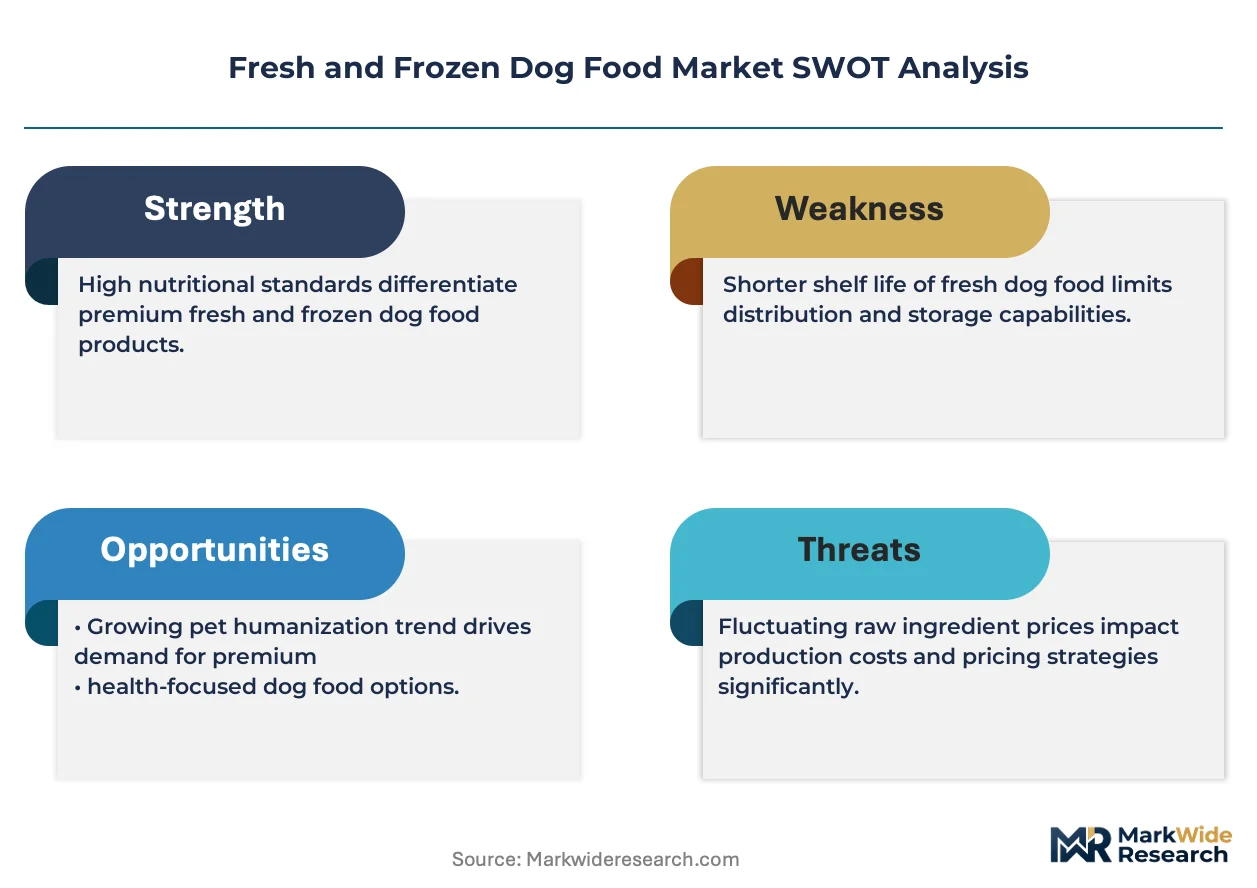
Subscription-based direct-to-consumer logistics is displacing conventional retail distribution in the fresh and frozen dog food category, compressing margin structures and forcing incumbent manufacturers to rebuild cold-chain capabilities around last-mile delivery density rather than store-door wholesale economics.
Growth Catalysts
- AAFCO Nutritional Adequacy Framework:Standardized feeding trial protocols reduce formulation ambiguity for new entrants entering refrigerated pet food production, accelerating product development cycles.
- Urban Cold-Chain Infrastructure:Metro consolidation of refrigerated warehousing and same-day delivery networks enables temperature-controlled subscription fulfillment in high-density zip codes.
- Veterinary Nutrition Counseling:Clinic-based dietary recommendation protocols steer allergy-management cases toward limited-ingredient fresh formulations over conventional therapeutic kibble.
Market Restraints
- Human-Grade Protein Input Costs:USDA-FSIS inspected facility requirements force reliance on human-consumption meat supply chains, exposing margins to beef and poultry commodity volatility.
- Refrigerated Retail Slotting Concentration:Dedicated cooler placements in grocery chains concentrate shelf access under national distribution agreements, marginalizing regional brands.
- Pathogen Compliance Burden:State feed control officials impose lot-tracking and environmental monitoring mandates that elevate fixed costs disproportionately for small-batch producers.
Strategic Opportunities
- Functional Refrigerated Snacks:Dental, hip-and-joint, and calming supplement formats extend addressable occasions beyond core meal replacement.
- USDA-FSIS Human-Grade Certification:Regulatory tailwind from federal inspection status supports premium positioning and cross-channel expansion into human-food retail adjacencies.
- Veterinary Clinic Channel Integration:Prescription fresh diet protocols and open-kitchen demonstration partnerships build professional endorsement moats.
Industry Challenges
- Cold-Chain Logistics Talent Scarcity:Refrigerated transport coordination and temperature-monitoring system management require specialized supply chain expertise in short supply.
- Legacy ERP Integration Friction:Batch-level traceability requirements for FDA Center for Veterinary Medicine compliance collide with inventory systems designed for dry-goods manufacturing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fresh and Frozen Dog Food Market |
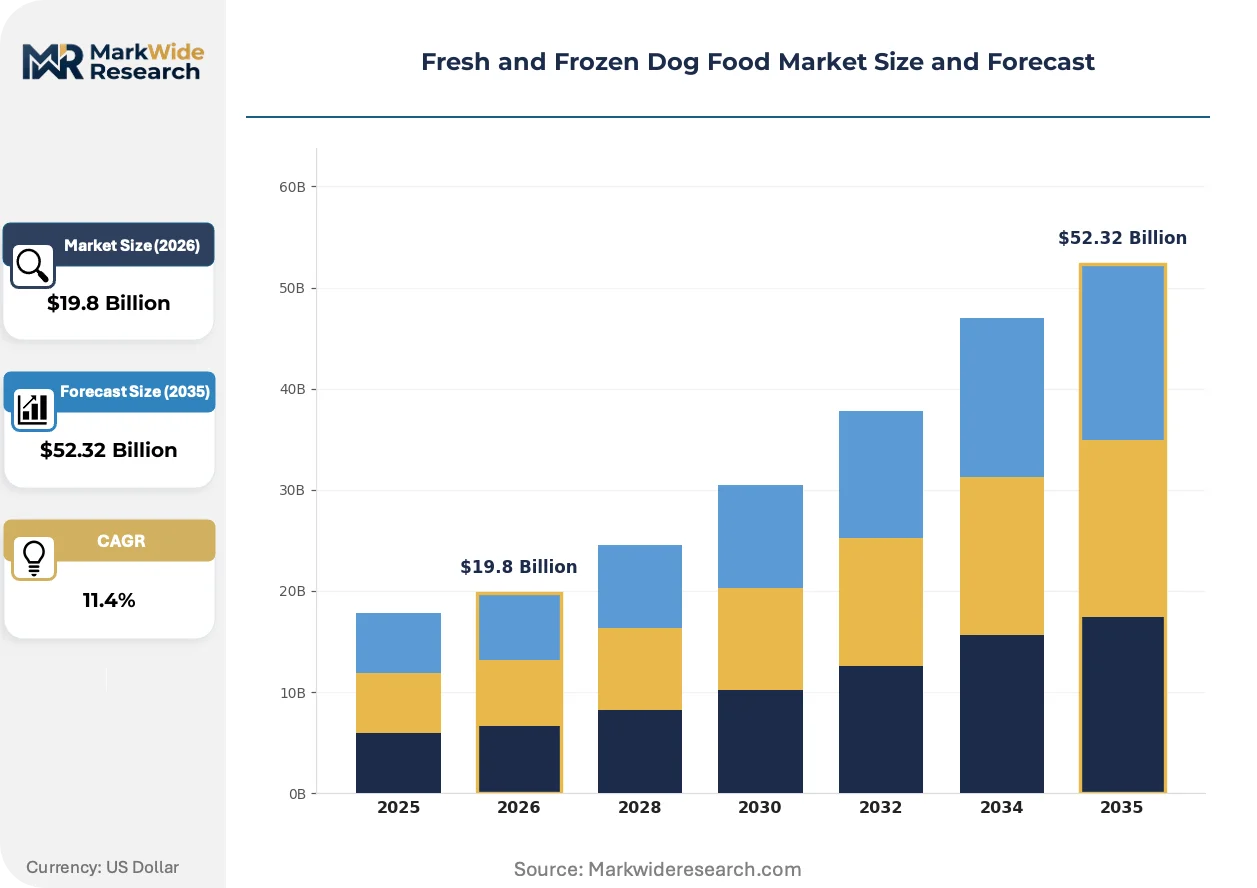
| Market Size in 2026 | $19.8 Billion |
| Market Size in 2035 | $52.32 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fresh Food, Frozen Meals, Raw Diet, Freeze-Dried, Refrigerated Snacks Formulation: Grain-Free, High-Protein, Organic, Limited Ingredient, Hypoallergenic Pet Size: Small Breed, Medium Breed, Large Breed, Giant Breed Distribution Channel: Pet Specialty Stores, Veterinary Clinics, Online Retailers, Grocery Chains, Independent Dealers |
| Companies Covered | Freshpet, JustFoodForDogs, The Farmer's Dog, NomNomNow, Stella & Chewy’s, Primal Pet Foods, Orijen, NW Naturals, Open Farm, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fresh and Frozen Dog Food Market Shifts & Advancements
High-pressure processing and modified-atmosphere packaging are compressing spoilage timelines and reshaping how minimally processed pet food achieves shelf stability without synthetic preservatives.
High-pressure processing applies isostatic pressure to eliminate pathogens while preserving enzymatic activity in raw and lightly cooked formulations. Premium subscription services and veterinary-channel brands are adopting this technology to bridge safety and nutritional claims. The method is displacing traditional thermal pasteurization in refrigerated raw diet segments where heat sensitivity compromises protein bioavailability.
EU F-Gas Regulation phase-down schedules are accelerating refrigeration equipment replacement cycles across European cold-chain infrastructure. Industrial consequence includes stranded asset risk for facilities running legacy hydrofluorocarbon systems and capital reallocation toward natural refrigerant alternatives. Small-batch frozen dog food manufacturers in Germany and France face compressed compliance timelines relative to mass-market producers with centralized distribution.
Pet owner purchasing has migrated toward auto-replenishment subscriptions with flexible portion sizing and veterinary-guided formulation adjustments. Direct-to-consumer platforms are capturing veterinary referral traffic and displacing specialty retail as the primary discovery channel for therapeutic fresh diets. Subscription concentration is most pronounced in coastal US metropolitan corridors where cold-chain density supports reliable delivery windows.
Fresh and Frozen Dog Food Market Segmentation
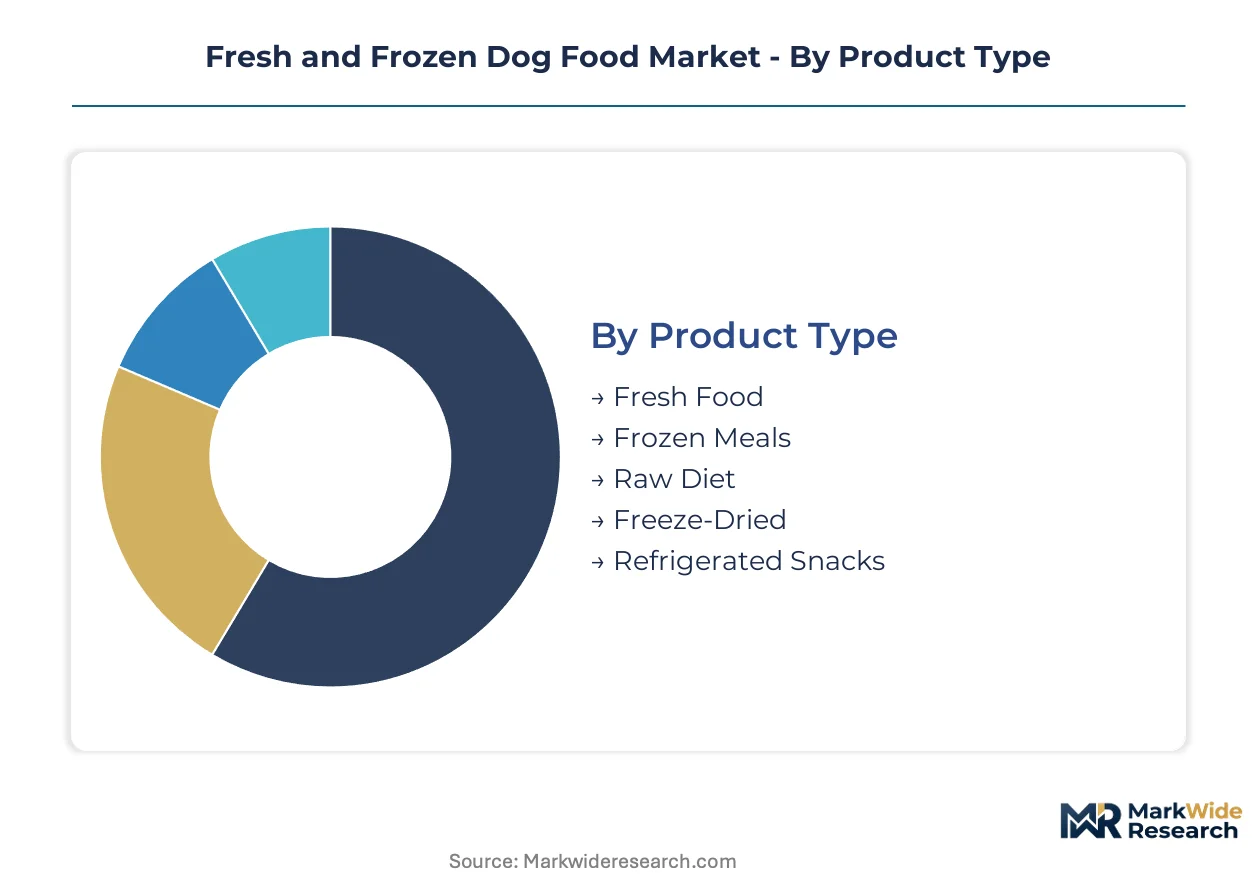
Fresh and frozen dog food segmentation reveals how substitution pressures from conventional kibble, raw diets, and human-grade alternatives fragment purchasing decisions across temperature states, protein formats, and channel access points. Understanding these divides exposes where margin pools concentrate and which formulations face the steepest competitive erosion from adjacent categories.
Product Type:
Substitution pressure runs strongest against frozen meals and raw diets, where home-prepared BARF protocols and commercial raw challengers erode branded positioning, while refrigerated snacks face minimal direct substitute threat due to format uniqueness.
- Fresh Food:Lightly cooked or pasteurized meals requiring continuous refrigeration below 40°F to maintain enzymatic activity and nutrient density. Demand concentrates in coastal US metropolitan corridors where same-day cold-chain delivery supports subscription auto-replenishment models driven by veterinary nutrition counseling protocols.
- Frozen Meals:Flash-frozen complete diets stored at 0°F or below, typically packaged in resealable pouches or trays for portion control. Demand clusters in suburban households with dedicated freezer capacity, constrained by home storage limitations and thaw-cycle inconvenience that drives churn toward fresh alternatives.
- Raw Diet:Unprocessed muscle meat, organ meat, and bone formulations maintained in frozen state until serving. Home-prepared BARF communities and direct-farm sourcing present persistent substitute pressure, particularly in Pacific Northwest and Northeast urban clusters with established raw co-op infrastructure.
- Freeze-Dried:Raw ingredients dehydrated under vacuum pressure for ambient shelf stability with water reconstitution at feeding. Lightweight logistics appeal to travel-oriented pet owners and backup feeding scenarios, though premium positioning limits household penetration.
- Refrigerated Snacks:Chilled functional formats including dental chews, training treats, and supplement-infused bites. Minimal substitute threat from dry alternatives due to palatability differentiation and veterinary endorsement in clinic-channel merchandising.
Fresh food anchors the volume base while refrigerated snacks gain share at the steepest rate.
Formulation:
Cost tier stratification separates premium-positioned organic and hypoallergenic lines from commodity-adjacent grain-free alternatives facing regulatory headwinds.
- Grain-Free:Formulations excluding wheat, corn, and rice in favor of legume, potato, or tapioca carbohydrate sources. FDA Center for Veterinary Medicine investigation into dilated cardiomyopathy associations has redirected R&D investment toward alternative binders and reduced market expansion velocity.
- High-Protein:Diets exceeding AAFCO minimums with animal-derived protein comprising 70% or more of caloric content. Athletic and working dog segments in Texas, Florida, and California drive concentration, supported by performance-oriented breeder and sport-dog trainer recommendations.
- Organic:USDA Organic certified ingredients with prohibited synthetic pesticides, fertilizers, and genetically modified organisms. Premium pricing restricts penetration to households exceeding $150,000 annual income, concentrated in Seattle, San Francisco, and Boston metropolitan statistical areas.
- Limited Ingredient:Single-protein and single-carbohydrate formulations designed for elimination diet protocols and allergy diagnosis. Veterinary dermatology and internal medicine referrals in specialty clinic networks channel demand, particularly for novel proteins like kangaroo, rabbit, and duck.
- Hypoallergenic:Hydrolyzed protein or novel protein formulations with molecular weight reduction to prevent immune recognition. Prescription status through veterinary channels creates formulary access moats, with compounding pharmacy and therapeutic diet manufacturers controlling distribution.
Grain-free formulations retain the largest installed base while limited ingredient diets expand most quickly through veterinary channel integration.
Pet Size:
Volume economics favor large and giant breed segments where per-animal consumption multiplies revenue per household, though small breed density enables premium pricing tolerance.
- Small Breed:Formulations calibrated for dogs under 20 pounds with smaller kibble analogs and higher metabolizable energy density. Urban apartment dwellers in New York, Chicago, and Los Angeles drive concentration, with portion-controlled packaging supporting subscription model stickiness.
- Medium Breed:Intermediate sizing for 20-50 pound dogs with balanced protein-to-fat ratios. Broadest addressable population creates competitive intensity and private-label vulnerability in mass retail channels.
- Large Breed:Controlled calcium and phosphorus profiles supporting orthopedic development in 50-90 pound dogs. Breed club recommendations and veterinary orthopedic surgeon guidance steer Great Dane, German Shepherd, and Labrador Retriever owners toward certified formulations.
- Giant Breed:Specialized growth curve management for dogs exceeding 90 pounds adult weight, with extended puppy feeding protocols. Mastiff, Saint Bernard, and Irish Wolfhound breeder networks maintain concentrated demand with strong price inelasticity.
Large breed diets anchor the volume base while small breed formulations command the steepest premium expansion trajectory.
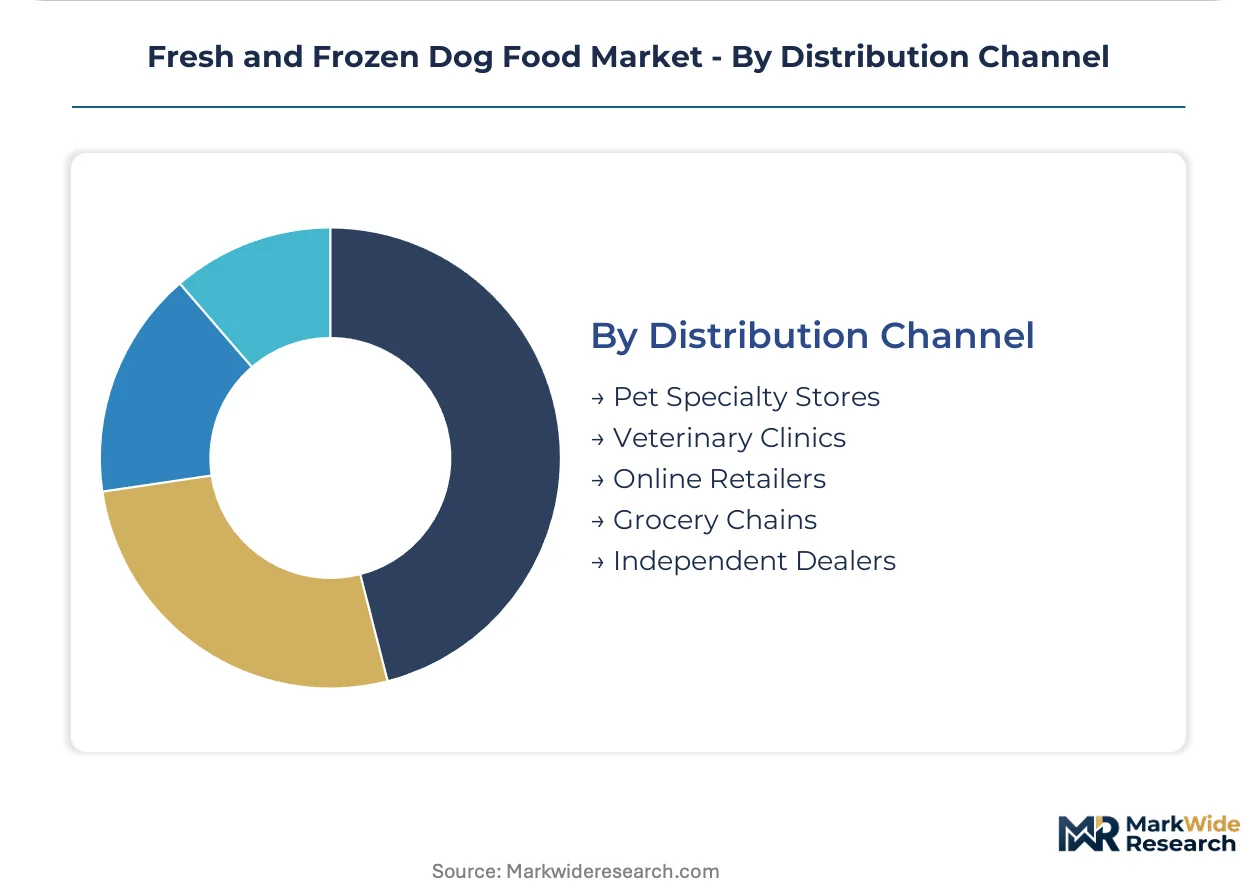
Distribution Channel:
Channel maturity separates established pet specialty and grocery footprints from emerging direct-to-consumer logistics requiring cold-chain infrastructure investment.
- Pet Specialty Stores:Dedicated cooler placements and trained staff consultation in Petco, PetSmart, and independent banners. Shelf-space concentration under national distribution agreements marginalizes regional brands, with reset cycles favoring proven velocity performers.
- Veterinary Clinics:Prescription diet authorization and open-kitchen demonstration partnerships building professional endorsement moats. VCA, Banfield, and independent practice networks control therapeutic fresh diet access, with compliance monitoring supporting recurring revenue.
- Online Retailers:Subscription auto-replenishment with flexible portion sizing and temperature-controlled last-mile delivery. Chewy, Amazon, and brand-direct platforms capture veterinary referral traffic, displacing discovery functions from physical retail in coastal metropolitan corridors.
- Grocery Chains:Mass-market penetration through dedicated refrigerated sections in Kroger, Safeway, and Whole Foods banners. Slotting fee concentration and cooler capital requirements filter entrants, with Freshpet maintaining dominant retail placement.
- Independent Dealers:Regional distributors and boutique pet retailers serving secondary markets with limited cold-chain density. Consolidation pressure from national account concentration threatens long-term viability without subscription logistics partnerships.
Pet specialty stores anchor the volume base while online retailers gain share at the steepest rate through subscription model penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cold-chain rail corridors and refrigerated port terminals underpin regional market development, with urban density and veterinary infrastructure determining subscription penetration rates.
United States
Coastal metropolitan corridors from Boston to Seattle concentrate subscription fulfillment density, driven by millennial pet owner migration to urban centers. FDA Center for Veterinary Medicine oversight shapes formulation standards and pathogen testing protocols. The Pacific Northwest corridor between Portland and Vancouver anchors raw diet co-op infrastructure and direct-farm sourcing networks.
Germany
EU F-Gas Regulation compliance deadlines accelerate refrigeration equipment replacement across Bavarian and North Rhine-Westphalian cold-chain facilities. The country's federal feed control system imposes strict lot-tracking mandates that elevate operational costs for small-batch producers. Berlin-Brandenburg cluster hosts emerging direct-to-consumer platforms targeting urban apartment dwellers with flexible portion sizing.
United Kingdom
London and Southeast England dominate veterinary referral traffic for therapeutic fresh diets, with specialty clinic networks channeling demand toward prescription formulations. FSA and DEFRA regulations govern human-grade production facility standards and cross-border cold-chain integrity. Midlands distribution hubs consolidate refrigerated warehousing for subscription logistics serving Greater Manchester and Birmingham corridors.
Japan
Tokyo-Osaka megalopolis cold-chain density supports premium fresh food subscription models among aging pet owner demographics. Ministry of Agriculture, Forestry and Fisheries (MAFF) and Ministry of Health, Labour and Welfare (MHLW) standards regulate pet food safety and labeling claims. Kansai region specialty retailers maintain dedicated cooler placements for imported and domestic refrigerated brands.
Australia
Sydney and Melbourne metropolitan areas concentrate demand for high-protein and limited-ingredient formulations among working dog and sport-dog owner segments. Australian Pesticides and Veterinary Medicines Authority (APVMA) and FSANZ standards govern ingredient safety and nutritional adequacy claims. Queensland distribution networks face seasonal cold-chain stress from tropical humidity and distance from southern manufacturing clusters.
Fresh and Frozen Dog Food Market Competitive Landscape
Concentration sits with vertically integrated subscription platforms and refrigerated retail specialists, while fragmented regional co-ops and farm-direct raw suppliers occupy niche positions. The market structures around three archetypes: national subscription platforms with captive cold-chain logistics, veterinary-channel brands with professional endorsement moats, and mass-retail refrigerated specialists with dedicated cooler placements. Dominant competitive moves include backward integration into USDA-FSIS inspected production facilities and strategic partnerships with veterinary clinic networks for prescription diet authorization.
Within the subscription-platform archetype, The Farmer's Dog and NomNomNow occupy positions emphasizing direct-to-consumer logistics control and flexible auto-replenishment models. Among veterinary-channel specialists, JustFoodForDogs exemplifies professional credibility through open-kitchen formulations and clinic partnership structures. Freshpet anchors the mass-retail refrigerated segment with dedicated cooler placements across national grocery chains.
| Leading Market Players |
|---|
| Freshpet |
| JustFoodForDogs |
| The Farmer's Dog |
| NomNomNow |
| Stella & Chewy's |
| Primal Pet Foods |
| Orijen |
| NW Naturals |
| Open Farm |
| Others |
Supply & Pricing Matrix
USDA-FSIS human-grade certification gates both supply qualification and price differentiation, forcing producers to absorb inspected-facility overhead while commanding subscription premiums that separate credentialed brands from commodity-adjacent competitors.
Pricing Analysis
Volume-discount tiering structures stratify across subscription auto-replenishment, veterinary prescription authorization, and mass-retail refrigerated placement. Price differentiation hinges on USDA-FSIS facility status and cold-chain delivery density, with coastal metropolitan households showing least price sensitivity and suburban frozen-meal buyers exhibiting highest churn elasticity. Cost compression in frozen raw segments intensifies because home-prepared BARF communities undercut commercial positioning.
Supply Chain Analysis
Just-in-time inventory preferences dominate subscription platforms while strategic stockpiling persists among veterinary-channel brands managing prescription fulfillment buffers. Protein sourcing concentrates in the United States, Australia, and New Zealand, with human-consumption meat supply chains anchoring input costs. Distribution runs through captive cold-chain logistics for direct-to-consumer platforms and dedicated retail cooler networks for mass-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
High-pressure processing adoption constitutes a technological inflection that disrupts thermal pasteurization economics and reshapes competitive moats around enzymatic preservation claims.
For Market Incumbents: Fortify veterinary channel partnerships against subscription-platform encroachment by embedding open-kitchen demonstration protocols in clinic networks. Deepen backward integration into USDA-FSIS inspected production to capture margin from human-grade protein inputs and insulate against commodity volatility.
For New Entrants and Emerging Players: Differentiate on functional refrigerated snack formats targeting dental, hip-and-joint, and calming supplement occasions that incumbent meal-replacement brands underweight. Penetrate secondary metropolitan corridors in Texas, Florida, and Arizona where cold-chain density lags coastal saturation.
For Investors and Strategic Acquirers: EU F-Gas Regulation phase-down schedules reshape the acquisition landscape by stranding legacy refrigeration assets and elevating compliance costs for small-batch European producers. Target vertically integrated subscription platforms with captive logistics infrastructure. Watch refrigerated retail slotting consolidation in national grocery chains as the inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into USDA-FSIS Production | Captures margin leakage from human-grade protein supply chains and supports premium positioning. |
| Veterinary Clinic Channel Partnership | Builds prescription authorization moats and steers allergy-management cases toward fresh formulations. |
| High-Pressure Processing Adoption | Bridges safety and nutritional claims in raw diet segments where heat sensitivity compromises bioavailability. |
| Direct-to-Consumer Logistics Investment | Controls subscription pricing and reduces retail margin leakage in high-density metropolitan corridors. |
| Functional Refrigerated Snack Launch | Extends addressable occasions beyond core meal replacement into dental, joint, and calming supplement formats. |
Research Methodology
Desk research of FDA Center for Veterinary Medicine guidance documents, AAFCO model regulations, and state feed control inspection records preceded structured interviews with cold-chain logistics directors, veterinary nutrition specialists, subscription platform operations leads, and grocery category buyers. Secondary validation drew from USDA-FSIS facility inspection databases, refrigerated transport trade associations, and pet specialty retail audit data. Bottom-up segmentation modeling triangulated against top-down market sizing across product type, formulation, and distribution channel dimensions.
Variance-decomposition framing separated volume growth drivers from price-mix effects across the projection horizon. The analytical framework modeled temperature state, protein format, certification tier, pet size segment, and channel access point as core dimensions. CAGRs derived from logistic diffusion curves fitted to subscription penetration data and cold-chain infrastructure buildout timelines, with veterinary referral traffic and metropolitan household formation as industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained cold-chain investment, stable human-grade protein supply, and regulatory tolerance for refrigerated pet food labeling would require recalibration. Forecasts reflect documented assumptions around subscription retention rates and clinic-channel expansion velocity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
China Pet Boarding Market
Pet Care Products
Gcc Pet Food Market
Pet Care Products
Omega-3 Pet Supplement Market
Pet Care Products
Japan Pet Food Market
Pet Care Products
Canada Pet Food Market
Pet Care Products
Pet Perfume Market
Pet Care Products
Cat Litter Boxes Market
Pet Care Products
Dog Bathing Systems Market
Pet Care Products
Automatic Cat Feeder Market
Pet Care Products
USA Bird Food Market
Pet Care Products
Pet Supplement Market
Pet Care Products
South America Cat Food Market
Pet Care Products
Pet Smart Tracker Market
Pet Care Products
Cat Collar Market
Pet Care Products
Pet Cups Market
Pet Care Products
Large Breed Dog Food Market