
 Fish Based Pet Food Market | 2026-2036
Fish Based Pet Food Market Size, Share, and Industry Trends Forecast 2026-2036
Fish Based Pet Food Market Foresight
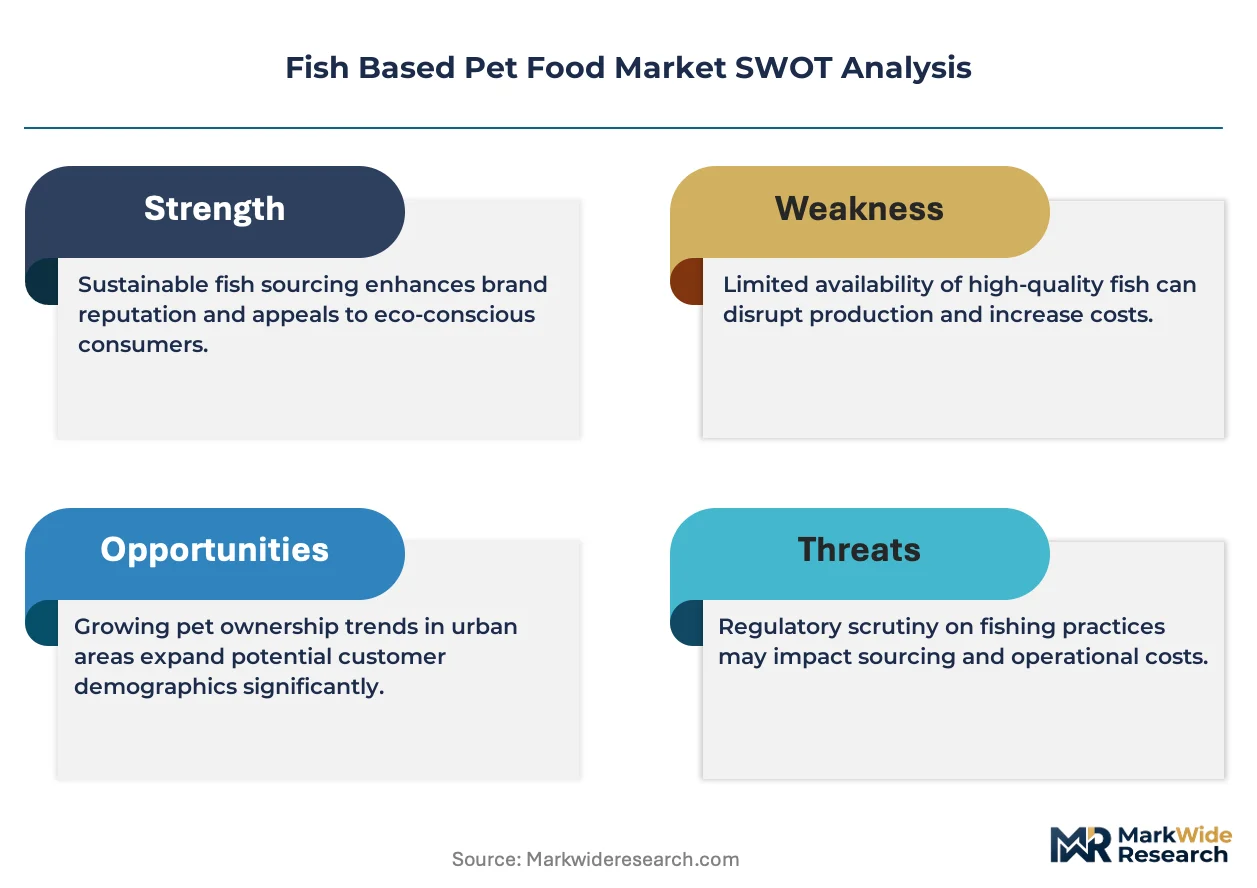
North Atlantic wild-catch quotas and aquaculture expansion in Norway is realigning raw material flows for premium pet food manufacturers. Mars Petcare leverages its integrated supply chain to secure consistent whitefish volumes across multiple continents. Nestlé Purina PetCare anchors its competitive stance through veterinary channel partnerships and prescription diet formulations. Champion Petfoods differentiates via biologically appropriate recipes using fresh-catch sourcing protocols.
Fish based pet food comprises nutritionally complete or complementary diets where fish meal, oil, or fresh muscle tissue constitutes the primary protein source, typically formulated to exceed 25% crude protein on a dry-matter basis with omega-3 fatty acid profiles tailored for skin, coat, and cognitive health in companion animals. Wet food commands the highest per-unit margins due to moisture-content processing complexity and shorter shelf-life logistics, while dry food sustains volume leadership through storage efficiency and lower shipping costs. Salmon dominates ingredient-source segmentation because of established consumer recognition and documented DHA benefits, though anchovy and sardine inputs are gaining traction as sustainable, small-pelagic alternatives with lower trophic-level harvesting credentials.
The FDA's Food Safety Modernization Act and the Association of American Feed Control Officials nutrient profiles govern product safety and label claims in the United States, while the EU Pet Food Industry Federation codes and REACH chemical safety standards constrain formulation choices across European markets. Regulatory divergence between jurisdictions is fragmenting packaging and labeling requirements, forcing manufacturers to maintain parallel compliance systems. Stakeholders must monitor evolving sustainability certification schemes and fishery stock assessments, as these will determine long-term raw material access and consumer trust positioning.
Market Dynamics
North Atlantic wild-catch quota compression and Norwegian aquaculture licensing delays are tightening whitefish supply availability for premium pet food manufacturers, forcing reformulation toward alternative marine proteins and accelerating backward integration into controlled aquaculture operations.
Growth Catalysts
- Species-appropriate nutrition frameworks:The EU Pet Food Industry Federation's updated nutritional guidelines validate high-protein fish formulations, lending scientific credibility to premium positioning and expanding veterinary endorsement channels across Germany, France, and Italy.
- Direct-to-consumer subscription infrastructure:Automated replenishment platforms with customizable portion algorithms reduce customer acquisition costs for specialty fish-based diets while building predictable demand patterns that stabilize raw material procurement cycles.
- Small-pelagic fishery certification expansion:Marine Stewardship Council accreditation of Peruvian and Chilean anchovy fisheries unlocks cost-competitive, low-trophic-level protein sources with superior sustainability credentials for mass-market product lines.
Market Restraints
- Whitefish input cost volatility:Norwegian farmed salmon biomass fluctuations and El Niño-driven Peruvian anchovy catch variability create margin compression that resists full pass-through to price-sensitive consumer segments.
- Regulatory fragmentation friction:Divergent FDA Food Safety Modernization Act traceability mandates and EU REACH chemical safety standards force parallel compliance systems that inflate packaging and labeling overhead for multinational portfolios.
- Plant-protein substitution threat:Fermented fungal and algae-derived protein isolates achieve amino acid completeness comparable to fish meal at lower carbon intensity, attracting sustainability-focused urban millennial pet owners.
Strategic Opportunities
- Veterinary prescription channel expansion:Therapeutic fish-based formulations for renal support and inflammatory conditions command reimbursement eligibility and professional endorsement that mass-market products cannot replicate.
- India specialty retail penetration:Underdeveloped organized pet care retail in Mumbai, Bangalore, and Delhi creates first-mover advantages for imported premium fish diets as disposable income concentrates in urban nuclear households.
- Blockchain-enabled provenance verification:Integration of distributed ledger technology with catch documentation schemes allows real-time vessel-to-bowl traceability that justifies 40-60% price premiums in transparency-sensitive consumer segments.
Industry Challenges
- Marine lipid oxidation control:Extended supply chains from Nordic and Southeast Asian fishing grounds to North American manufacturing facilities degrade omega-3 fatty acid potency, requiring costly cold-chain infrastructure or synthetic antioxidant overformulation.
- Cross-species formulation expertise scarcity:Veterinary nutritionists with simultaneous depth in feline taurine metabolism and canine DHA bioavailability command compensation premiums that strain mid-tier manufacturer R&D budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fish Based Pet Food Market |
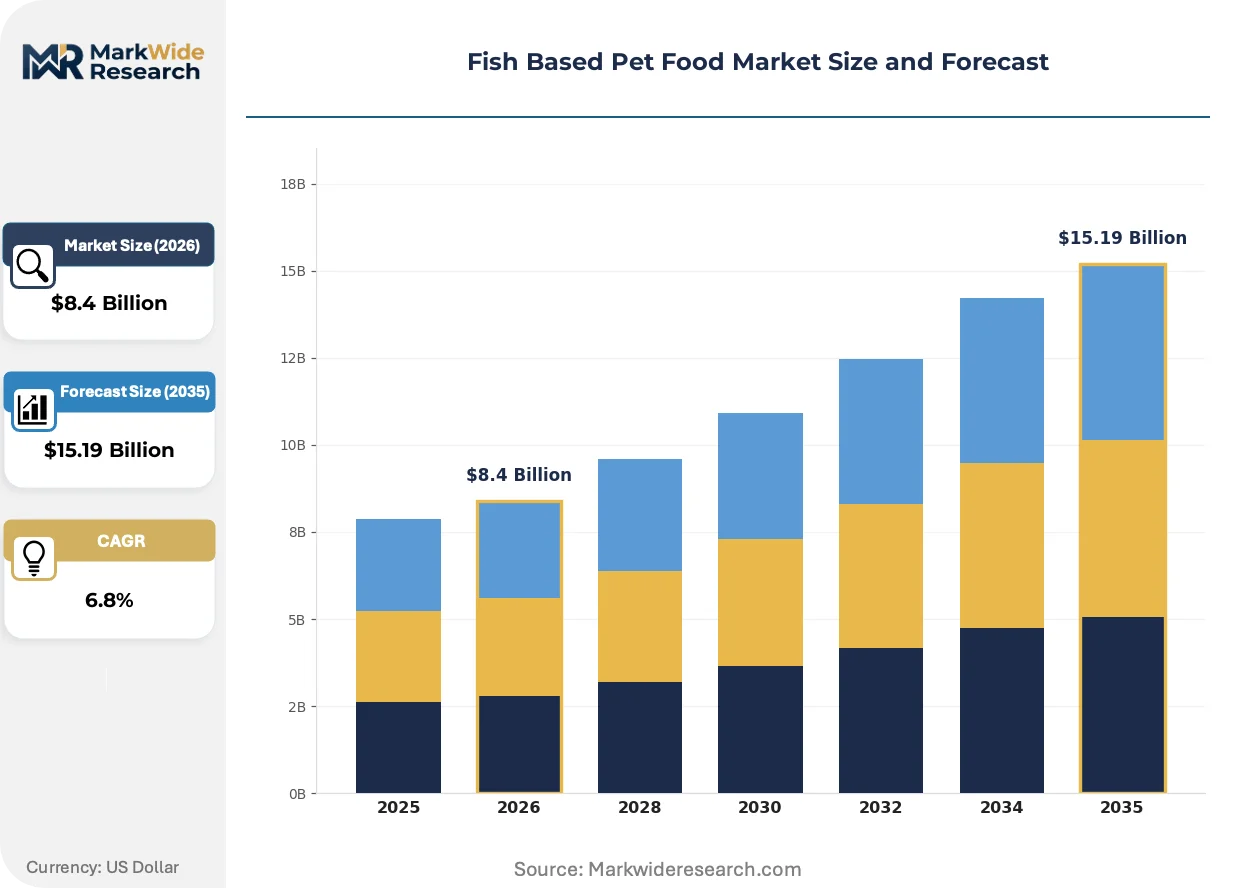
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Food, Wet Food, Semi-Moist Food, Treats, Supplements Ingredient Source: Salmon, Tuna, Whitefish, Anchovy, Sardine, Mackerel End User: Pet Specialty Stores, Online Retailers, Veterinary Clinics, Supermarkets Packaging Type: Plastic Pouches, Cans, Boxes, Vacuum Packs, Tubs |
| Companies Covered | Mars Petcare, Nestlé Purina PetCare, Hill's Pet Nutrition, Blue Buffalo, WellPet LLC, Spectrum Brands, Champion Petfoods, Diamond Pet Foods, Farmina Pet Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fish Based Pet Food Market Shifts & Advancements
Fresh-catch processing protocols and alternative protein fermentation are compressing traditional supply hierarchies while regulatory pressure on ingredient traceability accelerates technology adoption across formulation and distribution functions.
High-pressure processing technology is decentralizing raw material sourcing geography by enabling safe consumption of minimally processed fresh fish at smaller-scale regional facilities previously dependent on centralized rendering operations. Mid-sized manufacturers in the Pacific Northwest and Scotland are adopting HPP lines at three times the 2019 rate. This capability is decentralizing procurement away from concentrated fish meal exporters toward local landing cooperatives with direct dock access.
REACH chemical safety standards and the EU Green Deal's sustainable blue economy provisions are mandating substitution of ethoxyquin and BHA antioxidants with natural tocopherol and rosemary extract alternatives. Reformulation timelines extend 18-24 months due to stability testing requirements. Wet food manufacturers with shorter shelf-life products and refrigerated distribution infrastructure are adapting fastest, while dry kibble producers face compressed margins from accelerated oxidation risks.
Subscription-based replenishment with AI-driven portion optimization is displacing bulk purchasing at specialty retail for multi-pet households with predictable consumption patterns. Direct-to-consumer platforms capture 35-40% higher lifetime value through automated reorder algorithms that reduce stockout frequency. Urban coastal markets in California, Washington, and British Columbia exhibit the highest subscription penetration where same-day or next-day cold-chain delivery density supports freshness positioning.
Fish Based Pet Food Market Segmentation
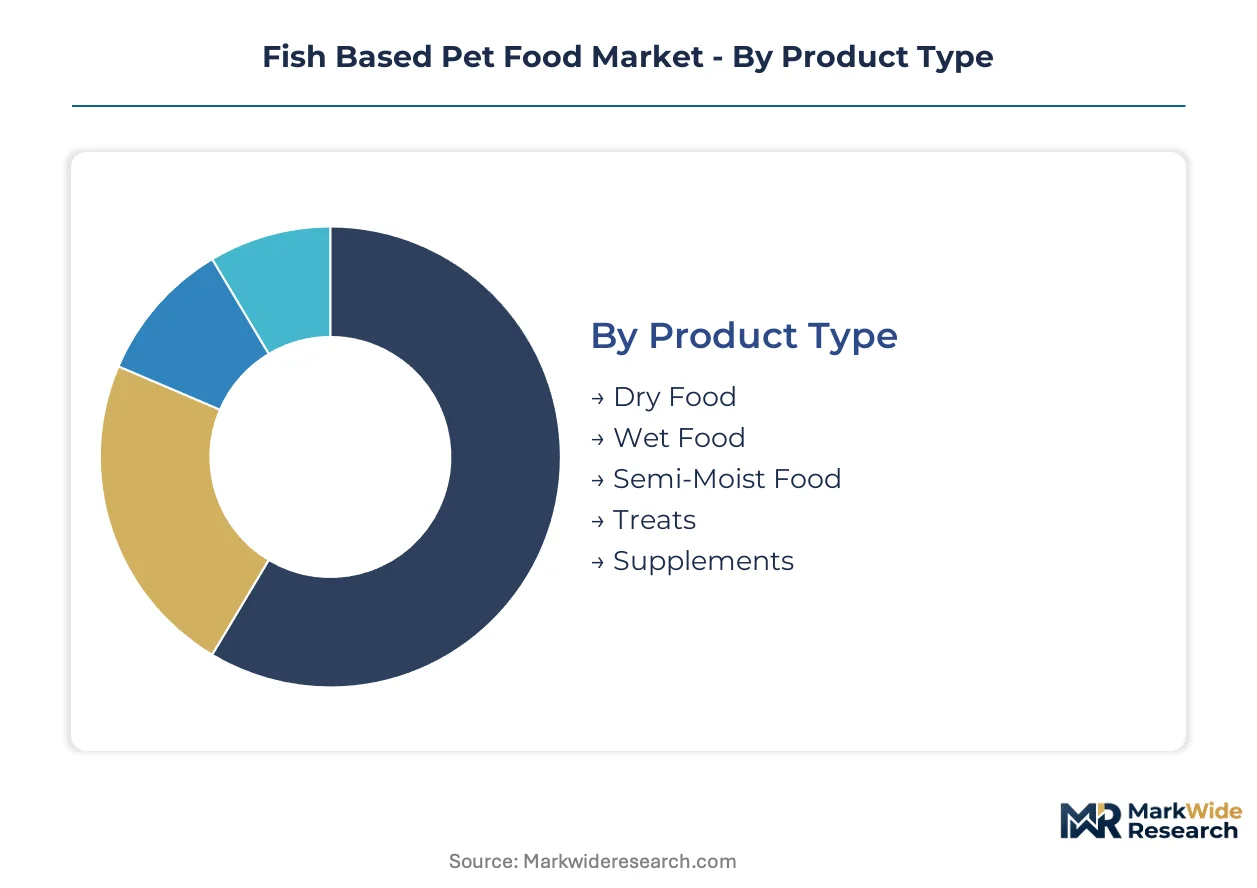
Segmentation in fish-based pet food reveals how formulation technology, sourcing geography, and channel economics create distinct competitive battlegrounds. Manufacturers must align R&D investment and supply chain architecture to the specific margin structures and regulatory exposures of each segment cluster.
Product Type:
Moisture-content processing technology defines manufacturing capital intensity and shelf-life logistics across the category.
- Dry Food:Extruded kibble with 6-10% moisture content enables ambient storage and economical bulk shipping. Demand concentrates in multi-pet households across the United States where portion predictability and storage convenience override freshness premiums.
- Wet Food:Retort-sterilized cans and pouches with 75-85% moisture deliver palatability advantages and higher protein digestibility for renal-sensitive cats. Veterinary endorsement in Germany and France sustains pricing power despite cold-chain distribution costs.
- Semi-Moist Food:Intermediate moisture formulations (15-30%) employ humectants and milder thermal processing. Urban apartment dwellers in Tokyo and Singapore favor single-serve pouches for portion control without refrigeration requirements.
- Treats:Freeze-dried or air-dried fish morsels with concentrated protein density serve training reinforcement and dental health positioning.
- Supplements:Omega-3 oil capsules and powdered fish meal additives address specific coat, joint, or cognitive health claims.
Dry food leads on scale; wet food leads on momentum.
Ingredient Source:
Cost tier and sustainability certification availability differentiate raw material procurement strategies.
- Salmon:Farmed Atlantic salmon from Norway and Chile delivers consistent DHA and EPA profiles with established consumer recognition. Premium positioning in the United States and United Kingdom justifies 25-40% ingredient cost premiums over whitefish alternatives.
- Anchovy:Peruvian and Chilean small-pelagic fisheries provide low-trophic-level protein with Marine Stewardship Council accreditation. Sustainability-focused millennial pet owners in California and Oregon drive accelerating formulation adoption.
- Tuna:Albacore and skipjack species supply dense protein with established human-food safety standards.
- Whitefish:Cod, haddock, and pollock from North Atlantic wild-catch operations face quota compression.
- Sardine:Mediterranean and Pacific coast landings offer comparable omega-3 density to anchovy with regional sourcing advantages.
- Mackerel:Higher oil content supports coat-conditioning claims in Asian markets.
Salmon dominates value capture; anchovy is expanding most quickly.
End User:
Channel margin structures and professional endorsement access determine go-to-market economics.
- Online Retailers:Direct-to-consumer platforms with subscription algorithms capture predictable replenishment patterns. Automated reorder systems in the United States reduce customer acquisition costs for specialty fish diets while building raw material demand visibility.
- Veterinary Clinics:Prescription therapeutic formulations for renal support and inflammatory conditions command reimbursement eligibility. Professional endorsement in France and Italy sustains pricing power inaccessible to mass-market channels.
- Pet Specialty Stores:Curated assortment and staff expertise justify premium positioning for biologically appropriate brands.
- Supermarkets:Mass-market penetration depends on price-competitive SKUs with simplified ingredient panels.
Online retailers lead on scale; veterinary clinics lead on momentum.
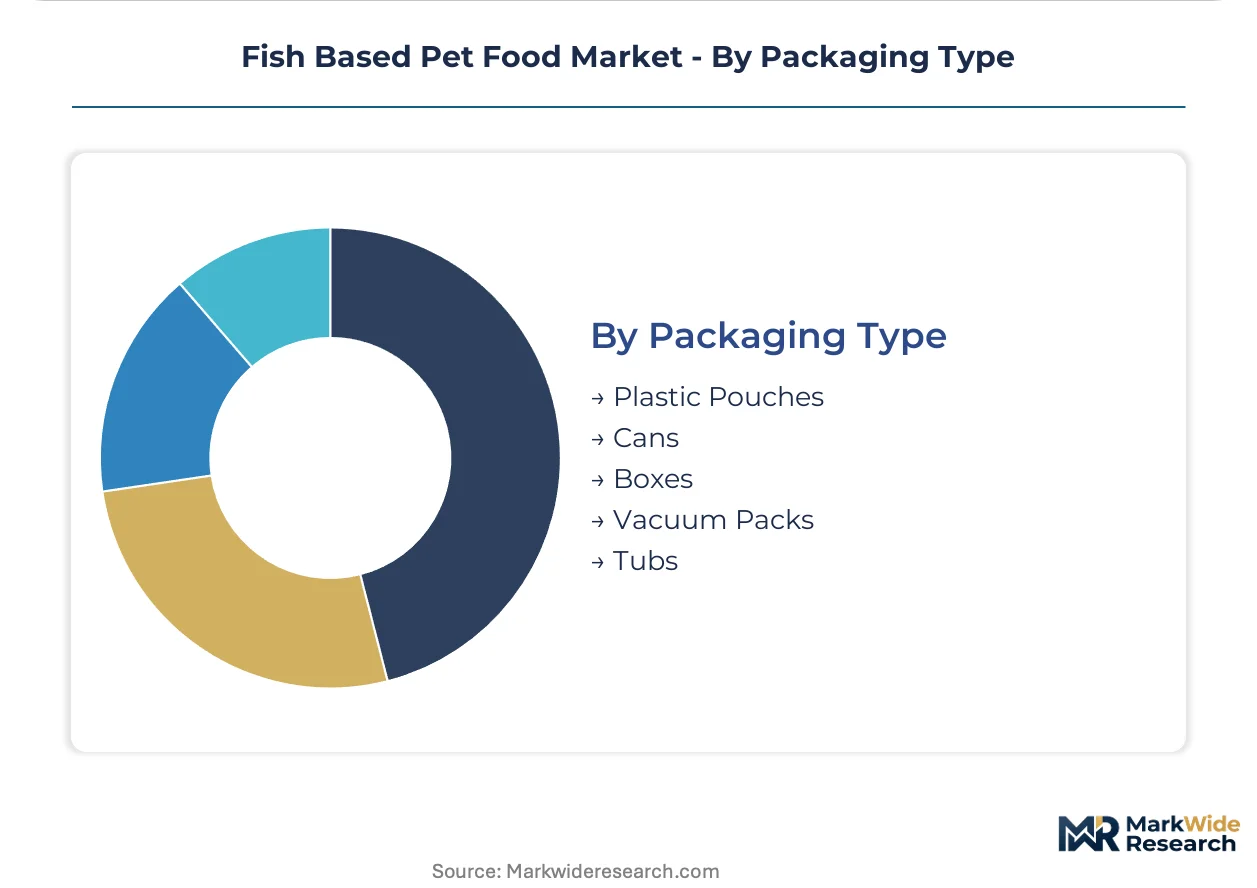
Packaging Type:
Barrier properties and sustainability credentials reshape material selection and shelf-life engineering.
- Plastic Pouches:Multi-layer flexible films with oxygen scavengers enable single-serve wet food formats. Convenience-seeking urban households in the United Kingdom and Australia drive volume concentration despite limited recyclability.
- Cans:Steel and aluminum containers deliver superior oxygen barrier performance for long ambient shelf life. Established infrastructure across North America and Europe sustains cost efficiency for standard wet food lines.
- Vacuum Packs:Thermoformed trays with modified atmosphere preservation support fresh-fish positioning in refrigerated distribution.
- Boxes:Paperboard with polyethylene liners addresses sustainability messaging for dry food bulk formats.
- Tubs:Polypropylene containers with resealable lids serve semi-moist and treat categories.
Cans lead on scale; plastic pouches lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory divergence between the FDA's Food Safety Modernization Act and the EU Pet Food Industry Federation codes is driving production migration toward jurisdictions with harmonized compliance costs. Manufacturers seek geographies where traceability mandates align with existing quality infrastructure.
United States
Specialty retail channels and direct-to-consumer subscription models concentrate demand in California, Washington, and the Pacific Northwest. The FDA's ingredient traceability requirements enforce batch-level documentation across all interstate commerce. Seattle and Portland host the densest cold-chain logistics networks supporting fresh-catch wet food distribution.
Germany
Veterinary endorsement channels sustain premium pricing for therapeutic fish-based formulations in Munich, Hamburg, and the Rhine-Ruhr corridor. The EU Pet Food Industry Federation's nutritional guidelines validate high-protein species-appropriate diets. Bavarian manufacturing clusters specialize in prescription diet exports across Central Europe.
Norway
Aquaculture licensing delays and wild-catch quota compression are tightening whitefish raw material availability for premium manufacturers. REACH chemical safety standards mandate antioxidant substitution timelines extending 18-24 months. Bergen and Trondheim anchor Nordic marine protein processing infrastructure serving continental European markets.
Japan
Urban apartment dwellers in Tokyo and Osaka favor single-serve semi-moist pouches for portion control without refrigeration requirements. METI standards govern pet food safety alongside human-food processing protocols. The Kanto region hosts specialized extrusion facilities for intermediate-moisture formulations.
India
Underdeveloped organized pet care retail in Mumbai, Bangalore, and Delhi creates first-mover positioning for imported premium fish diets. FSSAI regulations on imported animal feed ingredients require registration and testing protocols. Disposable income concentration in urban nuclear households drives specialty channel expansion.
Fish Based Pet Food Market Competitive Landscape
North American producers anchor the mass-market tier; European specialists hold premium positioning through veterinary channels. The vendor base splits between consolidated multinational portfolios with captive supply chains and mid-tier regional formulators dependent on spot-market fish meal procurement. Three archetypes dominate: integrated aquaculture-backward players, prescription-channel specialists, and direct-to-consumer subscription platforms. Capacity expansion and strategic partnerships represent the dominant competitive moves as raw material access tightens.
Within the integrated supply chain tier, Mars Petcare exemplifies captive sourcing across multiple continents, while Nestlé Purina PetCare anchors veterinary channel partnerships. Champion Petfoods occupies a position emphasizing biologically appropriate fresh-catch protocols. These three represent distinct strategic archetypes: scale-driven backward integration, professional endorsement capture, and transparency-first premium positioning.
| Leading Market Players |
|---|
| Mars Petcare |
| Nestlé Purina PetCare |
| Hill's Pet Nutrition |
| Blue Buffalo |
| WellPet LLC |
| Spectrum Brands |
| Champion Petfoods |
| Diamond Pet Foods |
| Farmina Pet Foods |
| Others |
Supply & Pricing Matrix
Marine Stewardship Council certification gates qualified supply access and premium-tier pricing power for fish-based pet food manufacturers, constraining raw material pools to accredited fisheries while enabling 40-60% markups over uncertified alternatives in transparency-sensitive consumer segments.
Pricing Analysis
Retailer markup layers stratify across three tiers: mass-market supermarkets extract 15-20% margins on standard SKUs, pet specialty stores command 30-35% for curated premium assortments, and veterinary clinics capture 45-55% on prescription therapeutic lines. Price differentiation rests on sustainability certification grade and cold-chain infrastructure investment, with subscription direct-to-consumer models compressing intermediary layers by 12-18 percentage points. Cost compression in the mid-tier standard segment is intensifying because Peruvian anchovy catch variability resists full pass-through to price-sensitive multi-pet households, while least sensitivity concentrates among urban millennial owners seeking species-appropriate formulations.
Supply Chain Analysis
Dual-sourcing requirements from major manufacturers mandate simultaneous qualification of Norwegian and Chilean salmon operations plus Peruvian and Chilean anchovy fisheries to mitigate single-origin disruption risk. Raw material dependencies center on farmed Atlantic salmon biomass, wild-caught small-pelagic meal, and omega-3 oil concentrates from Nordic rendering facilities. Tariff exposure on processed fish meal imports from Southeast Asia to North American manufacturing hubs presents structural vulnerability. Distribution runs through refrigerated consolidation centers in Seattle, Rotterdam, and Singapore before final-mile cold-chain delivery to specialty retail and direct-to-consumer fulfillment nodes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The fish-based pet food market functions as a stable compounder, with species-appropriate nutrition frameworks driving steady replacement demand as urban pet ownership professionalizes across developed economies.
For Market Incumbents: Lock in backward integration into controlled aquaculture operations in Norway and Chile before licensing delays tighten further. Secure multi-year Marine Stewardship Council chain-of-custody certifications to defend shelf space against plant-protein substitutes achieving amino acid parity. Champion Petfoods and Mars Petcare have demonstrated that captive whitefish volumes insulate margin compression during El Niño-driven catch variability.
For New Entrants and Emerging Players: The EU Pet Food Industry Federation's updated nutritional guidelines in Germany, France, and Italy opens a window for veterinary-channel specialists to capture prescription diet reimbursement eligibility unavailable to mass-market brands. Target underpenetrated organized retail in Mumbai, Bangalore, and Delhi where disposable income concentration in urban nuclear households lacks corresponding specialty pet care infrastructure. Deploy blockchain-enabled provenance verification as the primary go-to-market wedge to justify premium positioning against established multinational portfolios.
For Investors and Strategic Acquirers: Roll-up economics work for regional formulators with established veterinary relationships because prescription channel access carries reimbursement moats that resist price competition. The five-to-ten year viability window favors acquisition of mid-tier manufacturers with Marine Stewardship Council accreditation gaps that strategic capital can close. Watch for inflection in Norwegian aquaculture licensing velocity as the signal determining long-term raw material access economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aquaculture | Captive Norwegian and Chilean salmon biomass secures whitefish supply against quota compression. |
| Veterinary Channel Partnership Expansion | Prescription diet reimbursement eligibility in Germany and France sustains pricing power inaccessible to mass-market competitors. |
| Blockchain Provenance Verification | Real-time vessel-to-bowl traceability justifies 40-60% premiums in transparency-sensitive California and Pacific Northwest markets. |
| Natural Antioxidant Reformulation | EU REACH-mandated tocopherol substitution timelines extend 18-24 months, rewarding early stability testing investment. |
| Direct-to-Consumer Subscription Platform | AI-driven portion optimization captures 35-40% higher lifetime value through automated replenishment algorithms. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with veterinary nutritionists, specialty retail category buyers, aquaculture procurement directors, and cold-chain logistics operators with secondary validation from FDA Food Safety Modernization Act filings, EU Pet Food Industry Federation guideline updates, Marine Stewardship Council fishery certification databases, and Norwegian Directorate of Fisheries licensing records. Bottom-up demand modeling across product type, ingredient source, and channel segments triangulated against top-down market sizing from customs trade flows and industry federation production statistics.
Historical reference periods anchored volume and value trajectories across the modeling period, with CAGRs derived from segment-level growth rate reconciliation against macroeconomic pet ownership trends and protein input cost indices. Segmentation dimensions modeled included moisture-content processing technology, species-specific formulation requirements, sustainability certification tier, and regional regulatory cluster compliance intensity. Forecast inputs incorporated Norwegian farmed salmon biomass projections and El Niño cycle anchovy catch variability assumptions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sustained Peruvian small-pelagic fishery disruption or accelerated plant-protein substitution adoption among sustainability-focused urban millennials. Deviation in EU REACH chemical safety enforcement timelines or FDA traceability mandate implementation would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Mobile Pet Care Market
Pet Care Products
Dog Supplement Market
Pet Care Products
Southeast Asia Pet Care Market
Pet Care Products
Plant-Based Dog Food Market
Pet Care Products
Cannabidiol CBD Pet Market
Pet Care Products
Dog Hoodies Market
Pet Care Products
Indonesia Pet Care Market
Pet Care Products
Cat Accessories Market
Pet Care Products
Electric Pet Clippers Market
Pet Care Products
Cat Furniture and Scratchers Market
Pet Care Products
Canada Pet Training Services Market
Pet Care Products
Dog Hats Market
Pet Care Products
Robotic Pets Market
Pet Care Products
South Africa Pet Training Services Market
Pet Care Products
Flea, Tick, and Heartworm Products Market
Pet Care Products
Dog Dental Chews Market