
 Pet Feeder Market | 2026-2036
Pet Feeder Market Size, Share, and Industry Trends Forecast 2026-2036
Pet Feeder Market Analytics
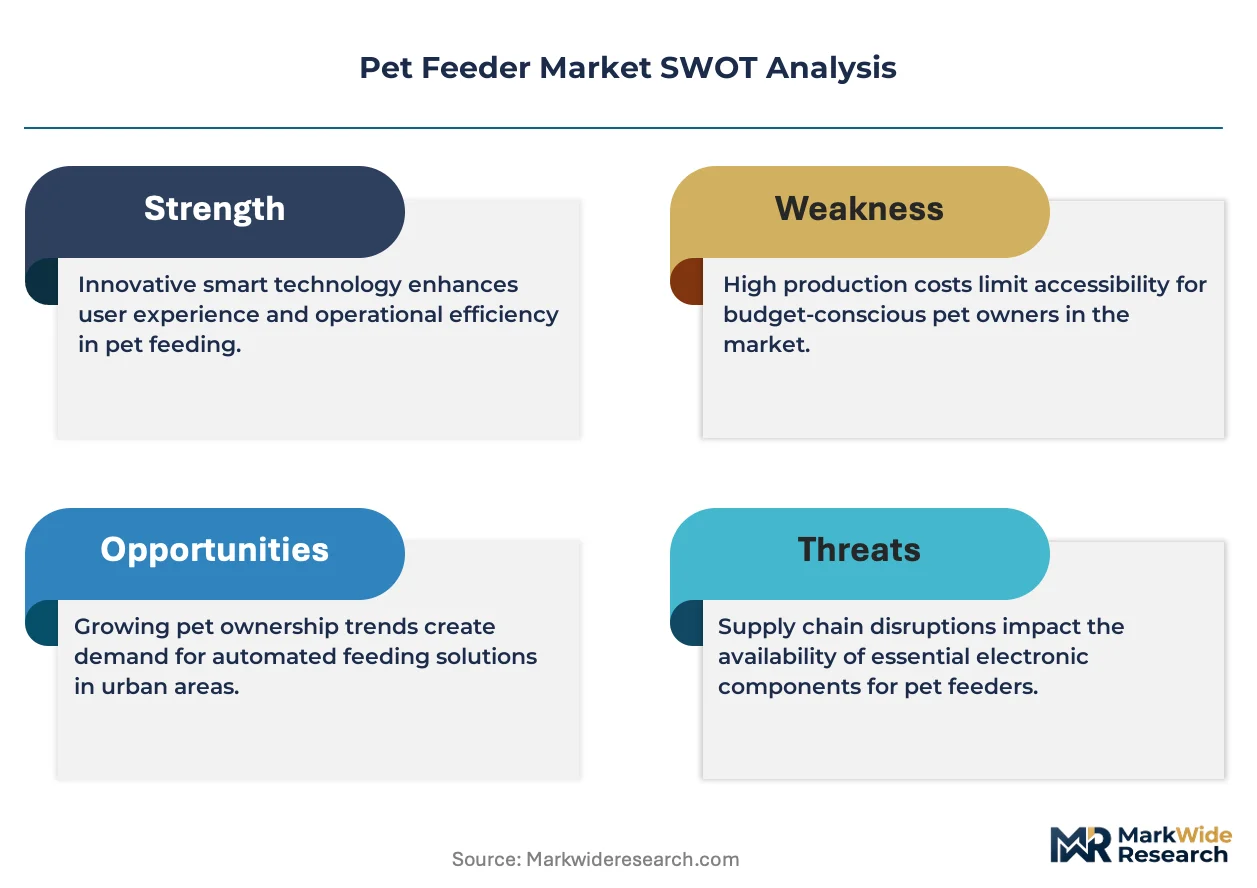
The pet feeder category is restructuring around a sharp split between app-enabled smart dispensers and basic gravity-fed units. Xiaomi leverages its IoT ecosystem to dominate connected feeding hardware at aggressive price points. PetSafe sustains brand authority across North American retail channels with broad distribution and veterinary endorsements. Petkit differentiates through integrated health-monitoring features that track consumption patterns and flag behavioral anomalies.
A pet feeder is a containerized dispensing device engineered to store, portion, and deliver food or water to companion animals on scheduled intervals or demand-triggered release, typically constructed from food-grade polymers, stainless steel, or ceramic with sealed hopper designs to preserve freshness and prevent contamination. Smart variants incorporate load-cell weighing, camera surveillance, and Wi-Fi connectivity to enable remote monitoring and dietary precision for owners managing obesity or medical conditions. Automatic feeders lead value generation due to premium pricing of electronic timer and sensor-integrated models, while smart feeders represent the fastest-expanding segment as pet humanization trends elevate willingness to pay for connected care infrastructure. Stainless steel bowls command margin concentration in the material dimension because of durability claims and veterinary preference for non-porous, bacteria-resistant surfaces.
The FDA Center for Veterinary Medicine oversees pet food contact material safety, compelling manufacturers to validate polymer and coating compositions for migration risk. The FCC regulates wireless transmission protocols in smart feeders, creating compliance barriers for unlicensed spectrum use and data transmission architectures. California Proposition 65 adds state-level chemical disclosure obligations that influence material selection and labeling investments. Stakeholders must monitor evolving interoperability standards between feeder hardware and third-party veterinary platforms as the sector moves toward integrated health data ecosystems.
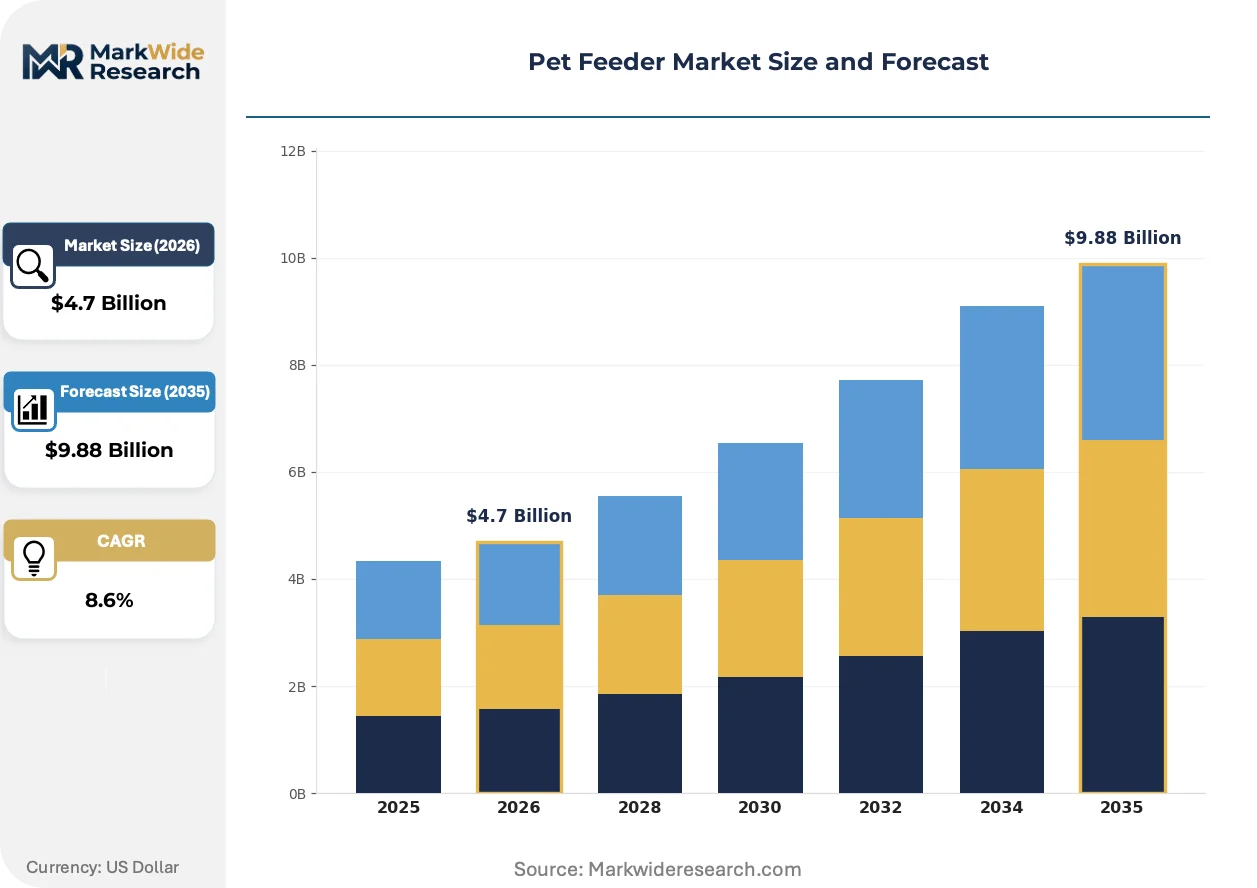
Market Dynamics
The pet feeder market is restructuring around the collision between smart home infrastructure penetration and veterinary-grade precision feeding requirements. Connected dispenser adoption accelerates as apartment-dwelling pet owners seek remote monitoring capabilities for portion control and behavioral tracking.
Growth Catalysts
- Smart Home Ecosystem Convergence:Wi-Fi-enabled feeders are integrating with voice assistants and home automation platforms, creating stickier purchase decisions for tech-forward households. This interoperability reduces switching costs between device brands.
- FDA Material Safety Standards:The Center for Veterinary Medicine's contact material guidelines are elevating baseline quality expectations, pushing marginal manufacturers toward food-grade polymer validation and certified coating compliance.
- Urban Pet Density:High-rise apartment living in metropolitan clusters concentrates demand for space-efficient, scheduled feeding solutions that reduce noise complaints and neighbor conflicts.
Market Restraints
- Semiconductor Supply Concentration:Load-cell sensors and Wi-Fi modules face sourcing bottlenecks from concentrated Asian foundry capacity, creating lead time volatility for smart feeder assembly.
- Substitution from Manual Feeding:Low-tech gravity bowls and timed mechanical dispensers retain cost advantage for price-sensitive owners, capping premium smart feeder penetration in budget segments.
- FCC Wireless Certification Friction:Unlicensed spectrum compliance for 2.4GHz and 5GHz transmission protocols adds months to product launch timelines and restricts firmware update architectures.
Strategic Opportunities
- Veterinary Platform Integration:API connectivity with telehealth and prescription diet management systems creates recurring revenue attachment for clinics recommending monitored feeding regimens.
- Subscription Consumables:Portion-controlled kibble and fresh food delivery bundles tied to dispenser usage data build predictable recurring revenue streams beyond hardware margins.
- California Proposition 65 Differentiation:Proactive chemical disclosure and BPA-free material positioning command shelf space in retail channels with stringent state-level labeling requirements.
Industry Challenges
- Cybersecurity Certification Complexity:IoT device penetration testing and data encryption standards for pet camera feeds require specialized firmware engineering talent that hardware manufacturers struggle to retain.
- Cross-Border Data Governance:Smart feeder cloud architectures must navigate fragmented privacy regulations across state and national jurisdictions, complicating unified platform deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pet Feeder Market |
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $9.88 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic Feeders, Gravity Feeders, Bowl Feeders, Smart Feeders Material: Plastic, Stainless Steel, Ceramic, Wood End User: Pet Owners, Pet Care Facilities, Animal Shelters, Veterinary Clinics Capacity: Small, Medium, Large, Extra Large |
| Companies Covered | PetSafe, Xiaomi, Dogness Group, Sure Petcare, Petkit, WOPET, Petlibro, Skymee, Petmate, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pet Feeder Market Evolving Landscape
Hardware differentiation is compressing as software-enabled services and data monetization emerge as the primary value capture mechanisms. Manufacturers are racing to own the dietary data layer rather than compete solely on dispensing mechanics.
Computer vision is integrating directly into feeder base stations, enabling real-time pet identification and consumption verification without separate collar-mounted devices. Multi-pet households in the United States are adopting camera-equipped models at accelerated rates. This convergence is compressing standalone pet camera sales while expanding total feeder addressable market.
The EU Green Deal's circular economy requirements are mandating recycled polymer content disclosures and end-of-life takeback provisions for electronic pet care devices. German retailers are demanding EPR compliance documentation before listing smart feeders. This regulatory pressure is forcing Asian contract manufacturers to requalify material streams and redesign housings for disassembly.
Pet owners are unbundling after-sales service expectations, demanding app-based troubleshooting and video-guided maintenance rather than traditional warranty claim processes. Direct-to-consumer brands are capturing this shift through chatbot-enabled support and replacement part subscription programs. This behavioral pivot is most pronounced in coastal United States metros with high smart home penetration.
Pet Feeder Market Segmentation
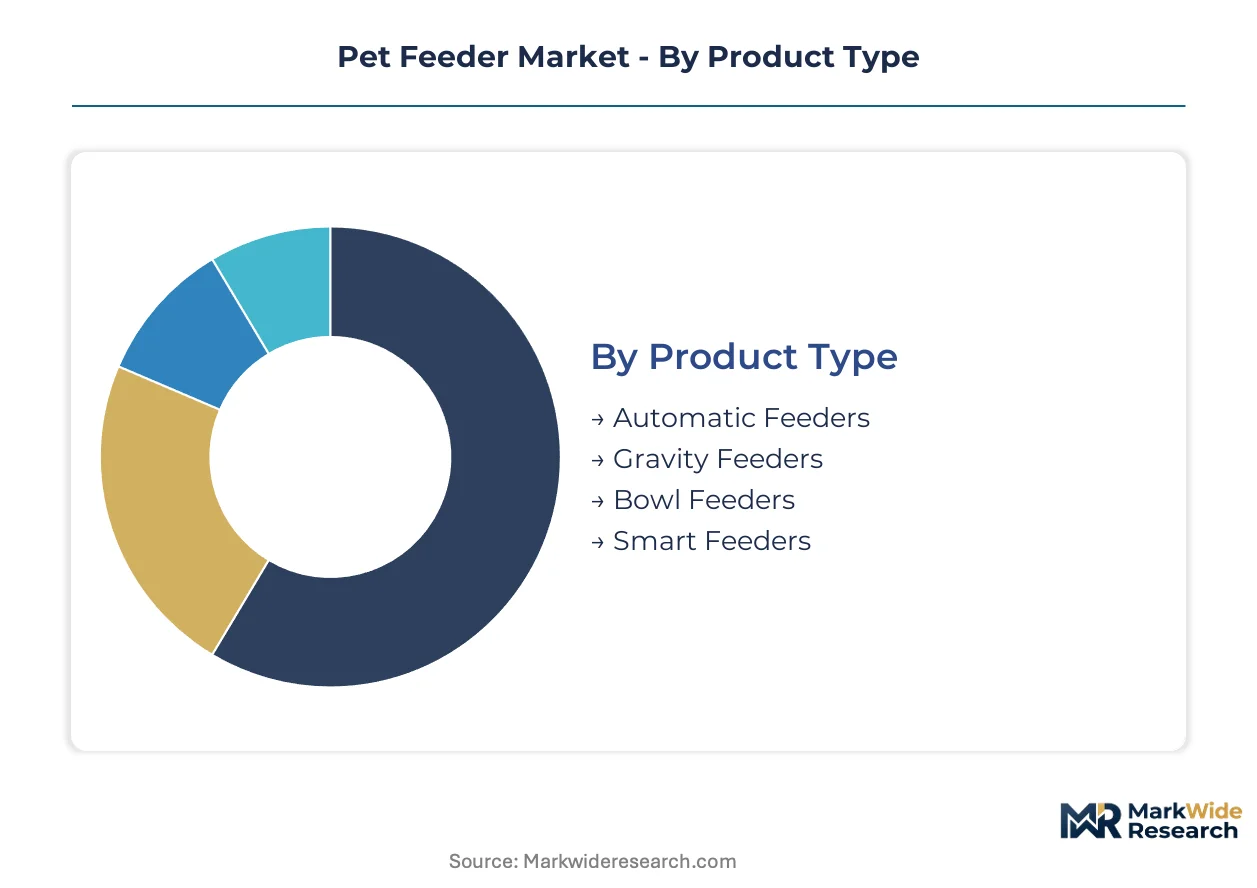
Pet feeder segmentation reveals how hardware sophistication, material durability, and user environment shape purchasing decisions. Manufacturers align R&D investment with the specific integration depth each segment demands.
Product Type:
Standalone dispensing units dominate household penetration, while embedded smart home systems capture the premium upgrade cycle.
- Automatic Feeders:Motorized hopper systems with programmable timers enable portion-controlled meal distribution without owner presence. Demand clusters in United States metropolitan apartments where irregular work schedules disrupt manual feeding routines.
- Smart Feeders:Wi-Fi-connected dispensers integrate camera surveillance, load-cell weighing, and mobile app control for real-time dietary monitoring. Coastal United States tech-forward households drive adoption as pet obesity management becomes a veterinary priority.
- Gravity Feeders:Passive reservoir designs rely on food weight to refill bowls automatically. Budget-conscious rural pet owners favor these for multi-pet households with unrestricted feeding access.
- Bowl Feeders:Static containers without dispensing mechanisms serve as water stations or supervised meal vessels. Veterinary clinics deploy stainless steel variants for examination room hygiene protocols.
Automatic feeders lead volumes today; smart feeders are gaining share fastest.
Material:
Cost tiers separate veterinary-grade durability claims from disposable convenience positioning.
- Stainless Steel:Non-porous, corrosion-resistant bowls resist bacterial colonization and withstand aggressive sanitization. United States veterinary practices and premium pet hotels specify these for liability reduction and FDA contact material compliance.
- Plastic:Injection-molded polymers enable complex hopper geometries and lightweight portability at mass-market price points. Big-box retail channels in the United States Midwest stock these for price-sensitive first-time pet owners.
- Ceramic:Glazed clay construction offers weight stability and aesthetic integration with home décor. Urban design-conscious consumers in New York and San Francisco select these for single-pet households.
- Wood:Elevated feeder stands and decorative housings use sealed hardwoods for furniture-grade presentation. Boutique pet retailers in Pacific Northwest markets differentiate through artisan-crafted limited editions.
Plastic commands unit volumes; stainless steel captures margin concentration.
End User:
Application context determines feature complexity, from basic reliability for institutional settings to data-rich monitoring for individual pet health management.
- Pet Owners:Individual households purchase across all product tiers based on pet count, work schedule, and technology comfort. United States millennials in high-rise apartments represent the core smart feeder demographic.
- Veterinary Clinics:Medical facilities require precise portion calibration and easy sterilization for post-surgical or prescription diet administration. These buyers prioritize FDA material certification and stainless steel construction.
- Pet Care Facilities:Boarding kennels and daycare operators need high-capacity, tamper-resistant units serving multiple animals simultaneously. Durability and replacement part availability drive procurement decisions.
- Animal Shelters:Non-profit and municipal shelters minimize per-unit expenditure while maximizing feeding reliability for unpredictable intake volumes. Gravity and basic automatic feeders predominate in this segment.
Pet owners generate the largest revenue pool; veterinary clinics deliver the highest per-unit margins.
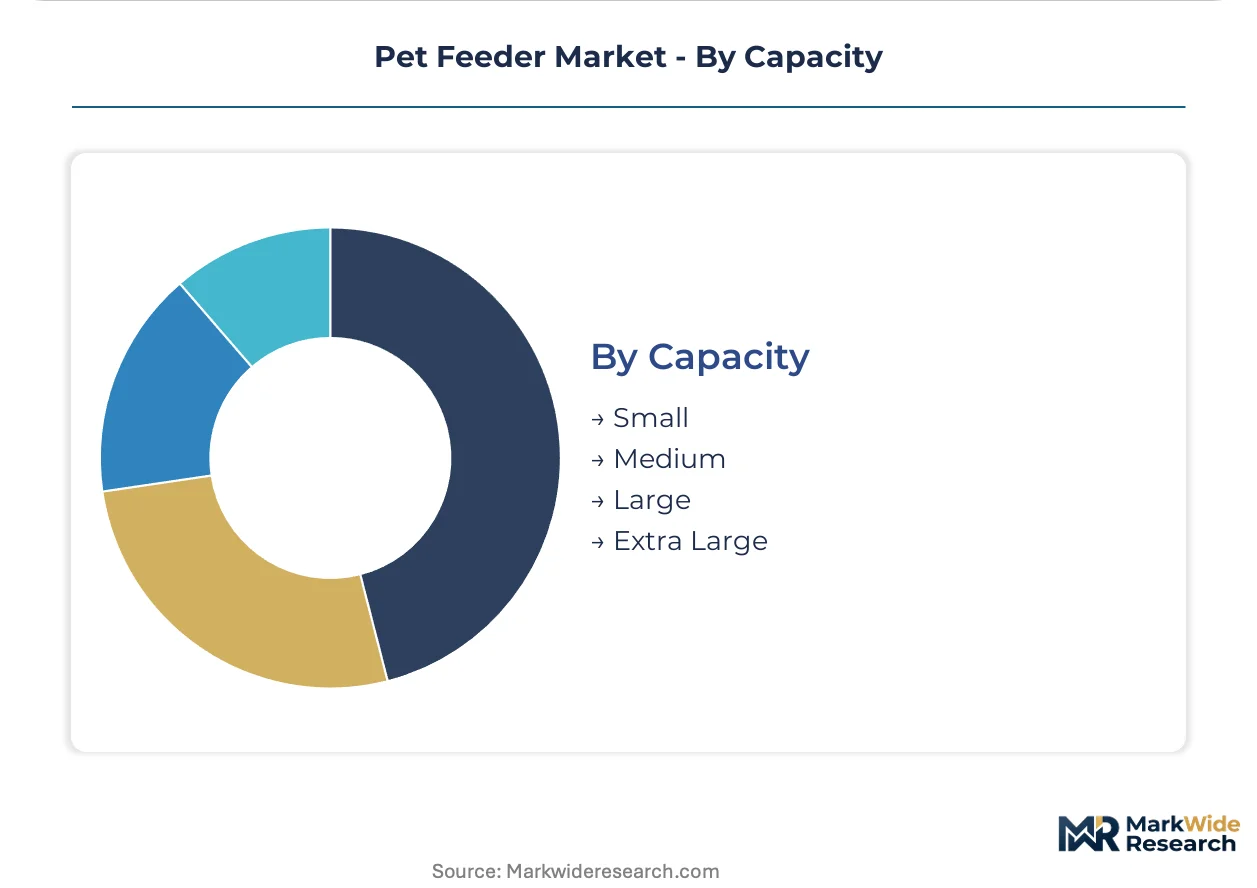
Capacity:
Volume scaling aligns with pet size distribution and multi-animal household prevalence.
- Large:Six-liter-plus hoppers accommodate multiple large-breed dogs or extended absence scenarios. Suburban United States households with outdoor space and travel schedules favor these configurations.
- Medium:Three-to-six-liter reservoirs serve single medium-breed dogs or multi-cat households. This segment captures the broadest cross-section of urban and suburban demand.
- Small:Under-three-liter designs target cat-only households and toy-breed dogs with restricted portion requirements. Apartment dwellers prioritize space efficiency over extended autonomy.
- Extra Large:Ten-liter-plus commercial-grade units serve breeding operations, kennels, and livestock-adjacent applications. Agricultural supply channels in Texas and Florida stock these for working dog facilities.
Medium capacity leads unit shipments; large capacity shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Software engineers and IoT hardware specialists cluster in coastal United States metros and Chinese manufacturing hubs, anchoring smart feeder development and production networks.
United States
Millennial pet owners in high-rise apartments drive demand for Wi-Fi-connected dispensers with camera surveillance. FDA Center for Veterinary Medicine guidelines on food-contact materials shape polymer selection and coating compliance. Los Angeles and New York City concentrate premium smart feeder adoption, with coastal households prioritizing obesity management features.
China
Contract manufacturers in Guangdong and Zhejiang provinces supply load-cell sensors and injection-molded housings for global brands. MIIT oversees wireless transmission certification for 2.4GHz and 5GHz modules in connected devices. Shenzhen anchors IoT ecosystem integration, where Xiaomi leverages supply chain density for aggressive smart feeder pricing.
Germany
Veterinary-grade precision feeding requirements from Munich and Berlin clinics elevate stainless steel construction standards. EU Green Deal circular economy mandates drive recycled polymer content disclosures and end-of-life takeback provisions. Bavarian retailers now demand EPR compliance documentation before listing electronic pet care devices.
Japan
Aging pet demographics in Tokyo and Osaka metros generate demand for health-monitoring dispensers tracking consumption anomalies. METI governs wireless device certification and data encryption standards for IoT hardware. Kansai industrial clusters specialize in compact, space-efficient designs suited to micro-apartment living.
United Kingdom
Urban professionals in London and Manchester seek scheduled feeding solutions reducing noise complaints in dense housing. GDPR compliance requirements shape cloud data architectures for camera-equipped feeders. Southeast England distribution hubs channel European-bound inventory, with Brexit customs friction redirecting some assembly to continental facilities.
Pet Feeder Market Competitive Landscape
Top-tier vendors anchor premium smart home integration, while mid-market specialists compete on veterinary endorsements and retail channel breadth. The vendor base stratifies across three tiers: ecosystem-integrated technology platforms, veterinary-channel incumbents with distribution scale, and direct-to-consumer brands capturing millennial demand. Dominant competitive moves include API partnerships with telehealth platforms and subscription consumables bundling hardware with recurring food delivery.
Among Asia-Pacific technology conglomerates, Xiaomi exemplifies ecosystem-leveraged positioning, while PetSafe occupies a position representing North American retail-channel incumbency. Petkit anchors the health-monitoring specialist archetype, with its integrated consumption tracking and behavioral analytics.
| Leading Market Players |
|---|
| PetSafe |
| Xiaomi |
| Dogness Group |
| Sure Petcare |
| Petkit |
| WOPET |
| Petlibro |
| Skymee |
| Petmate |
| Others |
Value Network & Pricing Analysis
Load-cell sensor miniaturization and Wi-Fi module commoditization are compressing smart feeder bill-of-materials costs while shifting assembly margin toward software-enabled service layers. This dual cost-service transition concentrates pricing power with brands that own cloud infrastructure and recurring revenue architectures.
Pricing Analysis
Hardware-software bundling versus standalone equipment sales defines competitive pricing postures. Three-tier pricing structure across premium, standard, and economy levels separates FDA-certified stainless steel construction from basic polymer gravity units. Price differentiation hinges on veterinary endorsement tier and cloud subscription attachment. Cost compression in entry-level smart feeders is intensifying because Xiaomi's ecosystem leverage forces margin sacrifice among pure-play hardware vendors. Budget-conscious rural households exhibit highest price sensitivity; coastal tech-forward apartment dwellers show lowest.
Supply Chain Analysis
Ocean freight rate volatility from Guangdong and Zhejiang province ports to Los Angeles and Long Beach directly shapes landed cost economics for North American-bound inventory. Contract manufacturing concentrates in China, Vietnam, and Mexico. Component sourcing draws from Taiwanese semiconductor foundries, South Korean battery cell suppliers, and domestic injection-molded polymer processors. Single-source vulnerability in load-cell sensor supply creates disruption exposure. Distribution runs through big-box retail channels, veterinary clinic networks, and direct-to-consumer platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The pet feeder market reads as a late-cycle quality story where veterinary-grade precision specifications and health-data integration now command purchase decisions over basic dispensing reliability.
For Market Incumbents: Anchor defensive positioning through backward integration into load-cell sensor sourcing and captive cloud infrastructure development. PetSafe and Xiaomi ecosystem leverage threatens pure-play hardware margins. Certification investment in FDA Center for Veterinary Medicine compliance creates switching costs against emerging entrants lacking validation timelines. For New Entrants and Emerging Players: Veterinary clinic procurement committees represent the most penetrable channel partner type for health-monitoring differentiation. White-space concentrates in subscription consumables bundling and telehealth platform API partnerships. Target animal shelter and municipal procurement with simplified automatic feeder designs lacking smart features. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-market hardware specialists lacking recurring revenue attachment and cloud data assets. Long-term viability favors platforms integrating feeding data with broader pet health ecosystems. Watch FDA enforcement intensity on food-contact material compliance as inflection indicator for margin compression among non-compliant manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| Veterinary Platform API Integration | Telehealth connectivity with Mars Petcare and IDEXX systems locks in clinic recommendation authority. |
| Subscription Consumables Bundling | Portion-controlled kibble delivery tied to dispenser usage data builds predictable recurring revenue. |
| California Proposition 65 Compliance Positioning | BPA-free material certification commands shelf space in stringent state-level retail channels. |
| EU Green Deal Circular Economy Certification | Recycled polymer content disclosures unlock German and French retail listings ahead of competitors. |
| Cybersecurity Penetration Testing Investment | IEEE 2410 IoT security certification differentiates camera-equipped feeders in privacy-sensitive households. |
Research Methodology
Multiple input streams — executive interviews with smart home device manufacturers, veterinary clinic procurement managers, and pet retail category buyers; secondary validation through FDA Center for Veterinary Medicine filings, FCC equipment authorization databases, and customs import records — were reconciled through bottom-up and top-down triangulation.
Data-stream reconciliation across product type, material grade, end-user application, and capacity tier segmentation dimensions produced volume and value outputs over the projection horizon. CAGRs were derived from fitted growth curves applied to historical shipment data and penetration rate assumptions. Industry-specific forecast inputs included smart home ecosystem adoption curves and veterinary telehealth platform expansion trajectories.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to semiconductor supply concentration, FCC certification timeline shifts, and pet humanization trend persistence. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Pet Perfume Market
Pet Care Products
Cat Litter Product Market
Pet Care Products
Pet Rugs Market
Pet Care Products
Animal Bedding Products Market
Pet Care Products
Dog Clippers Market
Pet Care Products
Pet Hair Care Market
Pet Care Products
Organic and Natural Dog Foods Market
Pet Care Products
Spain Pet Boarding Market
Pet Care Products
Pet Smart Tracker Market
Pet Care Products
Dog Crate Furniture Market
Pet Care Products
Aquarium and Fish Bowls Market
Pet Care Products
Smart Pet Supply Market
Pet Care Products
Pet Treats and Chews Market
Pet Care Products
Canada Pet Training Services Market
Pet Care Products
Japan Pet Clothing Market
Pet Care Products
Dog Hoodies Market