
 Global Organic Hair Color Market | 2026-2036
Global Organic Hair Color Market Size, Share, and Industry Trends Forecast 2026-2036
Global Organic Hair Color Market Foresight
Professional beauty salons are rotating away from ammonia-laden synthetic dyes toward certified organic alternatives, while home-use personal consumers follow with scaled-down purchases. Herbatint leverages its Italian manufacturing heritage to sustain European pharmacy distribution dominance. Naturtint competes through extensive e-commerce channel control across North American and Asian markets. Radico anchors its position in South Asia with henna-based specialization and Ayurvedic ingredient sourcing.
Organic hair color refers to pigmented formulations that exclude synthetic ammonia, parabens, and resorcinol while incorporating plant-derived dyes such as lawsonia inermis (henna), indigofera tinctoria, and vegetable colorants bound by natural conditioning bases. These products serve commercial hair coloring services and at-home applications where dermatological safety and reduced chemical exposure represent functional priorities. Henna-based and vegetable-based formulations capture the fastest-growing demand pool as consumers with sensitivities reject oxidative permanent dyes. Permanent color retains the largest volume share among salon professionals requiring gray coverage durability. E-commerce channels increasingly displace specialty stores for repeat purchases where ingredient transparency and certification badges drive selection behavior.
EMA cosmetic safety assessments and REACH chemical registration requirements in Europe restrict allergenic preservative use, while FDA color additive regulations and state-level Proposition 65 enforcement in California shape permissible ingredient disclosure in North America. ISO 16128 natural and organic cosmetics standards provide third-party certification frameworks that manufacturers adopt for market access differentiation. Stakeholders must monitor evolving EU Green Deal chemical hazard reclassifications and emerging state-level clean beauty legislation to anticipate reformulation timelines and certification investments.
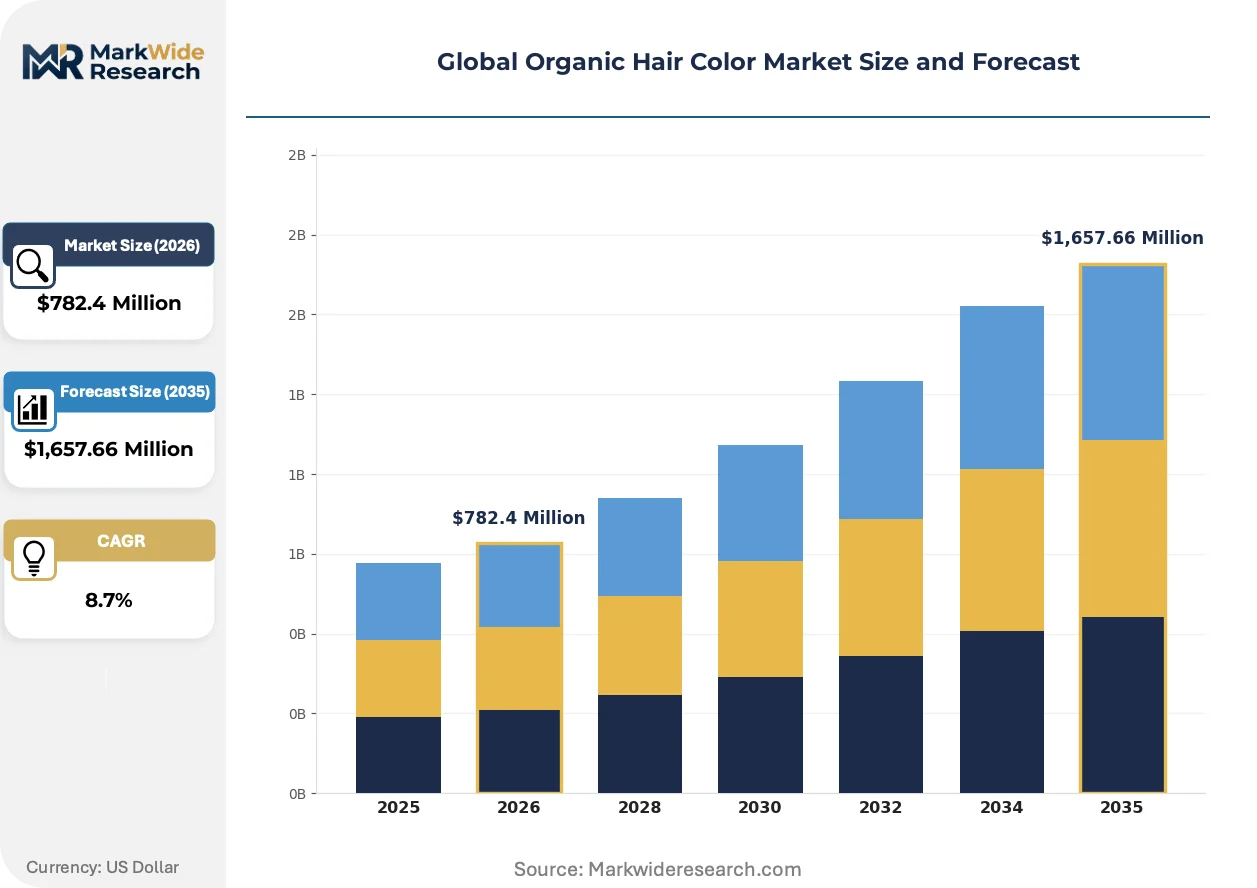
Market Dynamics
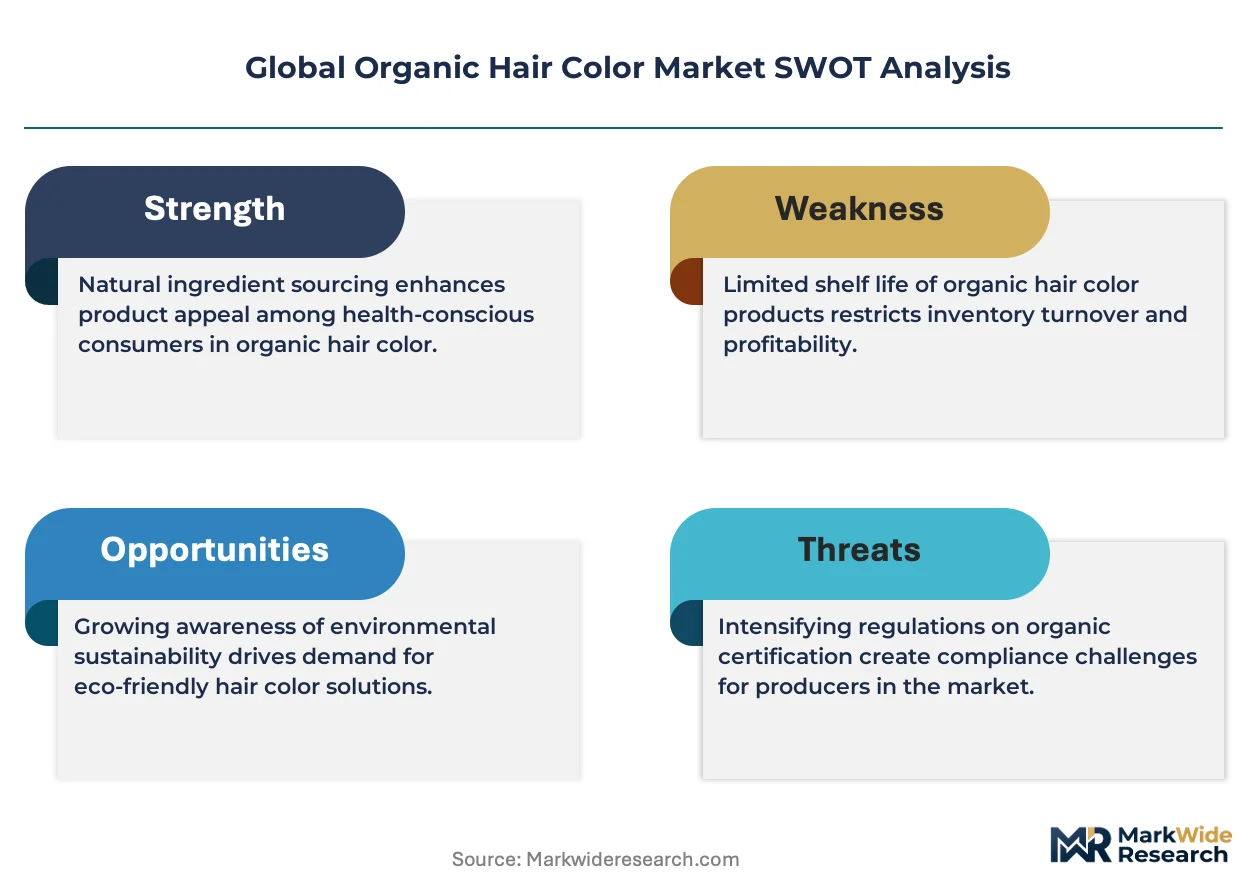
REACH chemical registration thresholds and FDA cosmetic ingredient scrutiny are compressing permissible synthetic ammonia levels, forcing reformulation investments across professional salon supply chains while certified organic alternatives capture service menu rotations.
Growth Catalysts
- EU Green Deal hazard reclassifications:The European Commission's chemical hazard reclassification timeline accelerates manufacturer migration toward plant-derived dye bases ahead of compliance deadlines.
- Professional salon service expansion:Beauty operators in Germany, Japan, and Brazil are building certified organic color service lines to capture consumer intolerance to oxidative permanent dyes.
- ISO 16128 certification frameworks:Third-party natural and organic cosmetics standards enable market access differentiation for henna-based and vegetable-based formulations in pharmacy and e-commerce channels.
Market Restraints
- Ayurvedic ingredient supply concentration:Lawsonia inermis and indigofera tinctoria sourcing clusters in Rajasthan and Gujarat create monsoon-dependent yield volatility for henna-specialist manufacturers.
- Performance durability gap:Plant-derived colorants exhibit faster fade rates versus oxidative permanent dyes, limiting gray coverage appeal among demographic segments prioritizing longevity.
- California Proposition 65 enforcement:State-level chemical disclosure mandates generate litigation exposure and labeling complexity for formulations containing trace resorcinol alternatives.
Strategic Opportunities
- Brazil certified organic distribution networks:Underdeveloped professional salon supply infrastructure in São Paulo and Rio de Janeiro creates first-mover positioning for pharmacy-channel entrants.
- E-commerce ingredient transparency:Digital repeat-purchase platforms are displacing specialty retail through certification badge visibility and subscription logistics.
- Convergence of Ayurvedic dermatology and color science:Ayurvedic ingredient sourcing combined with pH-optimized natural conditioning bases enables premium positioning in South Asian and diaspora markets.
Industry Challenges
- Cosmetic chemist talent scarcity:Formulation expertise bridging plant-extraction stability and salon-performance requirements remains concentrated in Italian and French technical institutes.
- Multi-jurisdiction certification timelines:Simultaneous EMA cosmetic safety assessments, FDA color additive reviews, and ISO 16128 audits extend product launch cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Organic Hair Color Market |
| Market Size in 2026 | $782.4 Million |
| Market Size in 2035 | $1,657.66 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Permanent, Semi-Permanent, Temporary, Henna-Based, Vegetable-Based Application: Salon Use, Home Use, Professional Styling, Theatrical Use, Personal Grooming End User: Beauty Salons, Personal Consumers, Hairdressers, Cosmetology Schools, Spa Centers Channel: E-commerce, Specialty Stores, Supermarkets, Pharmacies, Direct Sales |
| Companies Covered | Herbatint, Naturtint, Tints of Nature, Aubrey Organics, Radico, Natulique, Indus Valley, EcoColors, Organic Colour Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Organic Hair Color Market Shifts & Advancements
Plant-extraction stabilization technologies and digital certification verification systems are compressing the gap between professional salon performance and consumer safety demands.
Encapsulated pigment delivery systems are miniaturizing active dye particles for deeper cuticle penetration without ammonia oxidation. Professional colorists in Milan and Paris are adopting these systems for gray coverage applications previously dominated by synthetic permanent dyes. The technology is miniaturizing formulation complexity, enabling compact at-home kit formats that replicate salon-grade results.
EMA cosmetic safety assessments now mandate expanded allergenic preservative screening across rinse-off and leave-on hair color categories. Manufacturers serving European pharmacy channels are accelerating paraben-free and resorcinol-free reformulations to preempt regulatory non-compliance. Salon-exclusive permanent color lines face the steepest compliance costs due to higher chemical load requirements.
Ingredient transparency verification has displaced brand loyalty as the primary purchase determinant among repeat organic color buyers. E-commerce platforms in North America and Asia-Pacific are capturing subscription revenue through blockchain-traceable certification badges that specialty stores cannot replicate. This behavioral pivot concentrates demand share with digitally native brands capable of real-time supply chain disclosure.
Global Organic Hair Color Market Segmentation
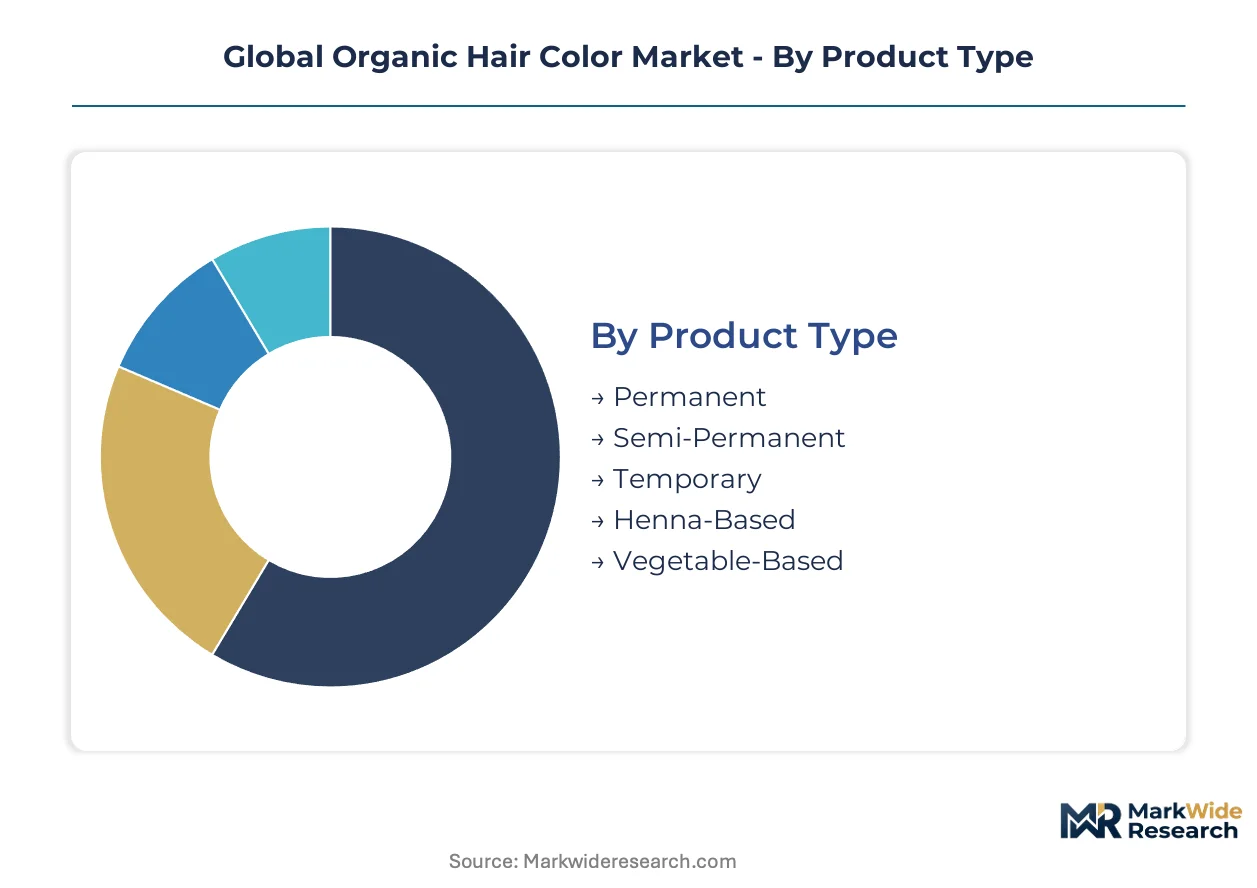
Segmentation in organic hair color reveals how certification tiers, application settings, and channel economics fragment margin capture across professional and personal use cases. Understanding these divisions exposes where reformulation investments concentrate and where distribution leverage determines pricing power.
Product Type:
Margin pools concentrate in permanent formulations where salon professionals pay premium multiples for gray coverage durability, while henna-based variants command specialty positioning in pharmacy channels.
- Permanent:Ammonia-free oxidative systems using pH-optimized developers achieve cuticle penetration comparable to synthetic benchmarks. German salon operators specify these for demographic segments requiring resistant gray coverage.
- Semi-Permanent:Direct dye molecules deposit without developer activation, serving consumers seeking tonal shifts without commitment. Japanese beauty operators rotate these into menu tiers between permanent services and conditioning treatments.
- Temporary:Surface-coating colorants wash out within 4-8 shampoos, targeting theatrical and festival applications where commitment avoidance dominates purchase logic.
- Henna-Based:Lawsonia inermis leaf extracts bond with keratin through lawsone molecules, anchoring Ayurvedic positioning in Indian and Middle Eastern markets.
- Vegetable-Based:Indigofera tinctoria, cassia obovata, and beet-derived pigments blended with conditioning bases serve European consumers rejecting oxidative chemistry entirely.
Permanent holds installed capacity. Henna-based is rotating up the share rankings.
Application:
Volume concentrates in salon-conducted services where labor markup absorbs product premium, while home-use kits scale through e-commerce subscription mechanics.
- Salon Use:Professional colorists apply certified organic lines in controlled environments where patch testing and developer customization justify service pricing. Brazilian operators in São Paulo and Rio de Janeiro are building dedicated organic color menus.
- Home Use:Pre-mixed kit formats with simplified application instructions capture repeat purchase through digital channels. North American consumers prioritize certification badge visibility over brand heritage in this segment.
- Professional Styling:Editorial and fashion contexts demand vibrant vegetable-derived pigments for temporary transformation without structural damage.
- Theatrical Use:Performance contexts require intense color saturation with rapid removal capability, favoring temporary formulations with specialized fixatives.
- Personal Grooming:Conservative tonal adjustments for gray blending in mature demographics favor semi-permanent vegetable systems with conditioning benefits.
Salon use anchors revenue per unit. Home use is expanding most quickly through digital subscription capture.
End User:
Procurement authority fragments across institutional buyers with certification mandates and individual consumers with ingredient transparency demands.
- Beauty Salons:Full-service operators in Milan and Paris specify ISO 16128-certified lines to differentiate menu tiers and justify premium pricing.
- Personal Consumers:Individual purchasers research ingredient lists through mobile platforms before repeat buying, concentrating demand with digitally native brands.
- Hairdressers:Independent chair renters purchase professional-format tubes with developer systems, seeking performance parity with synthetic benchmarks.
- Cosmetology Schools:Training institutions require hypoallergenic formulations for student practice, creating volume contracts with henna-specialist suppliers.
- Spa Centers:Wellness-integrated operators in German and Swiss markets bundle organic color with Ayurvedic scalp treatments.
Beauty salons command formulation specification. Personal consumers are climbing the fastest as a demand source.
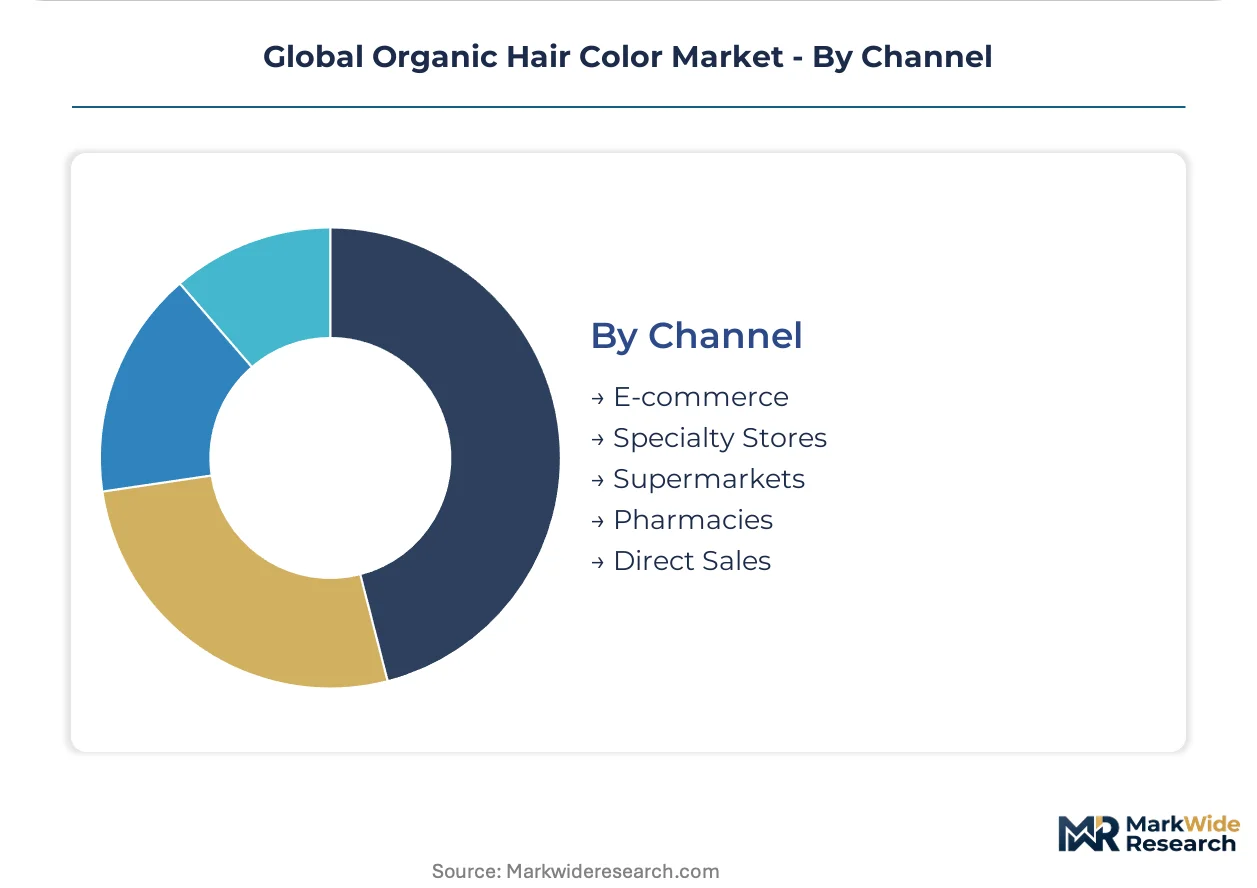
Channel:
Distribution economics favor direct digital relationships where certification verification and subscription logistics displace retail margin stacking.
- E-commerce:Platform algorithms surface certified organic options through ingredient-filter search, enabling subscription replenishment with blockchain traceability. This channel captures the steepest expansion trajectory among repeat purchasers.
- Specialty Stores:Curated beauty retailers in Tokyo and Seoul provide tactile evaluation and staff consultation, defending position through experiential service.
- Supermarkets:Mass-market placement reaches price-sensitive segments with simplified henna kits, though certification density remains lower than pharmacy or digital alternatives.
- Pharmacies:Italian and French pharmacy chains leverage healthcare adjacency to stock dermatologist-recommended organic lines with clinical packaging cues.
- Direct Sales:Salon-exclusive professional formats bypass retail markup, with field educators training colorists on application technique.
Pharmacies hold legacy positioning. E-commerce is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Professional salon operators and certified pharmacy chains in Germany, Japan, Brazil, the United States, and India concentrate procurement authority for organic hair color formulations. These markets exhibit divergent regulatory timelines and distribution infrastructure maturity that fragment competitive positioning across geographies.
Germany
REACH chemical registration thresholds and EU Green Deal hazard reclassifications are compressing permissible synthetic ammonia levels ahead of compliance deadlines. ECHA enforcement actions against oxidative dye formulations are accelerating manufacturer migration toward plant-derived bases. Berlin and Munich salon operators are building dedicated organic color service menus to capture consumer intolerance to synthetic compounds.
Japan
Professional beauty operators in Tokyo and Osaka specify ISO 16128-certified lines for gray coverage durability without ammonia oxidation. METI cosmetic safety guidelines mandate expanded allergenic preservative screening across rinse-off and leave-on categories. Kanto region salon chains are rotating semi-permanent vegetable systems into menu tiers between permanent services and conditioning treatments.
Brazil
ANVISA cosmetic ingredient scrutiny is tightening permissible chemical thresholds for professional salon supply chains. São Paulo and Rio de Janeiro operators are building certified organic distribution networks to capture first-mover positioning in underdeveloped pharmacy channels. Southeast Brazilian consumers exhibit rising intolerance to oxidative permanent dyes in service menu selections.
United States
FDA cosmetic ingredient scrutiny and California Proposition 65 enforcement are generating litigation exposure for formulations containing trace resorcinol alternatives. State-level clean beauty legislation is extending product launch cycles through multi-jurisdiction certification requirements. New York and Los Angeles salon operators specify ammonia-free oxidative systems for demographic segments requiring resistant gray coverage.
India
Lawsonia inermis and indigofera tinctoria sourcing clusters in Rajasthan and Gujarat create monsoon-dependent yield volatility for henna-specialist manufacturers. CDSCO cosmetic safety assessments are converging with Ayurvedic dermatology traditions to enable premium positioning in South Asian markets. Maharashtra and Karnataka salon operators bundle organic color with Ayurvedic scalp treatments for wellness-integrated service positioning.
Global Organic Hair Color Market Competitive Landscape
Player mix skews toward heritage European manufacturers and digitally native direct-to-consumer specialists with Ayurvedic sourcing advantages. Market structure exhibits moderate consolidation around pharmacy-channel incumbents with ISO 16128 certification frameworks, while e-commerce entrants fragment home-use kit segments through subscription logistics. Three strategic archetypes dominate: Italian and French heritage formulators with technical institute talent pipelines, Indian henna-specialists with captive Ayurvedic supply, and North American digital-first brands with blockchain traceability infrastructure. Dominant competitive moves include geographic expansion into underdeveloped Brazilian distribution networks and portfolio diversification toward encapsulated pigment delivery systems.
Within the heritage European tier, Herbatint and Naturtint exemplify divergent channel strategies—Herbatint leverages Italian manufacturing heritage for pharmacy dominance while Naturtint competes through e-commerce control across North American markets. Radico anchors the Ayurvedic-specialist archetype with Rajasthan-based sourcing concentration. These three occupy positions that reflect the broader market tension between technical formulation expertise and plant-extraction supply security.
| Leading Market Players |
|---|
| Herbatint |
| Naturtint |
| Tints of Nature |
| Aubrey Organics |
| Radico |
| Natulique |
| Indus Valley |
| EcoColors |
| Organic Colour Systems |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts between Rajasthan henna processors and Italian formulators lock in supply access and price visibility across monsoon-dependent harvest cycles. These arrangements compress margin volatility for European pharmacy-channel incumbents while exposing contract counterparties to yield shortfall penalties under force majeure clauses.
Pricing Analysis
Cost-plus contracts with Rajasthan agricultural indexation anchor raw material pricing for henna-specialist manufacturers. Three-tier pricing structure across premium salon-grade, standard pharmacy-channel, and economy supermarket tiers separates ISO 16128-certified formulations from uncertified alternatives. Pricing pressure stems from Ayurvedic ingredient supply concentration as monsoon failures trigger spot market premiums. Personal consumers exhibit highest price sensitivity through e-commerce filter-driven selection, while salon professionals absorb premiums for gray coverage durability.
Supply Chain Analysis
Strategic stockpiling of lawsonia inermis leaf inventory before monsoon seasons dominates working capital allocation for Indian henna processors. Rajasthan, Gujarat, and southern France concentrate botanical extraction capacity while indigofera tinctoria sourcing clusters in Tamil Nadu and Karnataka. Single-source vulnerability runs through Rajasthan monsoon dependency for lawsone pigment concentration. Distribution runs through pharmacy chains in Italy and France, e-commerce platforms in North America, and direct salon supply in Brazil.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a substitution defense against synthetic ammonia oxidative dyes as regulatory thresholds compress permissible chemical loads. Incumbents must navigate reformulation investments while defending margin position against digitally native entrants with blockchain traceability infrastructure.
For Market Incumbents: Compound ISO 16128 certification density with encapsulated pigment delivery system R&D to defend salon-grade performance positioning against synthetic dye substitution threats. Backward integration into Rajasthan henna estates secures supply access ahead of monsoon volatility while compressing spot market exposure. For New Entrants and Emerging Players: Anchor in Brazilian pharmacy-channel white space where São Paulo and Rio de Janeiro salon infrastructure remains underdeveloped for certified organic distribution. E-commerce subscription mechanics with blockchain-traceable certification badges offer the most penetrable go-to-market angle against heritage European incumbents. For Investors and Strategic Acquirers: Capital is best deployed toward Ayurvedic-specialist manufacturers with captive Rajasthan sourcing and ISO 16128 certification frameworks already in place. Long-term viability hinges on regulatory tailwinds compressing synthetic ammonia thresholds across the analysis window. Watch ECHA enforcement action intensity against oxidative dye formulations as inflection indicator for plant-derived substitution acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Investment | ISO 16128 compliance unlocks pharmacy-channel access in Milan and Paris. |
| Ayurvedic Supply Integration | Rajasthan henna estate acquisition secures lawsone pigment concentration stability. |
| E-commerce Platform Buildout | Digital subscription mechanics displace specialty retail margin stacking. |
| Encapsulated Pigment R&D | Cuticle penetration technology bridges salon performance and ammonia-free positioning. |
| Brazilian Distribution Expansion | First-mover pharmacy-channel positioning captures São Paulo salon operator procurement. |
Research Methodology
A standing panel of salon chain procurement directors, Italian cosmetic chemists, Rajasthan agricultural exporters, and e-commerce platform category managers provided ongoing calibration across primary interview cycles. Secondary validation drew from ECHA enforcement databases, ANVISA cosmetic registration filings, ISO 16128 certification registries, and customs trade records for lawsonia inermis leaf exports. Bottom-up salon operator survey data triangulated against top-down manufacturer shipment disclosures.
Consistency checks validated volume and value outputs against external regulatory filing benchmarks and channel inventory disclosures across the modeling period. Segmentation dimensions modeled include product type tier, application setting, end-user procurement authority, and distribution channel format alongside regional regulatory cluster intensity. CAGRs derived from logistic adoption curves fitted to salon service menu penetration data and e-commerce subscription cohort retention rates.
Decision-makers should treat outputs as directional under stable REACH enforcement intensity and monsoon yield patterns; material deviation would warrant model refresh. Forecasts reflect these base assumptions regarding regulatory trajectory and agricultural supply stability. Revision becomes warranted when ECHA hazard reclassification timelines accelerate or Rajasthan monsoon failure rates cross historical thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Global Personal Care Emollients Market
Beauty & Personal Care
Personal Care Shower and Bath Market
Beauty & Personal Care
Body Firming Creams Market
Beauty & Personal Care
Pre-Shave Care Market
Beauty & Personal Care
Wrinkle Release Spray Market
Beauty & Personal Care
US Cosmetics Market
Beauty & Personal Care
Hair and Nail Accessories Market
Beauty & Personal Care
South America Deodorants Market
Beauty & Personal Care
Beard Oil Market
Beauty & Personal Care
Color Protection Shampoo Market
Beauty & Personal Care
Spain Dermocosmetics Market
Beauty & Personal Care
Asia Pacific Beauty Fridges Market
Beauty & Personal Care
France Sustainable Personal Care Market
Beauty & Personal Care
Herbal Haircare Products Market
Beauty & Personal Care
Stretch Mark Removal Products Market
Beauty & Personal Care
Personal Care Products Market