
 Raw Pet Food Market | 2026-2036
Raw Pet Food Market Size, Share, and Industry Trends Forecast 2026-2036
Raw Pet Food Market Intelligence
AAFCO nutritional adequacy protocols is bifurcating the competitive landscape between certified formulators and unverified entrants. Primal Pet Foods leverages in-house grinding and flash-freezing infrastructure to sustain batch-level traceability. Stella & Chewy's dominates freeze-dried shelf-stable formats through controlled low-temperature dehydration tunnels.
Raw pet food denotes uncooked animal tissue, organ meats, and ground bone formulations maintained below 40°F through cold-chain distribution to preserve enzymatic activity and amino acid bioavailability. The category serves companion animal guardians seeking ancestral feeding patterns absent thermal nutrient degradation. Frozen raw food anchors volume throughput in pet specialty stores, while freeze-dried raw food commands premium shelf positioning in online retail channels where shipping logistics favor lightweight formats. Fresh raw food occupies nascent direct-to-consumer subscription models with compressed delivery windows.
The FDA enforces pathogen standards under the Federal Food, Drug, and Cosmetic Act, requiring HACCP documentation for raw pet food facilities processing USDA-inspected proteins. State agriculture departments in Wisconsin and Texas administer supplemental licensing for raw pet food manufacturers operating across interstate distribution networks. Stakeholders must monitor evolving state-level cottage food exemptions that currently fragment compliance thresholds for small-batch raw producers.
Market Dynamics
The FDA's zero-tolerance Salmonella enforcement is bifurcating raw pet food manufacturing into HACCP-certified facilities and marginal cottage producers, compressing supply-side capacity while elevating compliance costs across the value chain.
Growth Catalysts
- Millennial Premium Dog Ownership:Companion animal guardians aged 28-43 are converting to ancestral feeding protocols at accelerating velocity, creating concentrated demand in coastal metropolitan corridors.
- AAFCO Nutritional Adequacy Certification:Verified formulation protocols are creating competitive separation between certified manufacturers and unverified entrants, consolidating retailer shelf access.
- Cold-Chain Distribution Infrastructure:Refrigerated logistics networks reaching pet specialty stores are extending enzymatic preservation windows and reducing spoilage rates in last-mile delivery.
Market Restraints
- USDA-Inspected Protein Input Costs:Human-grade meat sourcing requirements under FDA HACCP documentation are tethering raw pet food margins to volatile beef and poultry commodity markets.
- Interstate Licensing Fragmentation:Wisconsin and Texas agriculture departments administer non-uniform supplemental licensing regimes, creating compliance friction for multi-state distribution networks.
- Thermal Processing Substitution:High-pressure pasteurization and gentle-cooked alternatives are capturing risk-averse consumers seeking pathogen reduction without full nutrient degradation.
Strategic Opportunities
- Direct-to-Consumer Subscription Models:Compressed delivery windows for fresh raw formats are opening recurring revenue streams bypassing pet specialty retail intermediaries.
- Freeze-Dried Shelf-Stable Expansion:Lightweight dehydration formats are penetrating online retail channels where shipping economics favor reduced cubic volume and extended ambient storage.
- State-Level Cottage Food Exemption Lobbying:Small-batch producers are organizing to shape evolving exemption thresholds that currently fragment compliance burdens across state agriculture departments.
Industry Challenges
- Batch-Level Traceability Engineering:In-house grinding and flash-freezing infrastructure demands substantial capex for lot tracking systems capable of satisfying FDA recall documentation requirements.
- Veterinary Nutritionist Talent Scarcity:Formulation science expertise combining raw diet biochemistry with AAFCO protocol navigation commands premium compensation and extended recruitment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Raw Pet Food Market |
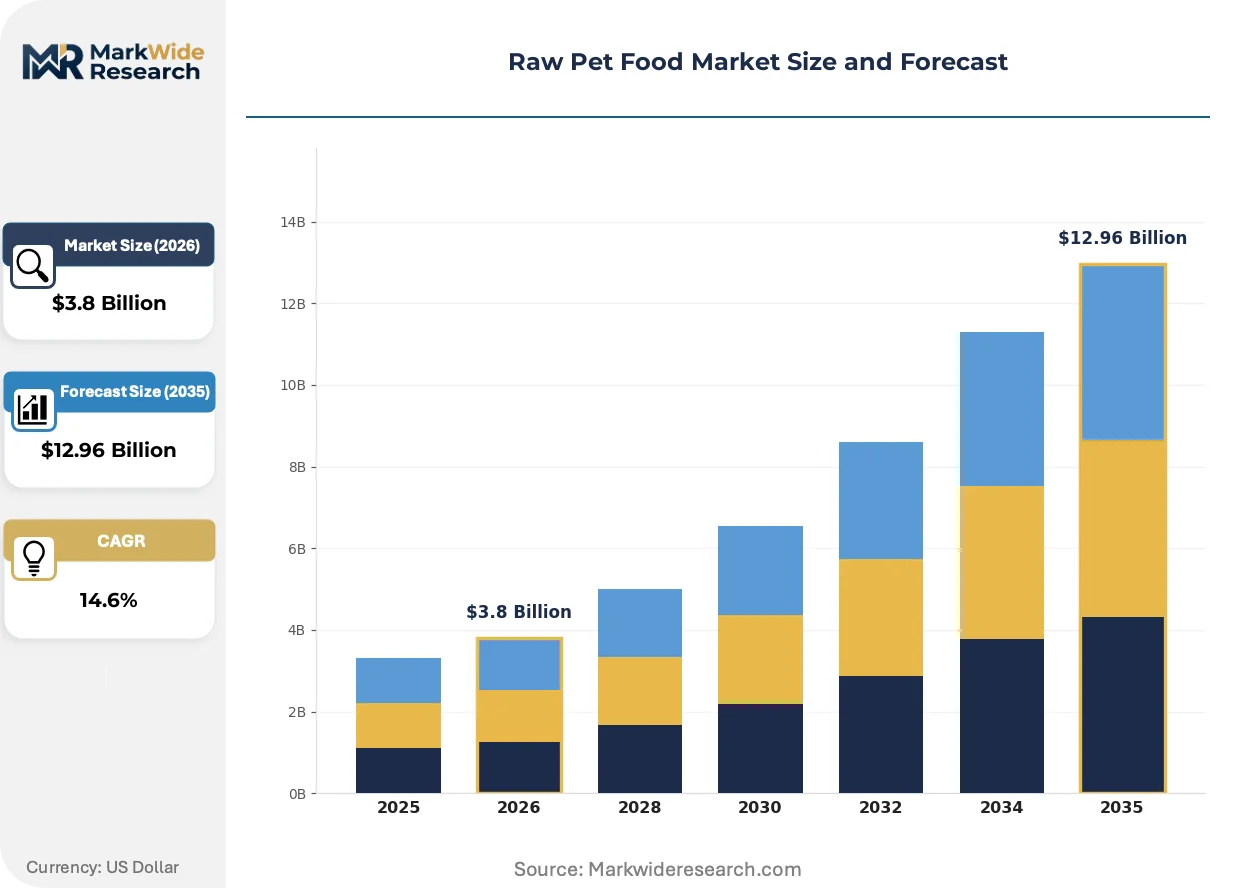
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Frozen Raw Food, Freeze-Dried Raw Food, Dehydrated Raw Food, Fresh Raw Food, Others Animal Type: Dogs, Cats, Birds, Small Mammals, Reptiles Ingredient Source: Beef, Chicken, Fish, Lamb, Game Meat Distribution Channel: Pet Specialty Stores, Online Retail, Veterinary Clinics, Supermarkets, Direct Sales |
| Companies Covered | Freshpet, Primal Pet Foods, Mars Petcare Inc., Spot & Tango, Nature's Variety, Nestlé Purina PetCare, Stella & Chewy's, JustFoodForDogs, The Farmer's Dog, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Raw Pet Food Market Strategic Shifts & Innovations
Processing technology and distribution logistics are converging to reshape competitive positioning across frozen, freeze-dried, and fresh raw formats, with preservation methods determining channel access and margin structure.
High-pressure processing systems are fragmenting the traditional frozen raw segment by delivering pathogen reduction without thermal nutrient degradation. Mid-size manufacturers are retrofitting existing facilities to capture safety-conscious consumers previously excluded by veterinary warnings. This technology is fragmenting the historical binary between raw and cooked, creating a third hybrid category with ambiguous regulatory classification.
The FDA's enforcement discretion under the Federal Food, Drug, and Cosmetic Act is tightening documentation requirements for raw pet food facilities processing animal proteins. Manufacturing sites must now maintain validated HACCP plans with environmental monitoring protocols previously reserved for human food operations. Small-batch producers in Texas and Wisconsin are responding by consolidating into shared commercial kitchens with pooled compliance infrastructure.
Subscription-based replenishment cycles are compressing traditional retail purchasing patterns for fresh raw formats. Direct-to-consumer platforms are displacing pet specialty store foot traffic in coastal metropolitan corridors where cold-chain logistics density supports weekly delivery windows. California and New York metropolitan clusters exhibit the highest concentration of these platform migrations, with guardians prioritizing convenience over tactile product evaluation.
Raw Pet Food Market Segmentation
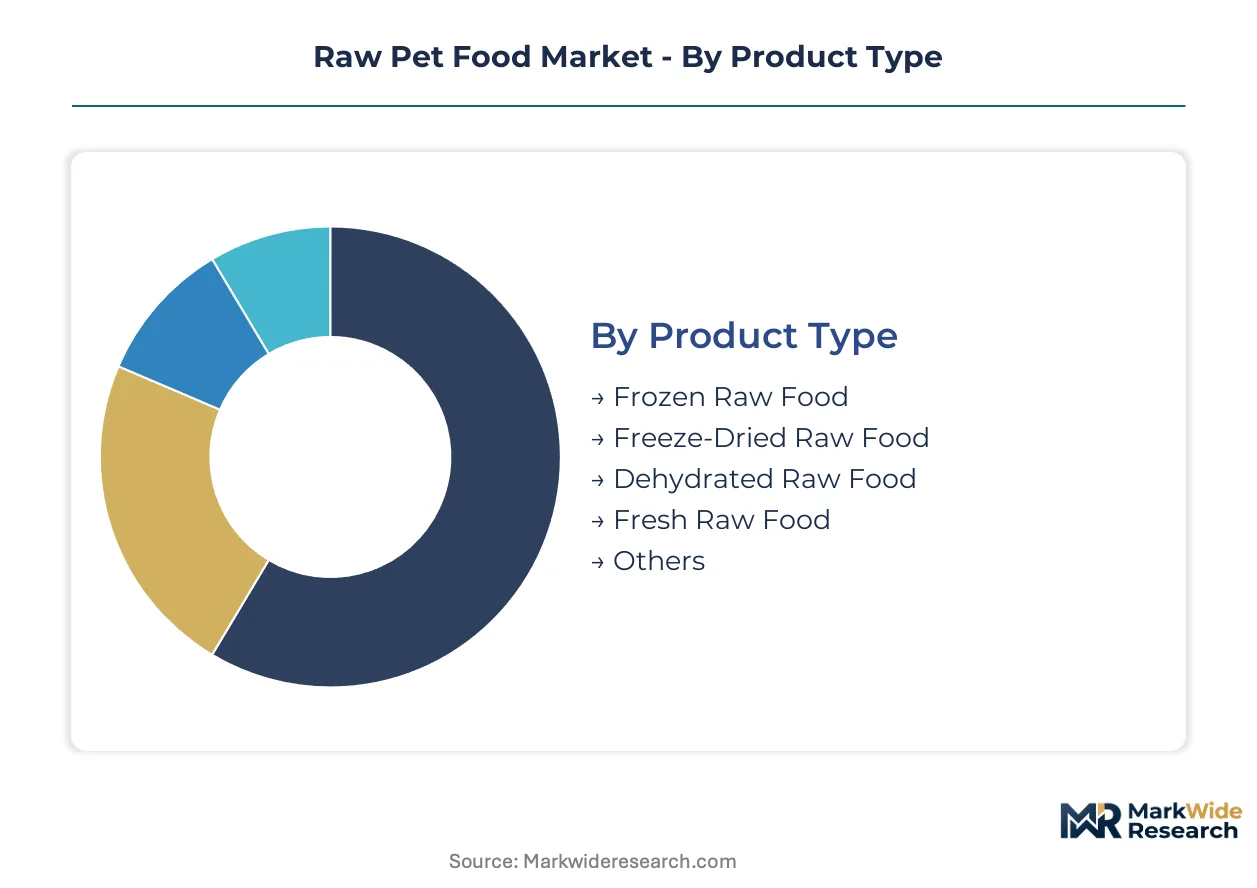
Segmentation in raw pet food reveals how preservation technology, species-specific formulation, protein sourcing, and channel economics allocate margin pools across incompatible operational models. Each dimension carries distinct capex requirements and regulatory exposure that determine competitive viability.
Product Type:
Frozen formats command the deepest margin pools due to cold-chain infrastructure barriers that filter out marginal competitors.
- Frozen Raw Food:Uncooked muscle tissue, organ meats, and ground bone formulations maintained below 40°F through continuous refrigeration. Demand concentrates in coastal metropolitan corridors where millennial premium dog ownership clusters and pet specialty store density supports reliable cold-chain throughput.
- Freeze-Dried Raw Food:Controlled low-temperature dehydration removes moisture while preserving enzymatic activity and amino acid structures. Online retail channels favor this lightweight format where shipping economics reward reduced cubic volume and extended ambient storage windows.
- Dehydrated Raw Food:Gentle air-drying at elevated but sub-cooking temperatures produces shelf-stable formats with partial nutrient retention.
- Fresh Raw Food:Refrigerated formulations with compressed production-to-consumption windows delivered through subscription models.
- Others:Emerging preservation formats including high-pressure processed and fermented raw variants.
Frozen raw food holds installed capacity. Freeze-dried raw food is rotating up the share rankings.
Animal Type:
Volume distribution across species reflects divergent formulation complexity and guardian willingness-to-pay for ancestral feeding protocols.
- Dogs:Canine formulations dominate raw pet food throughput with the highest per-animal consumption volumes and established veterinary nutritionist formulation standards. Coastal metropolitan corridors in the United States exhibit concentrated demand from millennial guardians converting to ancestral diets.
- Cats:Feline obligate carnivore physiology demands precise taurine and arachidonic acid balancing that elevates formulation expertise barriers. Premium pricing persists due to stricter AAFCO nutritional adequacy requirements for complete-and-balanced claims.
- Birds:Avian raw formulations occupy niche positioning with limited commercial scale.
- Small Mammals:Ferret, rabbit, and rodent raw diets serve specialized guardian segments with fragmented supply.
- Reptiles:Whole prey and ground reptile formulations address herpetological keeping communities.
Dog formulations anchor volume throughput. Cat formulations are climbing the fastest on premium pricing power.
Ingredient Source:
Protein input costs tether margin stability to commodity market volatility and USDA-inspected sourcing compliance.
- Beef:Bovine muscle and organ formulations carry the highest input cost exposure to cattle futures markets. Human-grade sourcing requirements under FDA HACCP documentation compress margins when beef commodity prices spike.
- Chicken:Poultry-based formulations benefit from vertically integrated supply chains with more stable pricing. Wisconsin and Texas processing infrastructure supports regional manufacturing concentration for this high-volume input.
- Fish:Marine protein formulations address omega-3 fatty acid positioning with supply concentration in Pacific Northwest coastal operations.
- Lamb:Ovine sourcing serves allergy-sensitive guardian segments with premium positioning.
- Game Meat:Venison, bison, and exotic proteins occupy ultra-premium tiers with limited supply scalability.
Chicken holds installed capacity. Beef is rotating up the share rankings on premium positioning.
Distribution Channel:
Channel selection determines cold-chain investment requirements and customer acquisition economics.
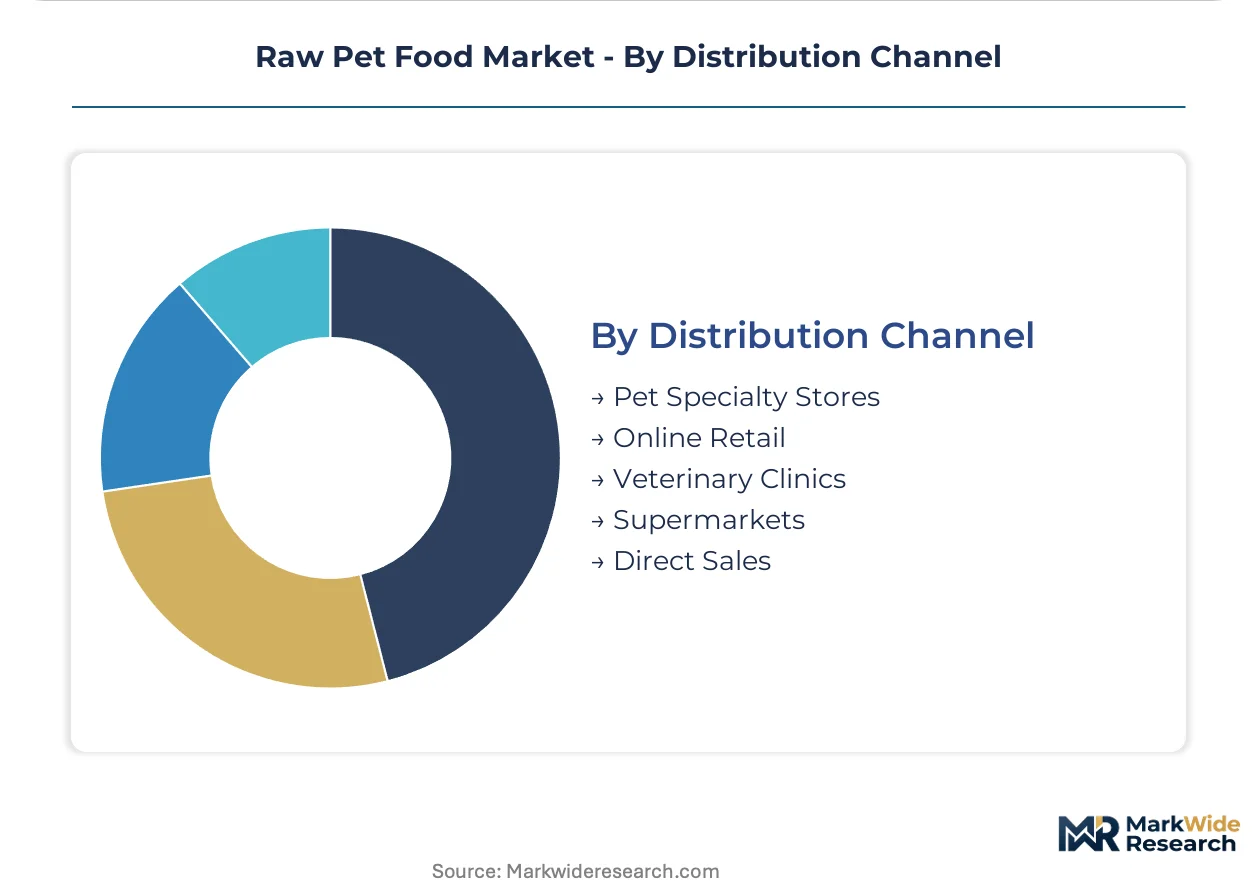
- Pet Specialty Stores:Brick-and-mortar retail with refrigerated display infrastructure and trained staff consultation. United States coastal metropolitan corridors concentrate foot traffic for frozen raw evaluation and tactile product assessment.
- Online Retail:E-commerce platforms favoring freeze-dried and dehydrated formats where ambient shipping eliminates cold-chain complexity. California and New York metropolitan clusters exhibit the highest platform migration velocity.
- Veterinary Clinics:Professional recommendation channels with formulation credibility endorsement.
- Supermarkets:Mass retail with limited refrigerated pet food shelf space and commodity positioning pressure.
- Direct Sales:Manufacturer-owned subscription platforms with compressed delivery windows for fresh raw formats.
Pet specialty stores hold installed capacity. Online retail is gaining share fastest on format lightweighting.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Millennial premium dog ownership concentrates in coastal metropolitan corridors across multiple continents, with cold-chain infrastructure density and regulatory stringency determining market penetration rates in each geography.
United States
Coastal metropolitan clusters in California and New York drive fresh raw subscription adoption, with guardians prioritizing convenience over tactile product evaluation. FDA zero-tolerance Salmonella enforcement under the Federal Food, Drug, and Cosmetic Act mandates HACCP documentation for all processing facilities. Wisconsin and Texas agriculture departments administer supplemental licensing regimes that create compliance friction for multi-state distribution networks.
United Kingdom
London and Southeast England exhibit concentrated demand for ancestral feeding protocols among urban professional households with discretionary pet expenditure. The Food Standards Agency maintains guidance alignment with EU withdrawal-era regulatory continuity, requiring pathogen controls for raw pet food manufacturing. Midlands-based cold-chain logistics providers are extending distribution reach into northern metropolitan corridors.
Germany
Bavaria and North Rhine-Westphalia anchor premium pet food consumption, with Berlin-Brandenburg emerging as a direct-to-consumer subscription growth node. EFSA nutritional adequacy benchmarks inform national implementation through the Federal Office of Consumer Protection and Food Safety. Baden-Württemberg manufacturing clusters specialize in high-pressure processing equipment retrofitting for hybrid raw-cooked formats.
Australia
New South Wales and Victoria metropolitan areas concentrate raw diet conversion among companion animal guardians seeking biologically appropriate feeding. The Department of Agriculture, Water and the Environment administers biosecurity protocols for imported protein inputs that elevate sourcing compliance costs. Queensland cold-chain infrastructure investments are expanding frozen format penetration into secondary population centers.
Canada
Ontario and Quebec urban corridors exhibit parallel millennial pet ownership patterns to adjacent US metropolitan markets, with cross-border regulatory awareness elevating formulation standards. Health Canada and the Canadian Food Inspection Agency enforce overlapping jurisdiction on pet food safety with emphasis on Salmonella documentation. British Columbia's Pacific coastal operations leverage marine protein sourcing advantages for omega-3 positioned formulations.
Raw Pet Food Market Key Industry Players
Player mix skews toward vertically integrated specialists with captive grinding and freezing infrastructure alongside diversified multinational pet care conglomerates with portfolio diversification into raw formats. The competitive structure bifurcates between HACCP-certified facilities capable of satisfying FDA documentation requirements and marginal cottage producers facing consolidation pressure. Two dominant strategic archetypes have emerged: in-house traceability engineers investing in batch-level lot tracking systems, and lightweight-format innovators capturing online retail channel economics through dehydration technologies. Capacity expansion and strategic partnerships represent the primary competitive moves, with shared commercial kitchen pooling arrangements proliferating among small-batch producers in Texas and Wisconsin.
Among US-based specialists, Primal Pet Foods and Stella & Chewy's occupy positions exemplifying divergent format strategies—frozen infrastructure depth versus freeze-dried shelf-stable lightweighting. Mars Petcare Inc. and Nestlé Purina PetCare represent diversified multinational archetypes with raw portfolio extensions leveraging existing distribution scale. Freshpet exemplifies the fresh refrigerated format with compressed delivery window capabilities.
| Leading Market Players |
|---|
| Freshpet |
| Primal Pet Foods |
| Mars Petcare Inc. |
| Spot & Tango |
| Nature's Variety |
| Nestlé Purina PetCare |
| Stella & Chewy's |
| JustFoodForDogs |
| The Farmer's Dog |
| Others |
Cost & Logistics Intelligence
Sixty-to-ninety-day cold-chain inventory cycles in frozen raw formats concentrate pricing power with HACCP-certified facilities possessing captive grinding infrastructure, while marginal producers face margin compression from USDA-inspected protein cost pass-through obligations.
Pricing Analysis
Cost-plus contracts indexed to CME live cattle and broiler futures dominate beef and chicken input sourcing, with premium freeze-dried formats commanding three-tier pricing structure across premium, standard, and economy levels based on AAFCO certification status and organic protein designation. Pricing pressure stems from volatile commodity markets tethering margins to livestock futures spikes, with subscription-based direct-to-consumer buyers exhibiting lowest price sensitivity versus mass retail supermarket channels.
Supply Chain Analysis
The United States anchors USDA-inspected protein processing with Wisconsin and Texas manufacturing clusters, while Australia and New Zealand supply premium grass-fed beef inputs. Cold-chain logistics draw from refrigerated trucking networks and last-mile frozen fulfillment centers, with single-source vulnerability concentrated in interstate licensing fragmentation disrupting multi-state distribution. Distribution runs through pet specialty stores with refrigerated display infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment through FDA HACCP certification creates enduring barriers against unverified cottage competitors.
For Market Incumbents: Fortify batch-level traceability systems with in-house flash-freezing infrastructure to satisfy FDA recall documentation requirements against emerging high-pressure processing substitution threats. Deepen channel control through exclusive pet specialty store refrigerated display partnerships. For New Entrants and Emerging Players: Lead with freeze-dried shelf-stable formats penetrating online retail channels where lightweight shipping economics bypass cold-chain capex barriers. Target coastal metropolitan corridors in California and New York with compressed delivery window subscription models. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified multinational pet care conglomerates seeking raw portfolio divestitures; veterinary nutritionist talent scarcity signals long-term formulation capability value. Watch FDA enforcement discretion tightening as inflection indicator for compliance cost acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| HACCP Certification Investment | FDA zero-tolerance Salmonella enforcement mandates validated environmental monitoring protocols. |
| Freeze-Dried Capacity Expansion | Lightweight formats capture online retail economics in California and New York corridors. |
| Direct-to-Consumer Platform Launch | Subscription models displace pet specialty foot traffic with compressed delivery windows. |
| Backward Integration into Protein Sourcing | Captive USDA-inspected supply buffers margin exposure to cattle futures volatility. |
| Veterinary Nutritionist Recruitment | AAFCO protocol expertise commands premium compensation and extends competitive moats. |
Research Approach
Findings reconcile primary fieldwork against secondary review of FDA enforcement documentation, USDA inspection records, and state agriculture department licensing databases through structured interviews with raw pet food manufacturing executives, cold-chain logistics operators, veterinary nutritionists, and pet specialty retail category buyers. Bottom-up volume triangulation across product format segments was validated against top-down protein input consumption estimates.
Segmentation dimensions modeled include preservation technology, species-specific formulation, protein sourcing, and distribution channel across the analysis window, with CAGRs derived from trend extrapolation of millennial pet ownership conversion rates and cold-chain infrastructure expansion timelines. Forecast inputs incorporated AAFCO certification adoption curves and FDA enforcement intensity scenarios.
The analysis sits within stated boundaries; outcomes outside sustained coastal metropolitan demand concentration or significant cottage food exemption liberalization would require recalibration. Recalibration cycles align with material shifts in FDA enforcement discretion and interstate licensing harmonization efforts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Japan Pet Boarding Market
Pet Care Products
Pet Transporting Service Market
Pet Care Products
Dog Food and Snacks Market
Pet Care Products
Australia Pet Boarding Market
Pet Care Products
Dog Treats Market
Pet Care Products
Europe Pet Treats Market
Pet Care Products
Dog Seat Belt Market
Pet Care Products
Brazil Cat Litter Market
Pet Care Products
Pet Meal Kit Delivery Services Market
Pet Care Products
UK Pet Treats Market
Pet Care Products
Elevated Dog Bowls Market
Pet Care Products
France Pet Food Market
Pet Care Products
Canada Pet Food Market
Pet Care Products
Pet Food Nutraceutical Market
Pet Care Products
Hypoallergenic Dog Food Market
Pet Care Products
Dog Litter Boxes Market