
 South Korea Organic and Natural Pet Food Market | 2026-2036
South Korea Organic and Natural Pet Food Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Organic and Natural Pet Food Market Intelligence
South Korea is narrowing the gap between imported and domestic organic pet food supply as local manufacturing capacity expands around Gyeonggi-do and North Chungcheong Province. Pulmuone Co., Ltd. leverages its cold-chain logistics network to anchor freshness positioning in wet food segments. LG Unicharm competes through vertical integration into absorbent material technologies that extend to pet hygiene adjacencies. Natural Core Co Ltd specializes in human-grade ingredient sourcing, occupying a premium niche among Seoul-based millennial pet owners.
Organic and natural pet food comprises formulated diets manufactured without synthetic pesticides, antibiotics, growth hormones, or artificial preservatives, typically requiring AAFCO nutrient profiles or equivalent digestibility standards exceeding conventional kibble thresholds. The category serves commercial purpose by addressing owner concerns about allergen reduction, longevity optimization, and ethical sourcing transparency in companion animal nutrition. Dry food dominates volume throughput due to shelf stability advantages, while wet food captures disproportionate margin pools through refrigerated distribution premiums. Ingredient source segmentation reveals organic certification commanding price multiples over natural claims, with non-GMO positioning gaining traction among regulatory-attentive buyers. Distribution channel structure shows online retail accelerating fastest, though pet specialty stores retain consultative influence for first-time premium conversions.
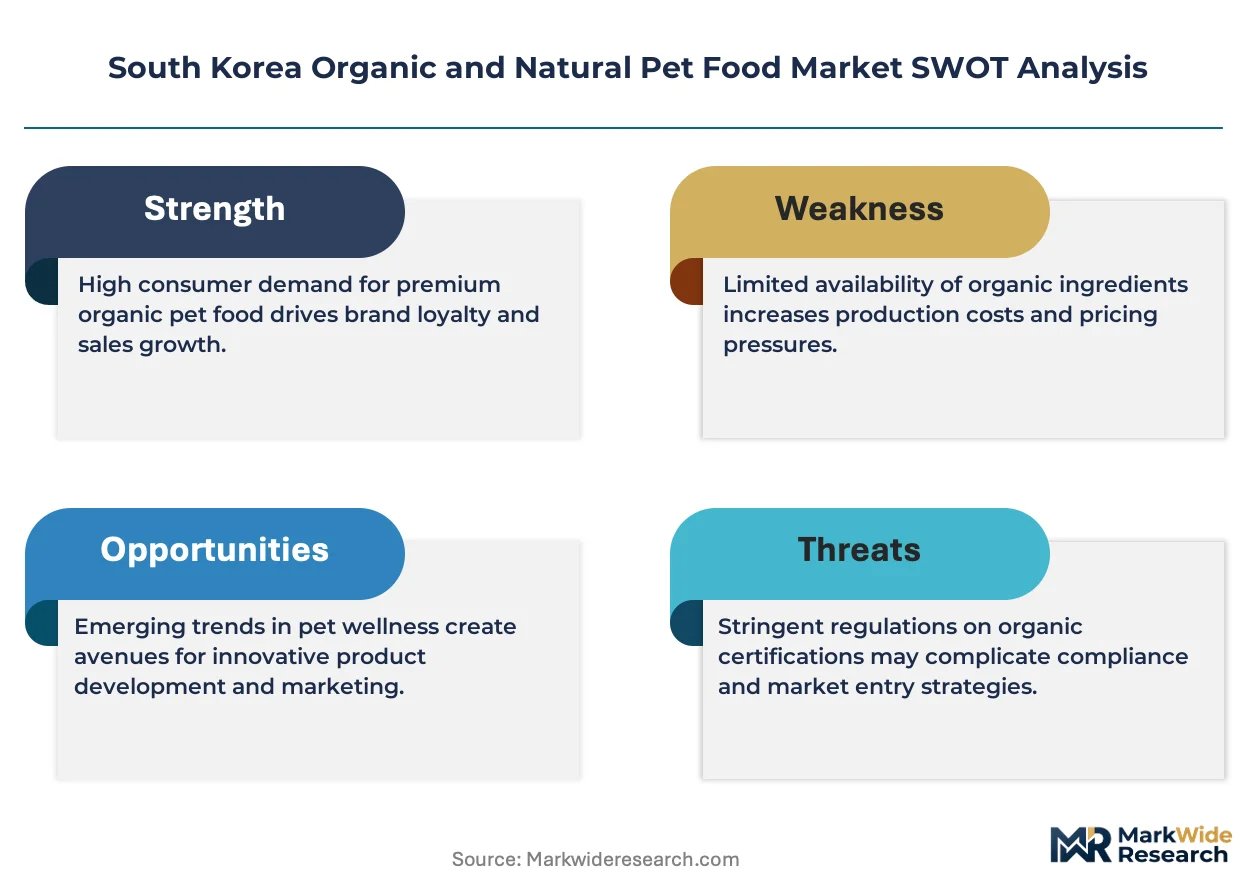
MFDS feed safety standards govern manufacturing facility audits and ingredient contaminant thresholds, while the Ministry of Agriculture, Food and Rural Affairs administers organic certification equivalency for pet food labeling claims. KFDA-aligned import inspection protocols shape market access timelines for foreign suppliers seeking Korean distribution partnerships. Stakeholders must monitor evolving labeling enforcement intensity and domestic certification capacity build-out to calibrate localization versus import strategies.
Market Dynamics
MFDS tightening of feed safety standards and ingredient traceability obligations is compressing formulation timelines for domestic manufacturers while elevating compliance costs across the supply base.
Growth Catalysts
- Pet Humanization in Seoul Metropolitan Area:Premium dog ownership among apartment dwellers is accelerating demand for certified organic formulations with AAFCO-equivalent nutrient profiles.
- MFDS Labeling Requirements:New enforcement intensity around organic certification equivalency is rewarding early compliance investments by established domestic producers.
- Cold-Chain Logistics Expansion:Wet food segments are capturing refrigerated distribution premiums as freshness positioning becomes a purchase determinant.
Market Restraints
- Import Inspection Protocols:KFDA-aligned border controls create extended market access timelines for foreign suppliers seeking Korean distribution partnerships.
- Organic Certification Capacity:Limited domestic equivalency assessment infrastructure bottlenecks new product launches requiring Ministry of Agriculture verification.
- Ingredient Source Concentration:Human-grade sourcing standards restrict supplier pools to premium agricultural regions, elevating input cost volatility.
Strategic Opportunities
- Busan Corridor Penetration:Secondary metropolitan markets exhibit lower competitive saturation while maintaining comparable pet humanization intensity to Seoul.
- Online Retail Channel Acceleration:Digital platforms are displacing traditional pet specialty stores for repeat purchases among digitally native millennial owners.
- Non-GMO Positioning:Regulatory-attentive buyer segments are creating price-premium capture opportunities distinct from full organic certification.
Industry Challenges
- Formulation Talent Scarcity:Veterinary nutrition specialists with human-grade food safety credentials command compensation premiums that strain mid-tier manufacturer budgets.
- Facility Audit Preparation:MFDS manufacturing site inspections require capex-intensive cleanroom upgrades and documentation systems that extend payback periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Organic and Natural Pet Food Market |
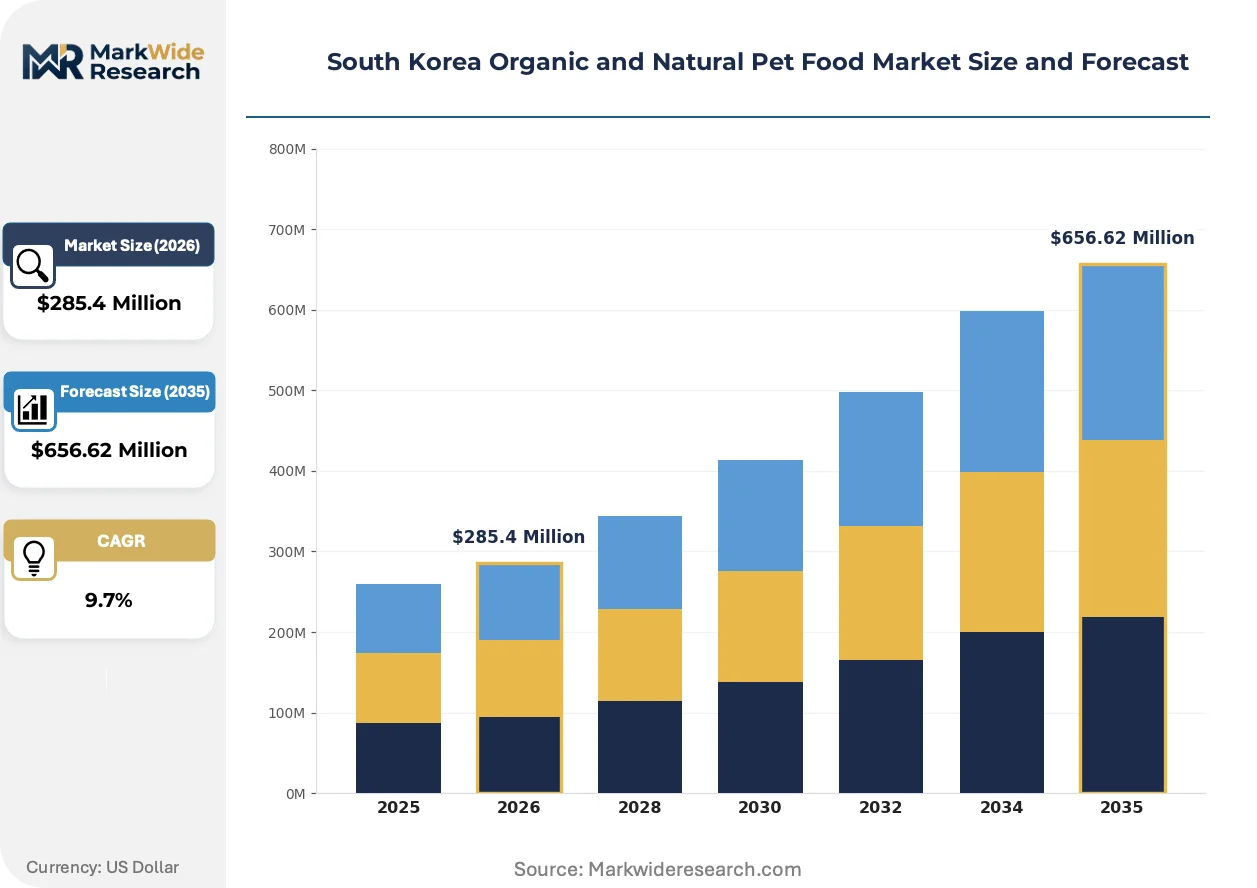
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $656.62 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Food, Wet Food, Treats, Supplements Ingredient Source: Organic, Natural, Non-GMO, Raw Target Animal: Dogs, Cats, Small Animals, Large Animals Distribution Channel: Online Retail, Pet Specialty Stores, Supermarkets, Direct Sales |
| Companies Covered | Pulmuone Co., Ltd., LG Unicharm, CARESIDE Co., Ltd., ANF, CJ CheilJedang Corp, Rosco Fine Foods Inc., Natural Core Co Ltd, Harim Co Ltd, Maya Trading Co, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Organic and Natural Pet Food Market Strategic Shifts & Innovations
Ingredient sourcing transparency and freshness preservation technologies are reshaping competitive positioning across wet and dry food segments, while regulatory enforcement intensity accelerates certification investments.
High-pressure processing (HPP) is migrating from human food applications into premium pet food manufacturing, extending shelf life without synthetic preservatives. Seoul-based millennial owners are adopting HPP-treated products at accelerated rates for allergen-sensitive companion animals. This migration from conventional thermal processing is compressing margin structures for legacy kibble manufacturers while enabling refrigerated distribution premiums.
MFDS organic certification equivalency requirements are tightening enforcement timelines for labeling claims, compelling manufacturers to accelerate documentation investments. Domestic producers with established Ministry of Agriculture relationships are securing faster approvals than import-dependent competitors. Wet food segments with shorter supply chains are responding most aggressively to capture first-mover positioning.
Subscription-based replenishment models are displacing episodic retail purchasing among premium segment owners, locking in recurring revenue streams. Digital-native platforms with cold-chain integration are capturing share from consultative pet specialty stores. This behavioral shift is most visible in Seoul apartment complexes with high pet ownership density and limited storage space for bulk dry food purchases.
South Korea Organic and Natural Pet Food Market Segmentation
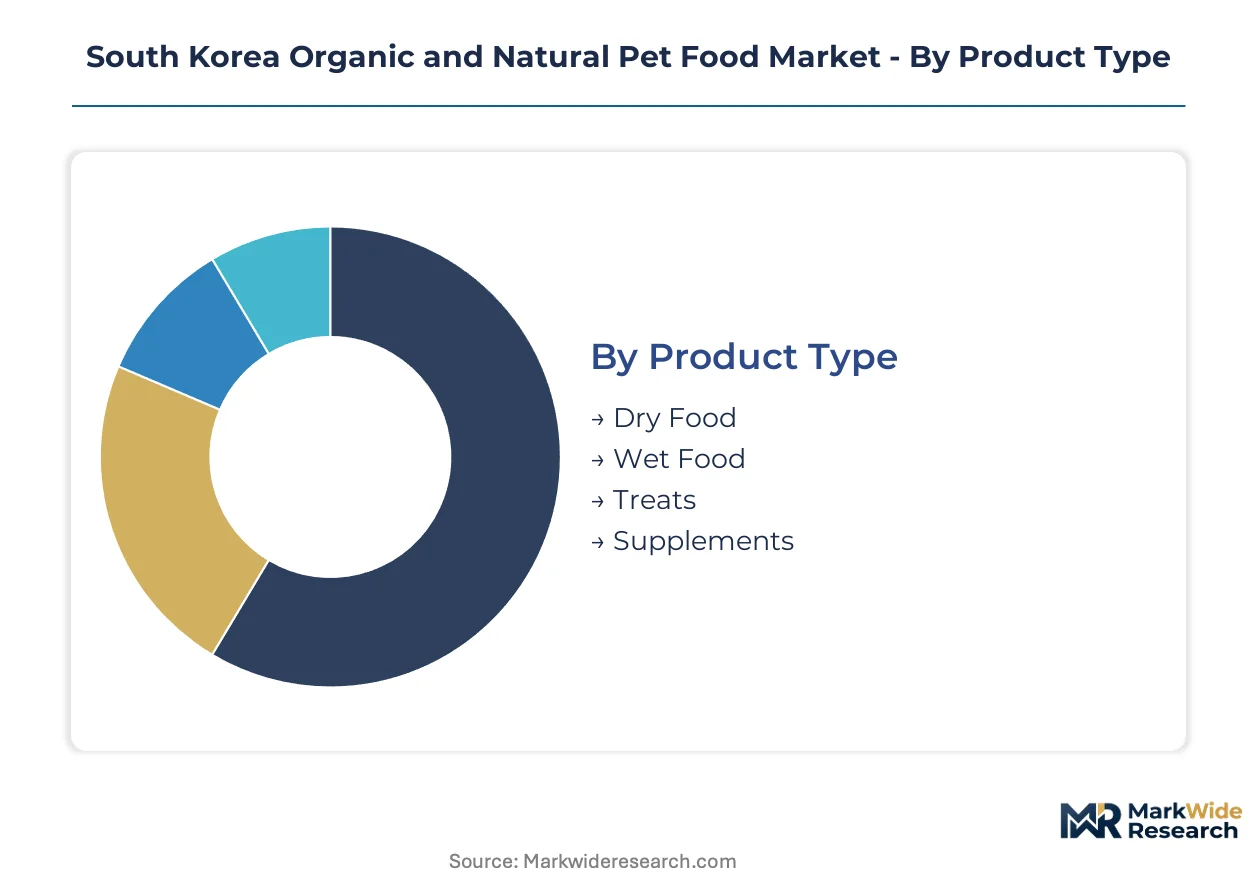
South Korea's organic and natural pet food market segments along four dimensions that determine pricing power, regulatory exposure, and channel strategy. Understanding these divisions reveals where MFDS compliance costs concentrate and which segments offer margin protection through certification premiums.
Product Type:
After-sales service intensity varies sharply across product types, with wet food requiring refrigerated logistics support and dry food demanding minimal post-purchase engagement.
- Wet Food:Formulated with higher moisture content and requiring cold-chain preservation, this segment commands refrigerated distribution premiums in Seoul apartment complexes where freshness positioning drives repurchase rates. Pulmuone's logistics network anchors competitive defense here.
- Dry Food:Shelf-stable kibble formulations dominate volume throughput due to storage convenience for space-constrained urban owners, though margin compression from conventional thermal processing limits pricing power relative to HPP-treated alternatives.
- Treats:Functional and reward-based formulations occupy a discretionary purchase position with lower regulatory scrutiny than complete diets.
- Supplements:Nutritional additives targeting longevity optimization and allergen management serve niche demand among veterinary-guided owners.
Dry Food holds the largest share; momentum sits with Wet Food.
Ingredient Source:
Cost tier differentiation separates segments that can absorb MFDS compliance investments from those competing on price proximity to conventional feed.
- Organic:Certified formulations meeting Ministry of Agriculture equivalency standards command the steepest price multiples, with Seoul-based millennial owners driving disproportionate adoption for allergen-sensitive companion animals. Documentation requirements and facility audit investments create barriers that favor established domestic producers.
- Natural:Human-grade ingredient positioning without full organic certification occupies a mid-premium tier, with Natural Core's sourcing transparency model capturing share among regulatory-attentive buyers.
- Non-GMO:Genetically modified organism avoidance claims are gaining traction as a distinct positioning axis for buyers seeking transparency without organic price premiums.
- Raw:Unprocessed or minimally processed formulations serve a niche of owners pursuing ancestral diet theories, with cold-chain dependency limiting geographic reach.
Natural holds the largest share; momentum sits with Organic.
Target Animal:
Application-specific formulation requirements create divergent R&D intensity and veterinary consultation dependencies across animal categories.
- Dogs:Premium ownership among Seoul apartment dwellers concentrates demand for certified organic formulations with AAFCO-equivalent nutrient profiles, driving the highest per-capita spending and subscription model adoption.
- Cats:Obligate carnivore physiology demands higher protein specifications, with wet food preference elevating refrigerated distribution requirements relative to canine segments.
- Small Animals:Rabbit, hamster, and bird formulations occupy a fragmented niche with limited organic certification penetration and lower regulatory visibility.
- Large Animals:Working dog and equine applications represent a marginal share with distinct bulk purchasing patterns and veterinary channel dependencies.
Dogs holds the largest share; momentum sits with Cats.
Distribution Channel:
Customer type segmentation separates digitally native repeat purchasers from consultative first-time converters requiring education on certification claims.
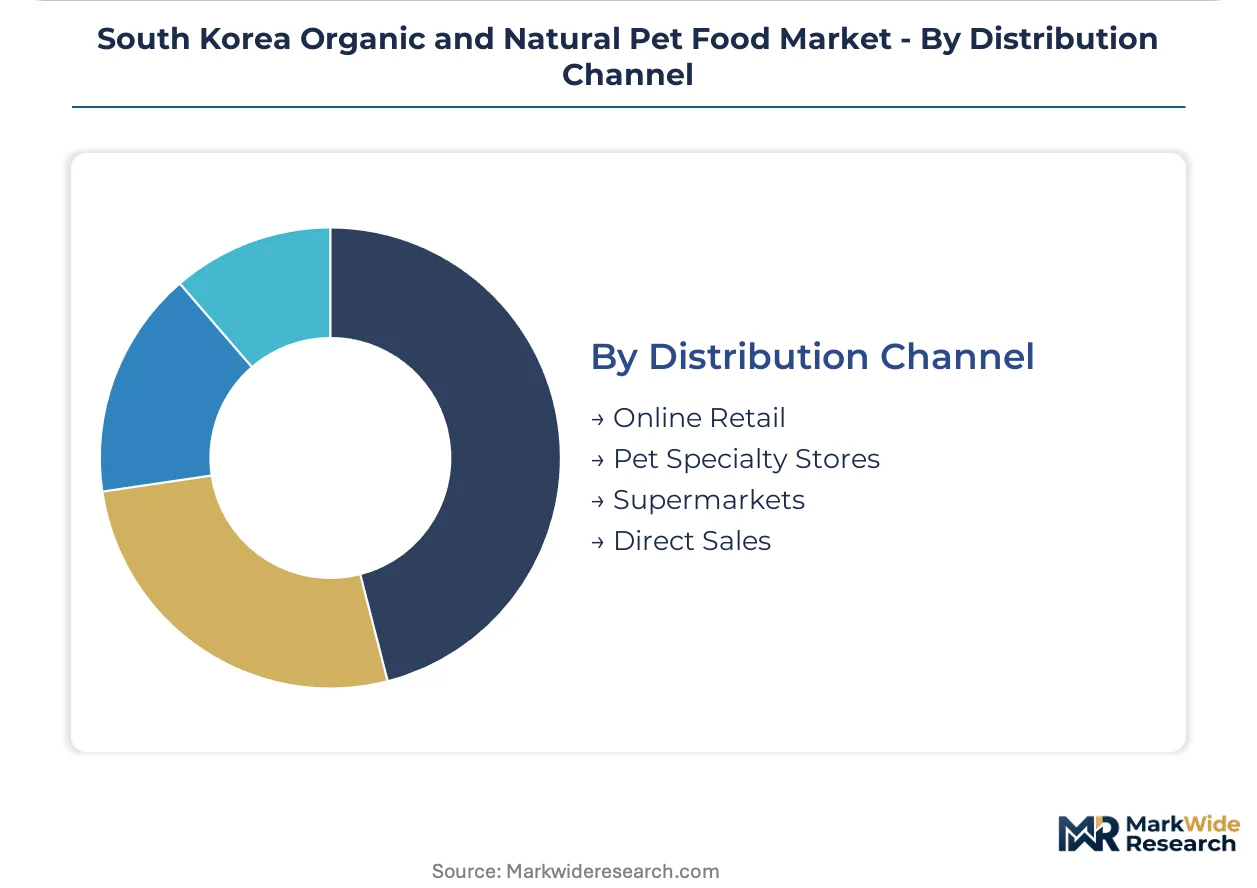
- Online Retail:Subscription-based replenishment models are displacing episodic purchasing among millennial owners, with cold-chain-integrated platforms capturing share from traditional stores. This channel is expanding most quickly in high-density Seoul apartment complexes.
- Pet Specialty Stores:Consultative staff retain influence for first-time premium conversions and complex dietary guidance, though their share of repeat purchases is eroding.
- Supermarkets:Mass retail placement offers volume access but limited certification education, compressing margins through price competition with conventional feed.
- Direct Sales:Veterinary clinic and breeder channel relationships provide trusted endorsement but constrain scale through professional gatekeeper dependencies.
Online Retail holds the largest share; momentum sits with Direct Sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Incheon International Airport cold-chain cargo terminal underwrites South Korea's position as the regional hub for temperature-sensitive pet nutrition imports, connecting Seoul's premium consumer base to European and North American organic suppliers.
Seoul Capital Area
Apartment-dwelling millennial pet owners drive certified organic formulation demand, with MFDS feed safety audits concentrating enforcement resources on Gyeonggi-do manufacturing facilities. Seongnam and Suwon host expanding wet food production clusters serving subscription-based replenishment models.
Busan-Ulsan Corridor
Secondary metropolitan markets exhibit comparable pet humanization intensity to Seoul with lower competitive saturation, attracting cold-chain logistics investment from domestic producers. Ulsan's port infrastructure facilitates ingredient import efficiency for natural formulation manufacturers.
Daegu-Gyeongbuk
Veterinary consultation networks in this region anchor direct sales channel penetration for longevity-focused supplement formulations. Daegu's distribution hub position enables reach into underserved inland markets with growing premium pet ownership.
Daejeon-Sejong
Government administrative concentration supports regulatory compliance service clustering, with Sejong hosting Ministry of Agriculture certification equivalency assessment capacity expansion. Daejeon-based R&D facilities focus on alternative protein sourcing for organic feed applications.
Gwangju-Honam
Agricultural supply base concentration in Jeolla provinces supports human-grade ingredient sourcing for natural positioning tiers, though organic certification penetration lags metropolitan corridors. Regional cold-chain gaps constrain wet food segment development.
South Korea Organic and Natural Pet Food Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in ingredient sourcing and certification compliance. Domestic manufacturers with established MFDS relationships consolidate share through faster organic equivalency approvals, while import-dependent competitors face extended KFDA-aligned inspection timelines. Three archetypes define competitive positioning: cold-chain logistics-integrated fresh food platforms, vertically integrated hygiene-to-nutrition conglomerates, and human-grade sourcing specialists. Capacity expansion in Gyeonggi-do and strategic partnerships with agricultural cooperatives represent the dominant competitive vectors.
Among domestic integrated food conglomerates, Pulmuone Co., Ltd. and CJ CheilJedang Corp occupy positions leveraging existing cold-chain infrastructure and agricultural supply relationships. LG Unicharm exemplifies the hygiene-to-nutrition vertical integration archetype, while Natural Core Co Ltd represents the human-grade sourcing specialist tier targeting Seoul-based premium segments. These anchors illustrate how regulatory compliance speed and supply chain control separate market tiers.
| Leading Market Players |
|---|
| Pulmuone Co., Ltd. |
| LG Unicharm |
| CARESIDE Co., Ltd. |
| ANF |
| CJ CheilJedang Corp |
| Rosco Fine Foods Inc. |
| Natural Core Co Ltd |
| Harim Co Ltd |
| Maya Trading Co |
| Others |
Cost & Logistics Intelligence
MFDS organic certification equivalency bottlenecks compress formulation timelines while elevating compliance investments, forcing tier spreads that separate cold-chain-integrated fresh platforms from conventional thermal processors and shaping supply chain decisions toward domestic Gyeonggi-do manufacturing clusters over import-dependent models.
Pricing Analysis
Volume-discount tiering structures dominate subscription-based replenishment models, with Seoul apartment complexes capturing steeper per-unit reductions for bulk dry food commitments. Certification grade and cold-chain service intensity drive price differentiation, with HPP-treated wet food commanding refrigerated distribution premiums. Pricing pressure stems from MFDS facility audit preparation costs elevating breakeven thresholds for mid-tier manufacturers. Mass retail buyers exhibit highest price sensitivity, while veterinary-guided direct purchasers accept premium positioning for longevity-focused formulations.
Supply Chain Analysis
KFDA-aligned import inspection protocols function as de facto export controls limiting foreign supplier market access, compressing timelines for domestic equivalency investments. Raw material sourcing draws from Jeolla province agricultural cooperatives for human-grade ingredients, Australian organic protein imports, and North American HPP equipment technology. Single-source vulnerability concentrates in Ministry of Agriculture certification assessment capacity. Distribution runs through cold-chain-integrated online platforms displacing traditional pet specialty stores for repeat purchases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation creates white-space opportunities as pet humanization splinters demand across allergen-specific, longevity-optimized, and ethically-sourced formulation niches that reward specialized positioning over mass-market scale.
For Market Incumbents: Pre-empt emerging entrant incursions by accelerating Gyeonggi-do wet food capacity expansion and locking exclusive agricultural cooperative supply contracts. MFDS relationship depth enables faster organic equivalency approvals than import-dependent competitors can match. Cold-chain infrastructure control anchors defensive positioning against digital-native platform challengers.
For New Entrants and Emerging Players: Build out Busan corridor penetration before competitive saturation replicates Seoul intensity, targeting secondary metropolitan markets with comparable pet humanization trends. Non-GMO positioning offers regulatory-attentive buyer capture without full organic certification infrastructure burdens. Subscription model partnerships with cold-chain-integrated platforms provide lowest-friction go-to-market entry.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors human-grade sourcing specialists with established Ministry of Agriculture relationships over import-dependent distribution plays. Long-term viability hinges on backward integration into agricultural supply and certification compliance speed. Watch MFDS enforcement intensity escalation as the inflection signal for compliance-capability valuation premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Chain Infrastructure Expansion | Refrigerated distribution premiums in Seoul apartment complexes defend margin pools against conventional thermal processors. |
| Organic Certification Investment | MFDS equivalency approval speed separates market tiers and compresses competitor formulation timelines. |
| Agricultural Cooperative Partnership | Exclusive Jeolla province human-grade ingredient sourcing locks in supply security for natural positioning tiers. |
| Subscription Platform Integration | Digital-native replenishment models capture recurring revenue from space-constrained urban millennial owners. |
| Busan Corridor Manufacturing Footprint | Secondary metropolitan penetration exploits lower competitive saturation with comparable pet humanization intensity. |
Research Approach
Operator-level perspectives from pet food manufacturing executives, veterinary nutrition specialists, cold-chain logistics managers, and Ministry of Agriculture certification officers anchored the qualitative base. Secondary validation drew from MFDS feed safety audit disclosures, customs import inspection records, agricultural cooperative supply reports, and Seoul metropolitan area retail audit data. Bottom-up segment sizing triangulated against top-down market value reconstruction across product type, ingredient source, target animal, and distribution channel dimensions.
Scenario-bracketing framed projections across the analysis window, with CAGRs derived from elasticity modeling against pet ownership density, disposable income trajectories, and regulatory enforcement intensity assumptions. Segmentation modeling incorporated product format, certification tier, animal physiology requirements, and channel digitalization pace. Forecast inputs included cold-chain infrastructure expansion timelines and organic equivalency assessment capacity build-out rates.
Sensitivities concentrate around MFDS enforcement intensity escalation, KFDA-aligned import protocol modifications, and agricultural commodity input volatility. Forecasts reflect documented assumptions about certification capacity expansion and pet humanization trend persistence. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Dog Safety Leash Market
Pet Care Products
Canada Pet Food Market
Pet Care Products
UAE Cat Food Market
Pet Care Products
Pet Clean-Up and Odor-Control Products Market
Pet Care Products
Cat Bed Market
Pet Care Products
UAE Pet Boarding Market
Pet Care Products
Pet Relaxants Market
Pet Care Products
Vegan Dog Food Market
Pet Care Products
Household Pet Water Dispenser Market
Pet Care Products
Cat Cage Market
Pet Care Products
Pet Food Nutraceutical Market
Pet Care Products
China Pet Clothing Market
Pet Care Products
UK Pet Treats Market
Pet Care Products
US Pet Daycare Market
Pet Care Products
Dog Sunglasses Market
Pet Care Products
Pet Jerky Treat Market